
 Off Road All Terrain E-Scooter Market | 2026-2036
Off Road All Terrain E-Scooter Market Size, Share, and Industry Trends Forecast 2026-2036
Off Road All Terrain E-Scooter Market Analytics
The EU Green Deal is decoupling off-road e-scooter demand from purely recreational positioning by embedding carbon-reduction mandates into outdoor tourism licensing. Segway-Ninebot leverages its manufacturing scale to dominate European distribution channels. Kaabo specializes in dual-motor architectures that sustain technical credibility among mountain pathway riders. Apollo Scooters anchors North American market presence through direct-to-consumer channel control.
An off-road all-terrain e-scooter is a battery-powered personal mobility device engineered with enhanced suspension travel, knobby pneumatic tires, and sealed drivetrain housings to traverse unpaved surfaces including gravel, mud, and loose rock; units typically deliver 1,000W to 5,000W peak motor output and carry IPX5 or higher ingress protection ratings for commercial durability. Folding frame configurations lead volume sales among urban commuters seeking multimodal transit integration, while enhanced suspension variants command the strongest margin pools from outdoor enthusiasts operating in mountain pathway terrain. Electric battery power sources retain structural dominance across all terrain capability segments, though regenerative systems are gaining fastest adoption in high-elevation markets where descent energy recovery extends range.
The EPA enforces lithium-ion battery recycling standards that shape end-of-life compliance costs for US manufacturers, while the EU's RoHS and REACH frameworks restrict hazardous substances in motor windings and frame coatings. China's MIIT governs GB standards for motor power classification and battery safety testing that determine export eligibility. Stakeholders must monitor evolving battery certification reciprocity between the EU and North America to anticipate supply chain reconfiguration requirements.
Market Dynamics
Adventure tourism operators across Colorado and British Columbia are expanding fleet purchases of enhanced suspension models, pulling capital toward commercial-grade durability specifications and away from consumer recreational positioning.
Growth Catalysts
- EU Green Deal micromobility incentives:Battery technology upgrades accelerate as outdoor tourism licensing embeds carbon-reduction mandates across Germany's Black Forest trail networks.
- Dual-motor architecture adoption:Mountain pathway riders sustain technical credibility demands that push peak output specifications toward 5,000W configurations.
- Regenerative braking systems:High-elevation markets including Australia's Outback prioritize descent energy recovery mechanisms that extend operational range.
Market Restraints
- Lithium-ion input cost volatility:EPA recycling standards shape end-of-life compliance burdens that compress margin structures for US-based manufacturers.
- Supply concentration in China:MIIT GB standards for motor power classification and battery safety testing determine export eligibility, creating single-point certification dependencies.
- Sealed drivetrain technical limitations:IPX5 ingress protection thresholds constrain deep-water fording applications, restricting commercial use-case expansion.
Strategic Opportunities
- Battery certification reciprocity gaps:Anticipated EU-North America mutual recognition agreements would reconfigure supply chain routing requirements for cross-border manufacturers.
- Direct-to-consumer channel innovation:North American market presence anchors through bypassing traditional outdoor retail distribution, capturing margin pools previously allocated to intermediaries.
- Folding frame multimodal integration:Urban commuter segments seek transit-adjacent storage solutions that knobby pneumatic tire configurations currently underserve.
Industry Challenges
- Suspension calibration skill scarcity:Enhanced suspension travel variants require specialized technician training that outdoor rental fleets struggle to staff at scale.
- REACH compliance timeline compression:RoHS hazardous substance restrictions in motor windings and frame coatings demand reformulation cycles that outpace product refresh schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off Road All Terrain E-Scooter Market |
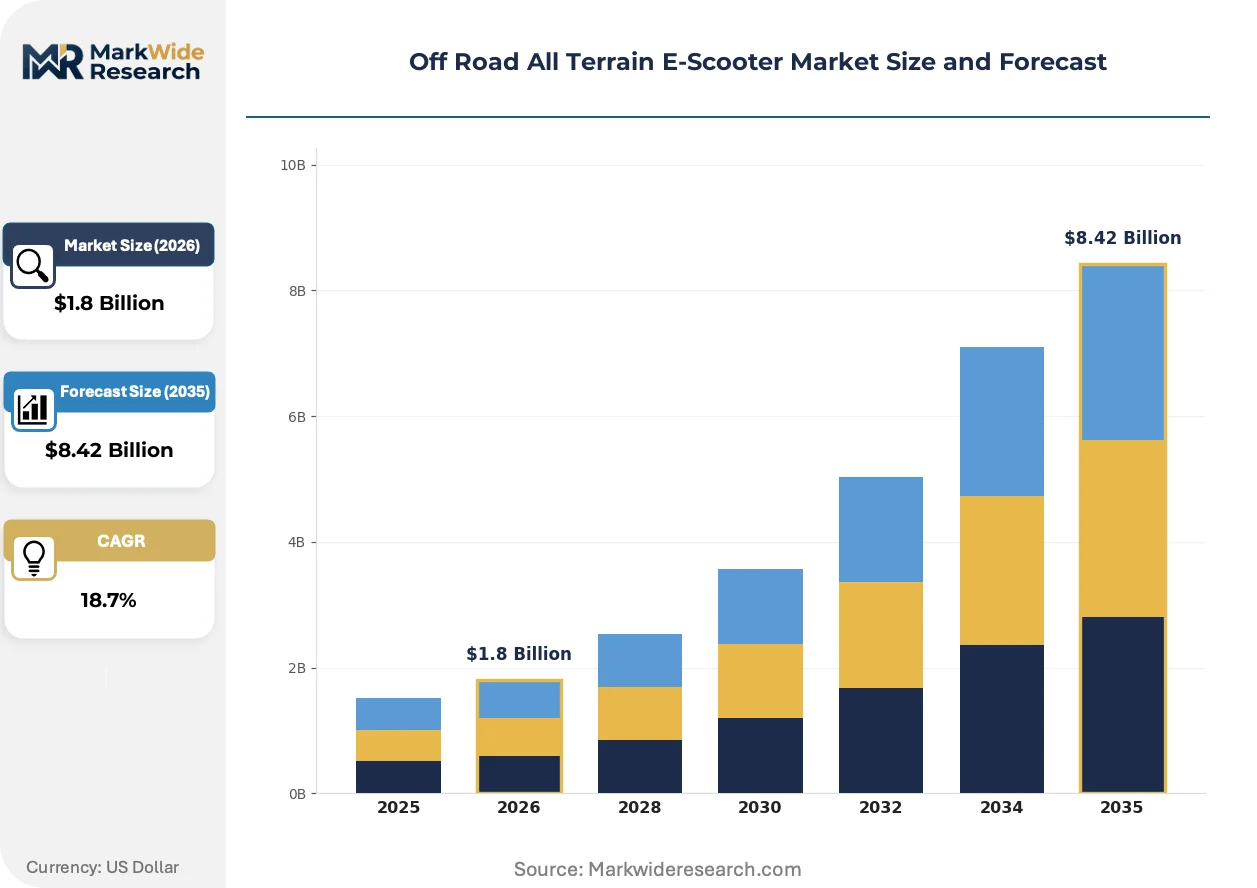
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Frame, Folding Frame, Compact Design, Enhanced Suspension End User: Outdoor Enthusiasts, Urban Commuters, Recreational Riders, Delivery Services Power Source: Electric Battery, Solar-Powered, Hybrid, Regenerative Systems Terrain Capability: Mountain Pathways, Gravel Roads, Snowy Surfaces, Sandy Dunes |
| Companies Covered | Apollo Scooters, Inokim, Segway-Ninebot, Varla Scooter, EMOVE, Kaabo, Xiaomi Corporation, Kugoo, Dualtron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off Road All Terrain E-Scooter Market Evolving Landscape
Active suspension telemetry is automating real-time damping adjustments, compressing the technical gap between commercial fleet operators and individual outdoor enthusiasts.
Regenerative braking integration is automating energy recovery protocols across high-elevation descent corridors, enabling adventure tourism operators in Colorado and British Columbia to extend daily fleet utilization without midday charging infrastructure. Mountain pathway riders adopt these systems fastest where elevation gain exceeds 500 meters per circuit. The technology is automating range anxiety reduction, compressing the competitive advantage of larger battery pack configurations.
REACH and RoHS frameworks are tightening hazardous substance restrictions in motor windings and frame coatings across European manufacturing nodes. Industrial consequence falls heaviest on small-batch frame producers lacking in-house chemical compliance laboratories. Segments serving Germany's Black Forest region respond fastest, embedding ECHA pre-certification into supplier qualification protocols.
Rental fleet procurement is consolidating around outcome-based utilization contracts that unbundle hardware ownership from maintenance liability. Adventure tourism operators in Australia's Outback now favor per-kilometer service agreements over capital purchase models. This behavioral pivot concentrates supplier selection power among manufacturers with captive service networks.
Off Road All Terrain E-Scooter Market Segmentation
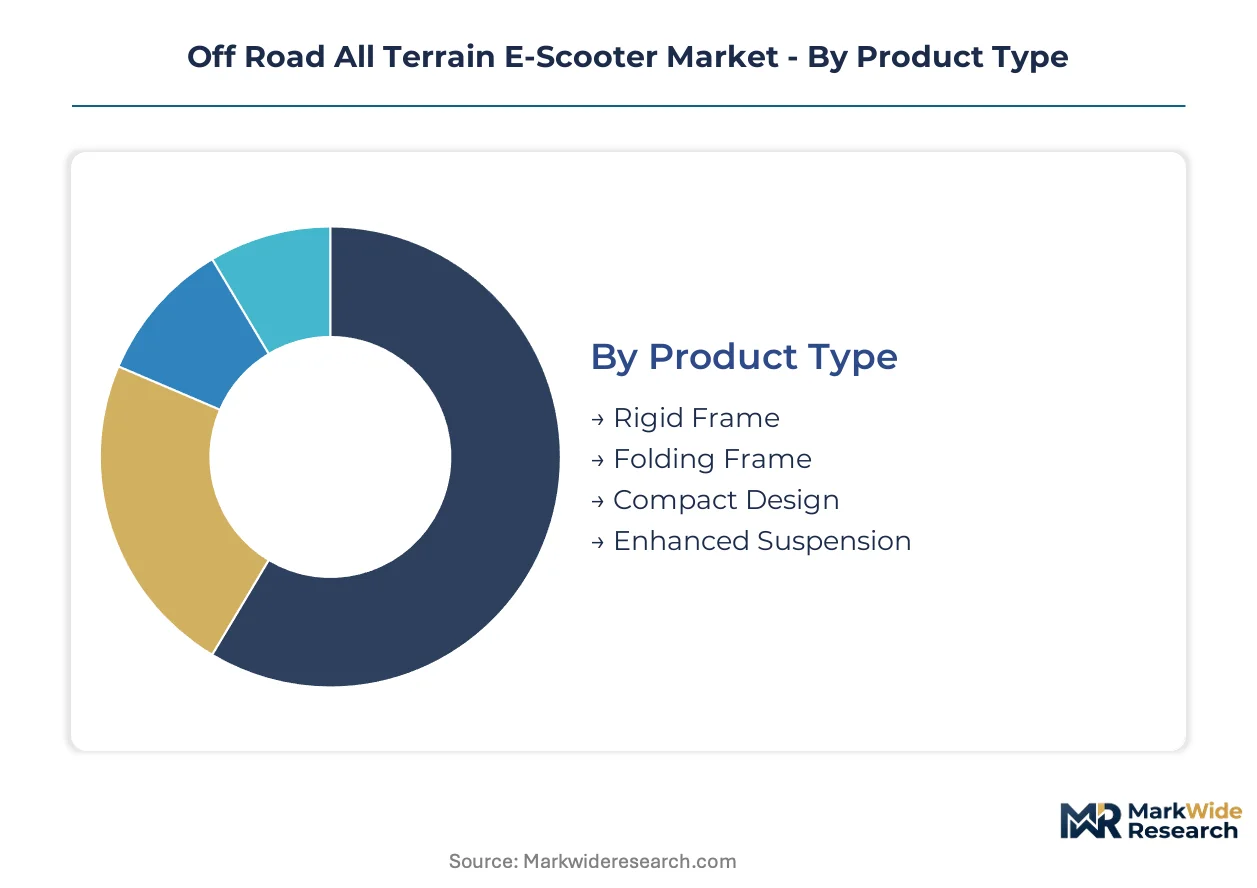
Off-road e-scooter segmentation reflects divergent engineering priorities between recreational portability and commercial durability. Product architecture choices cascade through powertrain specifications, end-use licensing requirements, and terrain-rated component sourcing.
Product Type:
Customization intensity spans from standardized commuter formats to purpose-built expedition chassis requiring suspension tuning expertise.
- Folding Frame:Hinge mechanisms with reinforced locking collars enable rapid stowage for multimodal transit integration. Demand concentrates among Germany's urban commuters seeking Deutsche Bahn-compatible dimensions where station-adjacent storage constraints dominate purchase criteria.
- Enhanced Suspension:Long-travel dampers with adjustable rebound settings sustain peak loads across Colorado's alpine descent corridors. Adventure tourism operators in British Columbia mandate these configurations for fleet insurance compliance on technical singletrack routes.
- Rigid Frame:Fixed geometry welded chassis prioritize manufacturing repeatability for high-volume export markets.
- Compact Design:Reduced wheelbase dimensions target last-mile delivery fleets operating within Australia's Outback station complexes.
Most installed capacity flows through Folding Frame configurations. Expansion is steepest in Enhanced Suspension variants.
End User:
Customer acquisition cost tiers separate individual recreational purchasers from enterprise fleet procurement with captive service requirements.
- Outdoor Enthusiasts:Technical specification literacy drives preference for dual-motor architectures with field-serviceable controllers. Germany's Black Forest trail network operators represent the densest concentration of high-aspiration purchasers seeking IPX6-rated drivetrain protection.
- Delivery Services:Route-optimized battery swapping protocols prioritize standardized charging interfaces over performance specifications. Australia's remote logistics contractors favor these units for station-to-station cargo movement where technician access is limited.
- Urban Commuters:Weight-minimization preferences align with folding frame compatibility for subway and bus integration.
- Recreational Riders:Weekend-use patterns sustain entry-tier pricing acceptance with reduced durability expectations.
Delivery Services account for the largest fleet procurement volume. Outdoor Enthusiasts generate the highest per-unit margin realization.
Power Source:
Energy architecture selection tracks elevation profile, charging infrastructure density, and regulatory incentive alignment across operating territories.
- Electric Battery:Lithium-ion cell configurations with 48V to 72V nominal voltage dominate commercial specifications. Colorado's high-elevation tour operators require these systems for consistent torque delivery where altitude degrades internal combustion efficiency.
- Regenerative Systems:Descent-activated charging circuits extend operational range without battery mass penalties. British Columbia's mountain pathway networks see fastest adoption where vertical drop exceeds 800 meters per circuit and midday charging infrastructure is absent.
- Hybrid:Dual-mode architectures retain fossil-fuel range extension for Australia's extended Outback traverse requirements.
- Solar-Powered:Integrated panel surfaces target scientific survey applications with extended stationary deployment patterns.
Electric Battery configurations retain structural dominance across all terrain ratings. Regenerative Systems are gaining share fastest in high-elevation commercial deployments.
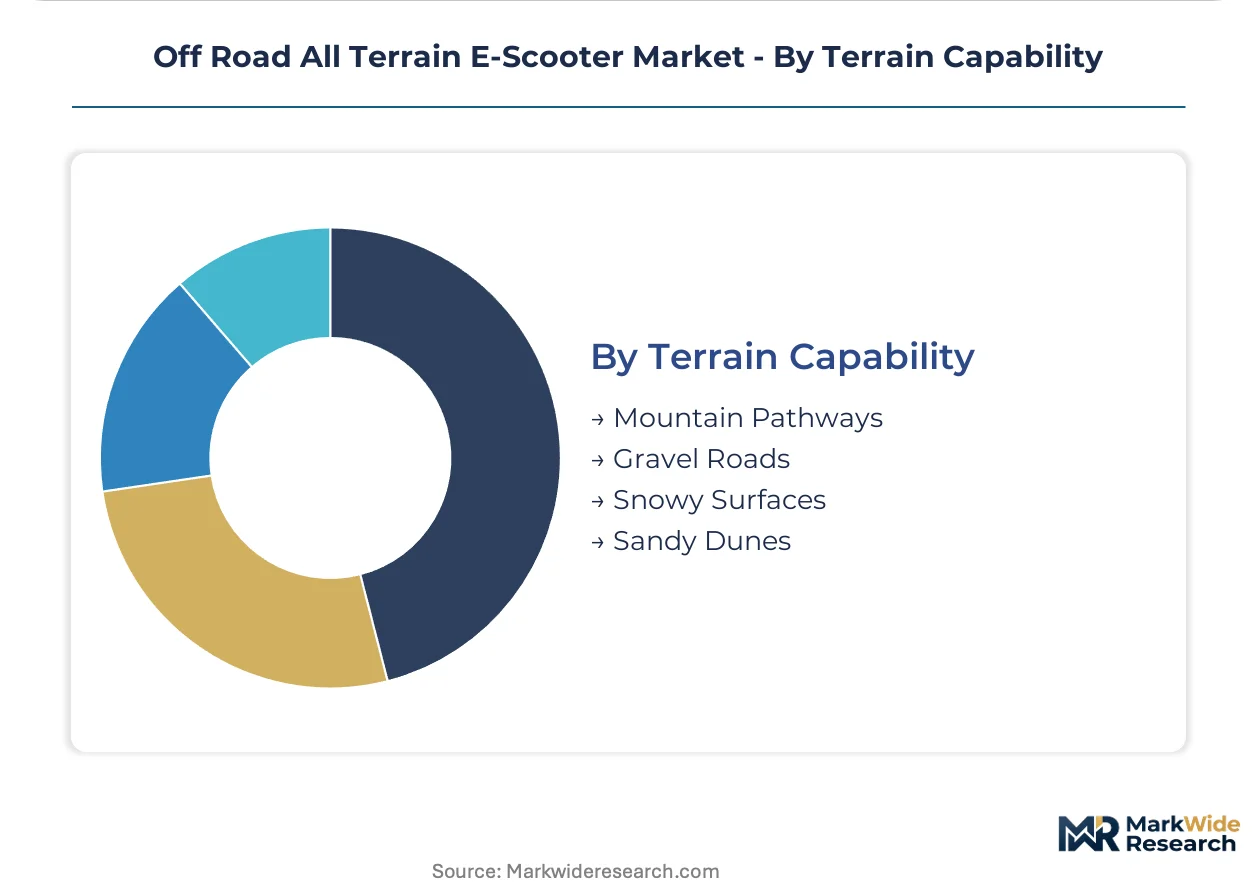
Terrain Capability:
Surface-rated component specifications determine tire compound selection, seal tolerances, and frame fatigue testing protocols.
- Mountain Pathways:Knobby tread patterns with 10-inch minimum diameter and reinforced sidewalls sustain root and rock impact loads. British Columbia's adventure tourism licensing framework mandates these ratings for commercial operation on designated technical trails.
- Gravel Roads:Intermediate tread designs balance rolling resistance with loose-surface traction for Germany's forest service route networks.
- Sandy Dunes:Paddle-tire configurations with reduced inflation pressure requirements target Australia's coastal tourism corridors.
- Snowy Surfaces:Carbide-studded tire options with sealed bearing upgrades enable winter operation in Colorado's Nordic trail systems.
Mountain Pathways specifications anchor fleet procurement standards. Sandy Dunes applications are expanding most quickly within coastal tourism development zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Germany's automotive belt and China's electronics manufacturing zones anchor production capacity for off-road e-scooter drivetrains and battery management systems.
United States
Adventure tourism operators in Colorado's alpine corridors and British Columbia's trail networks drive fleet procurement of enhanced suspension configurations. EPA lithium-ion battery recycling standards shape end-of-life compliance costs for domestic assemblers. Denver and Vancouver anchor commercial deployment density where rental operators negotiate per-kilometer service agreements.
Germany
Outdoor enthusiasts in the Black Forest region sustain technical specification demands for dual-motor architectures with IPX6-rated drivetrain protection. EU Green Deal micromobility incentives accelerate battery technology upgrades across outdoor tourism licensing frameworks. Stuttgart's engineering clusters concentrate suspension calibration expertise serving commercial fleet operators.
China
MIIT GB standards for motor power classification and battery safety testing determine export eligibility for manufacturers serving high-elevation markets. Shenzhen and Dongguan electronics corridors dominate lithium-ion cell and controller module production. Zhejiang province fabricators supply folding frame hinge mechanisms for European multimodal transit integration.
Australia
Remote logistics contractors across the Outback prioritize route-optimized battery swapping protocols for station-to-station cargo movement. The country's national environmental regulator enforces end-of-life electronics stewardship obligations on commercial fleet operators. Queensland coastal tourism corridors expand sandy terrain paddle-tire deployments.
Canada
Mountain pathway riders in British Columbia adopt regenerative braking systems fastest where vertical drop exceeds 800 meters per circuit. Health Canada governs electrical safety certification for personal mobility devices entering commercial rental service. Whistler and Banff anchor high-elevation fleet utilization testing for descent energy recovery mechanisms.
Off Road All Terrain E-Scooter Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the off-road e-scooter landscape, with integrated manufacturers controlling casting and motor winding operations while specialist brands outsource frame fabrication and final assembly. The vendor base stratifies across three tiers: multinational electronics conglomerates with captive battery supply, mid-scale outdoor equipment specialists with regional service networks, and direct-to-consumer pure-plays leveraging social media acquisition channels. Dominant competitive moves include backward integration into lithium-ion cell pack assembly and geographic expansion through outcome-based fleet service contracts that transfer maintenance liability from rental operators.
Within the multinational tier, Segway-Ninebot and Xiaomi Corporation exemplify scale-driven positioning anchored by electronics manufacturing ecosystems. Among specialist fabricators, Kaabo occupies a position representing dual-motor technical credibility, while Apollo Scooters sits within the direct-to-consumer archetype emphasizing channel margin capture. These three anchors illustrate how competitive positioning fragments across manufacturing scale, technical specialization, and distribution control rather than consolidating around unified platform strategies.
| Leading Market Players |
|---|
| Apollo Scooters |
| Inokim |
| Segway-Ninebot |
| Varla Scooter |
| EMOVE |
| Kaabo |
| Xiaomi Corporation |
| Kugoo |
| Dualtron |
| Others |
Value Network & Pricing Analysis
Adventure tourism fleet operators in Colorado and British Columbia anchor demand concentration for commercial-grade enhanced suspension models, driving outcome-based per-kilometer service agreements that transfer hardware ownership from rental operators to manufacturers with captive maintenance networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by motor power classification and suspension travel specifications. Price differentiation stems from IPX6 versus IPX5 ingress protection ratings and dual-motor versus single-motor architectures. Cost compression in entry-tier folding frame configurations is intensifying because China's MIIT GB standard certification creates single-point eligibility bottlenecks. Urban commuters in Germany exhibit highest price sensitivity, while outdoor enthusiasts in the Black Forest region accept premium positioning for field-serviceable controller specifications.
Supply Chain Analysis
Dual-sourcing requirements for lithium-ion cell packs are emerging among EU-based assemblers seeking to mitigate single-point dependencies on China's Shenzhen and Dongguan electronics corridors. Raw material flows draw from South Korean cathode suppliers, Australian lithium spodumene, and Japanese electrolyte formulators. Tariff exposure on controller modules shipped from Zhejiang province threatens margin structures for North American direct-to-consumer brands. Distribution runs through manufacturer-direct channels and adventure tourism fleet procurement offices, bypassing traditional outdoor retail intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Off-road e-scooter demand functions as a stable compounder, with EU Green Deal carbon-reduction mandates embedding micromobility incentives into outdoor tourism licensing frameworks that sustain replacement cycles.
For Market Incumbents: Cement technical credibility advantages by embedding active suspension telemetry into fleet management platforms, automating real-time damping adjustments that reduce technician training burdens. Deepen backward integration into lithium-ion cell pack assembly to offset EPA recycling compliance cost compression. Lock in long-term service contracts with British Columbia adventure tourism operators before regenerative braking system commoditization erodes differentiation. For New Entrants and Emerging Players: Direct-to-consumer social media acquisition channels offer the most penetrable entry vector for folding frame variants targeting Germany's Deutsche Bahn multimodal commuters. White-space exists in Australia's Outback remote logistics contractor segment, where route-optimized battery swapping protocols remain undersupplied by incumbent service networks. Pursue outcome-based utilization contracts that unbundle hardware ownership from maintenance liability, mirroring rental fleet procurement pivots in Queensland coastal tourism corridors. For Investors and Strategic Acquirers: Outdoor equipment conglomerates with regional service networks are the most active acquirer in this space, seeking dual-motor technical specialists to fill portfolio gaps. Long-term viability rests on battery certification reciprocity between EU and North American regulatory frameworks, which would reconfigure supply chain routing requirements and reward early positioning. Watch for MIIT GB standard amendments affecting motor power classification thresholds as the inflection signal for export eligibility disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Active Suspension Telemetry Integration | Automated damping adjustments compress the technical gap between commercial fleets and individual enthusiasts. |
| Battery Certification Reciprocity Investment | EU-North America mutual recognition agreements would reconfigure cross-border supply chain routing requirements. |
| Outcome-Based Fleet Service Contracts | Per-kilometer agreements transfer maintenance liability from Australia's Outback rental operators to manufacturers. |
| Dual-Motor Architecture Scale-Up | Peak output configurations toward 5,000W sustain technical credibility among British Columbia mountain pathway riders. |
| Regenerative Braking System Deployment | Descent energy recovery extends range in Colorado high-elevation markets where midday charging infrastructure is absent. |
Research Methodology
Bottom-up adventure tourism fleet procurement modeling reconciled against top-down lithium-ion cell production tracking forms the analytical core of this study. Primary interviews with suspension calibration technicians, outdoor rental fleet managers, battery management system engineers, and EU regulatory affairs specialists were cross-validated against secondary sources including MIIT GB standard filings, EPA lithium-ion recycling guidance documents, ECHA REACH pre-certification registries, and Deutsche Bahn multimodal transit compatibility specifications. Triangulation between demand-side utilization data and supply-side manufacturing capacity estimates ensures segmentation integrity across folding frame and enhanced suspension product architectures.
Historical trendline analysis of fleet replacement cycles and battery technology upgrade intervals informed the projection framework. Modeled dimensions span product type, end user archetype, power source configuration, and terrain capability rating, with regional regulatory cluster overlay capturing EU Green Deal incentive alignment versus EPA compliance cost burdens. CAGRs were derived from segment-level growth rate reconciliation against aggregate market value expansion. Industry-specific forecast inputs include elevation profile data from Colorado alpine corridors and Australia's Outback traverse requirements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery certification reciprocity timeline acceleration and MIIT GB standard amendment trajectories. Deviation in EU-North America mutual recognition agreement negotiations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Four-Wheel Drive Vehicles Market
Off Road Vehicles
Off-Highway Vehicle HVAC Market
Off Road Vehicles
Off-Road Vehicle Market
Off Road Vehicles
Off Highway Vehicles Brake Systems Market
Off Road Vehicles
Off-Road High Performance Vehicle Market
Off Road Vehicles
Small Off-Road Engines Market
Off Road Vehicles
Off Road Motorcycles Market
Off Road Vehicles
Off-Highway Engine Market
Off Road Vehicles
Off Highway Vehicle Lighting Market
Off Road Vehicles
Europe Off-Highway Vehicle HVAC Market
Off Road Vehicles
Middle East and Africa Utility Terrain Vehicles Market
Off Road Vehicles
Snowmobile Market
Off Road Vehicles
Electric Off-Road Vehicles Market
Off Road Vehicles
Snow Scooter Market
Off Road Vehicles
US Off-Road Vehicles Market
Off Road Vehicles
Automotive and Off-Road Vehicle Hoses Market