
 Middle East and Africa Utility Terrain Vehicles Market | 2026-2036
Middle East and Africa Utility Terrain Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Utility Terrain Vehicles Market Analysis
Skilled off-highway vehicle technician availability is rotating toward shortage across the Middle East and Africa, constraining aftermarket service capacity and pushing OEMs to expand dealer training networks. Polaris Inc. leverages its regional distribution infrastructure to sustain parts availability in remote mining and agricultural zones. BRP Inc. anchors its competitive stance through specialized desert-performance configurations engineered for Gulf climate extremes. Honda Motor Co. differentiates via engine durability reputations forged in African commercial farming applications.
Utility Terrain Vehicles are four-wheeled motorized platforms typically powered by internal combustion or electric drivetrains, engineered with side-by-side seating, cargo beds rated for substantial payloads, and suspension systems calibrated for unimproved terrain traversal across desert, savanna, and semi-arid environments. Diesel UTVs dominate commercial end-use owing to torque density and fuel accessibility across remote African operations, while electric UTVs represent the fastest-expanding product category as Gulf state energy diversification mandates reshape fleet procurement criteria. Four-Wheel Drive configurations command premium positioning in construction and military applications where traction failure carries operational cost penalties.
Saudi Arabia's SFDA product safety protocols intersect with UAE MOHAP equipment import standards to create a dual-compliance burden for manufacturers seeking Gulf market entry, while South Africa's Department of Transport administers quad bike homologation requirements that filter substandard imports from Eastern supply sources. Kenya's KEBS quality marks and Nigeria's SON certification add further layering for East and West African distribution strategies. Stakeholders must monitor how Gulf carbon-neutrality timelines and African agricultural mechanization subsidies converge to reshape powertrain mix decisions across the forecast horizon.
Market Dynamics
Powertrain electrification mandates across Gulf Cooperation Council states are restructuring procurement criteria for fleet operators, forcing simultaneous compliance with Saudi SFDA safety protocols and UAE MOHAP import standards while diesel infrastructure persists across African commercial farming zones.
Growth Catalysts
- Vision 2030 Giga-Projects:Saudi Arabia's tourism and construction megadevelopments are generating sustained fleet procurement volume for side-by-side vehicle operators.
- Agricultural Mechanization Subsidies:Smallholder and commercial farms across Kenya and Nigeria are accelerating diesel UTV purchases to replace animal traction and manual labor.
- Gulf Carbon-Neutrality Timelines:UAE and Saudi energy diversification mandates are reshaping fleet procurement criteria toward electric powertrains in municipal and recreational applications.
Market Restraints
- Dual-Compliance Burden:Intersecting Saudi SFDA and UAE MOHAP standards create certification friction for manufacturers seeking Gulf market entry.
- Technician Shortage:Skilled off-highway vehicle technician availability is rotating toward shortage across the region, constraining aftermarket service capacity.
- Fuel Infrastructure Asymmetry:Diesel accessibility in remote African operations contrasts with electric charging deserts, fragmenting powertrain viability by geography.
Strategic Opportunities
- East African Distribution Expansion:Kenya's KEBS quality mark adoption creates a certification pathway for manufacturers to establish regional hub operations.
- Desert-Performance Configuration Demand:Specialized suspension and cooling systems engineered for Gulf climate extremes represent premium product white space.
- Dealer Training Network Gaps:OEM investment in technician certification programs addresses the aftermarket service vacuum in remote mining and agricultural zones.
Industry Challenges
- Homologation Timeline Compression:South Africa's Department of Transport quad bike safety enforcement is accelerating certification deadlines without corresponding testing capacity expansion.
- Parts Availability Logistics:Remote mining and agricultural zones require inventory pre-positioning strategies that strain working capital and distribution economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Utility Terrain Vehicles Market |
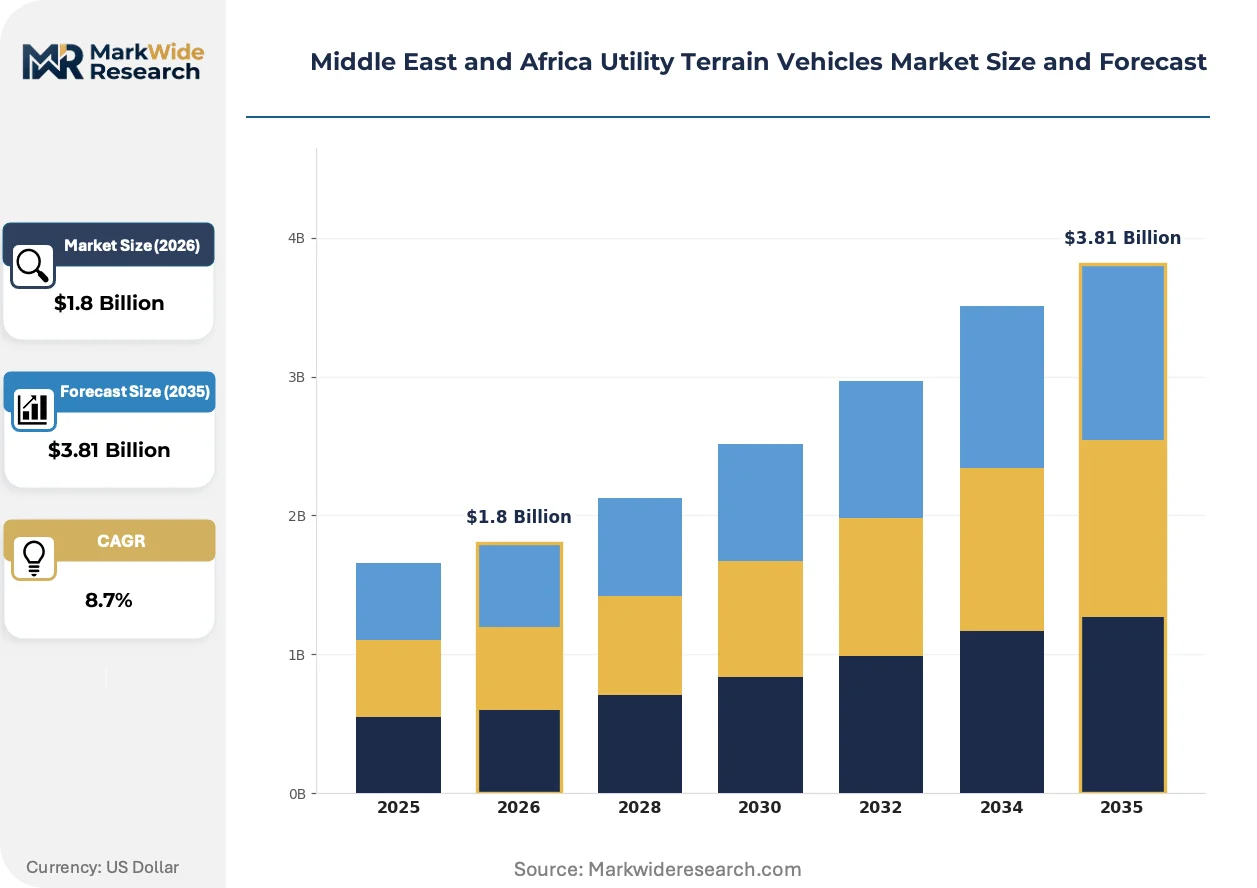
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard UTVs, Racing UTVs, Diesel UTVs, Electric UTVs End User: Agriculture, Construction, Military, Recreation Engine Capacity: 300cc, 500cc, 800cc, 1000cc Drive Type: Two-Wheel Drive, Four-Wheel Drive, All-Wheel Drive, Continuous Variable Transmission |
| Companies Covered | Polaris Inc., BRP Inc., Honda Motor Co., Yamaha Motor Co., Kawasaki Heavy Industries, John Deere, CFMOTO, Kubota, Club Car, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Utility Terrain Vehicles Market Emerging Trajectories
Electrification is bifurcating product development roadmaps between Gulf state fleet mandates and African diesel dependency, while regulatory layering across multiple national standards is elevating compliance engineering to a core competitive capability.
Lithium-ion battery packs with thermal management systems calibrated for 50°C ambient operation are supplanting lead-acid configurations in Gulf municipal fleet tenders. Dubai's waste management and airport ground services divisions are specifying these systems for 2025-2027 procurement cycles. The technology is compressing total cost of ownership calculations against diesel equivalents across 10,000-hour utilization benchmarks.
Saudi SFDA product safety protocols now intersect with UAE MOHAP equipment import standards to create overlapping testing requirements for rollover protection and occupant restraint systems. Manufacturers must maintain dual certification documentation for Gulf market access. Construction and military applications face the steepest compliance cost escalation given their four-wheel-drive configuration premiums.
Fleet operators are consolidating procurement decisions at the emirate and provincial level rather than individual site level, compressing vendor negotiation cycles and elevating volume discount thresholds. Tier-one distributors are displacing fragmented dealer networks in Saudi Arabia's Neom and Red Sea Project zones. This concentration is most visible in municipal and tourism fleet segments where standardization reduces maintenance parts complexity.
Middle East and Africa Utility Terrain Vehicles Market Segmentation
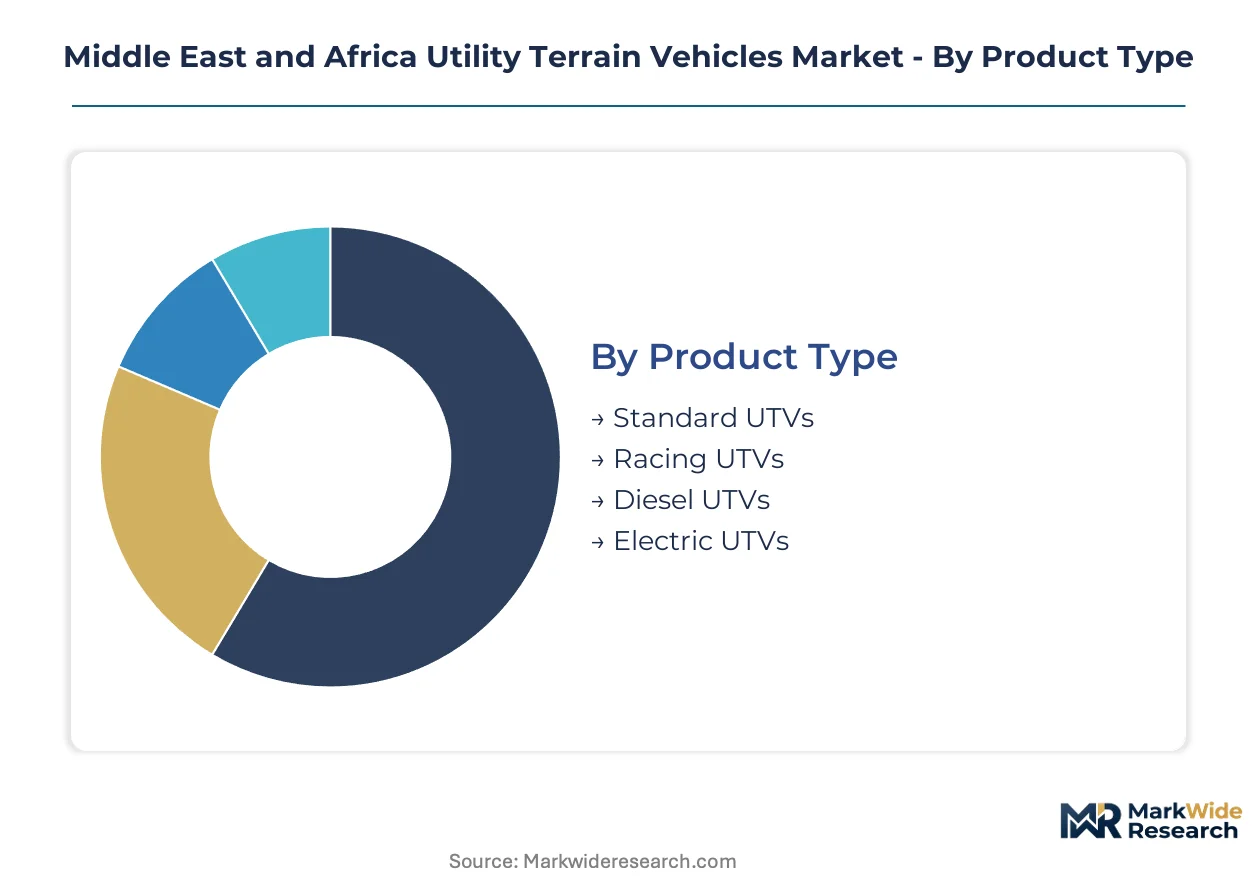
Powertrain electrification mandates and agricultural mechanization subsidies are fragmenting demand patterns across the Middle East and Africa Utility Terrain Vehicles Market. Segment performance diverges sharply between Gulf state fleet procurement criteria and African commercial farming requirements.
Product Type:
Electric UTVs face substitution pressure from diesel alternatives in remote African zones lacking charging infrastructure, while Gulf carbon-neutrality timelines accelerate fleet electrification mandates.
- Standard UTVs:Side-by-side platforms with internal combustion or electric drivetrains, cargo beds rated for substantial payloads, and suspension calibrated for unimproved terrain. Demand concentrates in Saudi Arabia's Vision 2030 giga-projects where fleet standardization reduces maintenance complexity across Neom and Red Sea Project zones.
- Electric UTVs:Lithium-ion battery packs with thermal management systems engineered for 50°C ambient operation, supplanting lead-acid configurations in municipal tenders. Dubai's waste management and airport ground services divisions specify these systems for procurement cycles, compressing total cost of ownership against diesel equivalents across high-utilization benchmarks.
- Diesel UTVs:Torque-dense powertrains dominating commercial end-use across Kenya and Nigeria where fuel accessibility persists in remote agricultural operations.
- Racing UTVs:High-performance configurations with reinforced suspension and enhanced power-to-weight ratios serving recreational demand in UAE desert tourism clusters.
Standard UTVs retain volume leadership; Electric UTVs hold the steepest expansion curve.
End User:
Cost tier stratification separates premium military specifications from subsidized smallholder agricultural procurement across the region.
- Agriculture:Mechanization subsidies accelerate diesel UTV purchases across smallholder and commercial farms in Kenya and Nigeria, displacing animal traction and manual labor. Kenya's KEBS quality mark adoption creates certification pathways for regional hub establishment.
- Construction:Four-wheel-drive configurations command premium positioning in Saudi giga-projects where traction failure carries operational cost penalties across desert construction sites.
- Military:Specialized armor-compatible platforms with enhanced payload ratings for tactical logistics in terrain-constrained environments.
- Recreation:Desert-performance configurations engineered for Gulf climate extremes, serving tourism fleet demand in UAE and Saudi Arabia.
Agriculture retains volume leadership; Construction holds the steepest expansion curve.
Engine Capacity:
Application maturity determines volume concentration, with mid-range displacements serving established agricultural workflows while larger engines penetrate emerging commercial segments.
- 800cc:Balanced power-to-efficiency ratio dominating commercial farming applications across Nigeria and Kenya where load hauling requirements intersect with fuel economy constraints.
- 1000cc:High-torque configurations preferred in construction and military applications requiring sustained performance under heavy payload conditions in Saudi Arabia's desert environments.
- 500cc:Entry-level displacement serving smallholder agricultural mechanization with lower capital barriers.
- 300cc:Compact platforms for recreational and light utility applications in UAE tourism zones.
800cc retains volume leadership; 1000cc holds the steepest expansion curve.
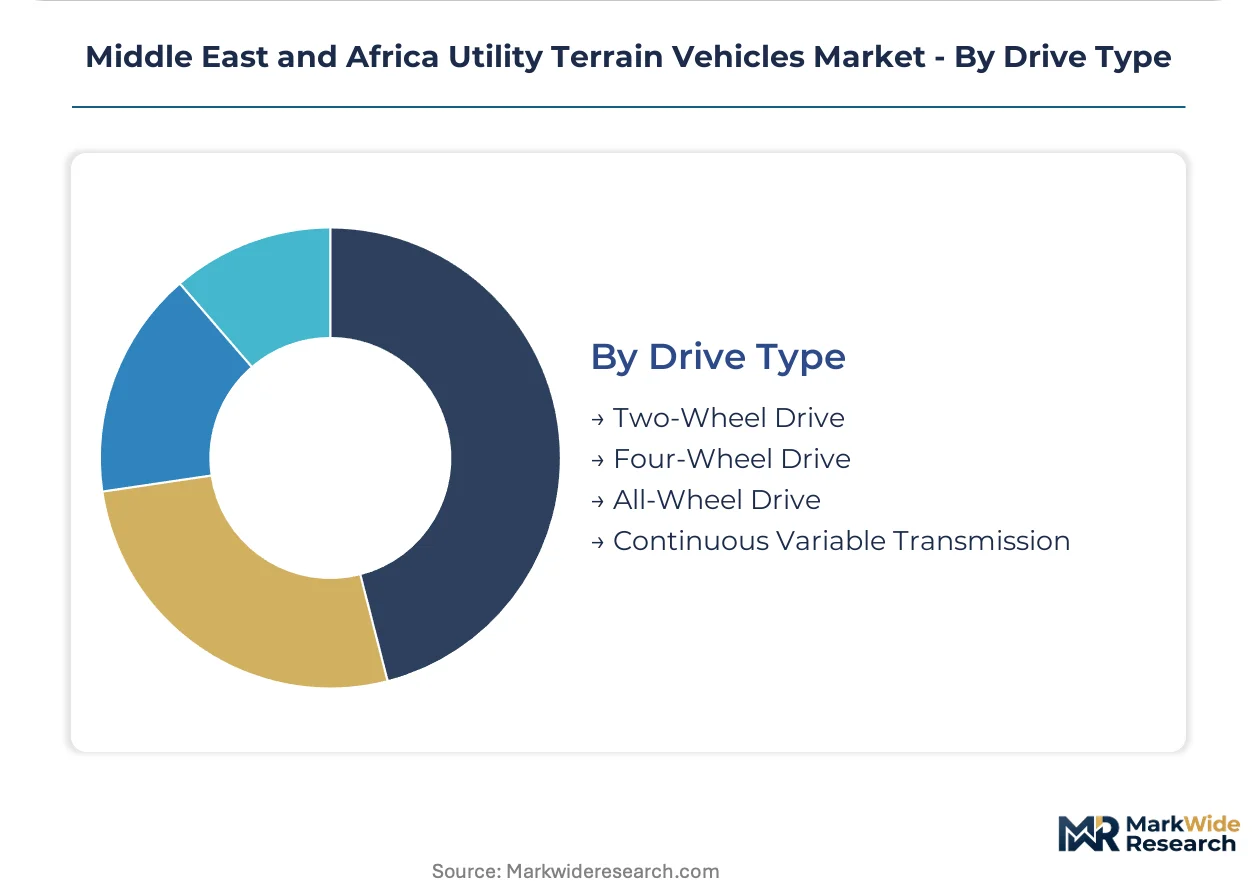
Drive Type:
Supply concentration in four-wheel-drive component manufacturing elevates procurement costs for traction-critical applications versus two-wheel-drive alternatives.
- Four-Wheel Drive:Differential-locking configurations commanding premium positioning in construction and military applications where traction failure carries operational cost penalties across Saudi giga-projects and South African mining zones.
- All-Wheel Drive:Continuous torque-vectoring systems gaining preference in municipal fleet tenders across Dubai and Riyadh where variable terrain demands adaptive traction.
- Two-Wheel Drive:Simplified mechanical architecture reducing acquisition cost for agricultural applications on improved rural roads.
- Continuous Variable Transmission:Seamless power delivery optimizing engine efficiency across variable load conditions in commercial farming operations.
Four-Wheel Drive retains volume leadership; All-Wheel Drive holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia and the UAE deploy UTVs primarily in municipal fleet and tourism applications, while Nigeria and Kenya concentrate procurement in agricultural mechanization. South Africa splits demand between mining operations and recreational desert tourism. This consumption-mix differential fragments powertrain and specification requirements across the region.
Saudi Arabia
Vision 2030 giga-projects including Neom and the Red Sea Project generate sustained fleet procurement volume for construction and tourism operators. The Saudi Food and Drug Authority enforces rollover protection and occupant restraint system standards that elevate certification costs for imported platforms. Riyadh and the Eastern Province concentrate municipal fleet consolidation decisions, compressing vendor negotiation cycles through emirate-level procurement.
United Arab Emirates
Dubai's waste management and airport ground services divisions specify lithium-ion UTVs with thermal management for 50°C ambient operation in 2025-2027 procurement cycles. The Ministry of Health and Prevention administers equipment import standards that intersect with Saudi protocols to create dual-compliance burdens. Abu Dhabi anchors municipal fleet standardization efforts, displacing fragmented dealer networks with tier-one distributor relationships.
South Africa
Mining operations in the Northern Cape and North West provinces sustain demand for four-wheel-drive configurations with differential-locking systems. The Department of Transport enforces quad bike homologation requirements that filter substandard imports from Eastern supply sources. Johannesburg-Pretoria corridor clusters aftermarket service capacity, though technician availability is rotating toward shortage.
Nigeria
Smallholder and commercial farms in the northern grain belt and cocoa-growing southwest accelerate diesel UTV purchases to displace animal traction. The Standards Organisation of Nigeria certification adds layering for West African distribution strategies. Lagos and Kano serve as import gateways where fuel infrastructure asymmetry favors torque-dense powertrains over electric alternatives.
Kenya
Mechanization subsidies drive diesel UTV adoption across the Rift Valley wheat and maize zones. The Kenya Bureau of Standards quality mark adoption creates certification pathways for manufacturers establishing regional hub operations. Nairobi anchors East African distribution expansion, with Mombasa port handling transshipment to landlocked neighbors.
Middle East and Africa Utility Terrain Vehicles Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the top tier commanding premium positioning through established distribution infrastructure and certification expertise. The middle tier fragments across regional specialists and agricultural equipment diversifiers. Two strategic archetypes dominate: Gulf-focused fleet solution providers leveraging municipal tender relationships, and Africa-oriented agricultural mechanization platforms optimized for diesel torque and parts availability. Competitive moves concentrate on dealer training network expansion to address technician shortages, and thermal management engineering for 50°C ambient operation specifications.
Within the integrated leader tier, Polaris Inc. and BRP Inc. occupy positions anchored by regional distribution infrastructure and desert-performance specialization respectively. Honda Motor Co. sits within the durability-focused agricultural tier, exemplifying engine reliability reputations forged in African commercial farming applications. These three represent distinct competitive vectors: fleet-scale procurement capability, climate-extreme engineering, and long-cycle commercial reliability.
| Leading Market Players |
|---|
| Polaris Inc. |
| BRP Inc. |
| Honda Motor Co. |
| Yamaha Motor Co. |
| Kawasaki Heavy Industries |
| John Deere |
| CFMOTO |
| Kubota |
| Club Car |
| Others |
Supply Flow & Price Mechanics
Lithium-ion battery packs displacing lead-acid configurations in Gulf municipal fleets simultaneously redraw component sourcing maps toward East Asian cell manufacturers and compress total cost of ownership benchmarks against diesel equivalents across high-utilization procurement cycles.
Pricing Analysis
Long-term offtake contracts dominate fleet procurement in Saudi Arabia's Vision 2030 giga-projects, with municipal tenders specifying thermal management systems for 50°C ambient operation as a price differentiation driver alongside volume scale discounts. Spot-market transactions persist for aftermarket parts in remote African mining zones where inventory pre-positioning costs elevate pricing. Price erosion runs through standard two-wheel-drive agricultural configurations as Kenyan and Nigerian mechanization subsidies expand addressable demand among smallholder buyers least sensitive to premium features.
Supply Chain Analysis
Strategic stockpiling of differential-locking four-wheel-drive components characterizes procurement behavior in South African mining corridors, contrasting with just-in-time lithium-ion cell delivery schedules for Dubai municipal fleets. Manufacturing concentration in China, Japan, and South Korea feeds powertrain and battery assembly operations, while steel chassis fabrication anchors in Turkey and India for regional distribution efficiency. Single-source vulnerability concentrates in thermal management system suppliers serving Gulf climate specifications. Distribution runs through tier-one distributors consolidating Saudi Arabia's Neom and Red Sea Project zones, displacing fragmented dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment via Saudi SFDA and UAE MOHAP dual-certification requirements creates substantial switching costs for fleet operators standardized on approved vendor platforms.
For Market Incumbents: Consolidate dealer training network coverage across Kenya's Rift Valley and Nigeria's northern grain belt to preempt technician shortage constraints from constraining aftermarket service capacity. Deepen backward integration into thermal management system engineering for 50°C Gulf specifications, insulating margin position from single-source component vulnerability as electric fleet mandates accelerate procurement criteria shifts. For New Entrants and Emerging Players: Kenya's KEBS quality mark adoption offers a certification fast-track for manufacturers establishing regional hub operations without navigating South Africa's compressed homologation timelines. Target diesel UTV configurations for smallholder agricultural mechanization in Nigeria's cocoa-growing southwest, where fuel infrastructure asymmetry deflects electric substitution pressure and parts availability logistics remain underserved by incumbent distribution density. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed agricultural equipment diversifiers holding Kenyan and Nigerian distribution infrastructure but lacking Gulf fleet tender relationships. Five-to-ten year viability hinges on powertrain mix flexibility across diesel dependency in African commercial farming and electrification mandates in Gulf municipal procurement. Watch for Saudi carbon-neutrality timeline acceleration as the inflection signal compressing diesel residual value assumptions.| Strategic Initiative | Industry Significance |
|---|---|
| Dealer Training Network Expansion | Addresses technician shortage constraints across Kenya's Rift Valley wheat zones and South African mining corridors. |
| Thermal Management Engineering Investment | Secures 50°C ambient operation specifications in Dubai waste management and Riyadh municipal fleet tenders. |
| Regional Hub Establishment | Leverages Kenya's KEBS quality mark adoption for East African distribution expansion into landlocked neighbors. |
| Powertrain Portfolio Diversification | Balances diesel torque density for Nigerian agricultural operations against electric mandates in UAE municipal procurement. |
| Dual-Certification Compliance Investment | Navigates overlapping Saudi SFDA and UAE MOHAP standards to unlock Gulf Cooperation Council fleet access. |
Methodological Framework
Operator-level perspectives from fleet procurement managers at Saudi giga-projects, Dubai municipal services divisions, Kenyan agricultural cooperatives, and South African mining maintenance directors anchored the qualitative base. Primary interviews triangulated against secondary validation from customs trade records, Standards Organisation of Nigeria certification databases, Kenya Bureau of Standards quality mark registries, and Saudi Food and Drug Authority product safety filings. Bottom-up unit economics across powertrain configurations reconciled with top-down market sizing from regional production and import data.
Sensitivity analysis tested forecast robustness across electrification mandate acceleration scenarios and African agricultural subsidy persistence assumptions. The analytical framework modeled segmentation across powertrain type, end-use application, engine capacity tier, and drive configuration throughout the projection horizon. CAGRs derived from regression analysis of historical fleet procurement cycles, overlaying policy-driven demand inflections from Vision 2030 infrastructure timelines and Gulf carbon-neutrality commitments. Industry-specific inputs incorporated technician availability indices and lithium-ion cell cost curves.
Decision-makers should treat outputs as directional under assumptions of sustained Saudi giga-project execution and stable African agricultural mechanization subsidy regimes; material deviation in either would warrant model refresh. Revision becomes warranted when Gulf electric fleet procurement thresholds cross 50% of annual municipal tender volume or when South African homologation testing capacity constraints trigger import approval delays exceeding six months.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
All-Terrain Vehicle (ATV) Engines Market
Off Road Vehicles
Snow Scooter Market
Off Road Vehicles
Off Road All Terrain E-Scooter Market
Off Road Vehicles
Hybrid Off-Road Vehicle Market
Off Road Vehicles
Amphibious ATV Market
Off Road Vehicles
Off Highway Hybrid Vehicles Market
Off Road Vehicles
Off-Highway Electric Vehicle Market
Off Road Vehicles
Off-Highway Vehicle Market
Off Road Vehicles
Off-Road Equipment Market
Off Road Vehicles
Global Off-Road Trailers Market
Off Road Vehicles
Utility Terrain Vehicles (UTV) Market
Off Road Vehicles
Off Road Motorcycles Market
Off Road Vehicles
Four-Wheel Drive Vehicles Market
Off Road Vehicles
Off-Highway Vehicle Engine Market
Off Road Vehicles
Snowmobile Market
Off Road Vehicles
Europe Off-Highway Vehicle HVAC Market