
 Off Highway Hybrid Vehicles Market | 2026-2036
Off Highway Hybrid Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Off Highway Hybrid Vehicles Market Analytics
Electrification-trained technician shortages across North American mining corridors is redrawing deployment timelines for hybrid construction fleets. Caterpillar Inc. leverages its Decatur, Illinois manufacturing complex to sustain integrated powertrain output for large excavators. Komatsu Ltd. anchors its hybrid loader strategy through Kobe-based component testing facilities. Deere & Company competes via its Waterloo, Iowa tractor engineering center focused on agricultural hybridization.
Off highway hybrid vehicles combine internal combustion engines with electric motor-generators and energy storage systems to deliver variable power output for heavy-duty cycles without grid dependency. Battery-electric assist enables peak shaving during digging or hauling operations while the diesel or alternative-fuel prime mover sustains baseline load and recharges cells. Parallel hybrid configurations dominate current mining and construction deployments due to mechanical simplicity and retrofit compatibility with existing drivetrain architectures. Series hybrid architectures are gaining traction in agriculture where constant-speed engine operation optimizes fuel efficiency during PTO-intensive fieldwork. Plug-in hybrid variants remain nascent in forestry applications where remote charging infrastructure constraints limit operational flexibility.
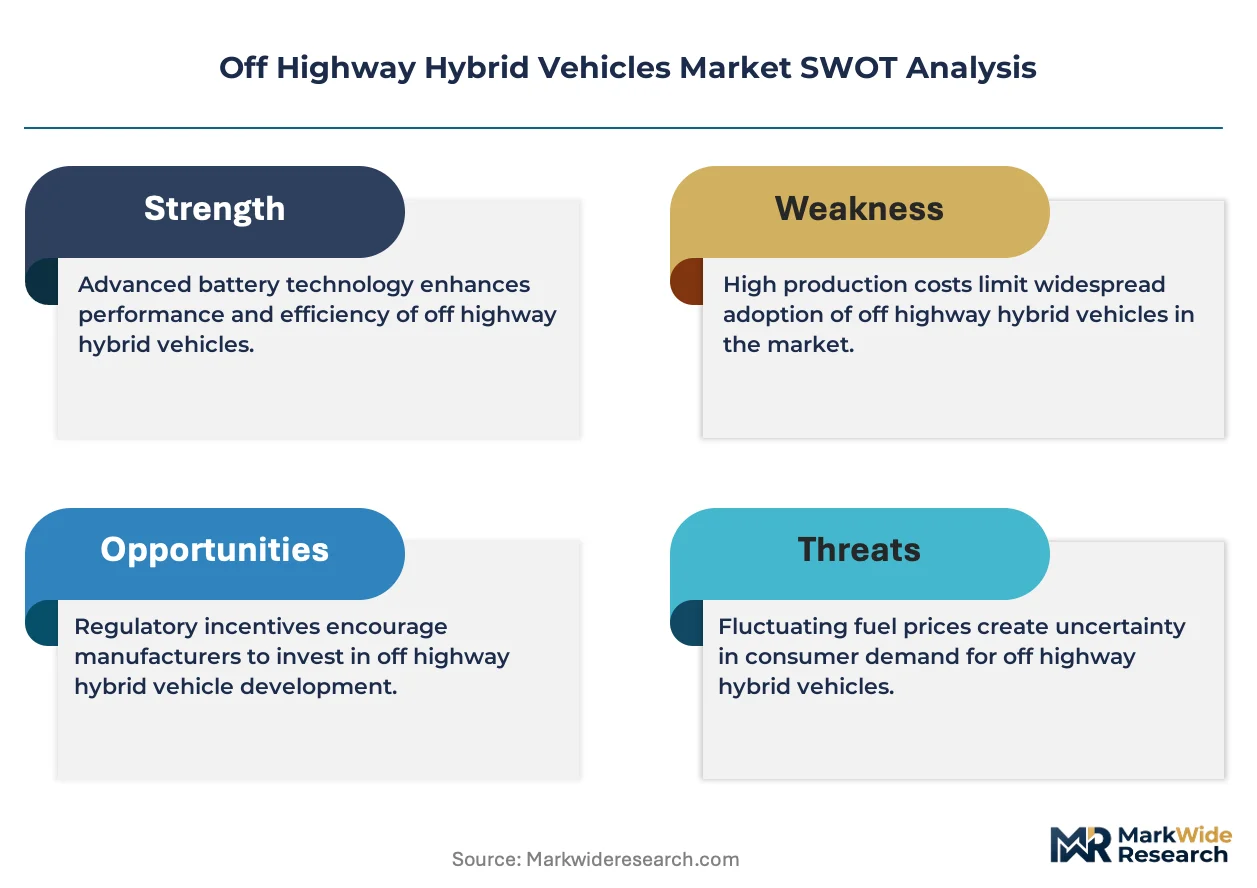
EPA Tier 4 Final and EU Stage V emission frameworks compel engine downsizing and aftertreatment integration that hybrid architectures accommodate more cost-effectively than conventional powertrains. China's MIIT dual carbon goals and GB 20891-2014 non-road emission standards are reshaping export compliance requirements for multinational OEMs serving Asian construction markets. Stakeholders must monitor battery supply chain localization mandates and carbon border adjustment mechanisms as these will determine landed cost competitiveness for hybrid fleet deployments across regulated jurisdictions.
Market Dynamics
EPA Tier 4 Final and EU Stage V emission standards are compressing diesel engine displacement limits, forcing powertrain architectures toward hybrid integration as the only viable path to maintain torque output without aftertreatment complexity. Mining fleet operators in Western Australia's Pilbara region now treat hybridization as a fuel logistics play rather than an emissions compliance tool.
Growth Catalysts
- Emission Standard Compression:EPA Tier 4 Final and EU Stage V frameworks mandate particulate matter and NOx reductions that hybrid architectures achieve more cost-effectively than conventional aftertreatment-heavy diesels. Construction fleets in Germany and California face procurement mandates favoring diesel-electric configurations.
- Fuel Logistics Arbitrage:Remote mining operations across Western Australia and northern Canada calculate hybrid payback periods against diesel trucking costs rather than fuel price alone. Battery-electric assist reduces refueling frequency for haul trucks operating beyond pipeline infrastructure.
- Power Density Demands:Hydraulic mining shovels and large wheel loaders require intermittent peak power that exceeds continuous diesel ratings. Supercapacitor and lithium-ion buffer systems enable right-sized prime movers without performance sacrifice.
Market Restraints
- Battery Supply Concentration:Cell manufacturing for heavy-duty hybrid applications concentrates in China and South Korea, exposing non-Asian OEMs to carbon border adjustment mechanisms and localization mandates that inflate landed powertrain costs.
- Technician Training Gaps:North American mining corridors face acute shortages of electrification-certified service personnel, extending deployment timelines for hybrid construction fleets by 18-24 months against original equipment delivery schedules.
- Alternative Fuel Substitution:Renewable diesel and hydrogen combustion engines are capturing R&D budgets from hybrid programs at agricultural OEMs, where constant-speed PTO operation favors single-fuel simplicity over dual-powertrain complexity.
Strategic Opportunities
- Forestry Plug-in Hybridization:Sweden and Finland's extensive grid-connected logging road networks enable opportunity charging for forwarders and harvesters, converting intermittent operation patterns into viable plug-in hybrid economics despite remote stand conditions.
- Retrofit Channel Development:Independent powertrain integrators in Texas and Alberta are building certified diesel-electric conversion programs for existing haul truck fleets, opening aftermarket revenue streams beyond OEM new-equipment cycles.
- Carbon Border Positioning:EU Carbon Border Adjustment Mechanism implementation is incentivizing battery pack assembly within European free trade zones, creating captive supply opportunities for hybrid powertrain producers with regional cell sourcing.
Industry Challenges
- Electrification Skill Scarcity:Mining maintenance departments lack personnel capable of diagnosing high-voltage inverter faults and thermal runaway precursors in battery modules, forcing reliance on OEM field service teams with 72-hour response windows.
- Legacy Fleet Integration:Mixed hybrid-conventional fleets require dual spare parts inventories and separate service bay configurations, complicating operational planning for contractors running blended equipment pools across multiple project sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off Highway Hybrid Vehicles Market |
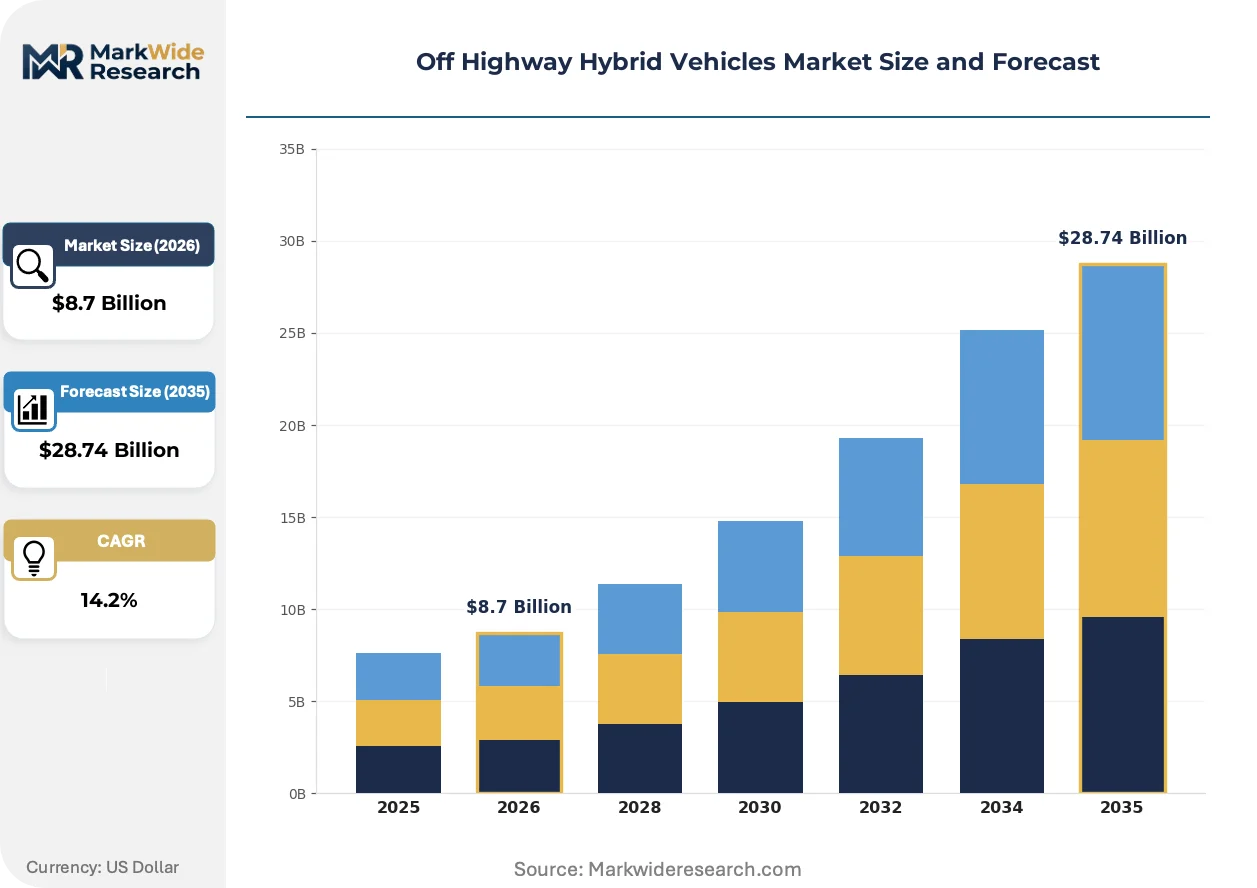
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Loaders, Bulldozers, Tractors Technology: Parallel Hybrid, Series Hybrid, Plug-in Hybrid, Mild Hybrid End User: Agriculture, Construction, Mining, Forestry Operating Environment: Off-road, Worksites, Farms, Industrial Sites |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Deere & Company, CNH Industrial N.V., Volvo Group, Hitachi Construction Machinery Co., Ltd., Liebherr Group, J C Bamford Excavators Ltd., Kobelco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off Highway Hybrid Vehicles Market Evolving Landscape
Power electronics packaging and thermal management systems are undergoing rapid densification, enabling hybrid powertrain integration into vehicle frames originally designed for mechanical drivelines. Component suppliers are compressing development cycles to match OEM platform refresh timelines.
Silicon carbide inverter modules are miniaturizing power conversion hardware for 800-volt hybrid architectures, reducing package volume by 40% against conventional IGBT designs. Underground mining equipment manufacturers in South Africa and Chile are adopting these compact inverters for continuous miner applications where machine envelope constraints previously excluded hybrid options. The technology is miniaturizing ancillary component placement, freeing frame rail space for enlarged battery packs without extending wheelbases.
EU Stage V compliance deadlines are accelerating software-defined engine control strategies that optimize diesel-electric load sharing in real time. Engine management systems now modulate generator loading to maintain exhaust temperatures within aftertreatment windows across variable duty cycles. Agricultural tractor producers serving France and Germany are deploying these calibrated hybrid maps for PTO-intensive field operations where engine speed stability directly impacts implement performance.
Fleet procurement committees are consolidating vendor relationships around full-lifecycle cost guarantees rather than upfront equipment pricing. Mining contractors in Western Australia now negotiate fuel consumption and maintenance cost ceilings as contract terms, shifting performance risk to OEMs and their financing partners. This restructuring concentrates purchasing power among operators with multi-site fleet scale, marginalizing smaller regional contractors from hybrid technology access.
Off Highway Hybrid Vehicles Market Segmentation
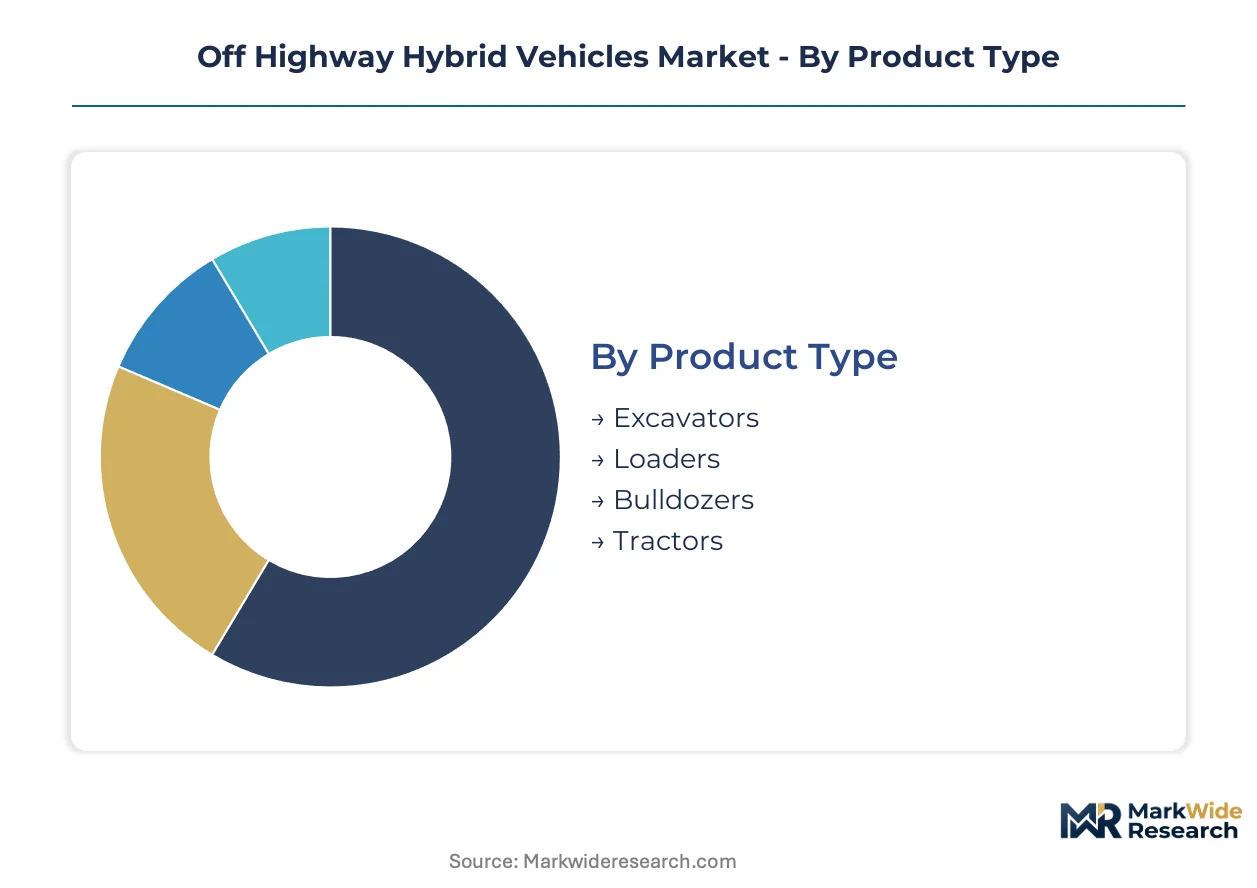
Hybrid powertrain architectures vary sharply in cost and complexity across vehicle categories, forcing OEMs to align product development with specific duty cycles and emission compliance timelines. Segment boundaries increasingly blur as modular battery platforms enable technology transfer between construction and agricultural applications.
Product Type:
Excavators and loaders dominate domestic procurement in Germany and Japan, while bulldozers and tractors concentrate in export-led demand across Brazil and India.
- Excavators:Diesel-electric configurations integrate motor-generators at the swing drive and hydraulic pump, enabling peak shaving during bucket loading cycles. Australian iron ore operators specify these for Pilbara fuel logistics savings against remote diesel trucking costs.
- Loaders:Parallel hybrid architectures with supercapacitor buffers dominate wheel loader deployments where intermittent peak power demands exceed continuous engine ratings. German construction fleets favor these for EU Stage V compliance without urea aftertreatment complexity.
- Bulldozers:Series hybrid traction drives optimize track power distribution across variable ground conditions.
- Tractors:PTO-integrated mild hybrids sustain constant engine speed for implement efficiency in row-crop operations.
Excavators command the established base. The steepest expansion runs through loaders.
Technology:
Cost tiers separate architectures by battery capacity and grid connectivity, with premium series configurations targeting mining and economy mild hybrids saturating agricultural volume.
- Parallel Hybrid:Mechanical coupling between diesel engine and electric motor preserves existing transmission infrastructure, minimizing retrofit costs for construction fleet operators. This architecture dominates Western Australian mining deployments where mechanical simplicity outweighs efficiency optimization.
- Series Hybrid:Complete decoupling of engine from drivetrain enables constant-speed operation at optimal efficiency points, though at 25-35% powertrain cost premiums. Agricultural OEMs serving France deploy these for PTO-intensive fieldwork where engine stability directly impacts implement performance.
- Plug-in Hybrid:Grid-chargeable battery packs extend electric-only operation for forestry forwarders on Sweden's electrified logging road networks.
- Mild Hybrid:Belt-integrated starter-generators provide torque assist without full electric drive capability, penetrating cost-sensitive tractor segments.
Parallel hybrid systems anchor current volume. Series architectures are gaining share fastest in regulated European markets.
End User:
Application-specific duty cycles dictate powertrain sizing, with mining's continuous high-load operation contrasting agriculture's intermittent PTO demands.
- Mining:Haul truck and shovel electrification focuses on fuel logistics arbitrage rather than emissions compliance in remote Western Australian and northern Canadian operations beyond pipeline infrastructure.
- Construction:Urban emission zones in California and Germany drive diesel-electric procurement for excavators and loaders facing EPA Tier 4 Final and EU Stage V mandates.
- Agriculture:Tractor hybridization emphasizes PTO output stability over fuel savings, with renewable diesel substitution threatening hybrid R&D budgets.
- Forestry:Plug-in viability depends on grid proximity along logging roads, limiting deployment to Nordic markets.
Mining commands the established base. Construction shows the steepest expansion trajectory.
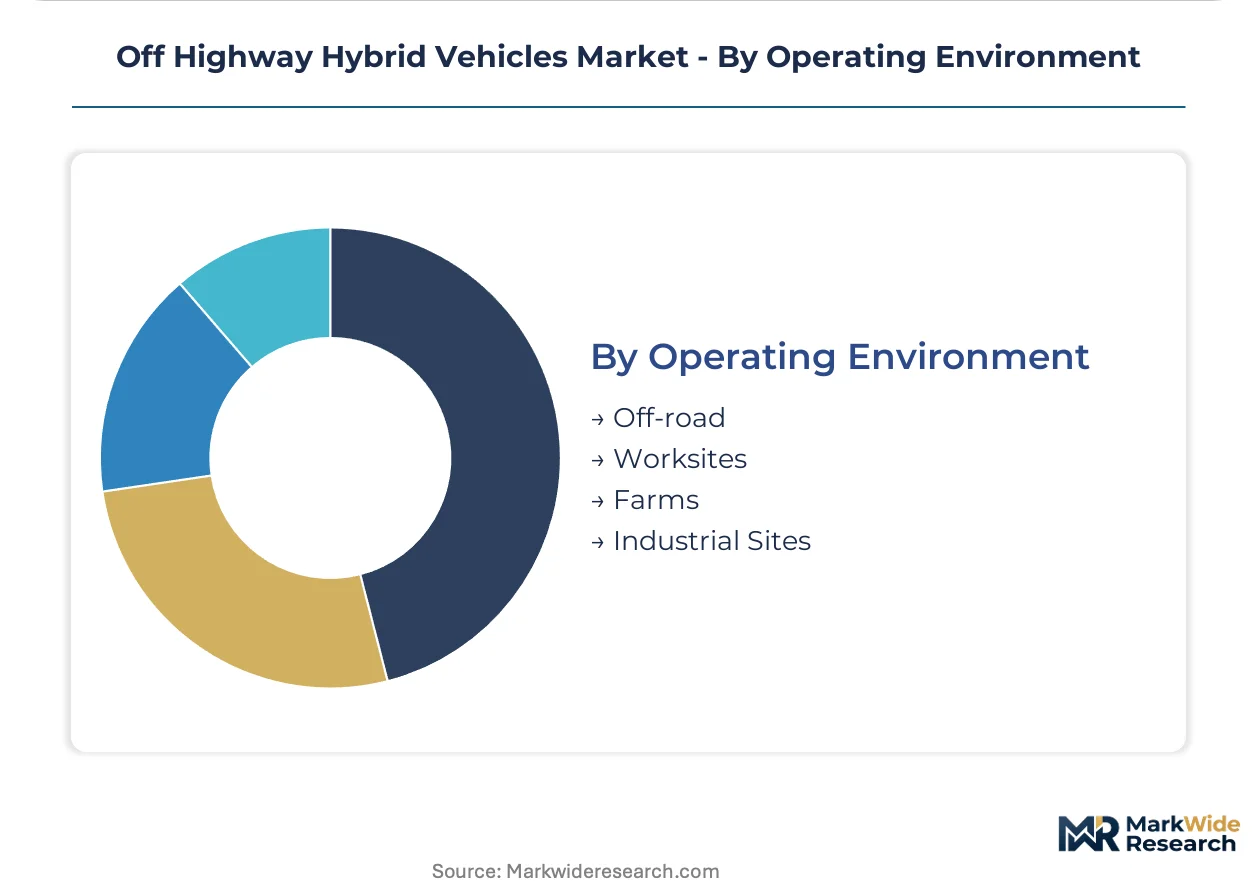
Operating Environment:
Site infrastructure availability separates electrification pathways, with grid-connected worksites enabling plug-in variants and fully off-road locations requiring self-contained hybrid systems.
- Off-road:Self-sufficient hybrid architectures dominate mining and remote construction where charging infrastructure is economically unviable, prioritizing diesel-electric range extension over grid dependency.
- Worksites:Intermittent grid access at German and Japanese construction zones enables opportunity charging for plug-in capable equipment during shift breaks.
- Farms:Barn and silo electrical infrastructure supports overnight charging for agricultural plug-in trials in Denmark and the Netherlands.
- Industrial Sites:Captive fleet operations at processing plants allow centralized charging depots for hybrid material handlers.
Off-road environments command the established base. Worksites demonstrate the steepest expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Tier 4 Final standards anchor North American demand compression, while EU Stage V frameworks reshape European procurement patterns. Mining corridors in Australia and agricultural zones across Brazil concentrate hybrid deployment against divergent infrastructure backdrops.
United States
Construction fleets in California face procurement mandates favoring diesel-electric configurations under EPA Tier 4 Final compliance deadlines. The EPA's emission frameworks compel engine downsizing that hybrid architectures accommodate more cost-effectively than conventional aftertreatment-heavy powertrains. Caterpillar leverages its Decatur, Illinois manufacturing complex to sustain integrated powertrain output for large excavators serving domestic mining and construction markets.
Germany
Urban emission zones and EU Stage V mandates drive diesel-electric procurement for excavators and loaders facing stringent particulate matter and NOx reduction requirements. The EU Green Deal and carbon border adjustment mechanisms are incentivizing battery pack assembly within European free trade zones. German construction fleets favor parallel hybrid loaders with supercapacitor buffers for compliance without urea aftertreatment complexity.
Australia
Western Australia's Pilbara iron ore region treats hybridization as a fuel logistics play rather than emissions compliance tool, calculating payback periods against remote diesel trucking costs. The country's mining safety regulators enforce stringent high-voltage system certification for underground equipment. Fleet operators across the Pilbara negotiate fuel consumption and maintenance cost ceilings as contract terms, shifting performance risk to OEMs.
China
MIIT dual carbon goals and GB 20891-2014 non-road emission standards reshape export compliance requirements for multinational OEMs serving Asian construction markets. The country's battery supply chain localization mandates expose non-Asian manufacturers to carbon border adjustment mechanisms. Domestic OEMs concentrate hybrid development for mining and agricultural segments where state procurement guidelines favor electrification.
Brazil
Agricultural tractor hybridization emphasizes PTO output stability over fuel savings, with renewable diesel substitution threatening hybrid R&D budgets at equipment producers. ANVISA and environmental regulators enforce emission standards aligning with EU Stage V benchmarks for imported machinery. Soybean and sugarcane operations in Mato Grosso and São Paulo states evaluate mild hybrid configurations against alternative fuel combustion engines for constant-speed fieldwork.
Off Highway Hybrid Vehicles Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the hybrid powertrain landscape. The market structure consolidates around integrated OEMs with captive engine manufacturing and independent powertrain integrators serving retrofit channels. Three archetypes dominate: full-line construction and mining equipment manufacturers, agricultural machinery specialists with PTO-integrated hybrid systems, and independent retrofit providers targeting existing haul truck fleets. Competitive moves concentrate on strategic partnerships for battery supply security and geographic expansion into mining corridors with fuel logistics arbitrage economics.
Among North American and Japanese equipment manufacturers, Caterpillar Inc., Komatsu Ltd., and Deere & Company exemplify distinct strategic positions. Caterpillar represents the integrated mining and construction archetype with captive powertrain manufacturing. Komatsu occupies a position within the hybrid loader segment anchored through component testing capabilities. Deere & Company sits within the agricultural machinery tier where PTO-integrated mild hybrids compete against renewable diesel substitution. These players collectively illustrate how divergent end-use economics—mining fuel logistics versus agricultural implement stability—shape technology portfolio priorities.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Deere & Company |
| CNH Industrial N.V. |
| Volvo Group |
| Hitachi Construction Machinery Co., Ltd. |
| Liebherr Group |
| J C Bamford Excavators Ltd. |
| Kobelco |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts for lithium-ion cells lock in supply access and price visibility for hybrid powertrain producers, insulating procurement costs against carbon border adjustment volatility while exposing non-Asian OEMs to localization mandates in China and South Korea. These contractual structures concentrate pricing power with cell manufacturers who dictate tiered supply commitments based on volume scale and geographic compliance requirements.
Pricing Analysis
Price spreads between German and Australian hybrid equipment markets exceed 20% after accounting for EU Carbon Border Adjustment Mechanism levies and freight logistics. Three-tier pricing structure across premium series configurations, standard parallel architectures, and economy mild hybrid tiers reflects battery capacity and grid connectivity differentials. Cost compression in economy tractor segments is intensifying because renewable diesel substitution programs are diverting R&D budgets from electrification programs. Agricultural cooperatives in Brazil exhibit highest price sensitivity, while Pilbara mining operators prioritize lifecycle fuel guarantees over upfront equipment costs.
Supply Chain Analysis
Strategic stockpiling of silicon carbide wafers and thermal management components dominates inventory strategy among power electronics suppliers serving 800-volt hybrid architectures. Cell manufacturing concentrates in China, South Korea, and Japan, with cathode active material processing drawing from Indonesian nickel and Chilean lithium operations. Single-source vulnerability pervades silicon carbide substrate supply, where substrate growth capacity limits inverter module output. Distribution runs through captive OEM assembly networks and independent retrofit integrators in Texas and Alberta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks mining capital expenditure cycles, with fleet renewal waves in Western Australia's Pilbara region driving procurement velocity as iron ore operators negotiate fuel consumption ceilings.
For Market Incumbents: Secure backward integration into battery pack assembly within EU free trade zones to neutralize Carbon Border Adjustment Mechanism exposure. Lock in long-term cathode material offtake from Indonesian nickel processors before supply commitments saturate. Renewable diesel substitution programs at agricultural OEMs threaten hybrid R&D budget allocations, requiring defensive patent portfolio investments in PTO-integrated mild hybrid architectures. For New Entrants and Emerging Players: Aftermarket retrofit certification gaps in North American mining corridors present service-layer white space where electrification-trained technician shortages extend OEM field service response windows to 72 hours. Target haul truck conversion programs in Alberta and Texas where independent integrators lack factory-authorized powertrain calibration capabilities. Go-to-market positioning should emphasize 18-24 month deployment acceleration against incumbent delivery timelines through specialized high-voltage training partnerships. For Investors and Strategic Acquirers: Capital is best deployed toward independent powertrain integrators with certified retrofit programs and established relationships with Pilbara mining contractors. Long-term viability hinges on fuel logistics arbitrage economics persisting in remote operations beyond pipeline infrastructure. Watch for battery supply chain localization mandates expanding beyond China into ASEAN jurisdictions as the inflection signal for captive assembly investment urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cathode material offtake secures cell allocation for 800-volt architectures ahead of supply saturation. |
| Retrofit Certification Program | Factory-authorized conversion protocols open aftermarket revenue streams beyond OEM new-equipment cycles in mining corridors. |
| Regional Assembly Footprint | EU battery pack assembly within free trade zones neutralizes Carbon Border Adjustment Mechanism cost inflation. |
| Technician Training Partnership | Electrification-certified service networks compress deployment timelines against 18-24 month industry delays. |
| Silicon Carbide Sourcing Alliance | Substrate growth capacity commitments de-risk inverter module supply for underground mining equipment manufacturers. |
Research Methodology
A standing panel of mining fleet procurement directors, construction equipment maintenance managers, agricultural OEM powertrain engineers, and independent retrofit integrators provided ongoing calibration against secondary validation from EPA emission certification filings, EU Stage V compliance databases, and mining operator sustainability reports. Primary fieldwork combined structured interviews with aftermarket service heads and OEM platform engineering leads across Decatur, Kobe, and Waterloo manufacturing clusters. Bottom-up equipment shipment tallies triangulated against top-down fuel consumption modeling across Western Australian and northern Canadian operations.
Consistency checks validated volume and value outputs against customs records for power electronics imports and battery cell trade flows. Segmentation modeling spanned propulsion architecture, vehicle category, end-use application, and regional regulatory framework across the projection horizon. CAGR derivation incorporated duty cycle intensity variations, emission compliance phase-in schedules, and fuel logistics cost differentials. Forecast inputs included mining commodity price trajectories and agricultural diesel substitution program announcements.
Underlying assumptions cover sustained iron ore production levels in Pilbara operations and stable battery raw material processing capacity in Indonesia and Chile, with deviation risk concentrated in carbon border adjustment mechanism expansion timelines and renewable diesel subsidy program durability. Revision becomes warranted when electrification technician training program enrollment crosses thresholds sufficient to eliminate deployment timeline extensions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Off-Highway Electric Vehicle Market
Off Road Vehicles
Four-Wheel Drive Vehicles Market
Off Road Vehicles
Global Electric Off-Highway Equipment Market
Off Road Vehicles
Off-Road High Performance Vehicle Market
Off Road Vehicles
Snowmobile Market
Off Road Vehicles
Snow Scooter Market
Off Road Vehicles
Mining Vehicle Attachments Market
Off Road Vehicles
Off-Highway Diesel Common Rail Injection System Market
Off Road Vehicles
Off-Road Vehicle Market
Off Road Vehicles
Europe Off-Highway Vehicle HVAC Market
Off Road Vehicles
Hybrid Off-Road Vehicle Market
Off Road Vehicles
Off Road All Terrain E-Scooter Market
Off Road Vehicles
US Off-Road Vehicles Market
Off Road Vehicles
Middle East and Africa Utility Terrain Vehicles Market
Off Road Vehicles
Utility Terrain Vehicles (UTV) Market
Off Road Vehicles
Off-Highway Vehicle Market