
 Four-Wheel Drive Vehicles Market | 2026-2036
Four-Wheel Drive Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Four-Wheel Drive Vehicles Market Foresight
Dealer networks and direct-to-consumer digital channels is reconfiguring how four-wheel drive vehicles reach buyers, with online configuration tools now capturing pre-orders before inventory hits lots. Toyota leverages its hybrid expertise to dominate electrified 4WD offerings in multiple segments. Ford anchors its position through manufacturing scale at Kentucky Truck Plant and Dearborn operations. Jeep specializes in off-road credibility, sustaining brand loyalty among recreational and commercial buyers alike.
Four-wheel drive vehicles distribute engine torque to all axles simultaneously through transfer cases, differentials, and multi-plate clutches, enabling traction on low-friction surfaces and steep gradients. The primary commercial purpose spans construction site access, agricultural fieldwork, mining haul roads, and consumer recreational travel across unpaved terrain. SUVs and pickup trucks occupy the largest volume pools, while battery electric variants within fuel type segmentation represent the fastest-growing margin opportunity as cell costs decline and charging infrastructure expands. Permanent 4WD systems lead in premium positioning, though on-demand AWD competes aggressively in crossover segments where fuel economy priorities dominate purchase decisions.
NHTSA crashworthiness standards and EPA corporate average fuel economy rules shape powertrain development timelines and lightweight material adoption across the industry. ISO 6469 electric vehicle safety standards and SAE J3061 cybersecurity guidelines add compliance layers for electrified 4WD architectures entering production. Stakeholders must monitor battery thermal management performance in severe-duty cycles and assess whether charging infrastructure density in rural corridors keeps pace with fleet electrification commitments.
Market Dynamics
EPA emissions standards are compressing powertrain development timelines while battery thermal management requirements for severe-duty cycles reshape electrification roadmaps across heavy-duty pickup and SUV segments.
Growth Catalysts
- Rural infrastructure spending:Federal highway and bridge appropriations in the United States sustain replacement cycles for commercial fleet operators requiring worksite access capabilities.
- Hybrid electric powertrains:Stricter EPA corporate average fuel economy rules push manufacturers toward electrified architectures that preserve towing capacity while reducing emissions.
- Recreational off-roading culture:Consumer demand for unpaved terrain travel sustains premium positioning for permanent 4WD systems in the United States market.
Market Restraints
- Battery cell cost volatility:Lithium and nickel price swings compress margin projections for battery electric 4WD variants targeting fleet electrification commitments.
- Charging infrastructure gaps:Rural corridor density limitations in the United States constrain fleet operator confidence in full electrification timelines.
- Transfer case manufacturing concentration:Specialized component supply clusters in the Midwestern United States create geographic vulnerability for multi-plate clutch sourcing.
Strategic Opportunities
- Agricultural fieldwork electrification:Battery electric 4WD variants for farm operations represent underpenetrated demand as diesel alternatives face emissions scrutiny.
- Direct-to-consumer digital channels:Online configuration tools capturing pre-orders before inventory hits lots reduce dealer holding costs and accelerate cash conversion.
- ISO 6469 compliance specialization:Electric vehicle safety certification expertise creates service revenue pools for engineering consultancies supporting manufacturer product launches.
Industry Challenges
- Cybersecurity engineering talent scarcity:SAE J3061 guideline implementation requires embedded systems specialists in short supply across the automotive supplier base.
- Lightweight material welding certification:Advanced high-strength steel and aluminum joining processes demand recertified technician workforces at assembly plants.
- Legacy transfer case integration:Electrified powertrain architectures must accommodate mechanical 4WD hardware with incompatible torque delivery profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Four-Wheel Drive Vehicles Market |
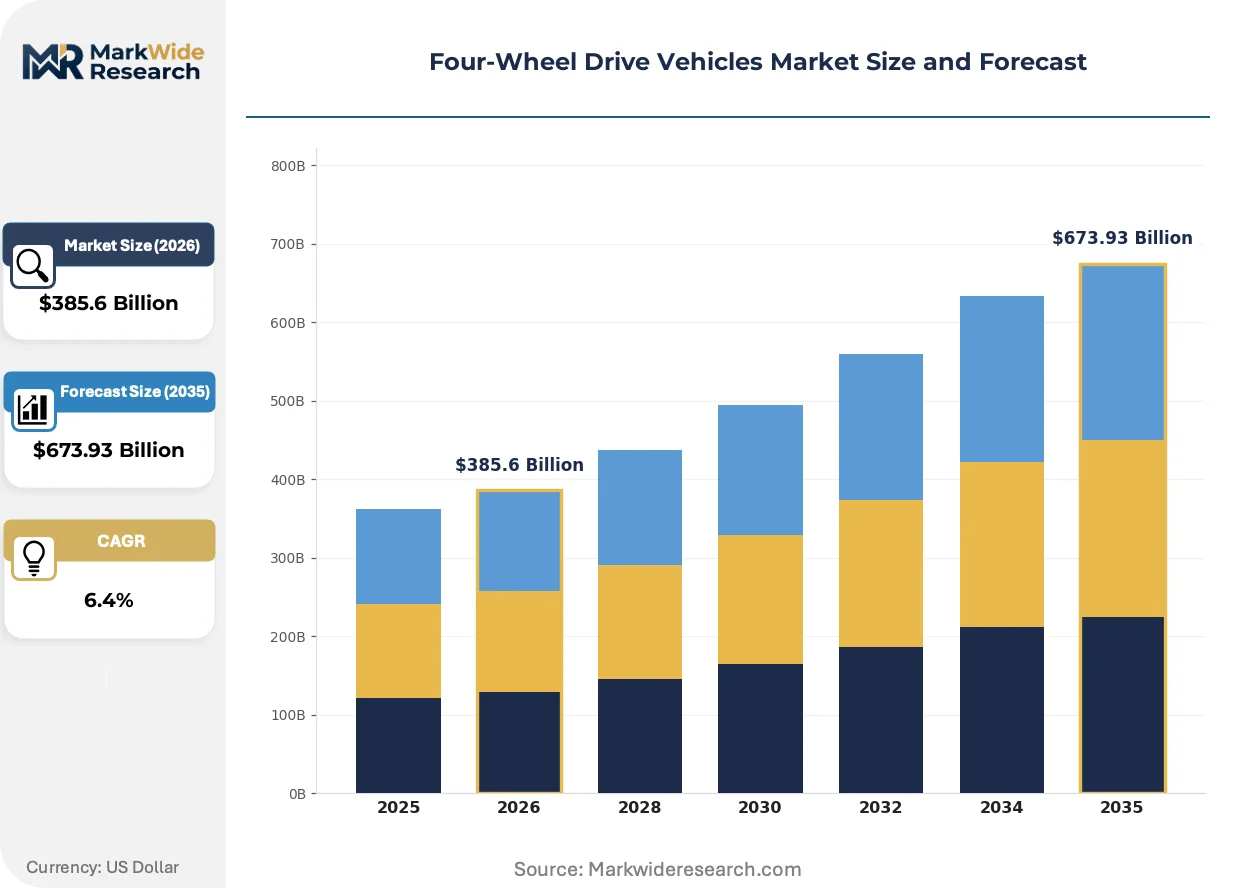
| Market Size in 2026 | $385.6 Billion |
| Market Size in 2035 | $673.93 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Pickup Trucks, SUVs, Crossovers, Off-Road Vehicles, Utility Vehicles Drive System: Permanent 4WD, Part-Time 4WD, On-Demand AWD, Mechanical AWD, Electronic AWD Fuel Type: Gasoline, Diesel, Hybrid Electric, Battery Electric, Hydrogen Fuel Cell End User: Personal Use, Commercial Fleet, Government Agencies, Mining Operators, Agricultural Enterprises |
| Companies Covered | Chevrolet, Lexus, Toyota, Ram, Mercedes-Benz, Ford, GMC, Range Rover, Jeep, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Four-Wheel Drive Vehicles Market Shifts & Advancements
Powertrain electrification is compressing traditional mechanical architectures while digital sales channels and thermal management advances reshape how four-wheel drive capabilities reach commercial and recreational buyers.
Multi-plate clutch-based on-demand all-wheel drive systems are collapsing the historical trade-off between fuel economy and traction capability. Crossover segment buyers in the United States now expect seamless torque vectoring without the weight penalty of permanent 4WD hardware. This compression is enabling manufacturers to standardize AWD across mid-trim configurations previously reserved for front-wheel drive.
EPA corporate average fuel economy rules are accelerating hybrid electric powertrain investments across light-duty truck portfolios. Manufacturers must achieve fleet-wide efficiency targets while preserving towing ratings that drive commercial purchase decisions. The United States heavy-duty pickup segment is responding with parallel hybrid architectures that maintain worksite capability during electric-only operation.
Fleet procurement departments are consolidating vendor relationships around electrification readiness metrics rather than historical service network density. Large commercial operators in construction and mining now require charging infrastructure compatibility assessments alongside traditional uptime guarantees. This consolidation is most visible in North American fleet RFPs where total cost of ownership calculations incorporate carbon accounting disclosures.
Four-Wheel Drive Vehicles Market Segmentation
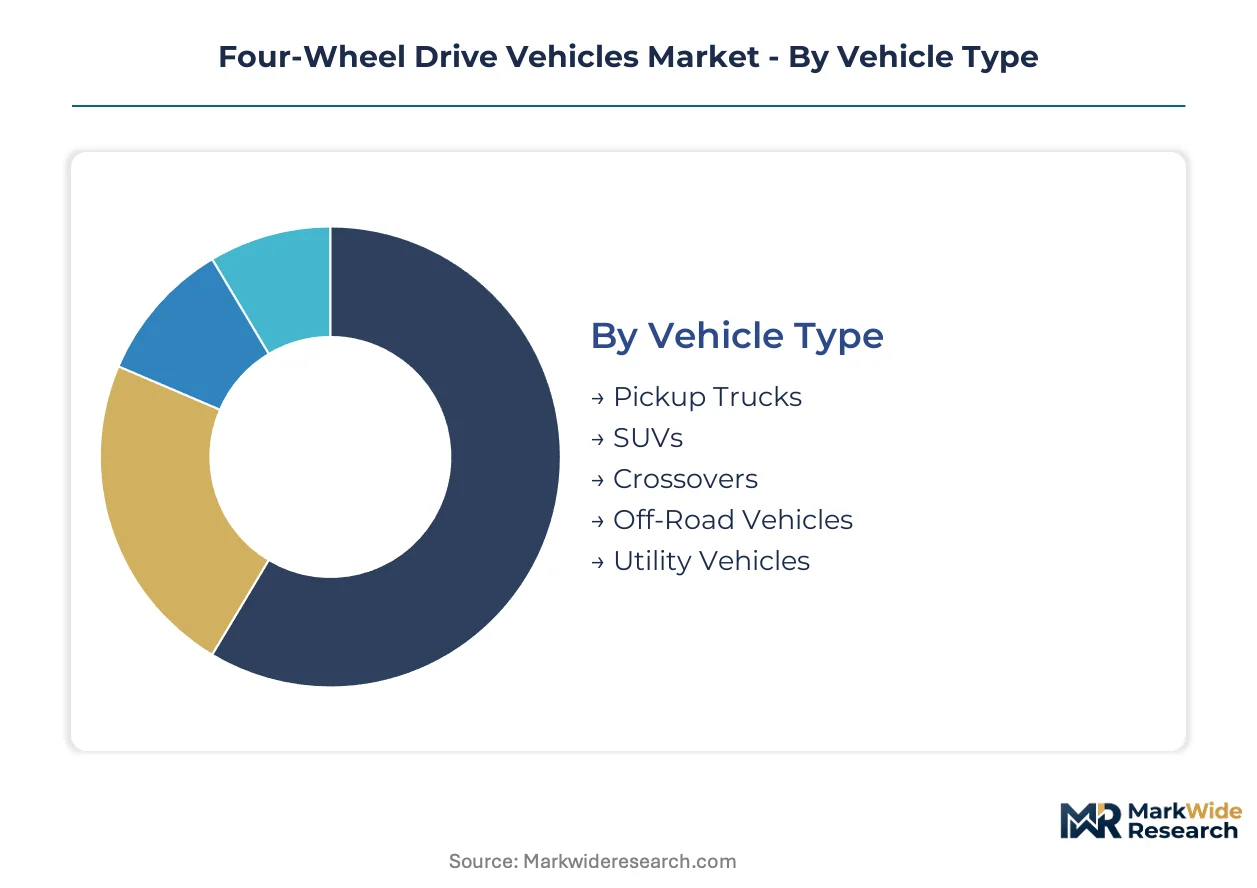
Segmentation in the four-wheel drive vehicles market reveals how powertrain architecture, duty cycle intensity, and procurement authority shape purchasing patterns. Manufacturers configure product portfolios across these dimensions to capture distinct margin pools while managing compliance complexity.
Vehicle Type:
The use-case spectrum spans worksite hauling, family transportation, recreational terrain traversal, and specialized industrial access.
- Pickup Trucks:Body-on-frame construction delivers towing capacity exceeding 12,000 pounds for commercial fleet operators. Demand concentrates in the United States where rural infrastructure spending sustains replacement cycles for construction and agricultural contractors.
- SUVs:Three-row configurations dominate family transportation segments while maintaining off-road credibility through available low-range transfer cases. Hybrid electric powertrains are penetrating this segment fastest as EPA corporate average fuel economy rules tighten.
- Crossovers:Unibody platforms prioritize fuel economy over extreme terrain capability for suburban buyers.
- Off-Road Vehicles:Specialized suspensions and locking differentials serve recreational enthusiasts in desert and mountain corridors.
- Utility Vehicles:Compact dimensions and cargo versatility address last-mile delivery and campus maintenance applications.
The dominant share belongs to Pickup Trucks, while SUVs are closing the gap fastest.
Drive System:
Cost tier differentiation separates premium permanent hardware from efficiency-optimized on-demand alternatives.
- Permanent 4WD:Continuous torque distribution through mechanical transfer cases and center differentials eliminates driver engagement. Mining operators in the United States specify these systems for haul road access where traction failure incurs production downtime penalties.
- On-Demand AWD:Multi-plate clutches automatically apportion torque based on wheel slip detection algorithms. Crossover buyers in suburban United States markets select this configuration for wet weather confidence without fuel economy sacrifice.
- Part-Time 4WD:Driver-selectable engagement preserves mechanical simplicity for cost-sensitive commercial buyers.
- Mechanical AWD:Viscous couplings and limited-slip differentials provide passive torque management without electronic intervention.
- Electronic AWD:Brake-based torque vectoring and software-controlled clutch packs enable predictive traction adjustments.
Permanent 4WD commands the highest average transaction prices, though On-Demand AWD is expanding volume share most rapidly.
Fuel Type:
Application severity and refueling infrastructure availability determine powertrain selection across customer types.
- Gasoline:Port-injection and direct-injection architectures dominate light-duty recreational applications with established service networks. Personal use buyers in the United States continue selecting gasoline V6 and V8 configurations for towing confidence.
- Hybrid Electric:Parallel architectures preserve mechanical four-wheel drive capability while capturing regenerative braking energy. Commercial fleet operators facing carbon accounting disclosures are adopting these powertrains for worksite access vehicles.
- Diesel:Compression-ignition torque characteristics sustain heavy-duty towing demand among agricultural enterprises.
- Battery Electric:Skateboard platforms with dual-motor configurations eliminate mechanical transfer cases while providing instantaneous torque vectoring.
- Hydrogen Fuel Cell:Long-haul commercial applications with centralized refueling infrastructure represent emerging deployment territory.
Gasoline retains the largest installed base, yet Hybrid Electric is climbing the fastest as manufacturers balance efficiency mandates with capability preservation.
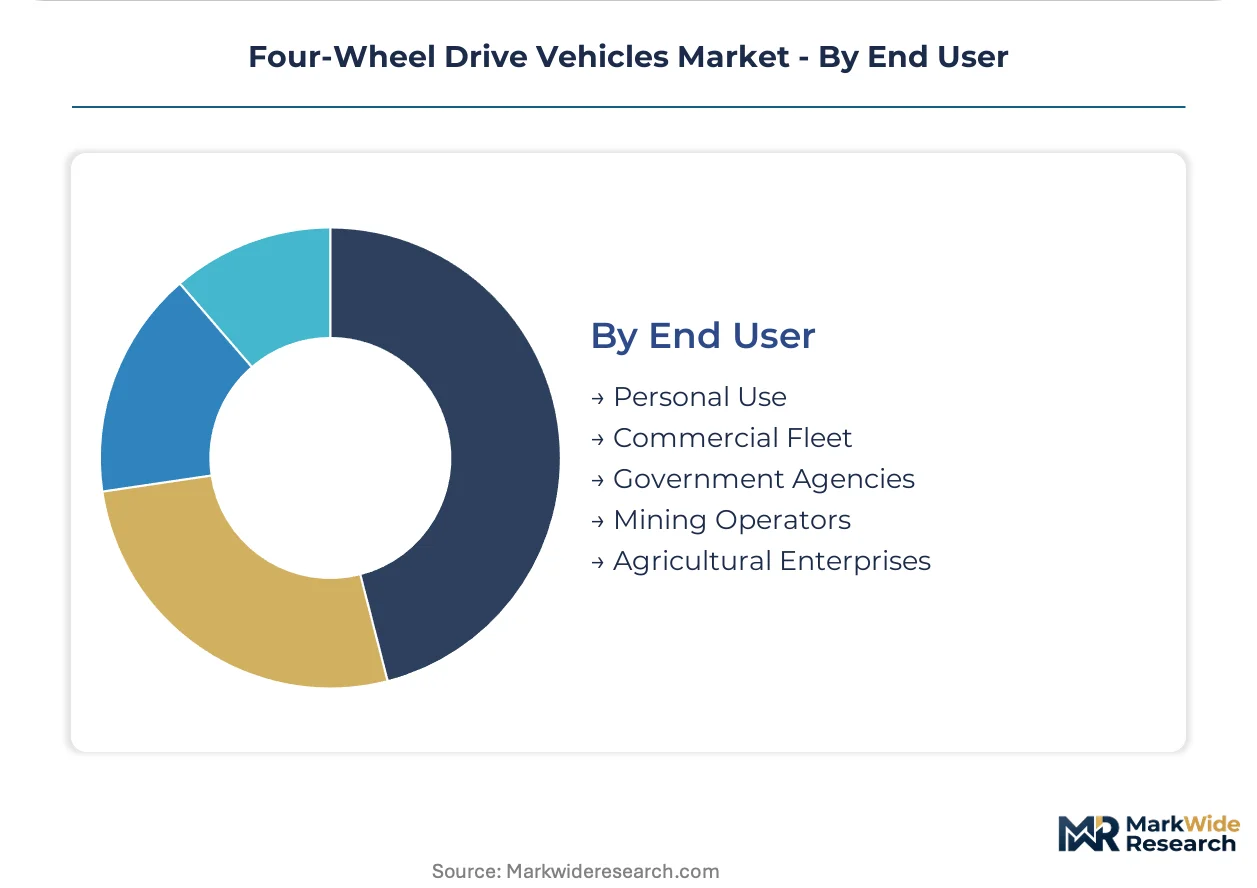
End User:
Procurement authority and total cost of ownership calculation methods create distinct specification requirements.
- Commercial Fleet:Centralized procurement departments negotiate volume contracts with uptime guarantees and charging infrastructure compatibility assessments. Construction and mining operators in the United States prioritize service network density and parts availability.
- Personal Use:Individual buyers respond to brand loyalty, financing terms, and recreational feature marketing. Off-roading culture in the United States sustains premium pricing for trail-rated configurations.
- Government Agencies:Federal and state procurement rules mandate domestic content percentages and alternative fuel vehicle quotas.
- Mining Operators:Severe-duty cycles and remote site access requirements drive specifications for reinforced frames and cooling systems.
- Agricultural Enterprises:Fieldwork duty cycles and implement towing needs shape powertrain and suspension selections.
Commercial Fleet generates the highest revenue per unit through specification complexity, while Personal Use accounts for the greatest transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where rural infrastructure spending sustains premium transaction values, while Canadian operators face compressed margins from cross-border fleet procurement consolidation. This asymmetry shapes manufacturer allocation decisions across North American production networks.
United States
Commercial fleet operators in Texas and the Mountain West are expanding heavy-duty pickup orders for oilfield and construction site access. EPA corporate average fuel economy rules are accelerating hybrid electric powertrain investments at Ford's Kentucky Truck Plant and Dearborn operations. Detroit's supplier corridor dominates transfer case and multi-plate clutch manufacturing for domestic OEMs.
Canada
Mining operators in Alberta and British Columbia require severe-duty 4WD systems for remote haul road access where traction failure incurs production penalties. Health Canada's vehicle safety standards align with NHTSA crashworthiness protocols while adding cold-weather performance verification requirements. Ontario's automotive corridor around Windsor and Oshawa hosts stamping and assembly operations serving both domestic and export demand.
Mexico
Light-duty truck assembly for US export dominates manufacturing investment in Nuevo León and the Bajío Region. Mexico's Secretariat of Economy automotive decree mandates domestic content thresholds for tariff-free access to USMCA markets. Guanajuato's supplier parks are expanding clutch and differential component capacity to serve integrated North American production.
Germany
Premium SUV demand from industrial executives and agricultural enterprises sustains permanent 4WD system volumes in Bavaria and Baden-Württemberg. KBA type-approval procedures enforce EU emissions standards while adding cybersecurity certification under UNECE R155 for connected vehicle architectures. Stuttgart's engineering consultancies specialize in ISO 6469 electric vehicle safety compliance for electrified 4WD architectures.
China
Domestic SUV sales in the Yangtze River Delta and Pearl River Delta are shifting toward on-demand AWD configurations for suburban family transportation. MIIT new energy vehicle mandates require minimum battery electric and plug-in hybrid production quotas from domestic manufacturers. Chongqing's automotive cluster hosts joint-venture assembly operations targeting western provincial markets with elevated terrain requirements.
Four-Wheel Drive Vehicles Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in clutch packs, transfer cases, and torque-vectoring software. The market structures around three archetypes: full-line OEMs with captive powertrain divisions, electrification-focused hybrid specialists, and off-road credibility brands with recreational buyer loyalty. Dominant competitive moves include manufacturing scale consolidation at single-site truck plants and direct-to-consumer digital channel development for pre-order capture.
Among US-based full-line manufacturers, Ford, General Motors, and Stellantis occupy positions across light-duty, heavy-duty, and performance 4WD segments. Toyota represents the hybrid specialist archetype with parallel electric architectures preserving mechanical four-wheel drive capability. Jeep exemplifies off-road credibility positioning with trail-rated configurations sustaining premium pricing in recreational segments.
| Leading Market Players |
|---|
| Chevrolet |
| Lexus |
| Toyota |
| Ram |
| Mercedes-Benz |
| Ford |
| GMC |
| Range Rover |
| Jeep |
| Others |
Supply & Pricing Matrix
The Detroit-Windsor freight corridor's cross-border logistics costs cascade through transfer case and multi-plate clutch sourcing clusters, concentrating pricing power among Midwestern suppliers while forcing downstream differentiation between configured-to-order heavy-duty pickups and standard inventory crossovers.
Pricing Analysis
Configured-to-order pricing for heavy-duty pickups with permanent 4WD systems commands substantial premiums over standard crossover AWD configurations. Price differentiation rests on EPA certification tier and customization depth, with commercial fleet buyers facing cost compression from carbon accounting disclosure requirements. Personal use buyers in recreational segments show lowest price sensitivity, prioritizing trail-rated capability over transaction value.
Supply Chain Analysis
Export-control regimes on advanced torque-vectoring software and battery thermal management systems limit technology flows to Chinese and Russian end-users. Component manufacturing concentrates in the United States, Mexico, and Germany, with lithium and nickel feedstock dependencies creating exposure to commodity volatility. Distribution runs through captive OEM dealer networks and emerging direct-to-consumer digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as hybrid electric powertrain penetration accelerates across commercial fleet replacement cycles, with rural infrastructure spending sustaining demand visibility.
For Market Incumbents: Insulate manufacturing scale advantages at Kentucky Truck Plant and Dearborn operations against emerging battery electric entrants by deepening captive supply of multi-plate clutches and transfer cases. Prioritize ISO 6469 compliance certification to capture electrification service revenue pools before engineering consultancies consolidate this capability. For New Entrants and Emerging Players: Establish a beachhead in agricultural fieldwork electrification, where diesel alternative scrutiny has created underpenetrated demand for battery electric 4WD utility vehicles. Target farm equipment distributors with charging infrastructure compatibility assessments bundled into total cost of ownership proposals. For Investors and Strategic Acquirers: Carve-out targets emerge from full-line OEMs spinning off legacy transfer case divisions incompatible with electrified powertrain architectures. Long-term viability hinges on thermal management software capabilities for severe-duty cycles; watch fleet electrification commitment acceleration in mining and construction RFPs as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium cell capacity for hybrid electric powertrain ramp at Ford's Kentucky Truck Plant. |
| Software-Defined Vehicle Investment | Enables predictive torque vectoring algorithms that differentiate on-demand AWD from mechanical systems. |
| Charging Infrastructure Partnership | Addresses rural corridor density gaps constraining fleet operator electrification confidence. |
| Platform Standardization | Reduces transfer case integration complexity across hybrid and battery electric 4WD architectures. |
| Geographic Manufacturing Footprint | Expands Nuevo León assembly capacity to serve USMCA tariff-free access requirements. |
Research Methodology
A standing panel of OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and dealership operations managers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation through EPA certification databases, NHTSA crashworthiness filings, vehicle production registries, and IHS Markit registration data. Bottom-up segment builds and top-down macroeconomic triangulation anchored volume and value estimates.
Scenario-bracketing around EPA emissions trajectory uncertainty and battery cell cost volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include vehicle class, propulsion architecture, drive system type, and regional production cluster. CAGRs derived from historical penetration curves adjusted for regulatory inflection points, with forecast inputs incorporating charging infrastructure buildout assumptions and fleet electrification commitment timelines.
Stress conditions across lithium price bands, EPA rulemaking stringency, and rural infrastructure appropriation levels were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about powertrain mix evolution and supplier consolidation patterns. Material shifts in battery thermal management performance standards or USMCA domestic content thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Off Highway Vehicles Brake Systems Market
Off Road Vehicles
Global Electric Off-Highway Equipment Market
Off Road Vehicles
Off Highway Vehicle Lighting Market
Off Road Vehicles
Global Off-Highway Vehicle Telematics Market
Off Road Vehicles
Off-Highway Vehicle HVAC Market
Off Road Vehicles
Off Road All Terrain E-Scooter Market
Off Road Vehicles
Small Off-Road Engines Market
Off Road Vehicles
Electric Utility-Terrain Vehicle (UTV) Market
Off Road Vehicles
US Off-Road Vehicles Market
Off Road Vehicles
Off Road Motorcycles Market
Off Road Vehicles
Off Highway Hybrid Vehicles Market
Off Road Vehicles
Off-Road High Performance Vehicle Market
Off Road Vehicles
Amphibious ATV Market
Off Road Vehicles
Utility Terrain Vehicles (UTV) Market
Off Road Vehicles
Off-Road Vehicles Cooling Fan Market
Off Road Vehicles
Automotive and Off-Road Vehicle Hoses Market