
 Snowmobile Market | 2026-2036
Snowmobile Market Size, Share, and Industry Trends Forecast 2026-2036
Snowmobile Market Outlook
Snowmobile dealer networks across North America and Scandinavia is fragmenting as direct-to-consumer digital sales and regional rental hubs erode traditional franchise density. Polaris Inc. leverages its captive parts-and-accessories ecosystem to sustain recurring revenue per unit. BRP anchors its premium positioning through proprietary Rotax engine architectures. Taiga Motors Corporation differentiates via in-house electric powertrain integration.
A snowmobile is a motorized vehicle engineered for travel over snow and ice, typically employing a track-and-ski chassis with engine displacements ranging from 400cc to 900cc and power-to-weight ratios optimized for flotation on powder surfaces. Its primary commercial purpose spans recreational tourism, backcountry utility transport, and competitive racing circuits. The touring segment occupies the largest installed base among casual riders seeking heated cabins and long-range fuel capacity, while the electric engine category registers the fastest trajectory as battery energy density improves for cold-climate operation. Utility-class machines command the strongest margin pools due to fleet purchasing by government agencies and commercial snow-removal contractors.
The EPA enforces Tier 3 emission standards that constrain two-stroke engine production volumes and accelerate four-stroke development cycles. EU F-Gas Regulation and REACH compliance add material-cost burdens for European manufacturers sourcing fluorinated greenhouse gas components. Health Canada and the CPSC coordinate recall protocols affecting cross-border distribution liability. Stakeholders must weigh electrification capital commitments against the residual demand durability of combustion platforms in remote Arctic service environments.
Market Dynamics
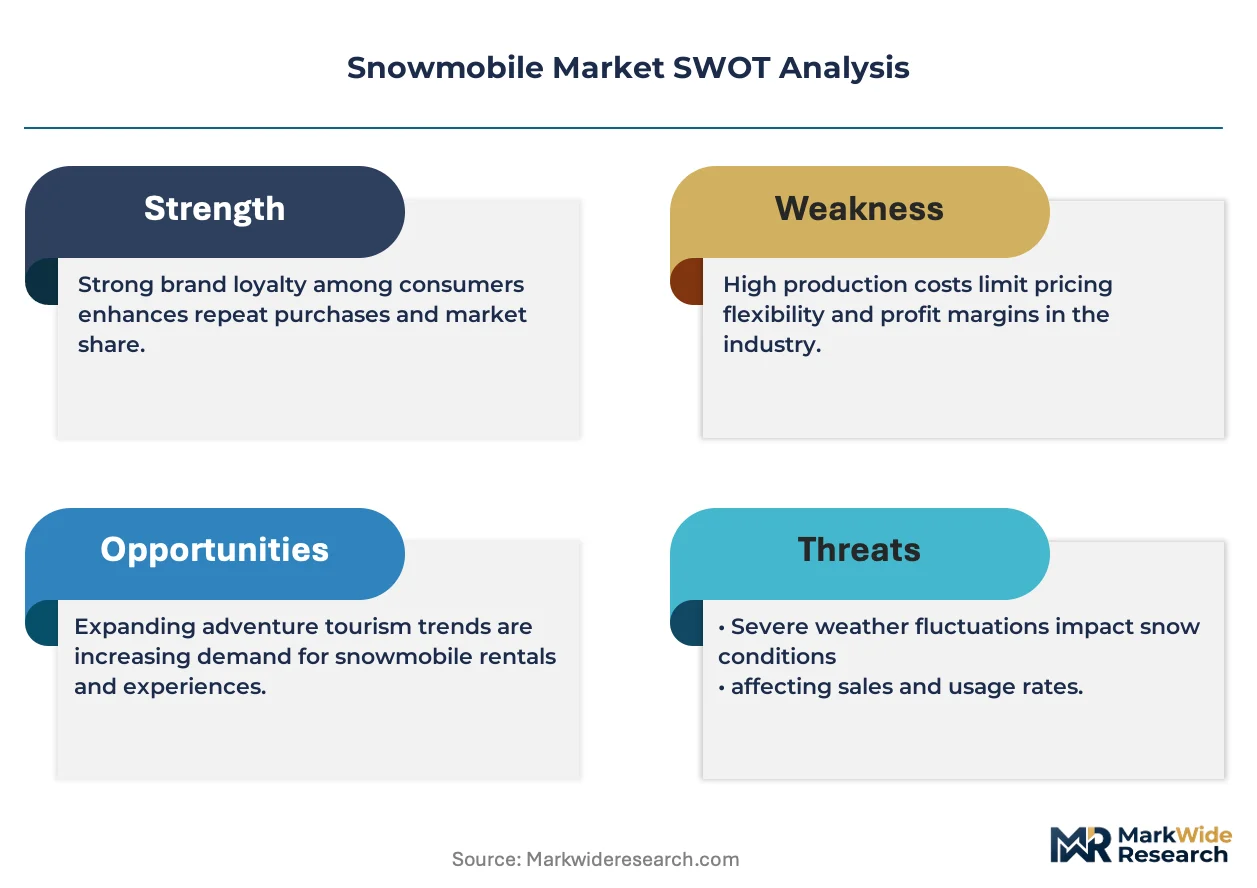
Electrification is forcing a capital reallocation across the snowmobile value chain as battery chemistry advances meet cold-climate performance thresholds, while EPA Tier 3 emission limits simultaneously compress two-stroke engine production economics.
Growth Catalysts
- Backcountry tourism expansion:Norwegian and Swedish fleet operators are scaling utility-class orders for guided wilderness access. Remote lodge infrastructure drives durable replacement cycles.
- EPA Tier 3 compliance:Stricter emission thresholds accelerate four-stroke R&D investment. Manufacturers capture margin premiums on cleaner engine architectures.
- Solid-state battery prototyping:Improved energy density for sub-zero operation unlocks electric platform viability. Arctic service providers pilot integrated charging depots.
Market Restraints
- Lithium supply concentration:Cathode material sourcing clusters in limited jurisdictions. Cell manufacturers face input cost volatility and geopolitical exposure.
- EU F-Gas Regulation:Fluorinated greenhouse gas restrictions add certification burden for European production. REACH compliance raises material overhead for cross-border distribution.
- Two-stroke residual demand:Remote Arctic operators prioritize field-repairable combustion platforms. Electrification capex faces payback skepticism in low-density service territories.
Strategic Opportunities
- Digital direct-to-consumer channels:Dealer network fragmentation creates white space for manufacturer-owned rental hubs. Regional logistics partnerships reduce franchise dependency.
- Utility fleet electrification:Government snow-removal contractors face procurement mandates for zero-emission equipment. Municipal RFPs specify battery-electric performance guarantees.
- Interoperable charging infrastructure:Standardized connectors across Nordic tourism corridors enable route confidence. Cross-operator network agreements reduce range anxiety for recreational riders.
Industry Challenges
- Power electronics thermal management:Cold-weather inverter reliability requires specialized engineering talent. Recruitment lags electrification program timelines.
- Dual-platform certification:Maintaining EPA and EU type-approval for combustion while scaling electric variants strains regulatory affairs capacity. Parallel homologation cycles extend product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snowmobile Market |
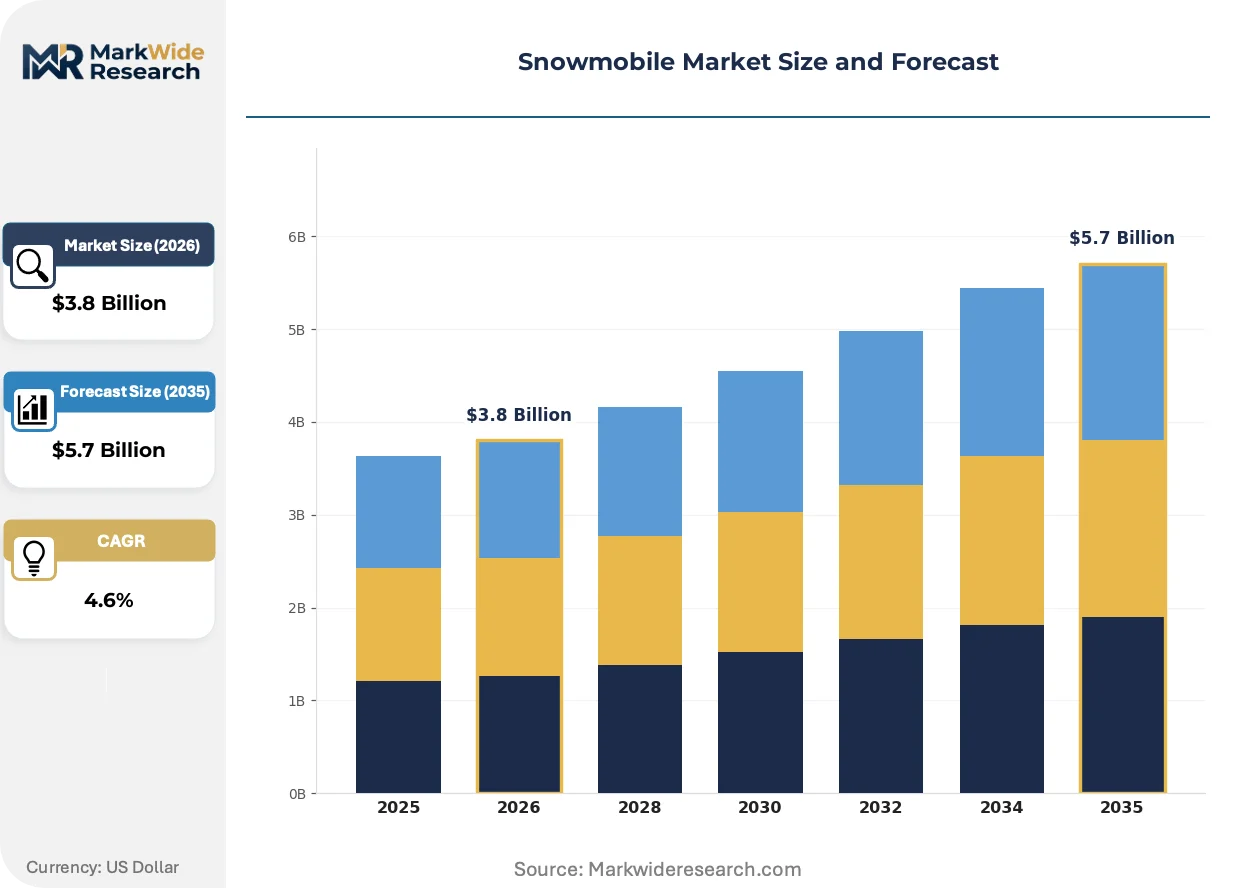
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
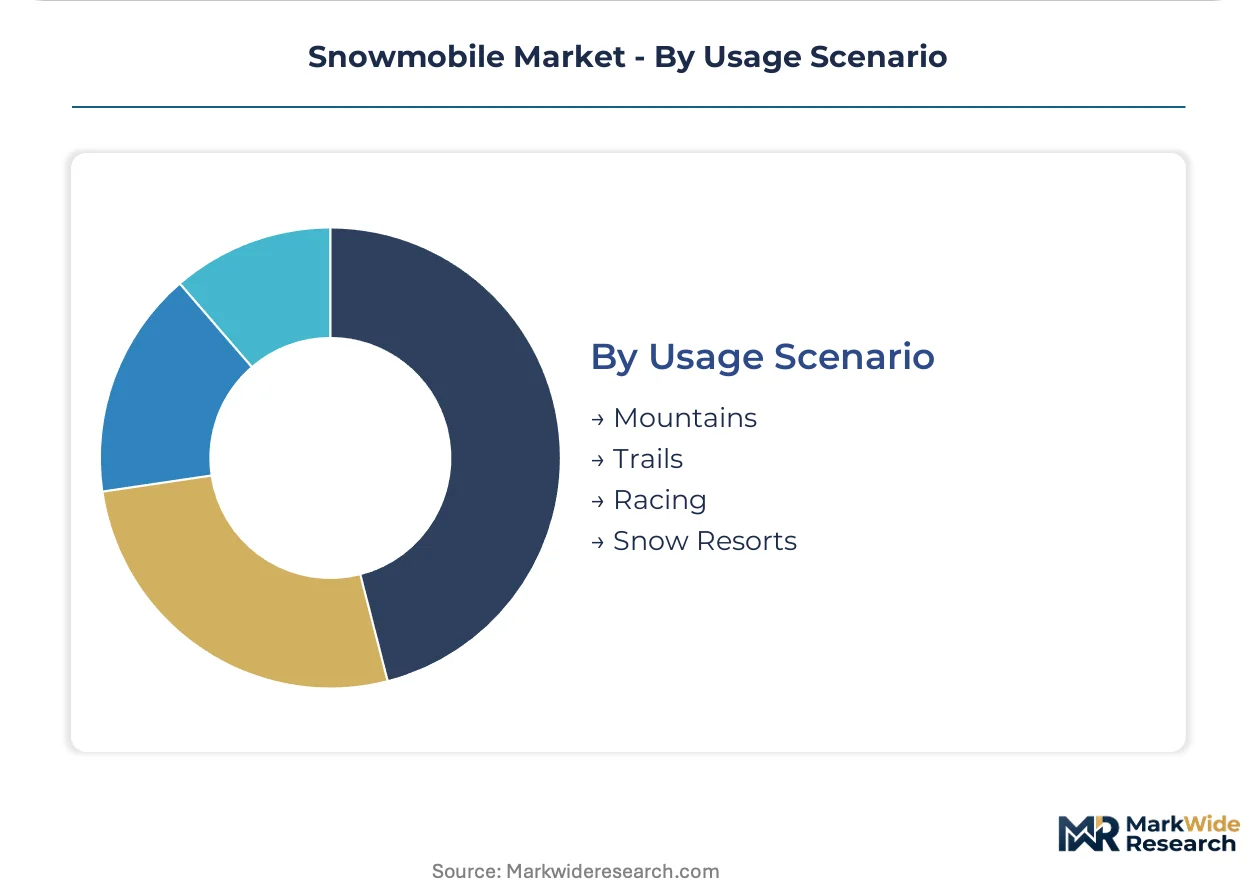
| Segmentation | Product Type: Recreational, Touring, Crossover, Utility Engine Type: 2-Stroke, 4-Stroke, Electric, Hybrid End User: Casual Riders, Enthusiasts, Dealers, Rental Agencies Usage Scenario: Mountains, Trails, Racing, Snow Resorts |
| Companies Covered | Polaris Inc., Bombardier Recreational Products (BRP), Arctic Cat Inc., Yamaha Motor Corporation, Taiga Motors Corporation, Alpina Snowmobiles, Lynx, Aurora Powertrains, AD Boivin Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snowmobile Market Strategic Shifts
Telematics integration is virtualizing the snowmobile ownership experience, compressing service intervals into predictive maintenance models while regulatory pressure on combustion architectures accelerates powertrain diversification.
Solid-state battery cell architectures are virtualizing range assumptions for electric snowmobile platforms. Arctic tourism operators in Norway pilot depot-based fast-charging networks to support multi-day backcountry itineraries. The technology is compressing the total-cost-of-ownership gap against refined four-stroke alternatives.
EPA Tier 3 emission enforcement constrains two-stroke engine production volumes. Manufacturers redirect engineering capacity toward four-stroke refinement and electric platform development. The touring segment faces the steepest compliance cost escalation due to its installed base scale.
Rental hub proliferation is fragmenting traditional dealer channel control. Regional tourism operators in Minnesota and Wisconsin consolidate fleet purchasing power through cooperative procurement entities. After-sales service unbundling accelerates as direct parts distribution reduces franchise dependency.
Snowmobile Market Segmentation

Snowmobile segmentation reveals divergent replacement cycles across product tiers, with fleet-driven utility units turning over every 5-7 years while recreational models face discretionary deferral during economic pressure. Understanding these velocity differentials informs inventory positioning and service revenue planning for manufacturers and regional distributors.
Product Type:
Replacement cycles vary dramatically across this category, with commercial utility fleets operating on rigid procurement schedules while recreational segments respond to snowpack variability and discretionary income shifts.
- Recreational:Lightweight chassis configurations prioritize powder flotation and maneuverability for ungroomed terrain. Minnesota and Wisconsin trail systems drive concentrated demand, though sales volatility tracks snowfall deviation from seasonal averages.
- Touring:Heated cabins, extended fuel capacity, and ergonomic seating define this segment for multi-day expedition use. Norwegian backcountry tourism operators anchor fleet demand, with replacement cycles extending during lodge infrastructure investment pauses.
- Crossover:Hybrid geometry bridges trail efficiency and off-trail capability. Enthusiast riders in Michigan's Upper Peninsula represent core demand clusters.
- Utility:Work-focused specifications emphasize towing capacity and attachment compatibility. Swedish government snow-removal contractors sustain predictable procurement rhythms.
Touring anchors the volume base while electric-adjacent recreational configurations gain share at the steepest rate.
Engine Type:
Cost tier stratification separates this category, with premium four-stroke architectures commanding margin premiums while electric platforms absorb development subsidies and battery cost curves.
- 2-Stroke:Simplified field-repairable architecture persists in Arctic service environments where technical support infrastructure remains sparse. EPA Tier 3 thresholds constrain production economics and compress available supplier base.
- 4-Stroke:Refined combustion efficiency meets emission mandates while delivering torque characteristics suited to utility applications. BRP's Rotax architecture exemplifies proprietary differentiation.
- Electric:Solid-state battery prototyping targets sub-zero energy density thresholds. Taiga Motors' in-house powertrain integration bypasses third-party cell dependency.
- Hybrid:Range-extender configurations bridge charging infrastructure gaps for remote tourism corridors. Nordic pilot programs evaluate depot-based fast-charging network viability.
Four-stroke architectures dominate current revenue contribution while electric platforms climb the fastest on improving total-cost-of-ownership metrics.
End User:
Customer type fragmentation is reshaping channel economics, with direct-to-consumer digital sales eroding traditional dealer margins while rental hub consolidation concentrates fleet purchasing power.
- Casual Riders:Seasonal enthusiasts prioritizing accessibility over performance specification. Minnesota lake-country regional tourism boards influence trail access permit structures.
- Enthusiasts:Technical buyers evaluating power-to-weight ratios and aftermarket modification compatibility. Racing circuit participation drives brand loyalty formation.
- Dealers:Franchise network operators facing margin compression from parts distribution unbundling. Wisconsin cooperative procurement entities aggregate negotiating leverage.
- Rental Agencies:Fleet managers optimizing utilization rates across variable snow seasons. Swedish wilderness guide operators standardize on utility-class durability specifications.
Rental agencies anchor fleet volume stability while enthusiast direct purchasing expands most quickly through manufacturer-owned digital channels.
Usage Scenario:
Geographic application determines specification requirements, with altitude and snowpack density driving chassis and suspension calibration differences.
- Mountains:High-altitude powder conditions demand specialized track geometry and elevation-compensated fuel mapping. Norwegian fjord-region tourism infrastructure supports guided expedition services.
- Trails:Groomed corridor networks prioritize fuel efficiency and rider comfort over extreme terrain capability. Michigan trail permit revenue funds maintenance equipment procurement.
- Racing:Competition circuits enforce displacement and modification restrictions. Aftermarket component certification creates technical compliance burdens.
- Snow Resorts:Commercial operator fleets balance guest experience consistency with maintenance interval minimization. Ski area procurement specifications emphasize interoperability with existing vehicle pools.
Trail applications anchor the installed base while mountain expedition services gain share fastest on backcountry tourism investment expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Scandinavian backcountry tourism corridors where fleet operators command volume discounts, while North American retail channels face margin compression from direct-to-consumer digital encroachment.
United States
Minnesota, Wisconsin, and Michigan trail systems anchor recreational demand through state-funded grooming infrastructure. EPA Tier 3 emission enforcement accelerates four-stroke transition timelines for domestic manufacturers. The Upper Peninsula of Michigan hosts concentrated enthusiast clusters where crossover geometry specifications dominate purchasing decisions.
Canada
Arctic service operators in northern territories sustain residual two-stroke demand for field-repairable platforms. Health Canada coordinates recall protocols with CPSC for cross-border distribution liability. Quebec's snowmobile manufacturing heritage supports specialized component supplier networks serving North American OEMs.
Norway
Backcountry tourism operators scale utility-class fleet orders for guided wilderness lodge access. EU F-Gas Regulation adds certification burden for fluorinated greenhouse gas components in imported machines. Fjord-region tourism infrastructure investments concentrate guided expedition service development.
Sweden
Government snow-removal contractors sustain predictable procurement rhythms for utility-class durability specifications. REACH compliance raises material overhead for European production sourcing. Swedish wilderness guide operators standardize fleet specifications through cooperative procurement entities.
Finland
Nordic tourism corridor charging infrastructure pilots target electric platform viability for multi-day itineraries. EU Green Deal procurement mandates pressure municipal fleet electrification timelines. Lapland regional tourism boards coordinate trail permit structures with cross-border Norwegian and Swedish operators.
Snowmobile Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying track systems, suspension assemblies, and thermal management modules. The vendor structure consolidates around captive engine architectures and proprietary track geometries. Three archetypes dominate: legacy combustion-platform incumbents with dealer network density, electric-native entrants with in-house powertrain integration, and regional utility specialists serving government fleet procurement. Competitive moves concentrate on electrification capex allocation and charging infrastructure partnerships.
Within the legacy combustion tier, Polaris Inc. and Bombardier Recreational Products Inc. occupy positions defined by captive parts-and-accessories ecosystems and proprietary Rotax engine architectures respectively. Taiga Motors Corporation exemplifies the electric-native archetype through in-house battery powertrain integration. These three anchors represent divergent strategic postures on the combustion-to-electric transition timeline.
| Leading Market Players |
|---|
| Polaris Inc. |
| Bombardier Recreational Products (BRP) |
| Arctic Cat Inc. |
| Yamaha Motor Corporation |
| Taiga Motors Corporation |
| Alpina Snowmobiles |
| Lynx |
| Aurora Powertrains |
| AD Boivin Inc. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Norwegian battery cell production for sub-zero applications drives supplier prioritization toward long-term offtake agreements with Arctic fleet operators, compressing spot-market availability and elevating pricing power for qualified cell manufacturers serving cold-climate powertrain specifications.
Pricing Analysis
Configured-to-order pricing for utility-class machines with government attachment specifications commands a 15-25% premium over standard recreational configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by engine certification tier and after-sales service bundling. Cost compression in the two-stroke tier is intensifying because EPA Tier 3 compliance constrains supplier economics. Rental agencies exhibit the highest price sensitivity due to fleet-scale procurement leverage, while backcountry tourism operators prioritize total-cost-of-ownership metrics over upfront unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates lithium cathode material sourcing decisions for North American electric platform manufacturers. Cell production concentrates in China, South Korea, and Japan, with solid-state prototyping anchored in Japanese and South Korean R&D facilities. The supply chain draws from fluorinated polymer track systems, aluminum chassis extrusions, and rare-earth magnet motor components. Single-source vulnerability persists for specialized cold-weather inverter semiconductors. Distribution runs through regional dealer networks in Minnesota and Wisconsin, with direct-to-consumer digital channels gaining share fastest in enthusiast segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The snowmobile market functions as a defensive-moat industry where regulatory entrenchment around EPA Tier 3 certification creates substantial barriers for unqualified entrants, locking in incumbent advantages through multi-year homologation cycles and captive service infrastructure.
For Market Incumbents: Harden dealer network loyalty through exclusive parts distribution agreements and predictive maintenance telematics integration that raises switching costs for fleet operators. Expand in-house battery pack assembly capacity to reduce cell supplier dependency as lithium supply concentration intensifies. Prioritize certification investment for dual-platform EPA and EU type-approval to maintain cross-border distribution flexibility against emerging electric-native competitors. For New Entrants and Emerging Players: Pursue white-space positioning in municipal utility fleet electrification where procurement mandates favor zero-emission guarantees over incumbent brand recognition. Target the Finnish and Norwegian Nordic tourism corridor charging infrastructure gap with depot-based fast-charging partnerships that enable multi-day itinerary completion. Deploy direct-to-consumer digital sales with regional logistics partnerships to bypass entrenched dealer density in Minnesota and Wisconsin recreational markets. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among captive parts-and-accessories ecosystem operators with established telematics platforms that compress service intervals into subscription models. Long-term viability across the analysis window favors vertically integrated powertrain specialists with in-house battery chemistry capabilities over assembly-dependent competitors. Monitor solid-state battery energy density breakthroughs as the primary inflection signal for electric platform total-cost-of-ownership parity against refined four-stroke alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Nordic depot networks enable electric platform route confidence for multi-day backcountry itineraries. |
| Platform Standardization | Common battery architecture reduces supplier qualification burden across utility and recreational segments. |
| Backward Integration into Cell Assembly | In-house pack production insulates margin from lithium cathode material cost volatility. |
| Long-term Supply Agreement | Offtake commitments with Norwegian fleet operators secure capacity utilization for qualified manufacturers. |
| Geographic Manufacturing Footprint | Quebec-based assembly leverages Health Canada regulatory alignment with CPSC protocols. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement managers at Norwegian backcountry tourism operators, EPA regulatory affairs leads at domestic manufacturers, Arctic service technicians in northern Canadian territories, and aftermarket parts distributors in Wisconsin cooperative networks. Secondary validation drew from EPA Tier 3 certification filings, EU F-Gas Regulation compliance databases, Health Canada recall protocols, and state trail permit revenue disclosures in Minnesota and Michigan. Bottom-up unit demand modeling triangulated against top-down value chain revenue estimates.
Calibration against historical replacement cycle data and snowpack variability indices refined volume assumptions across the projection horizon. Segmentation dimensions modeled include product type, engine architecture, end-user archetype, and geographic usage scenario. CAGRs derived from regression analysis of fleet procurement rhythms and discretionary recreational deferral patterns. Industry-specific forecast inputs incorporated battery energy density improvement curves and EPA enforcement trajectory assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by electric-native entrants with solid-state prototyping capabilities would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Amphibious ATV Market
Off Road Vehicles
Off Highway Hybrid Vehicles Market
Off Road Vehicles
Off Highway Vehicle Lighting Market
Off Road Vehicles
Off Road All Terrain E-Scooter Market
Off Road Vehicles
Small Off-Road Engines Market
Off Road Vehicles
Mining Vehicle Attachments Market
Off Road Vehicles
Off Road Motorcycles Market
Off Road Vehicles
Off-Highway Diesel Common Rail Injection System Market
Off Road Vehicles
Middle East and Africa Utility Terrain Vehicles Market
Off Road Vehicles
Off-Highway Wheels Market
Off Road Vehicles
Hybrid Off-Road Vehicle Market
Off Road Vehicles
Off-Highway Vehicle Engine Market
Off Road Vehicles
Four-Wheel Drive Vehicles Market
Off Road Vehicles
Electric Utility-Terrain Vehicle (UTV) Market
Off Road Vehicles
Global Electric Off-Highway Equipment Market
Off Road Vehicles
Global Automotive Off Highway Engine Market