
 Global Off-Road Trailers Market | 2026-2036
Global Off-Road Trailers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Off-Road Trailers Market Outlook
Australia is narrowing its manufacturing gap in off-road trailer fabrication as domestic steel costs and shipping constraints push brands toward localized assembly. Patriot Campers leverages vertical integration across chassis fabrication and suspension tuning to control lead times. BruderX sustains premium positioning through military-grade aluminum monocoque construction that commands price premiums in overland segments. Black Series Campers dominates volume distribution across North American dealer networks with aggressive channel expansion.
Off-road trailers are towable recreational and utility platforms engineered with reinforced suspension systems, elevated ground clearance exceeding twelve inches, and weather-sealed construction for unimproved terrain traversal. Their primary purpose centers on transporting living quarters, equipment, or cargo across surfaces inaccessible to standard highway trailers. Enclosed configurations command the deepest margin pools as integrated climate systems and composite wall assemblies justify premium pricing. Aluminum-intensive builds represent the fastest-expanding material segment as weight reduction directly improves tow vehicle compatibility and fuel efficiency. Heavy-duty load classifications anchor commercial and military procurement channels where specification rigor limits supplier eligibility.
FAA regulations on trailer transport via air cargo influence military logistics procurement specifications, while Australia's ADR standards govern braking performance and structural integrity for domestic sales. EPA emissions considerations indirectly shape demand as lighter trailer designs reduce aggregate tow vehicle fuel consumption and associated regulatory exposure. Stakeholders must monitor evolving U.S. NHTSA trailer lighting and conspicuity standards alongside European CE marking requirements for any future market entry, as regulatory divergence threatens to fragment product development roadmaps.
Market Dynamics
Composite monocoque fabrication is compressing chassis weight by forty percent while Australia's ADR braking mandates force suspension redesigns across export-bound production lines.
Growth Catalysts
- Dispersed camping access:Bureau of Land Management terrain in the western United States generates specialized off-grid trailer procurement from overland expedition operators.
- ADR compliance upgrades:Australia's structural integrity and braking performance standards accelerate heavy-duty platform development for domestic and export markets.
- Aluminum-intensive construction:Weight reduction protocols improve tow vehicle compatibility and fuel efficiency across recreational and commercial fleet segments.
Market Restraints
- Steel input volatility:Domestic Australian steel costs and trans-Pacific shipping constraints compress margin pools for chassis fabricators.
- FAA air cargo restrictions:Military logistics procurement specifications limit rapid deployment options for expedition-grade trailers.
- Highway trailer substitution:Standard recreational trailers with aftermarket lift kits capture price-sensitive buyers in accessible terrain markets.
Strategic Opportunities
- Military specification channels:Heavy-duty load classifications in defense procurement create insulated demand pools with limited supplier eligibility.
- European CE marking preparation:Early compliance investment opens pathway for market entry before regulatory divergence hardens.
- Climate-integrated enclosures:Composite wall assemblies with HVAC integration command premium positioning in overland tourism segments.
Industry Challenges
- Suspension tuning expertise:Specialized chassis fabrication and damping calibration skills concentrate among limited engineering teams.
- Multi-jurisdiction certification:Simultaneous NHTSA lighting standards, ADR braking requirements, and CE marking timelines extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Off-Road Trailers Market |
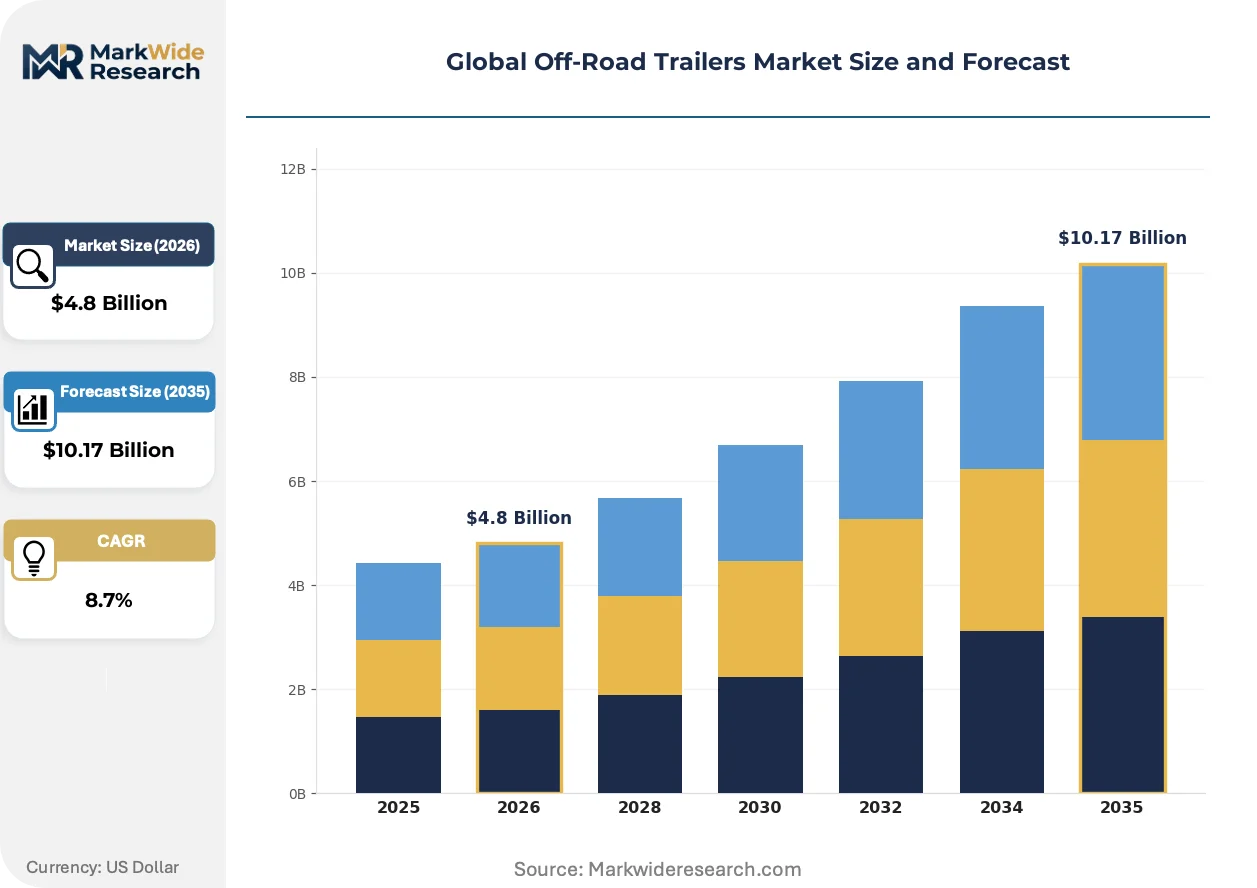
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Trailer Type: Flatbed, Enclosed, Utility, Fifth Wheel Material: Aluminum, Steel, Composite, Fiberglass Load Capacity: Light Duty, Medium Duty, Heavy Duty, Extra Heavy Duty End User: Recreational Users, Commercial Users, Government Agencies, Military |
| Companies Covered | Black Series Campers, Airstream, Inc., Patriot Campers, BruderX, Off Grid Trailers, Turtleback Trailers, Taxa Outdoors, Escapod Trailers, Opus Camper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Off-Road Trailers Market Strategic Shifts
Material substitution and regulatory harmonization pressures are compressing traditional manufacturing approaches while opening specialized fabrication niches.
Carbon fiber-reinforced polymer infusion is rendering obsolete welded steel space-frame construction in premium expedition segments. Australian overland fleet operators now specify composite-intensive builds for corrosion resistance in coastal and desert environments. This technology shift is rendering obsolete the established supplier relationships that dominated chassis fabrication for two decades.
REACH substance restrictions and EU Green Deal carbon accounting requirements are reshaping material sourcing protocols for aluminum and composite suppliers. European import compliance now demands full lifecycle documentation that most Asia-Pacific fabricators cannot yet provide. Trailer manufacturers targeting EU expansion are consolidating supply chains within REACH-compliant jurisdictions.
Direct-to-consumer digital configuration platforms are displacing traditional dealer network pre-order models in North American recreational segments. Buyers now specify suspension travel, wall insulation ratings, and solar integration through manufacturer-hosted design tools. This channel transformation concentrates order flow with vertically integrated producers capable of custom fabrication at volume scale.
Global Off-Road Trailers Market Segmentation

Off-road trailer segmentation reveals divergent replacement cycles across construction types and duty ratings. Material selection and load classification together determine margin architecture and procurement channel access for manufacturers.
Trailer Type:
Enclosed configurations turn inventory slowest due to extended build-to-order cycles, while flatbed platforms rotate fastest through dealer lots and commercial fleet channels.
- Flatbed:Open-deck architecture with reinforced perimeter railings supports equipment hauling and modular living quarter installations. Western United States overland operators favor these for Bureau of Land Management dispersed camping access where payload flexibility outweighs weather protection needs.
- Enclosed:Integrated composite wall assemblies with climate-sealed interiors command premium positioning through HVAC integration and insulation ratings. Australia's overland expedition tourism operators specify these for extended desert and coastal corridor traverses where corrosion resistance and thermal regulation prove critical.
- Utility:Hybrid configurations bridge cargo transport and temporary shelter functions with removable side panels.
- Fifth Wheel:Hitch-mounted designs distribute tongue weight directly over tow vehicle axles for enhanced stability in extreme terrain grades.
Enclosed dominates installed base value concentration. Flatbed is where expansion concentrates for price-accessible entry segments.
Material:
Cost tier stratification separates aerospace-grade aluminum procurement from commodity steel fabrication, with composite infusion occupying emerging premium positioning.
- Aluminum:Extruded and welded alloy construction reduces chassis mass by substantial margins versus steel equivalents, improving tow vehicle fuel efficiency and expanding compatible vehicle range. Australian manufacturers leverage localized aluminum smelting capacity to compress lead times against trans-Pacific steel supply constraints.
- Composite:Carbon fiber-reinforced polymer monocoque fabrication eliminates welded joints and delivers corrosion immunity in salt-air and alkaline dust environments. European REACH substance restrictions and EU Green Deal carbon accounting requirements now demand full lifecycle documentation that favors consolidated supply chains within compliant jurisdictions.
- Steel:Traditional space-frame construction maintains cost leadership in commercial utility segments where weight sensitivity ranks below acquisition price.
- Fiberglass:Molded shell production enables curved aerodynamic profiles and seamless weather sealing for recreational overland applications.
Steel anchors volume production across price-sensitive commercial channels. Composite is climbing the fastest as regulatory compliance and performance specifications converge.
Load Capacity:
Customer type clustering separates recreational weekend users from military procurement channels where specification rigor limits supplier eligibility to heavy-duty classifications.
- Heavy Duty:Reinforced suspension systems with elevated ground clearance and dual-axle configurations support expedition-grade equipment transport across unimproved terrain. Australia's ADR braking mandates and structural integrity standards accelerate platform development for domestic and export markets where compliance certification creates supplier barriers.
- Extra Heavy Duty:Military-grade specifications with monocoque aluminum construction and independent suspension travel exceed twelve inches for rapid deployment logistics. FAA air cargo restrictions on trailer transport dimensions constrain rapid deployment options, compressing procurement specifications toward modular disassembly capabilities.
- Light Duty:Single-axle designs compatible with mid-size SUV tow ratings dominate entry-level recreational penetration.
- Medium Duty:Dual-purpose architectures bridge weekend recreational use and light commercial equipment hauling.
Medium Duty dominates unit shipments through dealer network volume. Extra Heavy Duty is gaining share fastest as defense procurement channels insulate demand from consumer cyclicality.
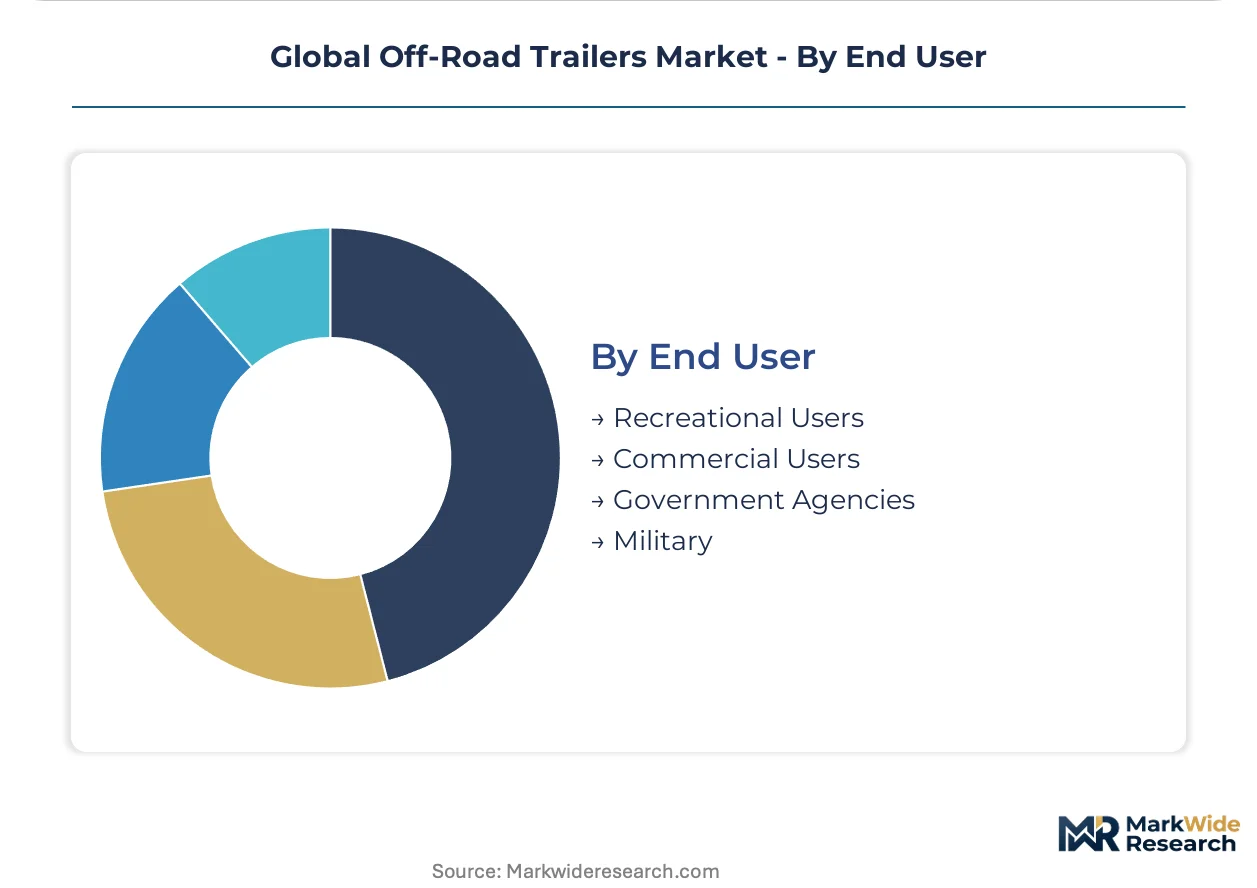
End User:
Application divergence creates fundamentally different product specifications between recreational comfort priorities and military durability requirements.
- Recreational Users:Direct-to-consumer digital configuration platforms now displace traditional dealer pre-order models, with buyers specifying suspension travel, wall insulation ratings, and solar integration through manufacturer-hosted design tools. This channel transformation concentrates order flow with vertically integrated producers capable of custom fabrication at volume scale.
- Military:Heavy-duty load classifications in defense procurement create insulated demand pools with limited supplier eligibility, where NHTSA lighting standards and CE marking timelines extend product launch cycles for multi-jurisdiction certification. Procurement specifications prioritize rapid field repairability and interoperability with existing logistics infrastructure.
- Commercial Users:Fleet operators in mining, agriculture, and remote construction prioritize total cost of ownership metrics over acquisition price.
- Government Agencies:Park services and emergency management departments specify standardized platforms for interoperability across dispersed operational territories.
Recreational Users anchor consumer-facing manufacturing capacity. Military is where margin expansion concentrates through specification-limited supplier pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA lighting and conspicuity standards in the United States establish the baseline for trailer safety certification that shapes export-bound production specifications. Regulatory divergence across major markets is fragmenting product development roadmaps and forcing manufacturers toward multi-jurisdiction compliance architectures.
United States
Bureau of Land Management terrain access in the western United States drives specialized off-grid trailer procurement from overland expedition operators. NHTSA trailer lighting standards govern conspicuity requirements for interstate commerce. Manufacturing activity concentrates in the Mountain West region where dispersed camping culture sustains demand for elevated ground clearance platforms.
Australia
ADR compliance requirements for trailer braking and suspension systems push manufacturers toward heavier-duty platform designs. Australia's structural integrity standards accelerate heavy-duty platform development for domestic and export markets. Domestic assembly expansion narrows the manufacturing gap as localized production controls lead times against trans-Pacific shipping constraints.
Germany
REACH substance restrictions and EU Green Deal carbon accounting requirements reshape material sourcing protocols for aluminum and composite suppliers. KBA vehicle certification standards govern trailer type approval for roadworthiness. Industrial clusters in Baden-Württemberg concentrate precision fabrication capacity for expedition-grade suspension systems.
China
GB standards for vehicle trailers establish technical specifications for domestic production and export qualification. MIIT industrial policy supports aluminum smelting capacity expansion that compresses material costs for chassis fabricators. Manufacturing gravity centers on the Yangtze River Delta where component supplier density enables rapid prototype iteration.
United Arab Emirates
Desert expedition tourism operators in Dubai and Abu Dhabi generate demand for corrosion-resistant composite construction in salt-air environments. MOHAP product safety frameworks govern consumer goods import standards. Logistics infrastructure in Jebel Ali Free Zone supports re-export distribution across Middle East and African markets.
Global Off-Road Trailers Market Competitive Environment
Vertically integrated specialists and regional fabricators split the market between premium expedition segments and price-accessible volume tiers. The vendor base concentrates among Australian and North American producers with established dealer network penetration. Three strategic archetypes dominate: composite-intensive premium builders, aluminum-focused weight-optimizers, and steel-based commercial utility suppliers. Competitive moves center on backward integration into chassis fabrication and geographic expansion through direct-to-consumer digital channels.
Within the premium expedition tier, BruderX and Patriot Campers exemplify divergent approaches to Australian market leadership. BruderX occupies a position anchored in military-grade construction protocols, while Patriot Campers represents vertically integrated control across suspension tuning and chassis fabrication. Black Series Campers sits within the volume-distribution archetype with North American dealer network density. These three Australian-origin entities illustrate how regulatory compliance expertise and material specialization stratify competitive positioning across price-performance segments.
| Leading Market Players |
|---|
| Black Series Campers |
| Airstream, Inc. |
| Patriot Campers |
| BruderX |
| Off Grid Trailers |
| Turtleback Trailers |
| Taxa Outdoors |
| Escapod Trailers |
| Opus Camper |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific container freight corridors from Shanghai to Long Beach transmit steel input volatility directly into Australian chassis fabricator margins, compressing cost structures for export-bound production while enabling price premiums for localized assembly in domestic markets.
Pricing Analysis
Geographic price spreads between Australian domestic assembly and Chinese import alternatives have widened as ADR compliance certification adds fifteen to twenty percent cost premiums for regulated markets. Three-tier pricing structure across expedition-grade, recreational-standard, and commercial-economy levels stratifies buyer segments, with military procurement channels showing lowest price sensitivity due to specification-limited supplier pools. Pricing pressure stems from steel input volatility and trans-Pacific logistics constraints, though composite-intensive builds retain margin insulation through material differentiation. Weekend recreational users exhibit highest price sensitivity, driving demand toward flatbed configurations and aftermarket modification pathways.
Supply Chain Analysis
Upstream feedstock flows for aluminum extrusion and carbon fiber-reinforced polymer concentrate in Chinese smelting capacity and Japanese precursor chemical production, with Australian bauxite refining providing regional raw material anchors. Chassis fabrication draws from Chinese steel rolling mills, German precision suspension component suppliers, and domestic Australian assembly operations. Single-source vulnerability in carbon fiber precursor supply creates concentration risk for composite-intensive builders targeting premium expedition segments. Distribution runs through North American dealer networks for volume recreational sales, direct-to-consumer digital platforms for custom configurations, and defense procurement channels for military specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Off-Road Trailers Market sits in early-cycle expansion as dispersed camping access on Bureau of Land Management terrain accelerates specialized off-grid trailer procurement beyond traditional recreational vehicle penetration curves.
For Market Incumbents: Entrench specification-limited supplier positions in military procurement channels through accelerated ADR and NHTSA certification investment, while capturing backward integration into aluminum smelting partnerships to offset steel input volatility. Threat substitution from highway trailers with aftermarket lift kits demands defensive innovation in suspension tuning expertise that concentrates among limited engineering teams. For New Entrants and Emerging Players: Establish a beachhead in European CE marking preparation ahead of regulatory divergence hardening, targeting the climate-integrated enclosure segment where REACH compliance creates incumbent vulnerability. The most penetrable white-space sits in modular disassembly capabilities for rapid deployment logistics constrained by FAA air cargo restrictions, with go-to-market execution through direct-to-consumer digital configuration platforms displacing traditional dealer pre-order models. For Investors and Strategic Acquirers: EU Green Deal carbon accounting requirements reshape the acquisition landscape toward REACH-compliant supply chain consolidation within European jurisdictions. Long-term viability frames around material substitution trajectories favoring composite-intensive fabrication with full lifecycle documentation capabilities. Acquisition target archetypes center on vertically integrated chassis fabricators with captive suspension tuning expertise. The signal to watch is defense procurement channel expansion rates as Extra Heavy Duty share gains accelerate.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Smelting | Captures localized feedstock supply against trans-Pacific steel cost volatility in Australian manufacturing. |
| CE Marking Pathway Investment | Opens European market entry before REACH substance restrictions harden regulatory barriers for Asia-Pacific fabricators. |
| Direct-to-Consumer Digital Launch | Displaces dealer network pre-order models with manufacturer-hosted configuration tools for custom fabrication scale. |
| Defense Procurement Channel Expansion | Accesses insulated demand pools with limited supplier eligibility through Extra Heavy Duty load classification certification. |
| Composite Supply Chain Consolidation | Consolidates carbon fiber precursor sourcing within EU Green Deal compliant jurisdictions for lifecycle documentation. |
Study Parameters
Operator-level perspectives from overland expedition fleet managers, chassis fabrication plant engineers, suspension system procurement leads at trailer OEMs, and defense logistics specification officers anchored the qualitative base for this study. Primary interview intelligence combined with secondary validation from ADR compliance filings, NHTSA trailer safety standards documentation, Bureau of Land Management dispersed camping access permits, and customs trade data for aluminum and steel inputs. Bottom-up demand modeling across trailer type, material, load capacity, and end user segments triangulated against top-down macroeconomic indicators.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning enclosed-flatbed-utility-fifth wheel configurations, aluminum-composite-steel-fiberglass material tiers, and recreational-military-commercial-government end user categories. CAGRs derived from trend extrapolation of fleet replacement cycles, regulatory compliance upgrade timelines, and material substitution trajectories. Industry-specific forecast inputs incorporated ADR braking mandate implementation schedules and FAA air cargo restriction evolution for military logistics procurement.
Macroeconomic conditions sit as an overlay; deviation in steel commodity pricing, trans-Pacific freight rates, or defense procurement budget allocations would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and material substitution adoption curves. Cross-checking against Bureau of Land Management permit issuance trends and defense logistics trailer procurement databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Off-Highway Wheels Market
Off Road Vehicles
Electric Off-Road Vehicles Market
Off Road Vehicles
Electric Utility-Terrain Vehicle (UTV) Market
Off Road Vehicles
Off-Road Vehicle Market
Off Road Vehicles
Off-Highway Vehicle HVAC Market
Off Road Vehicles
Europe Off-Highway Vehicle HVAC Market
Off Road Vehicles
Off-Road Vehicles Cooling Fan Market
Off Road Vehicles
Hybrid Off-Road Vehicle Market
Off Road Vehicles
Utility Terrain Vehicles (UTV) Market
Off Road Vehicles
Middle East and Africa Utility Terrain Vehicles Market
Off Road Vehicles
Off-Road High Performance Vehicle Market
Off Road Vehicles
Off Highway Vehicles Brake Systems Market
Off Road Vehicles
All-Terrain Vehicle (ATV) Engines Market
Off Road Vehicles
All-Terrain Vehicle Market
Off Road Vehicles
Automotive and Off-Road Vehicle Hoses Market
Off Road Vehicles
Snow Scooter Market