
 Off-Highway Diesel Common Rail Injection System Market | 2026-2036
Off-Highway Diesel Common Rail Injection System Market Size, Share, and Industry Trends Forecast 2026-2036
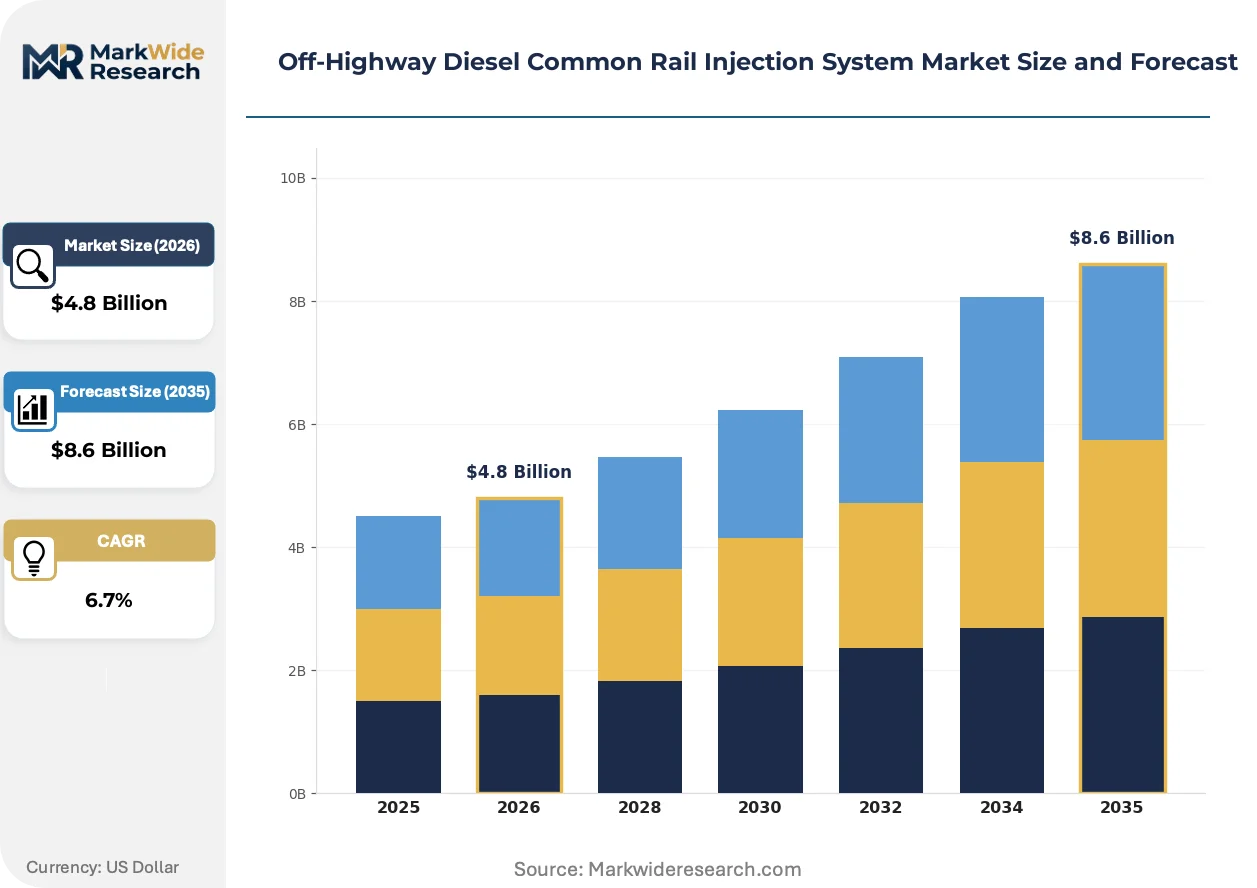
Off-Highway Diesel Common Rail Injection System Market Outlook
Consolidation among agricultural equipment OEMs is restructuring procurement patterns for diesel injection systems. Robert Bosch GmbH leverages its European manufacturing footprint to sustain high-pressure pump supply contracts with major tractor producers. Weichai Power Co. Ltd. anchors the Chinese market through captive engine production and backward integration into fuel system components. Denso Corporation differentiates via precision solenoid valve technology for construction machinery applications in Japan and Southeast Asia.
An off-highway diesel common rail injection system pressurizes fuel to 2,000–2,500 bar in a shared rail manifold before timed delivery through electronically controlled injectors, enabling precise combustion control for engines above 75 kW in non-road mobile machinery. CRDI technology dominates current installations due to its proven emissions reduction capability, while multi-stage injection architectures are gaining share in mining equipment where transient load response determines productivity. The 35mm injector segment occupies the largest volume position across agricultural tractors, though 40mm systems are expanding fastest in large mining haul trucks requiring higher fuel delivery rates.
The EPA Tier 4 Final mandate and EU Stage V regulations enforce particulate matter and NOx limits that compel OEMs to adopt advanced common rail architectures with closed-loop combustion control. China's MIIT implements GB 20891 non-road emission standards that align progressively with European test cycles, reshaping supplier qualification requirements for domestic manufacturers. Stakeholders must monitor regulatory divergence between EPA, ECHA, and Chinese GB standard update timelines when allocating R&D resources across regional product portfolios.
Market Dynamics
High-pressure common rail architectures are displacing mechanical pump-line-nozzle systems as EPA Tier 4 Final and EU Stage V emissions mandates tighten combustion precision requirements for engines above 75 kW. This technological substitution is restructuring supplier qualification criteria and procurement volumes across agricultural, construction, and mining equipment segments.
Growth Catalysts
- Stage V compliance deadlines:EU non-road mobile machinery regulations enforce closed-loop combustion control architectures that mandate 2,000+ bar injection pressures for NOx and particulate matter reduction.
- Mining productivity demands:Multi-stage injection strategies enable faster transient load response in large haul trucks, directly linking fuel system precision to equipment utilization rates.
- China:Domestic OEM expansion into medium- and heavy-duty off-highway machinery is concentrating demand for localized high-pressure pump and injector supply.
Market Restraints
- Precision manufacturing costs:Solenoid valve tolerances below 2 microns require specialized grinding equipment and cleanroom assembly, elevating capital intensity for component suppliers.
- Supply concentration:High-pressure rail forging and piezoelectric actuator sourcing concentrates among German and Japanese Tier 2 suppliers, creating single-source vulnerability.
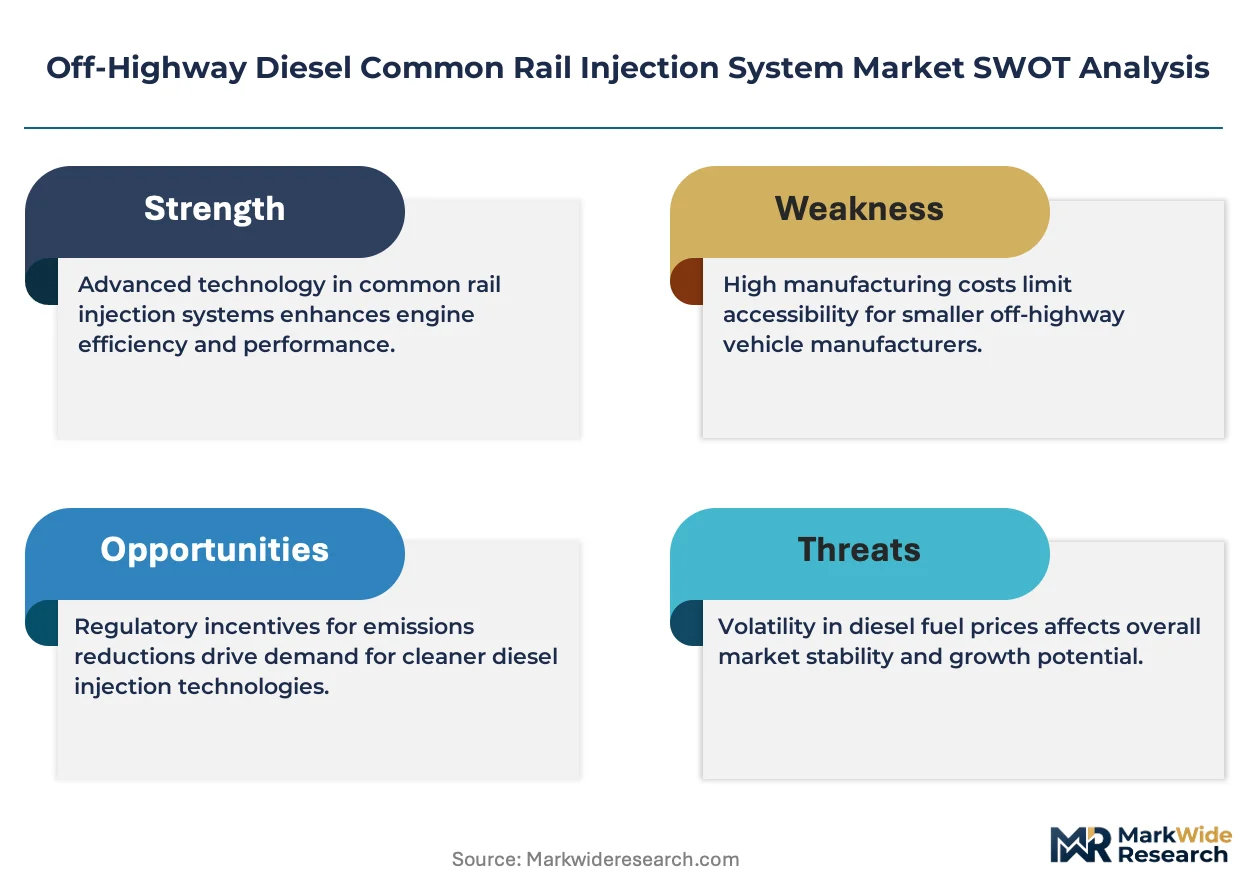
- Electrification substitution:Battery-electric powertrains for sub-75 kW construction equipment and autonomous mining haulage are compressing addressable diesel system volumes in specific horsepower bands.
Strategic Opportunities
- India:Tractor OEMs transitioning from mechanical to electronic fuel injection for BS-VI equivalent non-road standards create first-mover positioning for common rail system suppliers.
- Remanufacturing channels:Mining fleet operators extending asset life cycles through injector refurbishment programs generate recurring revenue streams independent of new equipment sales.
- Sensor fusion:Integration of cylinder pressure transducers with injection timing algorithms enables real-time combustion optimization, differentiating premium system architectures.
Industry Challenges
- Calibration engineering scarcity:Combustion modeling and injection map development for transient off-highway duty cycles require specialized expertise concentrated among aging European and Japanese engineering workforces.
- Homologation timeline compression:Divergent EPA, ECHA, and MIIT test cycle update schedules force parallel certification tracks that strain validation facility capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off-Highway Diesel Common Rail Injection System Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 25mm, 30mm, 35mm, 40mm Technology: CRDI, Multi-Stage Injection, Dual-Mass Damper, Fuel-Saving Technology End User: Agricultural Equipment, Construction Machinery, Mining Equipment, Marine Engines Installation: OEM, Aftermarket, Retrofit, New Installation |
| Companies Covered | Cummins Inc., Weichai Power Co. Ltd., Robert Bosch GmbH, Isuzu Motors Limited, Komatsu Ltd., Caterpillar Inc., Mitsubishi Heavy Industries Ltd., Kubota Corporation, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off-Highway Diesel Common Rail Injection System Market Strategic Shifts
Digital integration of fuel injection with engine management and telematics platforms is redefining system value propositions beyond hardware delivery. Suppliers are repositioning around combustion optimization software and predictive maintenance capabilities.
Multi-pulse injection strategies are unifying pilot, main, and post-injection events within single combustion cycles to simultaneously reduce particulate matter and NOx formation. Mining equipment manufacturers in Australia and Canada are adopting these architectures fastest due to high-altitude performance degradation concerns. The technology is unifying hardware and software development roadmaps, forcing fuel system suppliers to build embedded control competencies.
EPA enforcement of tampering penalties for emission defeat devices is tightening aftermarket modification liability for common rail system owners. Equipment rental fleets in the United States are responding by standardizing on factory-authorized service networks and encrypted calibration protocols. This regulatory pressure is consolidating authorized service channel control among OEM-captive distributors.
Equipment-as-a-service contracting is compressing injector replacement decision cycles from failure-based to predictive-interval schedules. Large agricultural cooperatives in Brazil and Ukraine are unbundling fuel system maintenance from full-machine service agreements. This shift concentrates purchasing authority with fleet management departments rather than traditional parts procurement functions.
Off-Highway Diesel Common Rail Injection System Market Segmentation
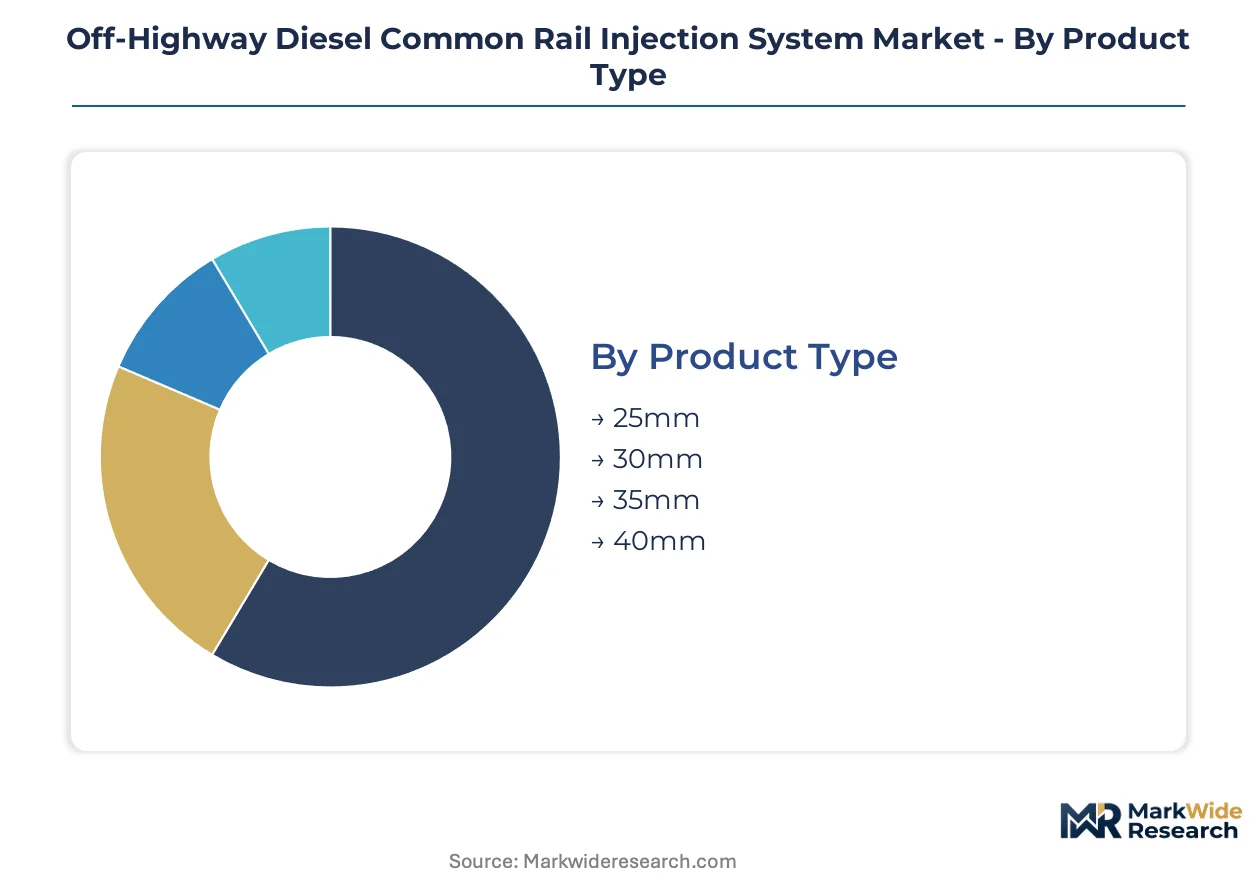
Equipment replacement cycles and emissions upgrade timelines fragment demand across injector sizes, combustion architectures, and installation channels. Procurement patterns diverge sharply between OEM line-fit programs and mining fleet refurbishment operations.
Product Type:
Injector diameter selection tracks directly to engine displacement upgrade waves and Tier 4 Final retrofit activity in mature markets.
- 35mm:Dominates agricultural tractor installations where 75-150 kW engines require balanced fuel delivery precision and component durability. Demand concentrates with European OEMs transitioning mechanical pump-line-nozzle fleets to electronic architectures in Poland and Romania.
- 40mm:Mining haul trucks above 300 kW deploy these systems for higher flow rates under transient load conditions. Australian iron ore operators drive specification intensity as altitude-compensated combustion becomes critical for pit-to-crusher productivity metrics.
- 25mm:Compact utility equipment and small tractors under 75 kW deploy these injectors where packaging constraints limit rail manifold sizing.
- 30mm:Mid-range construction loaders and excavators in the 100-200 kW band standardize on this diameter for cost-optimized Tier 4 Interim compliance.
Volume placements concentrate in 35mm systems; the faster expansion belongs to 40mm configurations.
Technology:
Cost tier differentiation separates proven emissions-compliant architectures from emerging precision combustion strategies.
- CRDI:The baseline high-pressure common rail architecture pressurizes fuel to 2,000-2,500 bar for electronically timed delivery. Construction machinery OEMs in Germany and Japan anchor procurement volumes for proven NOx reduction capability.
- Multi-Stage Injection:Pilot, main, and post-injection sequencing within single cycles enables simultaneous particulate matter and NOx reduction. Mining equipment manufacturers in Canada adopt these systems fastest for high-altitude performance retention.
- Dual-Mass Damper:Vibration isolation technology protects rail manifold integrity in severe-duty mining applications with high torsional oscillation.
- Fuel-Saving Technology:Combustion optimization algorithms and adaptive injection mapping target fuel consumption reduction in long-cycle agricultural operations.
Revenue concentration sits with CRDI platforms; steepest expansion trajectory belongs to multi-stage architectures.
End User:
Application-specific duty cycles dictate injection pressure requirements and refurbishment frequency.
- Agricultural Equipment:Tractors and harvesters with seasonal utilization patterns prioritize reliability over peak precision. Brazilian soybean cooperatives drive aftermarket injector replacement volumes through extended harvest season utilization.
- Construction Machinery:Excavators and wheel loaders with stop-start transient operation demand rapid load response. Chinese domestic OEM expansion concentrates new installation demand for medium-duty equipment.
- Mining Equipment:Continuous-duty haul trucks require extended injector service intervals and predictive replacement scheduling. Chilean copper operations lead adoption of cylinder pressure sensor integration for real-time combustion adjustment.
- Marine Engines:Propulsion and auxiliary systems in commercial vessels face IMO Tier III compliance timelines with distinct injection timing requirements.
Procurement volume aggregates in agricultural channels; mining applications generate premium pricing through sensor-fusion differentiation.
Installation:
Customer type and margin structure diverge between captive OEM supply and independent service channels.
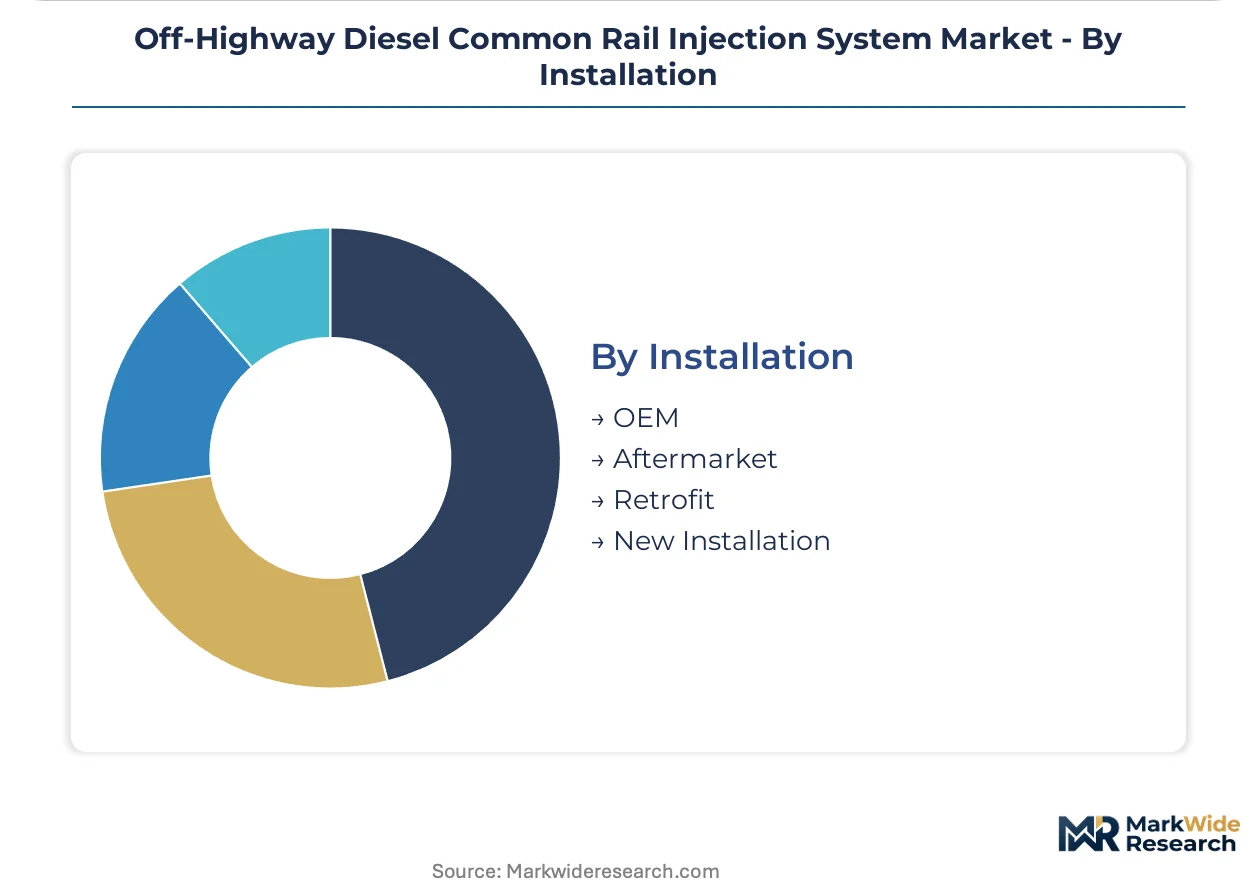
- OEM:Factory line-fit installations dominate new equipment production with encrypted calibration protocols and warranty-integrated service terms. John Deere and CNH Industrial procurement consolidation reshapes supplier qualification requirements.
- Aftermarket:Authorized service networks capture emission-compliant replacement demand as EPA tampering enforcement tightens. United States rental fleet standardization drives channel consolidation toward OEM-captive distributors.
- Retrofit:Tier 4 Final and Stage V upgrade programs for in-service equipment create specialized calibration engineering demand. Indian tractor OEMs transitioning from mechanical injection generate first-mover retrofit opportunity.
- New Installation:Greenfield production lines and capacity expansion projects concentrate in Chinese domestic OEM facilities.
Revenue weighting favors OEM channels; aftermarket expansion accelerates through fleet predictive maintenance contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates procurement volumes as domestic OEMs expand medium- and heavy-duty off-highway production capacity. Tier 4 Final and Stage V compliance deadlines in mature markets are redirecting supplier investment toward high-pressure pump and injector manufacturing.
China
Weichai Power Co. Ltd. anchors demand through captive engine production and backward integration into fuel system components. MIIT implements GB 20891 non-road emission standards that align progressively with European test cycles. Shandong Province hosts concentrated manufacturing clusters where domestic suppliers qualify for high-pressure rail forging contracts.
United States
EPA Tier 4 Final mandates enforce closed-loop combustion control architectures for engines above 75 kW. Equipment rental fleets standardize on factory-authorized service networks as tampering enforcement tightens. Illinois and Iowa agricultural machinery corridors drive aftermarket injector replacement volumes through seasonal utilization patterns.
Germany
Robert Bosch GmbH leverages its European manufacturing footprint to sustain high-pressure pump supply contracts with major tractor producers. ECHA REACH regulations govern chemical substance restrictions in fuel system materials. Stuttgart and Munich engineering clusters concentrate combustion modeling expertise for transient off-highway duty cycles.
Japan
Denso Corporation differentiates via precision solenoid valve technology for construction machinery applications. METI industrial policy supports advanced manufacturing equipment for sub-micron tolerance grinding operations. Nagoya and Tokyo metropolitan areas host specialized cleanroom assembly facilities for piezoelectric actuator production.
India
Tractor OEMs transition from mechanical to electronic fuel injection for BS-VI equivalent non-road standards. BIS certification requirements reshape supplier qualification criteria for domestic manufacturers. Maharashtra and Gujarat industrial corridors generate first-mover positioning opportunities for common rail system suppliers establishing localized production.
Off-Highway Diesel Common Rail Injection System Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue sensor fusion and predictive maintenance software. The market structures around three tiers: integrated engine manufacturers with captive fuel system production, specialized component suppliers with precision manufacturing capabilities, and regional fabricators serving aftermarket refurbishment channels. Consolidation among agricultural equipment OEMs compresses supplier counts while elevating qualification barriers. Dominant competitive moves include backward integration into high-pressure rail forging and strategic partnerships for cylinder pressure sensor integration.
Within the integrated engine manufacturer tier, Cummins Inc., Caterpillar Inc., and Weichai Power Co. Ltd. exemplify archetypes that combine propulsion system design with captive fuel injection component sourcing. Robert Bosch GmbH and Denso Corporation occupy positions as specialized precision component suppliers with established European and Asian manufacturing footprints respectively. Isuzu Motors Limited and Kubota Corporation represent mid-scale engine producers navigating procurement consolidation through long-term supply agreements. Komatsu Ltd. and Mitsubishi Heavy Industries Ltd. anchor mining equipment applications where extended service intervals and predictive replacement scheduling command premium positioning.
| Leading Market Players |
|---|
| Cummins Inc. |
| Weichai Power Co. Ltd. |
| Robert Bosch GmbH |
| Isuzu Motors Limited |
| Komatsu Ltd. |
| Caterpillar Inc. |
| Mitsubishi Heavy Industries Ltd. |
| Kubota Corporation |
| Denso Corporation |
| Others |
Value Chain & Pricing Dynamics
Precision grinding specialists concentrated in Stuttgart and Nagoya feed labor-cost differentials into three-tier pricing stratification across premium sensor-fusion systems, standard CRDI architectures, and economy mechanical retrofits. Tier 4 Final compliance engineering premiums widen spreads between encrypted OEM line-fit contracts and aftermarket refurbishment channels.
Pricing Analysis
High-volume 35mm agricultural injector contracts sacrifice margin for fleet placement, while 40mm mining systems with cylinder pressure integration capture premium positioning. Price differentiation separates EPA-certified encrypted calibrations from unlicensed aftermarket alternatives. Cost compression in standard CRDI hardware intensifies as Chinese domestic OEMs scale captive production. Brazilian agricultural cooperatives exhibit highest price sensitivity; Australian mining operators prioritize altitude-compensated performance over unit cost.
Supply Chain Analysis
EPA and ECHA certification gates restrict high-pressure rail forging to qualified German and Japanese Tier 2 suppliers. Geographic supply concentration centers on Germany for precision pump assemblies, Japan for piezoelectric actuators, and China for localized rail manifold production. Raw material dependencies include specialized alloy steels, rare-earth ceramics for actuators, and high-purity fuel filtration media. Single-source vulnerability in sub-micron solenoid valve grinding equipment creates structural risk. Distribution runs through OEM-captive authorized service networks tightening under EPA tampering enforcement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around procurement consolidation among agricultural equipment OEMs, forcing sub-scale precision component suppliers into acquisition or exit. Tier 4 Final calibration engineering scarcity accelerates competitive thinning.
For Market Incumbents: Anchor high-pressure pump supply relationships through backward integration into rail forging capacity in Shandong Province. Secure cylinder pressure sensor partnerships before combustion optimization software becomes table stakes. Defend against electrification substitution by extending predictive maintenance contracts into mining fleet management systems. For New Entrants and Emerging Players: Independent Indian tractor OEMs transitioning from mechanical injection represent the most penetrable buyer archetype. Target BS-VI equivalent retrofit channels with localized calibration engineering partnerships. Pursue sensor fusion development for real-time combustion adjustment in Chilean copper mining operations. For Investors and Strategic Acquirers: Re-rating potential sits with precision solenoid valve specialists given Stage V compliance deadlines tightening sub-micron tolerance requirements. Long-term viability favors suppliers with embedded control competencies unifying hardware and software roadmaps. Watch for EPA-ECHA-MIIT regulatory divergence as inflection indicator for regional portfolio reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rail Forging | Captive supply of high-pressure manifolds secures Tier 4 Final qualification with Deere and CNH Industrial procurement teams. |
| Cylinder Pressure Sensor Partnership | Real-time combustion optimization differentiates premium architectures for Australian altitude-compensated mining applications. |
| Localized Production in Maharashtra | BS-VI equivalent compliance positions first-mover suppliers for Indian tractor OEM electronic fuel injection transitions. |
| Predictive Maintenance Platform Launch | Equipment-as-a-service contracting unbundles fuel system purchasing authority toward fleet management departments. |
| Encrypted Calibration Protocol Development | EPA tampering enforcement consolidates authorized service channel control among OEM-captive distributors. |
Study Parameters
Independent corroboration across OEM procurement directors, aftermarket service network managers, and Tier 2 component engineering heads underwrites the qualitative findings. Primary fieldwork with high-pressure pump manufacturing specialists, mining fleet maintenance supervisors, and agricultural cooperative equipment managers combined with secondary validation from SEC filings of listed engine manufacturers, EPA enforcement action databases, and MIIT GB standard update notices. Bottom-up injector shipment estimates and top-down equipment production aggregates were cross-referenced for triangulation.
Rate-of-change decomposition across equipment replacement cycles, emissions upgrade timelines, and regional production capacity expansion generated volume and value trajectories. Segmentation dimensions modeled include injector diameter, combustion architecture, end-use application, and installation channel alongside regional regulatory cluster alignment. CAGRs were derived from fitted growth curves applied to historical shipment data. Industry-specific forecast inputs incorporated Tier 4 Final and Stage V compliance deadline phasing, plus Chinese domestic OEM capacity buildout schedules.
Revisions become necessary when EPA-ECHA-MIIT regulatory divergence accelerates, electrification substitution compresses addressable diesel volumes faster than projected, or precision manufacturing equipment lead times extend beyond supplier qualification windows. Forecasts reflect assumptions regarding emission standard enforcement continuity and mining commodity price support for fleet reinvestment. A model refresh is warranted upon material change in OEM procurement consolidation velocity or battery-electric powertrain cost parity timing in sub-75 kW construction equipment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
All-Terrain Vehicle Market
Off Road Vehicles
Off Road Motorcycles Market
Off Road Vehicles
Amphibious ATV Market
Off Road Vehicles
Snowmobile Market
Off Road Vehicles
Off-Highway Vehicle HVAC Market
Off Road Vehicles
Utility Terrain Vehicles (UTV) Market
Off Road Vehicles
Small Off-Road Engines Market
Off Road Vehicles
Off-Highway Vehicle Engine Market
Off Road Vehicles
Off Road All Terrain E-Scooter Market
Off Road Vehicles
Off-Road High Performance Vehicle Market
Off Road Vehicles
Off Highway Vehicles Brake Systems Market
Off Road Vehicles
Global Off-Road Trailers Market
Off Road Vehicles
Hybrid Off-Road Vehicle Market
Off Road Vehicles
Off-Highway Engine Market
Off Road Vehicles
Electric Off-Road Vehicles Market
Off Road Vehicles
US Off-Road Vehicles Market