
 Off-Highway Vehicle Market | 2026-2036
Off-Highway Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Off-Highway Vehicle Market Outlook
Skilled diesel technician shortages across North American dealer networks is reorganizing service capacity and aftermarket parts flow. Polaris Inc. sustains brand strength in recreational side-by-sides through proprietary chassis architectures. Yamaha Motor Company dominates small-displacement utility ATVs across Asian plantation economies. Mahindra & Mahindra Ltd. anchors tractor-derived off-highway platforms across South Asian and African markets.
Off-highway vehicles encompass wheeled and tracked machines operating beyond public roadways, typically powered by compression-ignition engines rated from below 50 HP to above 150 HP and constructed with high-strength steel frames, hydrostatic or powershift transmissions, and purpose-built undercarriages for soil, rock, or uneven terrain. These machines perform earthmoving, material handling, and traction tasks in agriculture, construction, mining, and landscaping where on-road certification provides no operational benefit. Excavators and skid-steer loaders command the largest installed base and replacement parts revenue pools, while bulldozers above 150 HP retain concentrated margin pools in mining applications. The below 50 HP segment serves landscaping and smallholder agriculture with price-sensitive, high-volume production, whereas 101-150 HP machines balance power density with fuel efficiency in mid-scale construction and broadacre farming.
EPA Tier 4 Final standards in the United States and EU Stage V regulations in Europe mandate diesel particulate filters, selective catalytic reduction, and onboard diagnostics, adding cost and complexity to engine supply chains. OSHA and MSHA inspection protocols in the United States further shape operator protection structures and rollover protection system specifications across construction and mining fleets. Stakeholders must monitor how California Air Resources Board waivers and impending Euro 7 deliberations recalibrate engine development roadmaps against electrification timelines.
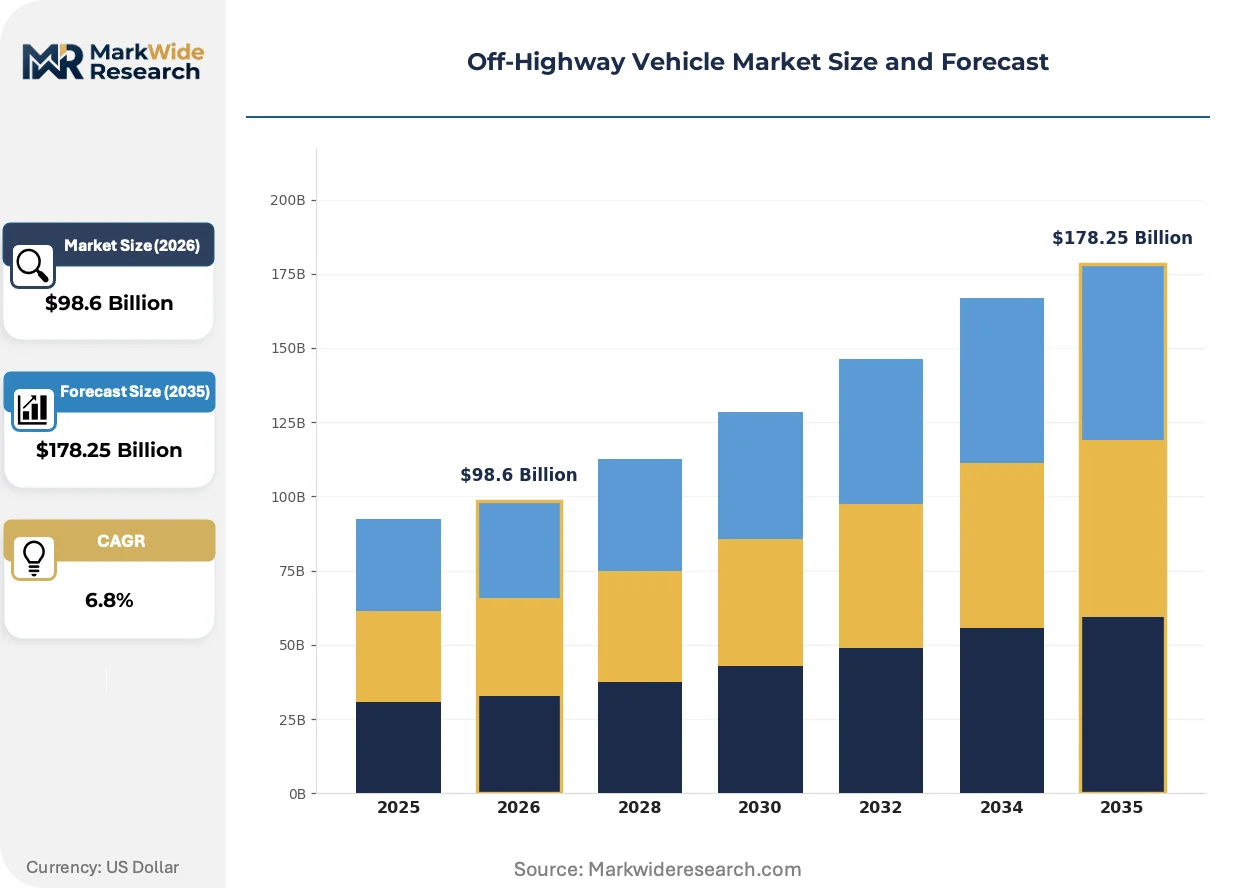
Market Dynamics
EPA Tier 4 Final and EU Stage V emissions mandates are compressing engine architecture choices while electrification timelines remain uncertain, forcing manufacturers to maintain dual development tracks for compression-ignition and battery-electric powertrains.
Growth Catalysts
- Broadacre mechanization:Australian and Brazilian grain operations are replacing aging tractor fleets with higher-horsepower articulated platforms to expand cultivation windows and reduce labor dependency.
- EU Stage V compliance:The regulation's particulate matter and nitrogen oxide limits are accelerating selective catalytic retrofits and creating aftermarket service revenue pools for certified technicians.
- Lithium extraction expansion:Chilean and Australian hard-rock and brine operations are scaling fleet orders for underground loaders and articulated haulers to match battery supply chain commitments.
Market Restraints
- Aftertreatment cost inflation:Diesel particulate filters and selective catalytic reduction systems now constitute 15-20% of engine bill-of-materials, compressing margin at sub-75 HP price points.
- Dealer technician scarcity:North American service networks face structural shortfalls in EPA-certified diesel mechanics, extending repair turnaround times and stranding fleet utilization rates.
- Steel and hydraulics concentration:High-strength plate and precision hydraulic component supply clusters in East Asian forging centers expose OEMs to shipping rate volatility and tariff friction.
Strategic Opportunities
- Telematics-enabled uptime contracts:Construction and mining fleets in Chile are piloting outcome-based service agreements where OEMs retain ownership and charge per operating hour.
- Smallholder mechanization:Sub-50 HP tractor demand across South Asian and African plantation economies remains underserved by premium-brand distribution networks.
- Battery-electric retrofit pathways:California Air Resources Board incentive structures are creating white space for repower kits that convert Tier 2-3 machines to zero-emission operation without full replacement.
Industry Challenges
- Dual-certification engineering:OEMs must maintain parallel EPA Tier 4 Final and EU Stage V validation tracks while prototyping battery-electric architectures, stretching R&D bandwidth across three powertrain generations.
- Embedded software complexity:Onboard diagnostics mandated by emissions regulations require cybersecurity-hardened telematics integration, creating warranty exposure and over-the-air update infrastructure costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off-Highway Vehicle Market |
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Excavators, Bulldozers, Forklifts, Skid-Steer Loaders Engine Capacity: Below 50 HP, 51-100 HP, 101-150 HP, Above 150 HP Application: Agriculture, Construction, Mining, Landscaping End User: Agricultural Sector, Construction Firms, Mining Companies, Rental Services |
| Companies Covered | BRP Inc., Arctic Cat Inc., Polaris Inc., CFMOTO Powersports Inc., Suzuki Motor Corporation, Yamaha Motor Company, Kawasaki Heavy Industries, Ltd., Mahindra & Mahindra Ltd., Honda Motor Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off-Highway Vehicle Market Strategic Shifts
Powertrain architecture is fragmenting along emissions compliance lines, with electrification advancing fastest in regulated urban construction zones while remote mining and agricultural applications extend diesel platform life through aftertreatment sophistication.
Electrification is bifurcating the product portfolio into battery-electric machines for sub-150 HP urban construction and hybrid-assisted diesel architectures for remote mining haulage where charging infrastructure remains uneconomical. Municipal fleets in California and New York are absorbing early-production electric excavators despite acquisition premiums, while Australian iron ore operations are extending diesel hauler replacement cycles through engine rebuild programs. This technology divergence is compressing R&D resource allocation and forcing suppliers to maintain competency across competing energy storage chemistries and thermal management systems.
EU Stage V enforcement through the European Commission's market surveillance framework is eliminating non-compliant engine imports and consolidating certified supplier relationships around established OEMs with in-house aftertreatment integration. The regulation's portable emissions measurement system testing protocols are extending type-approval timelines by 8-12 months, favoring incumbents with regulatory affairs capacity over emerging competitors. Construction equipment rental fleets in Germany and France are accelerating turnover to Stage V-certified machines to preempt municipal tender restrictions.
Service unbundling is disrupting traditional dealer-captive maintenance relationships as large mining and agricultural fleets insource diagnostics through proprietary telematics platforms and third-party parts sourcing. Komatsu and Caterpillar fleet management systems face displacement by independent software vendors offering multi-brand visibility, particularly in Chilean copper operations and Brazilian soybean logistics chains. This pattern is most pronounced in geographies with dense fleet concentrations where scale justifies dedicated technical staff and direct OEM negotiation leverage.
Off-Highway Vehicle Market Segmentation
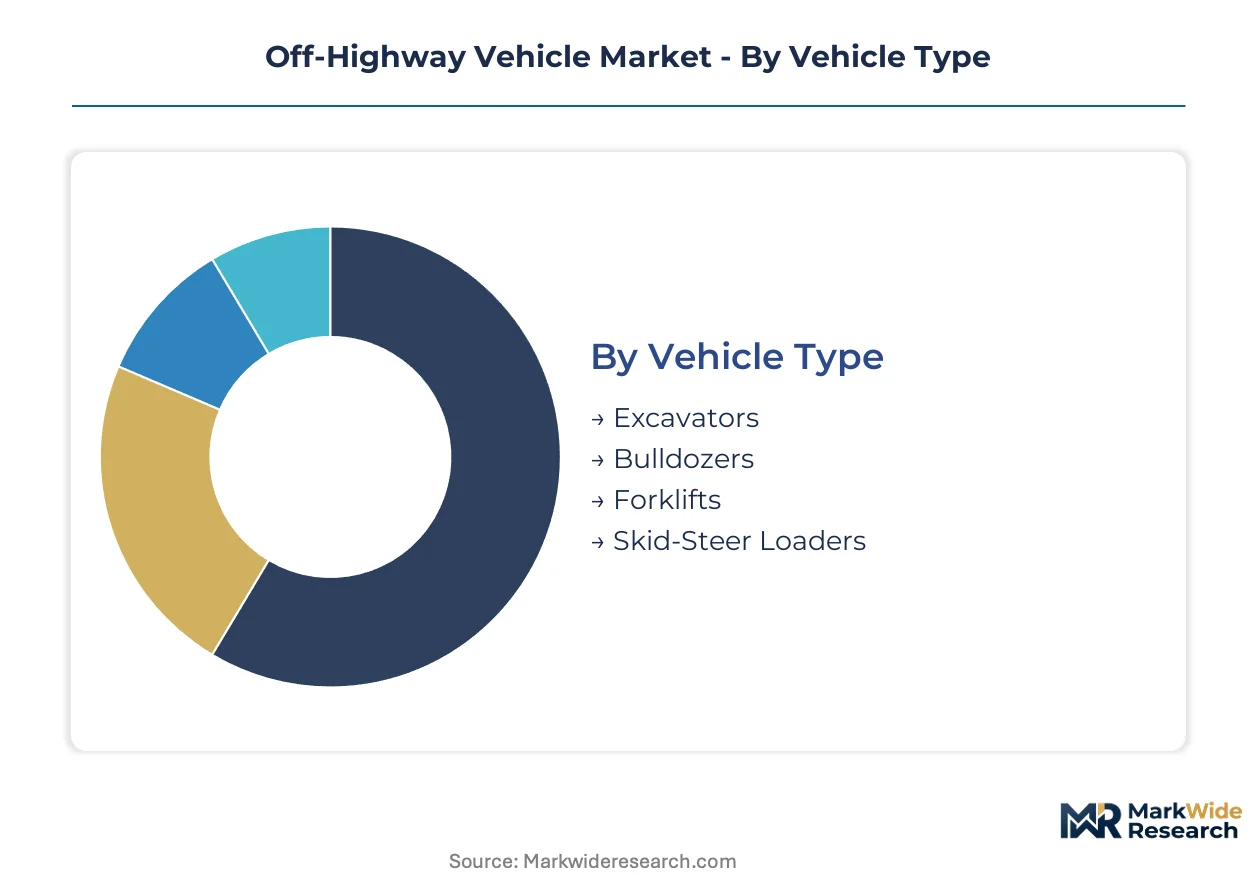
Segmentation in off-highway vehicles reveals how emissions architecture, power density requirements, and fleet ownership models fragment procurement patterns across end-use verticals. Equipment specifications diverge sharply between regulated urban construction zones and remote mining or agricultural operations.
Vehicle Type:
EPA Tier 4 Final and EU Stage V regulations differentiate compliance pathways across machine architectures, with excavators and skid-steer loaders facing distinct aftertreatment packaging constraints versus bulldozers and forklifts.
- Excavators:Hydraulic crawler and wheeled configurations dominate earthmoving fleets with operating weights from 6 to 90 metric tons. Australian iron ore operations and Chilean copper mines are standardizing on 30-50 ton class units for loading haul trucks, driven by fleet automation integration and fuel burn optimization targets.
- Skid-Steer Loaders:Compact rigid-frame machines with rated operating capacities from 700 to 3,700 pounds serve landscaping and light construction. Municipal fleets in California and rental yards across the US Great Plains are absorbing electric prototypes despite acquisition premiums, constrained by charging infrastructure gaps in exurban job sites.
- Bulldozers:Tracked tractors above 150 HP retain concentrated margin pools in mining applications where drawbar pull and blade capacity prioritize thermal efficiency over electrification timelines.
- Forklifts:Telehandlers and rough-terrain variants bridge material handling across construction logistics chains, with lithium-ion conversions advancing fastest in warehouse-adjacent yards.
Excavators handle the majority of throughput; skid-steer loaders are gaining share fastest on electrification momentum.
Engine Capacity:
Cost tier stratification aligns with aftertreatment burden, as sub-75 HP machines face acute margin compression from diesel particulate filter and selective catalytic retrofits.
- Below 50 HP:Compact utility platforms for landscaping and smallholder agriculture. Brazilian Cerrado grain operations and North American rental fleets drive volume, though price sensitivity limits OEM pricing power.
- 51-100 HP:Mid-range tractors and compact loaders balancing power with fuel efficiency. Indian and Indonesian plantation economies absorb significant volume through Mahindra-derived platforms.
- 101-150 HP:Broadacre farming and mid-scale construction applications. Australian grain operators are replacing aging fleets with articulated tractors in this bracket to expand cultivation windows and reduce labor dependency.
- Above 150 HP:Mining haulers and large dozers where engine rebuild programs extend platform life. Chilean lithium extraction operations are scaling articulated hauler orders in this segment to match battery supply chain commitments.
Machines above 150 HP capture the dominant share of aftermarket revenue; below 50 HP equipment shows the steepest expansion trajectory in emerging plantation economies.
Application:
Volume concentration varies by geography, with agricultural mechanization advancing across the North American Great Plains and Brazilian Cerrado while mining fleet renewal concentrates in Australia and Chile.
- Agriculture:Tractors, harvesters, and tillage equipment serving broadacre grain and plantation crops. Mechanization rates in South Asia and sub-Saharan Africa remain underserved by premium-brand distribution networks.
- Construction:Earthmoving and material handling fleets facing municipal tender restrictions in Germany and France that mandate EU Stage V certification.
- Mining:Underground loaders and articulated haulers for hard-rock and brine extraction. Fleet management systems here face displacement by independent software vendors offering multi-brand visibility.
- Landscaping:Compact loaders and utility vehicles with sub-50 HP engines. California Air Resources Board incentive structures are creating white space for repower kits converting Tier 2-3 machines to zero-emission operation.
Agriculture commands the largest installed base; mining exhibits the fastest climb on lithium extraction scaling.
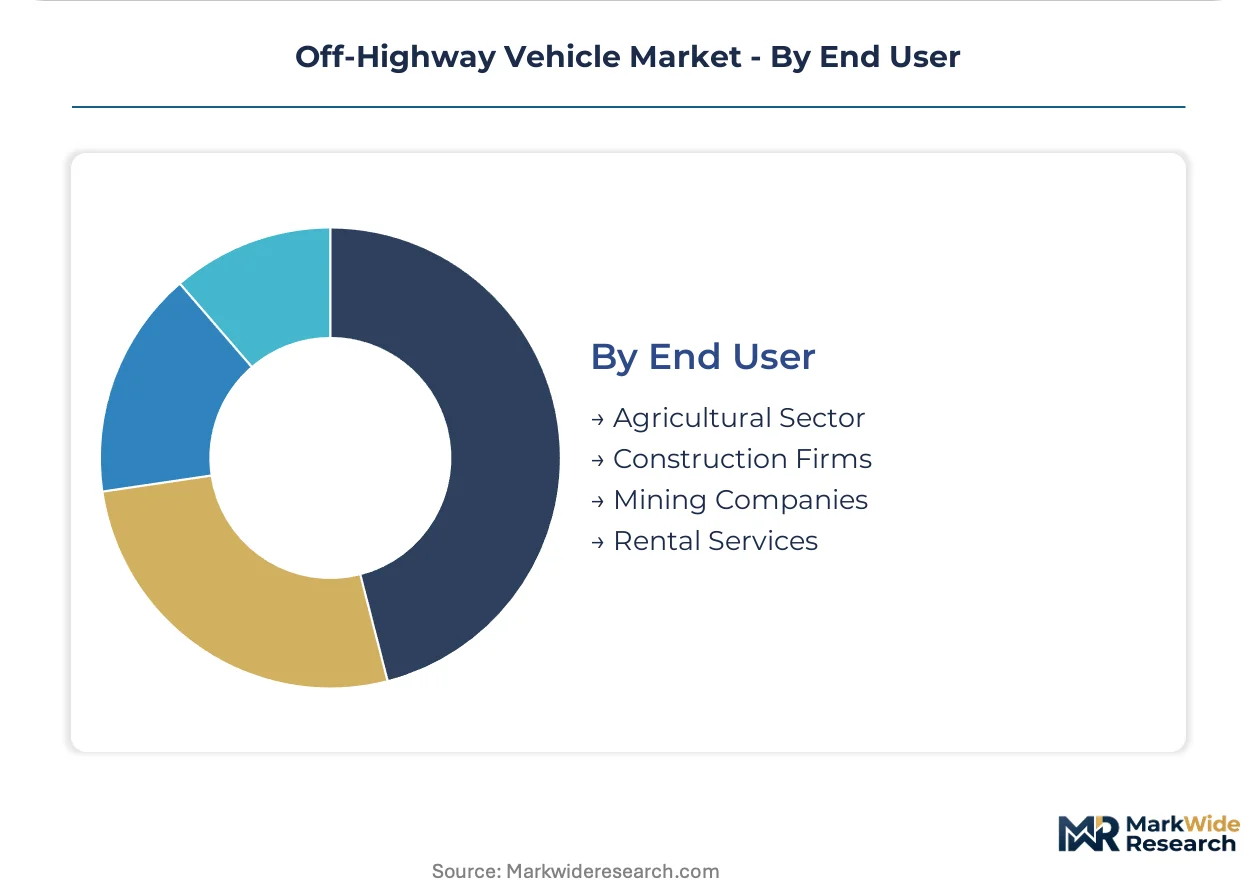
End User:
Customer type determines procurement architecture, with rental services and mining companies diverging from agricultural owner-operators on telematics adoption and service contract structures.
- Agricultural Sector:Owner-operators and cooperative fleets prioritizing total cost of ownership over acquisition price. Smallholder mechanization gaps persist across South Asian and African markets.
- Construction Firms:Project-based procurement with increasing preference for outcome-based service agreements where OEMs retain ownership and charge per operating hour.
- Mining Companies:Large fleet operators insourcing diagnostics through proprietary telematics platforms and third-party parts sourcing, particularly in Chilean copper operations.
- Rental Services:Equipment lessors accelerating turnover to Stage V-certified machines to preempt municipal tender restrictions in European urban construction zones.
Agricultural sector owners represent the broadest customer base; rental services are expanding most quickly on fleet modernization cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia deploys off-highway vehicles predominantly in mining automation, while Brazil concentrates on agricultural mechanization, creating divergent specification requirements across these volume markets.
United States
Great Plains grain operators are replacing aging tractor fleets with higher-horsepower articulated platforms to expand cultivation windows. EPA Tier 4 Final standards mandate diesel particulate filters and selective catalytic reduction across all engine classes. California's Central Valley and Texas Panhandle host dense equipment populations where CARB incentive structures are piloting battery-electric retrofit pathways for existing fleets.
Australia
Iron ore and lithium extraction operations are scaling fleet orders for underground loaders and articulated haulers to match battery supply chain commitments. The country's national environmental regulator enforces stringent emissions testing protocols for imported mining equipment. Western Australia's Pilbara region concentrates autonomous haul truck deployments where fleet management systems face displacement by independent software vendors.
Brazil
Cerrado grain operations drive demand for sub-75 HP tractors and mid-range harvesters amid labor scarcity and expanding cultivation frontiers. ANVISA and environmental licensing shape equipment import standards and local assembly requirements. São Paulo state anchors manufacturing clusters where Mahindra-derived platforms serve plantation economies across Latin America.
Germany
Construction equipment rental fleets are accelerating turnover to EU Stage V-certified machines to preempt municipal tender restrictions in urban zones. The European Commission's market surveillance framework eliminates non-compliant engine imports through portable emissions measurement system testing. Bavaria and Baden-Württemberg host precision hydraulic component suppliers exposed to steel price volatility and energy cost pressures.
Chile
Copper and lithium extraction operations are standardizing on 30-50 ton class excavators for loading haul trucks, driven by fleet automation integration targets. National mining and environmental regulators enforce operator protection structures and rollover protection system specifications across underground and open-pit fleets. The Atacama Desert mining corridor concentrates articulated hauler demand where telematics-enabled uptime contracts are displacing traditional dealer-captive maintenance relationships.
Off-Highway Vehicle Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with market structure consolidating around full-line manufacturers with captive engine development and aftertreatment integration capabilities. The middle tier fragments across regional assemblers dependent on outsourced powertrain supply and third-party hydraulic systems. Two strategic archetypes dominate: diversified industrial conglomerates with agricultural and construction equipment portfolios, and focused powersports specialists leveraging proprietary chassis architectures for recreational segments. Competitive dynamics center on dual-certification engineering bandwidth for EPA and EU compliance tracks, alongside telematics infrastructure investments to capture service revenue from fleet operators.
Among powersports-focused manufacturers, Polaris Inc. and Yamaha Motor Company occupy distinct positioning vectors within the recreational and utility ATV segments. BRP Inc. and Arctic Cat Inc. exemplify North American-engineered recreational platform specialists with established distribution across dealer networks facing technician scarcity pressures. Mahindra & Mahindra Ltd. anchors the tractor-derived off-highway tier across South Asian and African plantation economies, representing the diversified industrial conglomerate archetype with backward integration into diesel engine manufacturing. These named entities illustrate how geographic origin and corporate structure correlate with served end-use verticals, from Australian mining automation to Brazilian broadacre mechanization.
| Leading Market Players |
|---|
| BRP Inc. |
| Arctic Cat Inc. |
| Polaris Inc. |
| CFMOTO Powersports Inc. |
| Suzuki Motor Corporation |
| Yamaha Motor Company |
| Kawasaki Heavy Industries, Ltd. |
| Mahindra & Mahindra Ltd. |
| Honda Motor Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day engine component lead times in North American dealer networks concentrate pricing power with OEMs possessing captive aftertreatment integration, while spot-market steel volatility feeds back into tiered equipment quotations across agricultural and mining procurement channels.
Pricing Analysis
Long-term fleet service contracts dominate mining and large agricultural procurement, locking in per-operating-hour rates that insulate OEMs from spot steel volatility. Three-tier pricing structure across premium, standard, and economy levels differentiates by EPA Tier 4 Final certification completeness and telematics bundling. Cost compression in sub-75 HP equipment is intensifying because diesel particulate filter and selective catalytic retrofits now constitute substantial engine bill-of-materials. Smallholder owner-operators across South Asian plantation economies exhibit acute price sensitivity, whereas Australian iron ore mining companies prioritize uptime guarantees over acquisition cost.
Supply Chain Analysis
Port congestion across Shanghai-Ningbo and Busan trade lanes elevates inbound logistics costs for precision hydraulic components and high-strength steel plate destined for North American assembly plants. Manufacturing concentration in China, South Korea, and Germany anchors forging capacity for critical undercarriage components and emissions aftertreatment systems. Component sourcing rests on rare earth elements for catalytic substrates, high-grade steel plate, and semiconductor chips for onboard diagnostics. Single-source vulnerability in East Asian forging centers exposes OEMs to tariff friction and shipping rate spikes. Distribution runs through captive dealer networks facing technician scarcity, with independent parts distributors gaining share in Chilean and Australian mining corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation across Australian iron ore and Chilean copper belts concentrates buyer leverage, compressing OEM margin capture and forcing service unbundling across traditional dealer-captive maintenance relationships.
For Market Incumbents: Shield margin pools in above-150 HP mining haulers through engine rebuild program extensions and captive aftertreatment integration that emerging competitors cannot replicate. Fortify EPA-certified technician training pipelines to deflect service revenue erosion from independent software vendors offering multi-brand telematics visibility. Priority investment in battery-electric retrofit kit development addresses California Air Resources Board incentive structures without full platform replacement cycles. For New Entrants and Emerging Players: EU Stage V certification fast-track through portable emissions measurement system pre-validation offers entry wedge into German and French construction rental fleets facing municipal tender restrictions. Target sub-50 HP smallholder mechanization gaps across South Asian and African plantation economies where premium-brand distribution networks remain sparse. Go-to-market through regional assembly partnerships with Mahindra-derived platform licensors bypasses captive engine development overhead. For Investors and Strategic Acquirers: Long-term, this sits as a aftermarket-service-revenue play because telematics-enabled uptime contracts and outcome-based fleet agreements shift value capture from equipment sales to recurring service streams. Acquisition targets should display multi-brand diagnostic software capabilities or certified aftertreatment retrofit integration capacity. Signal to monitor: California Air Resources Board waiver expansions or Euro 7 deliberations that compress diesel platform life and accelerate electrification capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Engineering Investment | Parallel EPA Tier 4 Final and EU Stage V validation tracks favor incumbents with regulatory affairs capacity over emerging competitors. |
| Telematics Platform Integration | Proprietary fleet management systems face displacement by independent software vendors in Chilean copper and Brazilian soybean logistics chains. |
| Battery-Electric Retrofit Program | California Air Resources Board incentive structures create white space for Tier 2-3 machine repower kits without full replacement. |
| Aftertreatment Service Network Expansion | Certified technician scarcity across North American dealer networks extends repair turnaround times and strands fleet utilization rates. |
| Smallholder Distribution Partnership | Mahindra-derived platform licensing opens South Asian and African plantation economies underserved by premium-brand networks. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with fleet maintenance directors, OEM procurement teams, aftermarket service heads, and mining operations managers; and secondary validation through EPA certification databases, EU type-approval records, SEC equipment manufacturer filings, and customs trade flow data. Bottom-up triangulation across equipment shipment records and top-down reconciliation against mineral extraction and agricultural mechanization forecasts anchored volume estimates. Primary fieldwork concentrated in Australian Pilbara mining corridors, Brazilian Cerrado grain operations, and North American Great Plains agricultural equipment populations.
Across the analysis window, the forecasting framework modeled demand trajectories by vehicle type, engine capacity tier, application vertical, and end-user procurement archetype. CAGRs were derived from segmented growth rate reconciliation against macroeconomic drivers including lithium extraction scaling, broadacre mechanization rates, and emissions compliance deadlines. Industry-specific inputs incorporated fleet replacement cycles in Australian iron ore operations, Brazilian labor scarcity trends, and California electrification incentive uptake rates.
Decision-makers should treat outputs as directional under assumptions of sustained lithium demand growth and stable EPA-EU regulatory convergence; material deviation in battery chemistry substitution or emissions waiver expansions would warrant model refresh. Forecasts embed assumptions regarding technician training pipeline expansion and steel price normalization that may not materialize. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Global Off-Highway Vehicle Telematics Market
Off Road Vehicles
Mining Vehicle Attachments Market
Off Road Vehicles
Automotive and Off-Road Vehicle Hoses Market
Off Road Vehicles
Global Electric Off-Highway Equipment Market
Off Road Vehicles
Off-Highway Electric Vehicle Market
Off Road Vehicles
Off-Road Vehicles Cooling Fan Market
Off Road Vehicles
Off Road All Terrain E-Scooter Market
Off Road Vehicles
Europe Off-Highway Vehicle HVAC Market
Off Road Vehicles
All-Terrain Vehicle (ATV) Engines Market
Off Road Vehicles
Amphibious ATV Market
Off Road Vehicles
Utility Terrain Vehicles (UTV) Market
Off Road Vehicles
All-Terrain Vehicle Market
Off Road Vehicles
Off Highway Vehicles Brake Systems Market
Off Road Vehicles
Snow Scooter Market
Off Road Vehicles
Off Highway Vehicle Lighting Market
Off Road Vehicles
Middle East and Africa Utility Terrain Vehicles Market