
 Engines Market | 2026-2036
Engines Market Size, Share, and Industry Trends Forecast 2026-2036
Engines Market Foresight
Aftermarket service revenue is rewriting profitability expectations across the powertrain value chain as original equipment margins compress under material cost volatility. Cummins Inc. leverages its dense North American service network to capture recurring maintenance spend on heavy-duty diesel platforms. Caterpillar Inc. anchors its position through captive parts distribution and field rebuild programs that extend machine economic life. Toyota Motor Corporation competes via hybrid system refurbishment capabilities that address warranty-period fleets and second-life vehicle pools.
An engine is a thermodynamic machine that converts chemical or electrical energy into mechanical work through controlled combustion or electromagnetic torque generation, with specifications typically rated by displacement, brake horsepower, torque curve, and thermal efficiency. Its primary commercial purpose is to supply motive power for transportation, industrial machinery, and energy generation systems across mobile and stationary applications. Diesel engines retain structural dominance in marine and heavy industrial equipment where load-pulling torque and fuel energy density outweigh first-cost penalties. Hybrid systems represent the fastest-expanding product type as automotive OEMs balance emission compliance against battery supply constraints and charging infrastructure gaps. Electric motors capture concentrated investment in aerospace auxiliary power and urban automotive segments where duty cycles favor instantaneous torque delivery and reduced thermal management complexity.
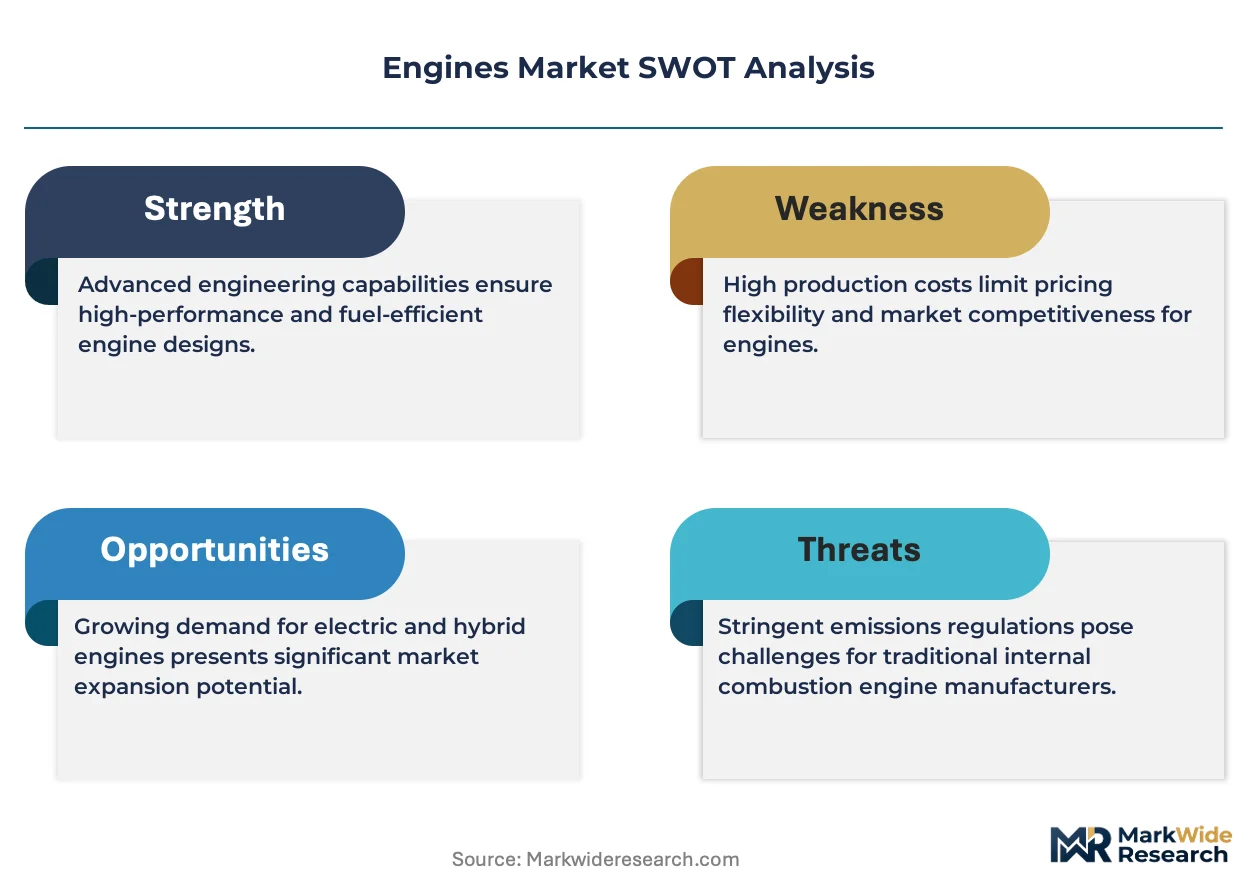
EPA tailpipe standards, Euro 7 emission frameworks, and China's MEE enforcement protocols collectively dictate combustion architecture viability and market access timelines across major production jurisdictions. These regulations compress product development cycles, elevate aftertreatment content per engine, and disqualify non-compliant platforms from fleet procurement tenders. Stakeholders must calibrate R&D allocation between incremental combustion efficiency gains and transformative electric or hydrogen propulsion bets before regulatory thresholds render legacy competencies obsolete.
Market Dynamics
Emission mandates from EPA Tier 4 and Euro 7 are compressing diesel engine lifecycles and forcing fleet operators toward hybrid architectures before total cost parity arrives.
Growth Catalysts
- Euro 7 emission frameworks:These standards eliminate grandfathering provisions for legacy diesel stock, compelling logistics operators across Germany and France to accelerate procurement of compliant powertrains.
- Long-haul trucking electrification pilots:California's Advanced Clean Trucks regulation creates fleet-scale demand validation for hybrid-diesel configurations operating along Interstate corridors.
- India's logistics infrastructure buildout:Dedicated freight corridors and inland container depots expand addressable fleet hours for medium-duty engines serving intermodal transfer points.
Market Restraints
- Aftertreatment material cost volatility:Platinum-group metal prices for diesel oxidation catalysts fluctuate with South African mining output, compressing supplier margins on Tier 4-compliant architectures.
- Battery cell supply concentration:Hybrid system production depends on cylindrical cell formats dominated by East Asian manufacturers, creating procurement bottlenecks for European powertrain assemblers.
- Hydrogen combustion technical limitations:Port fuel injection systems for H2 ICE applications suffer from pre-ignition knock at high loads, restricting viable duty cycles to steady-state industrial gensets.
Strategic Opportunities
- Brazil's biofuel mandate expansion:Proálcool regulatory extensions and RenovaBio credit mechanisms position ethanol-flex engines for fleet adoption ahead of battery infrastructure maturity.
- Maritime auxiliary power hybridization:Harbor craft and short-sea vessels face IMO Tier III enforcement in North Sea emission control areas, opening demand for battery-diesel parallel configurations.
- Powertrain-as-a-service distribution:Leasing structures with embedded maintenance contracts penetrate construction equipment markets where capital constraints delay outright engine purchases.
Industry Challenges
- Calibration engineer scarcity:Model-based development of transient emission maps requires expertise in GT-POWER and AVL simulation suites that outpaces university pipeline output.
- Dual-certification timeline compression:Simultaneous EPA and MEE homologation for China-bound engines demands parallel test cell booking that extends product launch windows.
- Legacy ECM integration complexity:Retrofit hybrid kits must handshake with proprietary J1939 CAN architectures from incumbent suppliers, creating software validation backlogs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engines Market |
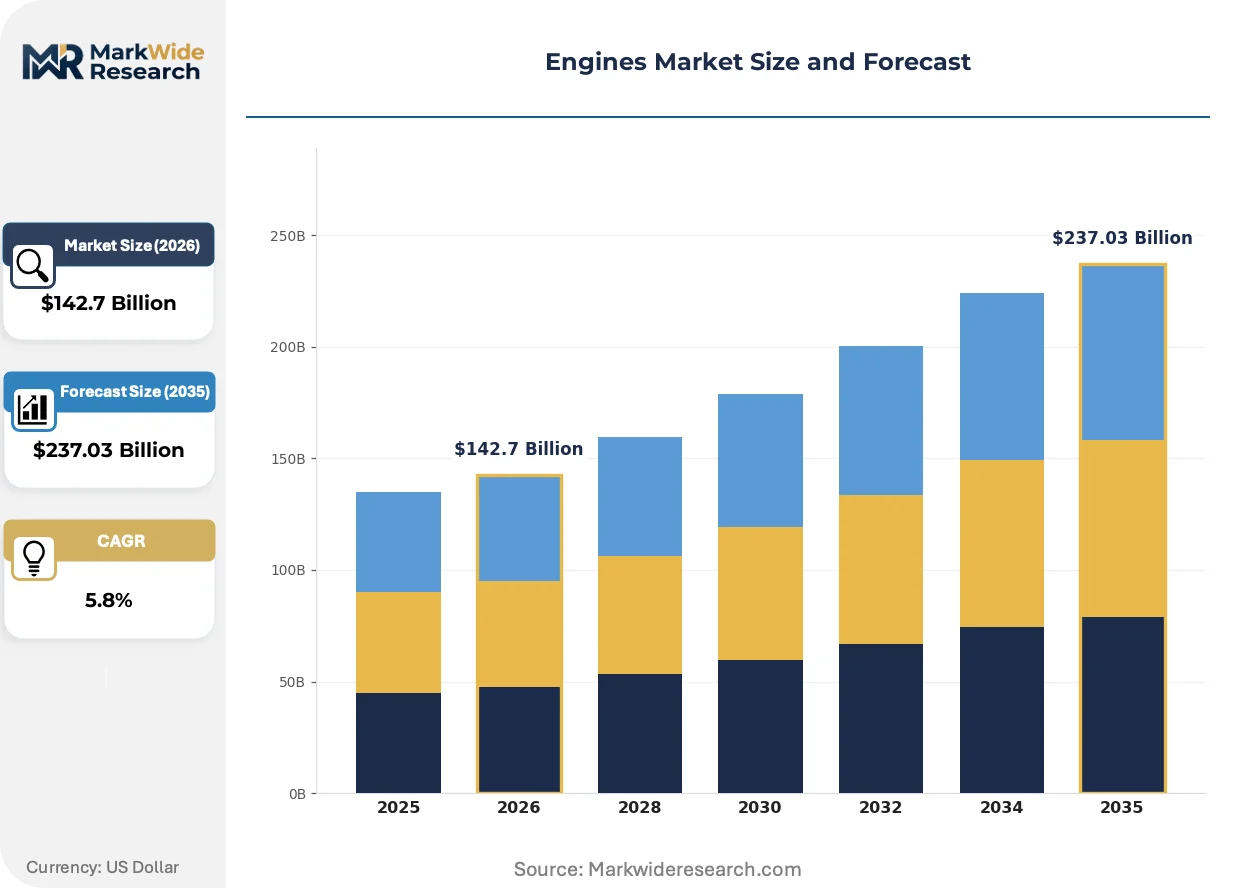
| Market Size in 2026 | $142.7 Billion |
| Market Size in 2035 | $237.03 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline Engines, Diesel Engines, Electric Motors, Hybrid Systems Application: Automotive, Marine, Aerospace, Industrial Equipment End User: OEMs, Aftermarket, Fleet Operators, Maintenance Providers Fuel Type: Petrol, Diesel, Biofuels, Electricity |
| Companies Covered | Cummins Inc., Caterpillar Inc., General Electric Company, Toyota Motor Corporation, Volkswagen AG, Ford Motor Company, General Motors, Rolls-Royce plc, AB Volvo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engines Market Shifts & Advancements
Powertrain architecture is bifurcating between combustion refinement for residual demand pockets and electrification for duty cycles where battery economics now clear threshold viability.
Advanced thermal management is hybridizing conventional diesel blocks with 48V electric superchargers and exhaust waste heat recovery circuits. Marine operators on Baltic Sea routes adopt these configurations to maintain propulsion redundancy while satisfying ECA fuel consumption indexing. The technology is hybridizing supplier R&D allocation between incremental efficiency gains and full platform replacement bets.
China's MEE enforcement protocols now mandate real-world emission monitoring via onboard refueling vapor recovery verification. Engine assemblers serving the domestic truck market must integrate PEMS hardware into series production, elevating per-unit electronics content. Heavy-duty OEMs are responding by consolidating supplier tiers to reduce interface validation burden.
Fleet procurement committees now unbundle powertrain acquisition from lifecycle service contracts, awarding maintenance spend to independent service networks with proprietary diagnostic tool access. This pattern concentrates in North American long-haul operations where telematics data ownership disputes complicate OEM-captive service retention. Third-party rebuild specialists capture margin pools previously held by factory-authorized channels.
Engines Market Segmentation
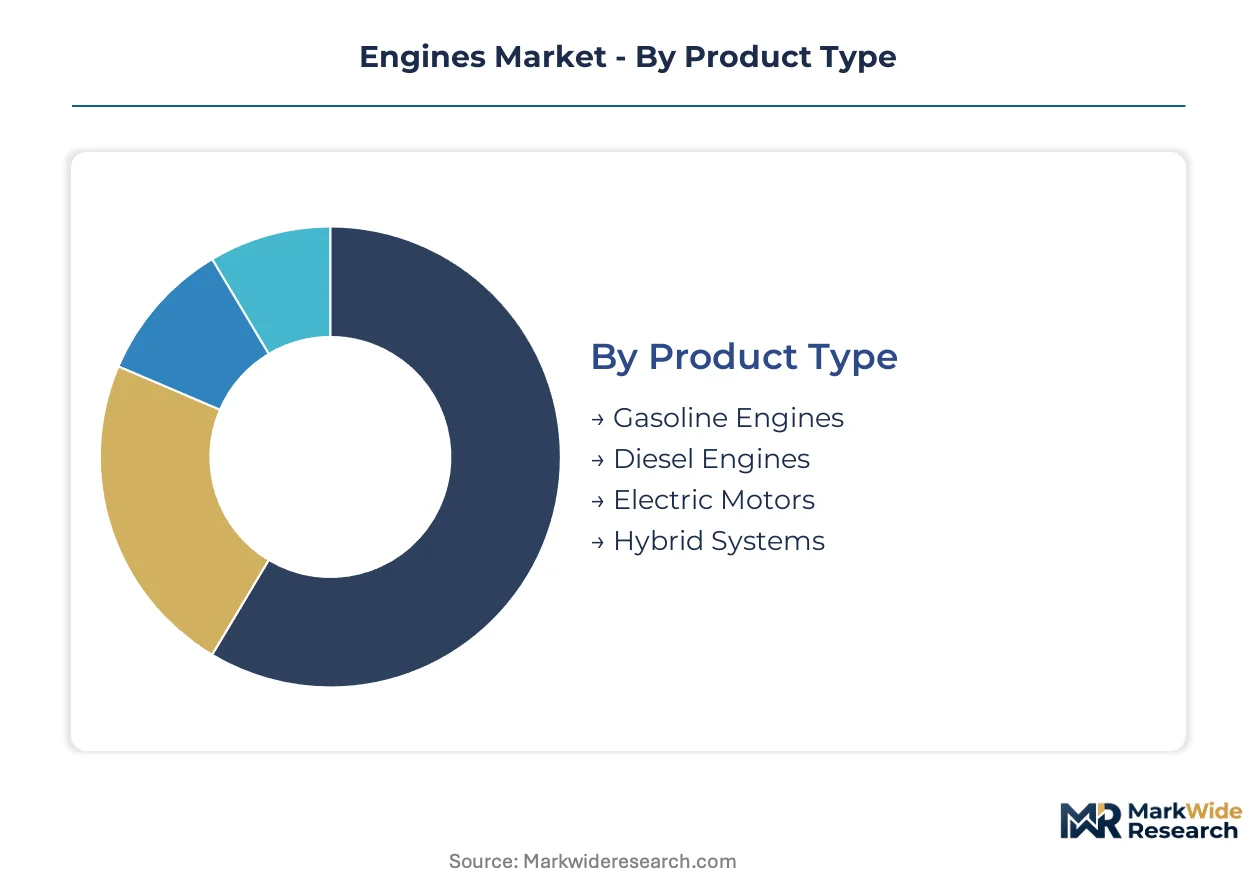
Powertrain segmentation in the engines market reflects divergent technology maturities and regulatory compliance horizons across mobile and stationary applications. Fleet procurement committees now weight total cost of ownership calculations against emission certification tiers when allocating capital across these categories.
Product Type:
Diesel engines anchor mature infrastructure networks while hybrid systems capture the steepest investment acceleration as OEMs navigate battery supply constraints.
- Gasoline Engines:Spark-ignition architectures with port or direct fuel injection dominate light-duty automotive applications where power-to-weight ratios favor rapid throttle response. Demand concentrates in Brazil and India's passenger vehicle segments where flex-fuel compatibility addresses biofuel mandate compliance.
- Diesel Engines:Compression-ignition platforms deliver high brake mean effective pressure for sustained load cycles in commercial trucking and marine propulsion. Euro 7 and EPA Tier 4 mandates compress viable product lifecycles, redirecting procurement toward compliant architectures with integrated selective catalytic reduction.
- Electric Motors:Permanent magnet synchronous and induction configurations supply instantaneous torque for urban duty cycles with regenerative braking recovery.
- Hybrid Systems:Parallel and series architectures combine thermal and electric prime movers to optimize efficiency across variable load profiles.
Diesel engines handle the majority of throughput in heavy-duty segments; hybrid systems are gaining share fastest as logistics operators pilot electrified long-haul corridors.
Application:
Volume distribution across applications tracks divergent duty cycle requirements and infrastructure maturity for each propulsion technology.
- Automotive:Passenger cars, light trucks, and commercial vehicles constitute the largest addressable equipment population, with powertrain specifications calibrated to urban congestion patterns and highway cruise efficiency targets. China's domestic OEMs and Germany's premium manufacturers drive specification-setting for global platforms.
- Marine:Propulsion and auxiliary power systems for harbor craft, coastal vessels, and deep-sea shipping face IMO Tier III enforcement in emission control areas. Baltic Sea and North Sea routes concentrate demand for dual-fuel and battery-hybrid configurations.
- Aerospace:Turbofan, turboprop, and auxiliary power units operate under FAA and EASA certification timelines with extended product development horizons.
- Industrial Equipment:Stationary gensets, construction machinery, and agricultural tractors require torque-rich architectures for intermittent high-load operation.
Automotive applications absorb the greatest unit volume; marine hybridization is expanding most quickly as port authorities enforce shore power and low-emission zone requirements.
End User:
Procurement authority fragmentation across the value chain creates divergent purchasing criteria and service contract structures.
- OEMs:Original equipment manufacturers integrate engines into complete vehicle or machine platforms, specifying performance envelopes and emission certification tiers for supplier qualification. Powertrain-as-a-service leasing structures penetrate construction equipment markets where capital constraints delay outright purchases.
- Aftermarket:Independent distributors and rebuild specialists capture margin pools in North American long-haul operations where telematics data ownership disputes complicate factory-authorized service retention.
- Fleet Operators:Logistics companies and rental fleets optimize total cost of ownership across duty cycle-matched powertrain selections.
- Maintenance Providers:Authorized and independent service networks compete for recurring maintenance spend on warranty-period and post-warranty equipment pools.
OEMs command the dominant share of new equipment procurement; aftermarket channels are climbing the fastest as fleet operators unbundle acquisition from lifecycle service contracts.
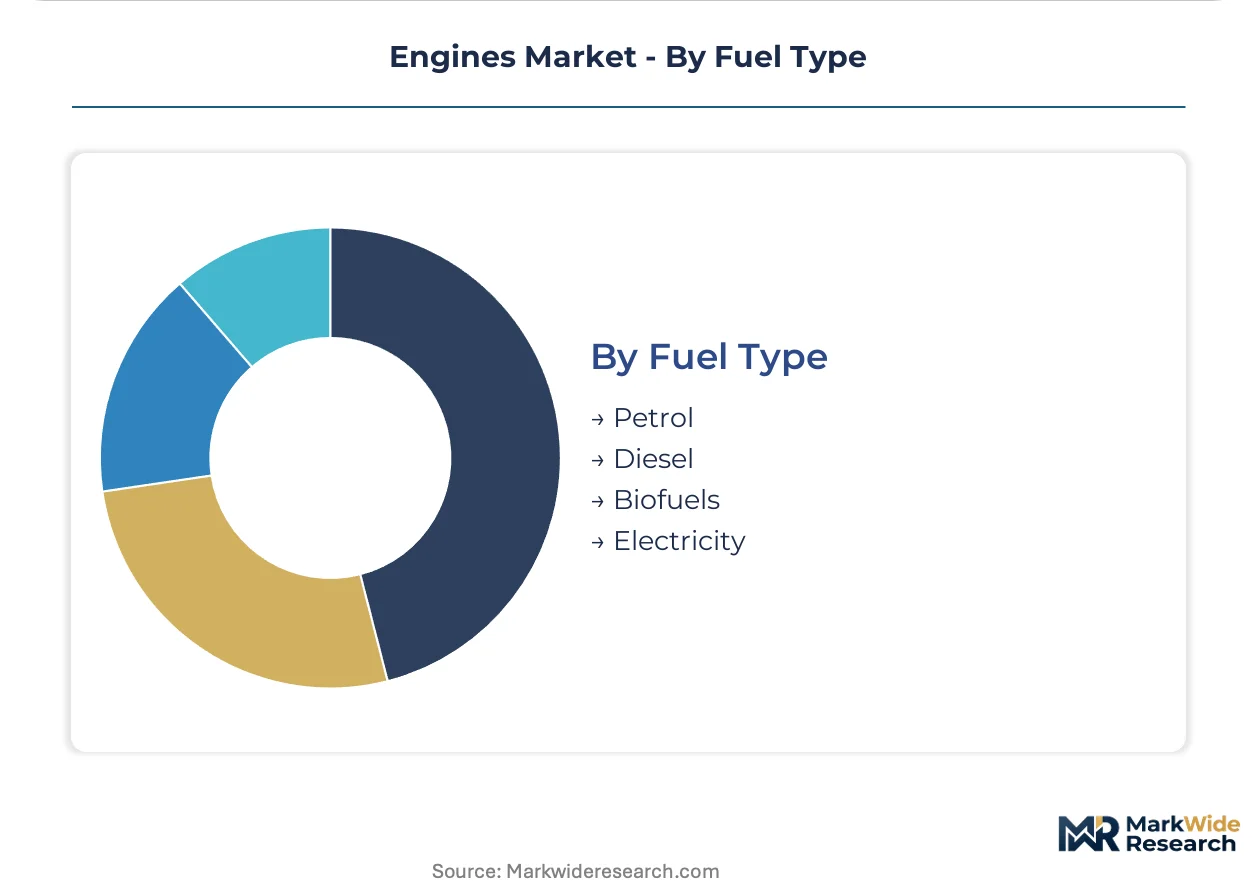
Fuel Type:
Energy carrier selection dictates combustion architecture, aftertreatment complexity, and infrastructure dependency for each deployment context.
- Petrol:Gasoline formulations with varying octane ratings and ethanol blending limits serve spark-ignition engines in markets with mature refinery infrastructure. Brazil's Proálcool regulatory extensions position ethanol-flex engines for fleet adoption ahead of battery infrastructure maturity.
- Diesel:Distillate fuel with standardized cetane and sulfur specifications enables compression-ignition operation across commercial transportation and industrial machinery. Platinum-group metal price volatility for oxidation catalysts compresses supplier margins on compliant architectures.
- Biofuels:Ethanol, biodiesel, and renewable diesel variants offer lifecycle emission reductions where feedstock supply chains achieve certification under RenovaBio or comparable credit mechanisms.
- Electricity:Grid-sourced and onboard-generated electrical energy powers motor-driven propulsion with efficiency advantages in stop-start duty cycles.
Diesel retains the largest share of energy consumption in heavy-duty segments; electricity is expanding most quickly in urban automotive and harbor craft applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Powertrain consumption patterns diverge sharply across major economies, with logistics fleet operators in Germany prioritizing Euro 7 compliance timelines while Brazilian agricultural buyers favor ethanol-flex architectures over electrification pathways.
United States
Long-haul trucking electrification pilots along California's Interstate corridors validate hybrid-diesel configurations under the state's Advanced Clean Trucks regulation. EPA Tier 4 enforcement compresses viable lifecycles for legacy diesel stock in the Midwest manufacturing belt. Detroit-Warren automotive cluster anchors powertrain R&D allocation toward compliant heavy-duty platforms.
China
Domestic OEMs drive specification-setting for global platforms as motorization deepens in inland provinces. MEE enforcement protocols mandate onboard emission monitoring hardware integration into series production truck engines. Yangtze River Delta manufacturing corridor concentrates hybrid system assembly capacity to serve domestic logistics infrastructure buildout.
Germany
Premium manufacturers calibrate performance envelopes for global export markets while navigating Euro 7 elimination of grandfathering provisions. KBA homologation timelines compress product development cycles for compression-ignition architectures. Stuttgart industrial cluster hosts supplier consolidation efforts to reduce interface validation burden for compliant powertrains.
India
Dedicated freight corridors and inland container depots expand addressable fleet hours for medium-duty engines serving intermodal transfer points. BIS emission standards align with MEE protocols for real-world monitoring capabilities. Maharashtra automotive corridor concentrates procurement authority for logistics operators modernizing aging powertrain inventories.
Brazil
Proálcool regulatory extensions and RenovaBio credit mechanisms position ethanol-flex engines for fleet adoption ahead of battery infrastructure maturity. ANVISA-aligned fuel quality standards support high-blend ethanol combustion architectures. São Paulo industrial belt anchors flex-fuel engine production for domestic agricultural and commercial vehicle demand.
Engines Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another, creating a bifurcated structure where specialized aftertreatment engineering competes against vertically integrated manufacturing footprints. The vendor base organizes around three strategic archetypes: captive powertrain divisions serving single OEM portfolios, independent suppliers selling across multiple vehicle manufacturers, and aftermarket service networks capturing recurring maintenance spend. Dominant competitive moves include portfolio diversification into hybrid system architectures and geographic expansion through localized assembly joint ventures.
Within the independent supplier tier, Cummins Inc. and Caterpillar Inc. exemplify North American engineering-centric positioning, while Toyota Motor Corporation anchors Japanese hybrid system refurbishment capabilities. These entities occupy positions defined by dense service network coverage and field rebuild program infrastructure rather than pure manufacturing scale.
| Leading Market Players |
|---|
| Cummins Inc. |
| Caterpillar Inc. |
| General Electric Company |
| Toyota Motor Corporation |
| Volkswagen AG |
| Ford Motor Company |
| General Motors |
| Rolls-Royce plc |
| AB Volvo |
| Others |
Supply & Pricing Matrix
California's Interstate 5 freight corridor concentrates cost dynamics that ripple through engine pricing structures, with long-haul fleet operators facing differentiated procurement economics based on supplier geographic concentration and EPA Tier 4 compliance tiers.
Pricing Analysis
Long-term offtake contracts dominate procurement for heavy-duty diesel platforms, while spot purchasing persists for aftermarket components and hybrid system batteries. Price differentiation rests on emission certification grade and volume scale, with Euro 7-compliant architectures commanding premiums over legacy stock. Cost compression in platinum-group metal aftertreatment content is intensifying because South African mining output volatility feeds into supplier margins. Fleet operators with consolidated purchasing authority exhibit lowest price sensitivity; independent owner-operators face acute cost pressure.
Supply Chain Analysis
Export-control regimes on permanent-magnet rare earth processing limit flows from Chinese refineries to European and North American motor assemblers. Manufacturing concentration centers on China, Germany, and Japan for precision engine components and hybrid system assembly. Raw material dependencies include platinum-group metals for catalytic aftertreatment, rare earth elements for electric motor magnets, and high-grade steel alloys for engine blocks. Single-source vulnerability in cylindrical battery cell formats creates procurement bottlenecks. Distribution runs through captive OEM service networks and independent aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as battery-electric powertrains displace combustion architectures in urban duty cycles and California's Advanced Clean Trucks regulation accelerates fleet pilot programs.
For Market Incumbents: Insulate core diesel service revenue through captive parts distribution and field rebuild programs that extend machine economic life. Secure backward integration into aftertreatment catalyst supply chains to offset platinum-group metal price volatility. Expand hybrid system refurbishment capabilities to capture warranty-period fleet spend.
For New Entrants and Emerging Players: Establish a beachhead in Brazil's ethanol-flex engine segment where Proálcool regulatory extensions outpace battery infrastructure maturity. Target maritime auxiliary power hybridization for harbor craft facing IMO Tier III enforcement in North Sea emission control areas. Pursue powertrain-as-a-service leasing structures with embedded maintenance contracts.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized engine divisions lacking hybrid transition roadmaps. Long-term viability hinges on R&D allocation discipline between incremental combustion efficiency and transformative electrification bets. Watch for inflection signals in battery cell cost curves crossing threshold parity for long-haul trucking duty cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid System Platform Standardization | Reduces validation burden across EPA and MEE dual-certification timelines for China-bound engines. |
| Aftertreatment Backward Integration | Captive catalyst production insulates margins from South African platinum-group metal supply volatility. |
| Powertrain-as-a-Service Launch | Embedded maintenance contracts penetrate construction equipment markets with capital-constrained buyers. |
| Maritime Hybrid Joint Venture | Battery-diesel parallel configurations address IMO Tier III enforcement in Baltic Sea emission control areas. |
| Ethanol-Flex Capacity Expansion | RenovaBio credit mechanisms position Brazilian production for fleet adoption ahead of battery infrastructure. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with powertrain procurement directors, fleet maintenance managers, and aftermarket service network heads; and secondary validation through EPA certification filings, Euro 7 regulatory texts, customs trade data for engine component flows, and OEM production disclosures. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and regional demand clusters.
Forecast inputs incorporated propulsion technology substitution curves, regulatory compliance timeline enforcement, and fleet modernization cycle patterns across the projection horizon. Segmentation dimensions modeled include fuel type, end-user procurement authority, and duty cycle requirements. CAGRs derived from logistic growth curve fitting adjusted for infrastructure buildout rates in China, India, and Brazil. Industry-specific inputs encompassed battery cell supply constraints and platinum-group metal price trajectory assumptions.
Stress conditions across emission mandate acceleration, rare earth export restriction severity, and freight demand cyclicality were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and battery cost curve progression. Material shifts in hydrogen combustion technical breakthroughs or breakthrough battery chemistry commercialization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Hydraulic Lash Adjuster Market
Powertrain
Automotive Engine Market
Powertrain
Automotive Engine Piston Rings Market
Powertrain
Automotive Clutch Slave Cylinder Market
Powertrain
Automotive Tuner Market
Powertrain
Reciprocating Engine Market
Powertrain
Engine Tuner Market
Powertrain
Automotive Retrofit Electric Vehicle Powertrain Market
Powertrain
Electric Powertrain Systems Market
Powertrain
High Speed Engine Market
Powertrain
Global Automotive Torque Converter Market
Powertrain
Advanced Gear Shifter System Market
Powertrain
Brazil Automotive Actuators Market
Powertrain
Automotive Fuel Injection Pump Market
Powertrain
Global Industrial Turbocharger Market
Powertrain
Automotive Fuel Cock Market