
 Automotive Exhaust Aftertreatment Systems Market | 2026-2036
Automotive Exhaust Aftertreatment Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Exhaust Aftertreatment Systems Market Analysis
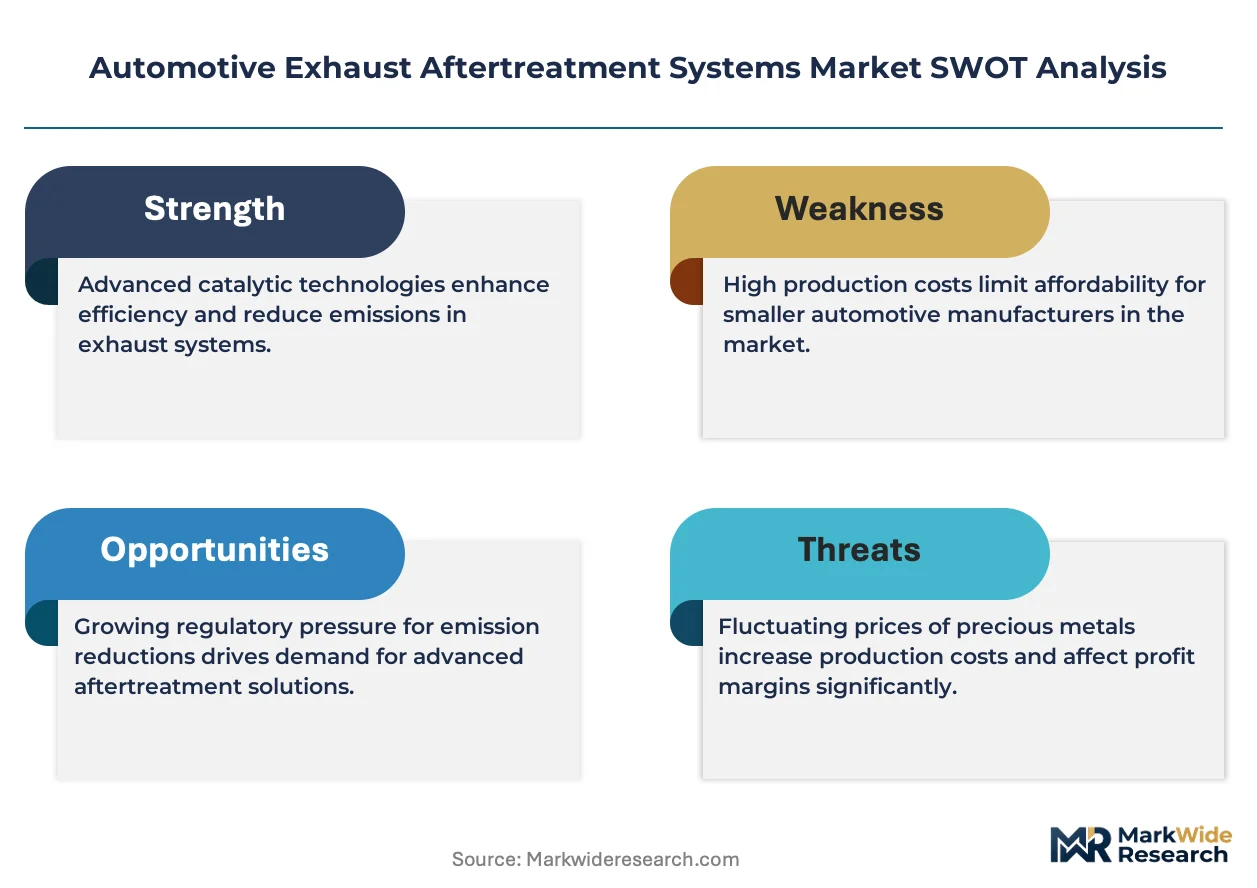
Electrification-resistant powertrain architectures is tilting investment toward hybrid-compatible aftertreatment platforms. Johnson Matthey anchors its position through advanced catalyst formulations for low-temperature SCR operation. Faurecia competes via integrated exhaust line modules that package DPF, SCR, and dosing hardware into single assemblies. Tenneco dominates the heavy-duty retrofit channel with modular replacement systems designed for aging diesel fleets.
Automotive exhaust aftertreatment systems combine catalytic substrates, particulate filters, reductant injection hardware, and electronic controls to transform engine-out pollutants into benign compounds before tailpipe release. Ceramic cordierite or silicon carbide wall-flow substrates in diesel particulate filters typically achieve filtration efficiencies above 95 percent for particulate matter while imposing controlled backpressure on engine breathing. Selective catalytic reduction catalysts command the largest value pool due to urea infrastructure lock-in and complex dosing precision requirements. Diesel particulate filter technology sustains volume leadership in markets where particulate limits lag NOx stringency. Factory installed configurations concentrate margin capture with OEMs, whereas retrofitted installations expand fastest among fleet operators seeking compliance deadline extensions.
The United States EPA enforces Tier 4 Final and upcoming Tier 5 standards that mandate combined NOx and particulate reductions, forcing manufacturers to validate systems across broader temperature and load maps. Euro VII proposals from the European Commission target cold-start emissions with real-driving monitoring, compelling Eberspächer and Continental to redesign thermal management strategies. China's MEE implements Stage VI-b standards with remote emissions monitoring, reshaping product architecture for connected diagnostics. Stakeholders must weigh catalyst precious metal loading against electrification timelines to avoid stranded technology investments.
Market Dynamics
Electrification timelines are compressing investment horizons for diesel aftertreatment platforms, forcing suppliers to engineer hybrid-compatible architectures that bridge combustion and zero-emission powertrains without stranding catalyst development.
Growth Catalysts
- EPA Tier 4 Final mandates:Combined NOx and particulate reduction requirements in the United States force fleet operators to retrofit aging heavy-duty vehicles with integrated SCR-DPF systems.
- Ceramic substrate advances:Silicon carbide wall-flow filters achieve filtration efficiencies above 95 percent for particulate matter while sustaining thermal durability under extreme duty cycles.
- Commercial fleet concentration:Heavy-duty trucking corridors across Germany and the American Midwest generate concentrated demand for factory-installed selective catalytic reduction configurations.
Market Restraints
- Platinum group metal volatility:Palladium and rhodium price swings in South African mining output destabilize catalyst coating cost structures.
- Urea infrastructure lock-in:Diesel exhaust fluid distribution gaps in rural North American corridors limit SCR adoption outside major freight corridors.
- Electrification substitution:Battery-electric and hydrogen fuel cell powertrains eliminate exhaust streams entirely, eroding addressable market for thermal aftertreatment.
Strategic Opportunities
- India Stage VI-b preparation:The country's central automotive regulator is tightening particulate and NOx limits, opening retrofit demand among aging commercial fleets in Maharashtra and Gujarat.
- Connected diagnostics integration:Remote emissions monitoring mandates in China's MEE framework require telematics-enabled aftertreatment controllers with real-time fault detection.
- Marine and off-highway extension:Non-road mobile machinery in European construction and agriculture sectors faces tightening Stage V standards, extending catalyst demand beyond on-road applications.
Industry Challenges
- Thermal management engineering:Cold-start emission compliance under Euro VII proposals demands sophisticated exhaust heat retention strategies that extend development timelines.
- Cross-supply chain coordination:Precise dosing hardware, ceramic substrates, and electronic controllers must synchronize across three distinct manufacturing tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Exhaust Aftertreatment Systems Market |
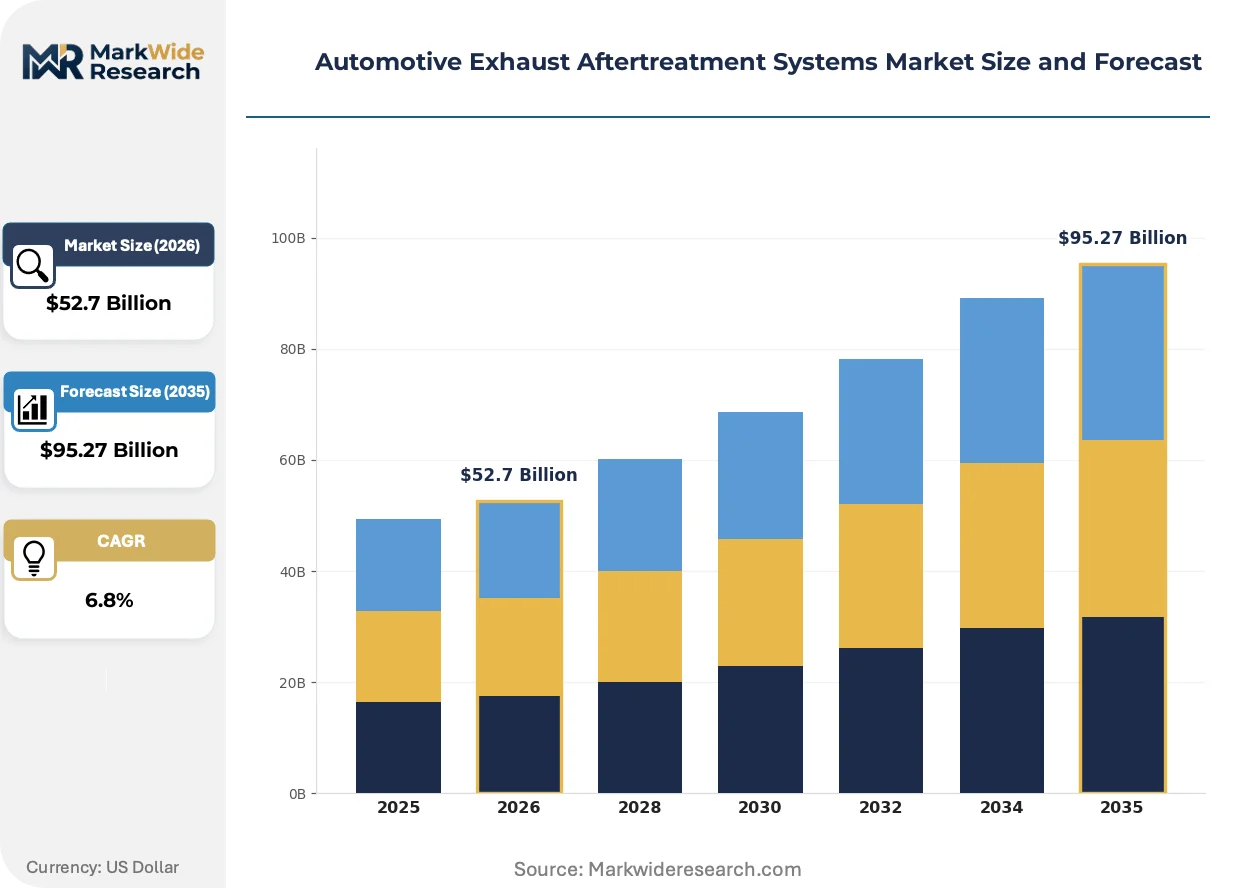
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel Particulate Filter, Selective Catalytic Reduction, Lean NOx Trap, Exhaust Gas Recirculation Technology: Catalytic Converter, SCR Catalyst, DPF Technology, EGR System End User: OEMs, Aftermarket Suppliers, Fleet Operators, Vehicle Manufacturers Installation: Factory Installed, Retrofitted, Modular, Integrated |
| Companies Covered | Continental, Faurecia, Johnson Matthey, Robert Bosch, Tenneco, Eberspächer, Cummins, Donaldson Company, BorgWarner, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Exhaust Aftertreatment Systems Market Emerging Trajectories
Digital twin architectures are virtualizing catalyst performance validation, compressing development cycles while regulatory pressure intensifies across multiple geographies simultaneously.
Model-based catalyst calibration is virtualizing the traditional engine-dyno validation workflow, allowing suppliers to simulate NOx conversion efficiency across temperature and space velocity maps before physical prototyping. Tier 1 system integrators in Stuttgart and Detroit are adopting these tools to halve validation timelines. This virtualization is compressing the competitive window for new market entrants who lack comparable simulation infrastructure.
Euro VII proposals from the European Commission mandate real-driving emissions monitoring with portable measurement systems, compelling thermal management redesigns that maintain catalyst light-off during urban cold-start cycles. The regulation forces integrated exhaust line packaging that co-locates SCR and DPF elements within minimal volume envelopes. Heavy-duty OEMs in Germany and Scandinavia are responding with electrically heated catalyst substrates that draw hybrid battery power.
Fleet procurement departments are consolidating vendor relationships around full-system suppliers capable of warrantying combined SCR-DPF-dosing performance as single contractual entities. This consolidation displaces component-level sourcing that previously separated substrate, catalyst, and hardware procurement. The shift is most visible among North American Class 8 trucking fleets seeking simplified compliance accountability.
Automotive Exhaust Aftertreatment Systems Market Segmentation
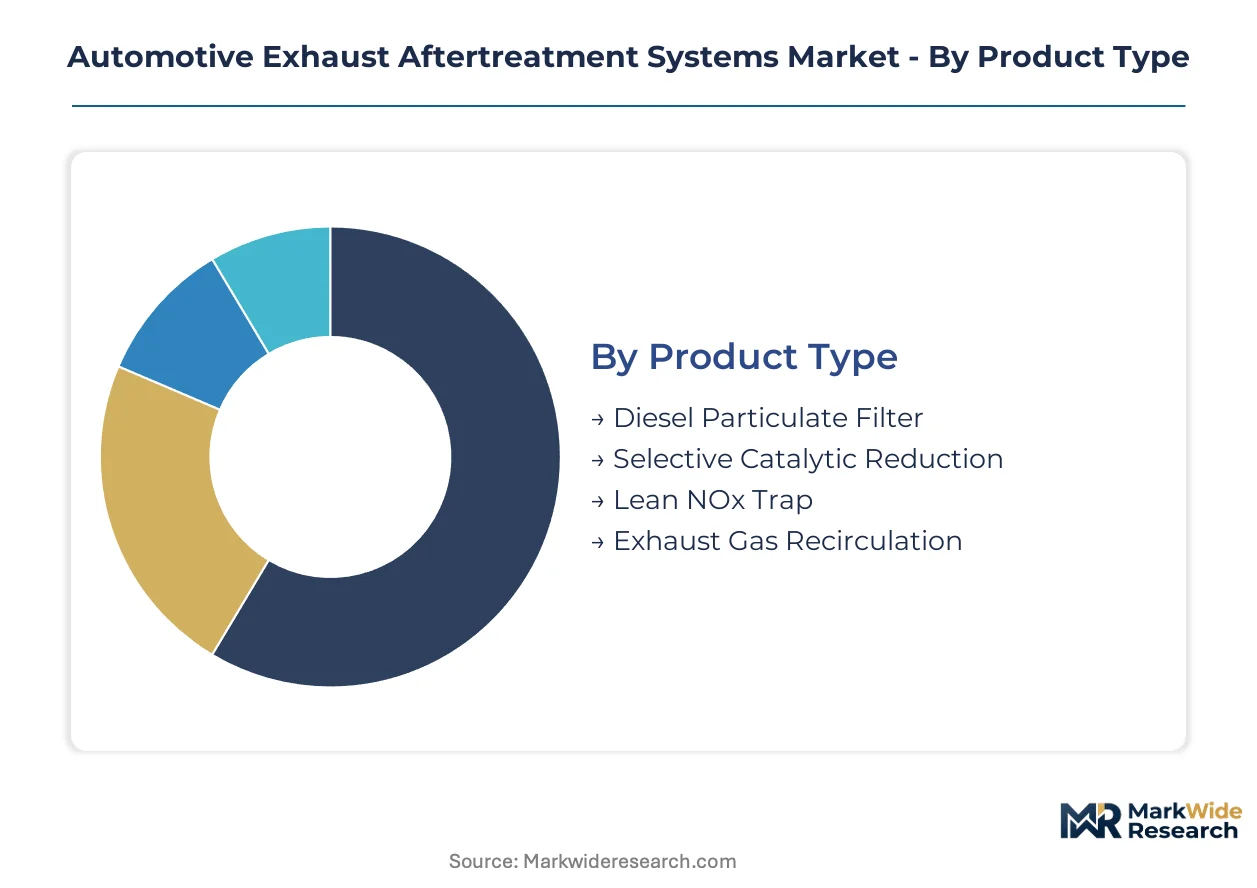
Product architecture in automotive exhaust aftertreatment systems fragments across hardware generations, installation timing, and customer procurement patterns. Suppliers must align catalyst formulations and thermal management strategies with distinct margin structures and compliance timelines embedded in each segment category.
Product Type:
Cost tier differentiation separates commodity particulate filtration from precision dosing systems with embedded urea infrastructure dependencies.
- Diesel Particulate Filter:Ceramic cordierite or silicon carbide wall-flow substrates achieve filtration efficiencies above 95 percent for particulate matter. Demand concentrates in markets where particulate limits lag NOx stringency, particularly among heavy-duty retrofit operators in the American Midwest seeking Tier 4 Final compliance extensions.
- Selective Catalytic Reduction:Urea-based reductant injection systems command the largest value pool due to complex dosing precision requirements and DEF infrastructure lock-in. Fleet procurement in Germany and the United States drives factory-installed configurations with integrated thermal management.
- Lean NOx Trap:Periodic rich regeneration cycles trap nitrogen oxides on precious metal coatings during lean operation.
- Exhaust Gas Recirculation:Cooled EGR architectures reduce combustion temperatures to suppress NOx formation at the source.
Selective catalytic reduction commands the established base. The steepest expansion runs through diesel particulate filters in retrofit-heavy corridors.
Technology:
Application focus distinguishes substrate-based passive systems from active dosing architectures requiring electronic control integration.
- Catalytic Converter:Three-way catalyst formulations oxidize carbon monoxide and hydrocarbons while reducing nitrogen oxides in stoichiometric gasoline applications. Passenger vehicle OEMs in Stuttgart and Detroit specify precious metal loadings calibrated to specific engine displacement tiers.
- SCR Catalyst:Vanadium-based or zeolite formulations enable NOx reduction across broad temperature windows with ammonia from urea decomposition. Euro VII cold-start mandates in Brussels are forcing electrically heated substrate redesigns drawing hybrid battery power.
- DPF Technology:Wall-flow filtration with active or passive regeneration manages soot accumulation.
- EGR System:High-pressure and low-pressure loop configurations modulate dilution rates.
SCR catalyst technology anchors the revenue base. The fastest technology climb belongs to DPF architectures extending into marine and off-highway Stage V compliance.
End User:
Customer type determines warranty accountability structures and procurement consolidation patterns across the value chain.
- OEMs:Factory-integrated systems capture margin concentration through multi-year platform supply agreements with thermal validation responsibility. German and American heavy-duty truck manufacturers specify combined SCR-DPF-dosing performance as single contractual entities.
- Aftermarket Suppliers:Modular replacement channels serve aging fleet populations with simplified compliance accountability.
- Fleet Operators:Direct procurement of retrofit systems accelerates among Class 8 trucking corridors seeking deadline extensions.
- Vehicle Manufacturers:Passenger car integration emphasizes packaging density and cold-start emission minimization.
OEM relationships dominate the established volume base. Aftermarket suppliers are gaining share fastest as electrification timelines compress replacement cycles.
Installation:
Volume and margin profiles diverge sharply between original equipment integration and post-vehicle deployment channels.
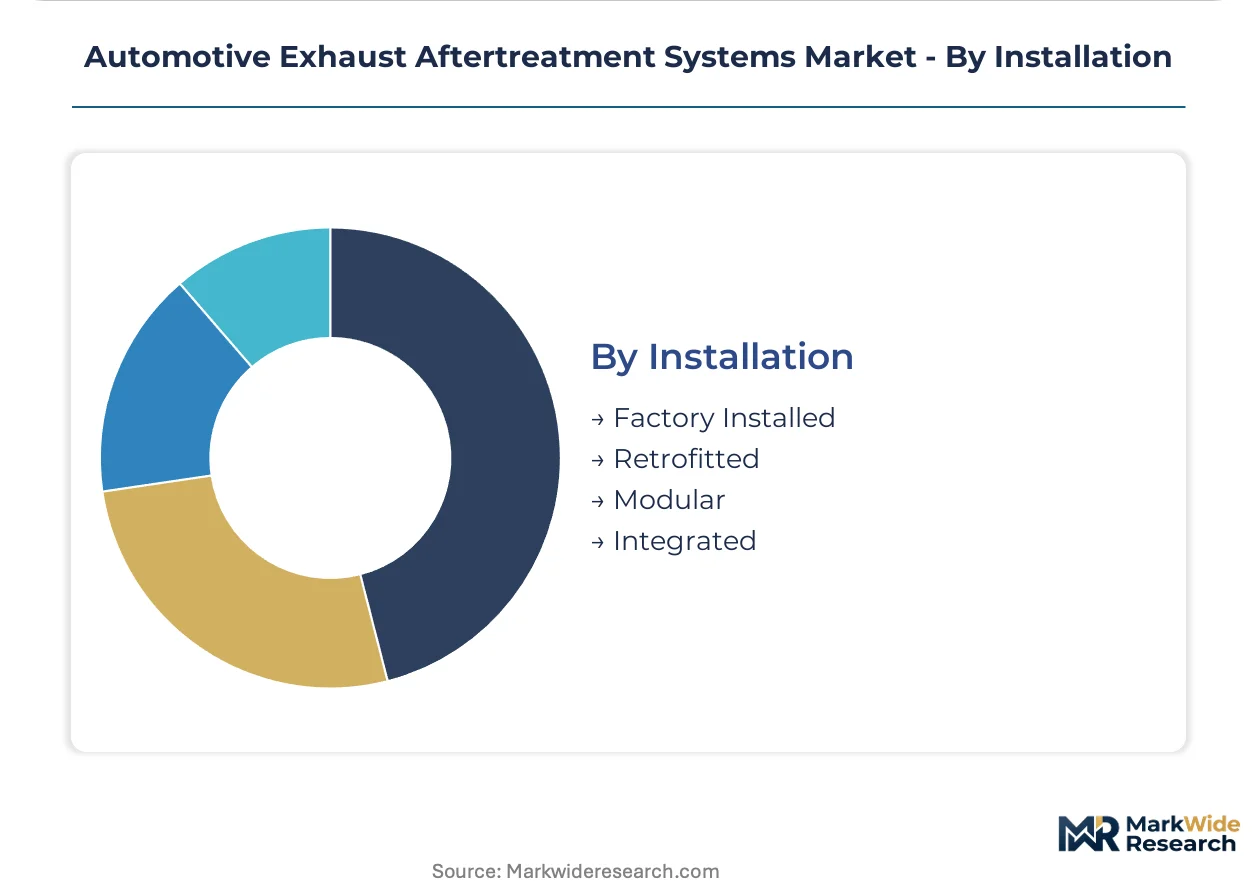
- Factory Installed:Engineered-in thermal management and packaging optimization during vehicle development cycles. OEMs in Germany and the United States validate systems across broader temperature and load maps for EPA Tier 4 and Euro VII compliance.
- Retrofitted:Post-production installation expands fastest among fleet operators with compliance deadline pressures.
- Modular:Standardized subassemblies enable rapid field replacement without full system redesign.
- Integrated:Co-located SCR and DPF elements within minimal volume envelopes respond to Euro VII urban cold-start mandates.
Factory installed configurations hold the established margin base. Retrofitted installations represent the steepest expansion trajectory as regulatory deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German suppliers export integrated exhaust line modules to American Midwest fleet operators, while Japanese catalyst manufacturers serve Southeast Asian retrofit markets through Bangkok and Jakarta distribution hubs.
United States
Class 8 trucking corridors across Illinois, Ohio, and Indiana generate concentrated demand for factory-installed SCR configurations. EPA Tier 4 Final and anticipated Tier 5 standards mandate combined NOx and particulate reductions validated across broader temperature maps. Detroit-based system integrators anchor heavy-duty OEM supply relationships with multi-year platform agreements.
Germany
Commercial vehicle manufacturers in Stuttgart and Munich drive precision dosing system procurement for Euro VII cold-start compliance. KBA type-approval processes enforce real-driving emissions monitoring with portable measurement systems. Eberspächer and Continental anchor thermal management redesigns drawing hybrid battery power for electrically heated catalyst substrates.
China
Stage VI-b implementation by MEE reshapes product architecture for connected diagnostics with remote emissions monitoring mandates. Yangtze River Delta manufacturing clusters in Shanghai and Jiangsu province concentrate ceramic substrate and catalyst coating capacity. Domestic suppliers compete with European joint ventures for heavy-duty truck OEM contracts.
India
Stage VI-b preparation opens retrofit demand among aging commercial fleets in Maharashtra and Gujarat. Central automotive regulator tightening of particulate and NOx limits accelerates fleet operator compliance investments. Pune and Ahmedabad industrial corridors concentrate aftermarket installation capacity for modular replacement systems.
Japan
METI carbon neutrality roadmaps compress diesel powertrain investment horizons while sustaining hybrid-compatible aftertreatment demand. Nagoya and Tokyo automotive clusters engineer low-temperature SCR operation for light-duty commercial applications. Domestic suppliers prioritize ceramic substrate advances for filtration efficiency above 95 percent under extreme duty cycles.
Automotive Exhaust Aftertreatment Systems Market Vendor Landscape
On the supply side, the industry is tiered between integrated system architects and component specialists. Catalyst formulators, substrate manufacturers, and dosing hardware engineers occupy distinct margin positions with varying electrification exposure. Three archetypes dominate: full-system integrators warrantying combined performance, catalyst specialists commanding precious metal formulation expertise, and modular retrofit suppliers serving deadline-pressured fleets. Consolidation pressures favor acquisition of dosing precision capabilities, while technology licensing agreements accelerate hybrid-compatible platform development.
Within the full-system integrator tier, Faurecia and Tenneco exemplify divergent strategic positioning. Faurecia occupies a position emphasizing integrated exhaust line modules that package multiple functions into single assemblies. Tenneco anchors the heavy-duty retrofit channel with modular replacement architectures. Johnson Matthey represents the catalyst formulation specialist archetype, with precious metal expertise concentrated in low-temperature SCR operation.
| Leading Market Players |
|---|
| Continental |
| Faurecia |
| Johnson Matthey |
| Robert Bosch |
| Tenneco |
| Eberspächer |
| Cummins |
| Donaldson Company |
| BorgWarner |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European ceramic substrate fabrication is compressing supplier margins while amplifying pricing power for silicon carbide wall-flow producers serving EPA Tier 4 Final compliance deadlines. This utilization imbalance forces fleet operators to accept longer contract terms and premium pricing for guaranteed delivery slots.
Pricing Analysis
Next-generation electrically heated catalyst substrates command substantial premiums over conventional vanadium-based SCR formulations, while prior-generation cordierite DPFs trade at commodity levels in oversupplied channels. Three-tier pricing structure across premium, standard, and economy levels reflects thermal performance grade and certification complexity under Euro VII proposals. Cost compression in economy-tier retrofit hardware is intensifying because Chinese substrate imports are flooding aftermarket channels. Fleet operators in rural North American corridors exhibit highest price sensitivity due to urea infrastructure gaps, while German OEMs tolerate premium pricing for integrated thermal management.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for ceramic substrate sourcing. Manufacturing gravity centers on Germany, China, and Japan for catalyst coating and substrate fabrication. The industry draws from South African platinum group metals, rare earth zeolite formulations, and silicon carbide precursors as critical inputs. Single-source vulnerability concentrates in palladium and rhodium supply channels. Distribution runs through Tier 1 system integrators in Stuttgart and Detroit, with modular retrofit channels expanding through Midwest fleet service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive exhaust aftertreatment systems market represents early-cycle expansion driven by regulatory ratcheting across multiple geographies simultaneously. Euro VII and EPA Tier 5 mandates are extending addressable demand beyond replacement cycles into hybrid-compatible platform development.
For Market Incumbents: Pre-empt margin erosion by acquiring dosing precision capabilities before electrification timelines compress catalyst development windows. Secure backward integration into ceramic substrate supply through joint ventures in Yangtze River Delta manufacturing clusters. Battery-electric substitution threatens long-term demand; hybrid-compatible architectures offer the critical bridge technology lever. For New Entrants and Emerging Players: Marine and off-highway Stage V compliance corridors in European construction and agriculture represent the most penetrable entry point for specialized catalyst formulators. India's Stage VI-b retrofit preparation among aging Maharashtra and Gujarat fleets offers second-mover advantage without incumbent supply agreements. Partner with telematics providers for connected diagnostics integration as the go-to-market wedge. For Investors and Strategic Acquirers: Capital is best deployed toward catalyst specialists with precious metal formulation expertise and low-temperature SCR operation capabilities. The five-to-ten year viability window hinges on hybrid powertrain persistence before full electrification. Watch hydrogen fuel cell commercialization rates as the inflection signal for stranded technology risk.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Compatible Platform Development | Bridges combustion and zero-emission powertrains without stranding catalyst investments. |
| Electrically Heated Catalyst Integration | Enables Euro VII cold-start compliance through hybrid battery power draw. |
| Connected Diagnostics Capability | Supports China's MEE remote emissions monitoring mandates with real-time fault detection. |
| Retrofit Channel Expansion | Captures deadline-pressured fleet operators seeking Tier 4 Final compliance extensions. |
| Ceramic Substrate Backward Integration | Secures silicon carbide supply against South African mining output volatility. |
Methodological Framework
Operator-level perspectives from Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and fleet maintenance directors anchored the qualitative base. These primary inputs combined with vehicle production databases, IHS Markit registration data, EPA certification filings, and KBA type-approval records for secondary validation. Bottom-up sizing of SCR, DPF, and EGR installations triangulated against top-down OEM production forecasts.
Scenario-bracketing around electrification penetration rates and regulatory delay probabilities bounded the projection horizon. The analytical framework modeled segmentation across vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derived from installation volume trajectories and average selling price evolution across factory-installed and retrofit channels. Industry-specific inputs included precious metal loading trends and urea infrastructure buildout rates.
Macroeconomic conditions sit as an overlay; deviation in freight transport demand, diesel fuel pricing, or commercial vehicle investment cycles would shift the trajectory. Forecasts reflect assumptions about regulatory implementation timelines and hybrid powertrain persistence that material regulatory delays or battery cost breakthroughs could revise. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Motor Winding Repair Service Market
Vehicle Maintenance & Aftermarket
Nitrogen Tire Inflators Market
Vehicle Maintenance & Aftermarket
Classic Car Restoration and Restomod Services Market
Vehicle Maintenance & Aftermarket
APEJ Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Body Repair Tools Market
Vehicle Maintenance & Aftermarket
US Maintenance Repair and Operations (MRO) Market
Vehicle Maintenance & Aftermarket
Stolen Vehicle Recovery Market
Vehicle Maintenance & Aftermarket
Global Fleet Maintenance Software Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Fuel Additives Market
Vehicle Maintenance & Aftermarket
Vehicle Recycling Market
Vehicle Maintenance & Aftermarket
Vehicle Wash System Market
Vehicle Maintenance & Aftermarket
United Kingdom Vehicle Recycling Market
Vehicle Maintenance & Aftermarket
Highway Maintenance Market
Vehicle Maintenance & Aftermarket
Car Care Products Market
Vehicle Maintenance & Aftermarket
North America Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Europe Automotive Exhaust Aftertreatment Systems Market