
 Europe Automotive Parts Die Casting Market | 2026-2036
Europe Automotive Parts Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Parts Die Casting Market Analysis
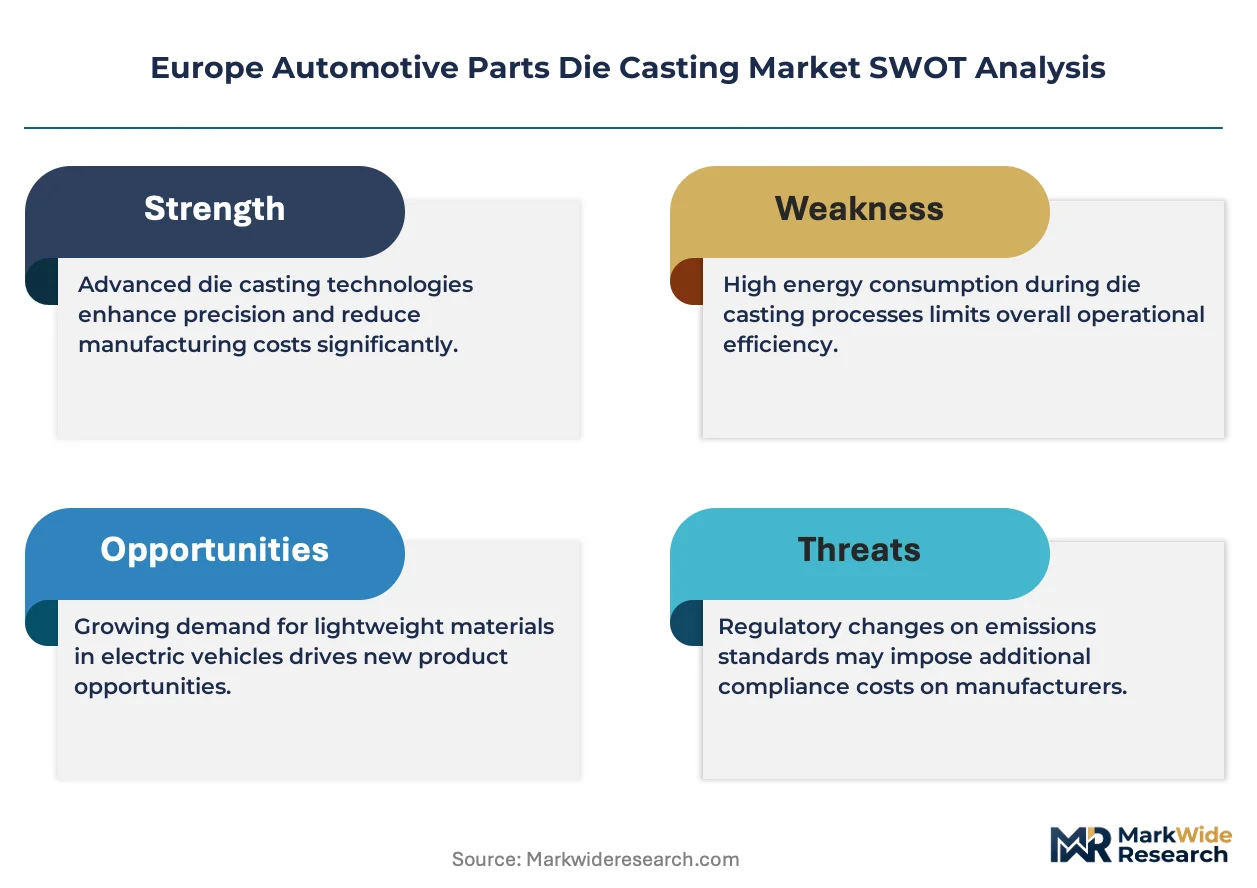
The Europe Automotive Parts Die Casting Market is recalibrating around a widening split between premium structural aluminum castings for EV platforms and commodity zinc components for legacy internal combustion vehicles. Rheinmetall Automotive leverages its captive foundry network to dominate large-format battery housing production for German OEMs. GF Casting Solutions anchors its position through deep specialization in magnesium powertrain components, while Nemak competes aggressively on high-pressure die casting scale across multiple European production sites.
Automotive parts die casting involves forcing molten non-ferrous metals—primarily aluminum alloys with 7-12% silicon content—into hardened steel molds at pressures exceeding 1,000 bar to produce net-shape components with wall thicknesses below 3 millimeters. This process delivers the dimensional precision and repeatability required for engine blocks, transmission cases, and structural nodes that must withstand cyclic thermal and mechanical loads. Aluminum die castings command the largest share of value given their strength-to-weight ratio and recyclability, while magnesium die castings represent the fastest-expanding category as OEMs pursue aggressive mass reduction targets for EV range optimization. High-pressure die casting technology leads in volume terms, though vacuum die casting is capturing margin pools in premium structural applications where porosity control determines fatigue performance.
The EU Green Deal's carbon border adjustments and REACH chemical restrictions are reshaping alloy sourcing and foundry emissions compliance across the value chain. ECHA's evolving substance restrictions on nickel and chromium compounds directly affect coating and surface treatment specifications for die cast automotive components. Stakeholders must monitor how the EU AI Act's quality assurance requirements intersect with automated die casting process control systems, as regulatory convergence between environmental and digital governance frameworks will determine competitive access to European OEM supply chains.
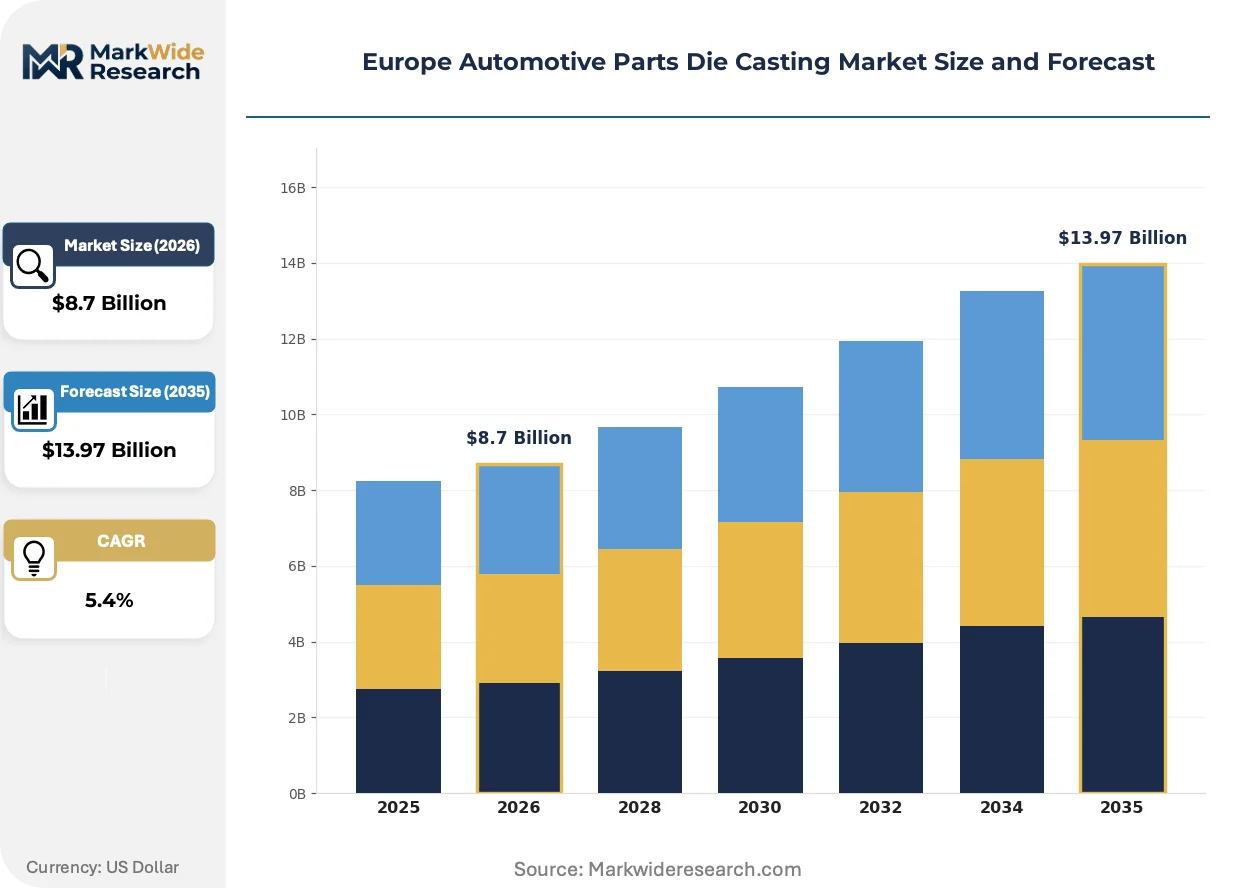
Market Dynamics
Electrification of European automotive platforms is forcing foundries to retool for aluminum-intensive battery housings and structural castings, compressing legacy zinc die casting capacity across the region.
Growth Catalysts
- EU Green Deal carbon border adjustments:Foundries investing in low-carbon primary aluminum and renewable-powered smelting gain preferential access to German OEM supply chains.
- High-pressure die casting scale-up:Equipment suppliers in Italy and Spain are deploying 4,000-ton clamping-force machines capable of single-shot battery tray production.
- EV powertrain housing demand:Electric motor enclosures and inverter housings require complex geometries with integrated cooling channels, specifications that favor precision die casting over competing processes.
Market Restraints
- Primary aluminum price volatility:Energy-intensive smelting costs tied to natural gas and electricity pricing expose margins to commodity swings.
- Silicon supply concentration:Ferrosilicon alloying elements sourced from limited European producers create input bottlenecks during energy rationing periods.
- REACH substance restrictions:ECHA's evolving nickel and chromium compound limitations constrain surface treatment options for corrosion-resistant castings.
Strategic Opportunities
- Poland and Czech Republic manufacturing corridors:Labor cost differentials and proximity to German assembly plants attract greenfield die casting investments.
- Structural battery enclosure integration:Cast-in cooling channels and crash-absorption features eliminate multi-part welded assemblies.
- F-Gas Regulation phase-down:Vacuum die casting systems using dry vacuum pumps instead of fluorinated gases qualify for accelerated depreciation incentives.
Industry Challenges
- High-pressure die casting simulation expertise:Computational fluid dynamics modeling for large-format castings requires specialized talent scarce outside Stuttgart and Munich industrial clusters.
- CSRD emissions reporting integration:Foundries must reconcile Scope 3 supplier data with OEM sustainability scorecards ahead of 2025 disclosure deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Parts Die Casting Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Die Castings, Magnesium Die Castings, Zinc Die Castings, Copper Die Castings End User: Vehicle Manufacturers, Tier-1 Suppliers, Aftermarket Providers, OEMs Application: Engine Components, Transmission Parts, Structural Components, Electrical Components Technology: High-Pressure Die Casting, Low-Pressure Die Casting, Gravity Die Casting, Vacuum Die Casting |
| Companies Covered | Rheinmetall Automotive, Nemak, Martinrea Honsel, Dynacast International, GF Casting Solutions, Ryobi Die Casting, Buhler Group, Handtmann Megacasting, Georg Fischer, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Parts Die Casting Market Emerging Trajectories
Process control digitization and alloy formulation advances are compressing development cycles for structural automotive castings. Foundries face pressure to demonstrate traceable sustainability credentials alongside dimensional precision.
Vacuum-assisted high-pressure die casting is absorbing porosity-sensitive applications previously reserved for gravity casting or machining from billet. BMW and Mercedes-Benz powertrain divisions specify vacuum die cast transmission cases for their premium EV platforms. The technology is absorbing margin pools in structural nodes where fatigue performance determines warranty exposure.
REACH chemical restrictions are tightening surface treatment specifications across the value chain. ECHA's proposed nickel compound limitations force foundries to qualify chromium-free passivation layers and alternative coating chemistries. Southern European suppliers with captive plating operations face disproportionate compliance retrofit costs.
Consolidated procurement of large-format structural castings is displacing fragmented supplier relationships. Volkswagen Group and Stellantis now specify single-source responsibility for integrated battery tray and crash management assemblies. Tier-1 die casters in Germany and Austria are capturing volume previously distributed across multiple component categories.
Europe Automotive Parts Die Casting Market Segmentation
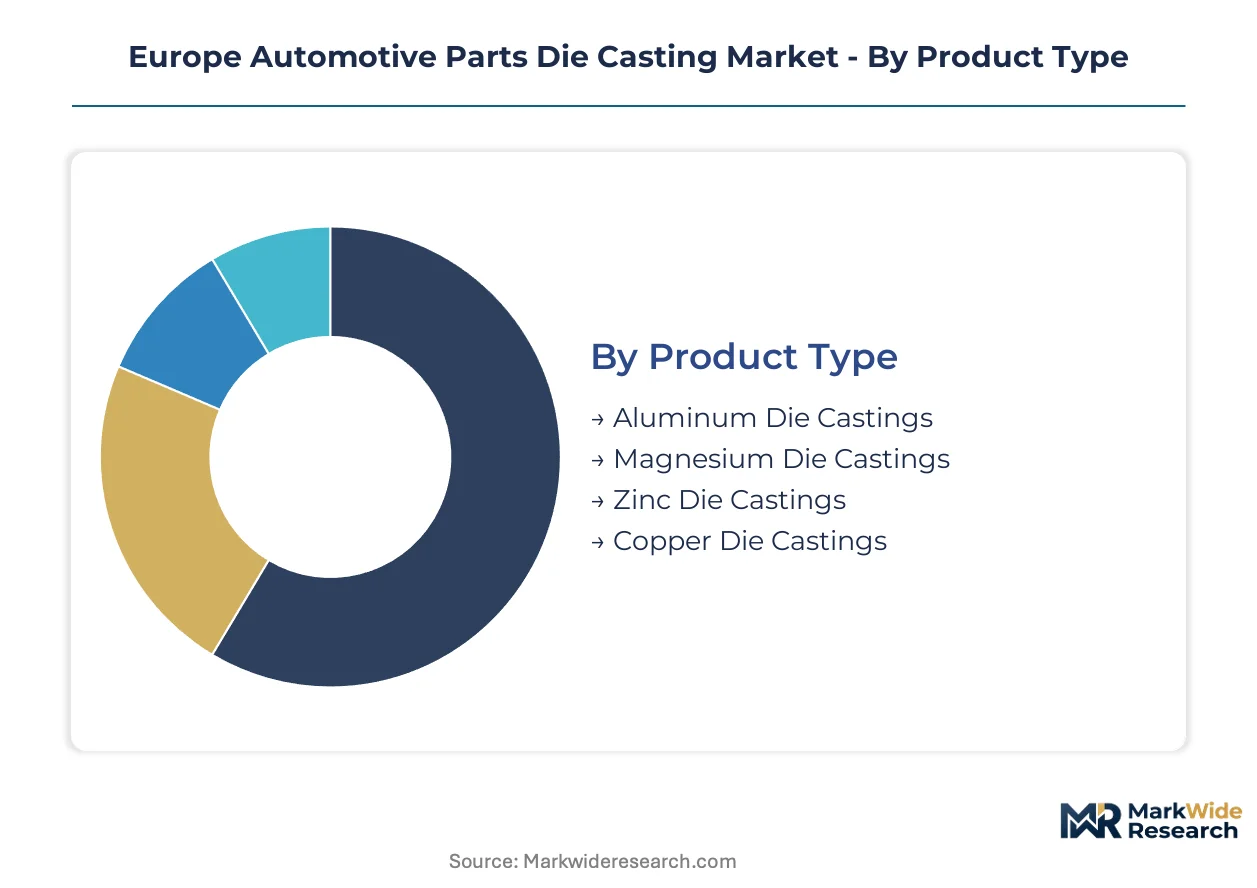
Die casting segmentation in Europe reflects divergent capital requirements across alloy systems and process technologies. Foundries must align equipment investments with OEM electrification roadmaps and regulatory compliance timelines.
Product Type:
Capital intensity varies sharply by alloy, with aluminum requiring the largest upfront melting and handling infrastructure.
- Aluminum Die Castings:Alloys with 7-12% silicon content dominate structural applications. German OEMs in Stuttgart and Wolfsburg specify these for battery housings and crash-management nodes under EU Green Deal carbon intensity requirements.
- Magnesium Die Castings:AZ91D and AM60B alloys deliver superior strength-to-weight ratios for powertrain brackets and steering column components. Demand concentrates in Munich-area EV platforms pursuing aggressive mass reduction targets.
- Zinc Die Castings:Zamak alloys serve interior trim and small engine hardware with lower furnace investment thresholds.
- Copper Die Castings:High-conductivity applications in electrical busbars and motor terminals occupy niche volumes.
Aluminum die castings absorb the bulk of installed capacity; magnesium die castings are expanding most quickly.
End User:
Procurement power concentrates with entities controlling platform architecture decisions and sustainability scorecards.
- Vehicle Manufacturers:Volkswagen Group and Stellantis consolidate sourcing for integrated battery tray assemblies, requiring single-source accountability and CSRD-aligned emissions reporting.
- Tier-1 Suppliers:Continental and Bosch specify die cast subcomponents for modular powertrain systems, pushing qualification costs onto foundries.
- OEMs:Premium German marques demand vacuum die casting for transmission cases with integrated cooling channels.
- Aftermarket Providers:Replacement engine blocks and transmission housings follow slower qualification cycles with less stringent traceability requirements.
Vehicle manufacturers command the largest procurement volumes; Tier-1 suppliers are climbing the fastest as outsourcing accelerates.
Application:
Functional requirements determine alloy selection and process tolerance specifications across vehicle systems.
- Structural Components:Battery enclosures and crash-absorption nodes require vacuum-assisted high-pressure die casting to achieve fatigue performance specifications.
- Engine Components:Cylinder heads and blocks face declining volumes as ICE platforms phase out across EU member states.
- Transmission Parts:EV reduction gear housings replace multi-speed transmission cases, altering geometry complexity and cooling integration requirements.
- Electrical Components:Motor housings and inverter enclosures demand tight dimensional control for thermal management interface precision.
Structural components absorb the bulk of installed capacity; electrical components are gaining share fastest.
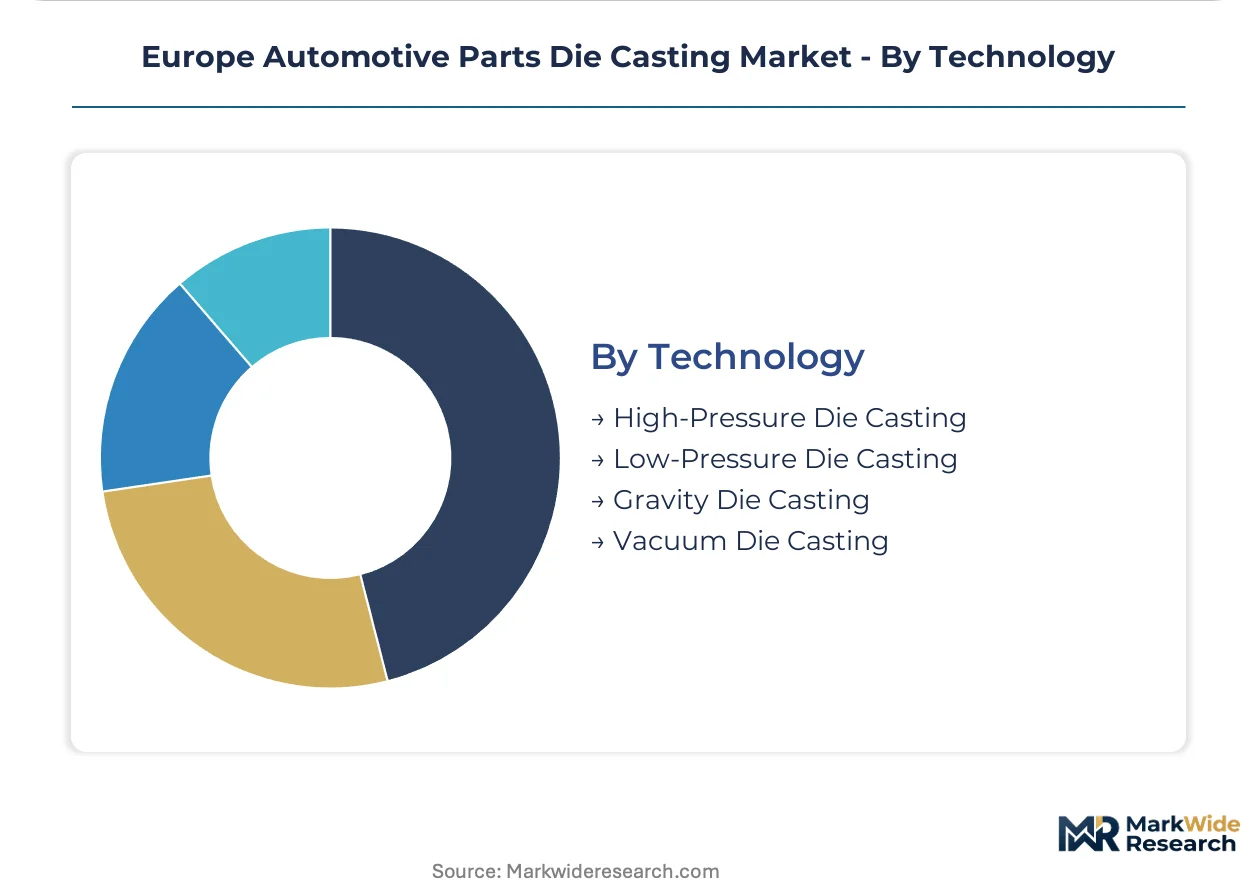
Technology:
Equipment scale and automation levels create tiered barriers to entry for foundry operators.
- High-Pressure Die Casting:Italian and Spanish equipment suppliers deploy 4,000-ton clamping-force machines for single-shot battery tray production, requiring substantial real estate and utility commitments.
- Vacuum Die Casting:BMW and Mercedes-Benz specify this technology for premium EV powertrain housings where porosity control determines warranty exposure.
- Low-Pressure Die Casting:Wheel and suspension components favor this method for directional solidification control.
- Gravity Die Casting:Lower tooling costs suit prototype volumes and legacy component categories with slower design refresh cycles.
High-pressure die casting commands the largest installed base; vacuum die casting is scaling most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European die casting demand through its concentration of premium OEM powertrain engineering. Munich and Wolfsburg complete the German manufacturing corridor that consumes the majority of high-pressure aluminum capacity. Foundry investment patterns track electrification roadmaps across member states.
Germany
Volkswagen Group and Mercedes-Benz specifications for integrated battery trays drive 4,000-ton machine deployments in Baden-Württemberg and Lower Saxony. The EU Green Deal's carbon border adjustments favor foundries sourcing low-carbon primary aluminum through renewable-powered smelting. Stuttgart-Munich-Wolfsburg corridor suppliers capture single-source contracts for structural EV castings requiring CSRD-aligned emissions reporting.
Italy
Equipment manufacturers in Brescia and Bologna provinces supply 4,000-ton clamping-force machines to German OEMs. REACH substance restrictions on nickel compounds force foundries to qualify chromium-free passivation layers for corrosion-resistant components. Lombardy-based suppliers face disproportionate compliance retrofit costs for captive plating operations.
Poland
Lower Silesia and Upper Silesia manufacturing corridors attract greenfield die casting investments through labor cost differentials and German assembly plant proximity. ECHA's evolving chemical restrictions apply equally to Polish suppliers accessing EU supply chains. Katowice-area foundries specialize in secondary aluminum processing for Tier-1 powertrain modules.
Czech Republic
Hyundai and Škoda Auto electrification programs generate demand for motor housings and inverter enclosures in the Central Bohemian Region. F-Gas Regulation phase-down incentives accelerate vacuum die casting adoption using dry vacuum pumps. Mladá Boleslav suppliers integrate cast-in cooling channels for battery thermal management systems.
Spain
Stellantis production consolidation in Zaragoza and Madrid drives structural casting demand for EV platform localization. Spanish equipment suppliers deploy large-format machines capable of single-shot battery tray production. Catalonia-based foundries serve aftermarket transmission housing volumes with slower qualification cycles.
Europe Automotive Parts Die Casting Market Vendor Landscape
Premium-margin players sit above commodity-margin players across alloy specialization and OEM qualification depth. German and Swiss-headquartered groups dominate structural aluminum for EV platforms through captive foundry networks. Three archetypes define competitive positioning: integrated automotive suppliers with captive casting divisions, pure-play die casting specialists with multi-OEM qualifications, and equipment manufacturers extending into production services. Consolidation pressure intensifies through OEM single-sourcing mandates for battery enclosures and Tier-1 supplier backward integration into primary casting.
Within the integrated supplier tier, Rheinmetall Automotive and GF Casting Solutions occupy positions shaped by captive foundry depth and magnesium specialization respectively. Nemak exemplifies the scale-driven archetype across multiple European production sites. Martinrea Honsel represents mid-cap specialists competing on high-pressure die casting process control for German OEM supply chains.
| Leading Market Players |
|---|
| Rheinmetall Automotive |
| Nemak |
| Martinrea Honsel |
| Dynacast International |
| GF Casting Solutions |
| Ryobi Die Casting |
| Buhler Group |
| Handtmann Megacasting |
| Georg Fischer |
| Others |
Supply Flow & Price Mechanics
German OEM procurement consolidation around single-source battery tray contracts concentrates buyer power and enforces value-based pricing tied to fatigue performance guarantees and CSRD-aligned carbon intensity. Volkswagen Group and Mercedes-Benz specifications reward foundries delivering vacuum die cast structural nodes with integrated cooling channels, compressing margins for commodity zinc suppliers serving legacy powertrain categories.
Pricing Analysis
Value-based pricing anchored to warranty exposure and porosity control specifications dominates premium structural aluminum castings for EV platforms. Pricing stratifies across vacuum die casting premiums, standard high-pressure capacity, and economy-grade zinc interior components, with differentiation driven by OEM qualification depth and renewable energy sourcing credentials. Cost compression in legacy zinc die casting intensifies as electrification retools capacity toward aluminum battery housings. Tier-1 suppliers exhibit lowest price sensitivity given single-source accountability requirements, while aftermarket providers face acute margin pressure from slower qualification cycles.
Supply Chain Analysis
EU Green Deal carbon border adjustments and domestic-content preferences for low-carbon primary aluminum reshape sourcing toward renewable-powered smelting in Norway and Iceland. Supply draws from bauxite refining concentrated in Guinea and Australia, ferrosilicon alloying elements from limited European producers, and specialized 4,000-ton machine capacity from Italian equipment manufacturers. Single-source vulnerability around silicon supply creates input bottlenecks during energy rationing periods. Distribution runs through just-in-sequence delivery to Stuttgart, Munich, and Wolfsburg assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Large-format vacuum die casting capacity operates under acute constraint, with 4,000-ton machine lead times extending beyond OEM electrification timelines and propping pricing premiums for qualified suppliers.
For Market Incumbents: Acquire captive magnesium alloying and secondary aluminum processing capabilities to secure input cost control against ferrosilicon price volatility. Consolidate regional foundry networks in Poland and Czech Republic manufacturing corridors to defend margin position against emerging Tier-1 backward integration into primary casting. Prioritize CSRD emissions reporting infrastructure ahead of disclosure deadlines to maintain German OEM supply chain access. For New Entrants and Emerging Players: F-Gas Regulation phase-down incentives in Czech Republic and Poland open a window for dry vacuum pump vacuum die casting adoption without legacy fluorinated gas retrofit burdens. Target structural battery enclosure integration for Hyundai and Škoda Auto electrification programs in Central Bohemia, where single-source qualification pathways remain less entrenched than German OEM supply chains. Lead with cast-in cooling channel expertise as the go-to-market wedge. For Investors and Strategic Acquirers: The window for entry favors pure-play die casting specialists with multi-OEM qualifications and unencumbered balance sheets capable of 4,000-ton machine deployment. Long-term viability hinges on positioning upstream of battery platform standardization cycles rather than downstream of declining transmission case volumes. Watch for Volkswagen Group and Stellantis single-sourcing mandate acceleration as the inflection signal for consolidation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Large-Format Machine Deployment | 4,000-ton clamping-force capacity captures single-shot battery tray contracts from German OEMs. |
| Renewable-Powered Smelting Integration | Low-carbon primary aluminum sourcing qualifies suppliers for EU Green Deal carbon border preferential access. |
| Vacuum Die Casting Scale-Up | Dry vacuum pump adoption aligns with F-Gas Regulation phase-down incentives in Czech and Polish corridors. |
| Magnesium Alloy Specialization | AZ91D and AM60B expertise addresses Munich-area EV mass reduction targets for powertrain brackets. |
| CSRD Reporting Infrastructure | Scope 3 emissions traceability secures Tier-1 supplier scorecard compliance ahead of OEM disclosure deadlines. |
Methodological Framework
Document review covered ECHA substance restriction filings, EU Green Deal implementation guidance, and foundry equipment manufacturer technical specifications, complemented by interviews with OEM platform engineers, Tier-1 supplier procurement leads, and secondary aluminum processors. Primary fieldwork engaged vacuum die casting specialists in Stuttgart and Munich industrial clusters, magnesium alloy formulators, and renewable energy procurement officers at smelting operations. Secondary validation drew from customs trade data, national emissions registries, and automotive production databases. Bottom-up capacity modeling and top-down OEM electrification roadmap analysis were triangulated against foundry investment announcements.
Historical capacity deployment patterns were cross-referenced against panel input from equipment manufacturers and foundry operators to construct the analytical framework. Segmentation modeling spanned alloy systems, process technologies, end-user procurement tiers, and regional manufacturing clusters across the projection horizon. CAGRs were derived from production volume trajectories mapped to OEM platform electrification schedules and content-per-vehicle assumptions for structural castings. Forecast inputs incorporated energy price scenarios affecting smelting economics and REACH chemical restriction implementation timelines.
Caveats apply where ECHA nickel compound limitation enforcement, natural gas price volatility, or silicon supply disruptions could materially shift the outlook for foundry input costs and capacity utilization. Forecasts reflect assumptions regarding OEM single-sourcing consolidation pace and battery platform standardization cycles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Central Lubrication System Market
Automotive Parts
Philippines Automotive Engine Oils Market
Automotive Parts
Global Fuel and Oil Filters Market
Automotive Parts
North America Automotive Airfilters Market
Automotive Parts
Global Automotive Plastic Fuel Tank Market
Automotive Parts
Ball Bearing Market
Automotive Parts
Europe Automotive Parts Zinc Die Casting Market
Automotive Parts
Global Automotive Cooler Market
Automotive Parts
North America Automotive Parts Die Casting Market
Automotive Parts
Automotive Trailing Arm Market
Automotive Parts
Automotive Belts Market
Automotive Parts
Electric Power Steering Market
Automotive Parts
Camshaft Lifters Market
Automotive Parts
Global Automotive Cylinder Liner Market
Automotive Parts
France Automotive Lubricants Market
Automotive Parts
Vehicle Transfer Case Market