
 Global Energy-Based Non-Invasive Medical Aesthetic Treatment System Market | 2026-2036
Global Energy-Based Non-Invasive Medical Aesthetic Treatment System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Energy-Based Non-Invasive Medical Aesthetic Treatment System Market Foresight
The EU Medical Device Regulation is repositioning the cost-of-entry calculus for aesthetic device manufacturers seeking European market access. Cutera leverages its specialized portfolio of laser and energy platforms to sustain competitive positioning across premium clinic segments. Alma Lasers anchors its global presence through manufacturing scale and broad technology coverage spanning radiofrequency and ultrasound modalities.
Energy-based non-invasive medical aesthetic treatment systems employ controlled electromagnetic energy delivery—typically operating at wavelengths between 400 nm and 10,600 nm for laser modalities or frequencies between 0.3 MHz and 40 MHz for radiofrequency systems—to remodel collagen, reduce adipose tissue, or eliminate targeted chromophores without epidermal breach. These devices serve commercial purposes across dermatology clinics, cosmetic surgery centers, and medical spas seeking outpatient alternatives to surgical intervention. Laser technology occupies the largest installed base among energy modalities, while cryolipolysis represents the fastest-growing application segment as body contouring demand expands beyond traditional cosmetic surgery channels. End-user concentration tilts toward dermatology clinics and medical spas, where higher procedure volumes support capital equipment returns.
The FDA maintains 510(k) premarket notification requirements for laser and radiofrequency aesthetic devices, while the EU MDR imposes strengthened clinical evidence standards for Class IIa and above energy-based systems. China's NMPA implements GB standards for laser safety classification and electromagnetic compatibility testing that manufacturers must satisfy for domestic market authorization. Stakeholders must monitor evolving post-market surveillance requirements across multiple jurisdictions as regulatory convergence around clinical performance data reshapes competitive barriers.
Market Dynamics
Multi-technology platform consolidation is compressing capital deployment cycles across dermatology clinics and medical spas, as operators replace single-modality devices with integrated systems that address multiple aesthetic indications through unified control interfaces.
Growth Catalysts
- EU MDR Clinical Evidence Requirements:Strengthened post-market surveillance mandates for Class IIa energy-based devices are accelerating replacement demand among European clinics seeking compliant equipment fleets.
- Radiofrequency Adipose Remodeling:Non-thermal radiofrequency protocols for subcutaneous fat reduction are expanding procedure volumes beyond traditional laser-centric practices into primary care and wellness settings.
- China's Tier-One Medical Spa Chains:Standardized procurement programs across Shanghai, Beijing, and Shenzhen clinic networks are concentrating equipment orders toward multi-modality platform suppliers.
Market Restraints
- Optical Component Supply Concentration:German and Japanese suppliers dominate high-power laser diode and fiber-optic delivery system manufacturing, creating input vulnerability for device assemblers.
- FDA 510(k) Substantial Equivalence Pathway:Evolving predicate device requirements are extending premarket notification review timelines and increasing regulatory consulting expenditures for novel wavelength introductions.
- Intense Pulsed Light Substitution:Lower-cost IPL platforms continue displacing dedicated laser systems in pigmentation and vascular applications, compressing average selling prices in the photorejuvenation segment.
Strategic Opportunities
- Brazil's Underpenetrated Aesthetic Clinic Network:São Paulo and Rio de Janeiro medical spa density remains below South Korean benchmarks, presenting equipment placement potential as disposable income rises.
- Combination Protocol Reimbursement:Integrated treatment sequences pairing cryolipolysis with radiofrequency skin tightening are commanding premium positioning in cash-pay aesthetic markets.
- Japan's PMDA Streamlined Review:Accelerated approval pathways for devices with prior FDA or CE marking are reducing time-to-market for manufacturers with established Western regulatory dossiers.
Industry Challenges
- Laser Safety Officer Certification Bottlenecks:Qualified clinical training personnel scarcity is delaying device activation and revenue recognition post-installation across multi-site clinic operators.
- Legacy EMR Integration Complexity:Proprietary device data formats from established laser and radiofrequency manufacturers resist seamless connectivity with prevalent dermatology practice management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Energy-Based Non-Invasive Medical Aesthetic Treatment System Market |
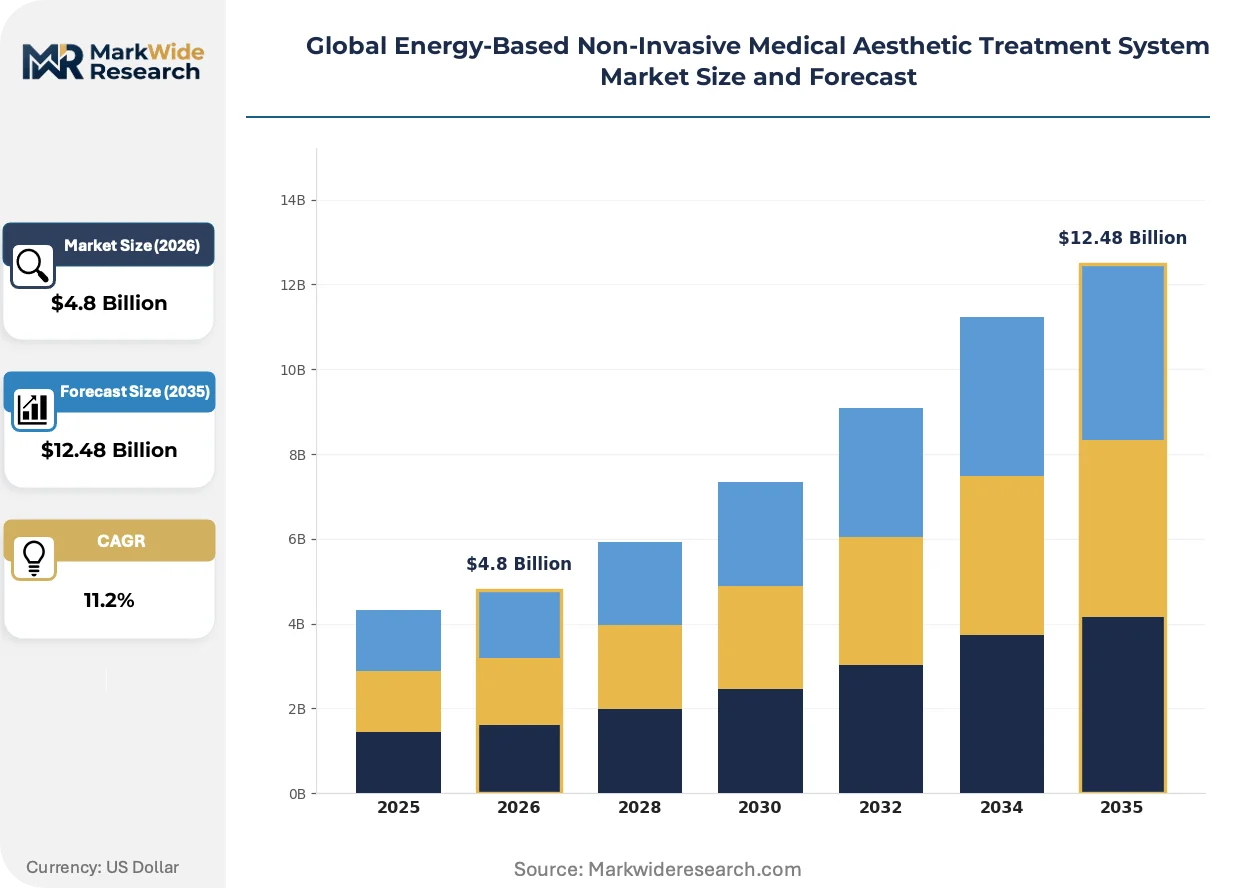
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.48 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radiofrequency, Ultrasound, Laser, Intense Pulsed Light, Cryolipolysis, Microcurrent Application: Skin Rejuvenation, Wrinkle Reduction, Body Contouring, Scar Treatment, Hair Removal, Vascular Lesion Treatment End User: Dermatology Clinics, Cosmetic Surgery Centers, Medical Spas, Beauty Salons, Wellness Centers, Home Use Deployment: Stationary Systems, Portable Devices, Handheld Tools, Integrated Platforms, Cabin-Based Units, Mobile Units |
| Companies Covered | Cutera, Merz Pharma, Allergan, Syneron Medical, Galderma, Cynosure, Alma Lasers, InMode Aesthetic Solutions, Lumenis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Energy-Based Non-Invasive Medical Aesthetic Treatment System Market Shifts & Advancements
Convergence between artificial intelligence-driven treatment planning and real-time tissue feedback systems is redefining operator skill requirements and procedure standardization across energy-based aesthetic platforms.
Picosecond-domain laser technology is electrifying tattoo removal and benign pigmented lesion protocols through mechanical photodisruption rather than thermal coagulation mechanisms. High-volume dermatology chains in South Korea and Spain are replacing nanosecond Nd:YAG systems at accelerated refresh cycles. This wavelength-domain shift is compressing residual value for legacy Q-switched installations while elevating capital intensity requirements for competitive positioning.
China's NMPA implementation of GB laser safety classification standards is harmonizing electromagnetic compatibility testing protocols with IEC baselines while maintaining domestic certification mandates. Manufacturers must duplicate conformity assessment procedures for GB mark acquisition alongside CE technical documentation. The regulatory friction most affects mid-tier device suppliers lacking dedicated Shanghai regulatory affairs capacity.
Subscription-based equipment access models are displacing traditional capital purchase arrangements among North American medical spa startups and fractional ownership clinic networks. Monthly per-procedure fee structures bundle maintenance, consumables, and software updates into predictable operating expenditures. This financing innovation concentrates most visibly in Texas and Florida aesthetic practice formations where physician oversight requirements enable multi-location service aggregation.
Global Energy-Based Non-Invasive Medical Aesthetic Treatment System Market Segmentation
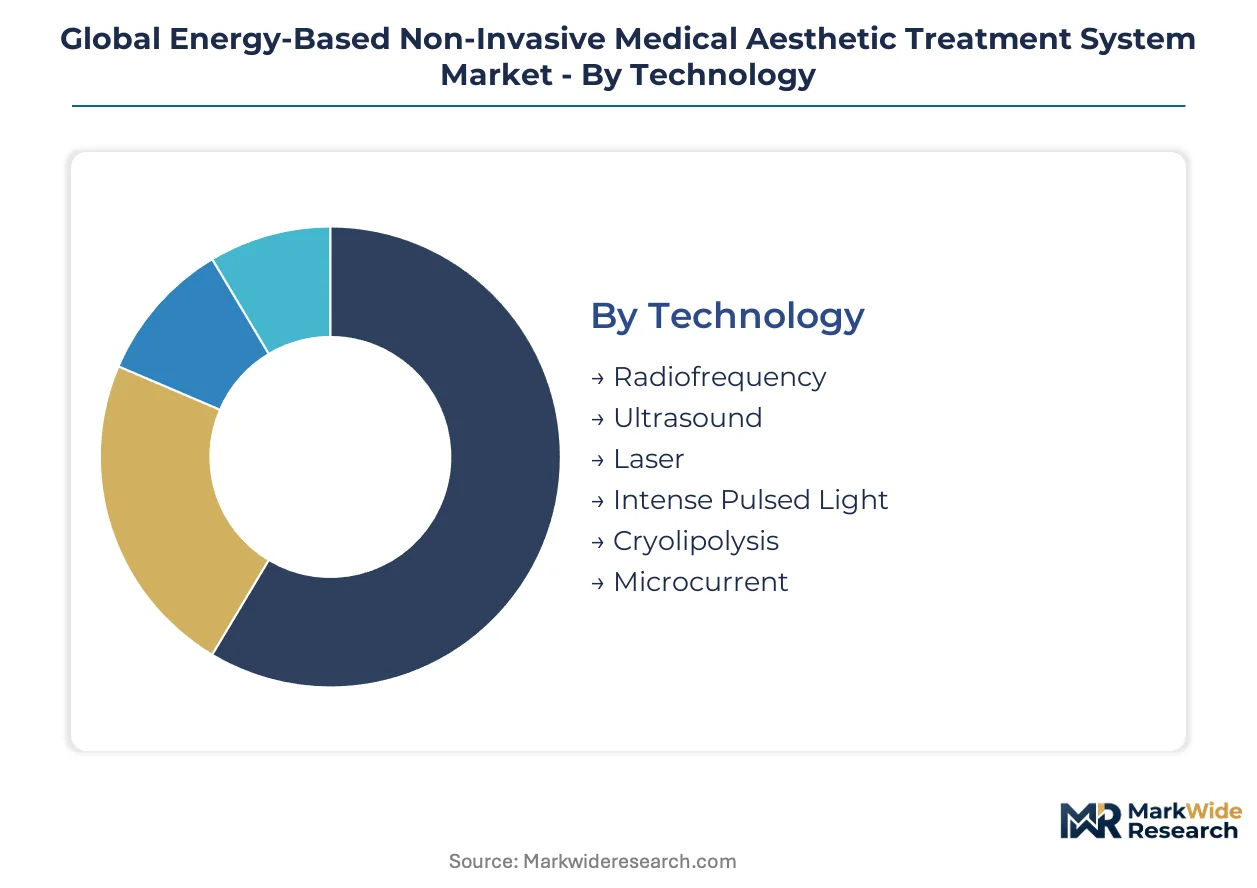
Technology modality determines equipment capital requirements and reimbursement positioning across aesthetic practices. Application focus shapes patient volume economics and seasonal utilization patterns. Deployment format influences clinic space allocation and multi-site standardization strategies.
Technology:
Laser and radiofrequency platforms demand the highest upfront capital deployment, with multi-wavelength systems requiring specialized optical infrastructure and cooling subsystems that stationary installations must accommodate.
- Laser:Solid-state and diode laser systems operating across visible to infrared wavelengths deliver precise chromophore targeting for pigmentation and vascular indications. Dermatology clinics in South Korea and Spain are refreshing nanosecond installations with picosecond-domain platforms. Capital intensity peaks here due to optical component sourcing concentration in German and Japanese supply chains.
- Radiofrequency:Monopolar and bipolar configurations generate dermal heating through tissue impedance, with non-thermal protocols now penetrating subcutaneous fat layers. Demand concentrates in China's tier-one medical spa chains seeking multi-modality platforms that combine adipose remodeling with skin tightening in unified treatment sequences.
- Ultrasound:Microfocused ultrasound systems create thermal coagulation points at precise tissue depths without epidermal damage. FDA-cleared indications for brow lifting and submental contouring drive placement in US cosmetic surgery centers.
- Intense Pulsed Light:Broadband filtered flashlamps address photorejuvenation and hair removal at lower hardware cost than dedicated lasers. IPL platforms displace laser systems in volume-sensitive pigmentation applications.
- Cryolipolysis:Controlled cooling applicators induce adipocyte apoptosis through selective cold exposure. Body contouring demand expansion beyond traditional surgical channels positions this modality for wellness center penetration.
- Microcurrent:Low-level electrical stimulation protocols target facial muscle toning with minimal regulatory burden. Home-use device proliferation competes with professional-grade systems in the facial aesthetic segment.
Most installed capacity flows through Laser. Expansion is steepest in Cryolipolysis.
Application:
Procedure volume and pricing power diverge sharply between facial rejuvenation protocols and body contouring sequences, with the latter requiring longer treatment times but commanding premium positioning in cash-pay markets.
- Skin Rejuvenation:Photodamage reversal and texture improvement protocols dominate aesthetic practice revenue through repeat visit structures. Combination treatments pairing fractional laser with radiofrequency tightening command premium positioning in Dubai and São Paulo medical spa markets.
- Wrinkle Reduction:Neurotoxin adjunctive protocols and standalone energy-based collagen remodeling address periorbital and perioral rhytides. China's tier-one cities concentrate demand as disposable income thresholds support elective facial aesthetic expenditure.
- Body Contouring:Non-invasive adipose reduction and skin laxity correction procedures extend aesthetic practice addressable market beyond facial applications. Cryolipolysis-radiofrequency combination protocols gain traction in Brazilian clinic networks.
- Scar Treatment:Fractional laser and radiofrequency microneedling protocols address acne and surgical scarring through controlled wound healing stimulation. Dermatology clinics prioritize this application for medical necessity positioning.
- Hair Removal:Long-pulse laser and IPL platforms target melanin-rich follicles across skin type categories. Price compression intensifies as diode laser cost curves enable salon-grade system proliferation.
- Vascular Lesion Treatment:Pulsed dye and long-pulse Nd:YAG systems address hemoglobin-selective chromophores. Pediatric and medical dermatology applications sustain professional-grade equipment demand against IPL substitution.
Skin Rejuvenation captures the largest procedure volume base. Body Contouring climbs the fastest as wellness center channels expand.
End User:
Regulatory oversight intensity and physician supervision requirements create distinct equipment procurement patterns across clinical and non-clinical settings.
- Dermatology Clinics:Board-certified dermatologist oversight enables the broadest indication claims and highest reimbursement positioning. South Korean clinic chains are expanding laser and radiofrequency device fleets at accelerated refresh cycles.
- Cosmetic Surgery Centers:Plastic surgeon-directed facilities integrate energy-based systems as surgical adjuncts and standalone offerings. Combination protocol bundling with invasive procedures supports premium pricing.
- Medical Spas:Physician-supervised non-clinical settings concentrate multi-modality platform demand in China's standardized procurement programs. Monthly subscription financing models displace capital purchases among North American startup formations.
- Beauty Salons:Lower-regulation environments in select jurisdictions permit IPL and microcurrent device operation. Price-sensitive procurement favors Chinese-manufactured platforms with simplified feature sets.
- Wellness Centers:Holistic health positioning drives cryolipolysis and body-focused radiofrequency adoption. Non-thermal fat reduction protocols expand addressable market beyond traditional aesthetic channels.
- Home Use:Consumer-grade IPL and microcurrent devices capture facial aesthetic demand outside professional settings. Regulatory classification as cosmetic rather than medical devices accelerates retail channel penetration.
Dermatology Clinics deploy the most capital-intensive equipment configurations. Medical Spas are gaining share fastest through chain standardization.
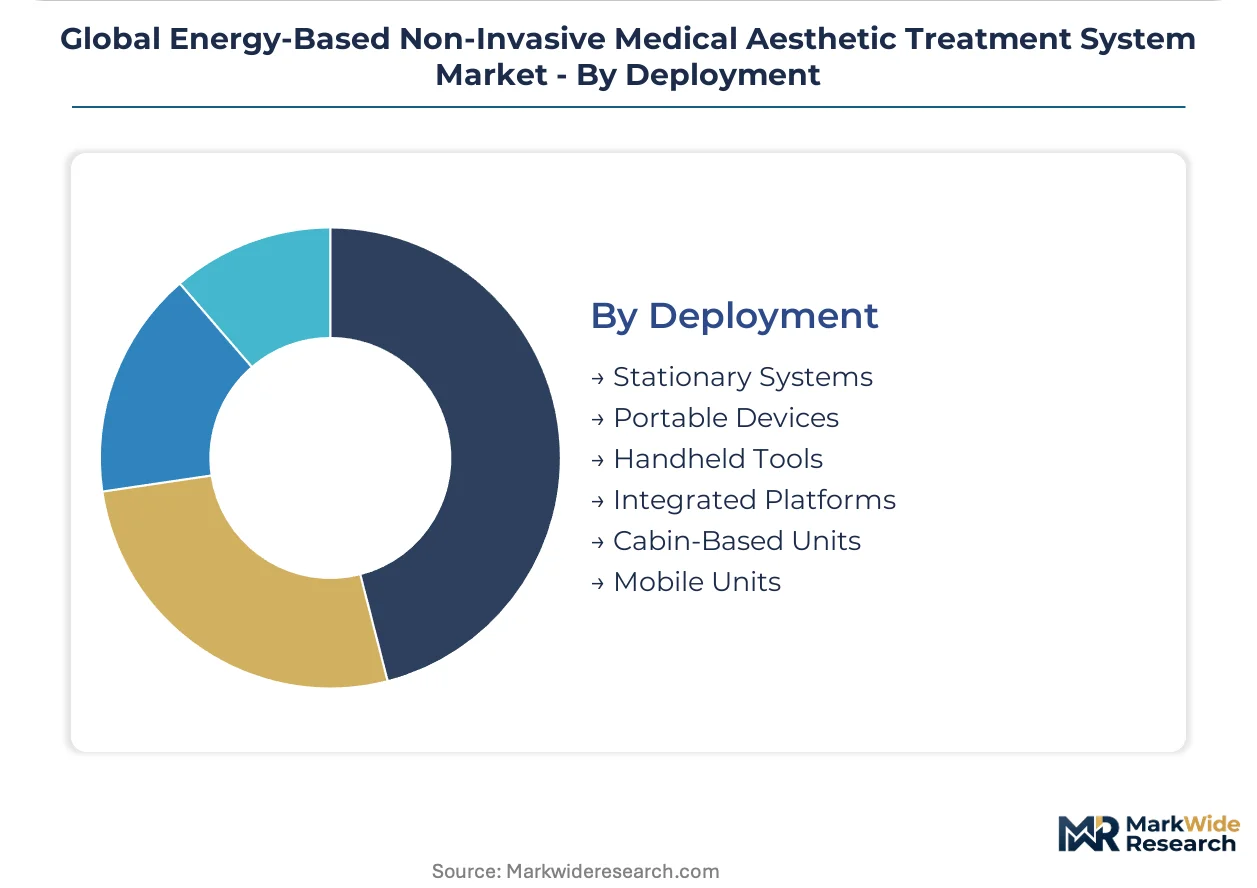
Deployment:
Physical footprint and mobility requirements shape lease-versus-buy decisions and multi-site fleet management complexity.
- Stationary Systems:Floor-mounted platforms with integrated cooling and power conditioning subsystems support the highest energy outputs. German and Japanese optical component integration demands fixed installation infrastructure.
- Portable Devices:Wheeled configurations enable room-to-room mobility within clinic environments. US dermatology practices favor this format for space-constrained urban locations.
- Handheld Tools:Operator-directed applicators reduce equipment footprint to treatment room drawer storage. Microcurrent and low-level laser devices dominate this category.
- Integrated Platforms:Multi-modality systems combining laser, radiofrequency, and ultrasound in unified control interfaces compress capital deployment cycles. China's tier-one medical spa chains standardize procurement on this format.
- Cabin-Based Units:Enclosed treatment environments for whole-body cryolipolysis or phototherapy protocols. Wellness center channel expansion supports this deployment category.
- Mobile Units:Vehicle-mounted systems serving event-based or rural aesthetic service delivery. Brazilian and Mexican markets experiment with this format for underpenetrated geographic coverage.
Stationary Systems retain the largest installed base. Integrated Platforms are expanding most quickly as clinic operators consolidate device fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Board-certified dermatologists and plastic surgeons cluster in South Korea, the United States, Germany, Brazil, and China's tier-one cities, anchoring procedure volume and equipment procurement decisions across distinct regulatory environments.
United States
Cosmetic surgery centers in Miami and Los Angeles drive cryolipolysis and microfocused ultrasound adoption for body contouring protocols. FDA 510(k) premarket notification requirements govern laser and radiofrequency device authorization, with evolving predicate device standards extending review timelines for novel wavelength introductions. Texas and Florida medical spa formations concentrate subscription-based equipment financing demand.
South Korea
Dermatology clinic chains in Seoul and Busan refresh picosecond laser installations at accelerated cycles, displacing legacy nanosecond systems. The MFDS maintains medical device licensing requirements that align with IEC baselines for electromagnetic compatibility. Gangnam district clinics deploy the densest multi-modality platform concentrations globally.
Germany
Precision manufacturing clusters in Munich and Stuttgart supply high-power laser diodes and fiber-optic delivery systems dominating global optical component sourcing. EU MDR strengthened clinical evidence standards for Class IIa energy-based devices reshape manufacturer compliance burdens. Bavarian clinic networks standardize procurement on CE-marked integrated platforms.
China
Medical spa chains in Shanghai, Beijing, and Shenzhen concentrate standardized procurement programs for multi-technology platforms. NMPA GB standards for laser safety classification and electromagnetic compatibility testing mandate duplicate conformity assessment procedures alongside CE technical documentation. Yangtze River Delta manufacturing bases serve domestic device assembly demand.
Brazil
São Paulo and Rio de Janeiro medical spa density remains below South Korean benchmarks, presenting equipment placement potential as disposable income thresholds rise. ANVISA medical device registration requirements govern market authorization for imported laser and radiofrequency systems. São Paulo state clinics experiment with mobile unit deployments for underpenetrated geographic coverage.
Global Energy-Based Non-Invasive Medical Aesthetic Treatment System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology modality boundaries. The vendor base stratifies between premium-tier integrated platform suppliers and mid-tier single-modality device assemblers. Three archetypes dominate: optical component-integrated manufacturers, regulatory dossier-heavy Western incumbents, and cost-optimized Asian fabricators. Competitive moves center on M&A for technology portfolio expansion and strategic partnerships for distribution reach into China's tier-one clinic networks.
Among diversified aesthetic device portfolios, Cutera and Alma Lasers occupy positions exemplifying premium-tier specialization archetypes, while Merz Pharma represents the pharmaceutical-conglomerate diversification model. Cutera's laser and energy platform concentration mirrors pure-play specialist positioning. Alma Lasers anchors manufacturing scale advantages through broad technology coverage spanning radiofrequency and ultrasound modalities. Merz Pharma sits within the diversified healthcare conglomerate tier, leveraging aesthetic device holdings alongside therapeutic pharmaceutical portfolios.
| Leading Market Players |
|---|
| Cutera |
| Merz Pharma |
| Allergan |
| Syneron Medical |
| Galderma |
| Cynosure |
| Alma Lasers |
| InMode Aesthetic Solutions |
| Lumenis |
| Others |
Supply & Pricing Matrix
China's tier-one medical spa chains concentrate procurement volume through standardized multi-technology platform programs, anchoring a subscription-based pricing model that bundles equipment access with per-procedure fees and maintenance coverage.
Pricing Analysis
Subscription-based service bundling separates capital-light clinic formations from traditional equipment purchase arrangements. Pricing stratifies across premium integrated platforms with AI-driven treatment planning, standard multi-modality systems, and economy-tier single-technology devices. Cost compression in the photorejuvenation segment intensifies as IPL platforms displace dedicated laser systems. Medical spa startups in Texas and Florida exhibit highest price sensitivity, while South Korean dermatology clinic chains prioritize performance specifications over acquisition cost.
Supply Chain Analysis
Reverse-logistics flows for laser diode refurbishment and radiofrequency handpiece remanufacturing concentrate in German and Japanese service hubs, extending component lifecycle value for high-power optical systems. Manufacturing draws from German precision optics clusters, Japanese fiber-optic delivery specialists, and Chinese assembly bases in the Yangtze River Delta. Single-source vulnerability in high-power laser diode sourcing creates supply chain risk. Distribution runs through regional device distributors with clinical training certification capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
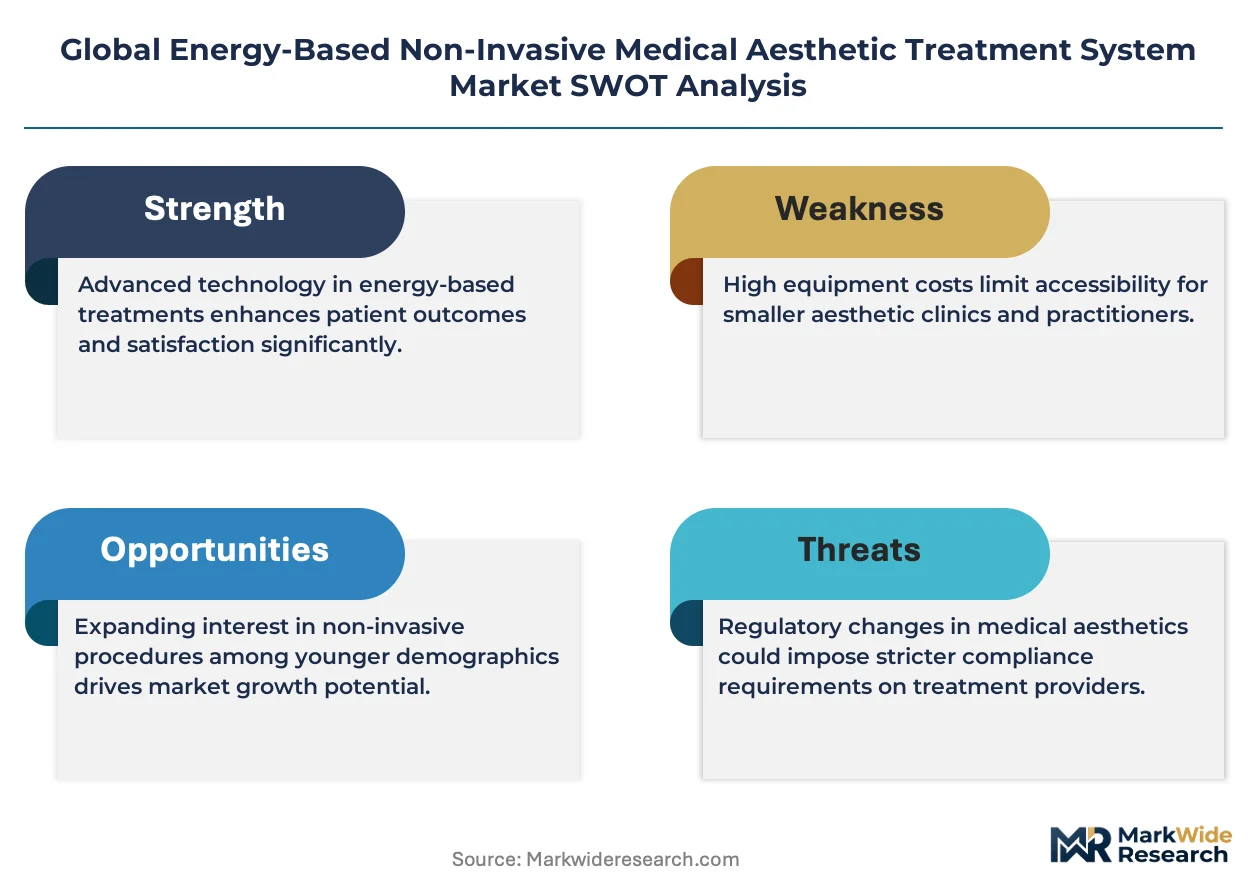
This market functions as a regulatory compounder, with EU MDR strengthened clinical evidence requirements for Class IIa energy-based devices accelerating replacement demand among European clinics seeking compliant equipment fleets.
For Market Incumbents: Deploy AI-driven treatment planning software as a platform stickiness mechanism. Cutera and Alma Lasers should deepen backward integration into optical component sourcing to mitigate German and Japanese supplier concentration. Defensive patent positioning around picosecond-domain laser technology blocks emerging entrant access to high-margin tattoo removal protocols. For New Entrants and Emerging Players: Enter via Brazil's underpenetrated medical spa network, where São Paulo and Rio de Janeiro clinic density remains below South Korean benchmarks. Target wellness center channels with non-thermal radiofrequency adipose remodeling protocols that bypass dermatology clinic regulatory barriers. Pursue subscription financing partnerships with North American fractional ownership clinic networks to bypass capital purchase friction. For Investors and Strategic Acquirers: Pharmaceutical conglomerates with aesthetic device holdings represent the most active acquirer in this space, seeking technology portfolio expansion beyond therapeutic drug pipelines. Long-term viability hinges on regulatory dossier depth across FDA, CE, and NMPA jurisdictions. Monitor Japan's PMDA streamlined review pathway adoption rates as an inflection signal for Western manufacturer time-to-market compression.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Investment | CE marking pathways for Class IIa devices now require post-market surveillance infrastructure that mid-tier assemblers cannot fund. |
| Multi-Technology Platform Consolidation | Integrated laser-radiofrequency-ultrasound systems compress capital deployment cycles for China's tier-one medical spa chains. |
| Subscription-Based Equipment Financing | Per-procedure fee structures bundle maintenance and software updates into predictable operating expenditures for Texas and Florida startups. |
| Picosecond Laser Technology Refresh | Mechanical photodisruption protocols displace nanosecond Q-switched systems in South Korean and Spanish dermatology chains. |
| AI-Driven Treatment Planning Integration | Real-time tissue feedback systems reduce operator skill requirements while standardizing outcomes across clinic networks. |
Research Methodology
Bottom-up dermatology clinic and medical spa equipment procurement modeling reconciled against top-down manufacturer shipment tracking forms the analytical core. Primary interviews with biomedical engineers, GPO contracts managers, clinic procurement directors, and regulatory affairs specialists combined with secondary validation from FDA 510(k) filings, NMPA registration databases, EU MDR notified body certificates, and hospital procurement records. Triangulation across these sources calibrated installed base estimates and replacement cycle assumptions.
Input-output matrices mapped technology modality penetration against application-specific procedure volumes across the projection horizon. Segmentation dimensions modeled include technology type, application focus, end-user category, and deployment format. CAGRs derived from equipment refresh cycle analysis, regulatory-driven replacement demand, and geographic expansion patterns in underpenetrated markets. Forecast inputs incorporated laser safety officer certification bottlenecks and legacy EMR integration complexity as utilization constraints.
Inputs from FDA premarket notification databases and EU MDR notified body registries were available through the study window; gaps in real-time China NMPA GB standard implementation timelines introduce uncertainty bands around domestic market authorization assumptions. Forecasts reflect documented assumptions regarding regulatory convergence trajectories and optical component supply stability. Practitioners should monitor EU MDR post-market surveillance enforcement intensity and Japan PMDA streamlined review pathway expansion for early signals of competitive barrier shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Facial Aesthetics Market
Medical Aesthetics
South Korea Hair Transplant Market
Medical Aesthetics
Injectable Anti-Wrinkle Treatment Market
Medical Aesthetics
Facial Injector Market
Medical Aesthetics
Australia Laser Hair Removal Market
Medical Aesthetics
Tattoo Removal Market
Medical Aesthetics
Photoelectric Medical Beauty Equipment Market
Medical Aesthetics
Global Medical Aesthetic Devices Market
Medical Aesthetics
France Hair Transplant Market
Medical Aesthetics
Lip Augmentation Market
Medical Aesthetics
Collagen Fillers Market
Medical Aesthetics
Gum Lift Market
Medical Aesthetics
Facial Injectables Market
Medical Aesthetics
Cosmetic Laser Market
Medical Aesthetics
Contouring Implants Market
Medical Aesthetics
Japan Hair Transplant Market