
 Skin Cancer Market | 2026-2036
Skin Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Cancer Market Outlook
CE marking under the EU Medical Device Regulation is collapsing the window for unvalidated diagnostic platforms to enter European channels. Bristol-Myers Squibb leverages its checkpoint inhibitor portfolio to anchor immuno-oncology leadership across melanoma indications. Merck & Co. competes through sustained investment in combination therapy trials that expand label opportunities beyond monotherapy settings.
Skin cancer encompasses malignant neoplasms arising from epidermal keratinocytes or melanocytes, classified histologically by cell of origin and invasive depth, with staging determined by tumor thickness, ulceration status, and nodal involvement. The condition demands precise intervention ranging from surgical excision with margin control to systemic therapy for metastatic disease. Melanoma commands premium pricing and R&D focus due to its metastatic potential and immunotherapy responsiveness, while basal cell carcinoma represents the highest procedure volume with mature surgical and topical modalities. Squamous cell carcinoma occupies an intermediate position where rising head-and-neck incidence is expanding systemic therapy demand.
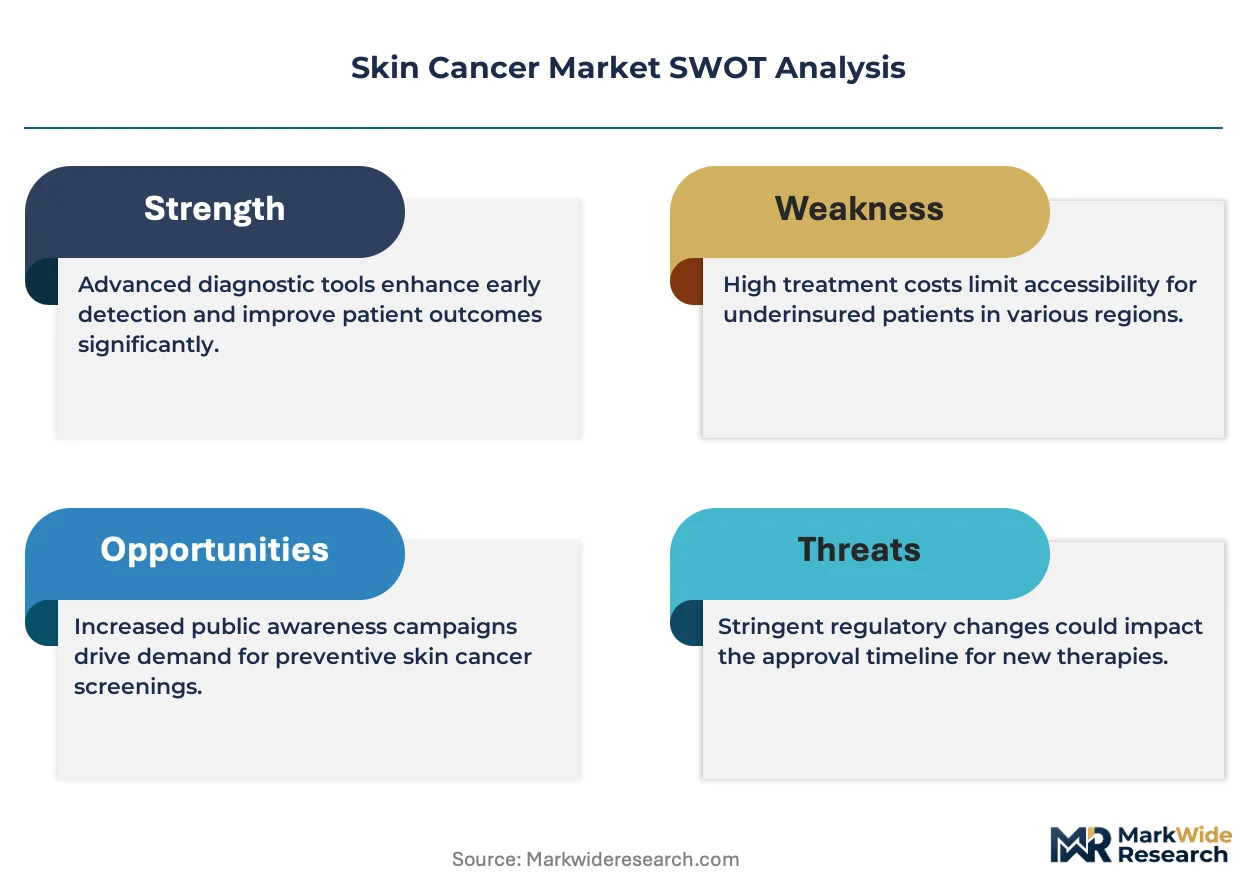
The FDA's Breakthrough Therapy designation and EMA's PRIME scheme are accelerating access pathways that reshape clinical trial investment and commercial prioritization for developers. ISO 13485 quality management requirements and evolving MDR technical documentation standards are raising barriers for diagnostic device entrants across major markets. Stakeholders must monitor how real-world evidence mandates from FDA and EMA reshape post-market study obligations and label expansion economics.
Market Dynamics
Checkpoint inhibitor portfolio expansions are compressing development timelines for melanoma therapeutics while FDA accelerated approval pathways reward biomarker-driven trial designs with earlier commercial entry.
Growth Catalysts
- Immunotherapy responsiveness in melanoma:Tumor-infiltrating lymphocyte biology enables durable responses that sustain pricing power and label expansion investments.
- FDA Breakthrough Therapy designation:Compressed review timelines reward developers prioritizing biomarker-enriched populations with earlier market access.
- Dermatology clinic consolidation:Integrated cancer networks in the United States standardize diagnostic protocols and concentrate procurement volume.
Market Restraints
- Biomarker testing infrastructure gaps:PD-L1 and BRAF mutation assay penetration remains uneven outside major metropolitan academic centers.
- CE marking compliance burden:EU MDR technical documentation requirements and notified body capacity constraints delay European diagnostic platform launches.
- Surgical modality maturity in basal cell carcinoma:Established excision and Mohs surgery techniques limit systemic therapy penetration in the highest-volume indication.
Strategic Opportunities
- Neoadjuvant immunotherapy expansion:Pre-surgical checkpoint blockade in resectable melanoma creates new treatment phases and combination trial opportunities.
- Real-world evidence mandates:FDA and EMA post-market study requirements reward developers with robust pharmacovigilance infrastructure for label expansion economics.
- Artificial intelligence-enabled dermoscopy:Algorithmic lesion classification tools integrate into teledermatology workflows for rural and underserved access points.
Industry Challenges
- Immuno-oncology talent scarcity:Translational medicine and biomarker strategy expertise concentrates at established biopharma clusters.
- Legacy pathology workflow integration:Digital pathology and computational diagnostic platforms require capital-intensive infrastructure retrofitting.
- Combination therapy IP complexity:Checkpoint inhibitor backbone patents and companion diagnostic exclusivity create licensing negotiation friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Cancer Market |
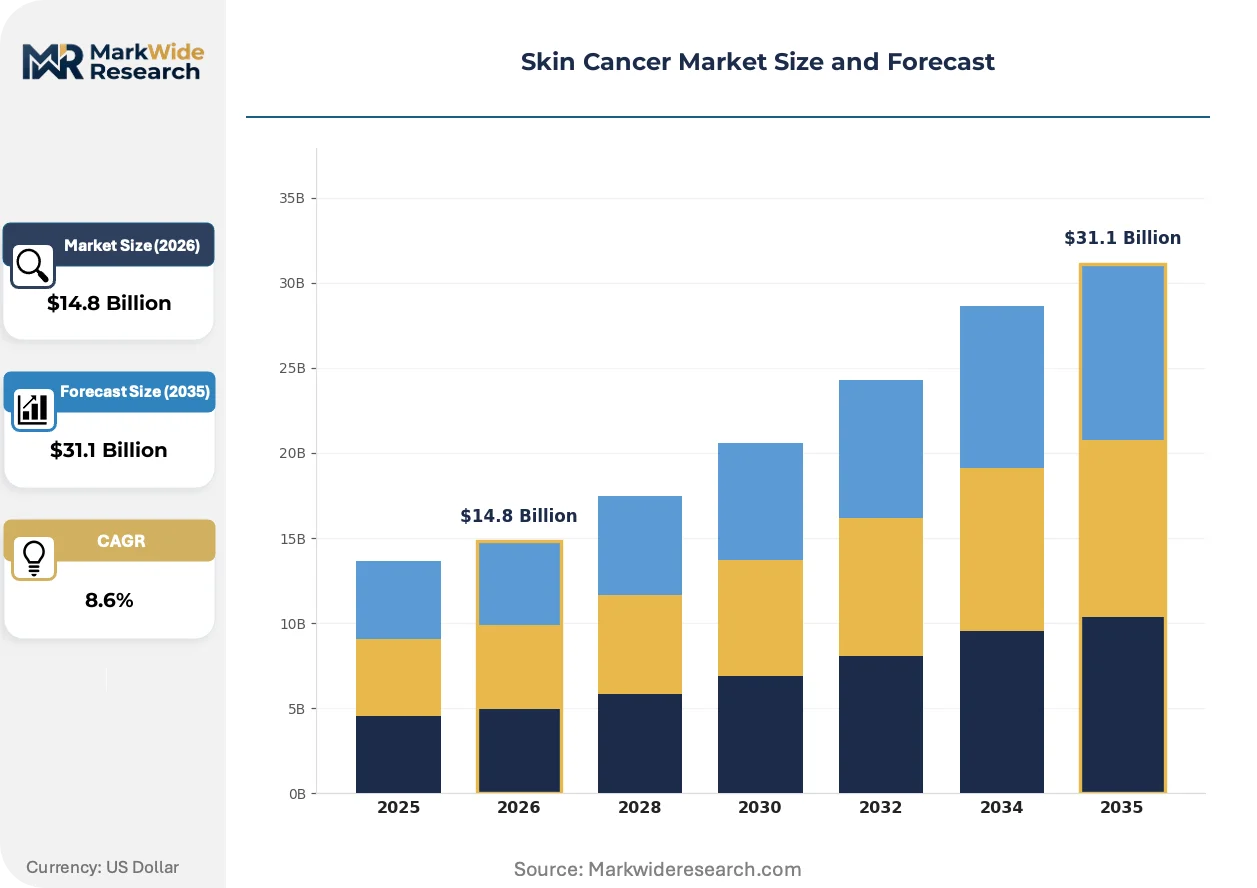
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Surgery, Immunotherapy, Chemotherapy, Radiation Therapy Product Type: Melanoma, Basal Cell Carcinoma, Squamous Cell Carcinoma, Others End User: Hospitals, Clinics, Research Laboratories, Home Care Delivery Mode: Topical, Oral, Injectable, Systemic |
| Companies Covered | Merck & Co., Bristol-Myers Squibb, F. Hoffmann-La Roche, Novartis AG, Amgen Inc., Pfizer Inc., AstraZeneca, Sun Pharmaceutical Industries, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Cancer Market Strategic Shifts
Therapeutic development is bifurcating between precision immunotherapy combinations and non-invasive diagnostic automation, with regulatory pathways rewarding biomarker-enriched trial designs.
Liquid biopsy circulating tumor DNA detection is decomposing the diagnostic timeline for metastatic melanoma monitoring. Academic medical centers and integrated cancer networks are adopting plasma-based BRAF mutation tracking to complement tissue sequencing. This molecular monitoring modality is decomposing the traditional imaging-based recurrence surveillance paradigm and enabling earlier therapeutic intervention decisions.
EMA's PRIME scheme accelerates access pathways for medicines addressing unmet melanoma needs through enhanced regulatory dialogue and accelerated assessment. The scheme compresses development timelines for developers willing to commit to conditional marketing authorization frameworks. European developers are responding by prioritizing biomarker-driven trial designs that satisfy PRIME eligibility criteria.
Pathology procurement is consolidating around integrated diagnostic platforms that bundle molecular testing with traditional histopathology. Hospital systems and cancer networks are unbundling standalone laboratory relationships in favor of vendor-agnostic digital workflow solutions. This vendor consolidation pattern is most visible in United States integrated delivery networks pursuing enterprise-scale laboratory standardization.
Skin Cancer Market Segmentation
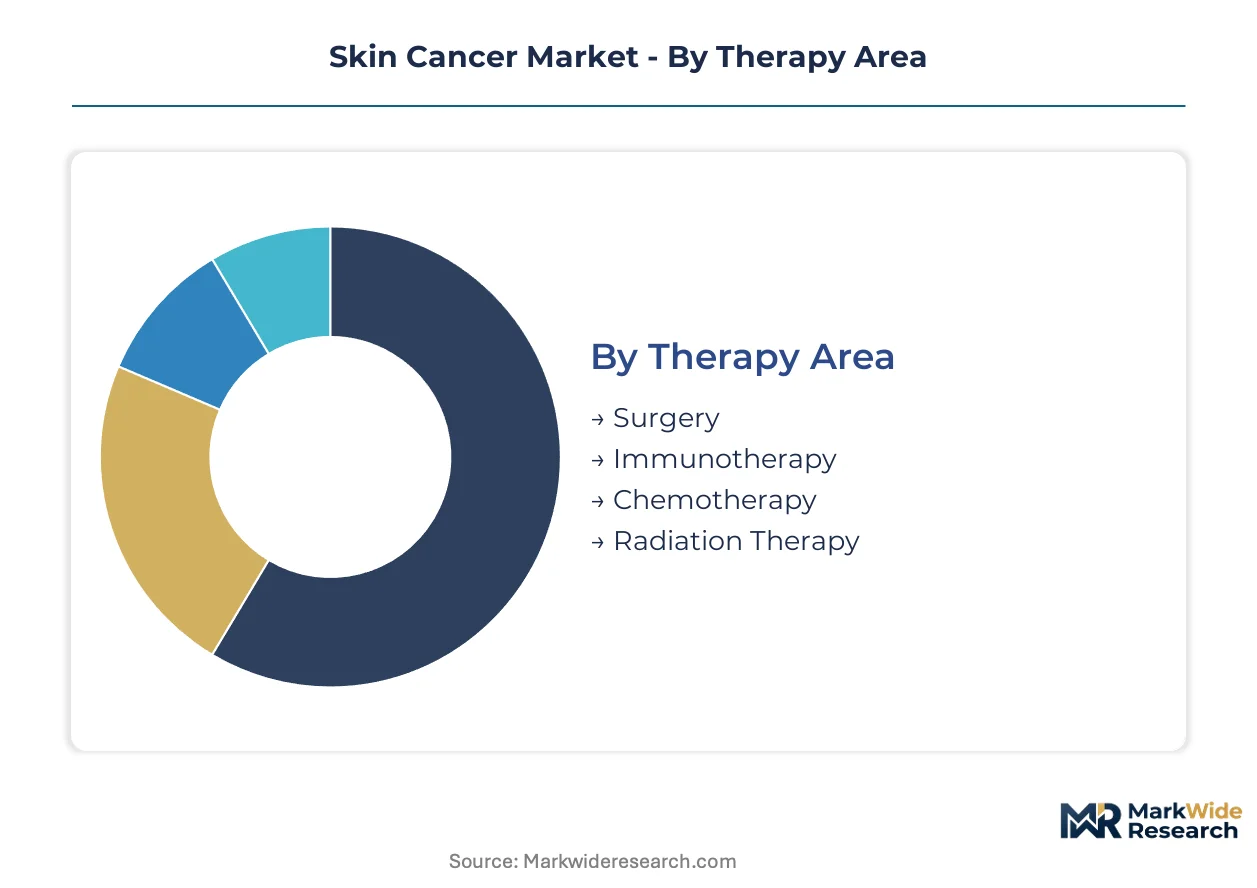
Segmentation in skin cancer therapeutics reveals how treatment modality, disease histology, and care setting interact to determine commercial access points. Understanding these dimensions exposes where pricing power concentrates and where commoditization pressures erode margins.
Therapy Area:
Surgical modalities face intensifying substitution pressure from systemic agents in resectable melanoma, while immunotherapy's efficacy gains threaten radiation's role in adjuvant settings.
- Surgery:Mohs micrographic surgery and wide local excision remain the foundation for basal cell and squamous cell carcinoma, with margin control techniques determining recurrence rates. Demand concentrates in United States dermatology clinics where integrated cancer networks standardize excision protocols and procurement volume.
- Immunotherapy:Checkpoint inhibitors targeting PD-1 and CTLA-4 pathways deliver durable responses in metastatic melanoma through tumor-infiltrating lymphocyte activation. United States academic medical centers drive adoption of neoadjuvant pembrolizumab and nivolumab combinations, compressing development timelines via FDA Breakthrough Therapy pathways.
- Chemotherapy:Dacarbazine and temozolomide regimens persist as salvage options for immunotherapy-refractory cases, though utilization is declining.
- Radiation Therapy:Adjuvant radiotherapy maintains role in nodal basin treatment for high-risk squamous cell carcinoma following surgery.
Surgery anchors the volume base while immunotherapy gains share at the steepest rate.
Product Type:
Cost tier stratification separates premium-priced metastatic melanoma therapeutics from commoditized basal cell carcinoma procedures where surgical margins dominate economics.
- Melanoma:Cutaneous malignancy arising from melanocytes with staging driven by Breslow thickness and ulceration status. United States integrated cancer networks concentrate demand for BRAF/MEK combination therapy and checkpoint inhibitor regimens, with FDA accelerated approval pathways rewarding biomarker-enriched trial designs.
- Basal Cell Carcinoma:Most common human malignancy with mature surgical and topical treatment paradigms limiting systemic penetration. High procedural volume in United States dermatology clinics sustains Mohs surgery and imiquimod cream utilization despite hedgehog pathway inhibitor availability for locally advanced cases.
- Squamous Cell Carcinoma:Keratinocyte-derived malignancy with rising head-and-neck incidence expanding systemic therapy demand.
- Others:Merkel cell carcinoma and cutaneous lymphomas represent orphan indications with concentrated specialist treatment.
Basal cell carcinoma generates the highest procedure count while melanoma commands the steepest pricing escalation.
End User:
Customer type fragmentation creates divergent procurement patterns between capital-intensive hospital systems and distributed clinic networks.
- Hospitals:Academic medical centers and integrated cancer networks concentrate complex melanoma staging, sentinel lymph node biopsy, and systemic therapy administration. United States hospital systems pursue enterprise-scale laboratory standardization, unbundling standalone pathology relationships in favor of vendor-agnostic digital workflow solutions.
- Clinics:Dermatology and surgical oncology clinics perform the majority of skin cancer excisions and superficial therapies. United States clinic consolidation is standardizing diagnostic protocols and concentrating procurement volume for Mohs surgery equipment and topical agents.
- Research Laboratories:Academic and commercial laboratories develop circulating tumor DNA assays and BRAF mutation tracking platforms.
- Home Care:Topical imiquimod and 5-fluorouracil applications for superficial basal cell carcinoma enable outpatient treatment completion.
Clinics anchor the volume base while hospitals capture the steepest therapy revenue per patient.
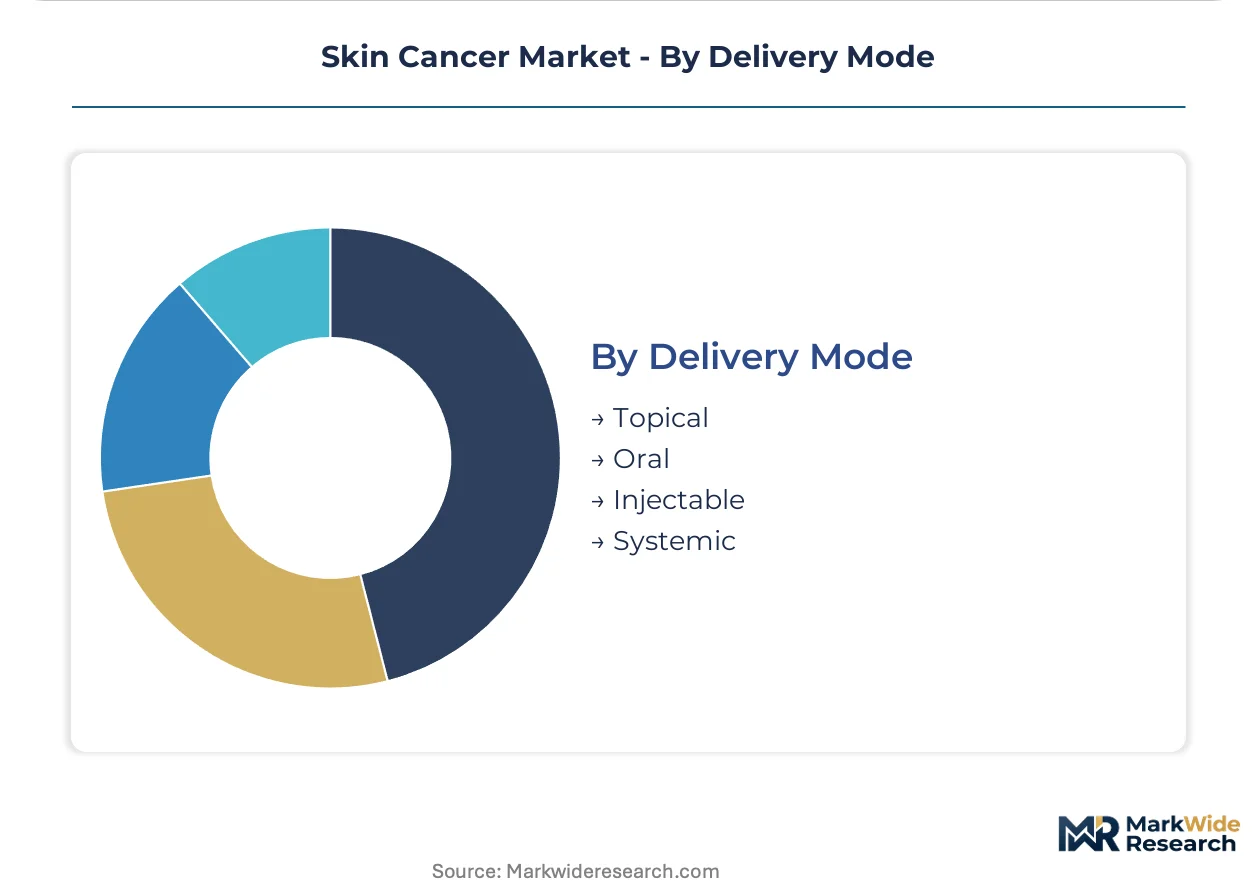
Delivery Mode:
Application route determines regulatory pathway complexity and manufacturing margin structure across the segment matrix.
- Injectable:Intravenous checkpoint inhibitors and subcutaneous interferon formulations require cold chain infrastructure and infusion center capacity. United States oncology clinics concentrate demand for pembrolizumab and nivolumab administration, with FDA Breakthrough Therapy designation compressing review timelines for biomarker-driven indications.
- Systemic:Oral BRAF and MEK inhibitors enable outpatient metastatic melanoma management with companion diagnostic requirements. United States integrated cancer networks drive encorafenib and binimetinib adoption through molecular tumor board protocols.
- Topical:Imiquimod, 5-fluorouracil, and photodynamic therapy agents address superficial lesions with limited invasive potential.
- Oral:Hedgehog pathway inhibitors vismodegib and sonidegib serve locally advanced basal cell carcinoma refractory to surgery.
Injectable modalities anchor the revenue base while systemic oral regimens are climbing the fastest as adjuvant indications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Breakthrough Therapy designation and EMA's PRIME scheme are compressing development timelines for developers willing to commit to biomarker-enriched trial designs. Reimbursement alignment across integrated cancer networks concentrates demand in markets with mature pathology infrastructure and consolidated procurement. Geographic variation in biomarker testing penetration and regulatory pathway efficiency determines commercial access sequencing.
United States
Integrated cancer networks in the United States standardize diagnostic protocols and concentrate procurement volume for checkpoint inhibitor regimens. FDA accelerated approval pathways reward developers prioritizing PD-L1 and BRAF mutation-enriched populations with earlier market access. Academic medical centers in Boston and the New York Metro area drive adoption of neoadjuvant pembrolizumab combinations.
Germany
CE marking under the EU Medical Device Regulation is collapsing the window for unvalidated diagnostic platforms to enter German channels. EMA's PRIME scheme accelerates access pathways for medicines addressing unmet melanoma needs through enhanced regulatory dialogue. Hospital systems in Bavaria and North Rhine-Westphalia pursue enterprise-scale laboratory standardization.
Japan
PMDA consultation frameworks enable earlier regulatory dialogue for developers targeting melanoma indications with biomarker-driven designs. METI industrial policy supports domestic pharmaceutical manufacturing capacity for oncology therapeutics. Tokyo and Osaka academic medical centers concentrate demand for BRAF/MEK combination therapy adoption.
United Kingdom
NICE technology appraisal processes determine reimbursement access for systemic melanoma therapies across NHS England. MHRA post-Brexit regulatory autonomy enables accelerated assessment pathways for innovative oncology medicines. London and Manchester integrated cancer networks drive protocol standardization and molecular tumor board adoption.
Australia
TGA priority review pathways compress evaluation timelines for breakthrough melanoma therapeutics addressing unmet clinical need. PBS listing negotiations determine patient access to premium-priced immunotherapy regimens. Sydney and Melbourne academic centers lead adoption of liquid biopsy circulating tumor DNA monitoring for metastatic disease surveillance.
Skin Cancer Market Competitive Environment
Listed leaders compete with private specialists across checkpoint inhibitor development and diagnostic platform commercialization. The vendor base concentrates around immuno-oncology portfolios and companion diagnostic ecosystems, with tiered competitive dynamics separating premium biologics from commoditized surgical modalities. Three archetypes dominate: integrated pharmaceutical conglomerates with oncology franchises, biotechnology specialists with single-asset or platform focus, and diagnostic device manufacturers with digital pathology capabilities. M&A activity targets biomarker strategy expertise and real-world evidence infrastructure, while strategic partnerships address combination therapy IP complexity.
Within the integrated pharmaceutical tier, Merck & Co. and Bristol-Myers Squibb occupy positions as checkpoint inhibitor portfolio anchors across melanoma indications. F. Hoffmann-La Roche represents the diagnostic-therapeutic convergence archetype with integrated pathology and oncology assets. These three companies exemplify how regulatory pathway expertise and biomarker-driven trial design capabilities concentrate competitive advantage in premium therapeutic segments.
| Leading Market Players |
|---|
| Merck & Co. |
| Bristol-Myers Squibb |
| F. Hoffmann-La Roche |
| Novartis AG |
| Amgen Inc. |
| Pfizer Inc. |
| AstraZeneca |
| Sun Pharmaceutical Industries |
| Abbott Laboratories |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles for checkpoint inhibitor biologics concentrate working capital demands at United States oncology infusion centers, compressing margins for distributors while reinforcing pricing power at portfolio-anchored manufacturers with cold chain captive networks.
Pricing Analysis
Certification level (FDA Breakthrough Therapy versus standard approval) creates the primary spread between premium checkpoint inhibitor regimens and commoditized basal cell carcinoma procedures. Three-tier pricing structure across premium immunotherapy, standard surgical modalities, and economy topical agents reflects biomarker-enriched trial investment and reimbursement alignment. Cost compression in basal cell carcinoma surgical tiers is intensifying because Mohs surgery equipment vendors face procurement consolidation at United States dermatology clinic networks. Academic medical centers exhibit lowest price sensitivity due to formulary control and molecular tumor board protocols, while independent clinics face steepest pressure from GPO contract standardization.
Supply Chain Analysis
Trans-Pacific container availability fluctuations from Shanghai to Long Beach elevate inbound logistics costs for diagnostic platform components manufactured in China, Japan, and South Korea. Active pharmaceutical ingredient production for BRAF/MEK inhibitors draws from Switzerland, Ireland, and Singapore, with fill-finish capacity concentrated in United States and German contract manufacturing sites. Single-source vulnerability in PD-1 antibody cell line supply creates exposure at Bristol-Myers Squibb and Merck & Co. manufacturing networks. Distribution runs through specialty pharmacy channels for injectable immunotherapies and direct-to-clinic logistics for Mohs surgery equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment via FDA Breakthrough Therapy designation and companion diagnostic exclusivity constructs defensive moats that concentrate returns at established checkpoint inhibitor developers with biomarker strategy infrastructure.
For Market Incumbents: Consolidate pathology procurement relationships through enterprise-scale laboratory standardization at United States integrated cancer networks, locking out standalone diagnostic vendors. Deepen backward integration into circulating tumor DNA assay development to capture molecular monitoring revenue streams. Threat substitution from artificial intelligence-enabled dermoscopy platforms demands preemptive acquisition of algorithmic classification capabilities. For New Entrants and Emerging Players: FDA Breakthrough Therapy designation fast-tracks compress development timelines for biomarker-driven melanoma indications, enabling earlier commercial entry against entrenched PD-1 portfolios. Target neoadjuvant immunotherapy expansion in resectable melanoma as the most penetrable treatment phase with undefined combination standards. Go-to-market angle centers on real-world evidence infrastructure investment to satisfy post-market study mandates from FDA and EMA. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates divesting non-core dermatology assets amid oncology portfolio prioritization. Long-term viability frames toward immuno-oncology platform consolidation over the coming decade as combination therapy IP complexity rewards integrated players. Acquisition target archetype: biotechnology specialists with single-asset checkpoint inhibitor candidates and biomarker strategy expertise. Signal to watch: EMA PRIME scheme adoption rates as inflection indicator for European commercial access efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Neoadjuvant pembrolizumab combinations in resectable melanoma expand addressable patient populations. |
| Regulatory Approval Pathway | FDA Breakthrough Therapy designation compresses review timelines for biomarker-enriched trial designs. |
| Licensing Agreement | Companion diagnostic exclusivity partnerships secure PD-L1 assay anchoring at academic medical centers. |
| Manufacturing Scale-Up | Cold chain capacity expansion supports checkpoint inhibitor volume concentration at United States oncology clinics. |
| Pipeline Diversification | Liquid biopsy circulating tumor DNA platforms decompose traditional imaging-based recurrence surveillance. |
Study Parameters
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions. Primary interviews across these stakeholder roles combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation anchored the analytical framework.
Segmentation dimensions modeled include treatment line, administration route, histology type, and regional regulatory cluster across the projection horizon. CAGRs derived from therapeutic adoption curves, pricing trajectory assumptions, and biomarker testing penetration rates. Forecast inputs incorporated FDA accelerated approval pathway utilization and EMA PRIME scheme eligibility trends.
Decision-makers should treat outputs as directional under assumptions of sustained immunotherapy responsiveness in melanoma and stable reimbursement alignment; material deviation in biomarker testing infrastructure buildout or regulatory pathway efficiency would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Acne Scar Treatment Market
Dermatology
US and Canada Skin Cancer Dermatology Market
Dermatology
Pigmented Lesion Treatment Market
Dermatology
Global Dermatological Therapeutics Market
Dermatology
Keratoacanthoma Market
Dermatology
Skin Excision Market
Dermatology
Skin Hyperpigmentation Treatment Market
Dermatology
Hyperpigmentation Treatment Market
Dermatology
Folliculitis Market
Dermatology
Japan Scar Treatment Market
Dermatology
Telogen Effluvium Treatment Market
Dermatology
Scar Treatment Market
Dermatology
Seborrheic Dermatitis Treatment Market
Dermatology
Dermal Facial Fillers Market
Dermatology
Hyperpigmentation Disorder Treatment Market
Dermatology
Darier Disease Drugs Market