
 Scar Treatment Oils Market | 2026-2036
Scar Treatment Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Scar Treatment Oils Market Insights
The EU Green Deal is rebalancing ingredient sourcing priorities across European cosmetic-dermatology supply chains. Bio-Oil leverages extensive retail pharmacy networks to sustain brand visibility in over 135 countries. Smith & Nephew anchors its position through clinical-grade silicone oil formulations backed by hospital procurement contracts. Molnlycke Health Care dominates advanced wound care channels with scar management products integrated into post-operative protocol bundles.
Scar treatment oils comprise topical formulations designed to improve scar appearance through hydration, collagen modulation, and anti-inflammatory action, typically containing silicone polymers, botanical extracts, or essential fatty acids at concentrations between 5% and 20% active ingredients. Silicone oils lead product type segments due to established clinical evidence in hypertrophic scar reduction, while essential oils represent the fastest-growing category as consumers seek preservative-free alternatives. Application demand concentrates in post-surgery care where hospital discharge protocols increasingly include scar management kits, though acne scar treatment generates premium pricing through dermatology center channels.
FDA cosmetic-dermatology boundary regulations and EU REACH restrictions on synthetic additives jointly determine permissible ingredient lists and label claims across major markets. BIS standards in India and China's NMPA cosmetic registration requirements create additional compliance layers for multinational manufacturers. Stakeholders must monitor evolving classification thresholds that could reclassify certain scar oils as medical devices in Europe under the MDR framework.
Market Dynamics
The EU Green Deal and FDA cosmetic-dermatology boundary guidance are jointly compressing formulation freedom while redirecting R&D spend toward bio-based silicone alternatives and preservative-free botanical systems.
Growth Catalysts
- Post-surgical protocol bundles:Hospital discharge kits in the United States now incorporate scar management oils as standard, creating institutional demand pull through procurement contracts.
- REACH synthetic additive restrictions:ECHA enforcement is accelerating reformulation toward plant-derived actives, opening premium positioning for compliant European manufacturers.
- Essential oil extraction advances:Supercritical CO2 methods are improving botanical potency consistency, enabling therapeutic-grade claims previously reserved for pharmaceutical channels.
Market Restraints
- Silicone feedstock concentration:Specialty silicone oil production clusters in Germany and China, exposing formulators to geopolitical supply disruption and freight cost volatility.
- MDR reclassification risk:EU Medical Device Regulation thresholds could shift scar oils with clinical claims into device compliance, extending approval timelines by 18-24 months.
- Topical steroid substitution:Dermatology practices in India and Brazil still favor corticosteroid injections for hypertrophic scars, limiting oil-based product penetration.
Strategic Opportunities
- China's tier-two city expansion:NMPA cosmetic registration simplification is unlocking pharmacy channel access in Chengdu, Wuhan, and Xi'an beyond saturated Shanghai-Beijing corridors.
- At-home microneedling convergence:Consumer dermaroller adoption is creating bundled demand for pre- and post-treatment oils, merging professional and retail market boundaries.
- India PLI scheme alignment:Domestic manufacturing incentives for active pharmaceutical ingredients extend to botanical extraction facilities, reducing import dependency for sandalwood and turmeric oils.
Industry Challenges
- Cosmetovigilance reporting systems:EU Responsible Person obligations for adverse event tracking require specialized pharmacovigilance staffing that mid-tier brands struggle to resource.
- Stability testing protocols:Oxidation-sensitive essential oil formulations demand accelerated aging studies under ICH guidelines, compressing product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scar Treatment Oils Market |
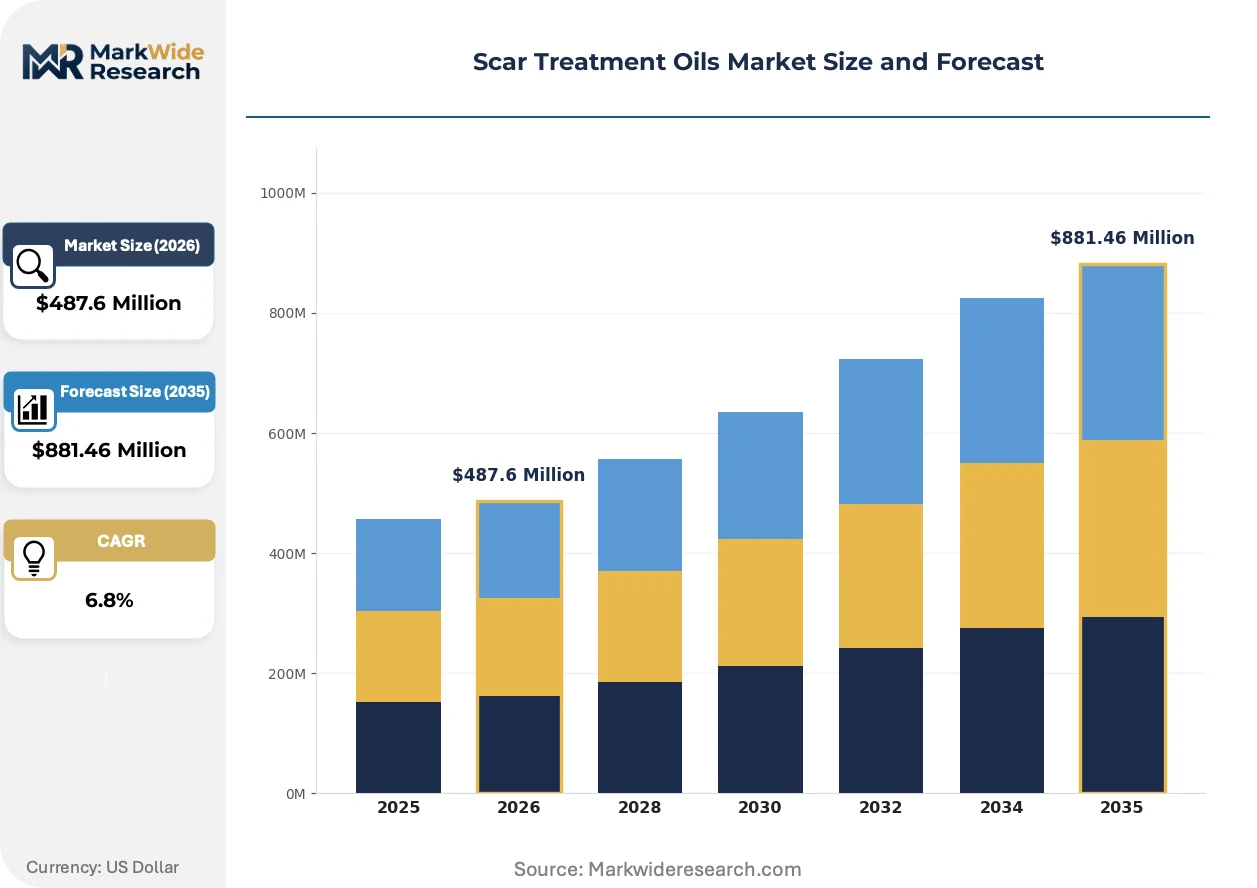
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Oils, Essential Oils, Herbal Oils, Emollient Oils Application: Post-Surgery Care, Acne Scar Treatment, Stretch Mark Prevention, Wound Healing End User: Clinics, Dermatology Centers, Home Care, Pharmacies Distribution Channel: Online Retail, Brick-and-Mortar, Direct Sales, Medical Supply Stores |
| Companies Covered | Perrigo Company, Smith & Nephew, Alliance Pharma, Rejuvaskin, HRA Pharma, Molnlycke Health Care, Sonoma Pharmaceuticals, Bio-Oil, Pacific World Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scar Treatment Oils Market Trends and Innovations
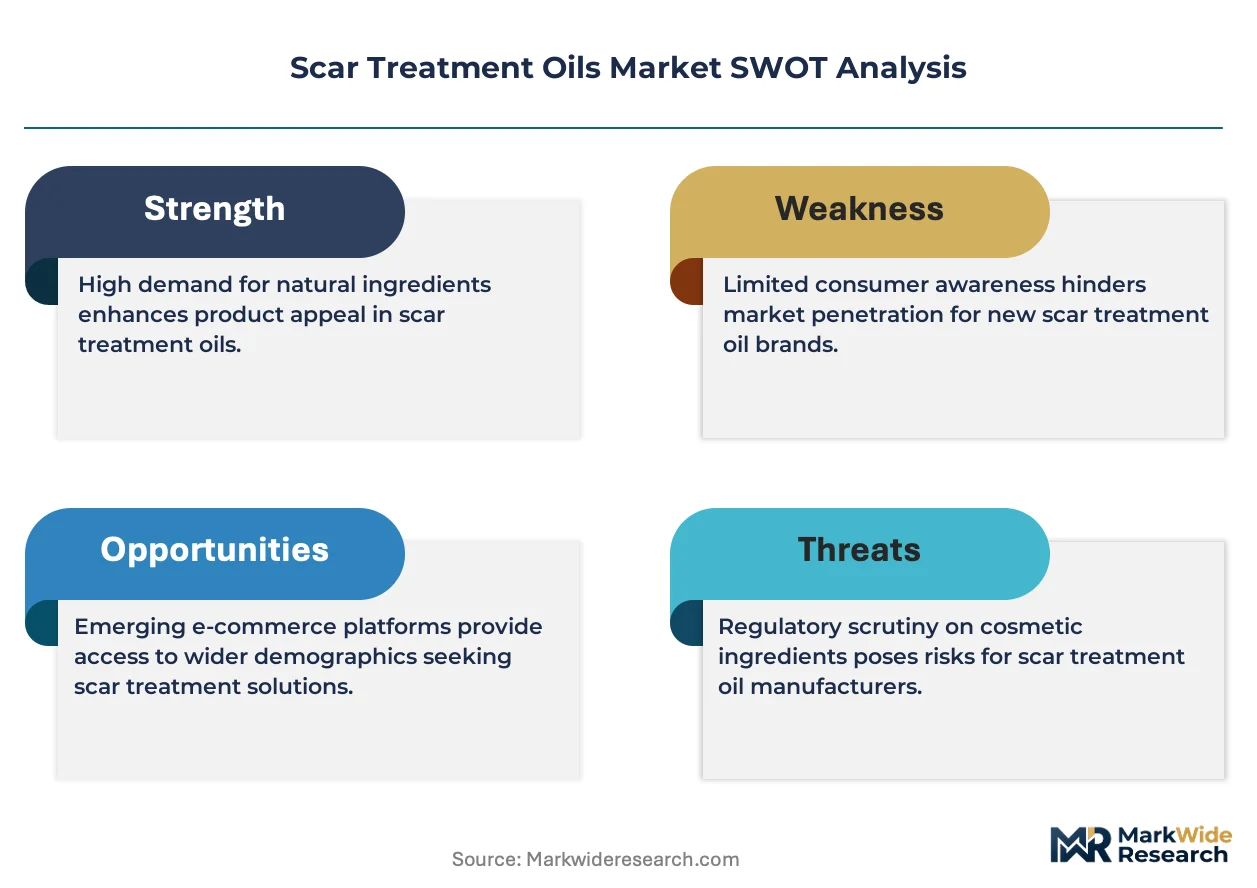
Formulation science and regulatory classification boundaries are converging to redefine competitive advantage, with automation, compliance architecture, and channel restructuring as the dominant vectors of change.
Encapsulation technology using lipid nanoparticles is automating controlled-release delivery of silicone and botanical actives. Dermatology centers in Germany and South Korea are adopting these systems for post-laser scar protocols. The technology is automating patient compliance monitoring through paired mobile applications that track application frequency and photograph scar progression.
EU MDR transitional provisions are forcing cosmetic-dermatology manufacturers to revalidate clinical evidence packages for products near the medical device threshold. Formulators with existing CE-marked wound care portfolios are absorbing compliance costs across product lines. Hospital procurement teams in France and Italy are now requiring MDR-compliant documentation for scar oils included in surgical recovery kits.
Direct-to-consumer subscription models are displacing traditional pharmacy replenishment for acne scar treatment oils. Millennial and Gen-Z buyers in the United States and United Kingdom are prioritizing tele-dermatology consultations bundled with personalized oil regimens. This channel rotation is most pronounced among post-inflammatory hyperpigmentation consumers who previously relied on Sephora or Boots counter recommendations.
Scar Treatment Oils Market Segmentation
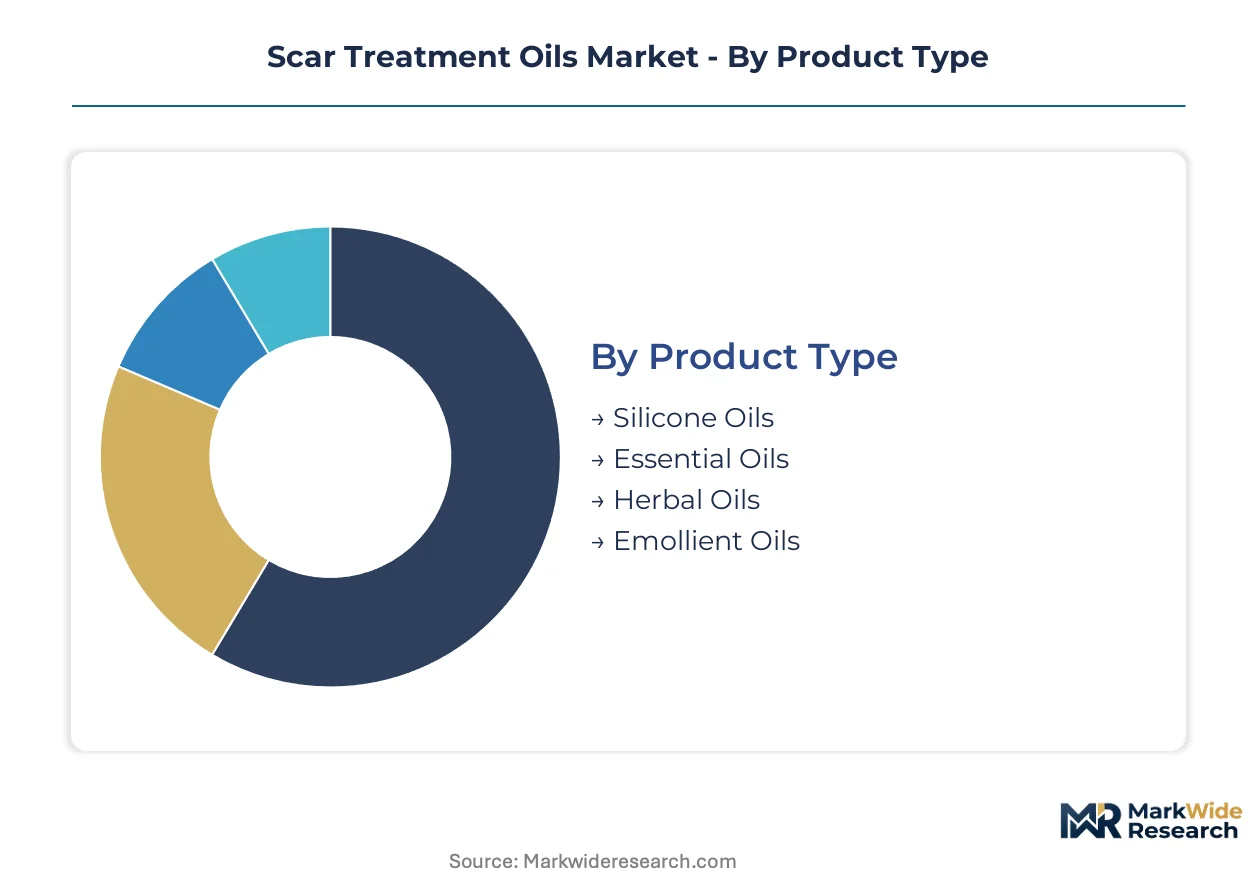
Scar treatment oils fragment across four intersecting dimensions that determine pricing power, channel access, and regulatory burden. Product chemistry dictates clinical credibility. Application context shapes reimbursement pathways. End-user setting controls volume throughput. Distribution method governs margin capture and brand control.
Product Type:
Silicone oils command institutional volume through hospital procurement contracts, while essential oils capture premium shelf space in clean beauty channels.
- Silicone Oils:Medical-grade polydimethylsiloxane formulations at 5-20% concentration deliver occlusive hydration and collagen modulation backed by decades of clinical evidence. Demand concentrates in post-surgical discharge kits across United States hospital systems where procurement teams require FDA-cleared documentation. Silicone feedstock dependence on German and Chinese specialty chemical producers exposes formulators to freight volatility.
- Essential Oils:Supercritical CO2-extracted botanical actives including rosehip, helichrysum, and frankincense offer preservative-free positioning for clean-label consumers. Dermatology centers in South Korea and Germany are integrating these into post-laser protocols. ECHA REACH enforcement on synthetic additives is accelerating European formulator migration toward this category.
- Herbal Oils:Traditional ayurvedic and TCM formulations leveraging turmeric, sandalwood, and gotu kola extracts target ethnic beauty segments and wellness-oriented consumers.
- Emollient Oils:Mineral oil and petrolatum-based carriers provide cost-accessible entry points in emerging markets where price sensitivity dominates purchasing decisions.
Today's leader: Silicone Oils. Tomorrow's challenger: Essential Oils.
Application:
Post-surgical protocols generate predictable institutional volume, whereas acne scar treatment commands the steepest consumer willingness-to-pay.
- Post-Surgery Care:Hospital discharge bundles in the United States now standardize scar management oils, creating contracted demand pull through group purchasing organizations. MDR-compliant documentation requirements in France and Italy are raising barriers for non-European suppliers.
- Acne Scar Treatment:Post-inflammatory hyperpigmentation consumers in the United States and United Kingdom are migrating from Sephora and Boots counters toward tele-dermatology subscription models. This segment is climbing the fastest as millennial and Gen-Z buyers prioritize personalized regimens over mass-market recommendations.
- Stretch Mark Prevention:Maternal wellness positioning targets pregnancy-planning consumers through pharmacy and direct-to-consumer channels with lower clinical validation requirements.
- Wound Healing:Advanced wound care integration with negative pressure therapy and hydrogel systems positions oils as adjunctive rather than primary interventions.
Institutional volume anchors Post-Surgery Care. Premium expansion favors Acne Scar Treatment.
End User:
Clinical settings validate efficacy claims that home care channels monetize through convenience positioning.
- Clinics:Outpatient surgical centers and aesthetic practices drive silicone oil adoption through procedure bundling and recovery kit inclusion.
- Dermatology Centers:Board-certified practices in Germany and South Korea prescribe encapsulated lipid nanoparticle formulations for post-laser protocols with compliance monitoring via paired mobile applications.
- Home Care:At-home microneedling convergence is creating bundled demand for pre- and post-treatment oils, dissolving boundaries between professional and retail markets.
- Pharmacies:Retail pharmacy networks sustain mass-market visibility, though shelf space competition from private-label alternatives is compressing branded margins.
Professional credibility flows through Clinics. Volume scale concentrates in Home Care.
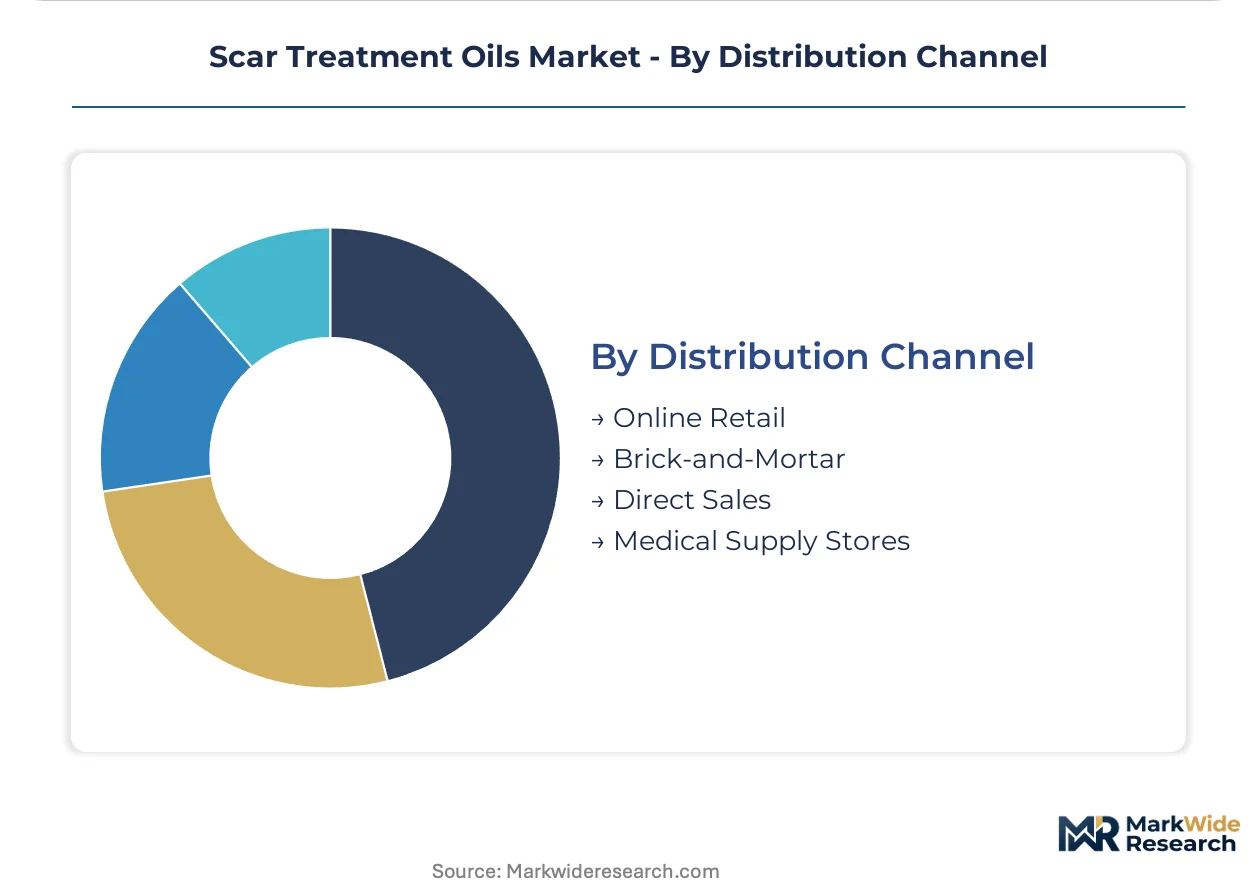
Distribution Channel:
Channel selection determines margin capture, with direct models preserving pricing power at the cost of customer acquisition investment.
- Online Retail:Amazon and Tmall dominance in the United States and China enables rapid scaling but subjects brands to algorithmic visibility volatility and counterfeit exposure.
- Brick-and-Mortar:Sephora, Boots, and Watsons counter presence sustains trial generation and sensory evaluation opportunities for essential oil formulations.
- Direct Sales:Tele-dermatology subscription bundling captures recurring revenue with higher lifetime value but requires specialized compliance infrastructure for cosmetovigilance reporting.
- Medical Supply Stores:Hospital procurement adjacent channels serve institutional customers with contracted pricing and volume guarantees.
Scale accrues to Online Retail. Margin defense favors Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scar treatment oils originated in European pharmaceutical laboratories during the 1980s, with silicone-based formulations first gaining clinical validation in German wound care centers before spreading to North American hospital systems and Asian cosmetic-dermatology markets.
United States
Hospital discharge protocols now standardize scar management oils in post-surgical recovery kits, creating institutional demand pull through group purchasing organizations. FDA cosmetic-dermatology boundary guidance continues reshaping permissible ingredient claims and label classifications. Procurement concentration in the Cleveland Clinic and Mayo Clinic networks validates clinical-grade formulations for nationwide distribution.
Germany
Specialty silicone feedstock production clusters in Leverkusen and Ludwigshafen supply global formulators with medical-grade polydimethylsiloxane. ECHA REACH enforcement on synthetic additives accelerates migration toward botanical extraction methods. Heidelberg and Berlin dermatology centers pioneer encapsulated lipid nanoparticle protocols for post-laser scar management.
China
NMPA cosmetic registration simplification unlocks pharmacy channel access in Chengdu, Wuhan, and Xi'an beyond saturated Shanghai-Beijing corridors. Domestic manufacturing incentives under the dual carbon goals extend to botanical extraction facilities for sandalwood and turmeric oils. Guangdong and Zhejiang provinces concentrate clean beauty formulators targeting millennial consumers through Tmall flagship stores.
India
PLI scheme alignment for active pharmaceutical ingredients now covers botanical extraction facilities, reducing import dependency for traditional ayurvedic actives. BIS standards create compliance layers for multinational manufacturers entering organized retail. Maharashtra and Karnataka host the majority of contract manufacturers serving both domestic pharmacies and export markets.
South Korea
MFDS regulatory frameworks support advanced dermocosmetic positioning for scar oils integrated into post-aesthetic procedure protocols. Seoul dermatology centers adopt mobile application pairing for patient compliance monitoring. Busan-Ulsan industrial corridors concentrate supercritical CO2 extraction capacity serving regional clean beauty brands.
Scar Treatment Oils Market Competitive Landscape
Capital-heavy specialty chemical producers compete with asset-light brand marketers for margin capture across institutional and retail channels. The vendor base organizes into three tiers: multinational pharmaceutical-dermatology conglomerates with hospital procurement contracts, mid-scale clean beauty specialists with direct-to-consumer infrastructure, and regional ayurvedic-TCM formulators serving ethnic wellness segments. Consolidation pressure concentrates among silicone feedstock suppliers, while brand fragmentation proliferates in essential oil categories. Dominant competitive moves include M&A absorption of compliant European manufacturers and strategic partnerships between tele-dermatology platforms and personalized regimen providers.
Among pharmaceutical-dermatology conglomerates, Smith & Nephew and Molnlycke Health Care occupy positions anchored by hospital procurement relationships and post-operative protocol integration. Bio-Oil exemplifies the brand-marketer archetype with extensive retail pharmacy network penetration across multiple continents. These three entities represent distinct strategic postures: clinical-grade institutional supply, advanced wound care channel dominance, and mass-market visibility through sensory marketing and distribution scale.
| Leading Market Players |
|---|
| Perrigo Company |
| Smith & Nephew |
| Alliance Pharma |
| Rejuvaskin |
| HRA Pharma |
| Molnlycke Health Care |
| Sonoma Pharmaceuticals |
| Bio-Oil |
| Pacific World Corporation |
| Others |
Pricing and Supply Chain Analysis
EU REACH synthetic additive restrictions gate qualified supply for silicone oil formulators while simultaneously filtering premium-tier pricing access toward botanical extraction specialists with compliant documentation. Hospital procurement teams in the United States and France now require REACH-aligned ingredient disclosure as a prerequisite for contract consideration, compressing margins for non-compliant manufacturers and elevating price floors for certified alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates encapsulated lipid nanoparticle formulations from conventional silicone oils and mineral-based emollient carriers. Price differentiation rests on clinical-grade certification tiers and supercritical CO2 extraction provenance. Cost compression in the economy tier is intensifying because Indian and Brazilian contract manufacturers are scaling petrolatum-based alternatives. Home care consumers exhibit highest price sensitivity, while dermatology center procurement demonstrates willingness-to-pay premiums for MDR-aligned documentation.
Supply Chain Analysis
Single-source vulnerability sits with German and Chinese specialty chemical producers controlling medical-grade polydimethylsiloxane feedstock. Raw material dependencies center on silicone polymers, rosehip and helichrysum botanical extracts, and sandalwood oil from Indian extraction facilities. Tariff exposure on Chinese silicone imports is forcing European formulators toward domestic botanical sourcing. Distribution runs through hospital procurement networks for institutional volume and Tmall-Amazon platforms for direct-to-consumer subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scar treatment oils constitute a late-cycle quality story as millennial and Gen-Z consumers migrate from mass-market pharmacy counters toward tele-dermatology subscription bundles with personalized regimen specifications.
For Market Incumbents: Anticipate MDR reclassification thresholds by pre-validating clinical evidence packages for products near the medical device boundary. Consolidate backward integration into supercritical CO2 extraction capacity in South Korea and Germany to secure botanical supply against REACH enforcement tightening. Channel control through hospital procurement contract renewal represents the critical defensive lever against direct-to-consumer subscription disintermediation. For New Entrants and Emerging Players: Tele-dermatology platforms present the most penetrable channel partner type for bypassing saturated retail pharmacy shelf space competition. White-space targets include tier-two Chinese cities with simplified NMPA registration pathways and at-home microneedling convergence creating bundled pre-post treatment oil demand. A go-to-market angle anchored in preservative-free essential oil positioning with compliance monitoring mobile applications unlocks premium pricing in South Korean and German aesthetic practice networks. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale European botanical formulators with existing REACH documentation but underdeveloped direct-to-consumer infrastructure. Long-term viability over the extended horizon favors assets with dual capability in silicone oil institutional supply and essential oil clean beauty positioning. Watch NMPA cosmetic registration simplification velocity in Chengdu and Wuhan as the signal indicating inflection toward pharmacy channel penetration in China's interior markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Botanical Extraction | Secures compliant supply chains against ECHA REACH synthetic additive enforcement actions. |
| MDR Clinical Evidence Pre-validation | Accelerates European market access before scar oil reclassification thresholds tighten. |
| Tele-dermatology Subscription Partnership | Captures recurring revenue from millennial acne scar consumers abandoning retail counters. |
| China Tier-two City NMPA Registration | Unlocks pharmacy channel access in Chengdu and Xi'an beyond saturated coastal corridors. |
| Mobile Application Compliance Monitoring | Enables therapeutic-grade claims through patient adherence tracking in Seoul dermatology centers. |
Research Methodology
Direct dialogue with hospital procurement managers, dermatology center directors, cosmetic formulators, and tele-dermatology platform executives grounded the qualitative foundation. Secondary validation drew from FDA cosmetic-dermatology guidance documents, ECHA REACH substance restriction databases, NMPA cosmetic registration filings, and hospital GPO contract disclosures. Bottom-up and top-down triangulation cross-referenced manufacturer production capacity with channel inventory velocity estimates.
Bottom-up modeling anchored volume projections to hospital discharge kit inclusion rates, pharmacy SKU replenishment patterns, and direct-to-consumer subscription cohort retention across the analysis window. Segmentation dimensions spanned product chemistry tiers, application context, end-user setting, and distribution channel structure. CAGRs were derived from regression-adjusted growth rate convergence across modeled segments, incorporating silicone feedstock cost volatility and botanical extraction capacity expansion timelines as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MDR reclassification timing, NMPA regulatory simplification velocity, and ECHA enforcement intensity on synthetic additive restrictions. Forecasts reflect documented assumptions regarding hospital procurement contract renewal rates and tele-dermatology platform subscriber acquisition economics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Dermatology Software Market
Dermatology
UK Scar Treatment Market
Dermatology
Global Veterinary Dermatology Drugs Market
Dermatology
Skin Hyperpigmentation Treatment Market
Dermatology
Erythema Treatment Market
Dermatology
Athletes Foot (Tinea Pedis) Treatment Market
Dermatology
Global Dermatology Cro Market
Dermatology
Telogen Effluvium Treatment Market
Dermatology
US and Canada Skin Cancer Dermatology Market
Dermatology
Porokeratosis Treatment Market
Dermatology
Global Dermatological Therapeutics Market
Dermatology
Psoriasis Treatment Market
Dermatology
Hyperpigmentation Disorder Treatment Market
Dermatology
Seborrheic Keratosis Market
Dermatology
Dermatology Cryosurgery Units Market
Dermatology
Seborrheic Keratosis Treatment Market