
 Darier Disease Drugs Market | 2026-2036
Darier Disease Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Darier Disease Drugs Market Analysis
A shift from single-source API procurement to multi-source active ingredient sourcing is pivoting supply security for Darier disease formulations. GlaxoSmithKline Plc leverages captive manufacturing for retinoid intermediates across European sites. Sun Pharmaceutical Industries Ltd. anchors its position through backward integration into generic dermatology APIs. BridgeBio Pharma Inc. specializes in precision genetic medicine platforms that target ATP2A2 pathway modulation.
Darier disease drugs comprise pharmaceutical agents and device-assisted modalities designed to manage keratotic papules and mucosal lesions caused by ATP2A2 gene mutations, with oral retinoids functioning as first-line systemic therapy by normalizing epidermal differentiation. Topical treatments occupy the largest revenue pool due to chronic symptomatic management requirements, while oral medications capture the fastest growth trajectory driven by disease-modifying efficacy in severe phenotypes. Dermatology clinics concentrate the highest prescription volume among end users, reflecting the need for specialist monitoring of retinoid toxicity and phototherapy protocols.
The FDA orphan drug designation framework and EMA rare disease incentives shape clinical trial design and exclusivity timelines for ATP2A2-targeted therapies, while the EPA regulates phototherapy device emissions standards that constrain device-assisted delivery mode expansion. Health Canada and the TGA maintain aligned but independently reviewed approval pathways that fragment launch sequencing across North America and Australia. Stakeholders must monitor evolving payer evidence requirements for genetic confirmation testing as a prerequisite for specialty pharmacy reimbursement.
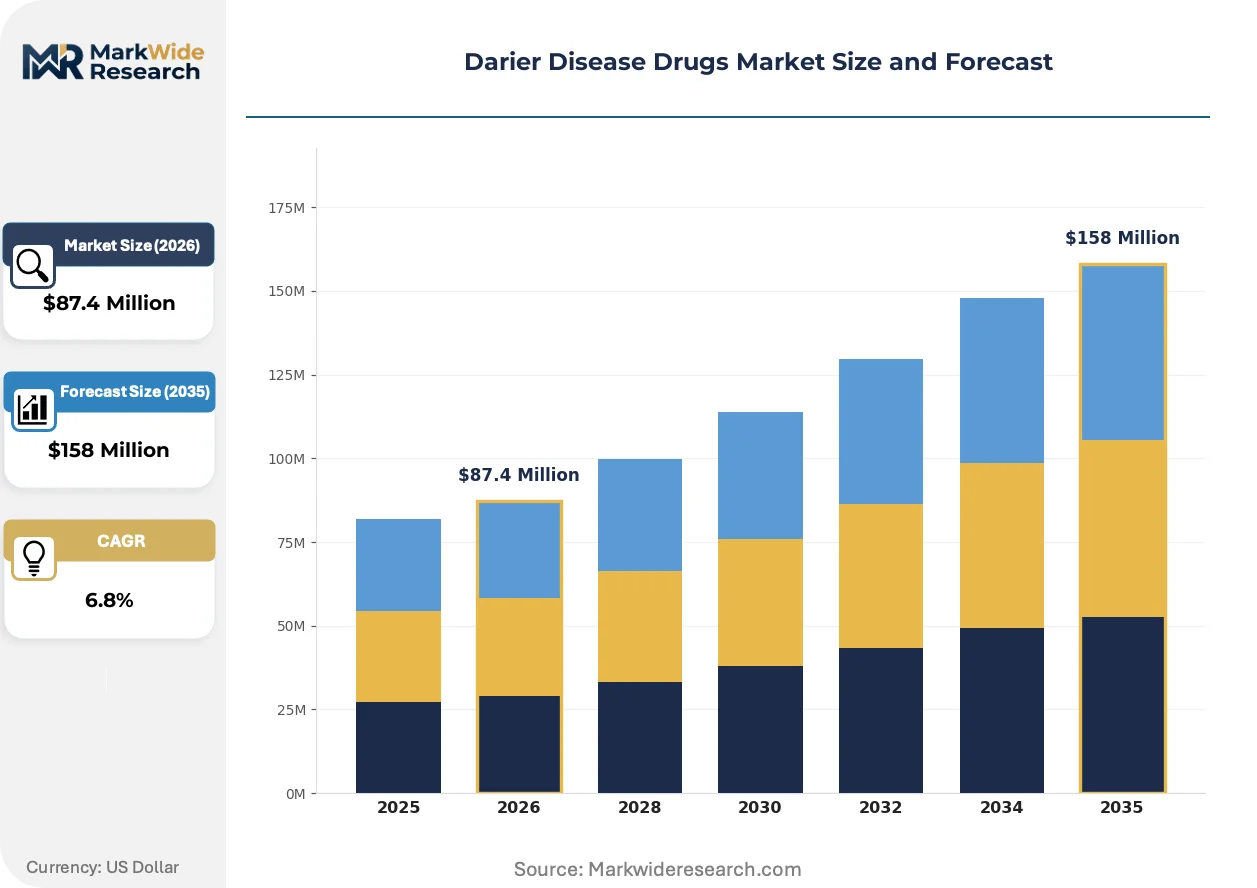
Market Dynamics
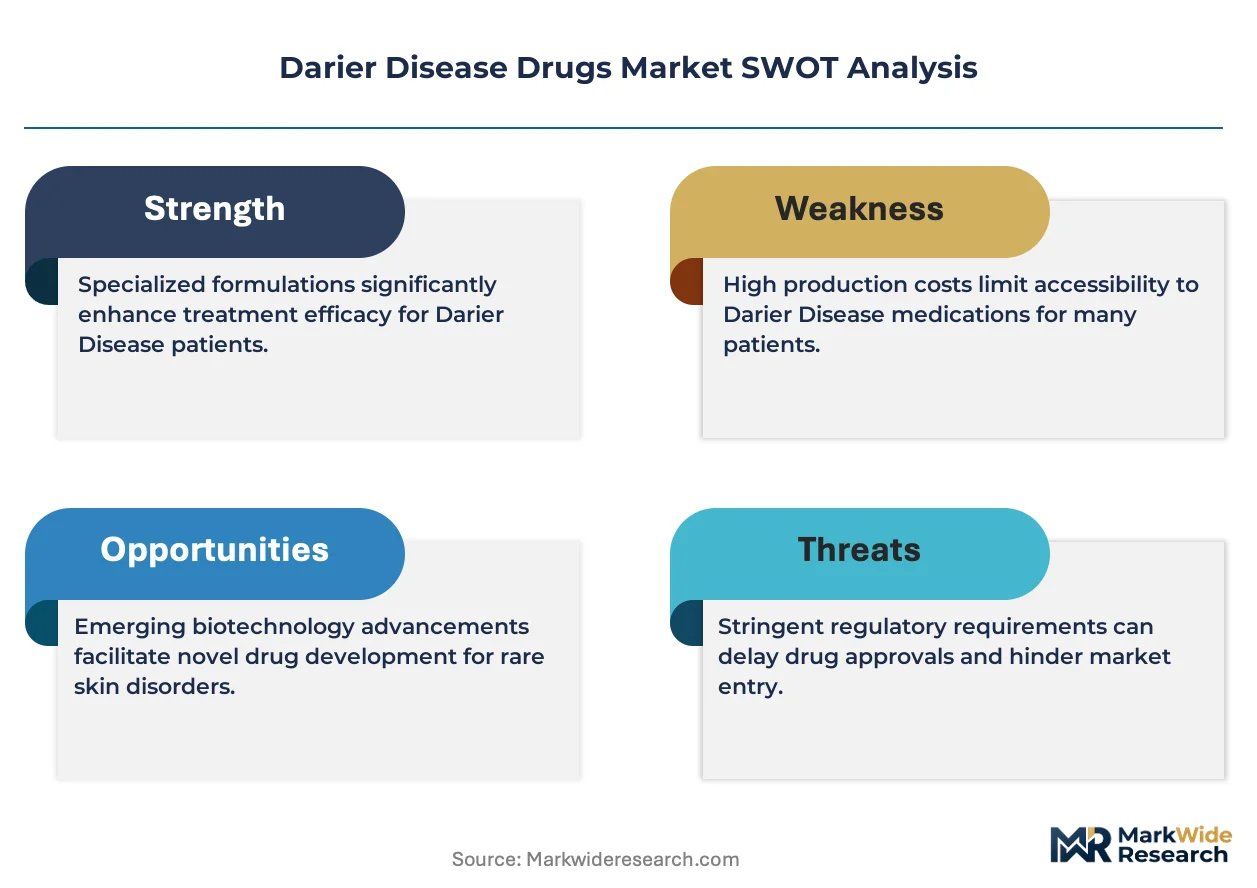
ATP2A2 pathway modulation is concentrating R&D investment toward precision genetic therapies, displacing empirical retinoid prescribing with biomarker-guided patient stratification that reshapes clinical trial endpoints and payer reimbursement criteria.
Growth Catalysts
- FDA Orphan Drug Incentives:Tax credits and seven-year exclusivity accelerate ATP2A2-targeted therapy development, pulling venture capital into rare dermatology pipelines.
- Dermatology Clinic Expansion:Specialist access networks in tertiary care centers widen patient screening for genetic confirmation testing.
- Phototherapy Protocol Refinement:Narrowband UV-B dosing algorithms improve lesion clearance rates in refractory cases.
Market Restraints
- Retinoid API Concentration:Three European manufacturers control isotretinoin active ingredient supply, creating single-source vulnerability.
- ATP2A2 Biomarker Assay Cost:Sanger sequencing and MLPA testing burden outpatient budgets before therapy initiation.
- Phototherapy Device Emission Standards:EPA ultraviolet radiation limits constrain device-assisted delivery mode expansion.
Strategic Opportunities
- EMA Rare Disease Pathways:Conditional marketing authorization accelerates ATP2A2 modulator access in severe pediatric phenotypes.
- Telemedicine Integration:Remote lesion photography and teledermatology platforms extend specialist reach into underserved rural catchments.
- Gene Therapy Convergence:CRISPR-based ATP2A2 correction combined with lipid nanoparticle delivery opens curative modality development.
Industry Challenges
- Retinoid Teratogenicity Risk Management:iPLEDGE program compliance demands specialized pharmacy infrastructure and patient counseling capacity.
- Genetic Counselor Workforce Scarcity:ATP2A2 variant interpretation expertise concentrates in academic medical centers, creating diagnostic bottleneck.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Darier Disease Drugs Market |
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Treatments, Oral Medications, Phototherapy Devices, Supportive Care Therapy Area: Dermatology, Genetic Disorders, Chronic Skin Conditions, Autoimmune Conditions End User: Hospitals, Dermatology Clinics, Home Care, Specialty Pharmacies Delivery Mode: Topical Application, Oral Administration, Device-Assisted, Infusion |
| Companies Covered | GlaxoSmithKline Plc, Amneal Pharmaceuticals Inc., AbbVie Inc., Novartis AG, Sun Pharmaceutical Industries Ltd., Bausch Lomb Corp., BridgeBio Pharma Inc., Johnson and Johnson Services Inc., Galderma SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Darier Disease Drugs Market Emerging Trajectories
Digital pathology and artificial intelligence are compressing diagnostic timelines while regulatory frameworks recalibrate around genetic evidence standards. Three intersecting developments are restructuring competitive positioning.
Machine learning-based histopathology analysis is automating keratotic lesion classification, distinguishing Darier disease mimics from true ATP2A2-driven pathology. Dermatology departments at academic medical centers are deploying convolutional neural networks to triage biopsy referrals. This automation is compressing time-to-diagnosis from weeks to days, reshaping patient funnel economics for specialty clinics.
EMA's updated rare disease guidelines now mandate natural history data collection prior to pivotal trials, extending ATP2A2-targeted therapy development timelines. Sponsors must establish patient registries across multiple member states before initiating Phase II studies. Pediatric severe phenotypes in France and Germany face the most pronounced protocol complexity, driving consortium-based trial designs.
Specialty pharmacy carve-outs are displacing traditional retail dispensing for oral retinoid therapies. Payers in the United States now require genetic confirmation through certified laboratories before authorizing high-cost ATP2A2 modulators. This channel shift concentrates fulfillment volume with three national specialty pharmacies, altering wholesaler relationships and inventory positioning.
Darier Disease Drugs Market Segmentation
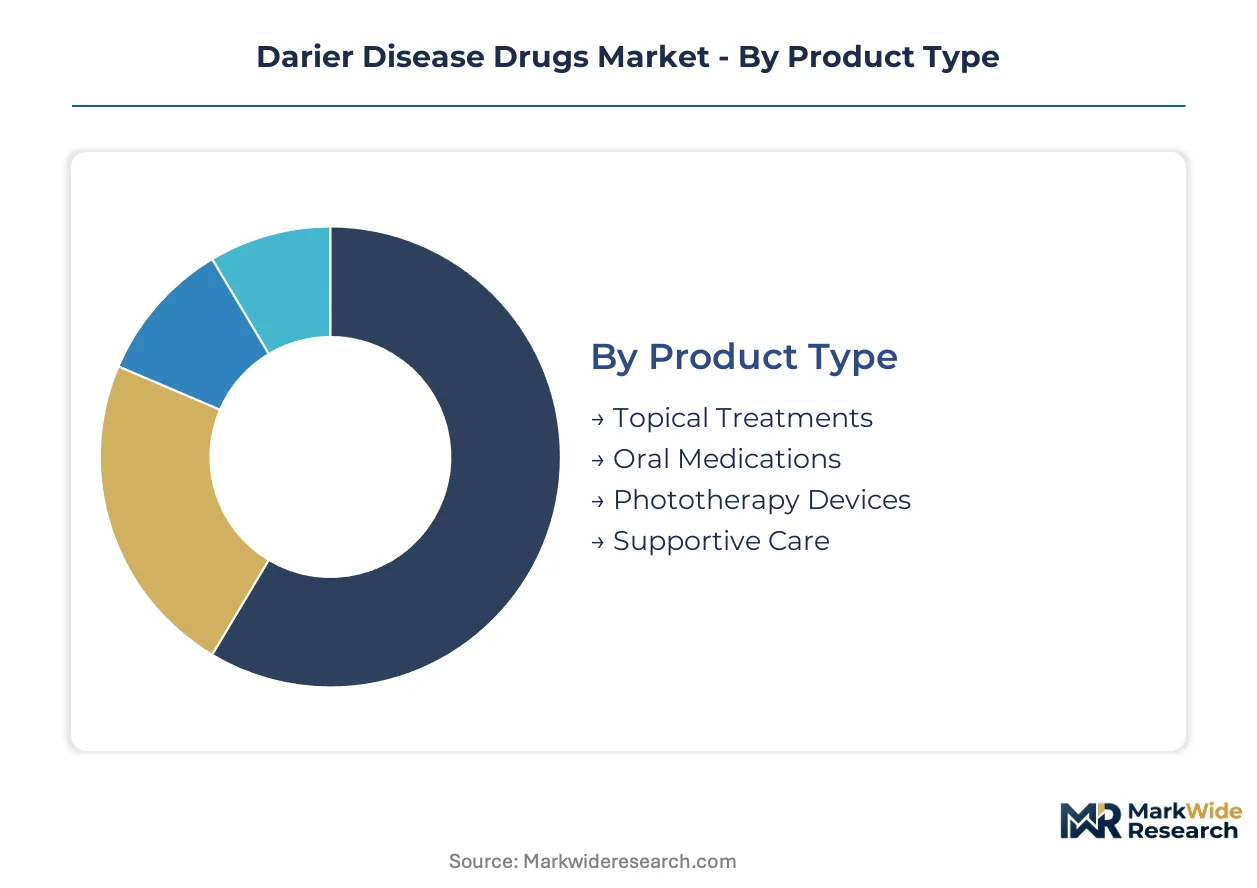
Darier disease drug segmentation reflects the tension between chronic symptomatic management and curative modality development. Therapy selection hinges on ATP2A2 mutation severity, lesion distribution patterns, and specialist access infrastructure.
Product Type:
Standardized formulations dominate high-volume segments while precision genetic therapies demand bespoke manufacturing protocols and cold-chain logistics.
- Topical Treatments:Keratolytic agents and retinoid creams constitute the volume foundation, with chronic application requirements driving recurring prescription cycles. Demand concentrates in dermatology clinics across the United States and Germany, where payer formularies favor first-line symptomatic management before systemic escalation.
- Oral Medications:Systemic retinoids including isotretinoin and acitretin target severe phenotypes through epidermal differentiation normalization. Prescription volume clusters in tertiary care centers with iPLEDGE-certified pharmacy infrastructure, particularly in France and the United Kingdom where genetic confirmation testing precedes authorization.
- Phototherapy Devices:Narrowband UV-B delivery systems serve refractory cases through outpatient protocol administration.
- Supportive Care:Emollient formulations and antiseptic washes manage secondary infection risk in intertriginous lesions.
Most installed capacity flows through Topical Treatments. Expansion is steepest in Oral Medications.
Therapy Area:
Reimbursement pathways diverge sharply between cosmetic-coded indications and genetically confirmed rare disease classifications.
- Dermatology:The primary treatment setting where lesion morphology drives clinical decision-making. Demand concentrates in academic medical centers with integrated genetic counseling services, particularly in Boston and Heidelberg where ATP2A2 variant interpretation expertise resides.
- Genetic Disorders:Precision medicine platforms target ATP2A2 pathway modulation through mechanism-based drug design. Investment flows toward pediatric severe phenotypes in regulatory jurisdictions with accelerated approval frameworks.
- Chronic Skin Conditions:Long-term management protocols align with psoriasis and eczema service lines.
- Autoimmune Conditions:Overlap syndromes with Darier disease phenotypes create diagnostic complexity.
Revenue concentration sits with Dermatology. Genetic Disorders is gaining share fastest.
End User:
Channel economics shift fulfillment volume toward sites capable of genetic confirmation and specialized toxicity monitoring.
- Dermatology Clinics:Specialist access networks concentrate prescription authority through teledermatology platforms and regional referral hubs. Patient screening for ATP2A2 mutations widens in tertiary centers across Sydney and Toronto.
- Hospitals:Inpatient management addresses acute exacerbations and surgical complications.
- Home Care:Self-administered topical protocols reduce clinic burden for stable patients.
- Specialty Pharmacies:Oral retinoid dispensing requires iPLEDGE compliance infrastructure and pregnancy prevention counseling capacity.
Prescription volume peaks in Dermatology Clinics. Specialty Pharmacies is expanding most quickly.
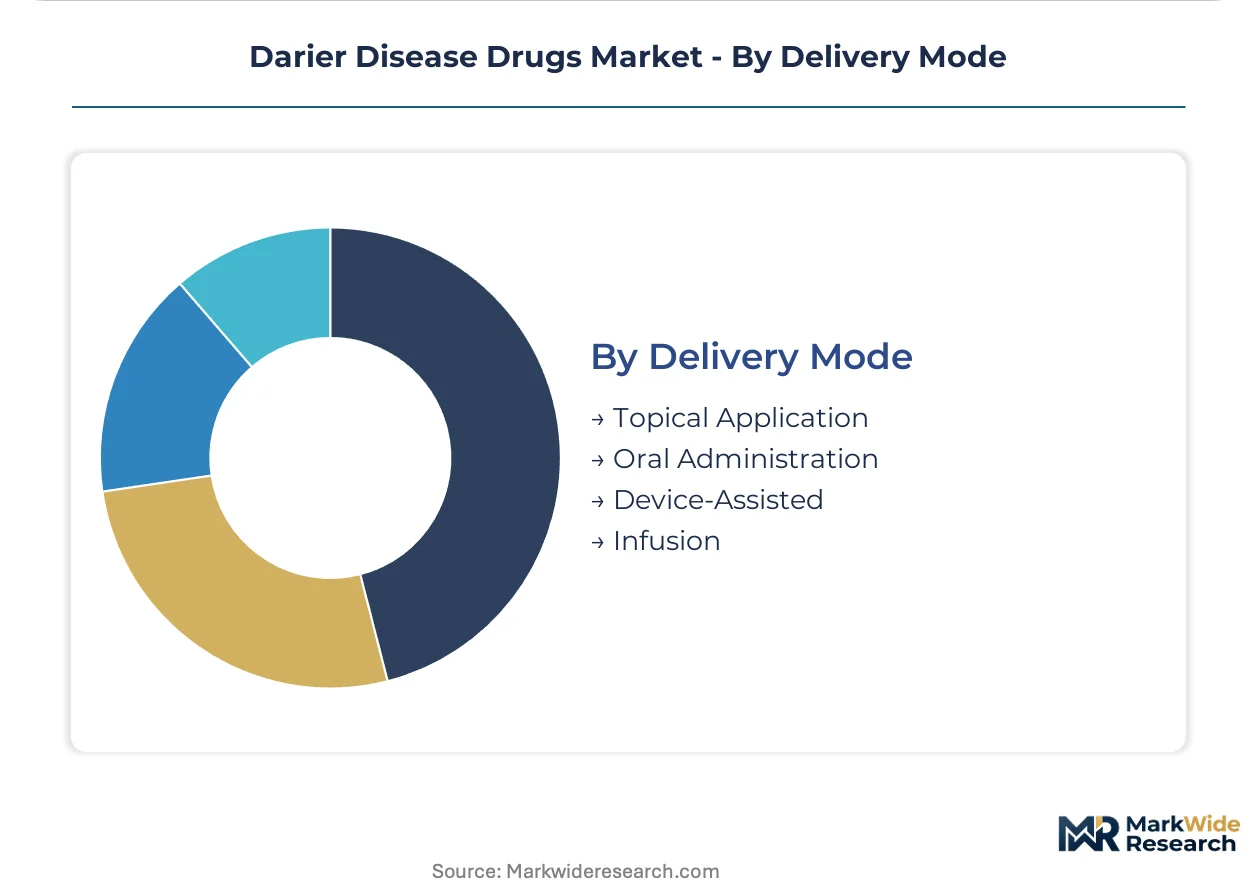
Delivery Mode:
Route selection balances lesion accessibility against systemic exposure risks and phototherapy device availability.
- Topical Application:First-line administration for localized lesions with minimal systemic absorption. Formulation stability challenges concentrate manufacturing in European sites with retinoid handling expertise.
- Oral Administration:Systemic bioavailability enables disease-modifying efficacy in widespread phenotypes. Teratogenicity risk management demands specialized pharmacy networks in the United States and centralized dispensing in France.
- Device-Assisted:Phototherapy protocols require calibrated UV-B emission systems.
- Infusion:Investigational ATP2A2 modulators may leverage intravenous delivery for tissue penetration.
Patient encounters favor Topical Application. Oral Administration is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Heidelberg corridor concentrates ATP2A2 variant interpretation expertise and retinoid toxicity monitoring infrastructure. Patient screening for genetic confirmation testing widens across tertiary dermatology centers in Sydney, Toronto, and Paris. Regulatory divergence between FDA orphan drug pathways and EMA rare disease frameworks fragments launch sequencing and reimbursement timelines.
United States
Dermatology clinic networks in Boston and New York Metro expand teledermatology platforms to screen rural catchments for ATP2A2 mutations. The FDA orphan drug designation framework grants seven-year exclusivity and tax credits that pull venture capital into precision genetic pipelines. Specialty pharmacy carve-outs in California and Texas concentrate oral retinoid dispensing with iPLEDGE-certified infrastructure.
Germany
Academic medical centers in Heidelberg and Berlin anchor EU-wide ATP2A2 variant interpretation capacity, creating diagnostic bottlenecks amid genetic counselor scarcity. The EMA rare disease pathway mandates natural history registries before pivotal trials, extending development timelines for pediatric severe phenotypes. Bavarian dermatology departments deploy machine learning histopathology tools to compress diagnostic timelines from weeks to days.
France
Tertiary care centers in Paris and Lyon concentrate prescription authority for systemic retinoids through centralized dispensing protocols. ANSM maintains aligned but independently reviewed approval pathways that fragment launch sequencing with Health Canada and the TGA. Pediatric severe phenotypes face pronounced protocol complexity under EMA updated guidelines, driving consortium-based trial designs across multiple member states.
Australia
Dermatology clinics in Sydney and Melbourne widen patient screening for genetic confirmation testing through integrated teledermatology platforms. The TGA maintains independently reviewed approval pathways that diverge from FDA and Health Canada sequencing, delaying ATP2A2-targeted therapy access. Narrowband UV-B phototherapy protocols in Queensland and Victoria serve refractory cases with calibrated emission systems.
Canada
Health Canada approval pathways align with FDA frameworks but require independent review, creating staggered launch timelines for ATP2A2 modulators. Dermatology centers in Toronto and Vancouver expand specialist access networks to screen underserved rural populations. Provincial payer formularies increasingly mandate genetic confirmation testing as a prerequisite for specialty pharmacy reimbursement of high-cost systemic therapies.
Darier Disease Drugs Market Vendor Landscape
Global majors compete with regional champions across retinoid API supply and precision genetic medicine platforms. Market structure tilts toward consolidated API manufacturing with fragmented downstream formulation and distribution. Three archetypes dominate: captive retinoid producers with backward integration into active ingredients, precision genetic platforms targeting ATP2A2 pathway modulation, and specialty dermatology marketers with clinic-centric distribution. Dominant competitive moves include M&A to secure genetic counseling networks and capacity expansion in cold-chain logistics for biologic delivery.
Within the precision genetic platform tier, BridgeBio Pharma Inc. exemplifies mechanism-based drug design targeting ATP2A2 pathway modulation, while GlaxoSmithKline Plc anchors the captive manufacturing archetype with European-based retinoid intermediate production. Sun Pharmaceutical Industries Ltd. occupies a position emphasizing backward integration into generic dermatology APIs.
| Leading Market Players |
|---|
| GlaxoSmithKline Plc |
| Amneal Pharmaceuticals Inc. |
| AbbVie Inc. |
| Novartis AG |
| Sun Pharmaceutical Industries Ltd. |
| Bausch Lomb Corp. |
| BridgeBio Pharma Inc. |
| Johnson and Johnson Services Inc. |
| Galderma SA |
| Others |
Supply Flow & Price Mechanics
EPA ultraviolet radiation emission standards for phototherapy devices gate qualified supply access and premium-tier pricing for device-assisted Darier disease modalities. Manufacturers achieving calibrated UV-B certification capture pricing power in tertiary care procurement, while non-compliant suppliers face channel exclusion.
Pricing Analysis
Input-cost pass-through from isotretinoin API supply concentration in European manufacturing sites shapes retinoid therapy pricing dynamics. Three-tier pricing structure across originator, authorized generic, and commodity generic levels reflects FDA orphan exclusivity windows and ATP2A2 biomarker confirmation requirements. Pricing pressure stems from specialty pharmacy carve-out consolidation and payer genetic-testing mandates. Academic medical centers exhibit lowest price sensitivity due to bundled reimbursement protocols, while rural dermatology clinics face acute budget constraints.
Supply Chain Analysis
Regional distribution centers in Germany, India, and the United States anchor cold-chain logistics for retinoid formulations and precision genetic therapies. Active pharmaceutical ingredient production draws from captive European sites and backward-integrated Indian manufacturers. Single-source vulnerability concentrates in isotretinoin intermediate supply from three specialized chemical producers. Distribution runs through specialty pharmacy networks with iPLEDGE compliance infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Darier disease therapeutics represent a late-cycle quality story as payer formularies pivot toward genetically confirmed ATP2A2 pathway modulation over empirical retinoid prescribing.
For Market Incumbents: Lock in API supply security through multi-source qualification of isotretinoin active ingredients across European and Indian manufacturing sites. Deepen genetic counseling network partnerships to defend against precision therapy entrants targeting pediatric severe phenotypes. For New Entrants and Emerging Players: Capture teledermatology-enabled rural screening networks in Australia and Canada where ATP2A2 confirmation testing penetration remains underdeveloped. Position through diagnostic-test bundling with therapy authorization workflows. For Investors and Strategic Acquirers: Roll-up economics work for precision genetic platforms because EMA rare disease pathway complexity fragments development timelines and creates acquisition arbitrage for Phase II-ready ATP2A2 modulators. Monitor FDA orphan drug exclusivity expiration signals as inflection indicators for generic retinoid substitution pressure.| Strategic Initiative | Industry Significance |
|---|---|
| ATP2A2 Biomarker Test Integration | Payer mandates from CMS and commercial insurers now require genetic confirmation before high-cost therapy authorization. |
| Specialty Pharmacy Network Expansion | iPLEDGE-certified dispensing infrastructure concentrates fulfillment volume with national pharmacy chains. |
| Orphan Drug Exclusivity Defense | Seven-year FDA exclusivity windows protect retinoid revenue streams against generic erosion. |
| Teledermatology Platform Partnership | Remote lesion photography extends specialist reach into underserved rural catchments across multiple countries. |
| Cold-Chain Logistics Investment | Precision genetic therapies require temperature-controlled distribution from manufacturing sites to infusion centers. |
Methodological Framework
Multiple input streams — structured interviews with dermatology clinic directors, regulatory affairs specialists at ATP2A2-targeted therapy developers, and specialty pharmacy procurement managers — were reconciled against FDA orphan drug designation databases, EMA rare disease pathway submissions, ClinicalTrials.gov protocol records, and payer formulary restriction documents. Bottom-up prescription volume modeling and top-down epidemiological prevalence estimates provided cross-validation.
Data-stream reconciliation across product type, therapy area, end user, and delivery mode segmentation dimensions generated volume and value outputs across the projection horizon. CAGRs were derived from patient population growth assumptions, therapy penetration curves, and pricing trajectory modeling. Forecast inputs incorporated iPLEDGE program compliance rates, genetic counselor workforce expansion projections, and phototherapy device emission standard evolution.
Regulatory pathway delays, ATP2A2 biomarker assay cost volatility, and retinoid API supply disruptions are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Folliculitis Market
Dermatology
Rosacea Treatment Market
Dermatology
Cutaneous Squamous Cell Carcinoma Market
Dermatology
Europe Scar Treatment Market
Dermatology
Dermatological Products Market
Dermatology
Skin Cancer Market
Dermatology
Dermatology Devices Market
Dermatology
Global Dermatitis Herpetiformis Market
Dermatology
Seborrheic Dermatitis Treatment Market
Dermatology
Dermatology Drugs Market
Dermatology
Alopecia Treatment (Hair Loss) Market
Dermatology
Prescription Dermatology Therapeutics Market
Dermatology
Saudi Arabia Hair Transplant Market
Dermatology
Dermabrasion and Micro Needling Market
Dermatology
Dermatophytic Onychomycosis Treatment Market
Dermatology
Common Warts Market