
 Acne Scar Treatment Market | 2026-2036
Acne Scar Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Acne Scar Treatment Market Intelligence
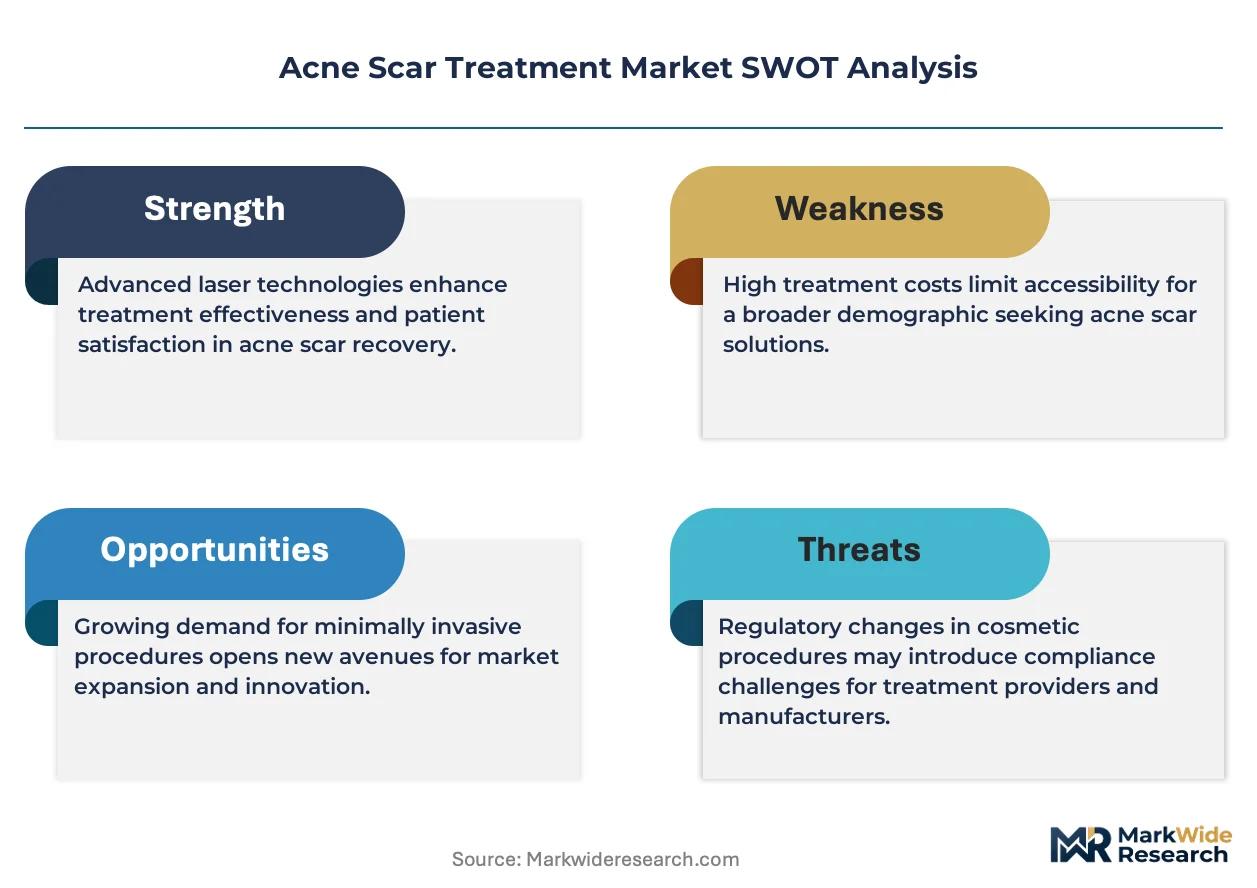
The market for acne scar treatments is shifting as high-efficacy, energy-based devices diverge from topical, over-the-counter products. Lumenis leverages its extensive portfolio in laser and light-based systems to command the premium clinical segment. Cynosure, Inc. competes on the strength of its radiofrequency microneedling and picosecond laser platforms. Sonoma Pharmaceuticals, Inc. specializes in prescription-based topical solutions for scar management.
Acne scar treatment encompasses medical and aesthetic procedures designed to improve or remove textural irregularities and discoloration left by healed acne lesions. These interventions, ranging from controlled dermal abrasion to collagen induction therapy, aim to remodel dermal collagen and elastin fibers to restore a smoother skin surface. Laser therapy and microneedling represent the highest-value in-clinic procedures within the treatment type segment. Dermatology clinics and medical spas constitute the primary end-user channels, capturing the bulk of procedural spending.
Device approvals from the US Food and Drug Administration (FDA) and CE marking under Europe's Medical Device Regulation (MDR) are critical for market access. These regulatory bodies mandate stringent clinical data on the safety and efficacy of energy-based devices and dermal fillers. Future competitive advantage will hinge on developing treatments that offer superior efficacy with minimal patient downtime and discomfort.
Market Dynamics
The central dynamic shaping the acne scar treatment market is the technological and clinical divergence between high-capital, energy-based devices and accessible topical solutions. This bifurcation creates distinct value chains, regulatory pathways, and competitive arenas for device manufacturers and pharmaceutical companies.
Growth Catalysts
- Non-Invasive Technology:The development of fractional laser and radiofrequency microneedling systems reduces patient downtime and improves safety profiles, encouraging higher procedure volumes in dermatology clinics and medical spas.
- Aesthetic-Driven Demand:Strong consumer demand for aesthetic improvement, particularly in markets like South Korea, Brazil, and the United States, supports sustained spending on clinical-grade scar revision procedures.
- Regulatory Pathways:Clearer device approval frameworks, such as the CE marking process under Europe's MDR, provide a structured route for novel energy-based systems to enter key geographic markets upon demonstrating safety and efficacy.
Market Restraints
- High Device Cost:The significant capital investment required for advanced laser and radiofrequency platforms can be a barrier to adoption for smaller clinics or practitioners in emerging economies.
- Substitution from Topicals:The wide availability of lower-cost, over-the-counter creams and prescription retinoids presents a constant substitution threat, particularly for patients with mild scarring or budget constraints.
- Stringent Clinical Requirements:Regulatory bodies, including the US FDA, mandate extensive and costly clinical trials to prove the safety and efficacy of new devices and fillers, potentially delaying market entry.
Strategic Opportunities
- Combination Therapy Protocols:Developing and validating protocols that combine different modalities, such as microneedling with platelet-rich plasma (PRP) or laser resurfacing with dermal fillers, creates new, higher-value treatment packages.
- Expansion in Southeast Asia:Markets with rising disposable incomes and growing aesthetic awareness offer significant penetration opportunities for both devices and topical treatments, representing a new growth frontier.
- Teledermatology Integration:Building platforms that integrate virtual consultations for scar assessment with e-commerce for prescription topicals or scheduling in-clinic procedures can capture a broader patient base.
Industry Challenges
- Practitioner Skill Gap:The safe and effective operation of sophisticated energy-based devices requires specialized training, and a shortage of qualified practitioners can limit the adoption and quality of treatments.
- Lack of Treatment Standardization:Variability in treatment protocols and device settings across clinics leads to inconsistent patient outcomes, which can affect overall market trust and patient satisfaction.
- Managing Patient Expectations:A significant operational challenge is aligning patient expectations with realistic clinical outcomes, as over-promising results can lead to dissatisfaction and damage a clinic's reputation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acne Scar Treatment Market |
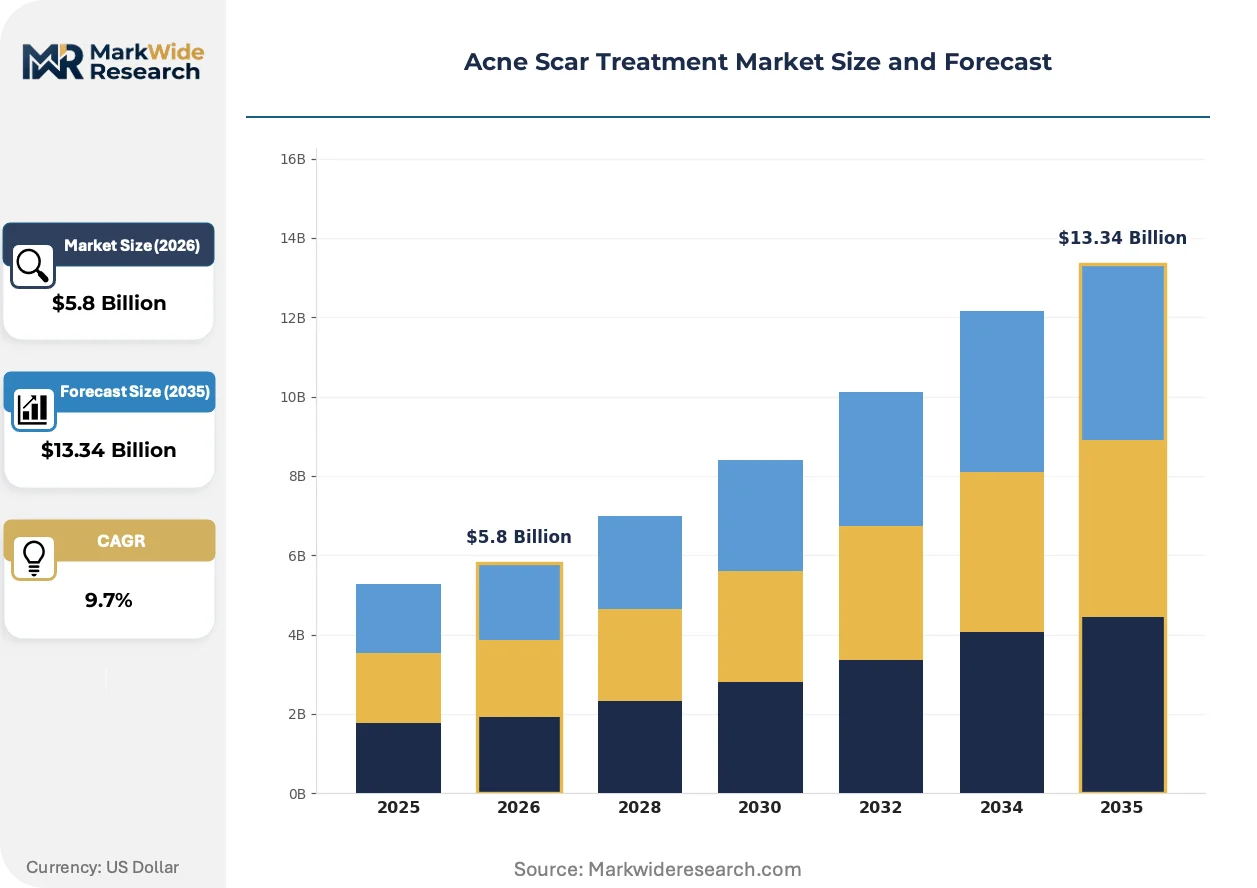
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $13.34 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Laser Therapy, Chemical Peels, Microneedling, Dermal Fillers, Subcision Application Area: Face, Neck, Chest, Back, Shoulders End User: Dermatology Clinics, Cosmetic Surgery Centers, Medical Spas, Skin Care Specialists Delivery Mode: In-Clinic Procedures, At-Home Treatments, Prescription Medications, Over-the-Counter Products |
| Companies Covered | Sonoma Pharmaceuticals, Inc., Cutera, Inc., Candela Corporation, BTL Industries, Merz Pharmaceuticals, Cynosure, Inc., Smith & Nephew PLC, Zimmer MedizinSysteme, Lumenis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acne Scar Treatment Market Strategic Shifts & Innovations
Technological refinement is focused on delivering superior collagen remodeling with minimal thermal injury, reducing patient recovery time. This pursuit of high efficacy and low downtime is driving innovation in energy delivery systems and combination treatment approaches that cater to rising patient expectations.
Picosecond lasers represent a significant evolution in laser-based scar revision. These systems deliver photomechanical impact through ultra-short energy pulses, shattering pigment and inducing collagenesis with less collateral heat than older nanosecond lasers. High-end dermatology clinics and medical spas are rapidly adopting this technology for its efficacy on both post-inflammatory hyperpigmentation and atrophic scars. This advancement is electrifying the premium treatment segment by enabling faster clearance with fewer required sessions and markedly reduced post-procedure downtime.
Europe's Medical Device Regulation (MDR) is imposing more stringent requirements on manufacturers of aesthetic devices. The regulation elevates the standards for clinical evidence, risk management, and post-market surveillance required to obtain and maintain a CE mark. Consequently, companies targeting the European market must now allocate greater resources to rigorous clinical trials and robust quality management systems. This shift disproportionately impacts smaller innovators and raises the barrier to entry for new energy-based platforms.
A behavioral shift toward combination therapies and "prejuvenation" is altering treatment plans. Patients are increasingly opting for a series of less-invasive procedures, such as microneedling paired with biostimulatory fillers, rather than a single, aggressive ablative laser session. This model disrupts the traditional one-off, high-downtime treatment paradigm by emphasizing gradual improvement and maintenance. This trend is most visible in the United States and Brazil, where consumers prioritize consistent results with minimal social or professional interruption.
Acne Scar Treatment Market Segmentation
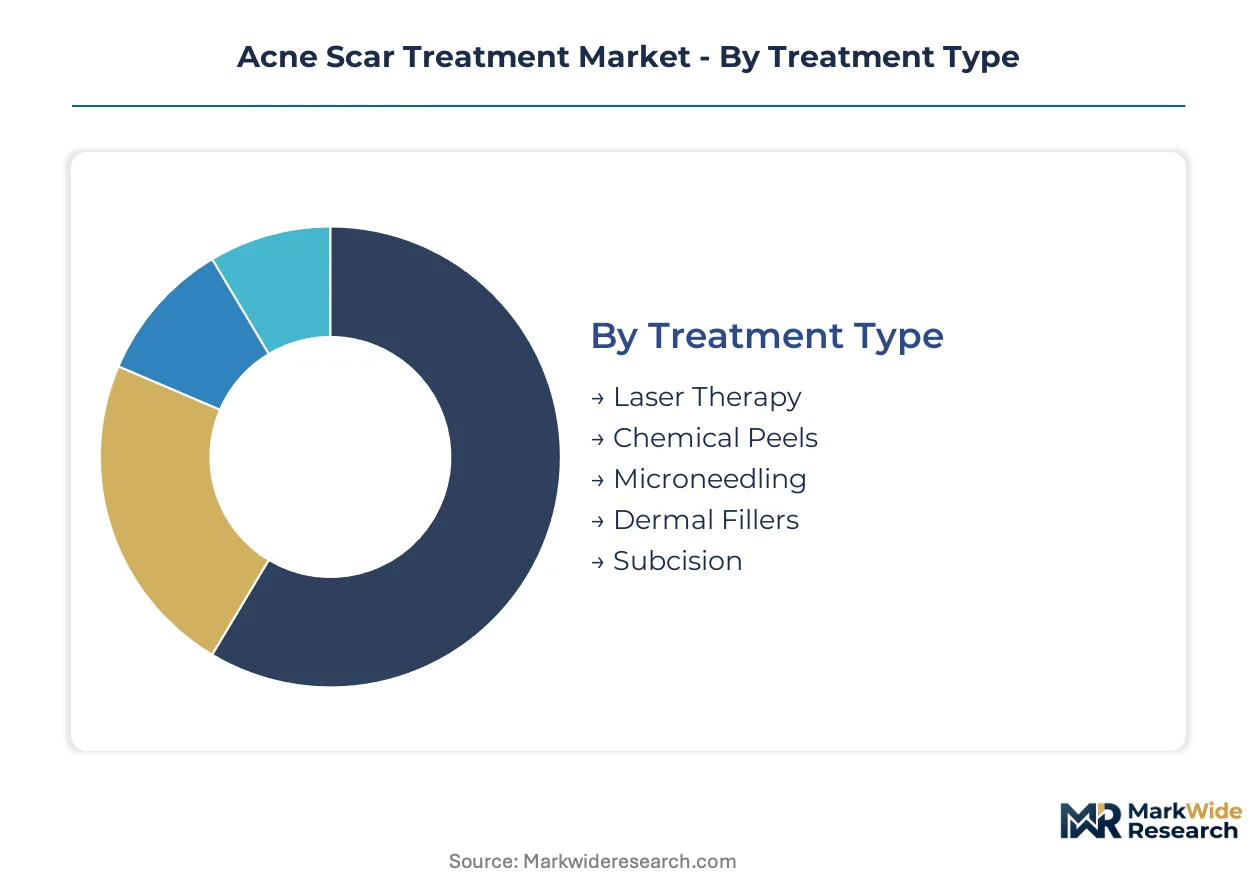
Segmentation provides a granular view of the acne scar treatment market, highlighting distinct consumer needs, technological preferences, and operational channels. Understanding these divisions helps stakeholders tailor solutions and optimize market penetration strategies across diverse patient demographics and clinical settings.
Treatment Type:
Patient preferences and the severity of scarring fundamentally differentiate buyers within the treatment type segment.
- Laser Therapy:These energy-based systems utilize focused light to ablate tissue or stimulate collagen production, addressing various scar types. Demand concentrates in the United States and South Korea due to strong aesthetic-driven consumer interest and advanced clinical infrastructure.
- Microneedling:This minimally invasive procedure uses fine needles to create controlled micro-injuries, inducing collagen and elastin remodeling. Brazil and Europe show significant adoption, driven by patient desire for reduced downtime and improving safety profiles compared to more aggressive treatments.
- Chemical Peels:These involve applying acidic solutions to exfoliate outer skin layers, promoting cell turnover and improving superficial scar texture.
- Dermal Fillers:Injectable substances like hyaluronic acid physically elevate depressed scars, providing immediate but temporary volume correction.
- Subcision:A surgical technique that releases fibrous bands tethering scars to deeper tissue, allowing the skin to rise and smooth out.
Laser Therapy leads volumes today; Microneedling is gaining share fastest.
Application Area:
The specific body region requiring treatment often dictates the choice of procedure and influences patient willingness to invest.
- Face:Facial scars are the primary concern for most patients, driving the highest demand for both cosmetic and medical interventions. Clinics in urban centers globally prioritize facial scar revision due to strong aesthetic market pressures.
- Neck:Treatment for neck scars requires careful consideration of skin laxity and sensitivity, often favoring less aggressive modalities. Demand in European markets is growing for subtle improvements in this visible area.
- Chest:Acne scars on the chest, particularly keloids or hypertrophic scars, often require specialized treatment protocols due to skin thickness.
- Back:Extensive scarring on the back may necessitate broader treatment approaches, with cost and coverage being significant patient considerations.
- Shoulders:Shoulder scars, like those on the back, often present challenges related to surface area and potential for recurrence.
The Face segment captures the highest procedural spending; the Neck segment exhibits the steepest expansion trajectory.
End User:
The clinical setting chosen by patients reflects their priorities regarding treatment complexity, practitioner expertise, and cost.
- Dermatology Clinics:These facilities offer a comprehensive range of medical and aesthetic treatments, staffed by highly trained dermatologists. They capture the bulk of high-value procedural spending, especially for advanced energy-based devices.
- Medical Spas:Medical spas provide a blend of aesthetic services and medical oversight, appealing to patients seeking less invasive procedures in a relaxed environment. Their growth in the United States is spurred by accessible services and competitive pricing.
- Cosmetic Surgery Centers:These centers focus on more invasive surgical options for severe scarring, often integrating with other aesthetic procedures.
- Skin Care Specialists:Professionals in this segment typically offer topical solutions and less aggressive treatments, catering to mild scarring or maintenance.
Dermatology Clinics generate the largest revenue; Medical Spas are expanding most quickly.
Delivery Mode:
Patient convenience, cost considerations, and the desired level of clinical intervention primarily define the delivery mode segment.
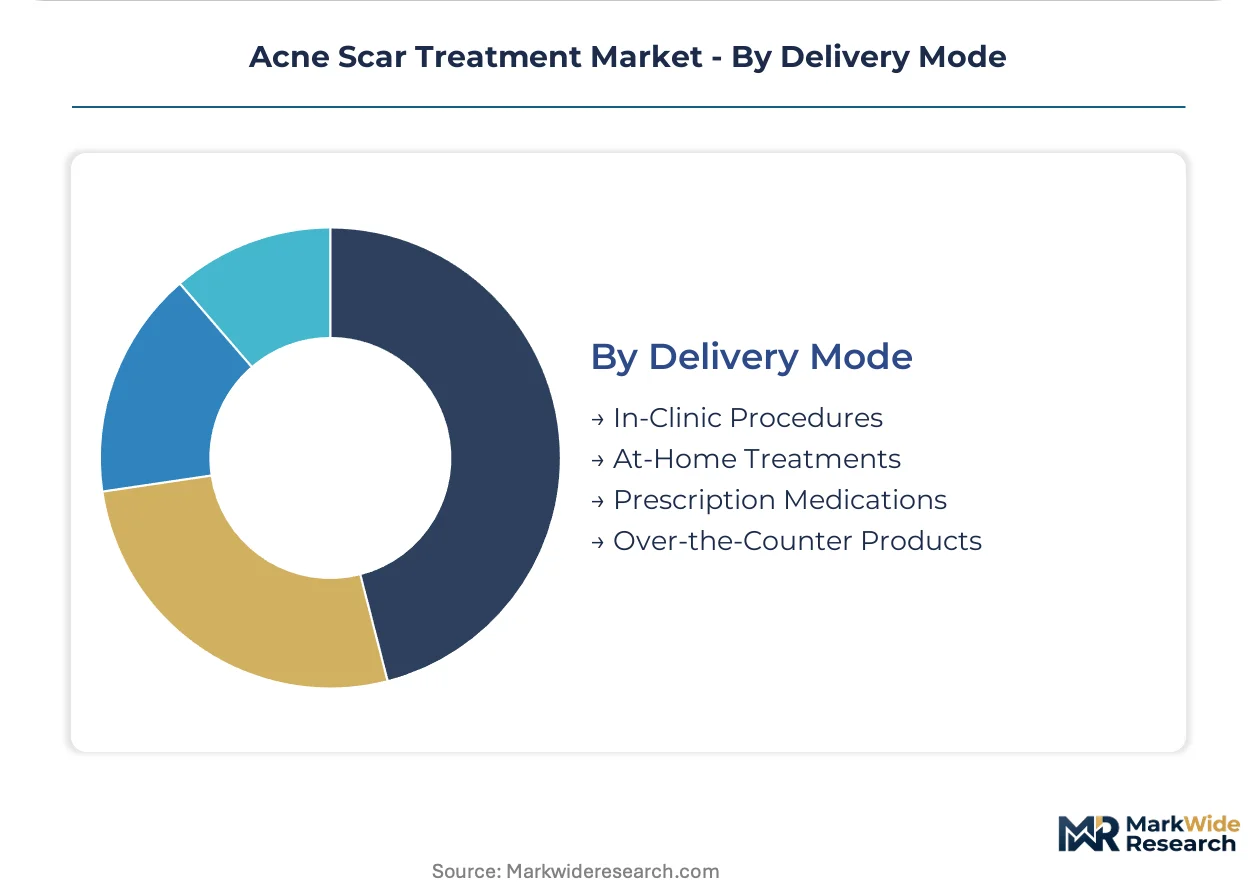
- In-Clinic Procedures:These involve treatments administered by trained professionals using specialized equipment, offering high efficacy for moderate to severe scars. They represent the highest-value segment, particularly in countries with robust private healthcare sectors like the United States.
- Over-the-Counter Products:Readily available creams, gels, and serums provide accessible, non-prescription options for mild scarring or adjunctive care. Their widespread availability in pharmacies globally presents a constant substitution threat to more expensive clinical treatments.
- At-Home Treatments:Devices and kits designed for self-application offer convenience but typically deliver less intensive results than professional interventions.
- Prescription Medications:Dermatologist-prescribed topicals or oral medications target specific scar characteristics or underlying inflammatory processes.
In-Clinic Procedures drive significant revenue; Over-the-Counter Products hold the largest volume share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The high concentration of skilled dermatologists and aesthetic practitioners anchors the global acne scar treatment market. These professionals drive the adoption of advanced energy-based devices and specialized clinical procedures. Their expertise ensures high-quality patient care and supports market innovation.
United States
Strong consumer demand for aesthetic improvement, particularly for facial scars, drives significant procedural spending in the United States. The US Food and Drug Administration (FDA) mandates rigorous clinical data for energy-based devices before market entry. Major medical device manufacturers in California continue to innovate in non-invasive laser and radiofrequency technologies.
South Korea
Aesthetic-driven demand and a high willingness to adopt advanced technologies characterize the South Korean market. The Ministry of Food and Drug Safety (MFDS) regulates medical devices, ensuring safety and efficacy standards. Seoul's Gangnam district remains a prominent hub for aesthetic clinics, offering diverse scar revision treatments.
Brazil
Patient desire for reduced downtime and improving safety profiles contributes to the adoption of microneedling and chemical peels in Brazil. Brazil's national health surveillance agency, ANVISA, oversees the approval of medical devices and aesthetic products. São Paulo is a key center for cosmetic procedures, reflecting strong regional aesthetic pressures.
Germany
High capital investment in advanced energy-based devices supports the premium segment of the German market. CE marking under Europe's Medical Device Regulation (MDR) sets stringent requirements for market access. Medical technology clusters in Bavaria are developing next-generation laser and radiofrequency platforms.
India
Rising disposable incomes and growing aesthetic awareness are expanding the patient base for clinical scar treatments across India. The Central Drugs Standard Control Organization (CDSCO) regulates medical devices, influencing market access for new technologies. The Delhi-NCR region sees increasing clinic expansion and adoption of modern aesthetic practices.
Acne Scar Treatment Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the acne scar treatment market. The market structure is tiered, with premium device manufacturers at one end and accessible topical solution providers at the other. Strategic archetypes include specialized energy-based device manufacturers, pharmaceutical companies focusing on topical solutions, and integrated aesthetic service providers. Portfolio diversification and strategic partnerships represent dominant competitive moves.
On the premium-tier vector, Lumenis exemplifies a company leveraging an extensive portfolio in laser and light-based systems. Cynosure, Inc. occupies a position among leading manufacturers of radiofrequency microneedling and picosecond laser platforms. Sonoma Pharmaceuticals, Inc. sits within the segment of companies specializing in prescription-based topical solutions for scar management.
| Leading Market Players |
|---|
| Sonoma Pharmaceuticals, Inc. |
| Cutera, Inc. |
| Candela Corporation |
| BTL Industries |
| Merz Pharmaceuticals |
| Cynosure, Inc. |
| Smith & Nephew PLC |
| Zimmer MedizinSysteme |
| Lumenis |
| Others |
Cost & Logistics Intelligence
Pharmaceutical-grade active ingredient costs, particularly for complex retinoids and specialized peptides, cascade through the acne scar treatment supply chain, influencing pricing tiers for both topical solutions and combination therapy packages. This cost structure differentiates accessible over-the-counter products from premium, prescription-based dermatological interventions.
Pricing Analysis
Bundled treatment packages versus unbundled individual procedures define the pricing landscape for in-clinic acne scar treatments. Pricing stratifies across premium, standard, and economy tiers based on device technology, clinic reputation, and practitioner expertise. Price differentiation stems from the sophistication of energy-based devices and the level of post-procedure care included. Pricing softness affects the economy segment due to competition from accessible medical spas. Patients with mild scarring exhibit higher price sensitivity compared to those seeking advanced solutions for severe textural irregularities.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke logistics patterns characterize the downstream supply chain for acne scar treatment devices and topicals. Geographic supply concentration for energy-based devices largely rests in the United States, Germany, and Israel, while pharmaceutical-grade active ingredients often source from India and China. The supply chain relies on specialized components like laser diodes and radiofrequency emitters. Regulatory restriction, particularly for cross-border medical device transfers, presents a structural risk. Distribution runs primarily through direct sales channels to dermatology clinics and medical spas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a late-cycle quality story, with patient demand shifting toward premium specifications offering superior efficacy and minimal recovery time.
For Market Incumbents: Extend R&D investments into next-generation energy delivery systems that offer enhanced safety and faster results. Acquire smaller innovators specializing in novel combination therapy protocols to broaden service offerings. Deepen channel control within high-value dermatology clinics through exclusive device placements and comprehensive training programs. The increasing regulatory burden, especially from Europe's MDR, poses a significant threat requiring consistent certification investment.
For New Entrants and Emerging Players: Begin with targeted penetration of underserved geographic markets, such as Southeast Asia, where aesthetic awareness is expanding. Focus on developing accessible, less-invasive microneedling or chemical peel solutions for medical spas, a rapidly growing end-user segment. Integrate teledermatology platforms for virtual consultations and streamlined appointment scheduling, capturing a broader patient base with convenience. Niche applications for specific scar types or non-facial areas also present white-space opportunities.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized energy-based device manufacturers holding strong intellectual property in photomechanical lasers or advanced radiofrequency microneedling. Long-term viability is supported by sustained consumer aesthetic demand and continuous technological advancements. Target acquisition of companies with proven efficacy in combination therapy protocols. Watch for increasing procedure volumes in the Face and Neck segments as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Validates new device safety and efficacy under stringent regulatory frameworks like FDA and CE marking. |
| Regulatory Approval Pathway | Secures market access for novel energy-based systems in key regions such as the United States and Europe. |
| Product Launch of Picosecond Lasers | Captures premium segment share by offering superior collagen remodeling with reduced patient downtime. |
| Strategic Partnership with Medical Spas | Expands market reach for less invasive treatments and captures the rapidly growing aesthetic consumer base. |
| Geographic Expansion into Southeast Asia | Leverages rising disposable incomes and growing aesthetic awareness in new, high-potential markets. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, establishing a robust data foundation. Primary interviews engaged dermatologists, medical spa owners, device engineers, and pharmaceutical R&D leads across key markets. Secondary validation drew from FDA filings, CE marking documentation, industry association reports, and clinical trial registries, ensuring comprehensive market understanding. This approach leveraged both bottom-up and top-down triangulation for data consistency.
The segment-weighting approach informed the analytical framework across the analysis window, projecting market trends and growth trajectories. Segmentation dimensions modeled included treatment type, application area, end-user, delivery mode, and scar severity, providing granular insights. Compound annual growth rates were derived from historical data and projected market dynamics. Procedure volumes in dermatology clinics and technological advancement rates for energy-based devices served as critical industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen global health crises or drastic shifts in consumer disposable income. Forecasts reflect assumptions concerning technological advancements and regulatory stability. Rapid technological obsolescence and changes in regulatory approval timelines represent specific risk factors that could revise projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Japan Scar Treatment Market
Dermatology
Hyperpigmentation Disorder Treatment Market
Dermatology
Dermabrasion Market
Dermatology
Global Dermatology Lasers Market
Dermatology
Global Online Dermatology Consultation Market
Dermatology
Dermatological Products Market
Dermatology
Immunodermatology Market
Dermatology
Radiation Dermatitis Market
Dermatology
Skin Excision Market
Dermatology
Dermatology Software Market
Dermatology
Scar Treatment Oils Market
Dermatology
Telogen Effluvium Treatment Market
Dermatology
Global Rosacea Market
Dermatology
Athletes Foot (Tinea Pedis) Treatment Market
Dermatology
China Scar Treatment Market
Dermatology
Androgenetic Alopecia Market