
 Common Warts Market | 2026-2036
Common Warts Market Size, Share, and Industry Trends Forecast 2026-2036
Common Warts Market Analysis
Modular treatment kits that bundle cryotherapy devices with topical adjuncts is rebalancing how dermatology clinics procure wart care solutions. Verrica Pharmaceuticals leverages its specialty focus on topical immunotherapy to sustain clinical differentiation. Merck & Co. anchors its position through in-house production of immunomodulatory compounds. Bayer AG competes across both prescription and over-the-counter channels with broad retail distribution.
Common warts are benign epidermal proliferations caused by human papillomavirus infection, typically presenting as hyperkeratotic papules on hands or feet and treated through destruction of infected tissue or immune modulation. Cryotherapy remains the most frequently deployed first-line intervention in clinical settings due to its established efficacy profile and minimal infrastructure requirements. Topical treatments occupy the largest volume segment driven by home care accessibility and pharmacy channel penetration. Laser therapy represents the fastest-growing structural category as device portability improves and reimbursement for in-office procedures expands.
The FDA governs prescription immunotherapy approvals and over-the-counter salicylic acid formulations, while the EMA's MDR framework imposes stricter clinical evidence requirements on cryotherapy devices marketed in Europe. Japan's PMDA maintains distinct efficacy benchmarks for combination therapies that delay cross-border product standardization. Stakeholders must monitor how regulatory divergence between FDA accelerated pathways and EMA MDR conformity assessments reshapes geographic launch sequencing and portfolio prioritization.
Market Dynamics
FDA accelerated pathways for immunotherapy approvals are compressing clinical development timelines while EMA MDR conformity assessments extend European market entry, creating divergent geographic launch sequencing that reshapes portfolio prioritization across manufacturers.
Growth Catalysts
- Specialist Clinic Network Density:Dense dermatology clinic networks in the United States, Germany, and Japan concentrate procedure volume and accelerate adoption of minimally invasive interventions.
- Home Care Accessibility:Pharmacy channel penetration for salicylic acid formulations expands patient self-treatment options and reduces clinic dependency for initial case management.
- Device Portability Improvements:Laser therapy equipment miniaturization enables point-of-care deployment without dedicated infrastructure investments.
Market Restraints
- Regulatory Divergence Friction:EMA MDR clinical evidence requirements for cryotherapy devices impose longer approval cycles than FDA 510(k) pathways, delaying cross-border standardization.
- Input Cost Volatility:Liquid nitrogen supply chain concentration creates price instability for cryotherapy-dependent practices.
- Substitution Pressure:Watchful waiting behavior among patients with asymptomatic lesions reduces immediate treatment-seeking rates.
Strategic Opportunities
- Combination Therapy Positioning:Japan PMDA distinct efficacy benchmarks for combination regimens create first-mover advantages for integrated topical-device protocols.
- Retail Channel Expansion:Over-the-counter immunomodulatory adjuncts represent underdeveloped shelf space in European pharmacy chains.
- Telehealth Integration:Remote lesion assessment protocols enable dermatology clinics to triage cases and reserve in-office capacity for procedural candidates.
Industry Challenges
- Reimbursement Code Fragmentation:Inconsistent CPT classification for laser versus cryotherapy procedures complicates revenue cycle management across US payor networks.
- Device Sterilization Protocol Standardization:Multi-site clinic operators face operational friction harmonizing reprocessing workflows across state-level OSHA inspection regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Common Warts Market |
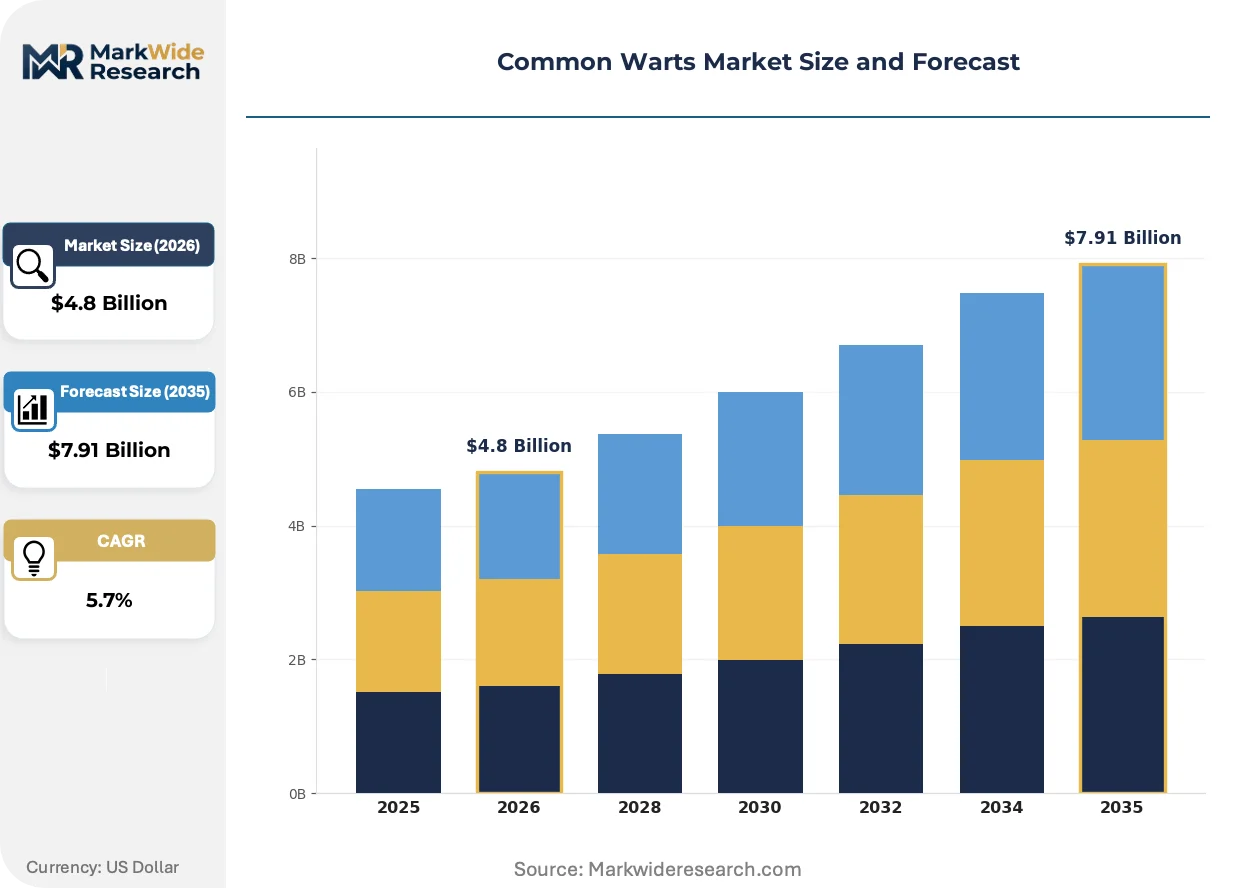
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Treatments, Cryotherapy, Laser Therapy, Surgical Removal Application: Dermatology Clinics, Hospitals, Home Care, Pharmacies End User: Children, Adults, Seniors, Healthcare Providers Treatment Method: Electrosurgery, Chemical Peels, Immunotherapy, Cryosurgery |
| Companies Covered | GlaxoSmithKline plc, Merck & Co., Inc., Verrica Pharmaceuticals, Bayer AG, Johnson & Johnson, Sanofi S.A., Aclaris Therapeutics, Inc., Bausch Health Companies Inc., Nielsen BioSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Common Warts Market Emerging Trajectories
Treatment delivery systems are fragmenting into component-based architectures that separate energy application from adjunctive care, enabling dermatology practices to customize procedural workflows without vendor lock-in.
Portable laser platforms are modularizing wart care delivery by separating diode arrays from cooling systems and control interfaces. Mid-sized dermatology groups in Texas and Florida are adopting these configurable units faster than hospital-affiliated networks. This architecture is modularizing capital deployment, allowing practices to upgrade subsystems rather than replacing entire platforms.
EMA MDR technical documentation requirements for cryotherapy devices are forcing manufacturers to generate clinical performance data beyond traditional equivalence claims. European notified bodies now demand prospective studies for class IIa devices previously cleared through predicate comparison. German and French distributors are delaying new product introductions to accumulate sufficient post-market surveillance records.
Patient-initiated treatment sequences are compressing the interval between symptom recognition and professional consultation. Direct-to-consumer diagnostic applications now photograph and classify lesions before clinic scheduling, shifting triage burden onto front-desk staff. This pattern is most visible in United States metropolitan markets where specialist appointment availability remains constrained.
Common Warts Market Segmentation
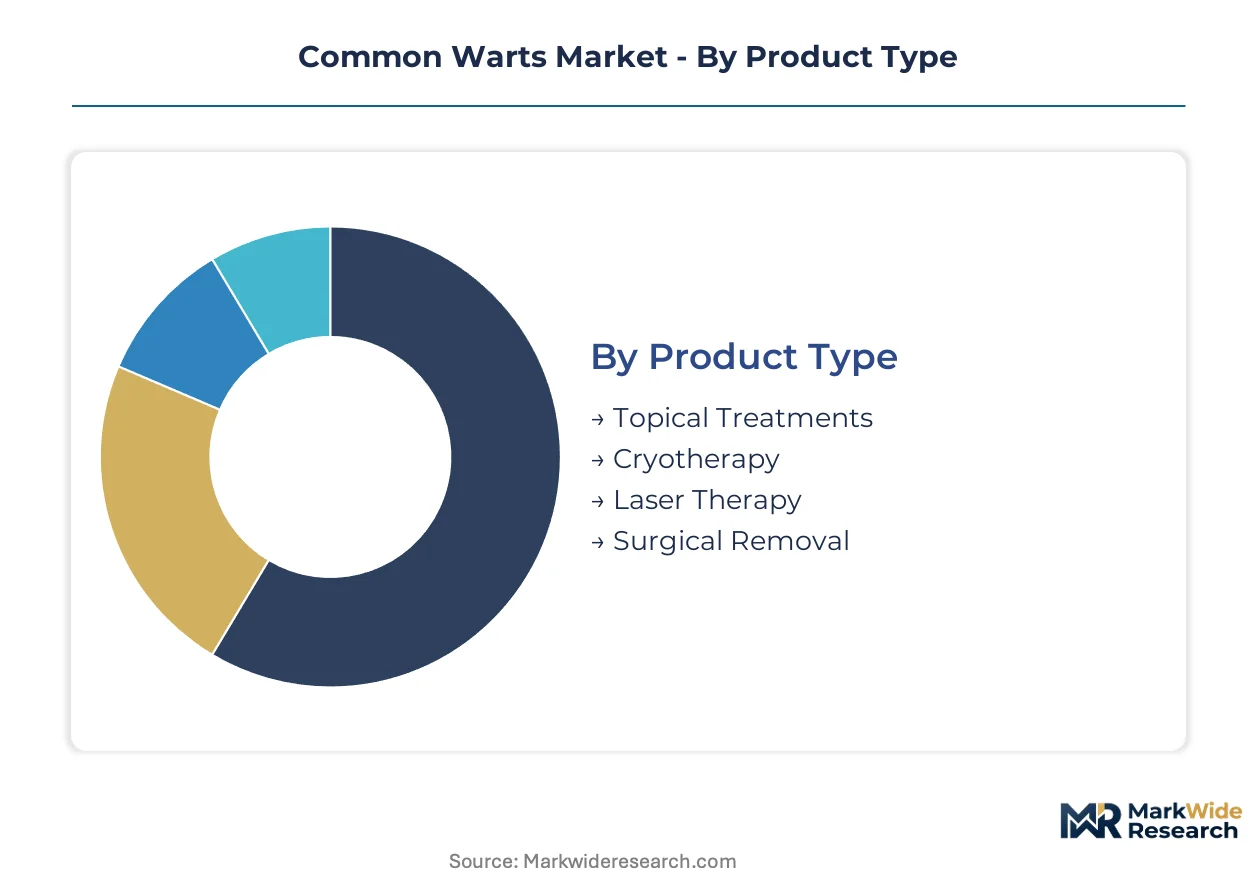
Common warts treatment procurement splits across professional and self-administered channels, with product form and care setting determining margin structures and regulatory pathways. Understanding these divides clarifies where manufacturers capture value versus where commoditization pressures concentrate.
Product Type:
Cost tier separates patients who self-treat from those seeking professional intervention, with price sensitivity and lesion severity driving channel selection.
- Topical Treatments:Salicylic acid and immunomodulatory formulations dominate pharmacy shelf space. Home care accessibility in the United States and Germany concentrates volume here, though reimbursement gaps for prescription topicals constrain premium pricing.
- Cryotherapy:Liquid nitrogen and nitrous oxide devices require minimal infrastructure. Dermatology clinics in Japan deploy these most intensively due to dense specialist networks and favorable procedural reimbursement.
- Laser Therapy:Portable diode platforms enable point-of-care deployment without dedicated suites. Device miniaturization is expanding addressable clinic populations.
- Surgical Removal:Excision and curettage for recalcitrant lesions. Higher complication rates limit this to hospital-affiliated dermatology units.
Volume sits with Topical Treatments; growth tilts toward Laser Therapy.
Application:
Customer type determines whether procurement flows through institutional purchasing or retail pharmacy networks.
- Dermatology Clinics:Independent and group practices performing procedural interventions. Specialist network density in the United States, Germany, and Japan accelerates adoption of minimally invasive modalities.
- Home Care:Patient-directed application of over-the-counter formulations. Pharmacy channel penetration in European markets expands self-treatment options and reduces clinic dependency.
- Hospitals:Academic medical centers handling complex or immunocompromised cases. Reimbursement code fragmentation across US payor networks complicates revenue cycle management.
- Pharmacies:Retail and community dispensaries stocking salicylic acid and adjunctive products. Shelf space competition constrains brand visibility.
Procedure revenue concentrates in Dermatology Clinics; patient touchpoints expand fastest through Home Care.
End User:
Age-related immune competence and treatment tolerance shape product selection and dosing protocols.
- Adults:Working-age patients seeking rapid resolution for cosmetic or functional concerns. Occupational exposure in healthcare and food service drives recurrence rates.
- Children:School-age populations with higher spontaneous clearance rates. Parental preference for non-invasive options limits procedural uptake.
- Seniors:Immunosenescence-associated persistent infections. Comorbidity burdens complicate surgical candidacy.
- Healthcare Providers:Institutional purchasers acquiring inventory for clinical deployment. Group purchasing organizations consolidate procurement power.
Adults generate the highest procedure volume; Children represent the most price-elastic segment.
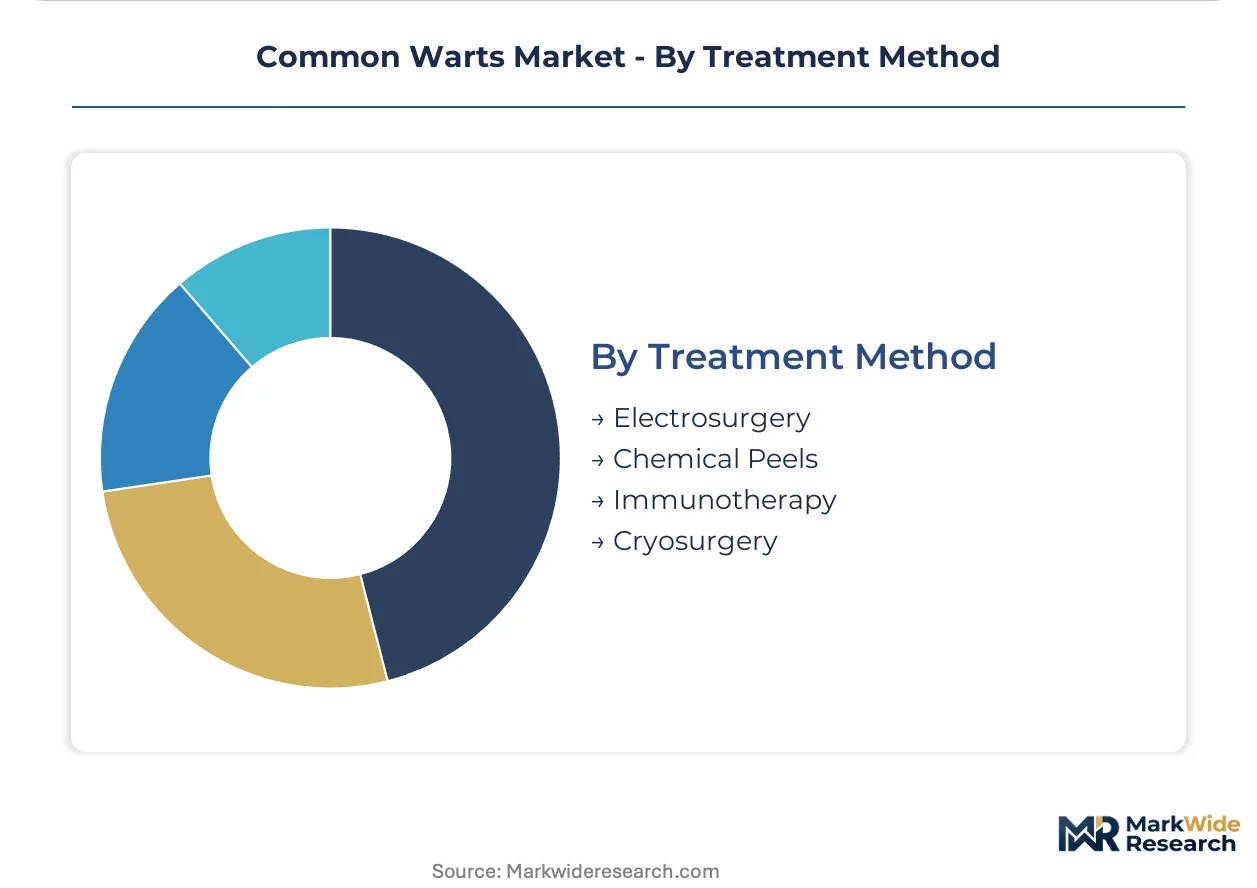
Treatment Method:
Maturity of clinical evidence and regulatory clearance timelines differentiate professional-grade interventions.
- Cryosurgery:Established tissue destruction through controlled freezing. FDA 510(k) pathways enable faster US market entry than EMA MDR assessments.
- Immunotherapy:Topical sensitizers and intralesional antigens stimulating cell-mediated response. PMDA distinct efficacy benchmarks in Japan delay cross-border standardization.
- Electrosurgery:High-frequency current for hemostatic excision. Device sterilization protocol standardization challenges multi-site clinic operators.
- Chemical Peels:Trichloroacetic acid and similar agents for superficial destruction. Lower efficacy rates relegate this to adjuvant status.
Cryosurgery anchors current practice patterns; Immunotherapy claims the steepest expansion trajectory as novel pathways advance through regulatory review.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of cryotherapy devices and immunomodulatory compounds clusters in Germany and the United States, while patient consumption concentrates in markets with dense specialist networks. Japan and the United Kingdom import finished formulations while developing domestic distribution infrastructure.
United States
Dermatology clinic density in Texas and Florida drives procedural volume for laser and cryotherapy modalities. FDA accelerated pathways compress immunotherapy development timelines, though reimbursement code fragmentation complicates revenue cycle management. The Dallas-Fort Worth metro anchors adoption of portable laser platforms among mid-sized practice groups.
Germany
EMA MDR conformity assessments extend approval cycles for cryotherapy devices beyond traditional predicate pathways. German notified bodies demand prospective clinical studies for class IIa devices previously cleared through equivalence claims. The Rhine-Ruhr region concentrates distribution networks serving adjacent European markets.
Japan
PMDA maintains distinct efficacy benchmarks for combination therapies that delay cross-border product standardization. Dense specialist networks in Tokyo and Osaka accelerate adoption of minimally invasive interventions. Kanto region clinics deploy cryotherapy most intensively due to favorable procedural reimbursement structures.
United Kingdom
Pharmacy channel penetration for salicylic acid formulations expands self-treatment options and reduces clinic dependency. MHRA alignment with EMA MDR frameworks imposes parallel evidence requirements on device introductions. London-based dermatology groups pilot telehealth triage protocols to manage specialist appointment constraints.
France
ANSM oversight of topical immunotherapy approvals maintains conservative clinical evidence standards. Regional hospital networks in Île-de-France handle complex or immunocompromised cases requiring surgical intervention. Parisian academic medical centers concentrate research activity for novel sensitizing agents.
Common Warts Market Vendor Landscape
The competitive structure tilts toward pharmaceutical incumbents with diversified dermatology portfolios. Market concentration remains moderate, with established players leveraging regulatory expertise and distribution scale against emerging specialty firms. Three archetypes dominate: diversified healthcare conglomerates with in-house immunomodulatory production, pure-play dermatology specialists focused on topical innovation, and device manufacturers modularizing treatment delivery systems. Competitive moves center on portfolio diversification into combination therapy formats and geographic expansion through distributor partnerships.
Among diversified pharmaceutical conglomerates, GlaxoSmithKline plc and Merck & Co., Inc. exemplify scale-driven positions anchored by broad therapeutic portfolios. Verrica Pharmaceuticals occupies a specialist archetype focused narrowly on dermatology indications. Bayer AG sits within the consumer health crossover tier, competing across prescription and over-the-counter channels through retail pharmacy networks.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Merck & Co., Inc. |
| Verrica Pharmaceuticals |
| Bayer AG |
| Johnson & Johnson |
| Sanofi S.A. |
| Aclaris Therapeutics, Inc. |
| Bausch Health Companies Inc. |
| Nielsen BioSciences |
| Others |
Supply Flow & Price Mechanics
Liquid nitrogen procurement costs cascade through dermatology clinic pricing tiers, with supply chain concentration in industrial gas production hubs determining regional cost differentials for cryotherapy-dependent practices across the United States, Germany, and Japan.
Pricing Analysis
Margin tightening in procedural tiers reflects liquid nitrogen supply chain volatility and reimbursement code fragmentation across US payor networks. Three-tier pricing structure across premium laser platforms, standard cryotherapy devices, and economy topical formulations separates patients by treatment setting and lesion severity. Cost compression in device-dependent tiers accelerates because German and French distributors delay introductions to accumulate EMA MDR post-market surveillance records. Home care patients exhibit highest price sensitivity, while hospital-affiliated dermatology units demonstrate lowest sensitivity due to consolidated procurement through group purchasing organizations.
Supply Chain Analysis
Regional distribution centers in the Rhine-Ruhr region and Dallas-Fort Worth metro anchor hub-and-spoke patterns for cryotherapy device fulfillment. Manufacturing concentrates in Germany, the United States, and Japan for immunomodulatory compounds and laser platforms. Raw material dependencies span liquid nitrogen production, diode laser components, and salicylic acid feedstocks. Single-source vulnerability in specialized laser diode arrays creates procurement risk for portable platform assemblers. Distribution runs through specialist medical device distributors serving dermatology clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable laser platforms are displacing legacy cryotherapy infrastructure in mid-sized dermatology groups, compressing capital deployment timelines and reshaping vendor relationships across Texas and Florida adoption clusters.
For Market Incumbents: Anticipate substitution pressure from modular laser architectures by securing backward integration into diode component supply and accelerating FDA 510(k) pathway submissions for combination therapy formats. Defensive positioning requires channel control through exclusive distribution agreements with German and Japanese specialist clinic networks. Capacity addition in Kanto region device servicing infrastructure addresses PMDA compliance friction. For New Entrants and Emerging Players: Rural dermatology practices in the United Kingdom represent an underserved buyer archetype with constrained specialist appointment availability and unmet demand for telehealth-integrated triage protocols. White-space targets include over-the-counter immunomodulatory adjuncts in European pharmacy chains and portable laser leasing programs for independent Texas practices. Direct-to-consumer diagnostic application partnerships offer the most penetrable go-to-market angle. For Investors and Strategic Acquirers: FDA accelerated pathway designations for novel immunotherapy candidates are the leading indicator that clinical differentiation timelines are compressing and first-mover premiums are expanding. Long-term viability favors platforms with regulatory expertise spanning FDA, EMA MDR, and PMDA frameworks. Acquisition target archetypes include specialty dermatology firms with in-house immunomodulatory production and European distributors with accumulated post-market surveillance records. Watch PMDA combination therapy approval velocity as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Technical Documentation Investment | German notified bodies now demand prospective studies for class IIa cryotherapy devices previously cleared through predicate comparison. |
| Portable Laser Platform Modularization | Texas and Florida mid-sized dermatology groups adopt configurable diode-cooling-control subsystems faster than hospital-affiliated networks. |
| Telehealth Triage Protocol Development | London-based dermatology groups pilot remote lesion assessment to manage specialist appointment constraints and reserve procedural capacity. |
| Combination Therapy Regulatory Positioning | Japan PMDA distinct efficacy benchmarks create first-mover advantages for integrated topical-device protocols in Kanto region clinics. |
| Retail Channel Immunomodulatory Expansion | Over-the-counter adjuvants represent underdeveloped shelf space in European pharmacy chains beyond salicylic acid formulations. |
Methodological Framework
FDA filings, EMA MDR submission databases, and ClinicalTrials.gov formed the secondary backbone for this analysis, supplemented by customs records tracking cryotherapy device trade flows. Primary interviews with dermatology clinic operators, biomedical equipment procurement managers, and regulatory affairs specialists at device manufacturers combined with secondary validation through bottom-up and top-down triangulation approaches.
Historical trendline analysis across cryotherapy procedure volume, laser platform installations, and topical formulation pharmacy sales established baseline growth patterns. Segmentation dimensions modeled include product type, application setting, end user age cohort, and treatment method maturity. CAGRs were derived from regression analysis against procedural reimbursement trends and device adoption curves, incorporating PMDA approval velocity and EMA MDR transition timelines as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory divergence between FDA accelerated pathways and EMA MDR conformity assessments. Outputs reflect documented assumptions regarding specialist network density expansion and liquid nitrogen supply chain stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Global Radiodermatitis Market
Dermatology
Prescription Dermatology Therapeutics Market
Dermatology
Pigmented Lesion Treatment Market
Dermatology
Alopecia Treatment (Hair Loss) Market
Dermatology
Derma Rollers Market
Dermatology
Japan Scar Treatment Market
Dermatology
Global Dermatology Lasers Market
Dermatology
Acne Scar Treatment Market
Dermatology
Scar Treatment Oils Market
Dermatology
Seborrheic Keratosis Treatment Market
Dermatology
Skin Cancer Market
Dermatology
Keratoacanthoma Market
Dermatology
Keloid Treatment Market
Dermatology
Rosacea Treatment Market
Dermatology
Folliculitis Market
Dermatology
Global Dermatitis Herpetiformis Market