
 Dermatological Products Market | 2026-2036
Dermatological Products Market Size, Share, and Industry Trends Forecast 2026-2036
Dermatological Products Market Analysis
Consumer self-pay dermatology is redrawing demand flows away from traditional hospital procurement. Johnson & Johnson Services, Inc. anchors its position through broad retail pharmacy distribution. Galderma differentiates via dedicated aesthetic and prescription skincare portfolios. AbbVie Inc. leverages immunology R&D depth to sustain biologic dermatology leadership.
Dermatological products comprise topical, oral, injectable, and transdermal formulations designed to treat acne, psoriasis, eczema, and rosacea through active pharmaceutical ingredients delivered at specified concentrations and pH levels. These products serve therapeutic and cosmetic purposes across prescription and over-the-counter channels, with efficacy measured by lesion reduction, barrier repair, and anti-inflammatory response. Creams and ointments occupy the largest volume share due to established reimbursement and patient familiarity, while injectable biologics capture the fastest value expansion driven by severe psoriasis and atopic dermatitis protocols. Transdermal delivery systems are gaining pipeline investment as manufacturers seek alternatives to first-pass metabolism limitations.
FDA bioequivalence standards for topical generics and EPA manufacturing emission guidelines constrain formulation switching and production site selection. EMA's MDR and REACH compliance requirements add certification burdens for European market entry, while WHO prequalification programs shape access pathways in lower-income settings. Stakeholders must monitor biosimilar interchangeability rulings and state-level pharmacy benefit carve-outs that could redirect volume toward lower-cost alternatives.
Market Dynamics
Specialty dermatology practice consolidation in the United States is compressing procurement timelines and elevating bulk purchasing power, forcing manufacturers to reconfigure distribution contracts and rebate structures around integrated delivery networks rather than independent physician offices.
Growth Catalysts
- FDA streamlined approval pathways for topical generics:Abbreviated new drug applications reduce time-to-market for reformulated dermatological actives, expanding the competitive supplier base.
- Consumer self-pay dermatology:Patients bypass traditional hospital procurement channels, creating direct-to-clinic demand flows that reward specialized aesthetic and prescription skincare portfolios.
- Injectable biologics:Severe psoriasis and atopic dermatitis treatment protocols drive value expansion in immunology-directed therapies.
Market Restraints
- API cost volatility:Corticosteroid and retinoid active pharmaceutical ingredients face supply concentration in Indian and Chinese manufacturing clusters.
- REACH compliance burdens:ECHA registration requirements for novel excipients extend European market entry timelines by 18-24 months.
- Transdermal delivery limitations:First-pass metabolism constraints restrict bioavailability of large-molecule therapeutics through skin penetration.
Strategic Opportunities
- Transdermal delivery systems:Microneedle and iontophoresis technologies converge to enable biologic administration without injection.
- Brazilian aesthetic clinic expansion:ANVISA regulatory harmonization with FDA standards accelerates product registration for premium skincare lines.
- Pharmacy benefit carve-outs:State-level Medicaid restructuring in the United States creates pathways for biosimilar interchangeability at lower net costs.
Industry Challenges
- Formulation scientist scarcity:Specialized expertise in topical bioequivalence testing and Q1/Q2 sameness criteria commands premium compensation.
- Legacy ERP integration:Track-and-trace compliance with DSCSA serialization requirements strains smaller manufacturers' IT infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dermatological Products Market |
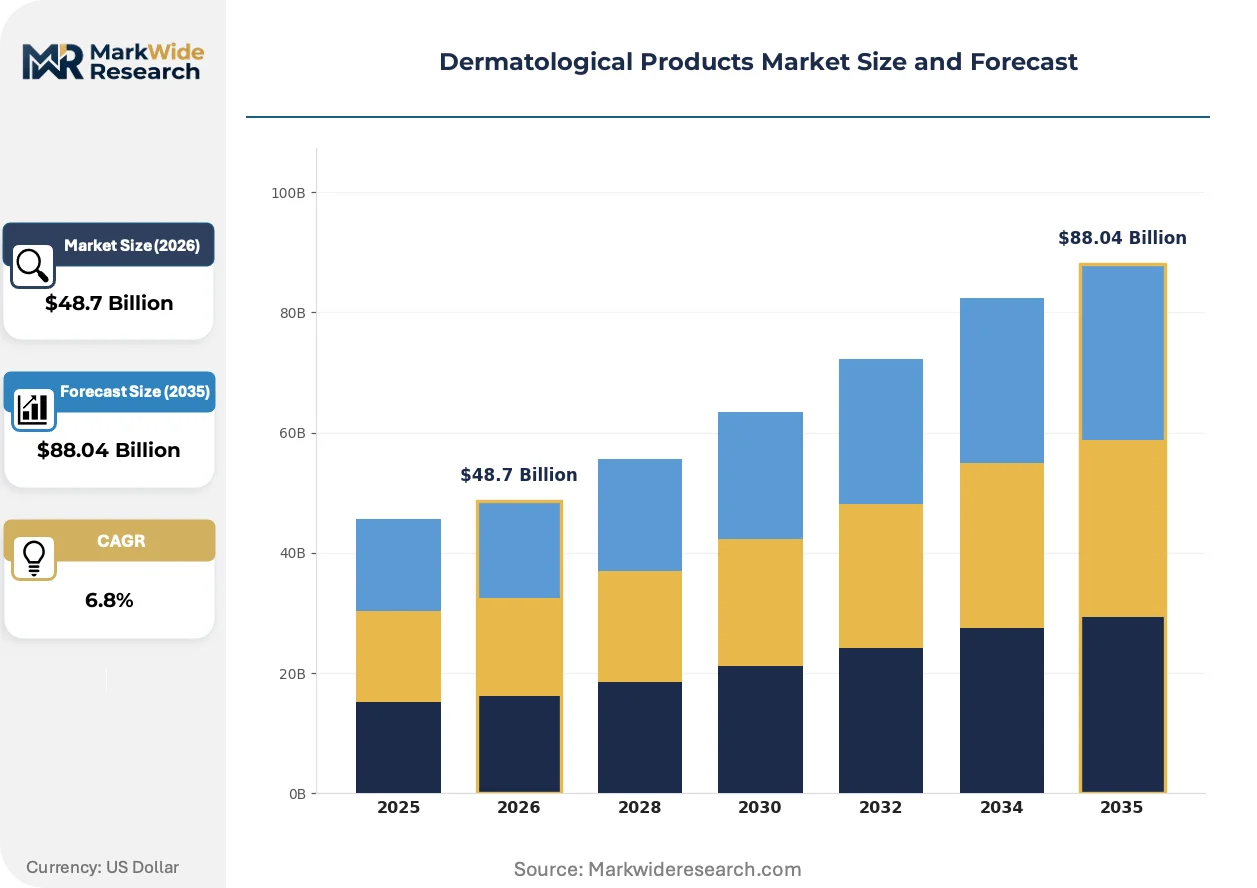
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Gels, Ointments, Lotions Formulation: Topical, Oral, Injectable, Transdermal Therapy Area: Acne, Psoriasis, Eczema, Rosacea End User: Hospitals, Clinics, Dermatology Centers, Pharmacies |
| Companies Covered | AbbVie Inc., Novartis AG, Pfizer Inc., Johnson & Johnson Services, Inc., Galderma, GSK plc, Eli Lilly and Company, LEO Pharma A/S, Sun Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dermatological Products Market Emerging Trajectories
Biologic therapy administration and topical delivery technologies are decomposing traditional boundaries between aesthetic and therapeutic dermatology, while regulatory harmonization efforts compress geographic expansion timelines for multi-market portfolios.
Microneedle arrays for transdermal biologic delivery is decomposing the injection-versus-topical dichotomy that has structured dermatological product categories for decades. Aesthetic dermatology clinics in South Korea and the United States are piloting dissolvable hyaluronic acid microneedles for at-home peptide delivery. This convergence is compressing the addressable market for traditional injectable administration in mild-to-moderate indications.
EMA's Medical Device Regulation reclassification of certain dermal fillers and energy-based devices is tightening clinical evidence requirements for aesthetic dermatology products marketed in Europe. Manufacturers must now submit prospective safety data rather than relying on predicate device equivalence. The aesthetic injectables segment is responding by accelerating post-market surveillance investments and withdrawing marginal SKUs from European distribution.
Direct-to-consumer telehealth platforms are fragmenting the traditional dermatology referral channel, with patients initiating prescription skincare consultations through mobile applications rather than primary care physicians. This disintermediation is most pronounced in the United States, where state-level scope-of-practice expansions enable nurse practitioners to prescribe independently, compressing the physician gatekeeper role in acne and rosacea management.
Dermatological Products Market Segmentation
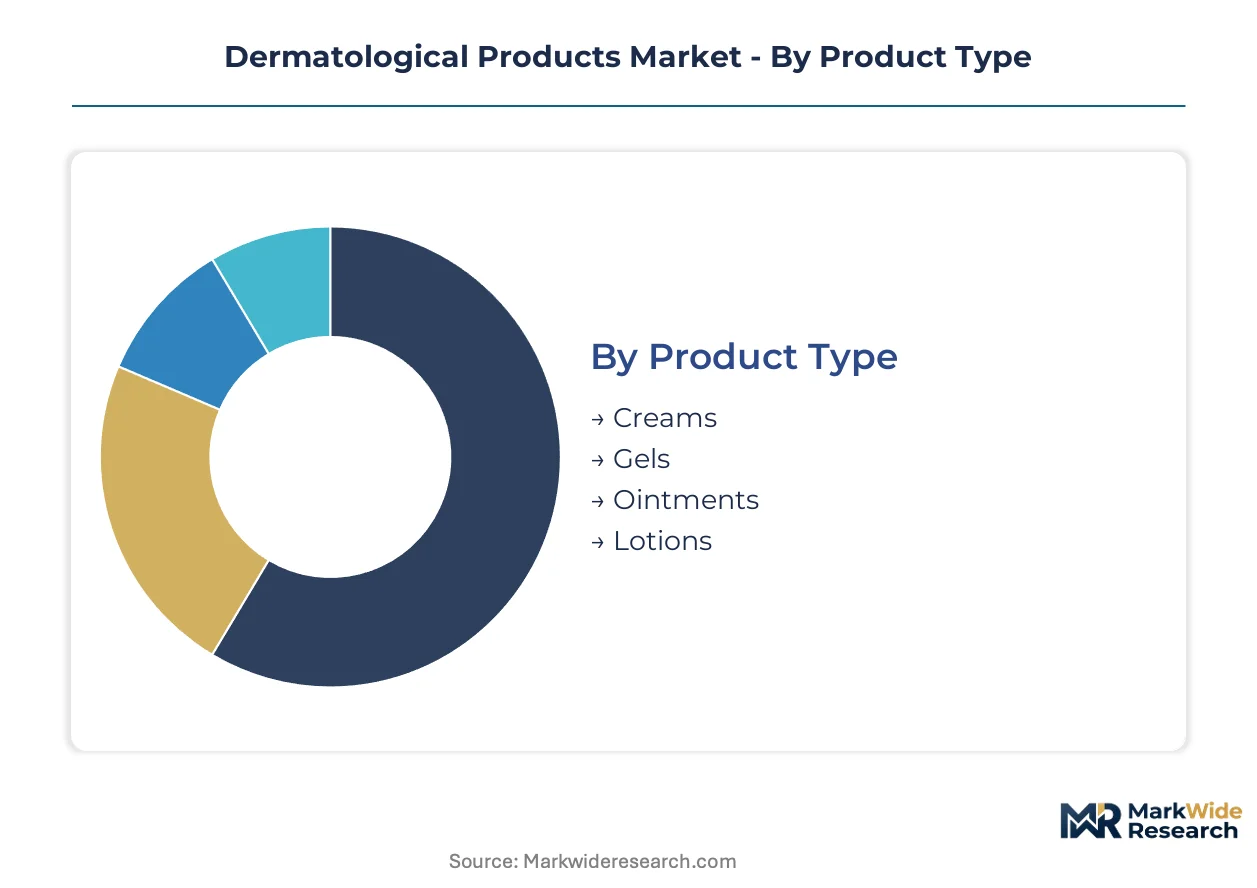
Dermatological products fragment across four intersecting dimensions that determine distribution strategy and reimbursement pathways. Product type and formulation dictate manufacturing complexity, while therapy area and end user shape pricing power and regulatory exposure.
Product Type:
Creams and ointments flow predominantly through domestic wholesale channels, whereas gels and lotions carry heavier export orientation due to stability advantages in tropical climates.
- Creams:Water-in-oil or oil-in-water emulsions with 15-40% lipid content deliver corticosteroids and antibiotics through established hospital procurement contracts. Demand concentrates in United States dermatology centers where bulk purchasing agreements with integrated delivery networks compress unit economics.
- Ointments:Occlusive petrolatum-based vehicles with minimal water content maximize drug penetration for hyperkeratotic conditions. Export volumes dominate to Middle Eastern markets where arid climates favor heavy barrier formulations over lighter alternatives.
- Gels:Hydroalcoholic matrices suspend retinoids and benzoyl peroxide with rapid drying properties suited to acne protocols in humid Asian markets.
- Lotions:Low-viscosity fluid preparations facilitate scalp and large-surface application, finding strongest uptake in European retail pharmacy self-pay segments.
Creams hold the largest share; momentum sits with gels as tropical market access expands.
Formulation:
Cost tiers separate premium biologic injectables from commoditized topical generics, with oral formulations occupying an intermediate position shaped by patent cliffs.
- Topical:Semisolid and liquid preparations applied directly to skin lesions account for volume leadership through FDA ANDA pathways that enable rapid generic substitution. United States retail pharmacies drive demand concentration as 90-day dispensing programs expand.
- Injectable:Monoclonal antibodies and fusion proteins targeting IL-17 and IL-23 pathways command premium pricing in severe psoriasis protocols. Specialty pharmacy distribution and prior authorization requirements limit penetration to insured populations in developed markets.
- Oral:Systemic retinoids, immunosuppressants, and JAK inhibitors bridge topical failure and biologic escalation, with demand clustering in markets with restrictive biologic reimbursement.
- Transdermal:Microneedle patches and iontophoresis devices circumvent first-pass metabolism for peptide delivery, currently piloting in South Korean aesthetic clinics with regulatory pathways still stabilizing.
Topical formulations dominate volume; injectable biologics are expanding most quickly through severe atopic dermatitis label expansions.
Therapy Area:
Application maturity varies sharply, with acne and eczema representing high-volume chronic conditions while psoriasis and rosacea command premium positioning through biologic and medical device adjacencies.
- Acne:Androgen-driven sebaceous hyperplasia and Cutibacterium acnes colonization create persistent demand across adolescent and adult demographics. Over-the-counter benzoyl peroxide and adapalene formulations flow through United States mass retail channels with minimal prescription friction.
- Psoriasis:Autoimmune keratinocyte hyperproliferation requiring long-term immunomodulation generates the highest per-patient revenue through biologic maintenance therapy. United States specialty dermatology practices concentrate prescribing authority for systemic agents.
- Eczema:Atopic dermatitis with barrier dysfunction and Th2 inflammation drives volume through pediatric populations and corticosteroid rotation protocols.
- Rosacea:Neurovascular and inflammatory facial dermatosis with limited curative options maintains steady prescription demand through topical metronidazole and ivermectin.
Acne holds the largest share; momentum sits with psoriasis as IL-17 and IL-23 inhibitor pipelines deepen.
End User:
Customer type determines procurement mechanics, with institutional buyers extracting volume discounts while direct-to-consumer channels preserve margin.
- Hospitals:Inpatient dermatology services and emergency department consultations for severe drug reactions and infectious complications drive formulary inclusion requirements. United States 340B pricing programs distort procurement economics for qualifying facilities.
- Dermatology Centers:Consolidated specialty practices with in-office dispensing capabilities capture premium self-pay aesthetic and therapeutic revenues. United States private equity-backed roll-ups concentrate purchasing power across multi-site networks.
- Clinics:Primary care and urgent care settings handle first-line acne and eczema with generic prescribing, representing price-sensitive volume.
- Pharmacies:Retail and mail-order channels fragment further between prescription fulfillment and front-of-store cosmeceutical placement.
Dermatology centers hold the largest share; momentum sits with pharmacies as telehealth prescribing expands direct-to-patient delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty dermatology practice consolidation and aesthetic clinic expansion are redrawing procurement geography across major demand centers. Buyer archetypes concentrate around integrated delivery networks in the United States, retail pharmacy chains in Germany, and direct-to-consumer telehealth platforms in South Korea.
United States
Private equity-backed dermatology roll-ups concentrate purchasing power across multi-site networks in Florida, Texas, and California. The FDA's streamlined ANDA pathways for topical generics accelerate generic substitution in 90-day retail pharmacy dispensing programs. Greater Boston and the Research Triangle host biologic R&D clusters where IL-17 and IL-23 inhibitor pipelines deepen.
Germany
Statutory health insurance reimbursement protocols sustain high-volume prescribing for corticosteroid creams and calcineurin inhibitors through community pharmacy networks. EMA's MDR reclassification of dermal fillers tightens clinical evidence requirements for aesthetic device market entry. The Rhine-Ruhr corridor anchors manufacturing concentration for excipient supply to European formulation sites.
Japan
Aging demographics and atopic dermatitis prevalence drive biologic adoption in severe psoriasis protocols through PMDA-accelerated approval channels. METI's regulatory harmonization initiatives compress registration timelines for transdermal delivery innovations. The Kansai region around Osaka hosts contract manufacturing organizations serving Asia-Pacific distribution.
Brazil
ANVISA regulatory harmonization with FDA standards accelerates product registration for premium skincare lines targeting aesthetic clinic expansion in São Paulo and Rio de Janeiro. Middle-class consumption growth shifts demand toward prescription retinoids and medical-grade sunscreens. The São Paulo state cluster concentrates import distribution infrastructure for Latin American re-export.
South Korea
K-beauty export momentum and domestic aesthetic clinic density create pilot markets for microneedle peptide delivery systems. MFDS fast-track designations for novel transdermal technologies attract venture investment to Seoul Capital Area R&D facilities. Busan-Ulsan hosts contract manufacturing for dissolvable hyaluronic acid array production.
Dermatological Products Market Vendor Landscape
Player mix skews toward diversified pharmaceutical conglomerates with immunology depth alongside pure-play dermatology specialists with aesthetic focus. Market structure exhibits tiered consolidation where biologic innovators command premium positioning and topical generic manufacturers compete on FDA ANDA execution speed. Strategic archetypes include immunology-directed biologic developers, retail pharmacy distribution anchors, and aesthetic-clinic-focused skincare portfolios. Competitive moves center on specialty practice consolidation partnerships and transdermal delivery technology licensing.
Within the biologic innovation tier, AbbVie Inc. and Eli Lilly and Company exemplify immunology R&D depth applied to IL-17 and IL-23 pathway modulation. Johnson & Johnson Services, Inc. anchors retail pharmacy distribution scale across mass-market and professional channels. Galderma occupies a position bridging prescription therapeutic and aesthetic skincare portfolios through dedicated clinic-focused business units.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Novartis AG |
| Pfizer Inc. |
| Johnson & Johnson Services, Inc. |
| Galderma |
| GSK plc |
| Eli Lilly and Company |
| LEO Pharma A/S |
| Sun Pharmaceutical Industries Ltd. |
| Others |
Supply Flow & Price Mechanics
FDA bioequivalence standards for topical generics simultaneously gate supplier qualification and compress price differentiation between reference-listed drugs and abbreviated new drug application entrants. This regulatory threshold forces manufacturers to absorb specialized bioequivalence testing costs while buyers exploit substitutability to extract rebates from integrated delivery networks.
Pricing Analysis
Cost-plus contracts with corticosteroid and retinoid API indexation dominate procurement between Indian and Chinese manufacturers and United States formulators. Three-tier pricing structure across premium biologic injectables, standard oral systemics, and economy topical generics separates insured specialty pharmacy channels from 90-day retail dispensing and cash-pay clinic segments. Price compression runs through the topical generic tier as FDA ANDA approvals accelerate therapeutic equivalence challenges. Dermatology centers with in-office dispensing capabilities exhibit lowest price sensitivity, while primary care clinics and Medicaid plans drive aggressive generic substitution.
Supply Chain Analysis
Strategic stockpiling of corticosteroid APIs and retinoid precursors prevails among United States formulators wary of Indian and Chinese supply disruptions, whereas just-in-time inventory governs finished goods distribution through domestic wholesale channels. Active pharmaceutical ingredient manufacturing concentrates in India, China, and selected European sites, with formulation finishing clustered in the United States, Germany, and Japan. Supply chain risk centers on single-source dependencies for high-potency corticosteroid APIs subject to environmental regulatory enforcement. Distribution runs through integrated delivery networks and specialty pharmacy channels rather than traditional hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in topical Q1/Q2 sameness criteria and bioequivalence testing commands compensation premiums that constrain formulation capacity expansion, creating persistent bottlenecks for generic entrants and biologic developers alike.
For Market Incumbents: Consolidate formulation scientist teams through targeted acquisition of boutique bioequivalence testing laboratories in Greater Boston and the Research Triangle. Deepen vertical integration into corticosteroid API production to mitigate Indian and Chinese supply concentration. Lock in multi-year exclusive distribution partnerships with private equity-backed dermatology roll-ups before biosimilar interchangeability rulings expand competitive substitution. For New Entrants and Emerging Players: Anchor in Brazilian aesthetic clinic networks where ANVISA-FDA harmonization compresses registration timelines for premium skincare portfolios. Target the transdermal microneedle peptide delivery segment piloting in South Korean clinics, where regulatory pathways remain unsettled and incumbent biologic manufacturers lack topical formulation heritage. Pursue direct-to-consumer telehealth platform partnerships to bypass traditional physician gatekeeper channels in acne and rosacea management. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biologic injectable manufacturing as IL-17 and IL-23 inhibitor pipelines deepen and cold-chain infrastructure requirements expand. Viable acquisition targets include mid-cap topical generic specialists with FDA ANDA execution speed and established integrated delivery network rebate contracts. Watch FDA biosimilar interchangeability rulings and state-level pharmacy benefit carve-outs as signals that margin structures in immunology-directed dermatology are compressing.| Strategic Initiative | Industry Significance |
|---|---|
| Transdermal Delivery Technology Licensing | Microneedle and iontophoresis patents enable biologic administration without injection infrastructure. |
| Specialty Practice Consolidation Partnership | Multi-site dermatology network contracts concentrate purchasing power and lock in formulary position. |
| FDA ANDA Execution Acceleration | Rapid bioequivalence approval captures first-mover advantage in topical generic substitution waves. |
| API Backward Integration | Captive corticosteroid and retinoid production mitigates Indian and Chinese supply volatility. |
| Aesthetic Clinic Direct Distribution | In-office dispensing capabilities preserve margin in self-pay premium skincare segments. |
Methodological Framework
Operator-level perspectives from dermatology practice administrators, specialty pharmacy procurement directors, FDA regulatory affairs consultants, and topical formulation scientists anchored the qualitative base. Primary interviews triangulated with secondary validation from FDA ANDA filings, EMA MDR submission databases, ClinicalTrials.gov dermatology trial registries, and United States 340B pricing program disclosures. Bottom-up patient-flow modeling across therapy areas converged with top-down pharmaceutical revenue estimates to establish market sizing boundaries.
Sensitivity analysis tested forecast robustness across API cost volatility scenarios, biosimilar interchangeability adoption curves, and telehealth prescribing penetration rates. Segmentation dimensions modeled include product formulation type, therapy area severity tier, distribution channel structure, and regional regulatory cluster. CAGRs derived from patient population epidemiology, treatment protocol evolution, and pricing trajectory assumptions across the projection horizon. Specific inputs incorporated IL-17 and IL-23 inhibitor pipeline advancement timelines and microneedle regulatory pathway stabilization in South Korea.
Underlying assumptions cover FDA ANDA approval velocity, corticosteroid API supply stability, and specialty practice consolidation pace, with deviation risk concentrated in biosimilar interchangeability rulings and state-level Medicaid pharmacy benefit restructuring. Revision becomes warranted when biosimilar substitution rates or transdermal delivery regulatory approvals cross threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Porokeratosis Treatment Market
Dermatology
Scar Treatment Oils Market
Dermatology
Skin Excision Market
Dermatology
Dermatology Cryosurgery Units Market
Dermatology
Scar Treatment Market
Dermatology
US and Canada Skin Cancer Dermatology Market
Dermatology
Skin Cancer Market
Dermatology
Athletes Foot (Tinea Pedis) Treatment Market
Dermatology
Rosacea Treatment Market
Dermatology
Microneedling Market
Dermatology
Folliculitis Market
Dermatology
Derma Rollers Market
Dermatology
Acne Vulgaris Market
Dermatology
Global Dermatological OTC Drugs Market
Dermatology
Dermabrasion Market
Dermatology
Acne Vulgaris Treatment Market