
 Athletes Foot (Tinea Pedis) Treatment Market | 2026-2036
Athletes Foot (Tinea Pedis) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Athletes Foot (Tinea Pedis) Treatment Market Insights
Asset-light licensing and contract manufacturing is fragmenting competitive dynamics in dermatological therapeutics. Bayer AG leverages its consumer health infrastructure to sustain shelf dominance across European and North American retail networks. Glenmark Pharmaceuticals Limited anchors its position through specialized generic manufacturing of terbinafine and clotrimazole formulations. Sun Pharmaceutical Industries Ltd competes on cost-optimized production scale, extending distribution into emerging markets where price sensitivity shapes purchasing decisions.
Athletes foot treatment encompasses topical and oral pharmaceutical interventions targeting Trichophyton rubrum and epidermophyton floccosum infections of the foot, with allylamine and azole compounds disrupting fungal cell membrane ergosterol biosynthesis at concentrations typically ranging from one to ten percent in cream or spray vehicles. The primary commercial purpose centers on symptom resolution and infection eradication across outpatient, retail, and self-directed care settings. Cream formulations occupy the largest revenue pool due to patient familiarity and clinician prescribing habits, while prescription medications capture concentrated margins where resistant or recurrent infections necessitate oral terbinafine or itraconazole therapy. Online retail channels represent the fastest-growing distribution vector, driven by subscription models and telehealth prescription fulfillment that bypass traditional pharmacy counter visits.
The FDA oversees OTC monograph compliance and new drug application pathways for topical antifungals, while the EMA's Committee for Medicinal Products for Human Use evaluates centralized marketing authorizations across EU member states. Health Canada and the TGA enforce comparable efficacy and safety benchmarks, creating a multi-jurisdictional compliance burden that favors companies with established regulatory affairs capabilities. Stakeholders must monitor evolving OTC switch dynamics and telehealth prescribing regulations that could redistribute volume between pharmacy and direct-to-consumer channels without warning.
Market Dynamics
The FDA's OTC monograph reform is collapsing traditional pathways for topical antifungal clearance, forcing manufacturers to restructure clinical evidence packages and accelerate direct-to-consumer channel investments.
Growth Catalysts
- Telehealth prescribing expansion:Digital health platforms in the United States now route dermatology consultations to retail fulfillment, bypassing physical clinic visits for recurrent tinea pedis cases.
- REACH compliance harmonization:The European Chemicals Agency's streamlined substance evaluations are reducing redundant toxicity testing burdens for allylamine-based formulations entering EU markets.
- Podiatric care integration:Sports medicine clinics in Australia are embedding antifungal prophylaxis into athlete screening protocols, creating institutional prescription pull-through.
Market Restraints
- Active pharmaceutical ingredient concentration:Three contract manufacturers in India control bulk terbinafine supply, exposing formulators to input cost volatility and qualification delays.
- Recurrence rate limitations:Topical azoles demonstrate incomplete mycological cure in plantar moccasin-type infections, restricting revenue per patient to single-course purchases.
- OTC switch friction:Health Canada's requirement for real-world evidence submissions extends prescription-to-nonprescription transition timelines by 18-24 months.
Strategic Opportunities
- Rural pharmacy networks:Brazil's ANVISA is fast-tracking simplified registrations for fixed-dose combination creams targeting underserved interior municipalities.
- Subscription fulfillment models:Direct-to-consumer platforms in Germany are bundling recurrence-prevention sprays with diagnostic kits, capturing lifetime value from chronic sufferers.
- Photodynamic adjunct therapy:Convergence of topical photosensitizers with LED devices is opening premium positioning for treatment-resistant infections in Japanese aesthetic dermatology channels.
Industry Challenges
- Formulation stability expertise:Shortage of pharmaceutical scientists specializing in hydrophobic drug dispersion is delaying spray vehicle development programs.
- Multi-jurisdictional label harmonization:Divergent pregnancy category classifications across FDA, EMA, and TGA requirements force SKU proliferation and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Athletes Foot (Tinea Pedis) Treatment Market |
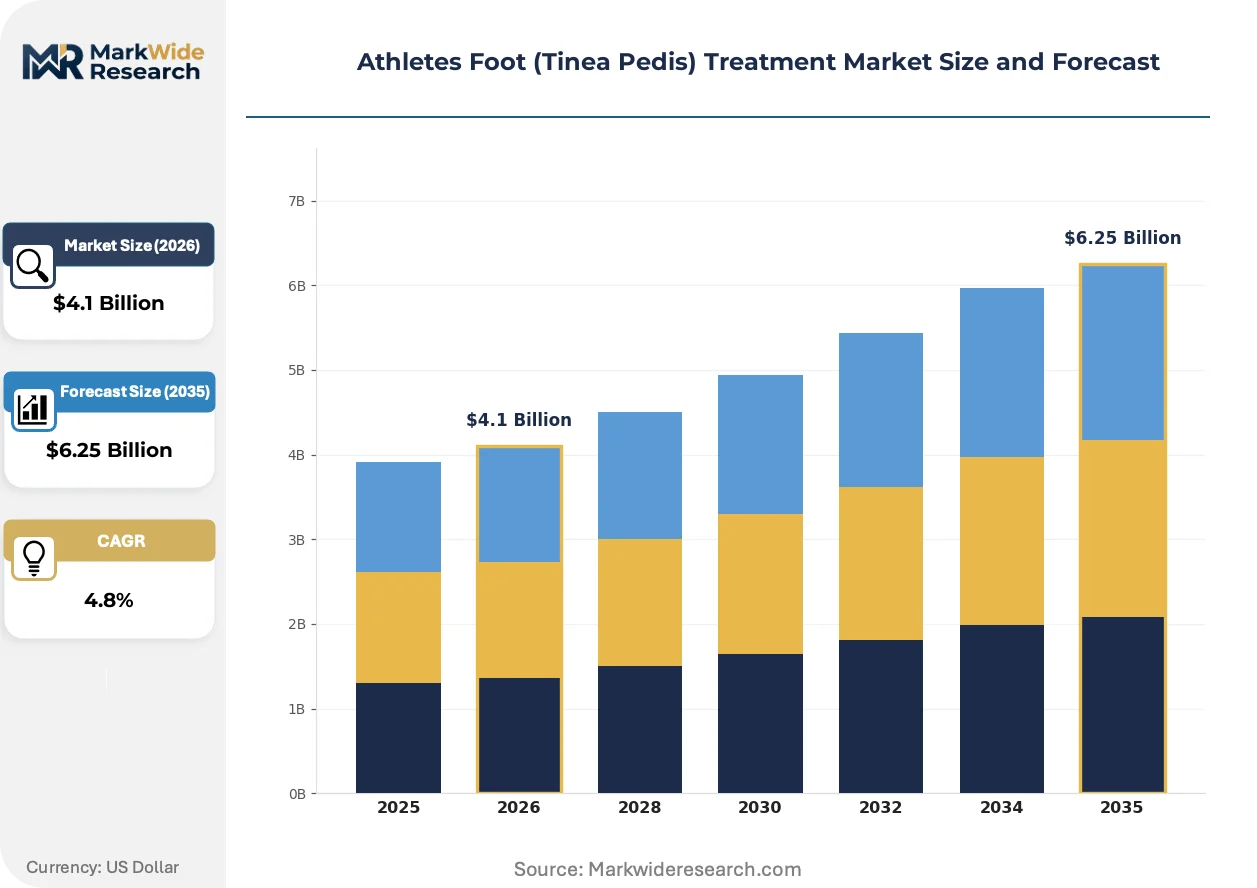
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.25 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Sprays, Powders, Prescription Medications Active Ingredient: Clotrimazole, Terbinafine, Miconazole, Tolnaftate Distribution Channel: Pharmacies, Online Retail, Supermarkets, Health Stores End User: Adults, Children, Athletes, General Population |
| Companies Covered | GlaxoSmithKline plc, Bayer AG, Bausch Health Companies Inc., Glenmark Pharmaceuticals Limited, Novartis AG, Pfizer Inc., Sanofi, Merck & Co., Inc., Sun Pharmaceutical Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Athletes Foot (Tinea Pedis) Treatment Market Trends and Innovations
Formulation science and distribution architecture are undergoing simultaneous transformation, with topical delivery systems and channel access models both compressing traditional competitive moats.
Nanoemulsion carrier technology is collapsing the efficacy gap between prescription and over-the-counter terbinafine concentrations. Dermatology-focused contract manufacturers in South Korea are adopting microfluidic production methods to achieve sub-100 nanometer droplet sizes. This particle reduction is enabling comparable fungal membrane penetration at one-third the active pharmaceutical ingredient load, threatening premium prescription positioning.
The FDA's ongoing OTC monograph reform is eliminating the time-and-extent application pathway for Category I antifungal ingredients. Manufacturers must now submit new drug applications with controlled clinical trials, raising capital requirements for market entry. Smaller generic houses are responding by licensing finished formulations rather than developing proprietary vehicles.
Subscription-based replenishment is displacing episodic pharmacy purchasing among chronic sufferers in the United States. Telehealth platforms integrate diagnostic photo submission with automated 90-day refill cycles, locking patient loyalty before retail intervention. This channel capture is most advanced in states with full practice authority for nurse practitioners prescribing topical antifungals.
Athletes Foot (Tinea Pedis) Treatment Market Segmentation
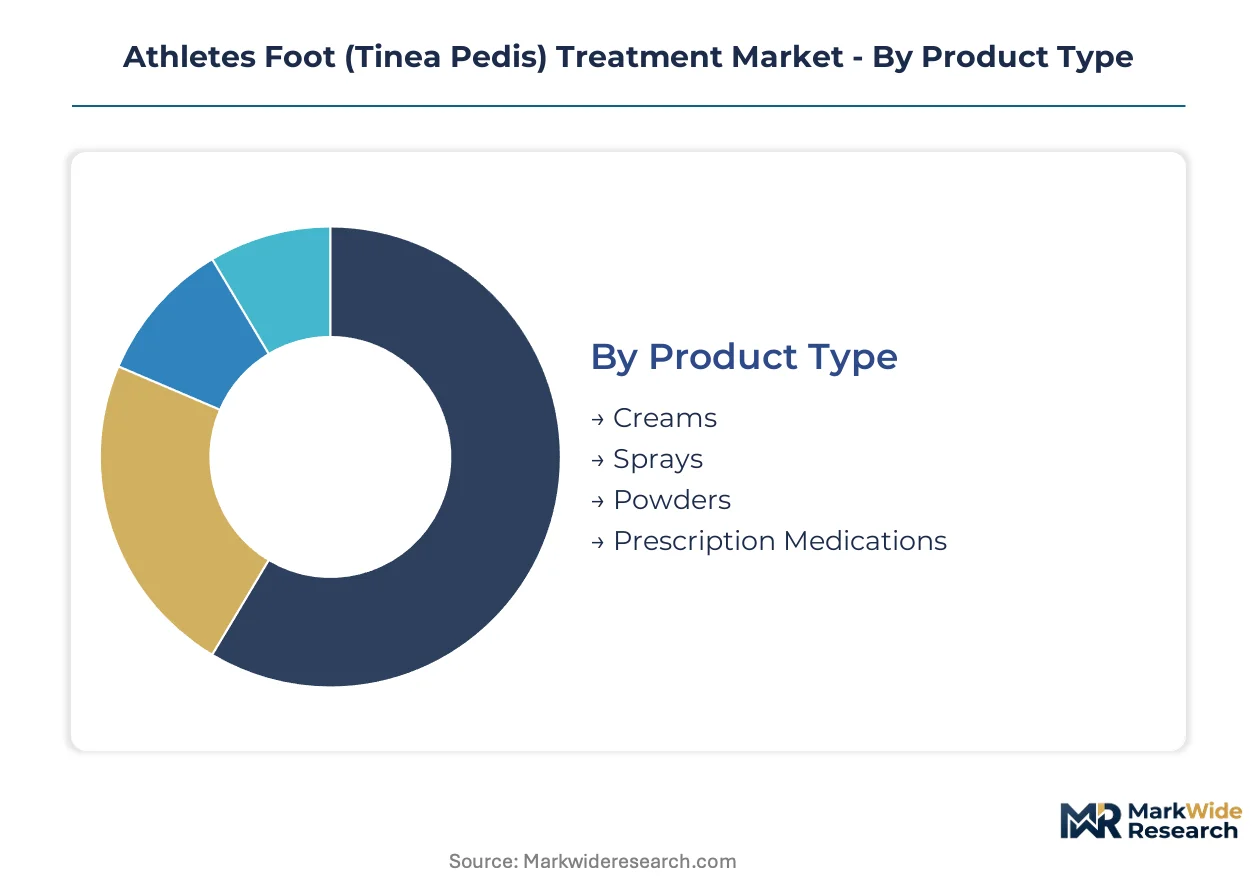
Segmentation in the tinea pedis treatment market determines channel strategy, pricing architecture, and formulation investment priorities. Product format and distribution pathway choices directly shape patient adherence rates and lifetime value capture for manufacturers.
Product Type:
After-sales service intensity varies sharply across formats, with creams requiring minimal patient education while prescription oral therapies demand pharmacovigilance follow-through.
- Creams:Semi-solid emulsion vehicles typically carrying one to ten percent active pharmaceutical ingredient concentration. Demand concentrates in retail pharmacy networks across the United States and Germany, where clinician prescribing habits favor familiar topical formats for interdigital infections. Patient familiarity sustains volume leadership despite slower onset versus sprays.
- Sprays:Aerosol or pump-dispensed solutions enabling application to plantar surfaces without manual rubbing. Sports medicine clinics in Australia are embedding spray formats into athlete screening protocols, creating institutional pull-through for prophylactic use cases. Convenience positioning commands modest price premiums in direct-to-consumer channels.
- Powders:Talc or starch-based carriers with antifungal actives for moisture absorption in footwear and socks. Brazil's ANVISA fast-track registrations target underserved interior municipalities where powder formats address humid climate conditions.
- Prescription Medications:Oral terbinafine or itraconazole tablets for resistant or recurrent infections unresponsive to topical therapy. Health Canada's extended prescription-to-nonprescription transition timelines concentrate margin capture in specialist dermatology practices.
Creams hold the largest share; momentum sits with sprays.
Active Ingredient:
Cost tier differentiation separates allylamine compounds from azole alternatives, with manufacturing scale and patent status determining competitive positioning.
- Terbinafine:Allylamine compound disrupting fungal cell membrane ergosterol biosynthesis through squalene epoxidase inhibition. Three contract manufacturers in India control bulk supply, exposing formulators to input cost volatility and qualification delays for new market entrants.
- Clotrimazole:Imidazole antifungal with broad-spectrum activity against dermatophytes and yeasts. Glenmark Pharmaceuticals anchors manufacturing through specialized generic production for European and North American retail networks.
- Miconazole:Imidazole derivative with additional gram-positive antibacterial activity. Price-sensitive purchasing decisions in emerging markets favor miconazole where terbinafine premiums face reimbursement resistance.
- Tolnaftate:Synthetic thiocarbamate primarily fungistatic rather than fungicidal. Limited prescription uptake restricts tolnaftate to over-the-counter positioning in supermarket and health store channels.
Terbinafine commands the premium tier; tolnaftate occupies economy positioning with steepest expansion trajectory in mass retail.
Distribution Channel:
Customer type segmentation separates acute episodic purchasers from chronic sufferers seeking subscription convenience.
- Pharmacies:Brick-and-mortar retail and hospital outpatient dispensaries with pharmacist consultation access. The FDA's OTC monograph reform is collapsing traditional clearance pathways, forcing restructuring of clinical evidence packages for pharmacy-bound formulations.
- Online Retail:Direct-to-consumer platforms and telehealth-integrated fulfillment services. Subscription-based replenishment is displacing episodic purchasing among chronic sufferers in United States states with full practice authority for nurse practitioners.
- Supermarkets:Mass merchandisers with self-service health and beauty aisles. Shelf space competition favors multi-symptom foot care bundles over standalone antifungal SKUs.
- Health Stores:Specialty retailers emphasizing natural or complementary formulations. REACH compliance harmonization is reducing redundant toxicity testing burdens for allylamine-based products entering EU health store networks.
Pharmacies retain volume leadership; online retail is gaining share fastest through telehealth integration.
End User:
Application context determines formulation preference, with moisture exposure and activity intensity shaping product selection.
- Adults:Working-age population with occupational or recreational footwear exposure. Podiatric care integration in sports medicine clinics drives sustained prescription and non-prescription uptake across adult demographics.
- Athletes:Competitive and recreational participants with repetitive trauma and communal facility exposure. Photodynamic adjunct therapy convergence is opening premium positioning for treatment-resistant infections in Japanese aesthetic dermatology channels serving athlete populations.
- General Population:Non-athletic adults and elderly with age-related immune compromise or diabetes-related susceptibility. Recurrence rate limitations for topical azoles restrict revenue per patient to single-course purchases in this broad segment.
- Children:Pediatric patients requiring lower concentration formulations and age-appropriate vehicles. Multi-jurisdictional label harmonization challenges force SKU proliferation where pregnancy category classifications diverge across FDA, EMA, and TGA requirements.
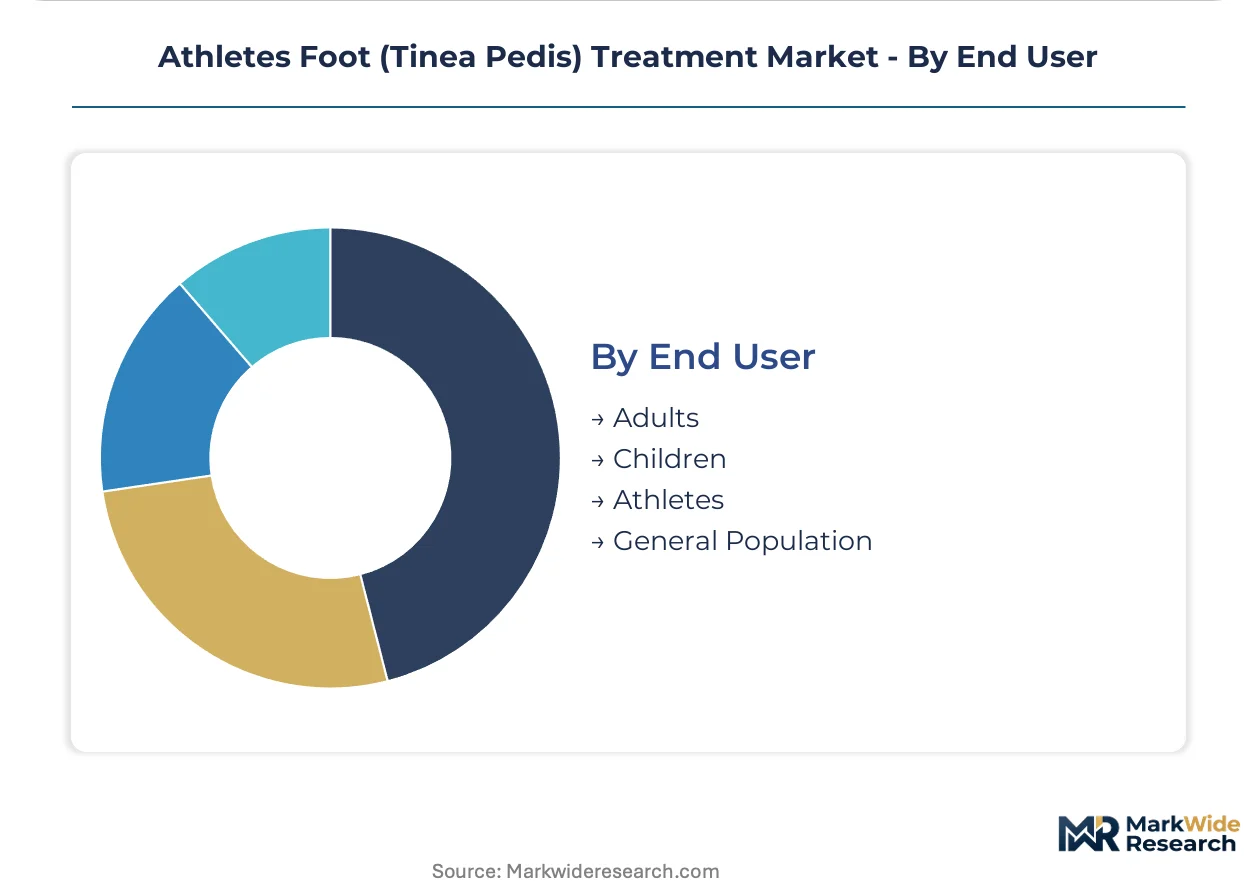
Adults represent the largest addressable base; athletes command the highest per-patient lifetime value through institutional screening protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health Canada is extending prescription-to-nonprescription transition timelines, reshaping how manufacturers prioritize North American market entry. The FDA's OTC monograph reform is collapsing traditional clearance pathways for topical antifungals. EMA's REACH compliance harmonization is reducing redundant toxicity testing burdens for allylamine-based formulations entering European markets.
United States
Telehealth prescribing expansion and podiatric care integration drive sustained prescription and non-prescription uptake. The FDA's OTC monograph reform forces manufacturers to restructure clinical evidence packages and accelerate direct-to-consumer channel investments. Subscription-based replenishment models in states with full nurse practitioner practice authority are displacing episodic pharmacy purchasing.
Germany
Direct-to-consumer platforms bundling recurrence-prevention sprays with diagnostic kits capture lifetime value from chronic sufferers. EMA's Committee for Medicinal Products for Human Use evaluates centralized marketing authorizations, creating compliance benchmarks favoring established regulatory affairs capabilities. Bavaria's consumer health infrastructure sustains shelf dominance across retail networks.
India
Three contract manufacturers control bulk terbinafine supply, exposing formulators to input cost volatility and qualification delays. CDSCO oversees new drug application pathways for oral therapies targeting resistant infections. Mumbai and Hyderabad anchor specialized generic manufacturing of terbinafine and clotrimazole formulations for export markets.
Brazil
ANVISA is fast-tracking simplified registrations for fixed-dose combination creams targeting underserved interior municipalities. Powder formats address humid climate conditions in rural pharmacy networks. São Paulo's distribution hubs channel products into mass retail and health store channels across the Southeast region.
Australia
Sports medicine clinics embed antifungal prophylaxis into athlete screening protocols, creating institutional prescription pull-through. TGA enforces efficacy and safety benchmarks comparable to FDA and EMA requirements. Melbourne and Sydney concentrate podiatric specialist practices driving premium positioning for treatment-resistant infections.
Athletes Foot (Tinea Pedis) Treatment Market Competitive Landscape
On the supply side, the industry is consolidating around asset-light licensing and contract manufacturing arrangements that fragment competitive dynamics in dermatological therapeutics. The vendor base separates into three strategic archetypes: multinational consumer health conglomerates with retail shelf dominance, specialized generic manufacturers with API-to-finished-formulation capabilities, and cost-optimized scale producers extending into emerging markets. Competitive moves center on portfolio diversification through OTC switch execution and geographic expansion via telehealth-integrated distribution partnerships.
Within the multinational tier, Bayer AG and GlaxoSmithKline plc occupy positions anchored by consumer health infrastructure across European and North American retail networks. Glenmark Pharmaceuticals Limited exemplifies the specialized generic archetype through concentrated manufacturing capabilities. Sun Pharmaceutical Industries Ltd sits within the scale-driven segment, competing on production economics for price-sensitive purchasing decisions in emerging markets.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Bayer AG |
| Bausch Health Companies Inc. |
| Glenmark Pharmaceuticals Limited |
| Novartis AG |
| Pfizer Inc. |
| Sanofi |
| Merck & Co., Inc. |
| Sun Pharmaceutical Industries Ltd |
| Others |
Pricing and Supply Chain Analysis
Mumbai's pharmaceutical manufacturing corridor anchors bulk terbinafine supply, concentrating API pricing power among three contract manufacturers whose capacity decisions ripple through downstream formulation costs across North American and European markets.
Pricing Analysis
Certification level creates the primary spread between prescription-grade and over-the-counter tiers, with FDA-monograph compliance commanding premium positioning against Health Canada and TGA benchmarks. Three-tier pricing structure across premium, standard, and economy levels stratifies by active ingredient concentration and delivery vehicle sophistication. Cost compression in the OTC tier is intensifying as nanoemulsion technology enables comparable efficacy at reduced API loads. Emerging market purchasers exhibit highest price sensitivity, while institutional sports medicine contracts in Australia demonstrate lowest elasticity due to bundled prophylaxis protocols.
Supply Chain Analysis
Contract manufacturing concentrates with Glenmark Pharmaceuticals, Sun Pharmaceutical Industries, and specialized Korean dermatology-focused producers holding spray vehicle development capacity. Active pharmaceutical ingredient production clusters in India, China, and selected European sites, with formulation finishing distributed across North American and EU regulatory zones. Raw material dependencies center on allylamine precursors, hydrophobic dispersion agents, and aerosol propellant systems. Single-source vulnerability in Indian terbinafine bulk supply exposes formulators to qualification delays. Distribution runs through retail pharmacy networks, direct-to-consumer platforms, and institutional procurement channels serving sports medicine clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward telehealth-integrated platforms and subscription fulfillment models, consolidating chronic patient capture before traditional retail pharmacy intervention.
For Market Incumbents: Pre-empt channel displacement by acquiring direct-to-consumer diagnostic and fulfillment capabilities, particularly in United States states with full nurse practitioner prescribing authority. Backward integration into nanoemulsion manufacturing technology defends margin position against generic entrants exploiting reduced API load equivalence claims. Lock institutional sports medicine contracts through embedded prophylaxis protocols before competitor spray format penetration.
For New Entrants and Emerging Players: Build out asset-light licensing arrangements with South Korean microfluidic contract manufacturers to bypass capital-intensive formulation science investments. Brazil's interior municipalities present the most penetrable geography, where ANVISA fast-track registrations for powder formats address humid climate conditions underserved by incumbent cream-focused portfolios. Target telehealth platform partnerships as primary go-to-market angle, bypassing retail pharmacy shelf space barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized generic manufacturers with API-to-finished-formulation capabilities and established regulatory affairs infrastructure across FDA, EMA, and TGA jurisdictions. Long-term viability hinges on OTC switch execution expertise and telehealth distribution integration rather than pipeline depth. Monitor Health Canada prescription-to-nonprescription transition timeline announcements as inflection indicator for North American margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| OTC Monograph Compliance Investment | FDA reform eliminates time-and-extent pathway, raising capital barriers for new entrants. |
| Telehealth Platform Partnership | Subscription models lock chronic patient loyalty before retail pharmacy intervention. |
| Nanoemulsion Technology Licensing | South Korean microfluidic methods enable reduced API load with comparable efficacy. |
| Institutional Sports Medicine Contracting | Australian clinic protocols create recurring prophylaxis revenue streams. |
| Emerging Market Registration Fast-Track | ANVISA simplified pathways target underserved interior Brazilian municipalities. |
Research Methodology
Desk research of FDA OTC monograph filings, EMA centralized marketing authorization submissions, and national pharmaceutical regulator databases preceded structured interviews with dermatology formulary directors, contract manufacturing executives, telehealth platform operators, and retail pharmacy procurement managers. Primary fieldwork with sports medicine clinic administrators and podiatric specialist practices was cross-validated against secondary trade data from customs records and health product distribution audits. Bottom-up patient population modeling and top-down pharmaceutical market sizing were triangulated to produce volume and value estimates.
Assumptions regarding telehealth prescribing expansion velocity, OTC switch timeline trajectories, and nanoemulsion technology adoption curves were held fixed across baseline scenarios while regulatory reform intensity and contract manufacturing concentration were varied in sensitivity analysis. Segmentation modeling incorporated product format, active ingredient class, distribution channel, and end-user application context dimensions. CAGRs were derived from trend extrapolation adjusted for named regulatory and technology inflection points, with API cost volatility and recurrence rate limitations incorporated as demand-side constraints.
Stress conditions across FDA monograph reform implementation timing, Indian API supply disruption scenarios, and telehealth prescribing regulatory reversals were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding patient adherence rates and clinician prescribing habit persistence. Quarterly review of Health Canada OTC switch submission volumes and ANVISA registration approval velocities is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Microdermabrasion Market
Dermatology
Global Hirsutism Market
Dermatology
Androgenetic Alopecia Market
Dermatology
Pigmented Lesion Treatment Market
Dermatology
Japan Scar Treatment Market
Dermatology
Homecare Dermatology Energy-Based Devices Market
Dermatology
Dermatology Cryosurgery Units Market
Dermatology
Acne Scar Treatment Market
Dermatology
Global Online Dermatology Consultation Market
Dermatology
Lichen Sclerosus Treatment Market
Dermatology
Global Radiodermatitis Market
Dermatology
Global Dermatology Excimer Laser Market
Dermatology
Dermabrasion and Micro Needling Market
Dermatology
Global Rosacea Market
Dermatology
Dermabrasion Market
Dermatology
Global Veterinary Dermatology Drugs Market