
 Dermatology Diagnostic Devices and Therapeutics Market | 2026-2036
Dermatology Diagnostic Devices and Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Dermatology Diagnostic Devices and Therapeutics Market Analysis
AI-enabled diagnostic accuracy tiers are redrawing competitive boundaries in dermatology. Novartis International AG leverages its biologics pipeline to dominate psoriasis and atopic dermatitis therapeutics. AbbVie, Inc. sustains leadership through deep specialization in immunology-driven skin conditions. Galderma S.A. differentiates by anchoring its portfolio across both prescription therapeutics and physician-dispensed skincare channels.
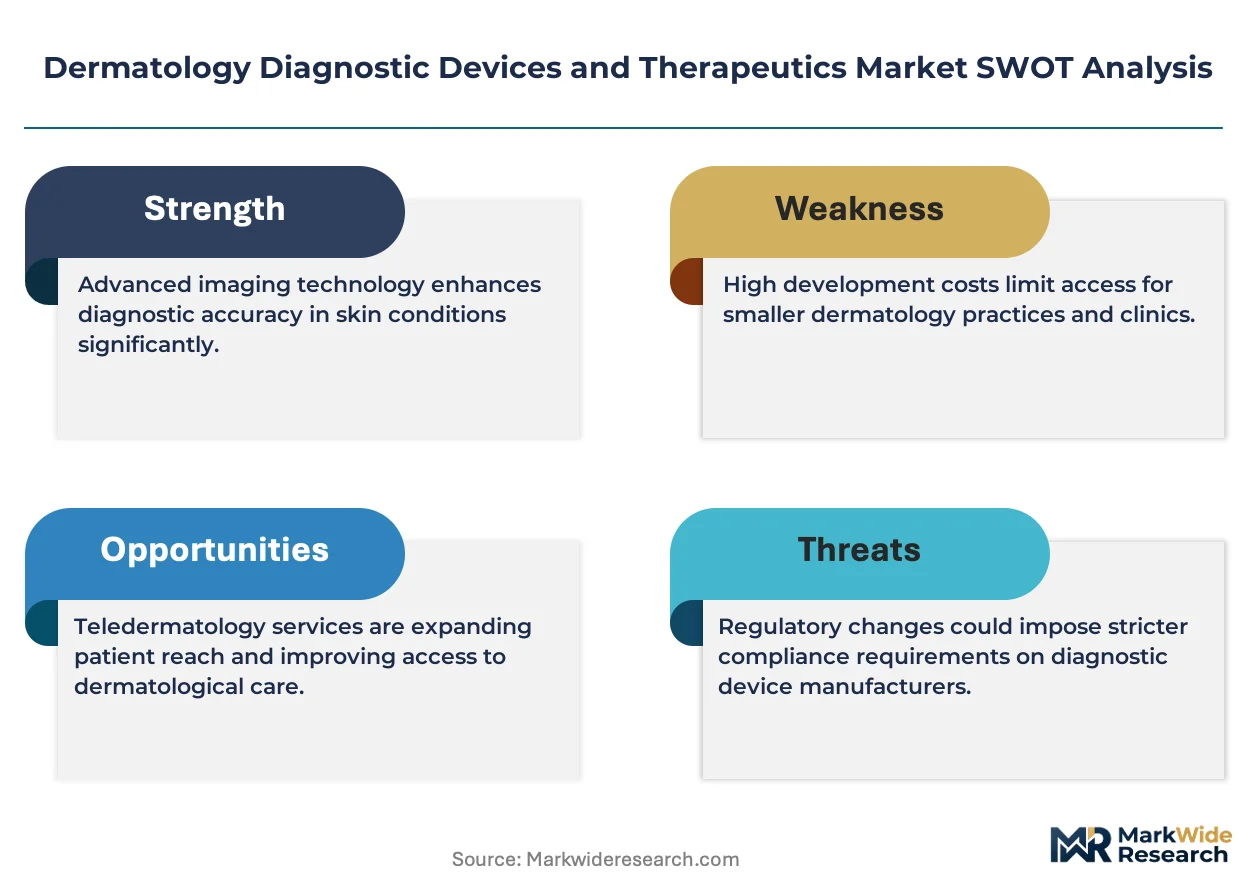
Dermatology diagnostic devices and therapeutics encompass instruments and pharmaceutical agents designed for the detection, monitoring, and treatment of skin pathologies, including confocal microscopy systems operating at cellular resolution and biologic monoclonal antibodies targeting IL-17 and IL-23 cytokine pathways. These technologies serve to reduce diagnostic latency for melanoma, enable precision therapy for chronic inflammatory conditions, and shift care delivery from reactive treatment to proactive disease management. Imaging Systems and AI Diagnostics represent the fastest-expanding technology pairing, as convolutional neural networks trained on dermoscopic image libraries compress specialist-level triage into primary care workflows. Biopsy Devices remain the revenue anchor in procedural dermatology, while Teledermatology platforms are capturing new patient volumes through asynchronous consultation models that extend specialist reach into underserved regions.
FDA premarket notification requirements and EMA's Medical Device Regulation govern clinical validation standards for AI diagnostic algorithms and laser therapeutic platforms, creating compliance barriers that favor well-capitalized developers with established quality management systems. The EU AI Act adds layered conformity obligations for automated diagnostic systems deployed in clinical settings, particularly around transparency and human oversight protocols. Stakeholders must monitor how divergent regulatory timelines between FDA breakthrough device designation and EMA notified body certification reshape geographic launch sequencing and reimbursement negotiations.
Market Dynamics
Convolutional neural networks trained on dermoscopic image libraries are compressing specialist-level triage into primary care workflows, redistributing diagnostic authority away from hospital-based dermatologists toward point-of-care settings.
Growth Catalysts
- FDA breakthrough device designation:The FDA's expedited pathway for AI-enabled diagnostic tools accelerates commercialization timelines for algorithm developers, reducing time-to-revenue for melanoma detection platforms.
- Primary care integration:Confocal microscopy systems and smartphone-connected dermoscopes enable general practitioners to triage skin lesions without specialist referral, expanding addressable patient volumes in underserved rural networks.
- Biologics pipeline expansion:Monoclonal antibodies targeting IL-17 and IL-23 cytokine pathways extend treatment options for moderate-to-severe psoriasis, driving therapeutic switching from conventional systemic agents.
Market Restraints
- Laser device input costs:Precision optics and rare-earth doping materials for therapeutic laser platforms face supply concentration from specialized German and Japanese component suppliers, creating margin pressure.
- EMA MDR compliance burden:The European Medical Device Regulation's clinical validation requirements for AI diagnostic algorithms impose documentation costs that disadvantage early-stage developers without established quality management systems.
- Teledermatology substitution ceiling:Asynchronous image-based consultation cannot replace histopathological confirmation for ambiguous lesions, limiting platform penetration in melanoma-suspect cases.
Strategic Opportunities
- India's dermatology infrastructure gap:The country's specialist-to-patient ratio of approximately one dermatologist per 400,000 population creates demand for AI-assisted triage tools deployable via smartphone.
- EU AI Act transparency mandates:Automated diagnostic systems deployed in European clinical settings must implement human oversight protocols, creating service revenue streams for compliance consulting and algorithm auditing.
- Phototherapy-homecare convergence:Narrowband UV-B devices are miniaturizing for patient-operated home use, bypassing clinic-based phototherapy units and capturing chronic condition management outside institutional settings.
Industry Challenges
- Computational pathology skill scarcity:Interpretation of AI-generated diagnostic probability scores requires training that most dermatology residency programs have not integrated, creating workforce adaptation friction.
- Multi-jurisdiction certification timelines:Developers must sequence FDA 510(k) clearance, EMA notified body certification, and PMDA shonin approval for global product launches, stretching regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dermatology Diagnostic Devices and Therapeutics Market |
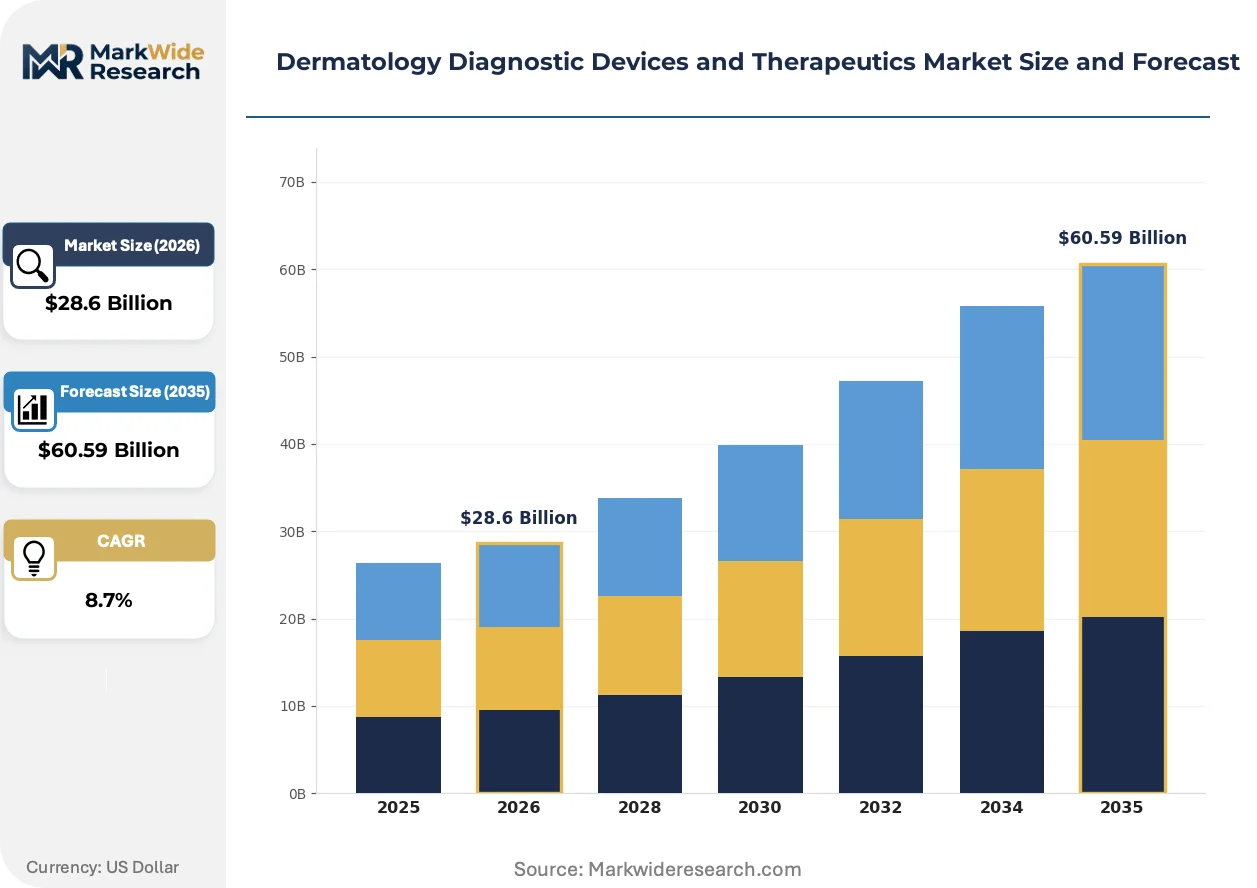
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biopsy Devices, Dermatoscopes, Imaging Systems, Therapeutic Lasers Application: Skin Cancer Detection, Acne Treatment, Psoriasis Management, Dermatological Surgery End User: Dermatology Clinics, Hospitals, Research Laboratories, Homecare Settings Technology: Teledermatology, AI Diagnostics, Phototherapy, Topical Delivery Systems |
| Companies Covered | Canfield Scientific, Inc., Novartis International AG, Cutera, Inc., Michelson Diagnostics Ltd., Caliber Imaging & Diagnostics, Galderma S.A., LEO Pharma A/S, FotoFinder Systems GmbH, AbbVie, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dermatology Diagnostic Devices and Therapeutics Market Emerging Trajectories
Diagnostic hardware and therapeutic modalities are converging around portability, algorithmic interpretation, and patient-operated delivery models that displace traditional clinic-centric care structures.
Confocal laser scanning microscopy is miniaturizing from laboratory-scale instruments to handheld devices capable of cellular-resolution imaging at the bedside. Dermatology departments in German university hospitals are piloting these units for real-time margin assessment during Mohs surgery. The technology is miniaturizing specialist-grade histological visualization into ambulatory settings, compressing the diagnostic pathway from days to minutes.
The EU AI Act's risk-based classification system places automated melanoma detection algorithms in the high-risk category, mandating conformity assessments through notified bodies before European market entry. This regulatory architecture elevates compliance costs for developers but simultaneously creates competitive moats against undercapitalized entrants. Dermatology AI platforms targeting European deployment are restructuring their technical documentation and human-in-the-loop protocols to satisfy transparency requirements.
Patient-initiated screening through consumer dermatology apps is fragmenting the traditional referral pathway from primary care to specialist. These platforms capture lesion images via smartphone, apply proprietary algorithms for risk stratification, and direct high-probability cases toward affiliated dermatology networks. This channel shift concentrates diagnostic volume in platform-integrated practices while marginalizing independent specialists, with the pattern most visible in United States metropolitan markets where consumer health app penetration exceeds clinical adoption rates elsewhere.
Dermatology Diagnostic Devices and Therapeutics Market Segmentation
Product and technology boundaries in dermatology are blurring as diagnostic hardware gains therapeutic connectivity and biologics integrate with digital monitoring. Segmentation clarity determines which development paths attract capital and which face reimbursement compression.
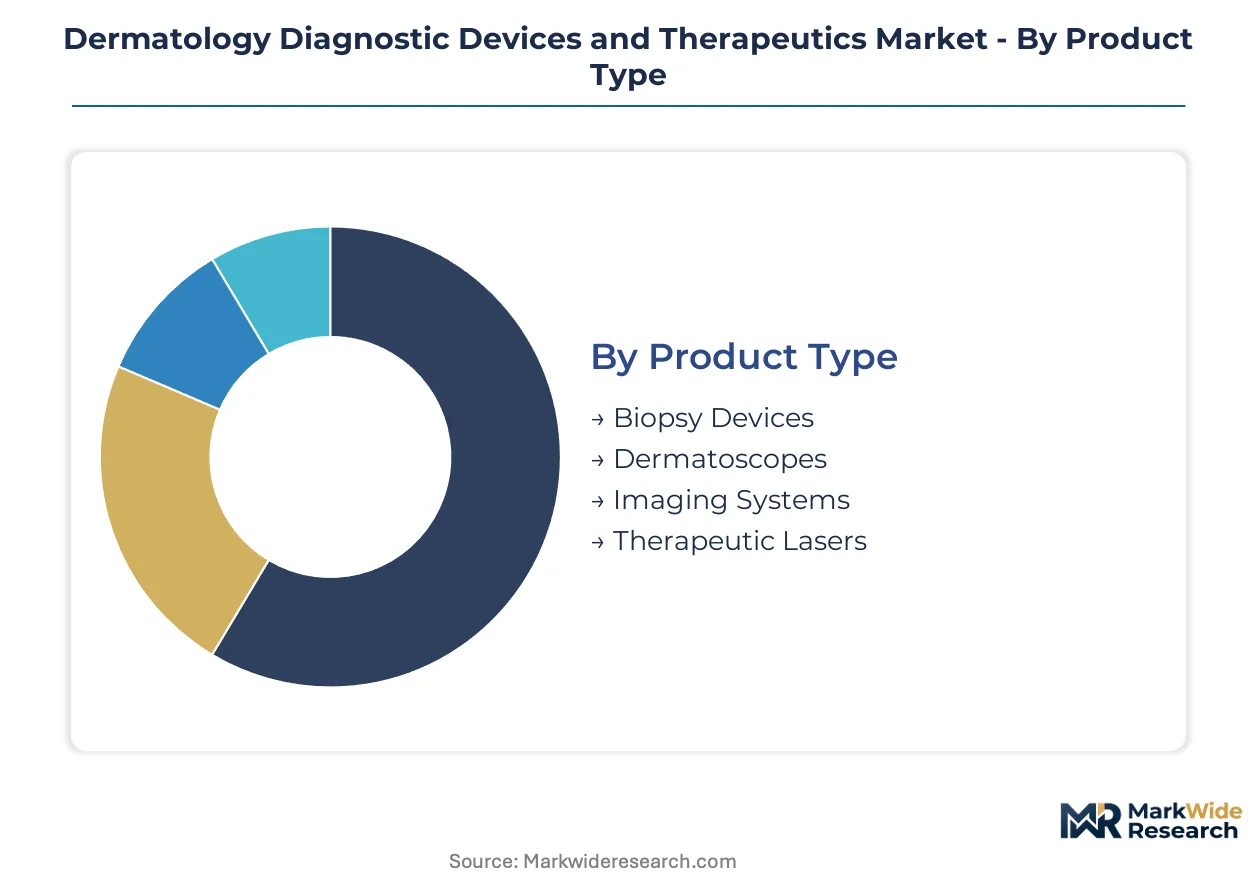
Product Type:
FDA 510(k) clearance timelines and EMA MDR conformity obligations diverge sharply across hardware categories, advantaging developers with established quality management systems in biopsy devices while delaying AI-enabled imaging entrants.
- Biopsy Devices:Punch, shave, and excisional instruments with integrated cautery functions dominate procedural revenue in hospital dermatology departments. Demand concentrates in German university hospitals expanding Mohs surgery programs, constrained by sterilization protocol harmonization across multi-site networks.
- Imaging Systems:Confocal laser scanning microscopy and optical coherence tomography platforms deliver cellular-resolution visualization without tissue destruction. Adoption is climbing fastest in Japanese tertiary centers where PMDA shonin pathways for novel imaging modalities have compressed approval timelines relative to European notified body processes.
- Dermatoscopes:Handheld polarized and non-polarized devices with smartphone connectivity enable primary care triage. Compact units from specialized German optics manufacturers supply clinic networks in the United States.
- Therapeutic Lasers:Pulsed dye, fractional CO2, and excimer platforms target vascular lesions, resurfacing, and psoriasis plaques. Rare-earth doping material sourcing from Japanese component suppliers creates input cost volatility.
Established volume favors Biopsy Devices; emerging adoption favors Imaging Systems.
Application:
Reimbursement codes and clinical validation requirements segment addressable markets by disease severity and treatment setting, with hospital-based procedures commanding premium rates over ambulatory management.
- Skin Cancer Detection:Melanoma and non-melanoma screening protocols integrate dermoscopic photography with AI risk stratification algorithms. Demand concentrates in United States metropolitan markets where consumer health app penetration has fragmented traditional referral pathways toward platform-integrated practices.
- Psoriasis Management:Biologic monoclonal antibodies targeting IL-17 and IL-23 cytokine pathways displace conventional systemic agents for moderate-to-severe cases. Prescription volume is climbing fastest in hospital outpatient departments with embedded infusion centers.
- Acne Treatment:Topical retinoids, antimicrobials, and hormonal therapies address mild-to-moderate inflammatory and comedonal presentations. Physician-dispensed skincare channels in Germany capture premium positioning for combination regimens.
- Dermatological Surgery:Mohs micrographic surgery and aesthetic reconstruction procedures require precision margin assessment tools. Real-time confocal microscopy pilots in German university hospitals are compressing operative timelines.
Therapeutic switching propels Psoriasis Management; diagnostic protocol expansion propels Skin Cancer Detection.
End User:
Capital intensity and regulatory compliance capacity determine which settings can absorb advanced diagnostic and therapeutic platforms, concentrating AI-enabled tools in well-capitalized institutions while homecare remains limited to established modalities.
- Hospitals:Tertiary centers with embedded dermatology departments deploy full-spectrum imaging, laser suites, and infusion centers for biologic administration. Japanese university hospitals lead adoption of handheld confocal devices for intraoperative margin assessment.
- Dermatology Clinics:Specialist practices integrate teledermatology platforms and physician-dispensed skincare to extend service reach. United States metropolitan clinics face patient volume concentration toward consumer app-affiliated networks.
- Research Laboratories:Academic and pharmaceutical R&D facilities utilize advanced imaging for biomarker validation and therapeutic mechanism studies. Funding concentration in German and Japanese research clusters shapes equipment procurement.
- Homecare Settings:Patient-operated narrowband UV-B devices and topical delivery systems bypass clinic-based phototherapy. Miniaturization trends are expanding chronic condition management outside institutional settings.
Capital deployment favors Hospitals; care model disruption favors Homecare Settings.
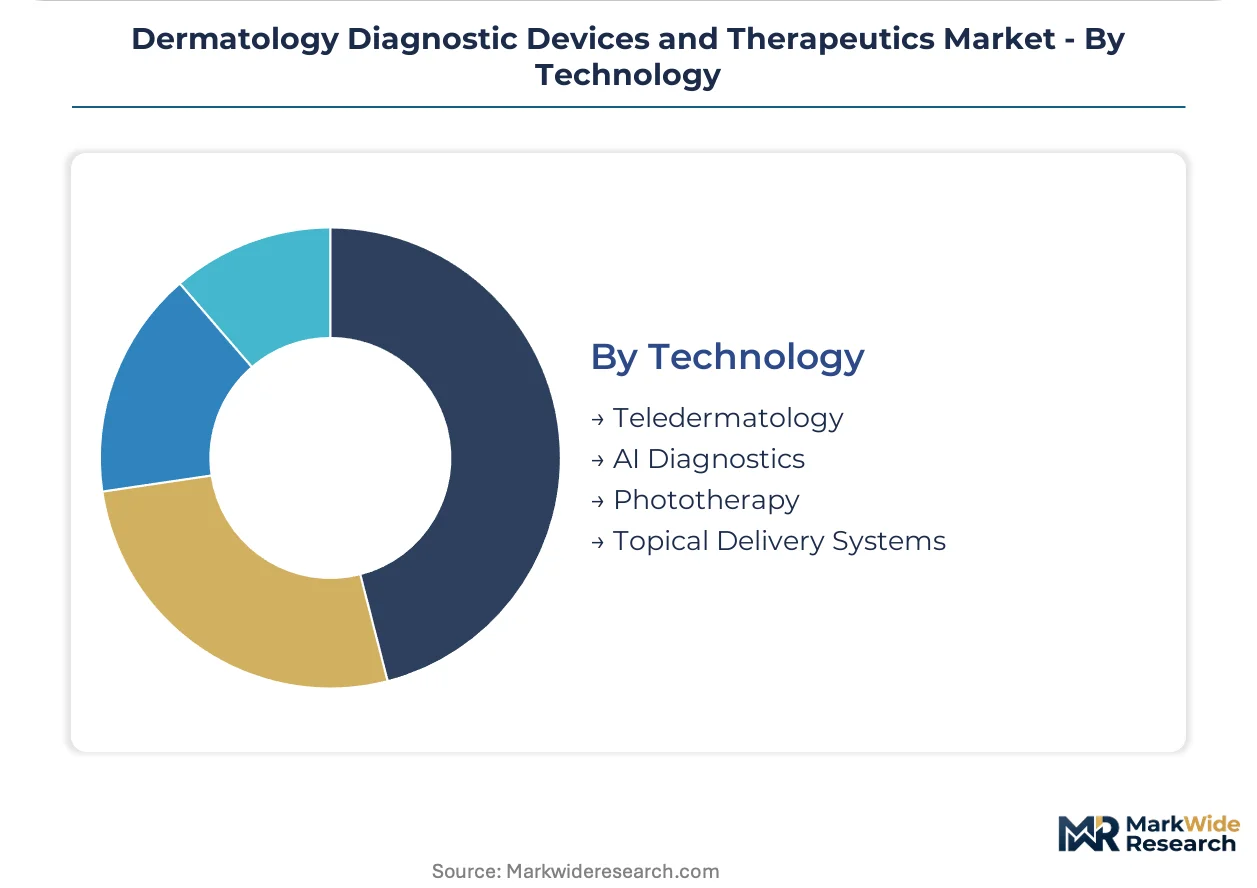
Technology:
EU AI Act risk classification and FDA breakthrough device designation create divergent compliance architectures that reshape competitive positioning for algorithm developers versus established hardware manufacturers.
- AI Diagnostics:Convolutional neural networks trained on dermoscopic image libraries compress specialist-level triage into primary care workflows. European deployment requires conformity assessments through notified bodies under high-risk classification, elevating documentation costs.
- Phototherapy:Narrowband UV-B and excimer laser platforms for psoriasis and vitiligo are miniaturizing for patient-operated home use. Supply concentration in German and Japanese component manufacturers shapes device economics.
- Teledermatology:Asynchronous image-based consultation platforms extend specialist reach into underserved regions. Penetration ceilings persist where histopathological confirmation remains mandatory for ambiguous lesions.
- Topical Delivery Systems:Microneedle arrays and transdermal patches enhance bioavailability for corticosteroids and immunomodulators. Formulation partnerships with specialized European contract manufacturers accelerate pipeline progression.
Regulatory acceleration favors AI Diagnostics; modality maturation favors Phototherapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in dermatology devices tilt toward deficit in India and surplus in Germany and Japan, reflecting specialized manufacturing concentration in precision optics and laser components. The United States absorbs the largest absolute import volume of AI-enabled diagnostic platforms. Regulatory divergence between FDA breakthrough pathways and EMA notified body processes fragments launch sequencing.
United States
FDA breakthrough device designation accelerates commercialization timelines for melanoma detection algorithms, compressing revenue realization cycles. Consumer health app penetration in metropolitan markets fragments traditional referral pathways toward platform-integrated practices. The Boston-Cambridge cluster anchors AI diagnostic development, with venture funding concentrating in convolutional neural network training for dermoscopic image libraries.
Germany
EMA Medical Device Regulation conformity assessments impose documentation costs that elevate competitive moats against undercapitalized AI entrants. University hospitals in Munich and Heidelberg pilot handheld confocal microscopy for real-time Mohs surgery margin assessment. Precision optics manufacturing in Jena and Oberkochen supplies dermoscope components to clinic networks across North America.
Japan
PMDA shonin approval pathways for novel imaging modalities compress timelines relative to European notified body processes, accelerating adoption in tertiary centers. Rare-earth doping material sourcing from domestic component suppliers shapes therapeutic laser device economics. Tokyo and Osaka university hospitals lead deployment of intraoperative margin assessment tools, redistributing diagnostic authority toward point-of-care settings.
India
A specialist-to-patient ratio of approximately one dermatologist per 400,000 population creates demand compression for AI-assisted triage tools deployable via smartphone. CDSCO regulatory frameworks for software-as-medical-device lag FDA and EMA precedents, delaying formal algorithm registration. Bangalore and Hyderabad clusters concentrate telemedicine platform development targeting underserved rural networks with asynchronous consultation models.
United Kingdom
NICE technology appraisal processes for biologic therapeutics create reimbursement negotiation friction for IL-17 and IL-23 pathway inhibitors. London teaching hospitals integrate teledermatology platforms to extend specialist reach into community care settings. The Cambridge life sciences cluster supports biomarker validation research utilizing advanced confocal imaging for pharmaceutical R&D partnerships.
Dermatology Diagnostic Devices and Therapeutics Market Vendor Landscape
Concentration sits with diversified pharmaceutical conglomerates and specialized dermatology device manufacturers rather than pure-play AI developers. The competitive terrain splits between biologics-heavy therapeutics portfolios and hardware-anchored diagnostic platforms. Strategic archetypes include immunology-driven biologics specialists, precision optics fabricators, and algorithm-enabled triage platform operators. Dominant competitive moves encompass portfolio diversification across prescription therapeutics and physician-dispensed skincare, plus geographic sequencing that prioritizes FDA clearance before EMA certification.
Within the biologics-heavy tier, Novartis International AG and AbbVie, Inc. exemplify immunology-driven specialization, while Galderma S.A. occupies a position bridging prescription therapeutics and skincare channels. Among device-centric specialists, Canfield Scientific, Inc. and FotoFinder Systems GmbH represent precision imaging archetypes with geographic anchoring in North America and Central Europe respectively. Cutera, Inc. sits within the therapeutic laser segment where rare-earth component sourcing shapes margin structures. These named entities illustrate how regulatory compliance capacity and quality management system maturity determine competitive positioning across FDA, EMA, and PMDA jurisdictions.
| Leading Market Players |
|---|
| Canfield Scientific, Inc. |
| Novartis International AG |
| Cutera, Inc. |
| Michelson Diagnostics Ltd. |
| Caliber Imaging & Diagnostics |
| Galderma S.A. |
| LEO Pharma A/S |
| FotoFinder Systems GmbH |
| AbbVie, Inc. |
| Others |
Supply Flow & Price Mechanics
FDA 510(k) clearance pathways and EMA MDR conformity assessments gate both supplier qualification and price differentiation simultaneously, concentrating premium pricing power among developers with mature quality management systems while compressing margins for early-stage entrants facing documentation cost barriers.
Pricing Analysis
Hospital procurement committees and dermatology clinic networks anchor pricing stratification across premium, standard, and economy tiers. Certification grade under FDA breakthrough designation and CE marking tier drive price differentiation, with AI-enabled imaging platforms commanding premiums over conventional dermoscopy. Cost compression in economy-tier biopsy instruments is intensifying because of sterilization protocol harmonization demands across multi-site hospital networks. Price sensitivity concentrates among independent dermatology clinics in United States metropolitan markets, while German university hospitals exhibit lower sensitivity for intraoperative margin assessment tools.
Supply Chain Analysis
Inventory lead times for precision optics and rare-earth doping materials have extended because of sourcing concentration from specialized German and Japanese component suppliers. Manufacturing of therapeutic laser platforms draws from Jena and Oberkochen in Germany for optical assemblies, and domestic Japanese suppliers for rare-earth materials. Supply chain risk centers on single-source vulnerability for confocal microscopy objectives and excimer laser gas mixtures. Distribution runs through specialized medical device distributors with GPO contracts in the United States, and direct hospital sales teams in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment story, where FDA breakthrough device designation and EMA notified body certification create switching costs that lock in incumbent advantages and raise barriers for algorithm developers without established quality management systems.
For Market Incumbents: Compound defensive positioning by deepening backward integration into precision optics manufacturing in German supplier clusters, and by accelerating certification investment for EU AI Act high-risk classification compliance. Emerging AI-native entrants threaten diagnostic imaging margins through primary care channel disruption. Vertical control over rare-earth doping material supply secures therapeutic laser cost structures against Japanese component volatility. For New Entrants and Emerging Players: FDA breakthrough device designation offers the fastest certification fast-track for melanoma detection algorithms targeting primary care integration. White-space opportunity concentrates in India's smartphone-deployable triage tools, where dermatologist scarcity creates demand compression for asynchronous consultation platforms. Teledermatology partnerships with Bangalore and Hyderabad telemedicine clusters provide the most penetrable go-to-market angle for algorithm developers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI diagnostic platforms because of European conformity assessment documentation costs. Long-term viability favors developers with dual FDA-EMA certification capacity and established reimbursement codes in United States hospital outpatient departments. Acquisition target archetype: algorithm-enabled triage platforms with proprietary dermoscopic image libraries. Signal to watch: PMDA shonin approval timeline compression for novel imaging modalities relative to European notified body processes.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerates commercialization timelines for melanoma detection algorithms in United States primary care networks. |
| EU AI Act Conformity Assessment | Elevates documentation costs for automated diagnostic systems, creating competitive moats against undercapitalized entrants. |
| Backward Integration into Optics | Captures margin from Jena and Oberkochen precision component suppliers for confocal microscopy manufacturing. |
| Smartphone Triage Deployment | Addresses India's one-dermatologist-per-400,000-population infrastructure gap through AI-assisted primary care workflows. |
| Phototherapy Homecare Miniaturization | Bypasses clinic-based UV-B units by enabling patient-operated chronic condition management outside institutional settings. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across dermatology departments, device manufacturers, and pharmaceutical development teams. Primary interviews captured perspectives from hospital purchasing committees, biomedical engineers, regulatory affairs leads, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, EMA MDR submission databases, PMDA shonin approval records, and hospital procurement databases. Bottom-up equipment shipment tracking and top-down therapeutic prescription volume analysis were triangulated against reimbursement code utilization data.
Across the analysis window, value projections were derived from segmented modeling across product type, application, end user, and technology dimensions. Forecast inputs incorporated biologics pipeline progression for IL-17 and IL-23 pathway inhibitors, AI diagnostic algorithm training data expansion rates, and phototherapy device miniaturization adoption curves. CAGRs were computed from annualized growth trajectory analysis across United States, German, Japanese, and Indian market clusters.
Underlying assumptions cover regulatory pathway stability, rare-earth material supply continuity, and reimbursement code maintenance, with deviation risk concentrated in EMA notified body backlog delays and CDSCO software-as-medical-device framework evolution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Japan Scar Treatment Market
Dermatology
Psoriasis Treatment Market
Dermatology
Dermatology Drugs Market
Dermatology
Inflammatory Skin Diseases Treatment Market
Dermatology
Dermatology Devices Market
Dermatology
Scar Treatment Market
Dermatology
Global Dermatology Excimer Laser Market
Dermatology
Global Rosacea Market
Dermatology
Rosacea Treatment Market
Dermatology
Global Dermatological OTC Drugs Market
Dermatology
Alopecia Treatment (Hair Loss) Market
Dermatology
Common Warts Market
Dermatology
Dermabrasion and Micro Needling Market
Dermatology
Chronic Spontaneous Urticaria Market
Dermatology
Dermatophytic Onychomycosis Treatment Market
Dermatology
Global Dermatological Therapeutics Market