
 Global Radiodermatitis Market | 2026-2036
Global Radiodermatitis Market Size, Share, and Industry Trends Forecast 2026-2036
Global Radiodermatitis Market Foresight
Buyer concentration among radiation oncology centers is pivoting toward larger hospital networks that negotiate centralized supply contracts for skin protectants and anti-inflammatory creams. ConvaTec Group Plc leverages its advanced wound care portfolio to anchor relationships with these consolidated purchasers. 3M Company competes through extensive distribution infrastructure that reaches ambulatory care facilities across multiple continents. Mölnlycke Health Care AB specializes in silicone-based barrier technologies that differentiate its offerings for head and neck cancer protocols.
Radiodermatitis refers to cutaneous inflammatory injury resulting from ionizing radiation exposure, typically manifesting as erythema, desquamation, and epidermal necrosis at cumulative doses exceeding 20 Gray, with primary purpose of requiring clinical intervention to maintain radiation therapy adherence. Skin protectants dominate current volume due to their preventive positioning before treatment cycles begin. Anti-inflammatory creams represent the fastest-expanding product category as protocols shift toward proactive management rather than reactive symptom control. Topical therapy captures the largest share of treatment method revenue, while phototherapy remains a niche option reserved for severe refractory cases in specialized dermatology clinics.
The U.S. FDA regulates topical corticosteroids and skin protectants as drugs or medical devices depending on intended use, while the EMA's Medical Device Regulation imposes stricter clinical evidence requirements on barrier products sold in Europe. Japan's PMDA maintains distinct approval pathways that delay market entry for novel formulations, creating regulatory fragmentation that shapes regional competitive dynamics. Stakeholders must monitor evolving classification decisions by these agencies, as reclassification of moisturizers or analgesics into higher-risk categories would fundamentally alter compliance costs and market access timelines.
Market Dynamics
Radiation oncology centers are consolidating procurement under centralized hospital networks, compressing vendor relationships into long-term supply contracts that favor manufacturers with diversified wound care portfolios and regulatory documentation depth.
Growth Catalysts
- EMA Medical Device Regulation:Stricter clinical evidence requirements for barrier products in Europe are elevating standards that differentiate premium formulations from commodity alternatives, rewarding manufacturers with robust dermatological testing capabilities.
- Proactive protocol adoption:Cancer treatment centers in Germany and Japan are implementing skin protectant regimens before first radiation exposure, expanding the addressable patient pool beyond reactive symptom management.
- Silicone-based barrier technologies:Advanced material science enables thinner, more conformable dressings for head and neck cancer protocols where anatomical complexity previously limited product efficacy.
Market Restraints
- API cost volatility:Corticosteroid active pharmaceutical ingredients face supply concentration among Indian and Chinese manufacturers, creating margin pressure for topical anti-inflammatory cream producers.
- PMDA approval timelines:Japan's distinct documentation requirements and inspection protocols delay novel formulation entry by 18-24 months versus FDA pathways, fragmenting product availability across developed markets.
- Moisturizer substitution:Over-the-counter emollient products positioned as radiation skincare by cosmetic brands capture price-sensitive patients outside reimbursed care pathways.
Strategic Opportunities
- Brazil and Mexico:Underpenetrated Latin American radiation oncology infrastructure presents first-mover advantage for manufacturers establishing distribution partnerships ahead of center expansion.
- Phototherapy-drug convergence:Combination protocols integrating topical sensitizers with narrowband UV delivery are creating new reimbursement categories for refractory radiodermatitis cases.
- Direct-to-clinic e-procurement:Hospital network purchasing platforms are disintermediating traditional medical device distributors, enabling margin recovery through manufacturer-controlled pricing.
Industry Challenges
- Clinical trial recruitment:Radiation therapy scheduling constraints complicate endpoint data collection for FDA 510(k) and PMA submissions, extending development timelines for novel protectant formulations.
- Legacy EHR integration:Skin toxicity grading documentation across Varian, Elekta, and proprietary oncology information systems requires fragmented API development, increasing deployment costs for digital adherence tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Radiodermatitis Market |
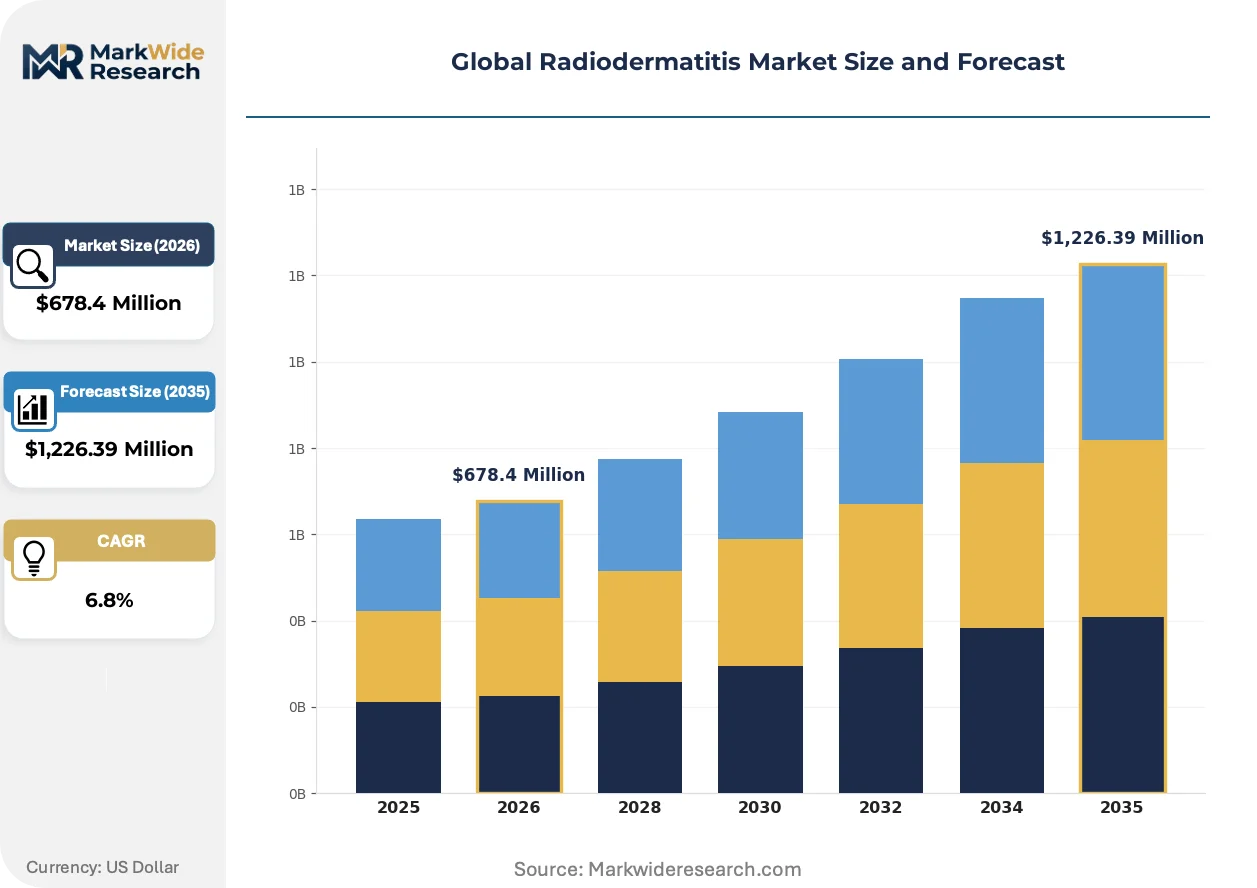
| Market Size in 2026 | $678.4 Million |
| Market Size in 2035 | $1,226.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Skin Protectants, Anti-inflammatory Creams, Moisturizers, Analgesics Application: Head & Neck Cancer, Breast Cancer, Lung Cancer, Prostate Cancer, Gynecological Cancer End User: Radiation Oncology Centers, Dermatology Clinics, Cancer Treatment Hospitals, Ambulatory Care Facilities Treatment Method: Topical Therapy, Phototherapy, Systemic Medication, Preventive Care, Supportive Care |
| Companies Covered | ConvaTec Group Plc, Stratpharma AG, 3M Company, Helsinn Healthcare SA, BMG Pharma S.p.A., Smith & Nephew, Bausch Health Companies Inc, Bayer AG, Mölnlycke Health Care AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Radiodermatitis Market Shifts & Advancements
Product development is pivoting from symptomatic relief toward prevention-first positioning, with formulation science and delivery mechanisms converging to support continuous skin barrier maintenance throughout fractionated radiation courses.
Hyaluronic acid-ceramide composite dressings are modularizing preventive care protocols by enabling single-application coverage across multi-day treatment intervals. Major cancer centers in the United States are piloting these systems for breast and pelvic radiation patients. The technology is compressing nursing intervention requirements while improving adherence to prophylactic regimens.
Japan's PMDA introduced streamlined QMS inspection procedures for designated medical device categories in 2023, reducing facility audit burdens for barrier product manufacturers with established ISO 13485 certification. European manufacturers with Tokyo-based regulatory affairs teams are accelerating dossier preparation to exploit this pathway. Dermatological dressing suppliers with existing JIS compliance documentation capture fastest approval velocity.
Hospital network consolidated purchasing is displacing individual radiation oncology center autonomy across Germany, France, and the United Kingdom. University hospital alliances in Bavaria and North Rhine-Westphalia now negotiate three-year supply contracts with tiered volume commitments. This concentration favors wound care portfolios with breadth across moist wound healing, negative pressure therapy, and radiodermatitis prevention categories.
Global Radiodermatitis Market Segmentation
Radiodermatitis treatment selection hinges on radiation dose intensity, anatomical site vulnerability, and institutional procurement protocols. Segmentation reveals where formulation innovation concentrates versus where commoditization pressures dominate purchasing decisions.
Product Type:
Procurement teams evaluate cost-effectiveness against clinical evidence depth when selecting across preventive and therapeutic formulations.
- Skin Protectants:Barrier-forming preparations containing petrolatum, dimethicone, or zinc oxide that shield epidermis from radiation-induced moisture loss. Volume concentrates in United States radiation oncology centers where FDA-cleared devices command preference in bundled payment contracts.
- Anti-inflammatory Creams:Topical corticosteroid and calcineurin inhibitor formulations targeting erythema and desquamation. Demand is climbing fastest in Germany and Japan as protocols shift toward proactive symptom suppression before Grade 2 toxicity manifests.
- Corticosteroids:Hydrocortisone and betamethasone-based preparations for established inflammatory response.
- Moisturizers:Emollient and humectant products for barrier maintenance without therapeutic claims.
- Analgesics:Topical lidocaine and capsaicin formulations for neuropathic pain associated with severe skin injury.
Volume sits with Skin Protectants; growth tilts toward Anti-inflammatory Creams.
Application:
Anatomical site determines dressing conformability requirements and nursing intervention intensity throughout fractionated treatment courses.
- Head & Neck Cancer:Complex anatomical contours around jawline, neck folds, and ear regions demand silicone-adherent barrier technologies. Mölnlycke Health Care AB specializes in this segment where standard film dressings fail to maintain adhesion.
- Breast Cancer:Large surface areas with skin-on-skin contact beneath inframammary folds create moisture-associated damage risks. Hyaluronic acid-ceramide composite systems are piloting across United States academic medical centers for this indication.
- Lung Cancer:Thoracic radiation fields with overlapping skin tolerance concerns.
- Prostate Cancer:Pelvic radiation with lower skin dose exposure but sensitive anatomical proximity.
- Gynecological Cancer:Perineal and abdominal fields requiring specialized moisture management.
Head & Neck Cancer commands premium pricing for conformable technologies; Breast Cancer offers the steepest expansion trajectory due to screening program volumes.
End User:
Facility type dictates reimbursement pathway complexity and inventory management sophistication for skin toxicity protocols.
- Radiation Oncology Centers:Dedicated linear accelerator facilities where prophylactic regimens originate. Consolidated purchasing across hospital networks in Germany and the United Kingdom compresses vendor relationships into multi-year contracts.
- Cancer Treatment Hospitals:Integrated oncology departments with inpatient capability for severe reactions. 3M Company leverages distribution infrastructure to reach these facilities across multiple continents.
- Dermatology Clinics:Specialist referral sites for refractory cases requiring phototherapy escalation.
- Ambulatory Care Facilities:Community-based settings with limited radiation therapy capability.
Radiation Oncology Centers anchor current procurement volume; Cancer Treatment Hospitals are gaining share fastest through network consolidation.
Treatment Method:
Clinical workflow integration determines whether interventions occur at point-of-care or require specialist referral pathways.
- Topical Therapy:Self-administered or nurse-applied creams, ointments, and dressings dominating ambulatory protocols. ConvaTec Group Plc anchors relationships with purchasers through wound care portfolio breadth spanning this category.
- Preventive Care:Prophylactic skin protectant regimens initiated before first radiation fraction. Japan's PMDA streamlined QMS inspection procedures in 2023 accelerated manufacturer dossier preparation for this approach.
- Phototherapy:Narrowband UV delivery for refractory cases in specialized dermatology clinics.
- Systemic Medication:Oral corticosteroids and antibiotics for severe radiation dermatitis complications.
- Supportive Care:Adjunctive interventions including nutritional support and pain management.
Topical Therapy captures dominant revenue share; Preventive Care is expanding most quickly as protocols shift toward toxicity avoidance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for radiodermatitis management concentrates in radiation oncology centers across the United States, Germany, and Japan where cancer treatment infrastructure is most developed. Procurement patterns in these markets diverge sharply based on regulatory pathway complexity and reimbursement structure. Emerging opportunities surface in Latin American markets where center expansion outpaces local supply capacity.
United States
FDA-cleared skin protectants command preference in bundled payment contracts across academic medical centers and community radiation oncology networks. The agency's emphasis on topical drug safety profiles pushes manufacturers toward rigorous dermatological testing standards. Major cancer centers in Boston and Houston pilot hyaluronic acid-ceramide composite systems for breast and pelvic radiation protocols.
Germany
University hospital alliances in Bavaria and North Rhine-Westphalia negotiate three-year supply contracts with tiered volume commitments for wound care portfolios. EMA Medical Device Regulation imposes stricter clinical evidence requirements on barrier products, elevating standards that differentiate premium formulations. Cancer treatment centers in Munich and Cologne implement skin protectant regimens before first radiation exposure.
Japan
PMDA maintains distinct approval pathways that delay market entry for novel formulations by 18-24 months versus FDA pathways. Streamlined QMS inspection procedures introduced in 2023 reduce facility audit burdens for barrier product manufacturers with established ISO 13485 certification. Tokyo-based regulatory affairs teams accelerate dossier preparation to exploit this pathway.
Brazil
Underpenetrated radiation oncology infrastructure presents first-mover advantage for manufacturers establishing distribution partnerships ahead of center expansion. The national pharmaceutical regulator oversees topical corticosteroid registration through ANVISA pathways that favor documented clinical evidence. São Paulo and Rio de Janeiro anchor demand concentration as private hospital networks consolidate cancer care capabilities.
United Kingdom
NHS England procurement frameworks favor cost-effectiveness analysis against clinical evidence depth for skin toxicity protocols. Hospital network consolidated purchasing displaces individual radiation oncology center autonomy across England and Scotland. London and Manchester cancer centers drive adoption of silicone-adherent barrier technologies for head and neck cancer applications.
Global Radiodermatitis Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent wound care and dermatology spaces to build radiodermatitis credibility. The vendor base organizes around diversified medical device portfolios, specialized barrier technologies, and pharmaceutical-grade topical formulations. Three archetypes dominate: wound care conglomerates with radiation oncology distribution reach, silicone-based dressing specialists for anatomically complex sites, and pharmaceutical manufacturers leveraging corticosteroid expertise. Competitive moves concentrate on portfolio diversification into adjacent skin toxicity management and strategic partnerships with radiation oncology equipment vendors.
Within the diversified wound care tier, ConvaTec Group Plc and 3M Company exemplify manufacturers anchoring relationships through portfolio breadth spanning moist wound healing and preventive skin protocols. Mölnlycke Health Care AB occupies a position among silicone-adherent dressing specialists targeting head and neck cancer applications where anatomical complexity demands conformable technologies. These three entities represent distinct competitive vectors: portfolio breadth, distribution infrastructure scale, and material science specialization.
| Leading Market Players |
|---|
| ConvaTec Group Plc |
| Stratpharma AG |
| 3M Company |
| Helsinn Healthcare SA |
| BMG Pharma S.p.A. |
| Smith & Nephew |
| Bausch Health Companies Inc |
| Bayer AG |
| Mölnlycke Health Care AB |
| Others |
Supply & Pricing Matrix
Petrolatum and dimethicone commodity benchmarks cascade through radiodermatitis manufacturing into three distinct pricing tiers, with API cost volatility from Indian and Chinese corticosteroid suppliers compressing margins at the standard formulation level while premium silicone-barrier technologies retain pricing power through specialized material science.
Pricing Analysis
Volume concentrates in skin protectants where per-unit margins compress under hospital network consolidated purchasing, while anti-inflammatory creams and silicone-adherent dressings for head and neck cancer applications capture premium pricing through FDA-cleared device status and anatomical conformability claims. Price differentiation hinges on clinical evidence depth and ISO 13485 certification tier, with EMA Medical Device Regulation compliance adding documentation costs that stratify offerings. Pricing pressure stems from over-the-counter moisturizer substitution capturing price-sensitive patients outside reimbursed pathways. Ambulatory care facilities exhibit highest price sensitivity; academic medical centers prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with corticosteroid API manufacturing concentrated in India and China, where supply concentration creates exposure to export restriction and quality inspection disruptions. Finished product formulation and barrier technology production centers on the United States, Germany, and Japan, with hyaluronic acid and ceramide raw materials drawing from specialized biotechnology suppliers in South Korea and Switzerland. Supply chain risk manifests through PMDA inspection backlog extending lead times for novel formulation entry. Distribution runs through hospital network e-procurement platforms disintermediating traditional medical device distributors, with direct-to-clinic contracts enabling manufacturer-controlled pricing recovery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API manufacturing bottlenecks in corticosteroid supply prop pricing stability for protectant and barrier product tiers, creating supply-constrained conditions that favor incumbent capacity holders over speculative entrants.
For Market Incumbents: Anticipate moisturizer substitution threat from cosmetic brands by deepening clinical evidence portfolios for prophylactic regimens, while securing backward integration into silicone polymer supply through partnerships with German and Japanese material science specialists. Hospital network consolidation demands multi-year contract readiness with tiered volume commitments across wound care categories. For New Entrants and Emerging Players: Enter via Brazil and Mexico radiation oncology infrastructure expansion ahead of distribution partnership saturation, targeting silicone-barrier white space for head and neck cancer applications where Mölnlycke's specialization leaves mid-tier pricing uncovered. Phototherapy-drug convergence protocols offer reimbursable entry point for topical sensitizer developers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap wound care specialists with ISO 13485 certification and Tokyo-based regulatory affairs capability in Japan, where PMDA streamlined QMS procedures reduce facility audit burdens. Long-term viability hinges on portfolio breadth spanning moist wound healing through preventive radiodermatitis protocols. Signal to watch: hospital network e-procurement platform adoption velocity as disintermediation indicator.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Shortens market entry timelines for novel barrier formulations against EMA MDR compliance burdens. |
| Hospital System Partnership | Secures multi-year supply contracts with Bavarian and North Rhine-Westphalian university hospital alliances. |
| Silicone Polymer Backward Integration | Captures margin recovery and supply security for head and neck cancer dressing production. |
| Phototherapy Protocol Development | Creates new reimbursement categories for refractory cases in specialized dermatology clinics. |
| Brazil Distribution Partnership | Establishes first-mover position ahead of São Paulo and Rio de Janeiro center expansion. |
Research Methodology
Multi-period observation of radiation oncology center procurement volumes, PMDA approval timelines, and corticosteroid API pricing anchored the trend analysis, supplemented by interviews with hospital purchasing committee directors, radiation oncology nursing staff, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at barrier product manufacturers. Secondary validation drew from FDA 510(k) filings, EMA Medical Device Regulation guidance documents, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up patient-volume modeling triangulated against top-down market sizing across product type, application, and end user segments.
The input-output matrix framed demand drivers against supply constraints, with segmentation dimensions spanning product type (skin protectants through analgesics), anatomical application (head and neck through gynecological), end user facility tier, and regional regulatory cluster. CAGRs derived from fractionated radiation therapy adherence rates, cancer screening program volumes, and prophylactic protocol adoption curves. Forecast inputs incorporated silicone-adherent technology penetration rates and hospital network consolidation velocity across Germany, the United Kingdom, and Japan.
Forecast precision tightens around the base case; tail outcomes carry wider variance under PMDA inspection backlog extension, API export restriction from Indian manufacturing regions, and moisturizer substitution acceleration outside reimbursed pathways. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Dermabrasion and Micro Needling Market
Dermatology
Common Warts Market
Dermatology
Lichen Sclerosus Treatment Market
Dermatology
Acne Vulgaris Treatment Market
Dermatology
Global Onychomycosis Market
Dermatology
US and Canada Skin Cancer Dermatology Market
Dermatology
Dermatology Devices Market
Dermatology
Australia Skin Treatment Market
Dermatology
Dermatology Software Market
Dermatology
Impetigo Treatment Market
Dermatology
China Scar Treatment Market
Dermatology
Seborrheic Keratosis Treatment Market
Dermatology
Cutaneous Squamous Cell Carcinoma Market
Dermatology
Dermatology Cryosurgery Units Market
Dermatology
Radiation Dermatitis Market
Dermatology
Australia Skin Laser Market