
 Point of Care (POC) Coagulation Testing Devices Market | 2026-2036
Point of Care (POC) Coagulation Testing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Point of Care (POC) Coagulation Testing Devices Market Intelligence
Market Context with Strategic Players
The premium-laboratory-grade segment is repositioning away from handheld commodity meters on the basis of assay breadth, connectivity depth, and anticoagulant panel coverage. Werfen leverages its vertical integration into hemostasis reagents and instruments to sustain pricing power in high-acuity hospital settings. Abbott Laboratories competes through geographic dominance in decentralized cardiac surgery centers across North America and Europe.
Technical Definition and Structural Segments
Point of Care Coagulation Testing Devices are electromechanical or optical instruments designed to measure clotting time, platelet function, and fibrinolytic activity at the patient bedside using whole blood samples of 50–500 microliters, with turnaround targets under ten minutes for clinical decision-making in bleeding management. The primary commercial purpose is to eliminate central laboratory transport delays during critical interventions. Portable analyzers anchor the installed base in emergency departments and field military medicine, while microfluidic technology represents the fastest-growing architecture due to disposable cartridge miniaturization and reduced operator training burden. Consumables and reagents capture the dominant recurring revenue pool, though margin compression intensifies as contract manufacturing scales in Asia-Pacific supply chains.
Regulatory Frame and Forward-Looking Close
The FDA's Clinical Laboratory Improvement Amendments moderate-complexity classification and the EU Medical Device Regulation CE marking pathway jointly determine market access timelines and clinical validation requirements for new coagulation assay introductions. Health Canada's Therapeutic Products Directorate and Japan's PMDA impose additional jurisdiction-specific performance standards that fragment registration strategies for multinational device portfolios. Stakeholders must monitor evolving harmonization between FDA 510(k) predicate pathways and MDR clinical evidence expectations to optimize regulatory capital deployment across dual-market submissions.
Market Dynamics
Microfluidic cartridge architectures are compressing operator training requirements and expanding deployability beyond specialized coagulation laboratories into emergency departments and ambulatory surgical centers.
Growth Catalysts
- Moderate-Complexity CLIA Waivers:The FDA's streamlined 510(k) pathway for waived coagulation assays accelerates bedside deployment in United States hospital emergency departments.
- Perioperative Bleeding Protocols:Enhanced surgical safety mandates in Germany and Japan institutionalize real-time hemostasis monitoring during cardiac and trauma procedures.
- Whole-Blood Microsampling:50-microliter volume requirements eliminate phlebotomy bottlenecks and enable pediatric and neonatal testing applications.
Market Restraints
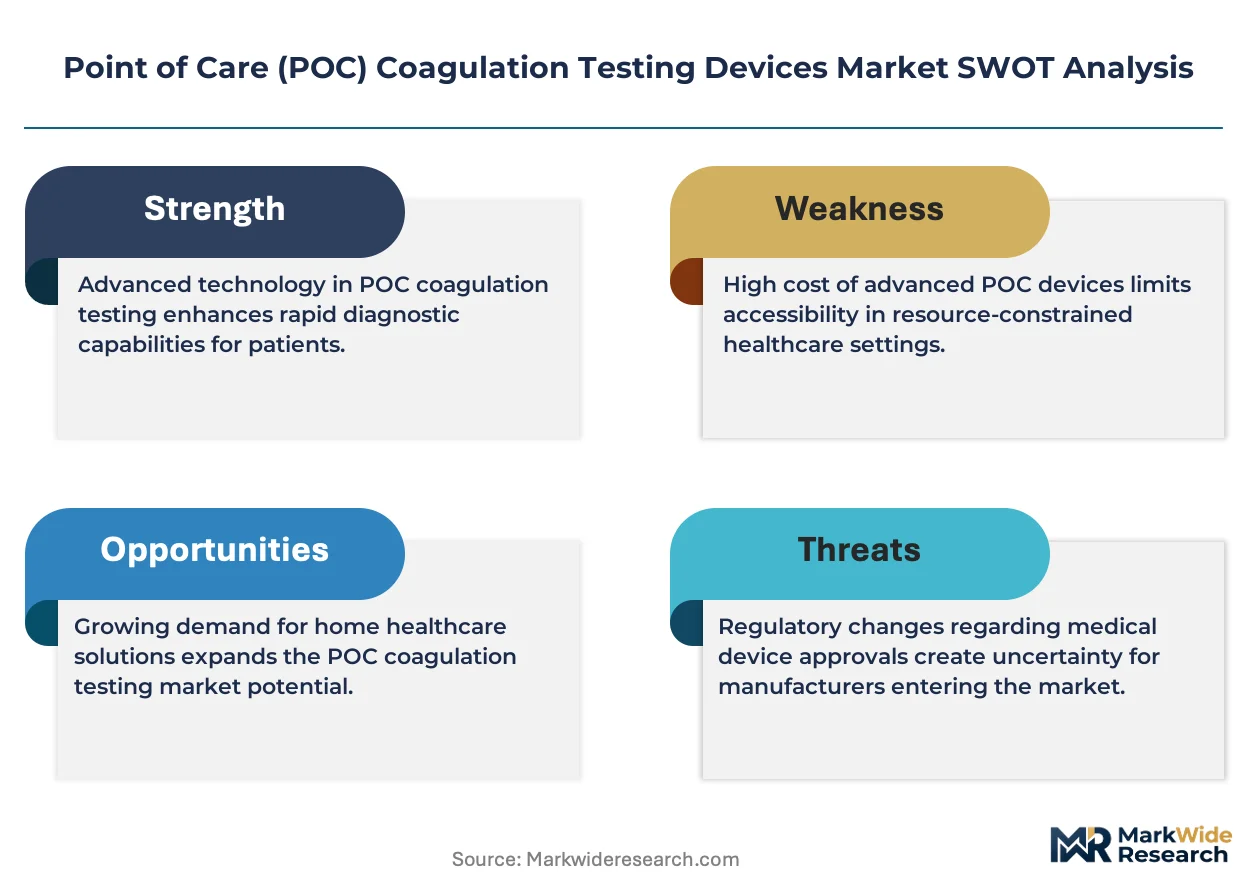
- Reagent Cold-Chain Fragility:Temperature-sensitive thromboplastin and activator reagents require controlled logistics that elevate distribution costs in tropical climates.
- Optical Sensor Component Concentration:Precision photodetector manufacturing concentrates among German and Japanese component suppliers, creating single-source vulnerabilities.
- Anticoagulant Polypharmacy Complexity:Direct oral anticoagulant proliferation fragments assay standardization and complicates result interpretation algorithms.
Strategic Opportunities
- Rural and Frontier Health Systems:United States Critical Access Hospitals lack on-site laboratory infrastructure and represent unserved demand for cartridge-based systems.
- EU MDR Harmonization:Converging clinical evidence requirements between FDA 510(k) and CE marking pathways enable synchronized dual-market submissions.
- Machine Learning Integration:Convergence of microfluidic hardware with cloud-based pattern recognition enables predictive bleeding risk stratification.
Industry Challenges
- Hemostasis Specialist Workforce Scarcity:Pathology and laboratory medicine fellowship programs produce insufficient trained personnel to support decentralized testing expansion.
- Laboratory Information System Interoperability:Bedside coagulation devices require HL7 FHIR integration with legacy hospital electronic medical record platforms.
- Quality Control Material Standardization:Commutability gaps between manufacturer-assigned values and patient sample performance create proficiency testing failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point of Care (POC) Coagulation Testing Devices Market |
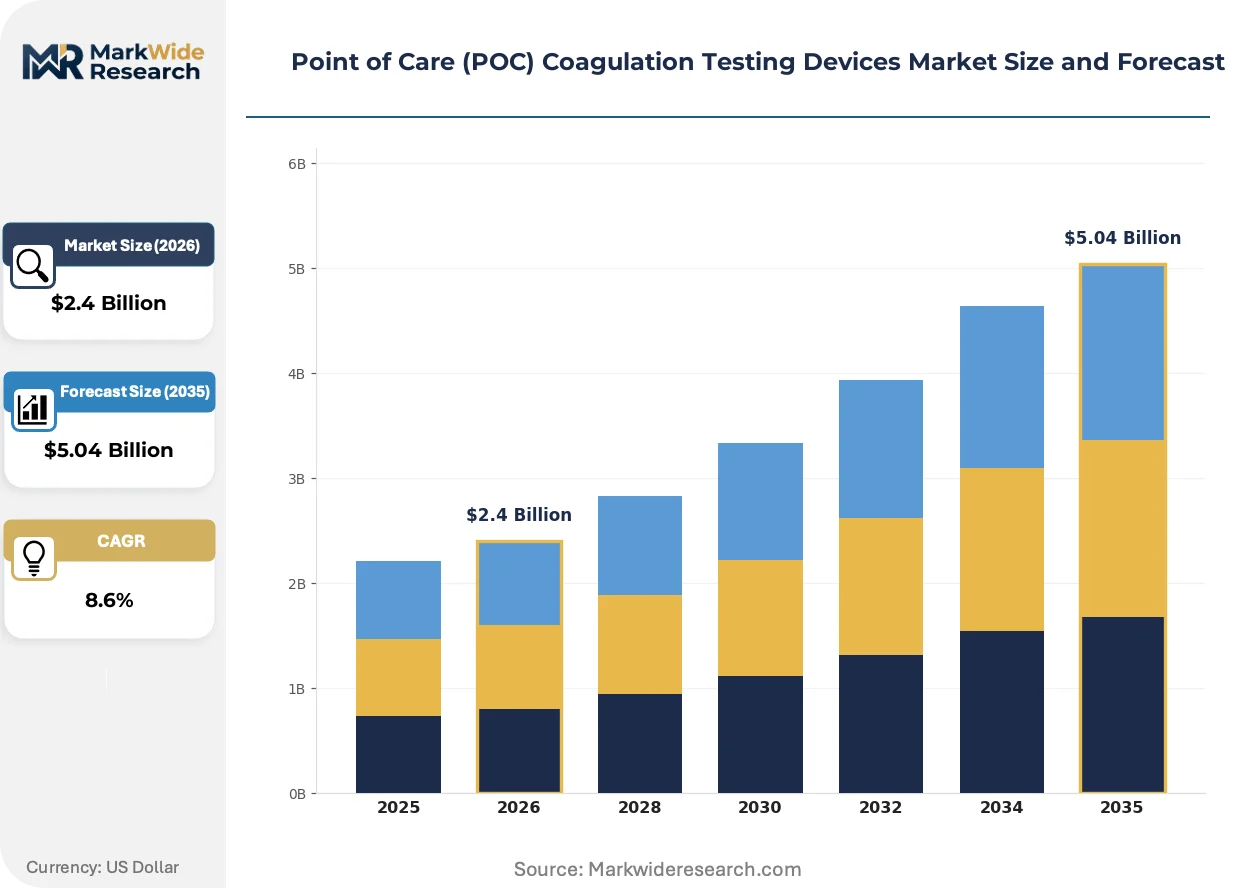
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.04 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Desktop Analyzers, Handheld Devices, Consumables, Reagents Application: Perioperative Monitoring, Anticoagulation Therapy, Emergency Diagnosis, Hemostasis Assessment, Critical Care End User: Ambulatory Care Centers, Diagnostic Laboratories, Blood Banks, Surgical Centers, Rehabilitation Clinics Technology: Electrochemical, Optical, Mechanical, Acoustic, Microfluidic |
| Companies Covered | Werfen, HemoSonics LLC, F. Hoffmann-La Roche AG, Sysmex Corporation, Medtronic plc, Abbott Laboratories, Haemonetics Corporation, Thermo Fisher Scientific, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point of Care (POC) Coagulation Testing Devices Market Strategic Shifts & Innovations
Electromechanical clot detection methods are yielding to optical and impedance-based architectures that reduce moving parts and enable disposable cartridge designs.
Microfluidic laminar flow chambers with embedded electrodes are consolidating hemostasis testing into single-use cartridges that eliminate calibration drift and reduce maintenance intervals. Cardiac surgery centers in the United States and Western Europe are adopting these systems at replacement cycle rates of four to five years. The shift is consolidating vendor relationships around reagent-locked platforms that capture recurring consumable revenue.
The EU Medical Device Regulation's enhanced clinical evidence requirements for Class IIa coagulation devices are extending notified body review timelines and elevating post-market surveillance obligations. Manufacturers must now generate prospective performance data rather than relying on predicate equivalence. High-acuity hospital segments are responding by concentrating procurement on established platforms with MDR certificates already in hand.
Hospital value-analysis committees are unbundling device capital acquisition from reagent supply agreements and negotiating multi-year total-cost-of-ownership contracts. Group purchasing organizations are displacing individual hospital negotiations in the United States acute care channel. This behavioral shift is most visible in integrated delivery networks exceeding ten hospital facilities, where standardization incentives override individual physician preference.
Point of Care (POC) Coagulation Testing Devices Market Segmentation
Segmentation in POC coagulation testing reveals how regulatory pathways, clinical workflows, and technology architectures intersect to shape procurement decisions. Each dimension carries distinct certification burdens and margin structures that determine vendor competitiveness across hospital systems.
Product Type:
Portable Analyzers require FDA 510(k) clearance under moderate-complexity CLIA classification, while Consumables and Reagents face separate IVD regulatory pathways in the United States and EU MDR technical documentation requirements.
- Portable Analyzers:Battery-powered electromechanical units weighing under 5 kilograms deploy in emergency departments and field military settings. Demand concentrates in United States cardiac surgery centers where five-minute turnaround times drive replacement cycles. The FDA's streamlined predicate pathway accelerates commercialization for devices with existing CLIA waivers.
- Consumables:Single-use cartridges and cuvettes capture recurring revenue through reagent-locked platform architectures. German hospital procurement committees negotiate multi-year total-cost-of-ownership contracts that unbundle capital acquisition from consumable supply. Cold-chain logistics for temperature-sensitive thromboplastin reagents elevate distribution costs in tropical climates.
- Desktop Analyzers:Higher-throughput systems for surgical suites requiring stationary installation and dedicated power supply.
- Handheld Devices:Pocket-sized meters for point-of-care testing in ambulatory settings with simplified user interfaces.
- Reagents:Liquid and lyophilized formulations including thromboplastin, calcium chloride, and phospholipid activators.
Consumables sit at the top of the volume ranking, with Portable Analyzers climbing the fastest as emergency departments replace aging installed bases.
Application:
Perioperative Monitoring commands premium pricing due to surgical safety mandates, while Emergency Diagnosis segments compete on speed-to-result and ease of use in high-stress clinical environments.
- Perioperative Monitoring:Real-time hemostasis assessment during cardiac bypass and trauma procedures using whole-blood microsampling. Japan's Ministry of Health institutionalizes bedside coagulation testing in national surgical safety protocols. Machine learning integration enables predictive bleeding risk stratification in high-acuity settings.
- Emergency Diagnosis:Rapid coagulation screening for trauma patients and acute bleeding events in emergency departments. United States Critical Access Hospitals lacking on-site laboratory infrastructure drive cartridge-based system adoption. Microfluidic architectures reduce operator training requirements for rotating clinical staff.
- Anticoagulation Therapy:INR monitoring for warfarin patients and direct oral anticoagulant reversal protocols.
- Hemostasis Assessment:Comprehensive platelet function and fibrinolytic activity evaluation in specialized coagulation laboratories.
- Critical Care:Continuous monitoring in intensive care units for disseminated intravascular coagulation and sepsis-induced coagulopathy.
Perioperative Monitoring captures the highest average selling prices, with Emergency Diagnosis expanding most quickly as CLIA-waived assays penetrate decentralized settings.
End User:
Ambulatory Care Centers and Surgical Centers represent the fastest-growing customer type as procedures shift away from inpatient facilities, while Diagnostic Laboratories defend volume through integrated health system standardization.
- Ambulatory Care Centers:Outpatient facilities performing same-day procedures requiring immediate coagulation assessment. United States group purchasing organizations consolidate procurement across integrated delivery networks exceeding ten hospital facilities. Value-analysis committees prioritize platforms with established EU MDR certificates.
- Surgical Centers:Dedicated facilities for cardiac, orthopedic, and trauma procedures with institutionalized bleeding protocols. Germany's regional hospital networks standardize on reagent-locked platforms to capture consumable revenue. Replacement cycles of four to five years consolidate vendor relationships.
- Diagnostic Laboratories:Central hospital labs and reference laboratories with high-throughput automation.
- Blood Banks:Transfusion services screening donor units and monitoring recipient coagulation status.
- Rehabilitation Clinics:Long-term care facilities managing anticoagulation in post-surgical and stroke recovery patients.
Surgical Centers lead in revenue per installed unit, with Ambulatory Care Centers gaining share fastest as procedure volumes migrate to outpatient settings.
Technology:
Microfluidic architectures command development investment due to disposable cartridge miniaturization, while Optical and Electrochemical methods dominate the current installed base with established predicate pathways.
- Microfluidic:Laminar flow chambers with embedded electrodes consolidate testing into single-use cartridges eliminating calibration drift. Western European cardiac surgery centers adopt these systems at replacement cycle rates of four to five years. Disposable designs reduce maintenance intervals and operator training burden.
- Optical:Photodetector-based clot detection measuring changes in light transmission or scatter during fibrin formation. Precision photodetector manufacturing concentrates among German and Japanese component suppliers creating single-source vulnerabilities. Impedance-based variants reduce moving parts versus electromechanical alternatives.
- Electrochemical:Amperometric and potentiometric sensors measuring clotting time through current or voltage changes.
- Mechanical:Electromechanical detection methods using moving probes or cups to sense clot formation.
- Acoustic:Ultrasound-based detection measuring changes in acoustic impedance during coagulation cascade.
Optical systems anchor the current installed base, with Microfluidic technology showing the steepest expansion trajectory as cartridge miniaturization enables pediatric and neonatal applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized coagulation technologists and perfusionists concentrate in United States cardiac surgery centers, German university hospitals, and Japanese metropolitan medical districts, creating regional expertise clusters that shape device procurement patterns.
United States
Critical Access Hospitals in rural Montana and Alaska drive cartridge-based system demand where laboratory infrastructure is absent. The FDA's moderate-complexity CLIA waiver pathway accelerates emergency department deployment. Texas Medical Center in Houston anchors high-acuity adoption with standardized bleeding protocols across its 21-hospital network.
Germany
Regional hospital networks in Bavaria and North Rhine-Westphalia consolidate procurement through reagent-locked platform standardization. The EU MDR's enhanced clinical evidence requirements extend notified body review timelines for new assay introductions. Berlin's Charité university hospital cluster drives replacement cycles of four to five years for microfluidic architectures.
Japan
PMDA performance standards for bedside coagulation devices fragment registration strategies for multinational portfolios. The Ministry of Health institutionalizes real-time hemostasis monitoring in national surgical safety protocols. Osaka's Kansai medical corridor concentrates cardiac surgery volume and drives premium-tier analyzer demand.
United Kingdom
NHS England's value-analysis committees unbundle device capital acquisition from consumable supply agreements. The MHRA's post-Brexit regulatory framework diverges from EU MDR pathways, complicating dual-market submissions. London's Imperial College Healthcare NHS Trust standardizes procurement across its five-hospital network.
Switzerland
Swissmedic's device certification requirements align with EU MDR standards while maintaining jurisdiction-specific vigilance obligations. University hospitals in Zurich and Geneva anchor precision medicine adoption of platelet function testing. The Basel pharmaceutical corridor drives demand for anticoagulant monitoring in clinical trial settings.
Point of Care (POC) Coagulation Testing Devices Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the POC coagulation testing landscape. The vendor base stratifies into three tiers: integrated diagnostic conglomerates with captive reagent supply, specialized hemostasis instrument manufacturers, and emerging microfluidic platform developers. Strategic moves concentrate on backward integration into consumable manufacturing and multi-year total-cost-of-ownership contracting with integrated delivery networks.
Among diversified diagnostic conglomerates, F. Hoffmann-La Roche AG and Abbott Laboratories exemplify the integrated archetype through geographic dominance in decentralized cardiac surgery centers. Werfen occupies a distinct position as a hemostasis-focused specialist with upstream control over reagent and instrument production. Siemens Healthineers represents the scale-driven tier with hospital information system integration capabilities that address interoperability demands.
| Leading Market Players |
|---|
| Werfen |
| HemoSonics LLC |
| F. Hoffmann-La Roche AG |
| Sysmex Corporation |
| Medtronic plc |
| Abbott Laboratories |
| Haemonetics Corporation |
| Thermo Fisher Scientific |
| Siemens Healthineers |
| Others |
Cost & Logistics Intelligence
Photodetector component pricing indices in German and Japanese supply tiers cascade through microfluidic cartridge manufacturing into three distinct procurement bands: premium laboratory-grade systems with full anticoagulant panels, mid-tier emergency department platforms with moderate-complexity CLIA waivers, and economy handheld meters for anticoagulation monitoring. Hospital value-analysis committees exploit this stratification to unbundle capital acquisition from consumable supply agreements, compressing margins on reagent-locked platforms while sustaining pricing power for integrated surgical suites.
Pricing Analysis
Bundled device-plus-reagent contracts versus unbundled capital-only procurement splits the market into divergent pricing architectures. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier and optical sensor precision grade. Cost compression in economy handheld segments is intensifying because contract manufacturing scales in Asia-Pacific supply chains. Critical Access Hospitals in rural United States markets exhibit highest price sensitivity, while German cardiac surgery centers prioritize assay breadth over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with precision photodetector manufacturing concentrated among German and Japanese component suppliers. Final assembly draws from China, Germany, and the United States, with microfluidic cartridge molding anchored in Swiss and Taiwanese facilities. Raw material dependencies include optical-grade polymers, thromboplastin reagents, and phospholipid activators. Tariff exposure on precision electronics threatens margin stability for mid-tier platform developers. Distribution runs through group purchasing organizations in United States acute care channels and regional hospital network consortia in Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Point of Care Coagulation Testing Devices Market functions as a stable compounder underpinned by institutionalized perioperative bleeding protocols in high-acuity surgical settings. Regulatory pathway convergence between FDA 510(k) and EU MDR frameworks sustains predictable demand visibility for established platform architectures.
For Market Incumbents: Hedge against optical sensor supply concentration by qualifying secondary photodetector sources in South Korea and Switzerland. Deepen backward integration into thromboplastin reagent manufacturing to defend margin position against contract manufacturing entrants. Prioritize EU MDR certificate maintenance to capture procurement consolidation in German regional hospital networks. For New Entrants and Emerging Players: Begin with microfluidic cartridge architectures targeting United States Critical Access Hospitals lacking on-site laboratory infrastructure. Rural and frontier health systems represent the most penetrable white space, with CLIA-waived assay status as the essential go-to-market credential. Machine learning integration for predictive bleeding risk stratification differentiates against incumbent hardware-only offerings. For Investors and Strategic Acquirers: Asymmetric upside sits with microfluidic platform developers possessing MDR certificates and reagent-locked consumable revenue streams. Long-term viability rests on sustained replacement cycles in cardiac surgery centers and ambulatory surgical center volume migration. Watch FDA 510(k) clearance velocity for moderate-complexity coagulation assays as the inflection indicator for competitive entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certificate Acquisition | Accelerates procurement access in German regional hospital standardization programs. |
| Microfluidic Cartridge Miniaturization | Enables pediatric applications and reduces operator training burden in emergency departments. |
| CLIA Waiver Pathway Navigation | Unlocks United States Critical Access Hospital demand through streamlined FDA predicate clearance. |
| Reagent-Locked Platform Development | Captures recurring consumable revenue and consolidates vendor relationships in surgical centers. |
| Machine Learning Algorithm Integration | Supports predictive bleeding risk stratification in high-acuity perioperative monitoring settings. |
Research Approach
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists informed demand-side assumptions. Secondary sources include FDA 510(k) clearance databases, EU MDR notified body documentation, hospital procurement records, and CMS Medicare reimbursement filings. Bottom-up installed base modeling and top-down market sizing triangulate volume estimates.
Granularity-level framing applies product type, application, end user, and technology architecture as core segmentation dimensions, with regional regulatory cluster as an overlay. CAGRs derive from replacement cycle analysis in cardiac surgery centers and ambulatory surgical center procedure volume trajectories across the projection horizon. Pricing assumptions incorporate unbundled capital-plus-consumable contract structures and group purchasing organization negotiation dynamics.
Caveats apply where FDA 510(k) predicate pathway revisions or EU MDR clinical evidence requirement escalations could materially shift the outlook for new assay commercialization timelines. Forecasts reflect assumptions regarding CLIA waiver expansion, anticoagulant polypharmacy standardization, and optical sensor supply diversification that may prove optimistic or conservative. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
C-Reactive Protein Analyzers Market
Laboratory Equipment
Hemostasis Analyzers Market
Laboratory Equipment
Electrophoresis Transilluminator Market
Laboratory Equipment
Capillary Blood Collection Tubes Market
Laboratory Equipment
Asia-Pacific Laboratory Hoods and Enclosure Market
Laboratory Equipment
Histopathology Testing Equipment Market
Laboratory Equipment
Cuvettes Market
Laboratory Equipment
Laboratory Freezers Market
Laboratory Equipment
Muffle Laboratory Furnaces Market
Laboratory Equipment
Lab Accessories Market
Laboratory Equipment
Mobile Sterile Units Market
Laboratory Equipment
Microplate Reader Market
Laboratory Equipment
Microplate Luminometer Market
Laboratory Equipment
Molecular Microplate Readers and Washers Market
Laboratory Equipment
Absorbance Micro Plate Reader Market
Laboratory Equipment
Blood Testing Equipment Market