
 Impetigo Treatment Market | 2026-2036
Impetigo Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Impetigo Treatment Market Analysis
Subscription-based physician education and formulary maintenance programs is realigning how antibiotic manufacturers engage dermatology and primary care channels. Pfizer Inc leverages its institutional relationships with hospital systems to sustain preferential procurement contracts for oral antibiotic portfolios. Teva Pharmaceutical Industries Ltd competes through generic topical formulations that anchor price-sensitive segments in outpatient retail pharmacies. GlaxoSmithKline plc differentiates via R&D intensity in combination therapy platforms targeting resistant Staphylococcus aureus strains.
Impetigo treatment encompasses pharmacological interventions designed to eradicate superficial bacterial skin infections, primarily caused by Staphylococcus aureus and Streptococcus pyogenes, with topical mupirocin and fusidic acid representing first-line therapies due to their minimum inhibitory concentration profiles against gram-positive cocci. The primary commercial purpose centers on reducing disease transmission, preventing post-streptococcal glomerulonephritis, and minimizing scarring in pediatric populations. Topical antibiotics command the dominant margin pool due to favorable safety profiles and reduced systemic absorption, while oral antibiotics serve hospitalized patients with extensive or bullous impetigo requiring broader tissue penetration. Outpatient treatment channels generate the highest prescription volumes, though home care delivery is expanding fastest as telehealth protocols streamline remote diagnosis and prescription fulfillment.
The US FDA regulates topical antibiotic efficacy claims and antimicrobial resistance labeling, while the EMA's MDR framework governs device-drug combination products in European dermatology markets. India's CDSCO enforces BIS quality standards for imported and domestically manufactured topical formulations, shaping market access for multinational suppliers. Stakeholders must monitor evolving resistance surveillance data and regulatory pressure on antibiotic stewardship to calibrate portfolio allocation between novel agents and established generics.
Market Dynamics
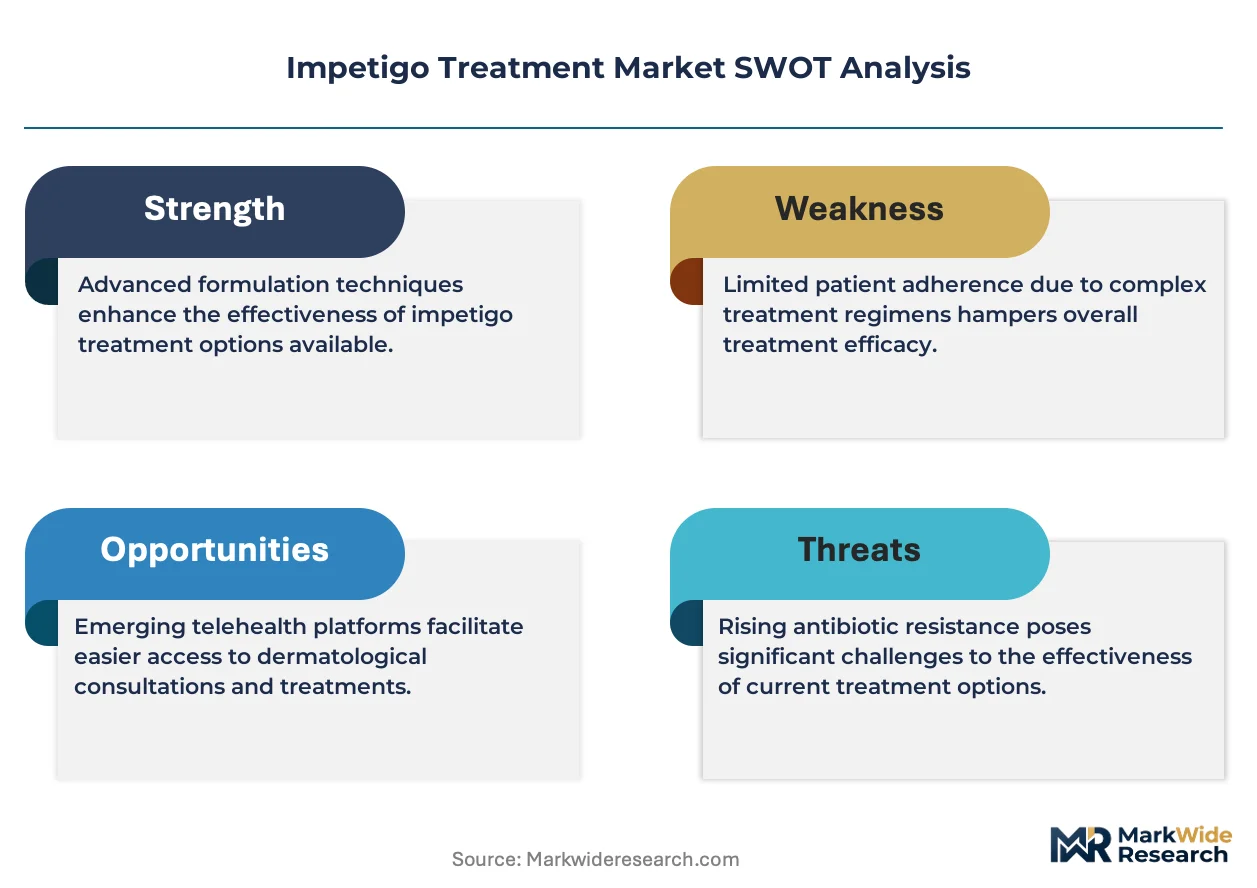
Antimicrobial resistance surveillance programs are compressing the commercial lifespan of established topical antibiotics while accelerating investment in combination therapies with novel mechanisms of action against resistant Staphylococcus aureus strains.
Growth Catalysts
- CDSCO BIS Quality Standards:India's enforcement of stricter import and domestic manufacturing standards is elevating quality benchmarks across South Asian supply chains, creating preference for certified multinational suppliers.
- Pediatric Outpatient Expansion:Primary care clinics and dermatology practices in tropical climate zones are standardizing topical mupirocin protocols as first-line intervention for non-bullous impetigo presentations.
- Telehealth Protocol Maturation:Remote diagnostic platforms with photographic lesion assessment are streamlining prescription fulfillment for home care delivery channels.
Market Restraints
- Topical Antibiotic Resistance Surveillance:The US FDA's ongoing scrutiny of minimum inhibitory concentration drift in gram-positive cocci is narrowing formulary eligibility for legacy single-agent therapies.
- API Supply Concentration:Active pharmaceutical ingredient production for fusidic acid concentrates among a limited supplier base in Eastern European manufacturing clusters.
- Substitution by Antiseptic Protocols:Povidone-iodine and chlorhexidine-based regimens are capturing price-sensitive segments where bacterial resistance concerns override antibiotic efficacy preferences.
Strategic Opportunities
- EMA MDR Device-Drug Combinations:The European framework for regulated combination products creates pathway differentiation for topical delivery systems with integrated resistance monitoring capabilities.
- Home Care Channel Penetration:Direct-to-patient fulfillment models in suburban and rural India bypass traditional pharmacy intermediaries for chronic recurrence management.
- Phage Therapy Convergence:Bacteriophage topical formulations targeting specific S. aureus strains are entering early clinical evaluation as resistance-agnostic alternatives.
Industry Challenges
- Antimicrobial Stewardship Compliance:Hospital system procurement committees now require resistance surveillance data packages that extend development timelines for new topical entrants.
- Photographic Diagnostic Standardization:Telehealth platforms lack unified lesion classification protocols, creating liability exposure for remote prescribing clinicians.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Impetigo Treatment Market |
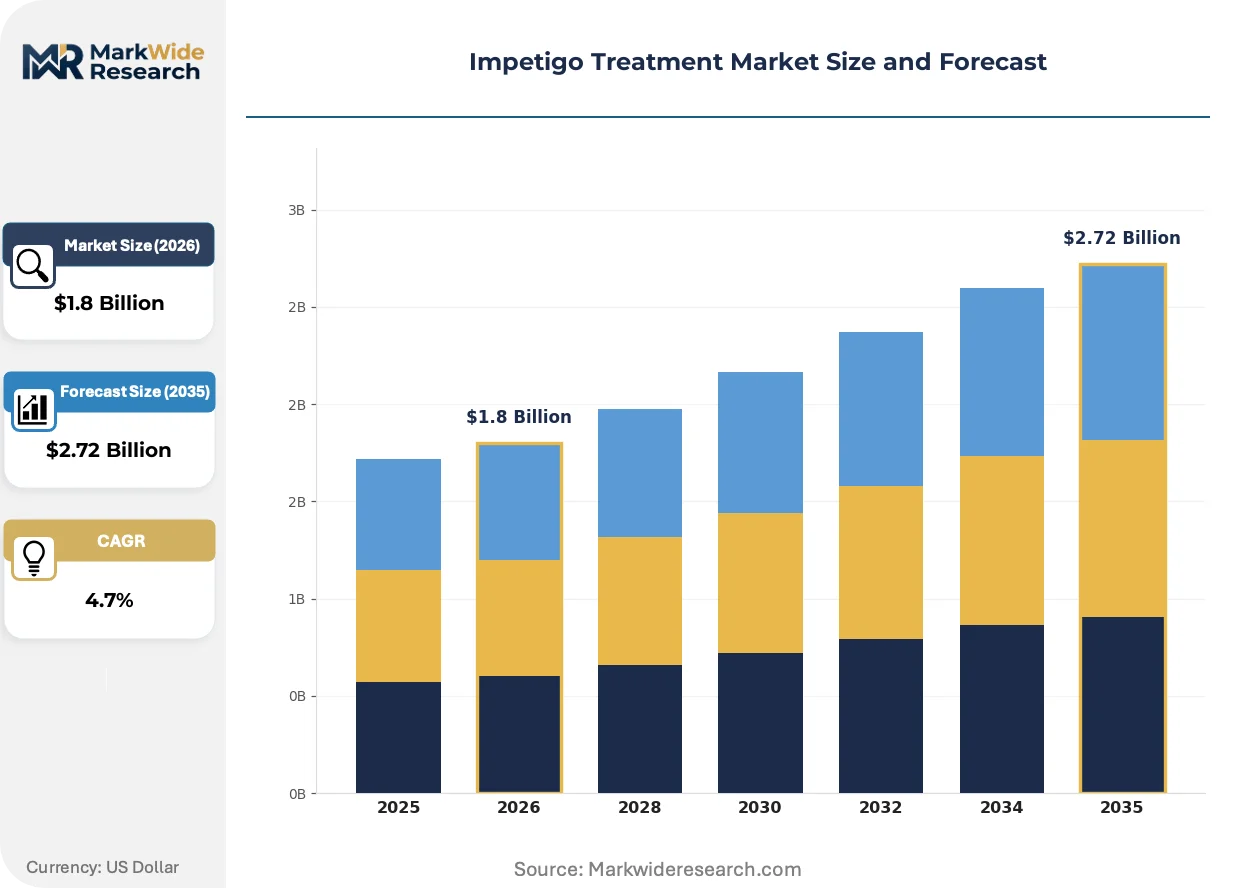
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Antibiotics, Oral Antibiotics, Antiseptics, Creams Application: Pediatric, Adult, Hospitalized Patients, Outpatient Treatment Delivery Mode: Topical, Oral, Injectable, Combination Therapy End User: Clinics, Hospitals, Home Care, Outpatient Facilities |
| Companies Covered | GlaxoSmithKline plc, Pfizer Inc, Novartis AG, Teva Pharmaceutical Industries Ltd, Medimetriks Pharmaceuticals Inc, NovaBay Pharmaceuticals Inc, Lupin Limited, Sandoz GmbH, Leo Pharma A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Impetigo Treatment Market Emerging Trajectories
Diagnostic automation and resistance-aware prescribing protocols are restructuring how clinicians select between topical and oral antibiotic tiers. Product development pipelines increasingly prioritize combination platforms over single-agent refreshes.
Microbiome-sparing topical formulations are absorbing development resources previously allocated to broad-spectrum antibiotics. Pediatric dermatology practices in the United States and Western Europe are piloting these selective agents for recurrent impetigo populations. The technology is absorbing margin pressure from generic mupirocin commoditization by creating prescriber loyalty through reduced collateral skin flora disruption.
The EMA's MDR framework for device-drug combination products is mandating clinical evidence standards that exceed traditional topical antibiotic requirements. Manufacturers must now generate resistance surveillance data across multi-year follow-up periods for integrated delivery systems. European dermatology markets are responding by consolidating procurement around suppliers with established post-market surveillance infrastructure.
Subscription-based physician education programs are displacing traditional pharmaceutical detailing in formulary maintenance. Primary care networks in South Asia now receive resistance pattern updates through digital platforms rather than field-based representatives. This shift is most visible in India's tier-2 and tier-3 cities where specialist dermatologist density remains insufficient for conventional channel coverage.
Impetigo Treatment Market Segmentation
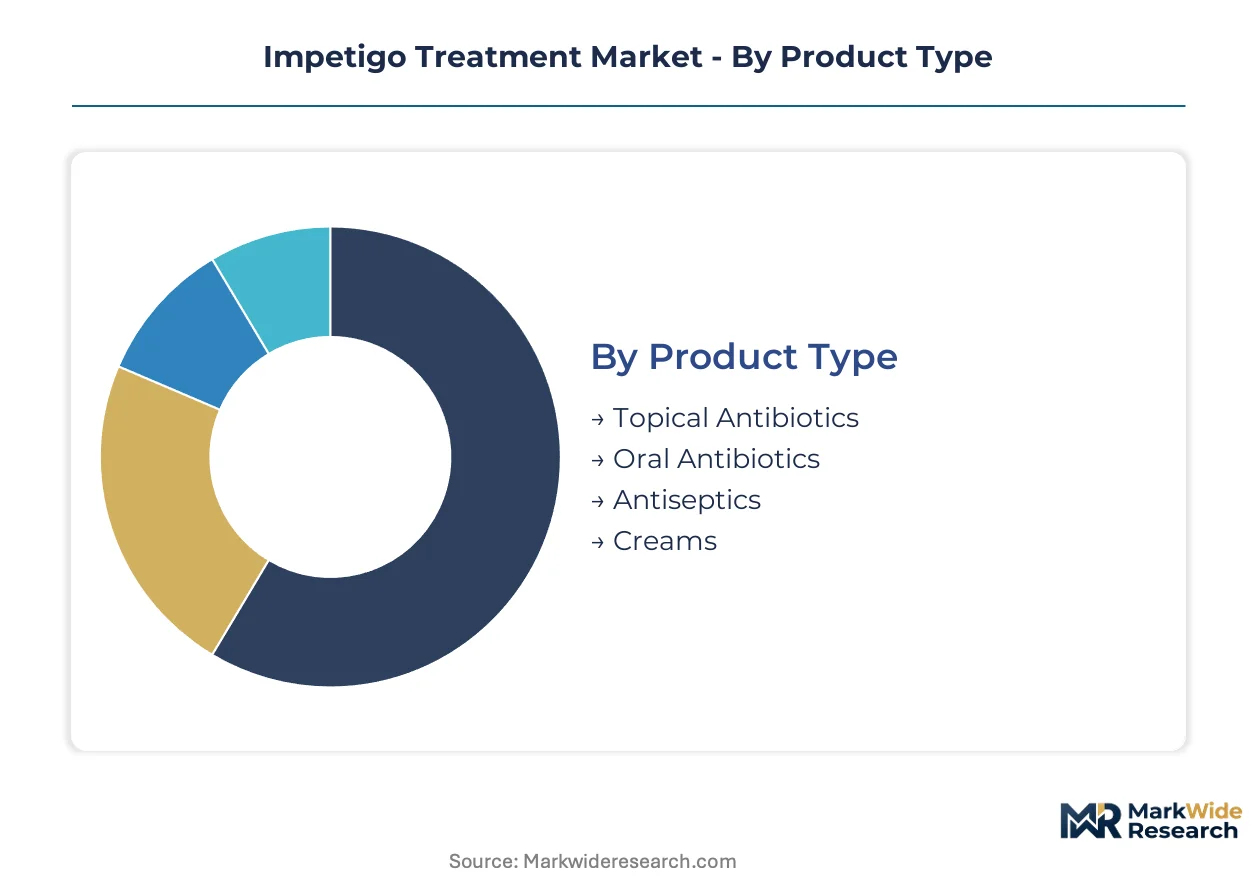
Impetigo treatment markets fragment across pharmacological form, patient population, and care setting. Portfolio allocation decisions hinge on matching resistance profiles to delivery mechanisms while navigating reimbursement complexity across institutional and retail channels.
Product Type:
Volume concentrates in established topical formulations, while premium capture shifts toward resistance-aware combination platforms.
- Topical Antibiotics:Mupirocin and fusidic acid formulations dominate first-line therapy for non-bullous presentations due to targeted gram-positive cocci activity. Pediatric outpatient clinics in South Asia generate concentrated prescription volumes where tropical climate sustains high recurrence rates. The US FDA's resistance surveillance programs are narrowing formulary eligibility for legacy single-agent variants.
- Oral Antibiotics:Cloxacillin and cephalexin serve hospitalized patients with extensive or bullous impetigo requiring deeper tissue penetration. Hospital procurement committees in the United States now mandate resistance surveillance data packages that extend commercialization timelines for new entrants.
- Antiseptics:Povidone-iodine and chlorhexidine regimens capture price-sensitive segments where bacterial resistance concerns override antibiotic preferences.
- Creams:Emollient-based delivery vehicles improve patient compliance in pediatric populations through reduced application discomfort.
Mature deployment sits with Topical Antibiotics. Newer deployment is concentrated in resistance-optimized combination platforms.
Application:
Patient age and severity stratification determines reimbursement tier and prescriber channel selection.
- Pediatric:School-age populations in tropical climate zones drive the steepest expansion trajectory as primary care standardizes mupirocin protocols. India's tier-2 and tier-3 cities show concentrated demand where specialist dermatologist density remains insufficient.
- Adult:Occupational exposure in agricultural and military settings sustains steady prescription flow. Home care delivery channels are gaining share fastest among working-age populations with telehealth-enabled remote diagnosis.
- Hospitalized Patients:Bullous and ecthyma presentations requiring intravenous escalation concentrate in tertiary care centers with infectious disease consultation capacity.
- Outpatient Treatment:Non-bullous presentations generate the highest prescription volumes through retail pharmacy fulfillment.
Volume leadership rests with Outpatient Treatment. Margin expansion concentrates in Pediatric segments through formulation differentiation.
Delivery Mode:
Route selection balances tissue penetration requirements against antimicrobial stewardship compliance burdens.
- Topical:Ointment and cream formulations command favorable safety profiles with minimal systemic absorption. The EMA's MDR framework for device-drug combinations is elevating evidence requirements for integrated delivery systems.
- Oral:Tablet and suspension formats serve patients with extensive lesions or treatment failure on topical regimens.
- Injectable:Intravenous administration reserves for severe bullous impetigo with systemic symptoms.
- Combination Therapy:Sequential topical-oral protocols target resistant Staphylococcus aureus strains through mechanism diversification.
Standard of care anchors on Topical delivery. Combination Therapy is climbing fastest as resistance patterns intensify.
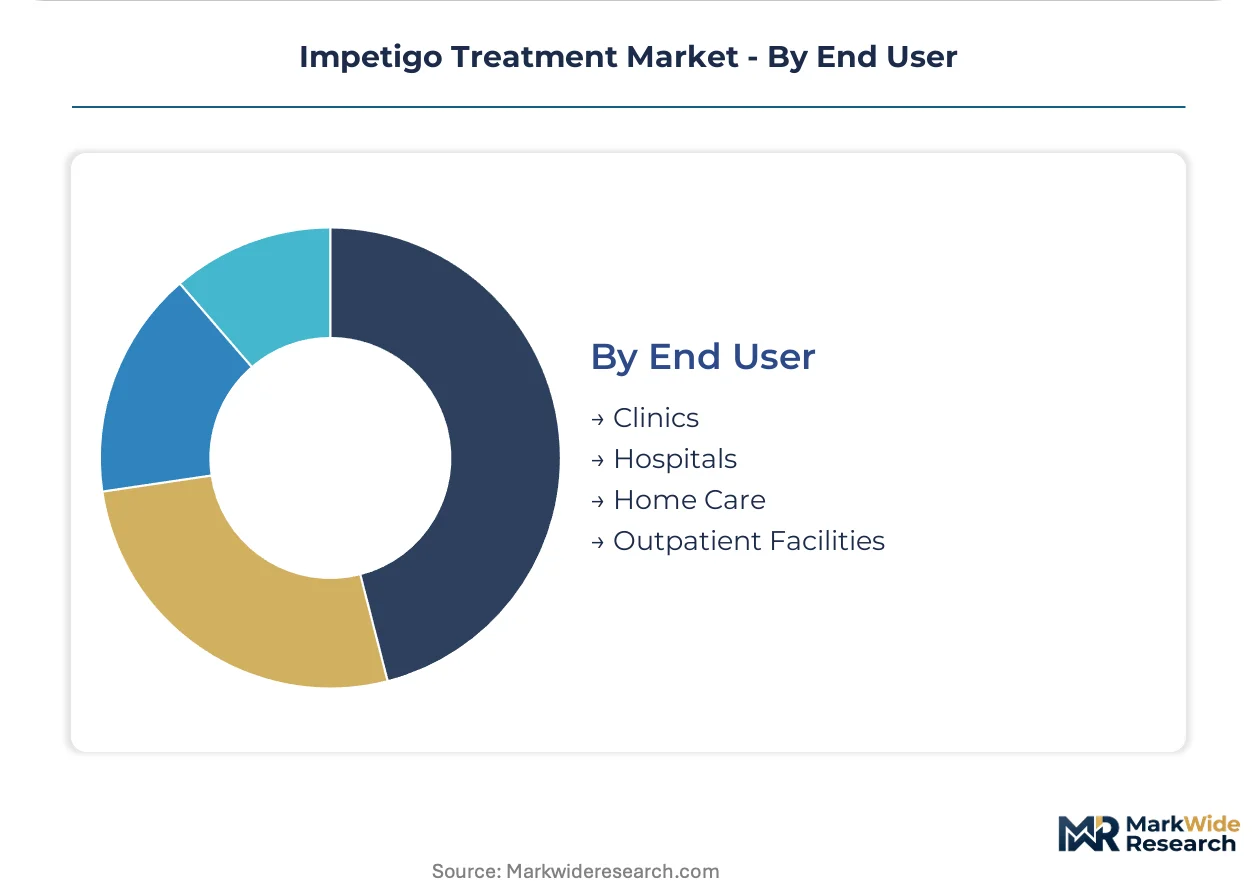
End User:
Channel selection determines formulary access, pricing power, and patient compliance monitoring capabilities.
- Clinics:Primary care and dermatology practices generate the highest prescription volumes through standardized treatment protocols.
- Hospitals:Inpatient units capture severe presentations requiring intravenous escalation and infectious disease consultation.
- Home Care:Direct-to-patient fulfillment models in suburban and rural India are bypassing traditional pharmacy intermediaries for chronic recurrence management.
- Outpatient Facilities:Urgent care and retail health clinics provide same-day diagnosis and prescription fulfillment.
Established volume flows through Clinics. Home Care is expanding most quickly via telehealth protocol maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai anchors South Asian demand concentration for impetigo therapeutics, where tropical humidity and dense pediatric populations sustain elevated bacterial skin infection incidence. The city's dermatology corridor connects to tier-2 and tier-3 distribution networks across Maharashtra state.
United States
Pediatric outpatient clinics in Houston and Miami drive prescription volume for topical mupirocin protocols. The FDA's resistance surveillance programs narrow formulary eligibility for legacy single-agent antibiotics. Philadelphia's hospital procurement networks mandate antimicrobial stewardship compliance data from new topical entrants.
India
Tier-2 cities including Pune, Nagpur, and Indore generate concentrated demand where specialist dermatologist density remains insufficient. CDSCO's BIS quality standards enforcement elevates import benchmarks for multinational suppliers. Gujarat's pharmaceutical manufacturing cluster near Ahmedabad produces generic fusidic acid formulations for domestic and export markets.
Germany
EMA's MDR framework for device-drug combination products mandates extended post-market surveillance for integrated delivery systems. Berlin's hospital networks consolidate procurement around suppliers with established resistance monitoring infrastructure. Bavaria's dermatology practices pilot microbiome-sparing formulations for recurrent pediatric cases.
United Kingdom
London's primary care networks standardize telehealth protocols with photographic lesion assessment for remote impetigo diagnosis. NICE guidelines pressure formulary committees toward antiseptic alternatives where resistance concerns intensify. Manchester's outpatient facilities generate concentrated prescription volumes for cream-based pediatric formulations.
Brazil
São Paulo's tropical climate sustains year-round transmission of Staphylococcus aureus and Streptococcus pyogenes in crowded urban settings. ANVISA's pharmaceutical quality enforcement shapes import preferences for certified topical antibiotics. Rio de Janeiro's public health system distributes generic mupirocin through community pharmacy networks.
Impetigo Treatment Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the impetigo treatment landscape, where manufacturing scale determines cost position in generic segments. The market structures around three tiers: multinational innovators with hospital system contracts, mid-scale generic manufacturers with regional pharmacy penetration, and specialty dermatology players with formulation differentiation. Consolidation pressures intensify as antimicrobial stewardship requirements raise compliance costs. Dominant competitive moves include strategic partnerships for resistance surveillance data and geographic expansion into South Asian outpatient channels.
Within the multinational tier, GlaxoSmithKline plc and Pfizer Inc occupy positions anchored by institutional procurement relationships and R&D infrastructure for combination therapies. Teva Pharmaceutical Industries Ltd exemplifies the generic manufacturer archetype, competing through price-accessible topical formulations in retail pharmacy segments. These three entities represent distinct strategic postures: innovation-focused platform development, hospital system integration, and commoditized volume capture.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Pfizer Inc |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd |
| Medimetriks Pharmaceuticals Inc |
| NovaBay Pharmaceuticals Inc |
| Lupin Limited |
| Sandoz GmbH |
| Leo Pharma A/S |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up generic manufacturers anchor supply behavior in the impetigo treatment market, compressing margins through scale-driven cost discipline while extracting pricing power from hospital formulary consolidation. Their financing structure rewards volume throughput over premium capture, reshaping how active pharmaceutical ingredient sourcing decisions translate into end-product pricing tiers.
Pricing Analysis
Value-based pricing anchored to resistance surveillance outcomes separates premium combination therapies from commoditized single-agent generics. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under FDA and EMA frameworks, with brand premiums attaching to post-market surveillance data packages. Price erosion runs through economy-tier fusidic acid generics as Indian and Chinese API oversupply intensifies. Retail pharmacy chains in South Asia exhibit highest price sensitivity, while US hospital procurement committees prioritize resistance stewardship compliance over unit cost.
Supply Chain Analysis
India's PLI scheme for pharmaceutical manufacturing is reshaping sourcing patterns, accelerating domestic production of topical antibiotic APIs previously imported from Eastern European clusters. Active pharmaceutical ingredient production draws from India, China, and Hungary, with fusidic acid fermentation capacity concentrated around Ahmedabad and Hyderabad. Mupirocin synthetic routes rest on key intermediate supplies from Zhejiang province manufacturers. Single-source vulnerability in Eastern European fermentation infrastructure creates exposure to regulatory inspection delays. Distribution runs through hospital system procurement consortia in developed markets and fragmented retail pharmacy networks in tropical climate zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API fermentation capacity constraints in certified manufacturing facilities prop pricing discipline, as post-approval inspection backlogs limit qualified supplier expansion. This supply-constrained structure favors incumbents with established regulatory dossiers and disadvantages price-competitive entrants lacking surveillance infrastructure.
For Market Incumbents: Anticipate formulary consolidation by investing in resistance surveillance data generation that satisfies US hospital procurement committee requirements. Secure backward integration into API fermentation capacity in India to defend margin position against generic import competition. Prioritize certification investment under EMA MDR device-drug combination pathways to create switching costs for European dermatology networks.
For New Entrants and Emerging Players: Enter via microbiome-sparing topical formulations targeting recurrent pediatric impetigo populations in Western Europe, where prescriber loyalty attaches to reduced collateral skin flora disruption. Target India's tier-2 and tier-3 cities through telehealth-enabled direct-to-patient fulfillment models that bypass entrenched pharmacy intermediaries. Deploy subscription-based physician education platforms rather than field-based detailing to achieve formulary access cost-effectively.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale generic manufacturers with CDSCO BIS certification and established South Asian distribution in Maharashtra and Gujarat states. Long-term viability hinges on regulatory dossier depth rather than manufacturing scale alone. Watch for FDA resistance surveillance program expansion as the inflection signal that accelerates consolidation around surveillance-capable suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Resistance Surveillance Data Generation | FDA formulary requirements now mandate multi-year post-market resistance monitoring for new topical entrants. |
| API Fermentation Capacity Expansion | CDSCO-certified manufacturing in Gujarat and Hyderabad reduces import dependency for fusidic acid supply. |
| Telehealth Protocol Development | Photographic lesion assessment platforms streamline prescription fulfillment for home care delivery channels. |
| Microbiome-Sparing Formulation R&D | Pediatric dermatology practices in Germany and the United States pilot selective agents for recurrent cases. |
| Subscription-Based Physician Education | Digital platforms displace field-based detailing in India's tier-2 and tier-3 cities with insufficient specialist density. |
Methodological Framework
Document review covered FDA resistance surveillance databases, EMA MDR submission filings, CDSCO BIS quality standards documentation, and ClinicalTrials.gov phage therapy trial records, complemented by interviews with dermatology formulary directors, hospital procurement managers, generic API manufacturing executives, and telehealth platform operators. Secondary validation drew from pharmaceutical customs data, hospital procurement contract disclosures, and regional dermatology society prescribing guidelines. Bottom-up prescription volume modeling triangulated against top-down market sizing from regulatory filings and industry association reports.
Segmentation outputs across the analysis window reflect disaggregation by pharmacological form, patient age stratification, care setting, and regional regulatory cluster. CAGRs were derived from epidemiological incidence modeling in tropical climate zones, formulary access probability weighting, and resistance surveillance program expansion trajectories. Forecast inputs incorporated antimicrobial stewardship compliance timelines, telehealth protocol maturation rates, and API manufacturing capacity utilization in certified facilities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated phage therapy clinical success or abrupt FDA formulary restriction shifts. Resistance surveillance data availability, CDSCO inspection enforcement intensity, and telehealth regulatory clarity represent key assumption dependencies. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Prescription Dermatology Therapeutics Market
Dermatology
Hyperpigmentation Disorder Treatment Market
Dermatology
Athletes Foot (Tinea Pedis) Treatment Market
Dermatology
Skin Cancer Market
Dermatology
Scar Treatment Oils Market
Dermatology
Lichen Sclerosus Treatment Market
Dermatology
Global Online Dermatology Consultation Market
Dermatology
Acne Vulgaris Market
Dermatology
Global Dermatological Therapeutics Market
Dermatology
China Scar Treatment Market
Dermatology
Psoriasis Treatment Market
Dermatology
Dermatological Products Market
Dermatology
Seborrheic Dermatitis Treatment Market
Dermatology
Dermabrasion and Micro Needling Market
Dermatology
Atopic Dermatitis Therapeutics Market
Dermatology
Global Dermatitis Herpetiformis Market