
 Corundum Market | 2026-2036
Corundum Market Size, Share, and Industry Trends Forecast 2026-2036
Corundum Market Intelligence
Advanced ceramic synthesis is reshaping how corundum performs in thermal management applications. Saint-Gobain Abrasives leverages fused grain technology to sustain dominance in precision grinding markets. Alteo Alumina anchors European supply through specialized calcined alumina production for technical ceramics. RUSAL competes on upstream bauxite-to-alumina integration, securing raw material access across Siberian operations.
Corundum is aluminum oxide in crystalline form, measuring 9 on the Mohs hardness scale and melting at approximately 2,045 degrees Celsius, valued for extreme hardness, chemical inertness, and thermal shock resistance in industrial and gem-grade applications. Synthetic corundum leads volume output due to controlled purity and lower cost than natural extraction, while specialty corundum commands premium positioning in semiconductor wafer polishing and LED sapphire substrates. Abrasives remains the largest application segment by tonnage, though electronics applications demonstrate the steepest growth trajectory driven by gallium nitride-on-sapphire device fabrication.
EPA enforcement of National Ambient Air Quality Standards constrains fused corundum smelter operations in the United States, while REACH registration requirements in Europe elevate compliance costs for imported abrasive products. OSHA permissible exposure limits for respirable crystalline silica intersect with corundum processing, mandating ventilation upgrades at grinding and crushing facilities. Stakeholders must monitor evolving semiconductor material specifications and carbon-border adjustment mechanisms that will reshape sourcing decisions for high-purity grades.
Market Dynamics
Semiconductor substrate specifications are compressing tolerances for synthetic corundum purity, forcing upstream alumina refiners to recalibrate calcination protocols and thermal management properties.
Growth Catalysts
- Gallium nitride-on-sapphire device fabrication:LED and power electronics manufacturers are scaling sapphire substrate orders for RF amplifiers and electric vehicle inverters.
- REACH registration requirements:European abrasive importers must document full supply chain substance data, favoring certified synthetic corundum over unverified natural sources.
- China's fused alumina dominance:Concentrated refractory-grade production in Henan and Shandong provinces anchors global supply for steel and cement industries.
Market Restraints
- Petroleum coke price volatility:Carbon anode costs for fused corundum smelting fluctuate with crude oil markets, squeezing margin predictability at energy-intensive operations.
- Upstream bauxite concentration:Guinean and Australian ore deposits sit with a handful of integrated miners, exposing non-integrated corundum producers to raw material access risk.
- Silicon carbide substitution:Harder abrasive grains are capturing precision grinding applications where thermal conductivity exceeds corundum performance thresholds.
Strategic Opportunities
- Indian refractory expansion:Domestic steel capacity additions under PLI scheme incentives are pulling high-alumina brick demand toward local fused grain suppliers.
- Carbon-border adjustment mechanisms:EU CBAM phase-in creates first-mover advantage for corundum producers with verified low-carbon smelting credentials.
- AI-driven process control:Machine vision sorting and predictive kiln analytics are converging to upgrade yield rates at synthetic crystal growth facilities.
Industry Challenges
- Respirable crystalline silica compliance:OSHA permissible exposure limits mandate ventilation retrofits at crushing and grinding installations, extending capital deployment timelines.
- Semiconductor material qualification cycles:Sapphire substrate vendors face 18-24 month certification protocols with foundry customers, delaying revenue recognition on purity upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corundum Market |
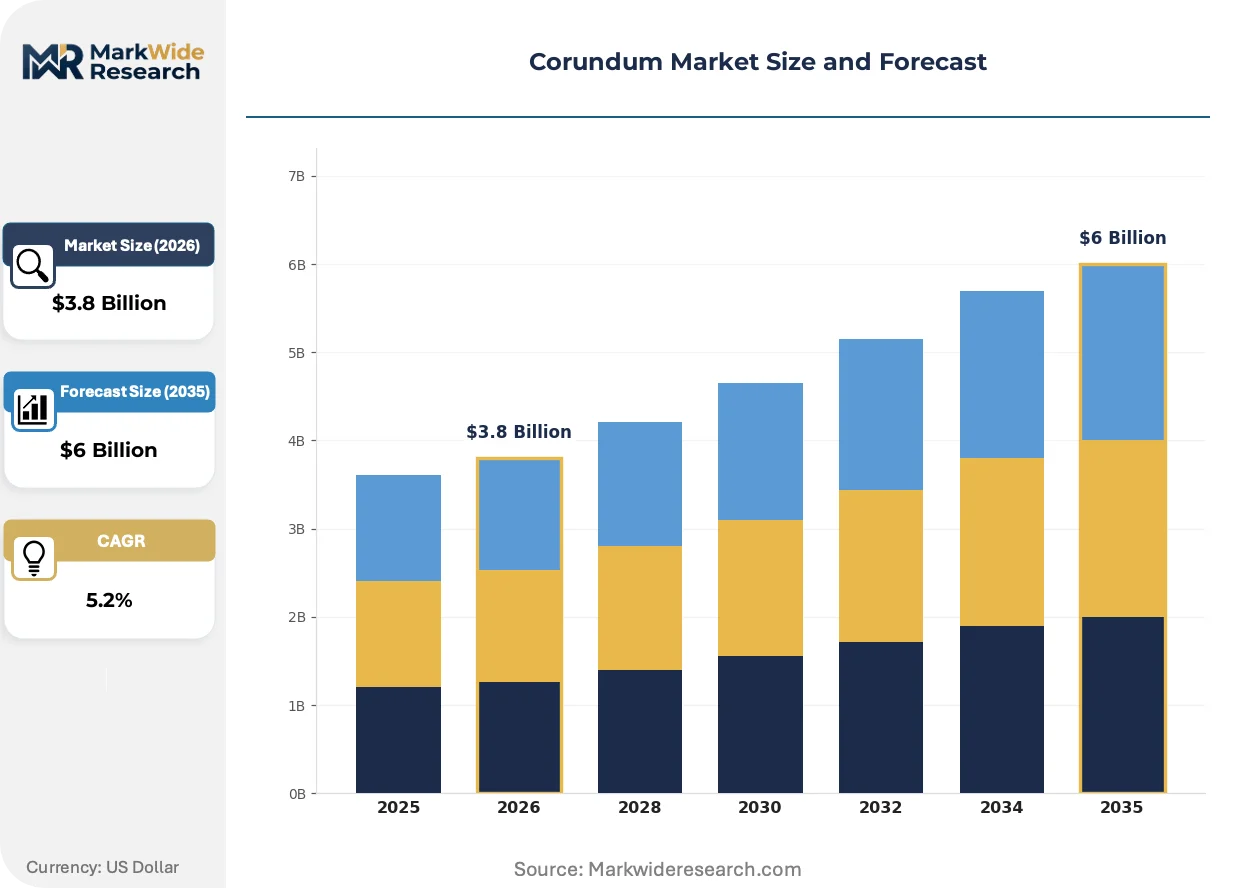
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Corundum, Synthetic Corundum, Fused Corundum, Specialty Corundum Application: Abrasives, Refractories, Jewelry, Electronics End User: Manufacturers, Retailers, Industrial, Artisans Form: Powder, Blocks, Grains, Lumps |
| Companies Covered | Saint-Gobain Abrasives, Imerys, Alteo Alumina, Washington Mills, RUSAL, Hindalco Industries, Almatis, Swarovski Gemstones, Riken Corundum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corundum Market Strategic Shifts & Innovations
Processing technology is compressing impurity thresholds while regulatory frameworks restructure competitive access across major consuming regions.
Sol-gel ceramic synthesis is migrating from laboratory demonstration to commercial abrasive grain production. Precision grinding tool manufacturers in Germany and Japan are qualifying seeded-gel alumina for camshaft and bearing applications. This migration from conventional fused grain is enabling sub-micron surface finishes that command pricing premiums in automotive powertrain machining.
EPA enforcement of National Ambient Air Quality Standards is tightening particulate emissions ceilings at fused corundum smelters. Facilities in Kentucky and Arkansas face retrofit deadlines or production curtailments. Abrasive-grade material sourcing is responding through geographic diversification toward Canadian and Mexican toll processing arrangements.
Direct long-term contracting is displacing spot market purchasing among major refractory consumers. Steel and cement producers in South Korea and Brazil are locking in multi-year fused alumina supply agreements with volume guarantees. This pattern is most visible where energy price volatility has made input cost predictability a strategic procurement priority.
Corundum Market Segmentation
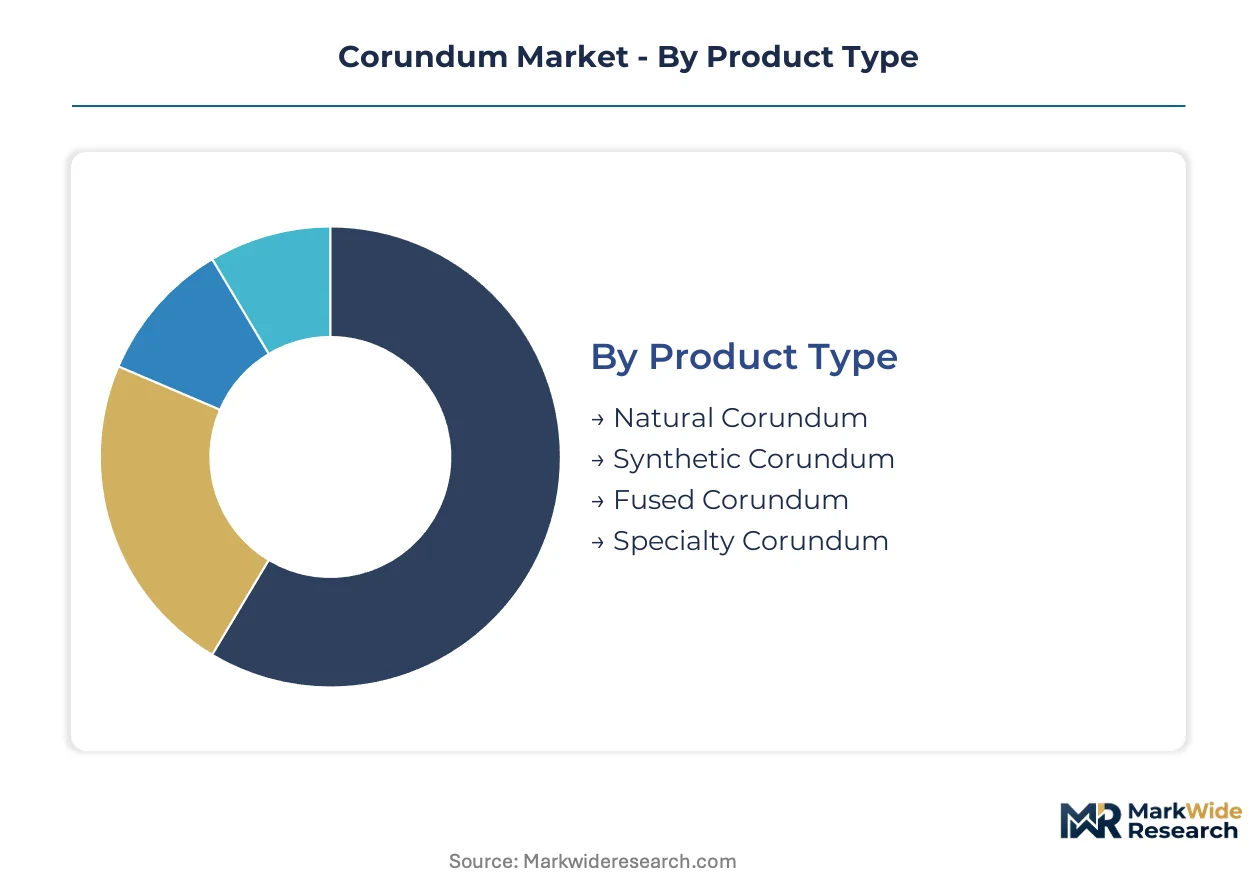
Corundum's industrial utility spans hardness-driven abrasives to purity-critical electronics substrates, demanding granular segmentation to capture divergent technical specifications and procurement patterns across end-use verticals.
Product Type:
Synthetic variants dominate mature volume channels while specialty grades capture emerging premium positioning in semiconductor applications.
- Synthetic Corundum:Manufactured through controlled fusion of high-purity alumina, this segment delivers consistent chemical composition and thermal stability. Demand concentrates in China's Henan and Shandong provinces, where fused alumina smelters serve steel and cement refractory markets under tightening MEE environmental enforcement.
- Specialty Corundum:Ultra-high purity grades engineered for semiconductor wafer polishing and LED sapphire substrates. Gallium nitride-on-sapphire device fabrication in Taiwan and South Korea is pulling precision crystal growth capacity expansion, though 18-24 month foundry qualification cycles delay revenue recognition.
- Natural Corundum:Gem-grade extraction from Myanmar and Madagascar deposits supplies jewelry channels with color-variant rubies and sapphires.
- Fused Corundum:Brown and white fused alumina grades produced via electric arc furnace reduction of calcined bauxite, serving bulk abrasive and refractory markets.
Synthetic corundum handles the majority of throughput; specialty corundum is climbing the fastest on share.
Application:
Cost-tier differentiation separates commodity tonnage from specification-driven premium positioning.
- Abrasives:Bonded and coated grinding wheels, sandpaper, and blasting media consume the largest tonnage volumes. Saint-Gobain Abrasives leverages fused grain technology to sustain dominance in precision grinding markets for automotive powertrain machining.
- Electronics:Sapphire substrates for LED epitaxy and RF power devices. Sol-gel ceramic synthesis is migrating from laboratory to commercial production, enabling sub-micron surface finishes that command pricing premiums.
- Refractories:High-alumina bricks and monolithic linings for steel, cement, and glass furnaces. Indian domestic steel capacity additions under PLI scheme incentives are pulling demand toward local fused grain suppliers.
- Jewelry:Gem-grade corundum for luxury watches and fine jewelry, distinct from industrial grades in clarity and color consistency requirements.
Abrasives commands the dominant cost-tier position; electronics is expanding most quickly on specification premiums.
End User:
Procurement patterns diverge sharply between specification-driven industrial buyers and fragmented artisan channels.
- Industrial:Steel mills, cement plants, and semiconductor foundries purchasing via direct long-term contracting. South Korean and Brazilian refractory consumers are locking in multi-year fused alumina supply agreements with volume guarantees.
- Manufacturers:Precision grinding tool producers in Germany and Japan qualifying seeded-gel alumina for camshaft and bearing applications.
- Retailers:Jewelry distributors and gem traders sourcing natural corundum through auction houses and certified dealer networks.
- Artisans:Independent lapidaries and small-scale abrasive product fabricators purchasing in smaller lot sizes.
Industrial buyers handle the majority of throughput; manufacturers are gaining share fastest on technical specification requirements.
Form:
Supply chain configuration determines form-factor availability, with powder and grains dominating bulk logistics.
- Grains:Sized abrasive grit for bonded and coated products, produced through crushing and precision screening operations.
- Powder:Micron and sub-micron grades for polishing compounds, ceramic injection molding, and thermal spray coatings.
- Blocks:Dense fused alumina masses for subsequent crushing or direct refractory brick fabrication.
- Lumps:Crude fused material for steelmaking slag conditioning and bulk refractory applications.
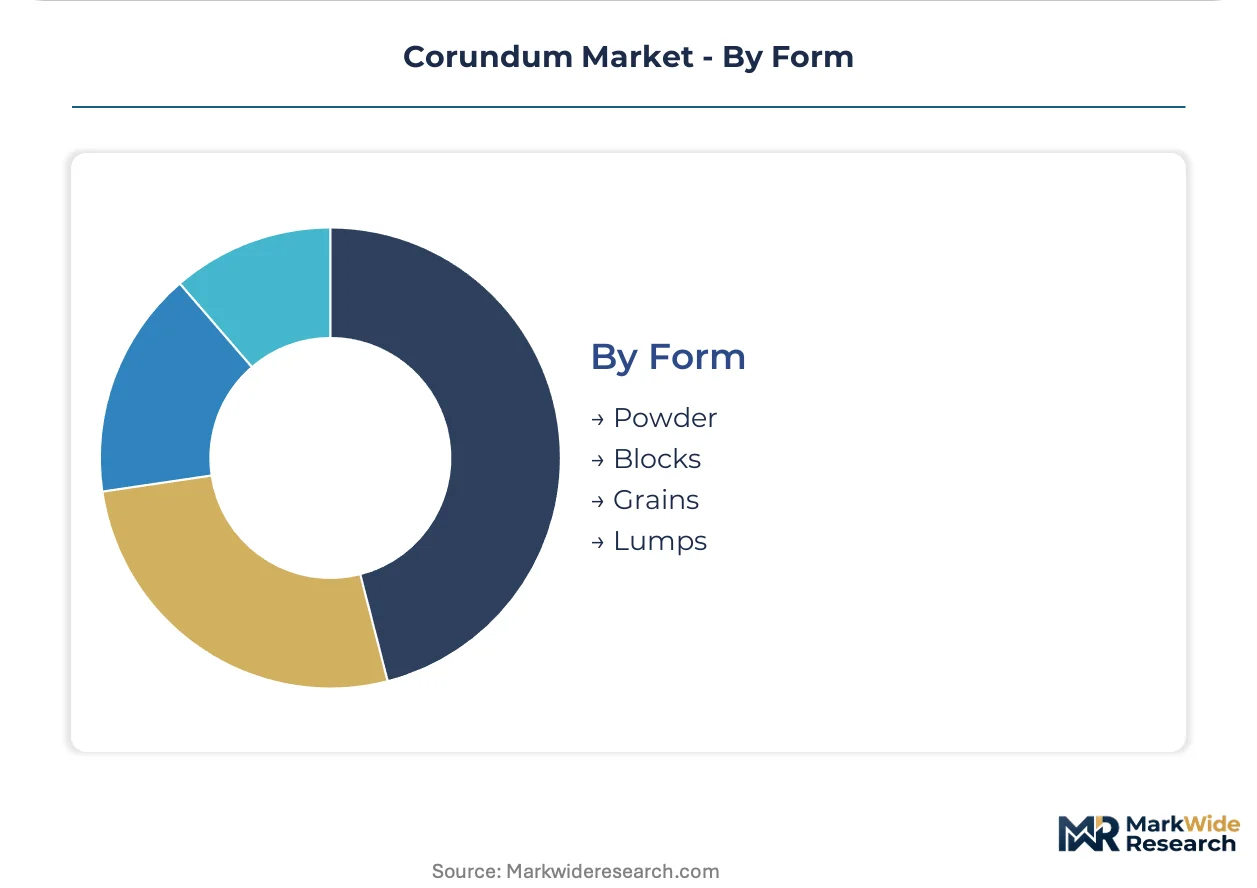
Grains handle the majority of throughput; powder is the fastest mover on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel mills and semiconductor foundries cluster procurement decisions in jurisdictions with fused alumina smelting infrastructure and sapphire substrate fabrication capacity. Geographic sourcing patterns track energy costs, environmental enforcement intensity, and bauxite refining proximity.
China
Henan and Shandong provinces host concentrated brown and white fused alumina smelting serving refractory and abrasive markets. MEE environmental enforcement has shuttered outdated capacity, consolidating output among larger operators with pollution control retrofits. Zhengzhou anchors trading and logistics for domestic distribution and export.
United States
Kentucky and Arkansas fused corundum smelters face EPA National Ambient Air Quality Standards enforcement requiring particulate emissions retrofits. Semiconductor substrate demand pulls high-purity synthetic grades toward Arizona and Texas foundry clusters. Toll processing arrangements in Canada and Mexico are diversifying supply.
Germany
Precision grinding tool manufacturers in Stuttgart and Solingen qualify seeded-gel alumina for automotive powertrain machining. REACH registration requirements favor certified synthetic corundum over unverified natural sources. Bavaria-based technical ceramics producers anchor European specialty grade consumption.
India
Domestic steel capacity additions under PLI scheme incentives are pulling high-alumina brick demand toward local fused grain suppliers. Odisha and Chhattisgarh refractory clusters are expanding captive smelting. BIS standards enforcement is tightening quality specifications for imported abrasive products.
Japan
Nagoya and Osaka precision manufacturers consume micron-grade powders for ceramic injection molding and thermal spray coatings. METI industrial technology roadmaps prioritize advanced abrasive grain development. Kyushu-based sapphire substrate producers supply LED epitaxy equipment makers.
Corundum Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered supply positions. The vendor base separates into scale-driven integrated alumina refiners, precision abrasive fabricators, and specialty crystal growth operators. Three archetypes dominate: upstream bauxite-to-alumina integrators securing raw material access; precision grinding specialists leveraging sol-gel synthesis; and gem-grade distributors commanding jewelry auction channels. Capacity expansion and geographic toll-processing partnerships represent the dominant competitive moves.
Among European-based specialty producers, Alteo Alumina and Saint-Gobain Abrasives exemplify divergent strategic positions. Alteo anchors calcined alumina supply for technical ceramics through French refining infrastructure. Saint-Gobain represents the precision abrasive archetype with fused grain technology dominance. RUSAL occupies the upstream integration position with Siberian bauxite-to-alumina control.
| Leading Market Players |
|---|
| Saint-Gobain Abrasives |
| Imerys |
| Alteo Alumina |
| Washington Mills |
| RUSAL |
| Hindalco Industries |
| Almatis |
| Swarovski Gemstones |
| Riken Corundum |
| Others |
Cost & Logistics Intelligence
Henan and Shandong fused alumina smelters anchor global refractory-grade supply, concentrating margin capture with integrated operators while fragmenting pricing power among non-integrated downstream fabricators. Petroleum coke cost pass-through mechanisms and REACH compliance premiums redistribute value toward certified synthetic producers.
Pricing Analysis
Long-term offtake contracts indexed to petroleum coke and calcined bauxite benchmarks dominate abrasive-grade transactions, with pricing stratifying across premium, standard, and economy tiers based on purity certification and volume scale. Semiconductor substrate vendors face downward pricing pressure from gallium nitride device manufacturers consolidating supplier panels, while steel refractory buyers exhibit highest price sensitivity due to energy-driven margin compression at mills.
Supply Chain Analysis
Tariff exposure between China and major importing jurisdictions dominates supply chain risk planning, with brown fused alumina shipments facing escalating customs scrutiny. Raw material flows draw from Guinean and Australian bauxite deposits, Siberian alumina refineries, and Henan smelting clusters. Distribution runs through Zhengzhou trading hubs for Asian markets and Rotterdam warehousing for European REACH-certified grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where REACH registration and EPA emissions compliance create asymmetric barriers favoring incumbent certifiers over unverified challengers.
For Market Incumbents: Build switching-cost moats through multi-year semiconductor foundry qualification pipelines and captive bauxite-alumina integration. Silicon carbide substitution in precision grinding and Chinese environmental enforcement shuttering outdated smelters threaten volume positions. Prioritize sol-gel ceramic synthesis R&D and Canadian toll-processing partnerships to defend margin pools.
For New Entrants and Emerging Players: Establish a beachhead in Indian refractory markets under PLI scheme steel capacity expansion, where domestic fused grain supply gaps persist. Carbon-border adjustment mechanism certification and low-carbon smelting credentials offer unclaimed positioning. Pursue direct contracting with Odisha steel clusters bypassing established trading layers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision abrasive specialists holding seeded-gel technology but lacking upstream alumina security. Five-to-ten-year viability hinges on semiconductor substrate qualification pipelines maturing into revenue. Watch for gallium nitride-on-sapphire device fabrication capacity announcements as inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Mining | RUSAL secures Guinean ore deposits to insulate smelter feedstock from spot volatility. |
| Green Smelting Certification Program | EU CBAM compliance creates first-mover pricing power for low-carbon fused alumina. |
| Long-term Supply Agreement | South Korean refractory consumers lock in volume guarantees against energy price swings. |
| Joint Venture in Sapphire Substrate Growth | Taiwan foundry partnerships compress 18-24 month qualification cycles through co-development. |
| AI-Driven Process Control Deployment | Machine vision sorting at synthetic crystal facilities upgrades yield rates and purity consistency. |
Research Approach
Initial hypotheses were tested against primary input from fused alumina plant managers, refractory procurement leads at steel mills, semiconductor substrate engineers, and abrasive distribution channel partners, then refined against customs trade data, SEC filings from integrated alumina refiners, EPA enforcement records, and REACH registration databases. Bottom-up capacity modeling and top-down end-use consumption estimates were triangulated to converge volume figures.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation modeled by product type, application vertical, purity grade tier, and regional production hub. CAGRs were derived from slope analysis of historical consumption patterns and forward-looking semiconductor material roadmaps, incorporating gallium nitride device fabrication forecasts and steel refractory replacement cycle assumptions.
Stress conditions across petroleum coke price bands, EPA enforcement intensity, and semiconductor foundry qualification timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about bauxite supply continuity and REACH implementation timelines. Material shifts in carbon-border adjustment mechanism scope or gallium nitride-on-silicon carbide substrate migration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Thermal Spray Materials Market
Advanced Materials
Europe Blanket Aerogel Market
Advanced Materials
Anisotropic Conductive Films (ACF) Market
Advanced Materials
Wood Foam Market
Advanced Materials
APAC Advanced Building Materials Market
Advanced Materials
Advanced Nanomaterials Market
Advanced Materials
Global Aluminum Honeycomb Market
Advanced Materials
Carbon Graphite Market
Advanced Materials
Extracellular Matrix Proteins Market
Advanced Materials
Natural Single Crystal Diamond Market
Advanced Materials
Curable Materials Market
Advanced Materials
Lithium Hydride Market
Advanced Materials
2D Materials Market
Advanced Materials
Advanced Sports Materials Market
Advanced Materials
Vacuum Insulation Panels Market
Advanced Materials
Advanced Functional Materials Market