
 Synthetic Graphite Market | 2026-2036
Synthetic Graphite Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Graphite Market Analysis
Electric vehicle battery producers is redrawing procurement priorities for synthetic graphite anode material. SGL Carbon SE leverages its vertical integration from precursor to finished electrode to secure long-term supply contracts. GrafTech International anchors its position through captive needle coke production and extensive graphite electrode capacity. Tokai Carbon Co. competes on high-purity grades tailored to semiconductor and nuclear applications.
Synthetic graphite consists of carbon atoms arranged in a layered hexagonal crystalline structure, typically manufactured through high-temperature graphitization of petroleum coke or coal tar pitch at temperatures exceeding 2,500°C to achieve electrical conductivity and thermal stability. Its primary commercial purpose centers on serving as conductive material in electric arc furnace steelmaking electrodes and as the dominant anode material in lithium-ion batteries. Graphite electrodes retains the largest revenue pool tied to steel recycling intensity, while spherical graphite commands the fastest growth trajectory as battery producers qualify higher-performance anode formulations. Isostatic pressing dominates premium-grade production for semiconductor and aerospace applications where uniformity and density specifications are most stringent.
The US EPA enforces emissions controls on graphitization furnace operations, pushing producers toward renewable energy-powered facilities or carbon capture retrofits. China's MEE implements dual carbon targets that constrain expansion of coal-dependent graphitization capacity while favoring electric-arc and hydrogen-reduction pathways. The EU Battery Regulation mandates carbon footprint declarations and recycled content thresholds for batteries placed on the European market. Stakeholders must monitor evolving anode chemistry substitutions, silicon-graphite composite adoption curves, and regional carbon border adjustments that could reroute trade flows.
Market Dynamics
Battery-grade spherical graphite procurement is concentrating among vertically integrated anode producers in China, South Korea, and Japan, compressing margins for merchant suppliers while rewarding captive needle coke-to-electrode operations.
Growth Catalysts
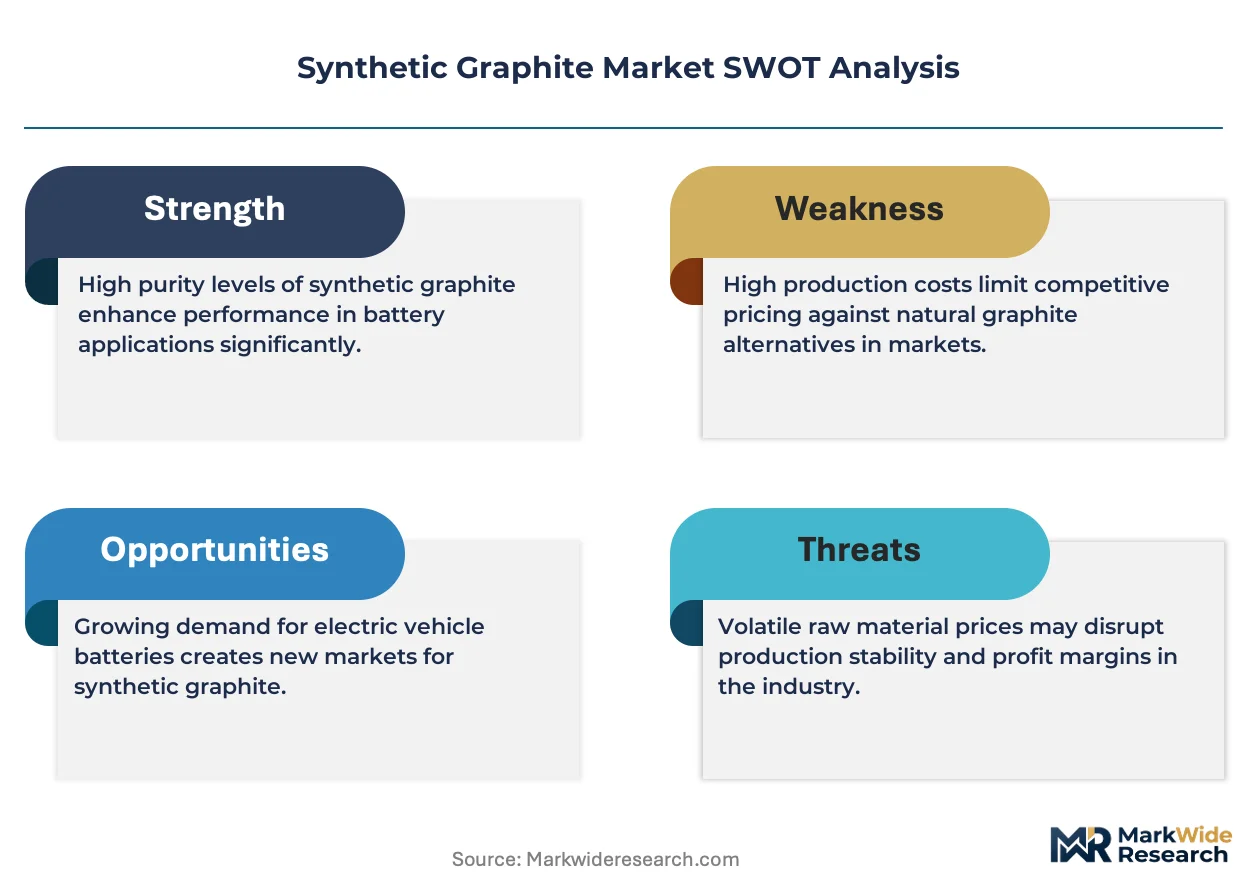
- Lithium-ion anode qualification:Electric vehicle manufacturers are locking in multi-year spherical graphite supply contracts as gigafactory capacity scales in China and South Korea.
- EU Battery Regulation recycled content mandates:Battery producers sourcing anode material for European markets must document carbon footprints and recycled content thresholds, favoring synthetic over natural graphite.
- Graphite electrode replacement cycles:Electric arc furnace steelmakers in Turkey and India are accelerating electrode consumption as scrap-based steelmaking expands.
Market Restraints
- Needle coke supply concentration:Premium petroleum needle coke production clusters with a handful of integrated oil refiners, exposing electrode manufacturers to feedstock allocation risk.
- Graphitization energy intensity:Furnace operations require sustained temperatures above 2,500°C, making electricity costs and carbon border exposure decisive competitive variables.
- Silicon anode substitution threat:Silicon-graphite composite formulations promise higher energy density, threatening pure synthetic graphite anode share in premium battery segments.
Strategic Opportunities
- North American anode supply gap:The US Inflation Reduction Act domestic content incentives are pulling battery supply chain investment toward localized synthetic graphite production.
- Semiconductor-grade isostatic graphite:Wafer processing equipment and crucible applications demand ultra-high purity grades where Japanese and German producers command technical barriers.
- Hydrogen-reduction graphitization:Pilot facilities in Norway and Canada are demonstrating near-zero-emission production pathways eligible for green hydrogen subsidies.
Industry Challenges
- Graphitization furnace operator scarcity:The specialized skill set for high-temperature furnace management and quality control is concentrated among aging workforces in China and Japan.
- Battery qualification timeline compression:Cell manufacturers demand 18-24 month anode material validation cycles that conflict with construction timelines for new graphitization capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Graphite Market |
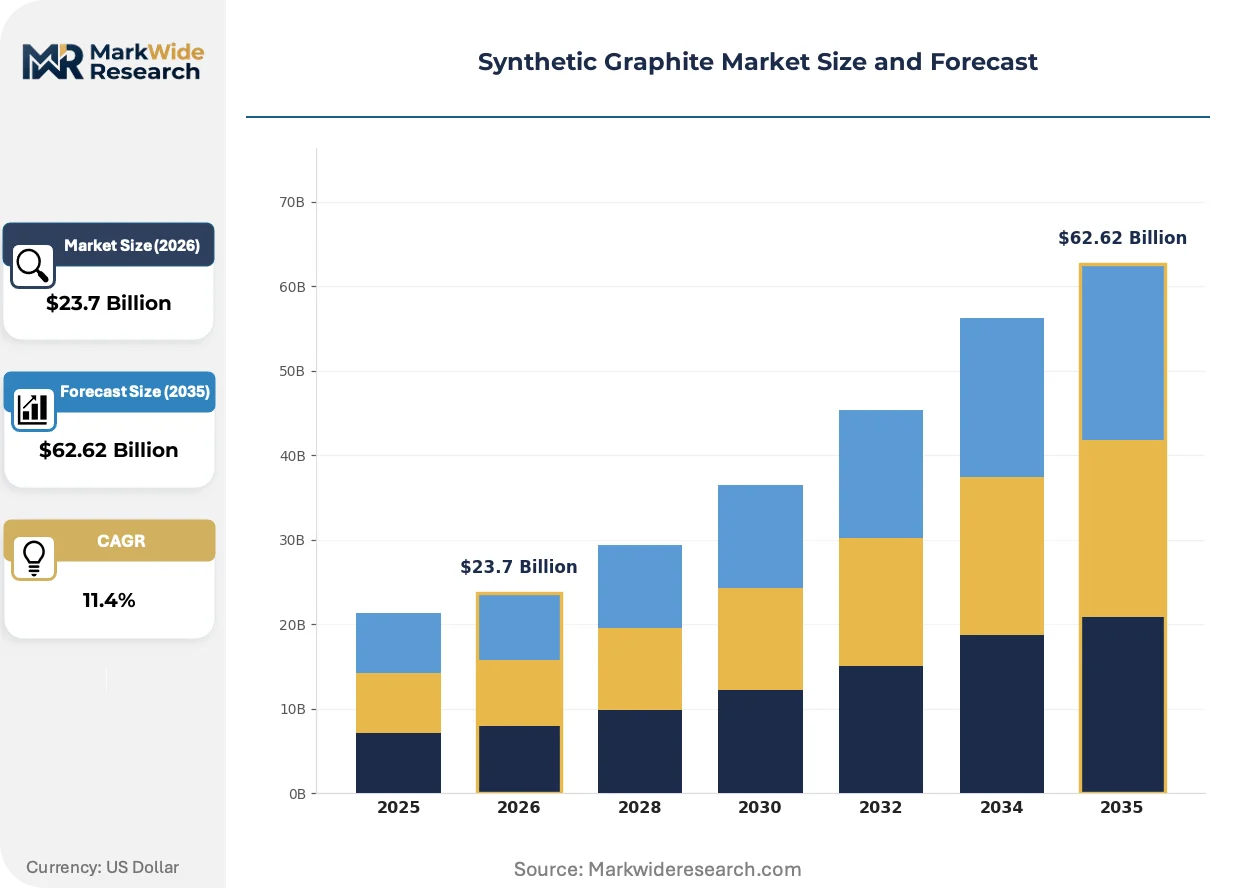
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphite Electrodes, Spherical Graphite, Other Forms, Fine Grain Application: Battery Production, Steelmaking, Foundry, Lubricants Technology: Isostatic Pressing, Vibration Molding, Extrusion, Casting End User: Automotive, Electronics, Aerospace, Renewable Energy |
| Companies Covered | SGL Carbon SE, GrafTech International, Mersen Group, Tokai Carbon Co., Toyo Tanso, Showa Denko K.K., Superior Graphite, HEG Limited, Imerys Graphite & Carbon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Graphite Market Emerging Trajectories
Electrification of transport and heavy industry is rewiring raw material specifications across the value chain, with purity thresholds, carbon intensity accounting, and circular feedstock claims emerging as decisive competitive dimensions.
Silicon-graphite composite anode formulations are fragmenting the historical dominance of pure synthetic graphite in lithium-ion cells. Battery producers in South Korea and Japan are qualifying 5-10% silicon loadings for next-generation electric vehicle platforms, compressing addressable volume for conventional spherical graphite while opening premium niches for engineered carbon-silicon interfaces. This fragmentation is forcing synthetic graphite suppliers to reposition as blend component providers rather than standalone anode material sources.
China's Ministry of Ecology and Environment dual carbon enforcement is tightening emissions benchmarks for coal-powered graphitization furnaces in Inner Mongolia and Shandong provinces. Producers are retrofitting facilities with electric-arc heating or relocating to regions with renewable energy access, raising capital intensity and favoring state-backed enterprises with balance sheet capacity. The policy is accelerating consolidation among smaller graphitization operators unable to fund compliance upgrades.
Anode material purchasing is consolidating under direct long-term offtake agreements between battery cell producers and integrated graphite suppliers, displacing spot market and trader-mediated transactions. Korean cathode and anode producers are negotiating five-to-seven-year supply contracts with Chinese graphitization specialists, locking in volume and carbon intensity specifications. This shift is most pronounced in the supply chains feeding European electric vehicle assembly plants subject to EU Battery Regulation due diligence requirements.
Synthetic Graphite Market Segmentation
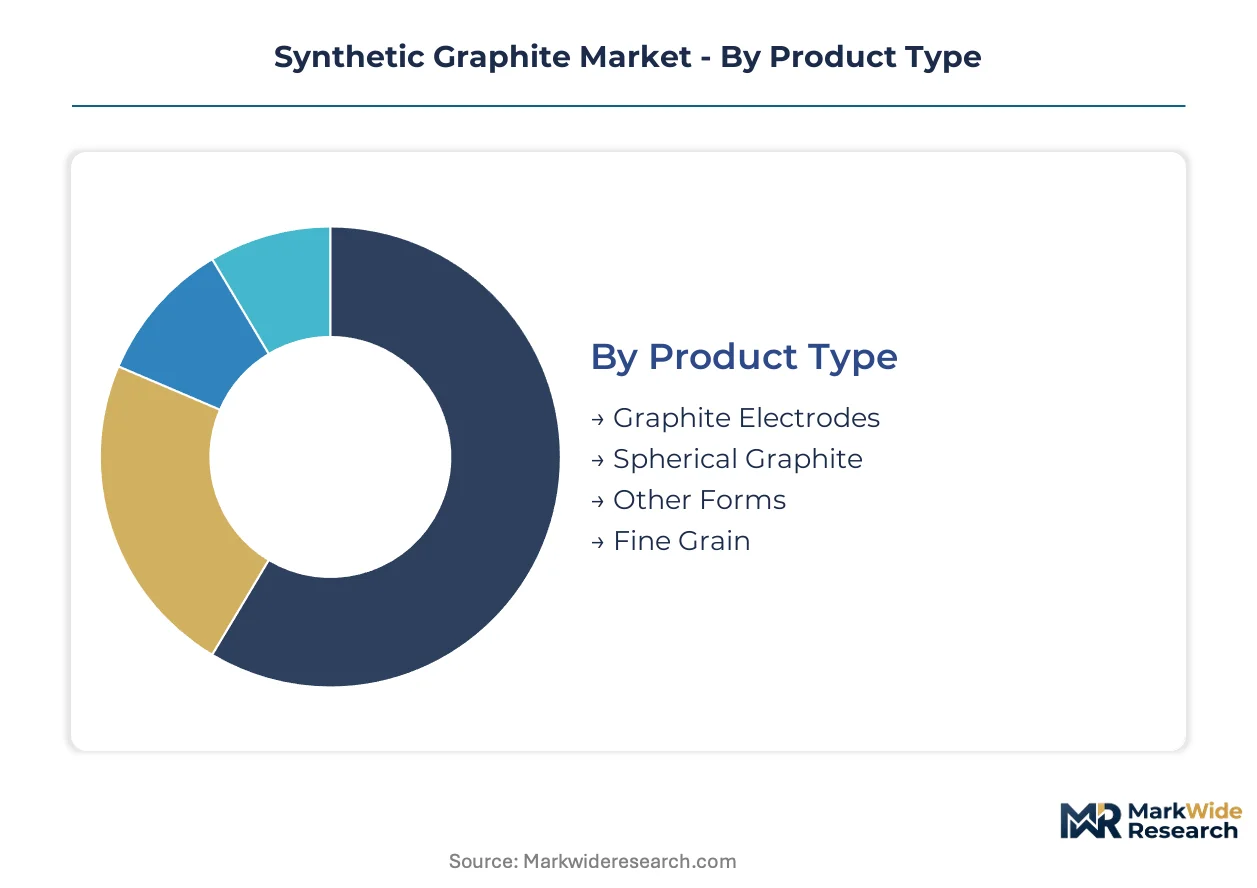
Synthetic graphite specifications diverge sharply across end-use applications, with battery-grade purity thresholds and electrode conductivity requirements driving distinct manufacturing pathways. Regulatory carbon accounting in the EU, China, and the US is fragmenting procurement criteria by segment.
Product Type:
EU Battery Regulation carbon footprint declarations and China's MEE dual carbon enforcement are bifurcating qualification standards between battery-grade and industrial-grade material streams.
- Spherical Graphite:Spheroidized particles with controlled particle size distribution and low surface area optimize packing density in lithium-ion anodes. Demand concentrates in South Korea and Japan as cathode-anode clusters expand for European electric vehicle supply chains, constrained by 18-24 month cell manufacturer qualification timelines.
- Graphite Electrodes:Ultra-high-power grades manufactured from premium petroleum needle coke sustain electric arc furnace temperatures exceeding 1,600°C. Procurement clusters in Turkey and India as scrap-based steelmaking accelerates, exposed to needle coke allocation risk from integrated oil refiners.
- Other Forms:Includes blocks, rods, and specialty shapes for crucibles and mechanical seals.
- Fine Grain:Dense microstructure grades for precision tooling and EDM electrodes requiring tight dimensional stability.
Established volume favors graphite electrodes; emerging adoption favors spherical graphite.
Application:
Carbon intensity accounting reshapes segment economics as the EU Battery Regulation and US IRA domestic content incentives reroute supply chain investment.
- Battery Production:Anode material qualification centers on spherical graphite with sub-50 ppm impurities and specified tap density. Korean producers negotiate five-to-seven-year offtake agreements with Chinese graphitization specialists, locking carbon intensity specifications for European market access.
- Steelmaking:Electric arc furnace electrode consumption tracks scrap availability and steel recycling intensity. Turkish and Indian mills accelerate replacement cycles as flat-rolled capacity expands.
- Foundry:Inoculation and chill applications in cast iron production.
- Lubricants:Colloidal dispersions for high-temperature and extreme-pressure environments.
Revenue concentration sits with steelmaking; steepest expansion trajectory belongs to battery production.
Technology:
Energy input requirements and capital intensity stratify competitive positioning across formation methods.
- Isostatic Pressing:Uniform omnidirectional pressure achieves near-theoretical density for semiconductor wafer processing equipment and nuclear moderator applications. Japanese and German producers command technical barriers in ultra-high purity grades.
- Extrusion:Continuous forming dominates graphite electrode production for electric arc furnaces, with conductivity specifications tied to needle coke quality hierarchy.
- Vibration Molding:Bulk forming for large-diameter electrodes and furnace linings.
- Casting:Near-net-shape production for complex geometries in limited specialty applications.
Margin premiums accrue to isostatic pressing; volume scale belongs to extrusion.
End User:
Customer technical specifications and qualification rigor segment supplier relationships by industry.
- Automotive:Cell producers demand documented carbon footprints and recycled content thresholds under EU Battery Regulation, favoring synthetic over natural graphite anodes. US IRA domestic content incentives pull investment toward localized production.
- Electronics:Semiconductor wafer processing equipment and crucible applications require isostatic grades with sub-5 ppm ash content.
- Aerospace:Thermal management components and ablative materials for extreme environments.
- Renewable Energy:Grid-scale battery storage systems qualifying anode material for cycle life performance.
Procurement consolidation concentrates in automotive; technical barriers protect electronics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Graphitization capacity clusters heavily in China, Japan, and South Korea, with emerging investments in North America responding to domestic content incentives. Regulatory carbon accounting in the EU, China, and the US is fragmenting qualification standards by geography.
China
Battery anode production scales in Inner Mongolia and Shandong provinces, driving spherical graphite procurement. The Ministry of Ecology and Environment enforces dual carbon targets that constrain coal-powered graphitization expansion. Qingdao and Dalian host integrated needle coke-to-electrode operations where producers retrofit facilities with electric-arc heating.
United States
Domestic anode material demand accelerates as battery cell gigafactories expand in the Midwest and Southeast. The Inflation Reduction Act domestic content incentives pull supply chain investment toward localized synthetic graphite production. Louisiana and Texas petrochemical corridors attract needle coke precursor investments to anchor electrode manufacturing.
Germany
Steel recycling intensity in the Ruhr region sustains ultra-high-power graphite electrode consumption. The EU Battery Regulation mandates carbon footprint declarations for batteries placed on the European market. Bavaria hosts isostatic pressing specialists serving semiconductor wafer processing equipment demand.
Japan
High-purity grades for semiconductor and nuclear applications command technical premiums in Osaka and Nagoya industrial clusters. METI industrial policy supports carbon intensity reduction in materials processing. Chubu region producers maintain captive relationships with Korean battery cell manufacturers for anode material qualification.
South Korea
Cathode and anode production clusters in Gyeonggi and Chungcheong provinces concentrate spherical graphite demand. Cell manufacturers negotiate five-to-seven-year offtake agreements with Chinese graphitization specialists. Korean producers lock carbon intensity specifications to secure European electric vehicle supply chain access.
Synthetic Graphite Market Vendor Landscape
Concentration sits with integrated needle coke producers and captive graphitization operators. The competitive terrain stratifies between state-backed Chinese enterprises with balance sheet capacity for MEE compliance retrofits, Japanese specialists commanding isostatic grade premiums, and North American players positioning for IRA-driven reshoring. Two dominant competitive moves define current positioning: backward integration into needle coke production to secure feedstock allocation, and geographic expansion toward renewable energy-powered graphitization to satisfy carbon intensity accounting.
Among European-anchored specialists, SGL Carbon SE exemplifies the integrated precursor-to-electrode archetype. GrafTech International occupies a position among North American electrode producers with captive needle coke supply. Tokai Carbon Co. represents the high-purity specialist tier targeting semiconductor and nuclear qualification requirements.
| Leading Market Players |
|---|
| SGL Carbon SE |
| GrafTech International |
| Mersen Group |
| Tokai Carbon Co. |
| Toyo Tanso |
| Showa Denko K.K. |
| Superior Graphite |
| HEG Limited |
| Imerys Graphite & Carbon |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four month qualification timelines for battery-grade spherical graphite concentrate procurement power among integrated producers in China, South Korea, and Japan, compressing merchant supplier margins while amplifying pricing leverage for captive needle coke-to-electrode operators with carbon intensity documentation capabilities.
Pricing Analysis
The EU Battery Regulation dictates the pricing tier structure across the synthetic graphite market, mandating carbon footprint declarations and recycled content thresholds that stratify material streams. Three-tier pricing structure across premium, standard, and economy levels separates battery-grade spherical graphite with documented low-carbon intensity from industrial electrode grades and unqualified merchant supply. Cost compression in merchant spherical graphite is intensifying because Korean and Japanese cell manufacturers are locking in five-to-seven-year direct offtake agreements with integrated Chinese producers. Automotive battery producers exhibit the lowest price sensitivity due to qualification rigor and regulatory compliance requirements, while foundry and lubricant applications remain most price-sensitive.
Supply Chain Analysis
China, Japan, and South Korea anchor synthetic graphite production across battery anode, electrode, and semiconductor-grade segments. Feedstock supply draws from petroleum needle coke refined in integrated oil complexes and coal tar pitch from steelmaking byproduct streams. Single-source vulnerability concentrates in premium needle coke allocation from a handful of integrated refiners, exposing electrode manufacturers to feedstock rationing during capacity expansion cycles. Distribution runs through direct long-term offtake agreements between cell producers and integrated graphitization specialists, displacing spot market and trader-mediated transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The synthetic graphite market sits in a cyclical recovery phase driven by electric arc furnace steelmaking intensity in Turkey and India accelerating electrode replacement demand alongside battery gigafactory expansion.
For Market Incumbents: Compound backward integration into needle coke production to secure feedstock allocation against integrated refiner rationing risk. Expand renewable energy-powered graphitization capacity in regions with green hydrogen subsidy access to satisfy EU Battery Regulation carbon intensity accounting. Lock five-to-seven-year direct offtake agreements with Korean and Japanese cell manufacturers before qualification timeline compression freezes new supplier entry. For New Entrants and Emerging Players: Fast-track EU Battery Regulation carbon footprint certification for battery-grade spherical graphite to access European electric vehicle supply chains. Target North American anode material production gaps created by US Inflation Reduction Act domestic content incentives. Pursue joint development agreements with Midwest and Southeast gigafactory developers to anchor localized supply relationships before incumbent capacity comes online. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded graphitization assets in high-renewable-energy regions. Long-term viability centers on producers with demonstrated pathways to near-zero-emission hydrogen-reduction graphitization and established Korean-Japanese cell manufacturer qualification relationships. Monitor silicon-graphite composite adoption curves in South Korean and Japanese next-generation electric vehicle platforms as inflection indicator for conventional spherical graphite volume displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Needle Coke | Captive feedstock supply from Louisiana and Texas petrochemical corridors secures allocation priority against refiner rationing. |
| Renewable Energy Graphitization Retrofit | Electric-arc and hydrogen-reduction pathways in Norway and Canada unlock green hydrogen subsidies and EU market access. |
| Long-term Anode Material Offtake Agreement | Five-to-seven-year contracts with Korean cathode-anode clusters lock volume and carbon specifications for European supply chains. |
| Semiconductor-grade Isostatic Capacity Expansion | Ultra-high purity production in Bavaria and Osaka commands technical premiums for wafer processing equipment demand. |
| North American Localized Production Buildout | Midwest and Southeast gigafactory proximity satisfies US Inflation Reduction Act domestic content incentive thresholds. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with graphitization furnace operators, battery cell procurement directors, electric arc furnace steelmakers, and needle coke refinery planning officers; and secondary validation through customs and trade flow databases, SEC filings from listed electrode producers, Chinese Ministry of Ecology and Environment enforcement notices, and EU Battery Regulation implementation guidance. Bottom-up capacity and demand modeling triangulated against top-down market sizing across product type, application, technology, and end-user segmentation dimensions.
Across the analysis window, the analytical framework modeled volume and value trajectories by spherical graphite purity grade, graphite electrode power rating, isostatic pressing versus extrusion technology pathway, and regional production hub carbon intensity profile. CAGRs were derived from regression analysis of historical procurement patterns and forward projection of gigafactory commissioning schedules and steel recycling intensity curves. Forecast inputs incorporated silicon-graphite composite adoption elasticity and dual carbon policy enforcement timelines in Inner Mongolia and Shandong provinces.
Decision-makers should treat outputs as directional under base assumptions of sustained electric vehicle penetration, continued EAF steelmaking expansion in Turkey and India, and stable needle coke refinery capacity; material deviation in silicon anode substitution rates or carbon border adjustment implementation would warrant model refresh. Recalibration cycles align with material shifts in battery chemistry roadmaps and MEE enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Graphite Materials Market
Advanced Materials
Advanced Nanomaterials Market
Advanced Materials
Reinforcement Materials Market
Advanced Materials
Si-C Anode Material Market
Advanced Materials
North America Next Generation Anode Materials Market
Advanced Materials
North America Advanced Phase Change Materials Market
Advanced Materials
Curable Materials Market
Advanced Materials
Anisotropic Conductive Films (ACF) Market
Advanced Materials
Carbon Fiber Reinforced Thermoplastic (CFRTP) Composite Market
Advanced Materials
Long-Range Ordered Porous Carbon (LOPC) Market
Advanced Materials
Organic Aerogel Market
Advanced Materials
Europe Next Generation Anode Materials Market
Advanced Materials
Global Glass Filled Nylon Market
Advanced Materials
Carbon Prepreg Market
Advanced Materials
Corundum Market
Advanced Materials
Cold Plasma Market