
 Carbon Fiber Reinforced Thermoplastic (CFRTP) Composite Market | 2026-2036
Carbon Fiber Reinforced Thermoplastic (CFRTP) Composite Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Fiber Reinforced Thermoplastic (CFRTP) Composite Market Outlook
The CFRTP composite industry is pivoting around a widening split between aerospace-grade prepreg systems and automotive-commoditized injection-moldable compounds. Toray Industries leverages its carbon fiber precursor dominance to sustain premium-grade supply chains for commercial aviation. Solvay anchors European resin formulation capabilities, while Teijin Limited competes through integrated fiber-to-composite manufacturing in Asia.
Carbon fiber reinforced thermoplastic composites combine continuous or discontinuous carbon fiber reinforcement with thermoplastic matrices such as PEEK, PPS, or polyamide, processed via automated fiber placement, tape laying, or injection overmolding to achieve specific strength-to-weight ratios exceeding 200 MPa/(g/cm³). These materials serve industries requiring rapid processing cycles and end-of-life recyclability unlike thermoset alternatives. Sheet formats currently dominate commercial aerospace programs where automated layup justifies material premiums, while custom shapes represent the fastest-expanding category as automotive OEMs adopt hybrid overmolding for structural battery enclosures. Rod and tube segments remain mature, serving industrial automation and sporting goods with stable but lower-margin demand pools.
The Federal Aviation Administration certifies CFRTP airframe components under evolving damage-tolerance protocols, while the European Union Aviation Safety Agency enforces REACH-compliant resin formulations that restrict certain thermoplastic chemistries. Automotive deployment faces EPA fuel-economy standards and California Air Resources Board zero-emission vehicle mandates that reward mass reduction. Stakeholders must monitor regulatory divergence between aviation certification timelines and automotive speed-to-market requirements.
Market Dynamics
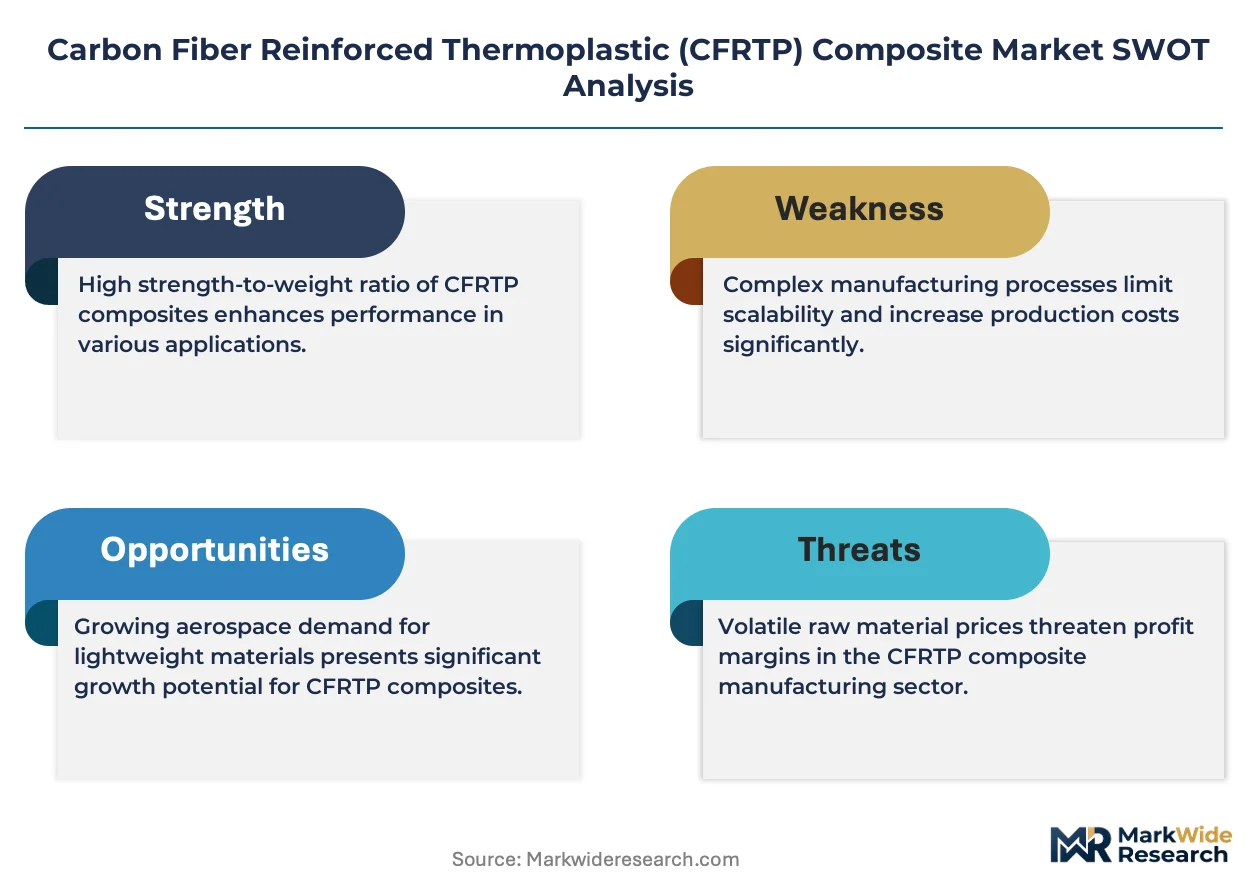
The CFRTP composite market pivots on thermoplastic substitution pressure against legacy thermoset dominance, with automated fiber placement costs dropping below manual layup thresholds in aerospace programs above five hundred units annually.
Growth Catalysts
- EU Green Deal fleet mandates:Automotive OEMs in Germany face binding CO2 reduction targets that reward thermoplastic recyclability over thermoset landfill disposal, accelerating material substitution in structural battery enclosures.
- Automated fiber placement maturation:Tape laying head speeds exceeding one meter per second now justify CFRTP premiums in commercial aviation programs, compressing processing cycles from hours to minutes.
- Damage-tolerance protocol evolution:The FAA's updated certification pathways for thermoplastic airframe components reduce qualification timelines, enabling faster program adoption by tier-one aerostructures suppliers.
Market Restraints
- Acrylonitrile price volatility:Carbon fiber precursor costs swing with propylene feedstock markets, compressing margins for composite converters locked into annual supply agreements.
- PEEK resin concentration:European polymer supply chains cluster around Solvay and Victrex production facilities, creating single-source vulnerability for aerospace-grade matrix systems.
- Welding protocol immaturity:Fusion bonding of thermoplastic laminates lacks standardized non-destructive testing methods, forcing mechanical fastening that negates weight advantages.
Strategic Opportunities
- India automotive localization:The country's PLI scheme for advanced chemistry cell batteries creates demand for thermoplastic battery tray structures currently imported from East Asia.
- Hybrid overmolding convergence:Continuous fiber tape laying combined with injection molding enables complex geometries previously requiring machined aluminum, opening industrial automation applications.
- REACH-compliant formulation gaps:ECHA restrictions on certain flame retardants in thermoplastic matrices create openings for bio-based alternatives in cabin interior applications.
Industry Challenges
- Certification timeline compression:Aviation damage-tolerance protocols require extensive fatigue testing that conflicts with automotive twelve-month product cycles, forcing dual-track qualification investments.
- Process technician scarcity:Automated fiber placement programming and in-situ consolidation monitoring demand skills absent from traditional composites training pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Fiber Reinforced Thermoplastic (CFRTP) Composite Market |
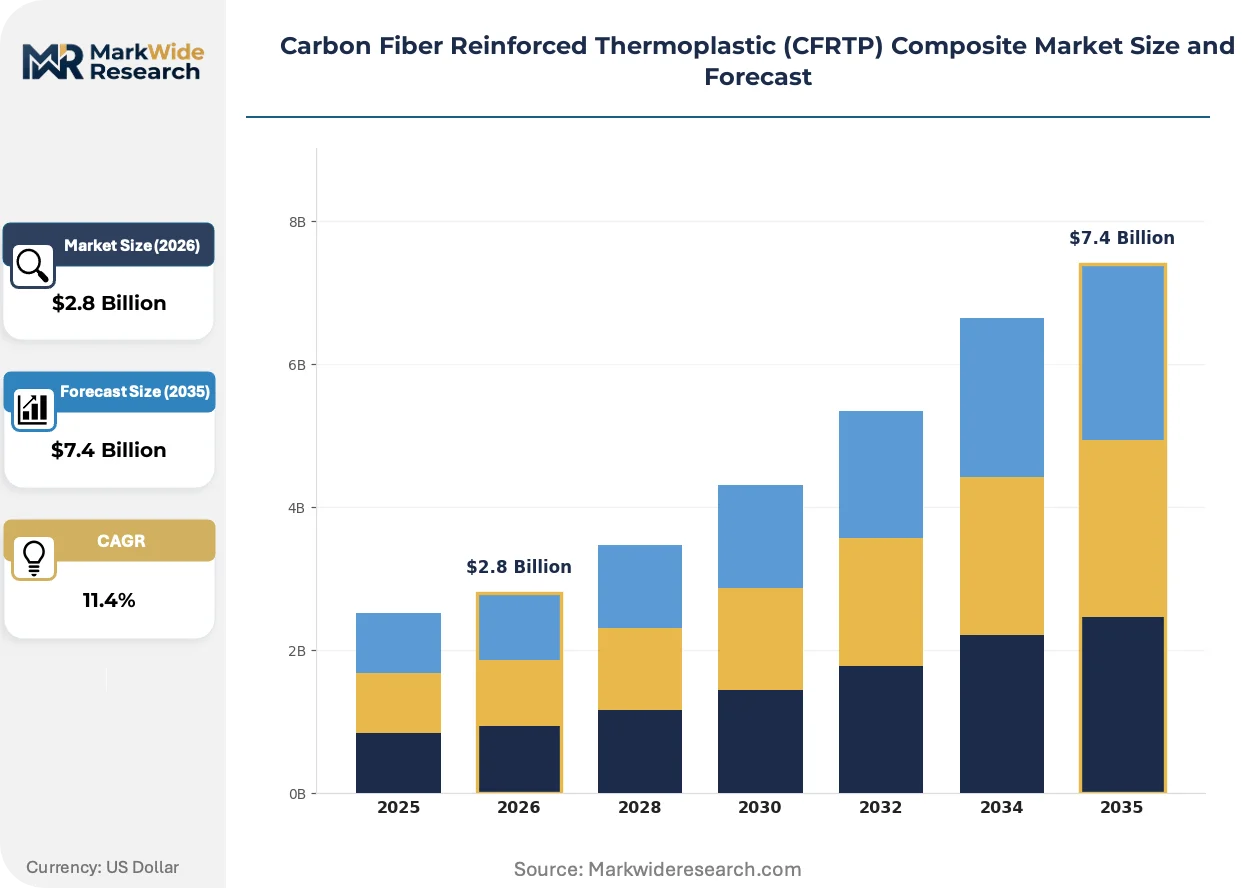
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet, Rod, Tube, Custom Shapes Application: Aerospace, Automotive, Sporting Goods, Consumer Electronics End User: Manufacturers, Engineers, Designers, OEMs Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesalers |
| Companies Covered | Toray Industries Inc., Solvay SA, Teijin Limited, Hexcel Corporation, SGL Carbon SE, Mitsubishi Chemical Corporation, BASF SE, Celanese Corporation, Asahi Kasei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Fiber Reinforced Thermoplastic (CFRTP) Composite Market Strategic Shifts
Thermoplastic processing automation is collapsing the cost barrier between aerospace-grade and industrial-grade applications, while regulatory frameworks fragment across aviation and automotive certification timelines.
Induction welding of thermoplastic composites is decentralizing assembly workflows by eliminating autoclave bottlenecks. Automotive suppliers in Germany now bond structural nodes in ninety-second cycles versus four-hour oven cures. This speed compression is enabling distributed manufacturing footprints closer to final assembly plants.
REACH Article 33 disclosure requirements are forcing resin reformulation across European aerospace supply chains. Manufacturers must now document Substances of Very High Concern in PEEK and PPS matrices, triggering substitution toward polyamide chemistries in non-critical applications. German tier-one suppliers report eighteen-month reformulation cycles to maintain EASA compliance.
Buyer consolidation among automotive OEMs is compressing supplier qualification windows. Volkswagen and BMW now mandate simultaneous engineering participation from CFRTP converters during concept phases, displacing arm's-length component procurement. This integration pressure concentrates in Munich and Stuttgart engineering centers where program decisions finalize eighteen months before production launch.
Carbon Fiber Reinforced Thermoplastic (CFRTP) Composite Market Segmentation
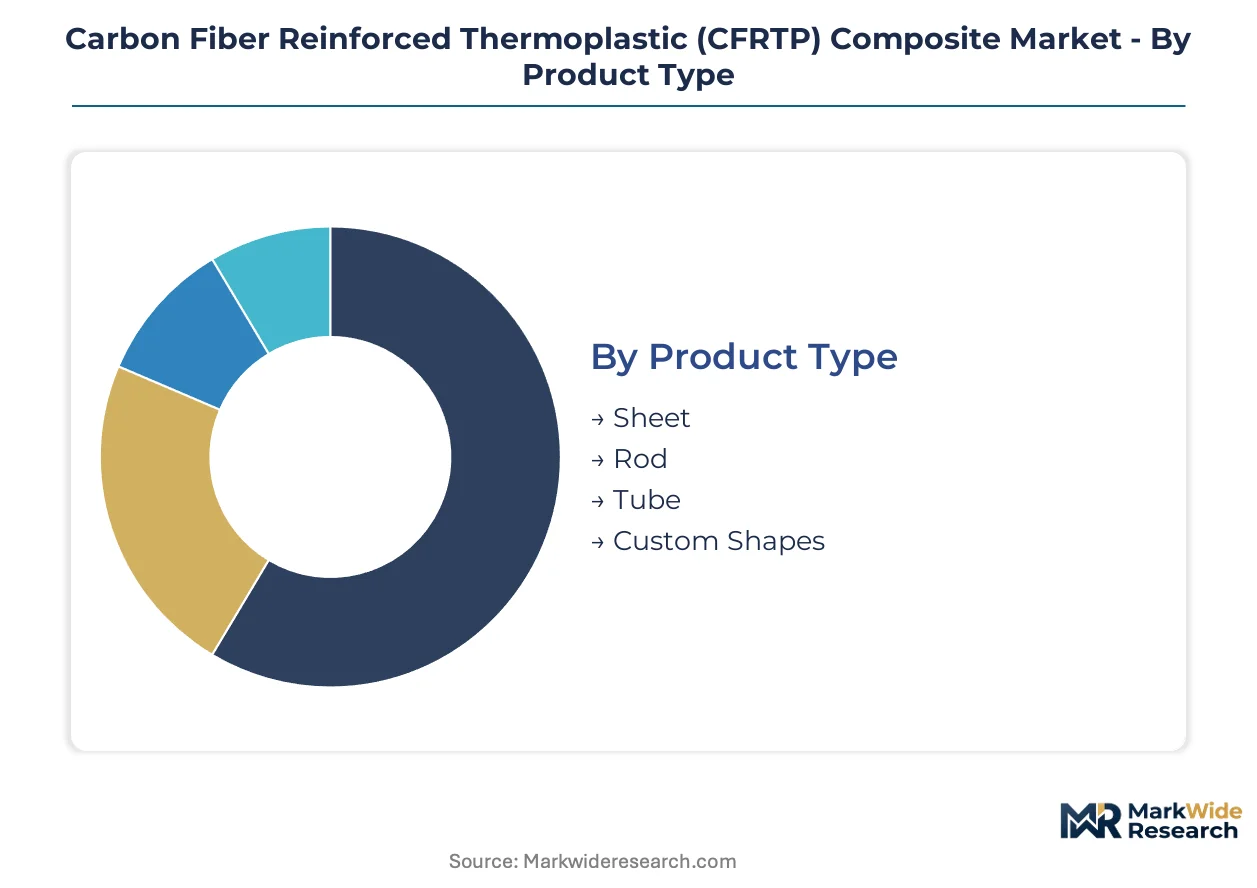
CFRTP procurement decisions split across performance thresholds, processing methods, and certification requirements. Each segmentation axis reveals distinct margin structures and buyer power dynamics that reshape supplier positioning.
Product Type:
Cost tier determines automation compatibility and scrap economics, with premium formats commanding aerospace qualification premiums and commodity shapes competing on cycle time.
- Sheet:Continuous fiber unidirectional or woven reinforcements in PEEK, PPS, or PEI matrices, supplied as consolidated laminates for automated fiber placement. Boeing and Airbus wing programs in Germany and Japan absorb volume, though autoclave-free processing mandates from EASA compress qualification windows.
- Custom Shapes:Hybrid overmolded structures combining continuous fiber cores with injection-molded thermoplastic skins. BMW structural battery enclosures in Munich anchor European demand, with Volkswagen's ID platform expanding the addressable market.
- Rod:Pultruded unidirectional profiles serving industrial automation and robotics, with standard diameters from 3mm to 50mm.
- Tube:Filament-wound or pull-braided hollow sections for sporting goods and medical equipment, competing against aluminum in weight-sensitive applications.
Volume sits with Sheet; growth tilts toward Custom Shapes.
Application:
Application selection hinges on damage-tolerance requirements versus production scale, with aviation demanding traceable fiber lots and automotive prioritizing ninety-second cycle targets.
- Aerospace:Primary and secondary structures certified under FAA damage-tolerance protocols, including wing ribs, control surfaces, and fuselage frames. Toray's T800S fiber dominates Boeing 787 successor programs, while Solvay's KetaSpire PEEK anchors European content.
- Automotive:Structural battery enclosures, seat frames, and front-end carriers where mass reduction satisfies EPA fleet standards and CARB zero-emission mandates. BMW Leipzig and Tesla Berlin Gigafactory localize German CFRTP consumption.
- Sporting Goods:Bicycle frames, hockey sticks, and golf club shafts where performance premiums justify material costs.
- Consumer Electronics:Laptop chassis and smartphone structural frames, with Apple and Samsung suppliers in South Korea and Vietnam driving thin-wall processing innovation.
Aerospace commands absolute value; automotive scales fastest.
End User:
Technical capability gaps between user types force tiered support models, with OEMs demanding co-development and designers requiring stock material availability.
- OEMs:Tier-one aerostructures and automotive suppliers with captive processing capability and direct resin formulation relationships. Airbus Hamburg and BMW Dingolfing facilities maintain in-house automated fiber placement cells.
- Manufacturers:Component converters without upstream fiber or resin capabilities, dependent on prepreg suppliers for material certification packages.
- Engineers:Product development teams specifying CFRTP for weight reduction projects, often bridging thermoset legacy designs.
- Designers:Industrial design consultancies specifying aesthetic and structural thermoplastic composites for limited-run products.
Procurement authority concentrates with OEMs; design influence spreads through Engineers.
Distribution Channel:
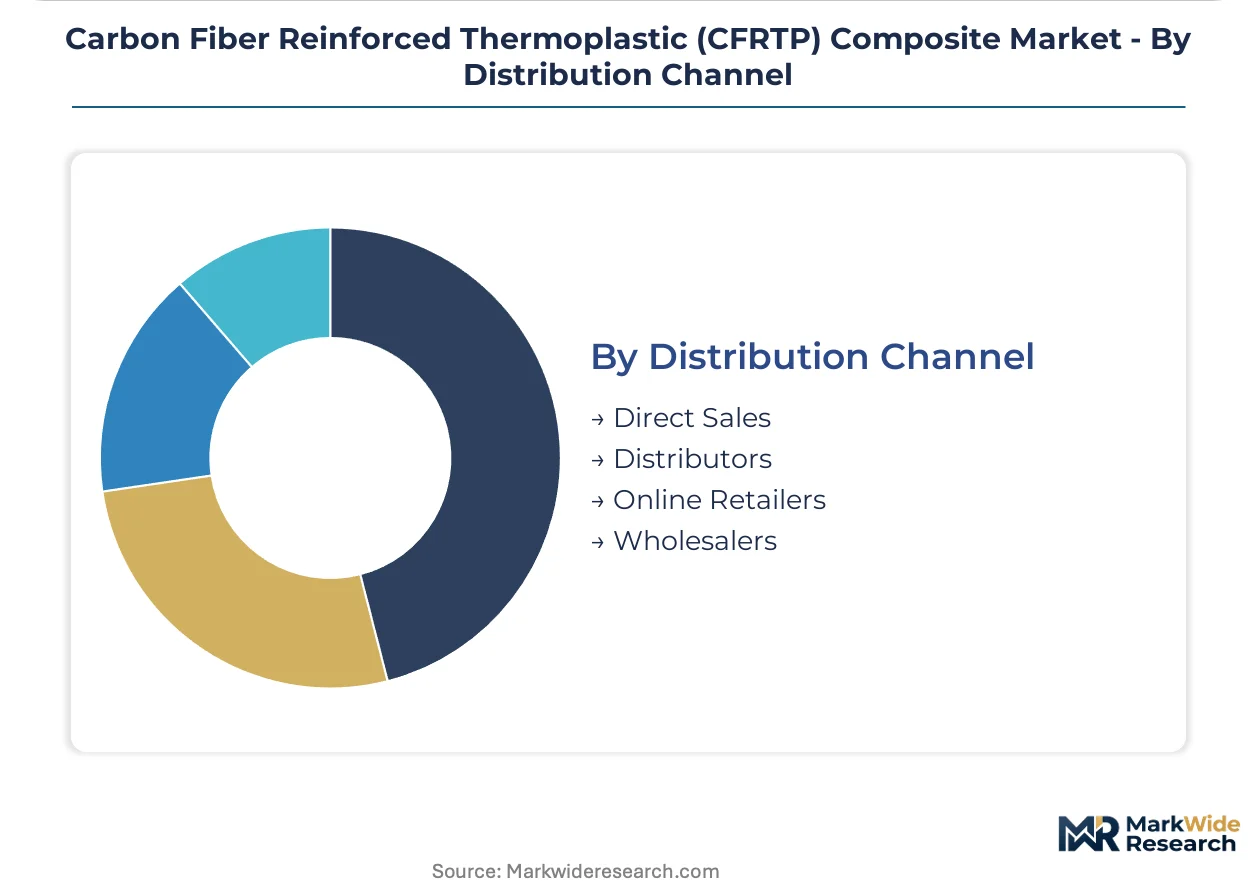
Channel selection tracks order size and technical service intensity, with direct relationships reserved for qualified aerospace programs and distributors serving fragmented industrial demand.
- Direct Sales:Long-term supply agreements with certified aerospace and automotive OEMs, including dedicated production lines and lot traceability. Toray and Teijin maintain direct sales teams in Toulouse, Hamburg, and Nagoya.
- Distributors:Regional stockists serving industrial automation and sporting goods manufacturers with standard sheet and rod formats.
- Online Retailers:E-commerce platforms supplying small-format sheet and rod to designers, prototyping shops, and research institutions.
- Wholesalers:Volume aggregators for commodity-grade injection-molding compounds and chopped fiber reinforced pellets.
Direct Sales capture program value; Distributors extend geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European CFRTP consumption through BMW and Airbus engineering centers, while Tokyo and Nagoya host integrated fiber-to-composite manufacturing clusters. Supply chain decisions concentrate in Germany, Japan, and the United States where aerospace and automotive OEMs maintain captive processing capabilities.
Germany
BMW Leipzig and Airbus Hamburg absorb volume for structural battery enclosures and wing programs. The EU Green Deal fleet mandates bind automotive OEMs to CO₂ reduction targets that reward thermoplastic recyclability. Bavaria and Baden-Württemberg host tier-one suppliers maintaining in-house automated fiber placement cells.
United States
Boeing 787 successor programs and Tesla Gigafactory Texas localize demand for aerospace-grade prepreg and automotive overmolding compounds. The FAA certifies CFRTP airframe components under evolving damage-tolerance protocols that reduce qualification timelines. Seattle and Wichita engineering centers concentrate aerostructures supplier decisions.
Japan
Toray Industries leverages carbon fiber precursor dominance to sustain premium-grade supply chains for commercial aviation. METI industrial policy supports advanced materials manufacturing competitiveness. Nagoya and Tokyo house integrated fiber-to-composite operations serving Boeing and domestic automotive programs.
China
Commercial Aircraft Corporation of China programs and BYD structural battery tray demand expand domestic CFRTP consumption. MIIT dual carbon goals accelerate lightweight material substitution in transportation applications. Shanghai and Shenzhen clusters concentrate composite converter capacity for aviation and electric vehicle supply chains.
India
The PLI scheme for advanced chemistry cell batteries creates demand for thermoplastic battery tray structures currently imported from East Asia. BIS standards development lags material qualification requirements for aerospace applications. Maharashtra and Tamil Nadu automotive corridors anchor potential localization investments.
Carbon Fiber Reinforced Thermoplastic (CFRTP) Composite Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the CFRTP composite market, with integrated fiber manufacturers holding supply chain leverage over converters dependent on external resin formulation. Market structure tilts toward consolidation at the precursor and prepreg tiers, while component fabrication remains fragmented. Two strategic archetypes dominate: integrated fiber-to-composite conglomerates controlling upstream carbon fiber supply, and specialized resin formulators anchoring matrix chemistry capabilities. Competitive moves center on backward integration into precursor production and geographic co-location with aerospace OEM engineering centers.
Within the integrated conglomerate tier, Toray Industries and Teijin Limited exemplify upstream control strategies spanning carbon fiber precursor through consolidated laminate supply. Solvay SA occupies a position as the European resin formulation anchor, with Victrex plc representing specialized high-performance polymer capabilities. These three companies collectively illustrate the geographic and functional segmentation shaping supplier relationships: Japanese fiber dominance, European chemistry expertise, and converter networks clustering around Toulouse, Hamburg, and Nagoya final assembly sites.
| Leading Market Players |
|---|
| Toray Industries Inc. |
| Solvay SA |
| Teijin Limited |
| Hexcel Corporation |
| SGL Carbon SE |
| Mitsubishi Chemical Corporation |
| BASF SE |
| Celanese Corporation |
| Asahi Kasei Corporation |
| Others |
Value Chain & Pricing Dynamics
Automated fiber placement maturation is collapsing the cost gap between aerospace-grade and automotive-commoditized CFRTP formats, concentrating margin capture with fiber precursor producers while forcing converters to absorb acrylonitrile volatility. This technology shift simultaneously enables tier-one suppliers to command qualification premiums and exposes commodity-grade processors to raw material price swings.
Pricing Analysis
Throughput-based pricing anchors aerospace prepreg contracts, where Boeing and Airbus wing programs pay for guaranteed fiber placement rates and damage-tolerance certification packages. Pricing stratifies across aerospace qualification tiers, automotive volume scale, and industrial commodity grades. Cost compression in automotive sheet formats is intensifying because BMW and Volkswagen mandate simultaneous engineering participation that front-loads R&D investment. Automotive OEMs exhibit highest price sensitivity, while FAA-certified aerostructures suppliers accept material premiums for lot traceability.
Supply Chain Analysis
Regional distribution centers in Munich, Nagoya, and Seattle maintain hub-and-spoke patterns for qualified aerospace prepreg, with tape formats shipped direct to Airbus Hamburg and Boeing Wichita facilities. Supply concentrates in Japan, Germany, and the United States, where Toray, Solvay, and Hexcel anchor precursor and resin formulation capacity. The chain rests on acrylonitrile feedstock, carbon fiber precursor, and PEEK resin inputs. Single-source vulnerability around Solvay and Victrex PEEK production creates concentration risk. Distribution runs through direct sales agreements for qualified programs and regional distributors for industrial rod and tube segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CFRTP market participation functions as a cost-of-compliance story where EASA REACH-compliant resin formulation investments create barrier-to-entry moats for qualified European suppliers.
For Market Incumbents: Acquire automated fiber placement programming capabilities to defend against Tier 1 supplier backward integration. Secure captive acrylonitrile supply through long-term propylene feedstock agreements. Certification investment in FAA damage-tolerance protocols remains the critical lever against emerging Asian fiber producers. For New Entrants and Emerging Players: Launch via hybrid overmolding partnerships with Indian automotive OEMs targeting PLI-scheme battery tray localization. White-space concentrates in REACH-compliant bio-based polyamide formulations for cabin interiors and distributed induction welding service networks for German automotive clusters. Target co-development relationships with Volkswagen and BMW engineering centers during concept phases. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated fiber-to-composite conglomerates seeking European resin formulation assets. Long-term viability favors suppliers with backward integration into carbon fiber precursor production and captive aerospace qualification relationships. Watch FAA certification timeline compression as the inflection signal for automotive-aerospace convergence plays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Toray's acrylonitrile-to-fiber control insulates margin from propylene volatility. |
| REACH-Compliant Resin Reformulation | Solvay's eighteen-month EASA certification cycles lock out unqualified competitors. |
| Hybrid Overmolding Capacity Expansion | BMW Leipzig battery enclosure demand justifies dedicated tape laying-to-injection molding lines. |
| Induction Welding Protocol Development | Ninety-second bonding cycles enable distributed manufacturing footprints near Stuttgart assembly plants. |
| India Automotive Localization Partnership | PLI scheme for advanced chemistry cell batteries creates import substitution opportunities for structural trays. |
Study Parameters
Document review covered regulatory filings from FAA and EASA, trade data from EU and Japanese customs authorities, and SEC disclosures from carbon fiber producers, complemented by interviews with aerospace procurement directors, automotive platform engineers, thermoplastic resin R&D leads, and automated fiber placement technicians. Secondary validation drew from EU Green Deal implementation reports, REACH Article 33 substance databases, and production statistics from METI and BIS. Bottom-up segment sizing and top-down macro constraint checks provided triangulation.
Market value and volume outputs across the projection horizon reflect segment-level modeling across product format, application sector, end-user capability tier, and regional production cluster. CAGRs were derived from elasticity-adjusted demand functions incorporating acrylonitrile price scenarios and automotive fleet efficiency mandate trajectories. Forecast inputs included Boeing and Airbus program ramp schedules, BMW and Volkswagen platform content assumptions, and EASA certification timeline evolution.
Feedstock price shocks, regulatory divergence between FAA and EASA damage-tolerance protocols, and welding standardization delays are the dominant revision risks. Forecasts reflect documented assumptions around automation adoption curves and OEM co-development integration depth. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Cathode Active Material Market
Advanced Materials
Synthetic Graphite Market
Advanced Materials
Carbon Graphite Market
Advanced Materials
Wood Foam Market
Advanced Materials
Rigid Foam Market
Advanced Materials
North America Polyether Ether Ketone (Peek) Market
Advanced Materials
Organic Aerogel Market
Advanced Materials
Global Aerogel Insulation Market
Advanced Materials
Global High Performance Thermoplastics Market
Advanced Materials
Liquid Thermal Interface Materials Market
Advanced Materials
High Nickel Cathode Materials Market
Advanced Materials
Vacuum Insulation Panels Market
Advanced Materials
Reinforcement Materials Market
Advanced Materials
US Graphene Market
Advanced Materials
Advanced Carbon Materials Market
Advanced Materials
Transparent Wood Market