
 Silver Nitrate Market | 2026-2036
Silver Nitrate Market Size, Share, and Industry Trends Forecast 2026-2036
Silver Nitrate Market Outlook
Consolidation among healthcare procurement groups is realigning how silver nitrate volumes flow into hospital systems and wound care distributors. Ames Goldsmith leverages its North American refining infrastructure to sustain long-term supply contracts with medical device manufacturers. Rochester Silver Works anchors its position through specialty-grade production tailored to photographic and laboratory end users. Merck differentiates via stringent analytical-grade certification protocols that command premium positioning in European laboratory markets.
Silver nitrate is an inorganic salt with the chemical formula AgNO₃, typically manufactured through the dissolution of silver metal in nitric acid followed by crystallization, yielding a colorless crystalline solid highly soluble in water and sensitive to light degradation. It serves as an essential precursor in photographic emulsions, antiseptic formulations, and organic synthesis catalysts. Pharmaceutical-grade material commands the strongest margin pool due to USP and EP compliance burdens, while analytical-grade supply competes on batch certification reliability for research institutions. Wound care applications within the healthcare end-user segment represent the fastest-expanding demand channel, driven by chronic ulcer prevalence and silver-based antimicrobial adoption in burn centers.
EPA registration requirements govern silver nitrate deployment in water treatment and antimicrobial applications across the United States, while REACH restrictions on hazardous substance classification shape formulation standards and labeling obligations throughout Europe. FDA oversight of pharmaceutical-grade silver nitrate for topical wound management imposes current Good Manufacturing Practice compliance that filters out smaller chemical suppliers. Stakeholders must monitor evolving antimicrobial resistance policies and purity standard revisions that could redirect procurement toward certified-grade producers with established regulatory dossiers.
Market Dynamics
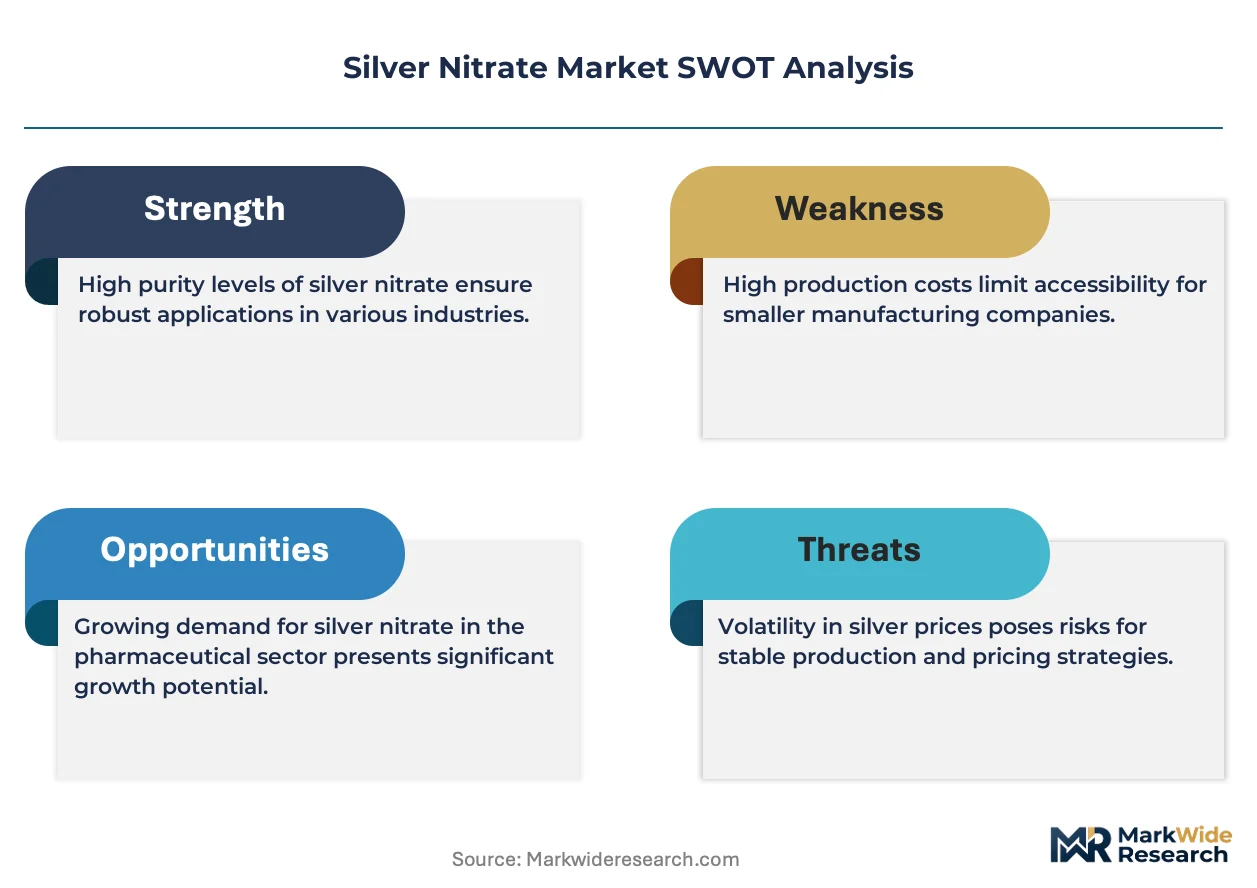
Pharmaceutical-grade purity mandates are compressing supplier margins while concentrating procurement among certified producers with established regulatory dossiers. REACH and EU MDR compliance timelines are filtering smaller chemical manufacturers from wound care supply chains.
Growth Catalysts
- Chronic wound prevalence:Rising diabetes-related ulcer incidence in Germany and the United States is expanding hospital formulary inclusion of silver-based antiseptics. Burn centers are standardizing silver nitrate protocols for partial-thickness injuries.
- REACH purity specifications:ECHA hazardous substance reclassification is forcing formulation upgrades that favor certified-grade suppliers. Medical device manufacturers are locking in long-term contracts with compliant refiners.
- Photographic emulsion stabilization:Specialty-grade demand from archival film preservation projects is creating niche volume anchors. Laboratory reagent consumption for analytical chemistry maintains baseline offtake.
Market Restraints
- Silver price volatility:London Bullion Market Association spot fluctuations transmit directly to raw material costs. Smaller compounders lack hedging infrastructure to absorb margin compression.
- Supply concentration in German chemical corridor:Refining capacity clusters along the Rhine-Ruhr industrial zone. Disruption risks from waterway logistics or environmental enforcement cascade downstream.
- Antimicrobial resistance scrutiny:WHO stewardship guidelines are tightening silver deployment in prophylactic applications. Clinical evidence requirements are extending approval timelines for new formulations.
Strategic Opportunities
- Underpenetrated Indian pharmaceutical manufacturing:CDSCO regulatory alignment with ICH standards is opening export pathways for USP-grade producers. Contract manufacturing organizations in Hyderabad and Ahmedabad are qualifying new excipient suppliers.
- EU Green Deal chemical substitution incentives:REACH authorization pressures on chlorinated disinfectants are creating tailwinds for silver-based alternatives. Green public procurement mandates favor biodegradable antimicrobial systems.
- Point-of-care diagnostic convergence:Lateral flow assay manufacturing is integrating silver nitrate reduction chemistry for signal amplification. In-vitro diagnostic producers in South Korea and Japan are scaling reagent volumes.
Industry Challenges
- Analytical chemistry talent scarcity:Batch certification for EP-grade material requires ICP-MS proficiency that competes with semiconductor and pharmaceutical quality labs. Refiners struggle to retain spectroscopy specialists.
- Multi-jurisdiction dossier maintenance:Simultaneous FDA Drug Master File, EMA CEP, and PMDA registration creates documentation overhead. Smaller producers lack regulatory affairs bandwidth for parallel submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silver Nitrate Market |
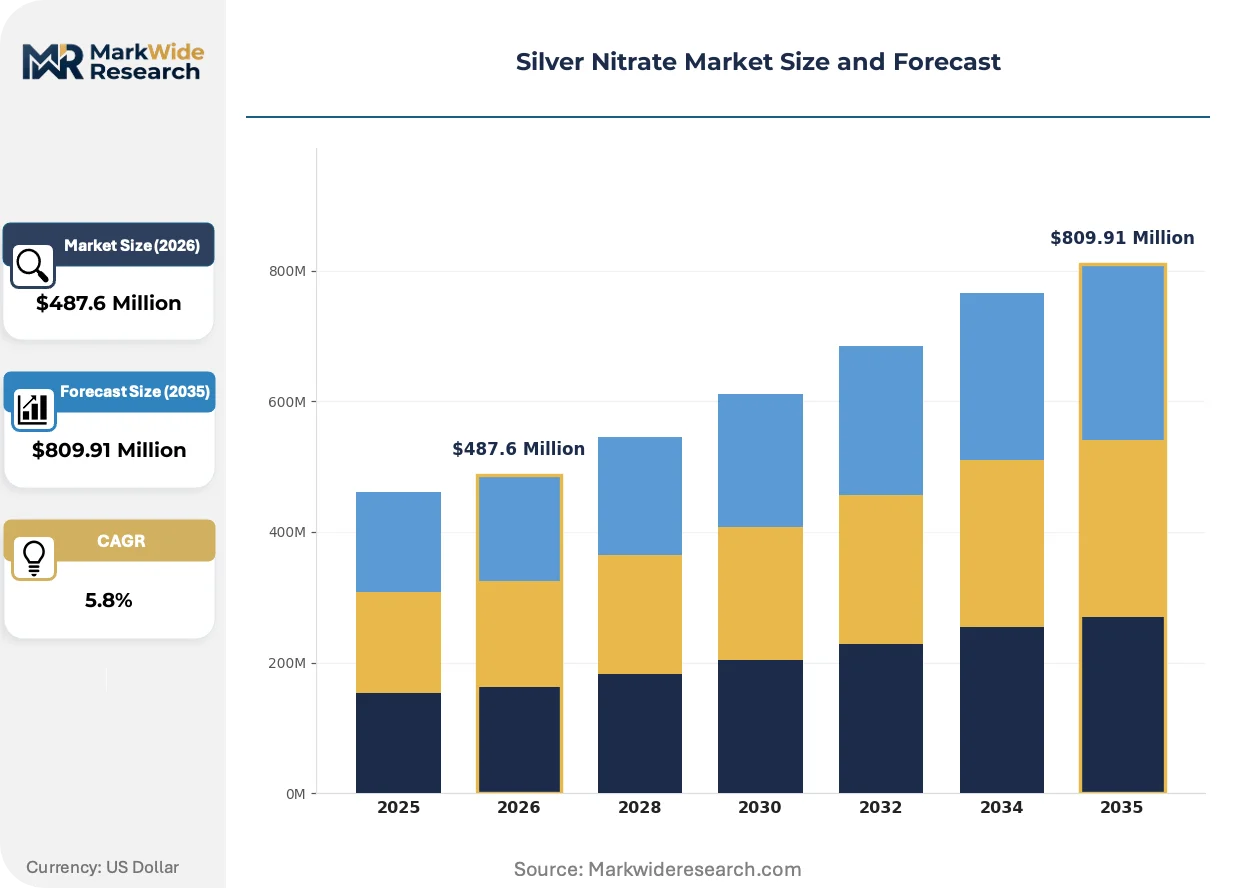
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Pharmaceutical Grade, Analytical Grade, Industrial Grade Application: Wound Care, Photography, Chemical Synthesis, Water Treatment End User: Healthcare, Laboratory, Manufacturing, Agriculture Packaging Type: Bottles, Jars, Bags, Drums |
| Companies Covered | Ames Goldsmith, Rochester Silver Works, Alfa Aesar, Merck, American Elements, Avantor, GFS Chemicals, Columbus Chemical Industries, Ricca Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silver Nitrate Market Strategic Shifts
Continuous crystallization systems are displacing batch processing in pharmaceutical-grade production, compressing impurity variation while reducing solvent waste. Regulatory data integrity requirements are automating batch record verification.
Membrane filtration integration with controlled precipitation is automating particle size distribution for wound care formulations. German refiners deploying this technology are securing multi-year hospital procurement contracts. The shift is compressing qualification timelines for new supplier onboarding.
EU MDR technical documentation requirements are expanding analytical testing burdens for silver nitrate-based devices. Notified bodies in Germany and the Netherlands are demanding extended biocompatibility studies. Wound care manufacturers are consolidating supplier bases to reduce audit complexity.
Hospital procurement groups are centralizing antiseptic purchasing through national framework agreements. Group Purchasing Organizations in the United States are displacing distributor-led replenishment with direct manufacturer contracts. The consolidation is most visible in burn center networks across Texas and California.
Silver Nitrate Market Segmentation
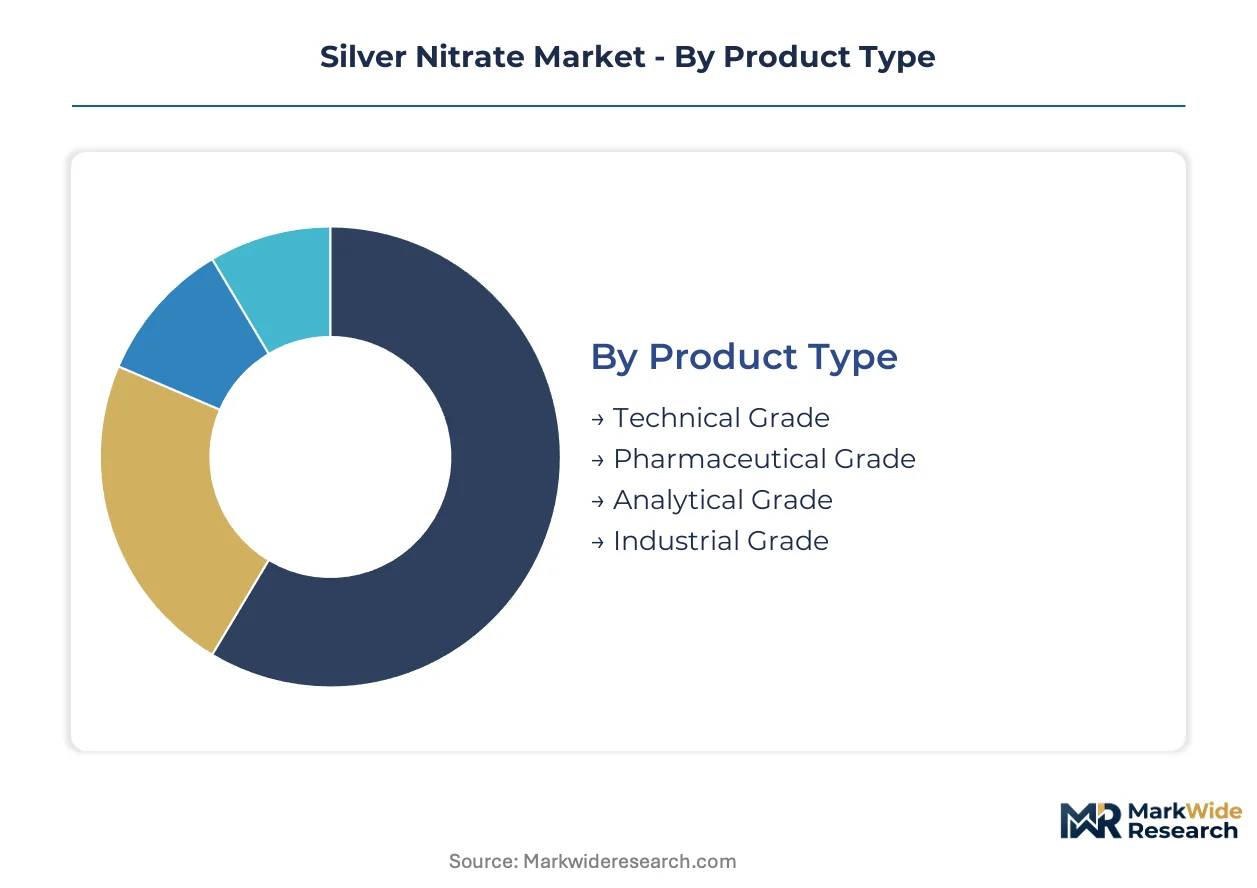
Silver nitrate procurement patterns diverge sharply across purity grades and end-use specifications. Pharmaceutical and analytical certifications command substantial price premiums, while industrial volumes flow through commodity chemical channels with minimal regulatory overhead.
Product Type:
Volume concentrates in industrial and technical grades, yet margin pools accrue disproportionately to certified pharmaceutical and analytical specifications.
- Pharmaceutical Grade:USP and EP compliance mandates govern dissolution testing, heavy metal limits, and endotoxin thresholds. German hospital procurement groups and US burn centers are locking in multi-year supply agreements with certified refiners to secure batch-to-batch consistency for wound care formulations.
- Analytical Grade:ACS and ISO 6353 specifications require sub-ppm trace metal certification and documented homogeneity across lot sizes. Research institutions in Japan and South Korea are expanding reagent procurement as analytical chemistry programs scale, though ICP-MS testing capacity constraints limit supplier qualification rates.
- Technical Grade:Standard purity for industrial catalyst production and mirror silvering.
- Industrial Grade:Bulk volumes for electroplating baths and general chemical processing.
Mature deployment sits with Industrial Grade. Newer deployment is concentrated in Pharmaceutical Grade.
Application:
Antimicrobial efficacy requirements are redirecting formulation chemistry toward silver-based systems as chlorinated alternatives face regulatory pressure.
- Wound Care:Silver nitrate solutions and impregnated dressings target biofilm disruption in diabetic foot ulcers and partial-thickness burns. Texas and California burn center networks are standardizing 0.5% silver nitrate protocols, while German hospital formulary committees expand reimbursement coverage for chronic wound management.
- Photography:Archival film preservation and specialty holographic emulsions sustain niche demand. Rochester-area production facilities maintain dedicated crystallization lines for grain-size-sensitive photographic specifications.
- Chemical Synthesis:Precursor for organic halogenation and silver salt derivatives.
- Water Treatment:EPA-registered antimicrobial dosing for cooling towers and potable systems.
Photography represents legacy demand with stable offtake. Wound care is gaining share fastest among application channels.
End User:
Procurement centralization through group purchasing organizations is compressing distributor margins and favoring direct manufacturer relationships.
- Healthcare:Hospital systems, outpatient wound clinics, and burn centers drive pharmaceutical-grade consumption. US GPOs and German hospital procurement alliances are consolidating antiseptic purchasing under national framework agreements that privilege suppliers with FDA Drug Master File and EMA CEP documentation.
- Laboratory:Academic and industrial research facilities require batch-certified analytical reagents. Japanese national university consortia are expanding silver nitrate procurement for materials science programs.
- Manufacturing:Chemical processors and electronics fabricators.
- Agriculture:Limited deployment in seed treatment and hydroponic systems.
Laboratory procurement follows established qualification protocols. Healthcare is expanding most quickly as antimicrobial stewardship programs elevate silver-based alternatives.
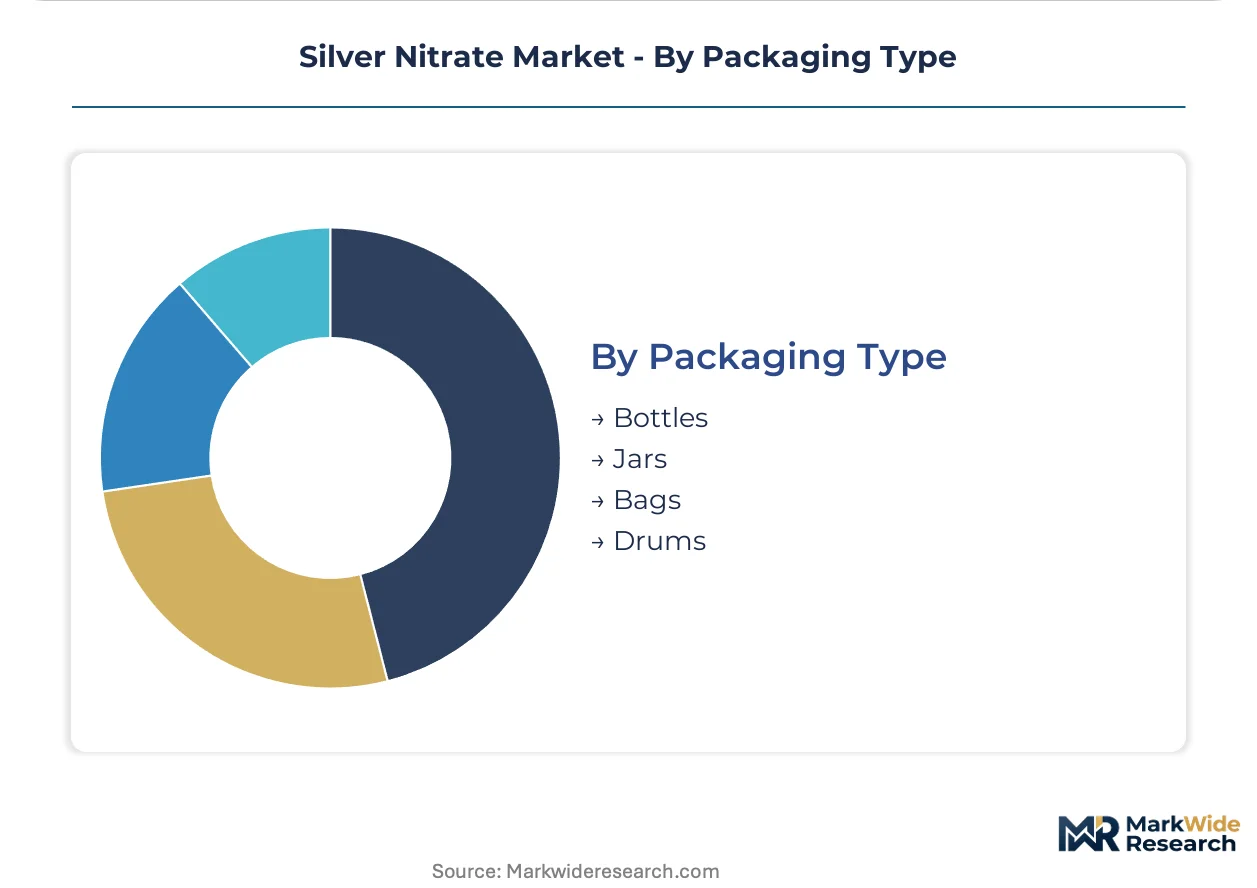
Packaging Type:
Light sensitivity and hygroscopicity dictate packaging engineering, with amber glass and inert atmosphere requirements adding cost layers to premium grades.
- Bottles:Amber borosilicate glass with PTFE-lined closures protects pharmaceutical and analytical grades from photodegradation. German refiners are automating fill-line verification to meet EU MDR traceability requirements for device-grade materials.
- Drums:Stainless steel and polyethylene bulk containers serve industrial-scale chemical synthesis and electroplating operations. Rhine-Ruhr chemical corridor logistics hubs manage drum consolidation for just-in-time delivery to manufacturing plants.
- Jars:Wide-mouth containers for laboratory powder handling.
- Bags:Laminated foil sacks for moisture-sensitive technical grade shipments.
Drum shipments dominate industrial corridors. Bottles command premium positioning in certified-grade distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silver metal refining corridors along the Rhine-Ruhr industrial zone anchor European supply capacity for pharmaceutical-grade material. Hospital procurement centralization in Germany and burn center network expansion across Texas and California are redirecting volume flows toward certified producers with established regulatory dossiers.
Germany
Burn center formulary standardization and chronic wound management protocols drive pharmaceutical-grade consumption. EMA CEP documentation requirements and EU MDR technical file obligations filter supplier pools toward certified refiners. The Rhine-Ruhr chemical corridor concentrates crystallization capacity, with automated membrane filtration systems securing multi-year hospital procurement contracts.
United States
Texas and California burn center networks are consolidating silver nitrate purchasing under Group Purchasing Organization framework agreements. EPA registration requirements for antimicrobial applications and FDA Drug Master File compliance govern topical wound management formulations. Rochester-area production facilities maintain dedicated crystallization lines for photographic emulsion specifications.
India
Contract manufacturing organizations in Hyderabad and Ahmedabad are qualifying USP-grade excipient suppliers for export pharmaceutical production. CDSCO regulatory alignment with ICH standards opens pathways for certified producers. National pharmaceutical manufacturing clusters are expanding silver-based antiseptic formulation capacity for domestic hospital procurement.
Japan
National university consortia are scaling analytical chemistry programs, expanding ACS-grade reagent procurement for materials science research. PMDA registration requirements and METI industrial standards govern laboratory chemical imports. Kanto-region research institutions anchor demand for sub-ppm trace metal certification protocols.
South Korea
In-vitro diagnostic producers are scaling silver nitrate reduction chemistry for lateral flow assay signal amplification. MFDS medical device regulations and national biotech investment programs support reagent manufacturing expansion. Seoul-capital area diagnostic clusters are integrating specialized-grade material into point-of-care manufacturing lines.
Silver Nitrate Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue adjacent certification spaces and regional regulatory dossiers. The supplier base concentrates around three strategic archetypes: integrated precious metal refiners with captive silver supply, specialty chemical houses with analytical-grade certification infrastructure, and pharmaceutical excipient specialists with USP/EP compliance bandwidth. Competitive positioning hinges on multi-jurisdiction registration maintenance and automated batch verification systems. Consolidation among healthcare procurement groups favors direct manufacturer relationships over distributor-led replenishment.
Within the integrated refiner tier, Ames Goldsmith and Rochester Silver Works exemplify geographic anchoring strategies tied to North American production infrastructure. Merck occupies a position representing the analytical-grade certification archetype, with stringent batch protocols commanding premium positioning in European laboratory markets. These three entities illustrate how regulatory dossier depth and geographic production clustering shape sustainable supply relationships with hospital systems and research institutions.
| Leading Market Players |
|---|
| Ames Goldsmith |
| Rochester Silver Works |
| Alfa Aesar |
| Merck |
| American Elements |
| Avantor |
| GFS Chemicals |
| Columbus Chemical Industries |
| Ricca Chemical Company |
| Others |
Value Chain & Pricing Dynamics
Spectroscopy specialists concentrated in Germany's Rhine-Ruhr chemical corridor command wage premiums that compress margins at the analytical-grade tier while widening spreads between certified pharmaceutical batches and commodity industrial volumes.
Pricing Analysis
Volume concentrates in industrial-grade drum shipments while margin pools accrue to pharmaceutical and analytical certifications. Three-tier pricing structure across pharmaceutical, analytical, and industrial levels reflects USP/EP compliance burdens, ICP-MS batch verification costs, and volume scale. Cost compression in the industrial tier is intensifying because silver spot volatility transmits directly to raw material costs without hedging buffers. Hospital procurement groups exhibit lowest price sensitivity due to formulary standardization mandates, while electroplating operators face acute margin pressure from commodity-grade competition.
Supply Chain Analysis
Silver metal reclamation from photographic waste streams and spent catalyst materials feeds circular supply loops back into refining circuits. Production gravity centers on Germany, the United States, and India for pharmaceutical-grade crystallization. Raw material flows draw from London Bullion Market Association silver supply, nitric acid industrial networks, and membrane filtration equipment. Single-source vulnerability concentrates in the Rhine-Ruhr corridor where waterway logistics and environmental enforcement cascade downstream. Distribution runs through direct manufacturer contracts with hospital GPOs and national procurement alliances, displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The silver nitrate sector sits in a manufacturing-technology transition as continuous crystallization systems displace legacy batch processing, automating impurity control while reducing solvent waste streams.
For Market Incumbents: Extend regulatory dossier depth across FDA Drug Master File, EMA CEP, and PMDA registrations to lock out smaller competitors lacking parallel submission bandwidth. Backward integration into captive silver refining secures raw material cost control against London Bullion Market Association spot volatility. Automated batch record verification systems defend positioning as EU MDR data integrity requirements tighten.
For New Entrants and Emerging Players: E-commerce laboratory reagent channels offer lower qualification barriers than hospital formulary onboarding for pharmaceutical-grade entry. Contract manufacturing organizations in Hyderabad and Ahmedabad present the most penetrable white-space for USP-grade excipient supply. Target lateral flow assay manufacturers in South Korea with specialized-grade material for point-of-care diagnostic convergence.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier refiners possessing membrane filtration automation and existing EMA CEP documentation given EU Green Deal chemical substitution tailwinds for silver-based antimicrobials. Long-term viability favors producers with multi-jurisdiction registration maintenance infrastructure over commodity-grade volume players. Monitor CDSCO regulatory alignment progress in India as inflection signal for export pathway expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Crystallization Deployment | Membrane filtration integration secures multi-year German hospital procurement contracts through automated particle size control. |
| Multi-Jurisdiction Dossier Expansion | Parallel FDA, EMA, and PMDA registrations filter competitor pools and command premium positioning in laboratory markets. |
| Silver Supply Backward Integration | Captive refining infrastructure absorbs London Bullion Market Association spot volatility that crushes unhedged compounder margins. |
| Diagnostic Reagent Partnership | Lateral flow assay manufacturing alliances in Seoul-capital area clusters open specialized-grade volume anchors beyond wound care. |
| EU Green Deal Alignment | REACH authorization positioning against chlorinated disinfectant substitution captures green public procurement mandate flows. |
Study Parameters
Trade databases, ECHA substance registration filings, and SEC chemical company disclosures formed the secondary backbone, cross-referenced with primary interviews involving refinery plant managers, hospital procurement directors, laboratory reagent buyers, and wound care formulary committees. Bottom-up volume modeling triangulated against top-down silver consumption estimates from precious metals industry associations.
Bottom-up segment sizing across pharmaceutical grade, analytical grade, technical grade, and industrial grade purity tiers integrated with wound care, photography, chemical synthesis, and water treatment application channels. CAGRs derived from regression against chronic wound prevalence trajectories, burn center network expansion, and EU MDR implementation timelines. Forecast inputs incorporated REACH authorization pressures on chlorinated disinfectants and lateral flow assay manufacturing scaling in East Asian diagnostic clusters.
The model holds under stable silver spot price corridors and REACH enforcement continuity; deviation in antimicrobial resistance policy tightening or Rhine-Ruhr logistics disruption would shift volume trajectories. Practitioners should monitor CDSCO regulatory alignment milestones and EPA registration renewal timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Aluminum Smelting Market
Metals
Aluminum Slugs Market
Metals
Aluminum Sheet Market
Metals
Russia Metal Fabrication Market
Metals
Global Aluminum Market
Metals
Global Tantalum Market
Metals
Ore Metals Market
Metals
North America Metal Finishing Market
Metals
Galvanizing Market
Metals
Vietnam Aluminum Market
Metals
Global Titanium Metal Market
Metals
Titanium Mill Products Market
Metals
Global Precious Metal Market
Metals
Nickel Powder Plating Market
Metals
Cold Drawn Wire Market
Metals
US Copper Scrap Market