
 Cathode Active Material Market | 2026-2036
Cathode Active Material Market Size, Share, and Industry Trends Forecast 2026-2036
Cathode Active Material Market Analytics
Automotive OEMs are unwinding legacy consumer electronics procurement patterns as their cathode material volumes overtake portable device demand. Umicore leverages its European precursor-cathode integration to secure long-term supply agreements with European automakers. POSCO FUTURE M anchors its position through captive nickel refining and Korean government-backed battery material investments. CNGR Advanced Material dominates the LFP precursor segment with cost-optimized manufacturing footprints in China.
Cathode active materials are lithium-bearing compounds—typically layered oxides, spinels, or olivine phosphates—engineered to reversibly intercalate lithium ions at voltages between 3.2V and 4.3V versus Li/Li+, serving as the electrochemical heart of rechargeable lithium-ion cells. Lithium Nickel Manganese Cobalt formulations lead in energy density-critical automotive applications where nickel-rich ratios above 80% are becoming standard, while Lithium Iron Phosphate captures the fastest growth trajectory in grid-scale energy storage and entry-level electric vehicles prioritizing cycle life and thermal stability over volumetric energy. The purity grade dimension stratifies margin pools, with high-purity battery-grade material commanding substantial premiums over technical-grade alternatives used in industrial applications.
China's MIIT enforces GB standards for cathode material performance and safety certification, while the EU's Battery Regulation mandates recycled content thresholds and carbon footprint declarations for cells sold in Europe. South Korea's MFDS and METI coordinate standards alignment with Japan through bilateral battery supply chain agreements. Stakeholders must monitor how evolving cobalt due diligence rules and nickel processing emissions accounting reshape supplier qualification timelines and capital allocation decisions.
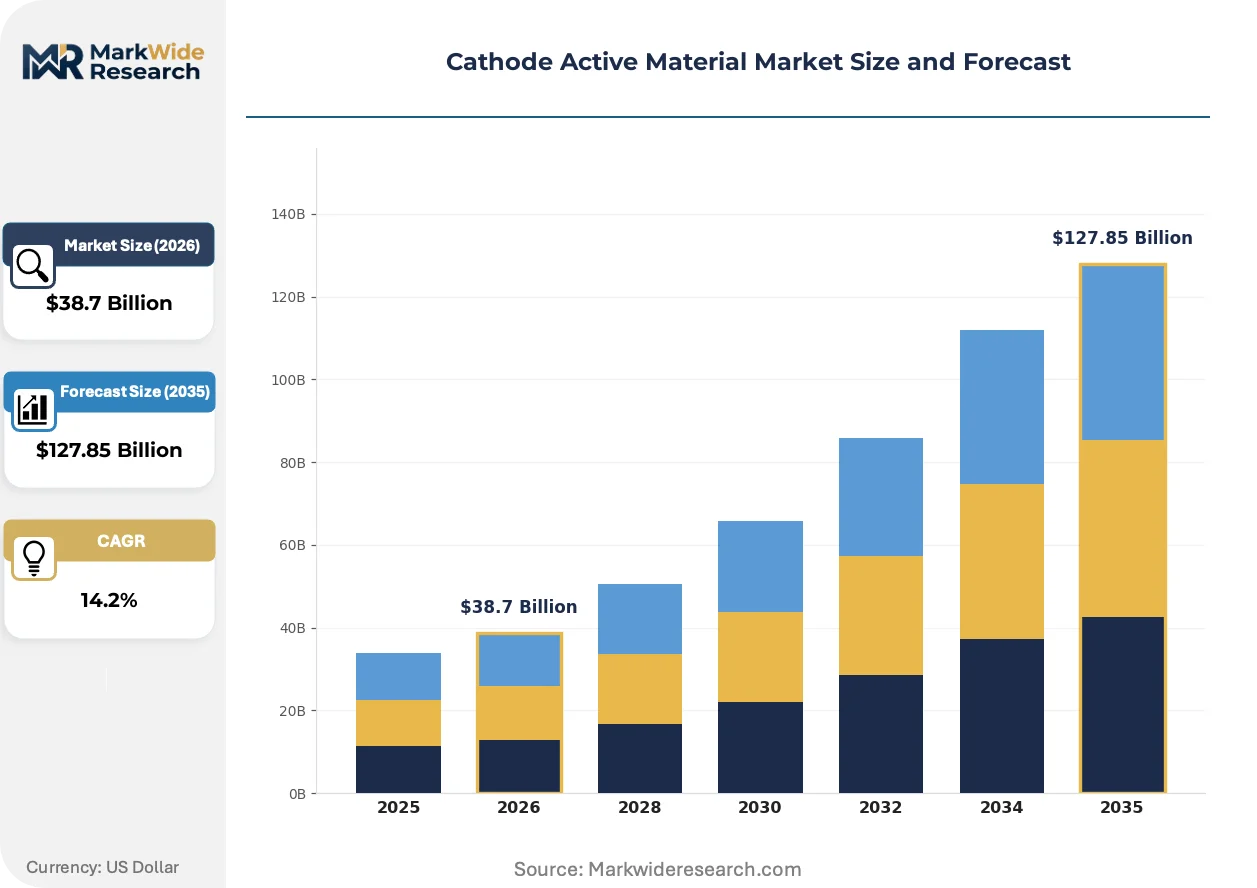
Market Dynamics
The cathode active material market is undergoing a fundamental restructuring as automotive OEM procurement volumes displace legacy consumer electronics demand patterns, forcing suppliers to reconfigure production footprints and qualification protocols for multi-gigawatt-hour contract structures.
Growth Catalysts
- EU Battery Regulation recycled content mandates:The regulation's carbon footprint declaration requirements and minimum recycled lithium thresholds are accelerating investment in closed-loop precursor recovery infrastructure across European cell manufacturing corridors.
- High-nickel NMC chemistries:Nickel-rich ratios exceeding 80% in layered oxide formulations are capturing automotive platforms prioritizing range extension and pack-level energy density optimization.
- South Korea's battery material industrial policy:Government-backed financing for integrated precursor-cathode facilities is concentrating technical talent and capital equipment within Korean chemical processing zones.
Market Restraints
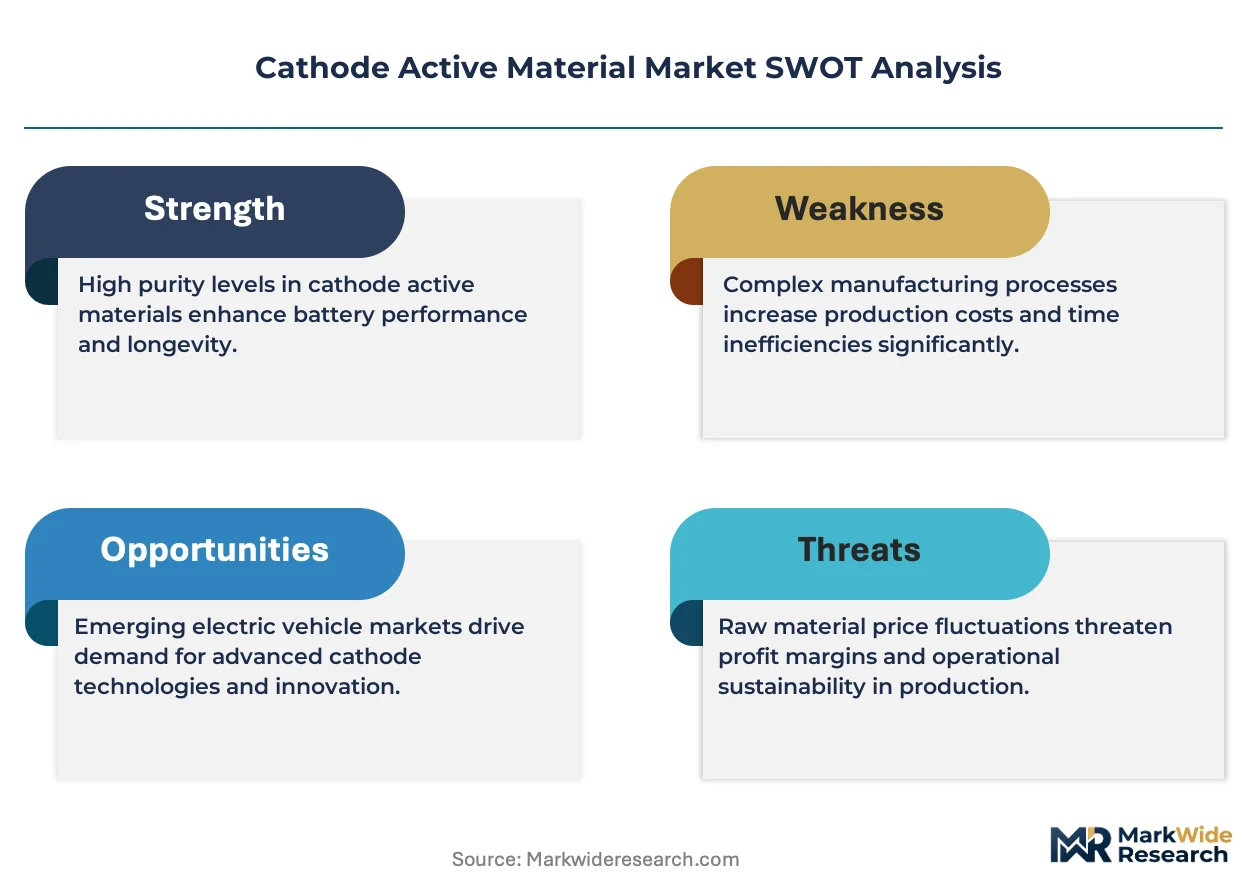
- Class 1 nickel supply concentration:Battery-suitable nickel sulfate production remains concentrated among a limited set of integrated mining-refining operations, creating feedstock vulnerability for cathode precursor expansion.
- Cobalt due diligence compliance costs:The EU Conflict Minerals Regulation and OECD sourcing guidelines impose traceability system investments that elevate qualification barriers for smaller precursor suppliers.
- LFP energy density ceiling:The olivine phosphate crystal structure's theoretical capacity limits constrain Lithium Iron Phosphate penetration into premium automotive segments requiring maximum range.
Strategic Opportunities
- India's PLI scheme for cell manufacturing:Production-linked incentive allocations for advanced chemistry cell gigafactories are creating first-mover advantages for cathode material suppliers establishing local precursor operations.
- Direct recycling technologies:Hydrometallurgical and direct cathode regeneration processes are converging with pyrometallurgical recovery to enable lower-emission material loops qualifying for EU Battery Regulation carbon thresholds.
- Grid-scale energy storage procurement:Utility-scale battery installations are generating dedicated LFP demand streams with qualification cycles shorter than automotive applications, accelerating revenue recognition timelines.
Industry Challenges
- Battery-grade purity certification timelines:Transitioning from technical-grade to battery-grade production requires 18-24 month customer qualification cycles that strain working capital during capacity ramp phases.
- Precursor-cathode integration engineering:Constructing co-located pCAM and CAM facilities demands simultaneous mastery of hydrometallurgical refining and solid-state synthesis process control.
- Cross-border emissions accounting:Scope 3 nickel processing attribution under EU Battery Regulation carbon footprint rules complicates supplier qualification for integrated miners with multi-jurisdictional refining footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cathode Active Material Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium Cobalt Oxide, Lithium Iron Phosphate, Lithium Nickel Manganese Cobalt, Lithium Nickel Cobalt Aluminum End Use Industry: Consumer Electronics, Automotive, Industrial, Energy Storage Form: Powder, Coated, Composite, Sheet Purity Grade: High Purity, Standard Purity, Technical Grade, Others |
| Companies Covered | Umicore, Shenzhen Dynanonic Co., Ltd., BASF, LANDF CORP., Hunan Yuneng New Energy Battery Materials Co., Ltd., POSCO FUTURE M, XTC New Energy Materials (Xiamen) Co., Ltd., CNGR Advanced Material, LG Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cathode Active Material Market Evolving Landscape
Active material formulation strategies are diverging across end-use verticals as energy density, cycle life, and thermal stability trade-offs harden into distinct technical roadmaps with incompatible manufacturing equipment requirements.
Single-crystal NMC architectures are fragmenting the high-nickel cathode landscape by eliminating grain boundary degradation pathways that plague polycrystalline alternatives. Automotive OEMs with 800V electrical architectures are adopting single-crystal formulations for premium platforms despite 15-20% cost premiums over conventional structures. This materials divergence is fragmenting equipment supplier order books as distinct calcination and milling specifications proliferate.
China's MIIT GB standards for cathode material safety certification are tightening particle morphology and impurity thresholds that affect import eligibility for non-domestic suppliers. The standards revision process has compressed qualification windows for foreign material entering Chinese cell manufacturing supply chains. Korean and Japanese precursor suppliers are responding by establishing joint testing protocols with Chinese certification bodies to accelerate compliance timelines.
Automotive OEMs are consolidating cathode material procurement under single-source frameworks with decade-long volume commitments and embedded price adjustment mechanisms. Tier 1 battery manufacturers are losing negotiating leverage as cell customers secure direct CAM supply agreements, bypassing traditional module integrator intermediaries. This channel restructuring is most visible in European automotive corridors where OEMs are replicating Tesla's direct material sourcing model.
Cathode Active Material Market Segmentation
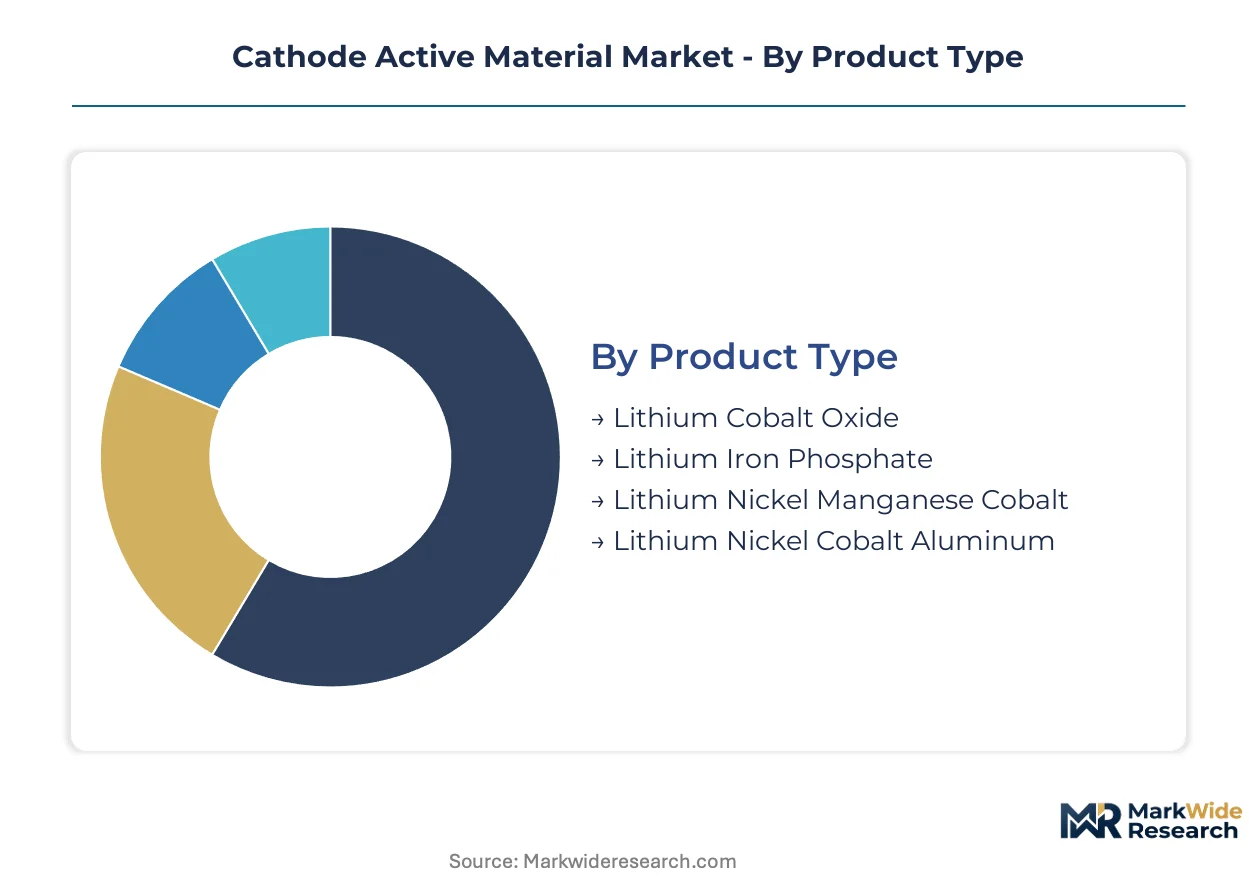
Cathode active material segmentation reflects diverging technical roadmaps across energy density, cycle life, and cost requirements. Formulation choices lock manufacturers into incompatible synthesis equipment and precursor supply chains. End-use verticals impose distinct qualification protocols that fragment supplier-customer relationships.
Product Type:
Substitution pressure intensifies as nickel-rich formulations displace cobalt-dependent alternatives in premium automotive applications.
- Lithium Nickel Manganese Cobalt:Layered oxide structures with nickel content exceeding 80% dominate European and Korean automotive platforms prioritizing range optimization. Cell manufacturers in South Korea's industrial corridors concentrate procurement of high-nickel ratios under long-term offtake agreements with integrated precursor suppliers.
- Lithium Iron Phosphate:Olivine phosphate crystal structure delivers superior thermal stability and cycle life at lower material cost. Grid-scale energy storage developers in China and utility procurement programs in Texas and California are concentrating demand for this chemistry.
- Lithium Cobalt Oxide:High-voltage layered oxide retains position in premium consumer electronics where volumetric energy density constraints dominate pack design.
- Lithium Nickel Cobalt Aluminum:Aluminum-stabilized layered oxide serves niche aerospace and high-performance automotive segments requiring extreme fast-charge capability.
Lithium Nickel Manganese Cobalt retains volume leadership; Lithium Iron Phosphate holds the steepest expansion curve.
End Use Industry:
Cost tier stratification separates qualification-intensive automotive contracts from shorter-cycle industrial and energy storage procurement.
- Automotive:OEM direct sourcing agreements now span decade-long horizons with embedded price adjustment mechanisms. European automakers replicate Tesla's material procurement model, bypassing traditional battery integrators to secure cathode supply directly.
- Energy Storage:Utility-scale battery installations generate dedicated Lithium Iron Phosphate demand streams with qualification cycles compressed to 6-12 months versus 18-24 months for automotive applications.
- Consumer Electronics:Legacy portable device demand patterns unwind as automotive volumes overtake procurement volumes, forcing suppliers to reconfigure production footprints.
- Industrial:Forklift, mining equipment, and material handling applications prioritize cycle life over energy density, accepting lower-nickel formulations.
Automotive commands margin concentration; Energy Storage delivers the fastest volume scaling.
Form:
Supply concentration in powder synthesis creates barriers for alternative form factors requiring specialized coating or composite engineering.
- Powder:Uniaxially pressed and sintered particulate constitutes the dominant feedstock for calendaring and electrode coating operations. Chinese and Korean suppliers optimize particle morphology distributions under MIIT GB standards and MFDS alignment protocols.
- Coated:Surface-modified particles with alumina or carbon coatings extend cycle life in high-voltage operation. Single-crystal NMC architectures increasingly specify coated variants for 800V automotive platforms.
- Composite:Blended active-conductive matrices target niche applications requiring enhanced rate capability.
- Sheet:Pre-formed electrode substrates remain experimental for solid-state cell prototyping.
Powder dominates manufacturing scale; Coated variants gain share in premium automotive specifications.
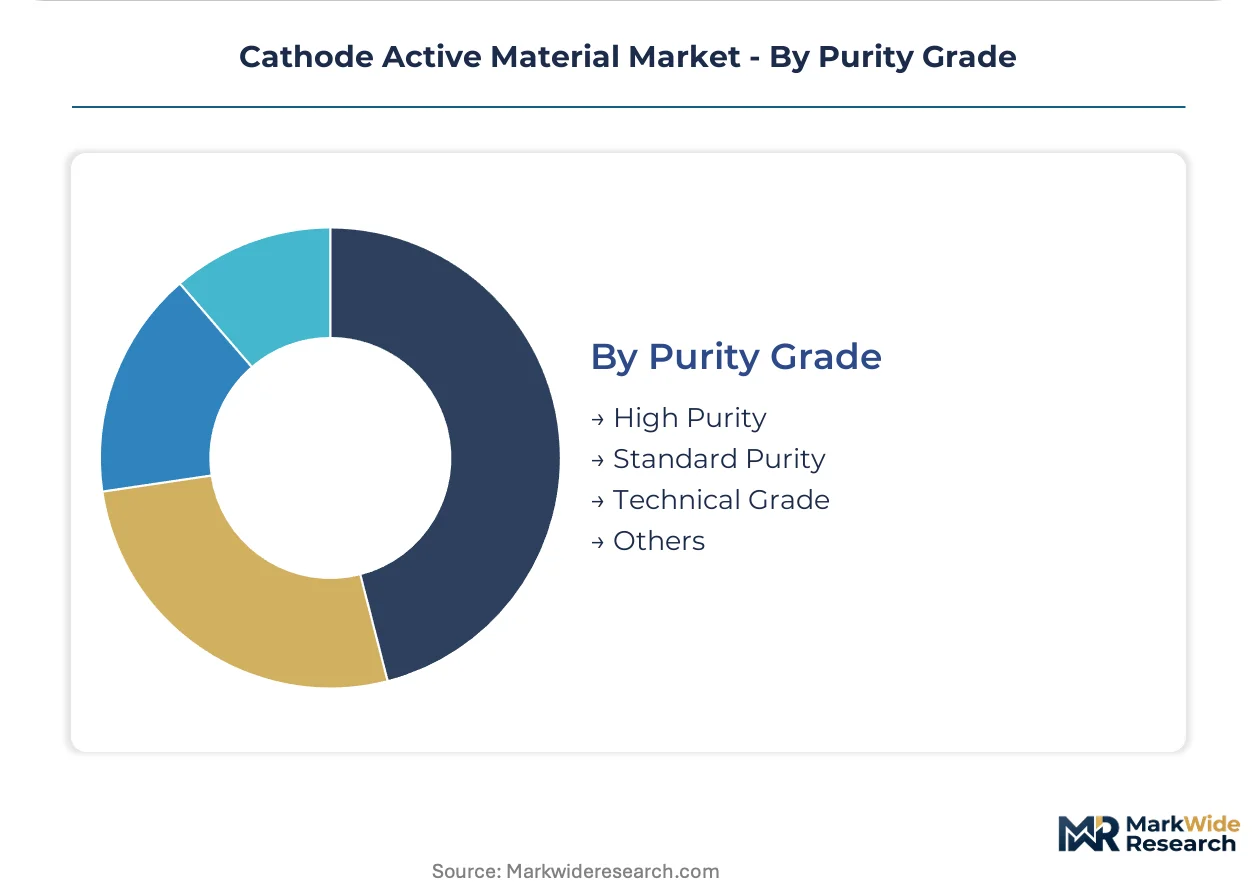
Purity Grade:
Margin pools stratify sharply as battery-grade certification timelines create qualification moats around high-purity production.
- High Purity:Battery-grade material with impurity thresholds below 50 ppm for transition metals commands substantial premiums over technical-grade alternatives. EU Battery Regulation carbon footprint declarations and recycled content mandates accelerate demand for traceable high-purity supply chains.
- Standard Purity:Intermediate grade serves secondary automotive applications and industrial energy storage where extreme cycle life requirements relax.
- Technical Grade:Industrial-grade material with elevated impurity levels supplies non-battery applications including catalysts and ceramics.
- Others:Emerging specifications for solid-state electrolyte interfaces and specialized research quantities.
High Purity captures margin concentration; Standard Purity scales fastest in cost-sensitive energy storage deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese cathode material exports flow predominantly toward South Korean battery manufacturers serving European and North American automotive OEMs. This trade corridor reshapes procurement patterns across three continents simultaneously.
China
Domestic EV manufacturers and grid-scale storage developers drive lithium iron phosphate consumption at unprecedented scale. MIIT enforces GB standards for cathode material safety certification that tighten particle morphology thresholds affecting import eligibility. The Yangtze River Delta concentrates precursor-cathode integrated facilities where CNGR Advanced Material and XTC New Energy Materials optimize cost structures.
South Korea
POSCO FUTURE M and LG Chem anchor demand for high-nickel NMC formulations targeting premium automotive platforms. MFDS coordinates standards alignment with METI through bilateral battery supply chain agreements. The Busan-Ulsan industrial corridor hosts government-backed precursor-cathode facilities concentrating technical talent and capital equipment.
Germany
BASF leverages European precursor-cathode integration to secure decade-long supply agreements with domestic automakers replicating Tesla's direct sourcing model. The EU Battery Regulation mandates recycled content thresholds and carbon footprint declarations for cells sold in Europe. The North Rhine-Westphalia chemical processing zone attracts closed-loop precursor recovery infrastructure investments.
United States
IRA production tax credits accelerate gigafactory construction creating first-mover advantages for cathode suppliers establishing local precursor operations. EPA and NHTSA coordinate emissions accounting frameworks affecting Scope 3 nickel processing attribution. The Texas and California utility-scale battery procurement programs generate dedicated LFP demand streams with compressed qualification cycles.
Japan
Specialized high-performance automotive and aerospace segments sustain demand for aluminum-stabilized NCA formulations requiring extreme fast-charge capability. METI coordinates technical standards alignment with South Korean counterparts through bilateral agreements. The Kanto and Kansai regions maintain precision material synthesis capabilities for niche premium applications.
Cathode Active Material Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive precursor supply and specialized battery material pure-plays. The structure concentrates around three tiers: diversified multinationals with full precursor-to-cathode integration, Asian pure-plays with government-backed capacity expansion, and regional specialists serving qualification-intensive niche segments. Dominant competitive moves include backward integration into nickel refining and strategic partnerships with automotive OEMs for multi-gigawatt-hour offtake agreements.
Among diversified chemical conglomerates, Umicore and BASF exemplify the European integrated archetype combining precursor refining with cathode synthesis. POSCO FUTURE M and LG Chem occupy positions within the Korean government-backed tier leveraging captive nickel refining and industrial policy financing. CNGR Advanced Material and Hunan Yuneng represent the Chinese cost-optimized manufacturing tier dominating LFP precursor segments through scale-driven production footprints.
| Leading Market Players |
|---|
| Umicore |
| Shenzhen Dynanonic Co., Ltd. |
| BASF |
| LANDF CORP. |
| Hunan Yuneng New Energy Battery Materials Co., Ltd. |
| POSCO FUTURE M |
| XTC New Energy Materials (Xiamen) Co., Ltd. |
| CNGR Advanced Material |
| LG Chem |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with embedded price adjustment mechanisms lock in both supply access and cost visibility for automotive OEMs procuring high-nickel cathode formulations from integrated precursor suppliers in South Korea and China. These multi-gigawatt-hour agreements insulate buyers from nickel sulfate volatility while binding suppliers to performance specifications under EU Battery Regulation carbon footprint rules.
Pricing Analysis
High-nickel NMC formulations command substantial premiums over Lithium Iron Phosphate alternatives due to energy density advantages in premium automotive platforms. Pricing stratifies across battery-grade purity tiers, with impurity thresholds below 50 ppm for transition metals capturing margin concentration from technical-grade alternatives. Cost compression in LFP segments is intensifying as Chinese manufacturers optimize Yangtze River Delta production footprints. Energy storage developers exhibit highest price sensitivity, while aerospace and 800V automotive platforms show lowest sensitivity to single-crystal NMC premiums.
Supply Chain Analysis
Inventory buffers for Class 1 nickel sulfate extend lead times for cathode precursor expansion as battery-suitable refining capacity concentrates in Indonesia, Australia, and Russia. The supply chain draws from captive nickel mining operations, hydrometallurgical refining complexes, and solid-state synthesis facilities. Single-source vulnerability persists for cobalt feedstock originating from DRC mining operations subject to EU Conflict Minerals Regulation traceability requirements. Distribution runs through integrated battery-chemical industrial corridors in South Korea's Busan-Ulsan zone and China's Yangtze River Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cathode active material market represents a high-growth disruption as EU Battery Regulation recycled content mandates and carbon footprint declaration requirements force capital reallocation toward closed-loop precursor recovery infrastructure.
For Market Incumbents: Consolidate backward integration into Class 1 nickel refining to secure feedstock against concentrate supply risks from Indonesian mining operations. Expand high-purity battery-grade certification capacity in European chemical processing zones to capture EU Battery Regulation compliance premiums before qualification timelines elongate. For New Entrants and Emerging Players: Lead with direct recycling technology platforms targeting EU carbon threshold qualification for lower-emission material loops. India's PLI scheme for advanced chemistry cell manufacturing offers the most penetrable geography for first-mover precursor operations with compressed regulatory approval pathways versus automotive qualification cycles. For Investors and Strategic Acquirers: Specialized precursor-cathode integration engineers with simultaneous hydrometallurgical refining and solid-state synthesis mastery represent the highest-conviction acquisition archetype. Monitor cobalt due diligence compliance cost trajectories as the signal for when smaller precursor supplier distress creates consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Refining | POSCO FUTURE M and Umicore secure captive Class 1 nickel sulfate supply against concentrate bottlenecks. |
| Direct Recycling Technology Deployment | Hydrometallurgical recovery platforms qualify for EU Battery Regulation recycled lithium thresholds. |
| High-Purity Battery-Grade Certification | 18-24 month qualification cycles create moats around premium cathode material margin pools. |
| Long-Term Automotive OEM Offtake Agreements | Decade-long volume commitments with embedded price mechanisms displace spot procurement patterns. |
| Precursor-Cathode Co-Location Investment | Integrated pCAM-CAM facilities in Korean government-backed corridors concentrate technical talent. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cathode material procurement directors at automotive OEMs, precursor plant managers in Chinese and Korean chemical corridors, battery cell manufacturing executives, and EU regulatory affairs specialists covering Battery Regulation compliance. Secondary validation drew from MIIT GB standard filings, EU Battery Regulation delegated acts, Korean MFDS alignment protocols, SEC 10-K disclosures from listed material suppliers, and customs trade data for lithium compound flows. Bottom-up capacity build-up triangulated against top-down automotive production forecasts.
Across the analysis window, volume and value outputs reflect segmentation by cathode chemistry formulation, end-use vertical qualification intensity, purity grade certification tier, and regional production cluster regulatory framework. CAGRs were derived from fitted growth curves incorporating electric vehicle platform rollout schedules, grid-scale storage procurement pipelines, and precursor capacity expansion announcements. Nickel price volatility bands and cobalt due diligence compliance cost trajectories informed scenario-weighted projections.
Forecasts assume regulatory continuity in EU Battery Regulation implementation, China's MIIT GB standard enforcement, and South Korea's MFDS-METI bilateral alignment; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Europe Advanced Building Materials Market
Advanced Materials
Long-Range Ordered Porous Carbon (LOPC) Market
Advanced Materials
Si-C Anode Material Market
Advanced Materials
Silica Aerogel Market
Advanced Materials
Extracellular Matrix Proteins Market
Advanced Materials
Hexagonal Boron Nitride (HBN) Market
Advanced Materials
Global Diamond-Like Carbon (DLC) Market
Advanced Materials
Borophene Market
Advanced Materials
Europe Next Generation Anode Materials Market
Advanced Materials
Inorganic Non-Metallic Materials Market
Advanced Materials
Artificial Marble Products Market
Advanced Materials
Lab-Grown Rough Diamond Market
Advanced Materials
Vacuum Insulation Panels Market
Advanced Materials
Cold Plasma Market
Advanced Materials
Advanced Sports Materials Market
Advanced Materials
Global Electrostrictive Material Market