
 Industrial Silver Market | 2026-2036
Industrial Silver Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Silver Market Foresight
Refined silver leasing and offtake subscription structures is expanding how industrial buyers secure physical supply without outright ownership. Fresnillo plc leverages its Mexican mining breadth to sustain long-term concentrate supply contracts with Asian smelters. Pan American Silver Corp anchors its competitive stance through jurisdictional diversification across the Americas. Hecla Mining Company specializes in high-grade underground operations that command premium concentrate terms.
Industrial silver comprises refined metal and chemical derivatives with minimum purity of 99.9 percent, valued for thermal conductivity of 429 W/m·K and electrical resistivity of 1.59 μΩ·cm at standard conditions. Manufacturers deploy it in brazing alloys, electrical contacts, and antimicrobial coatings where substitution carries performance penalties. Silver nanoparticles command widening application in printed electronics and antimicrobial medical textiles as miniaturization demands intensify. Electronics applications dominate volume absorption, while medical devices certification under FDA and DEA protocols captures margin concentration through compliance barriers.
EPA hazardous waste rules and OSHA workplace exposure limits govern U.S. refining and fabrication emissions, while REACH and RoHS frameworks in Europe restrict certain silver compound discharges and mandate substance registration. China's MEE enforces wastewater discharge standards for electroplating facilities that consume substantial silver salts. Stakeholders must track evolving battery-grade silver specifications and solar paste formulation shifts that could redirect demand between chemical derivatives and refined metal forms.
Market Dynamics
Photovoltaic paste formulation shifts and China's dual carbon mandates are compressing refined silver availability while redirecting chemical derivative demand toward battery-grade specifications.
Growth Catalysts
- EU REACH substance restrictions:Tighter compliance requirements are accelerating substitution-resistant silver adoption in medical device coatings where performance penalties block alternatives.
- Solar cell metallization:Photovoltaic manufacturers are expanding silver paste consumption as PERC and TOPCon cell architectures multiply finger-line density requirements.
- East Asian electronics clusters:South Korean semiconductor packaging facilities concentrate demand for high-purity wire bonding and flip-chip interconnect materials.
Market Restraints
- Concentrate supply concentration:Mexican mining jurisdictions anchor long-term smelter contracts, exposing buyers to single-source geopolitical and labor disruption risks.
- Copper-aluminum substitution:Electrical contact manufacturers face persistent cost pressure to downgrade from silver alloys where thermal cycling tolerance permits.
- China MEE wastewater standards:Electroplating facility discharge limits are elevating capital requirements for silver salt consumers without grandfathering provisions.
Strategic Opportunities
- Printed electronics miniaturization:Silver nanoparticle inkjet formulations are penetrating flexible circuit substrates as roll-to-roll manufacturing scales.
- Antimicrobial medical textiles:FDA certification pathways for wound dressing applications create margin-protected niches through compliance barriers.
- Refined metal leasing structures:Industrial buyers are securing physical supply through offtake subscriptions that reduce working capital intensity.
Industry Challenges
- Smelter qualification timelines:Asian concentrate buyers face 18-24 month validation cycles for new Mexican mining sources.
- Dual carbon compliance:China's MEE enforcement requires electroplaters to retrofit effluent treatment without technology transfer guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Silver Market |
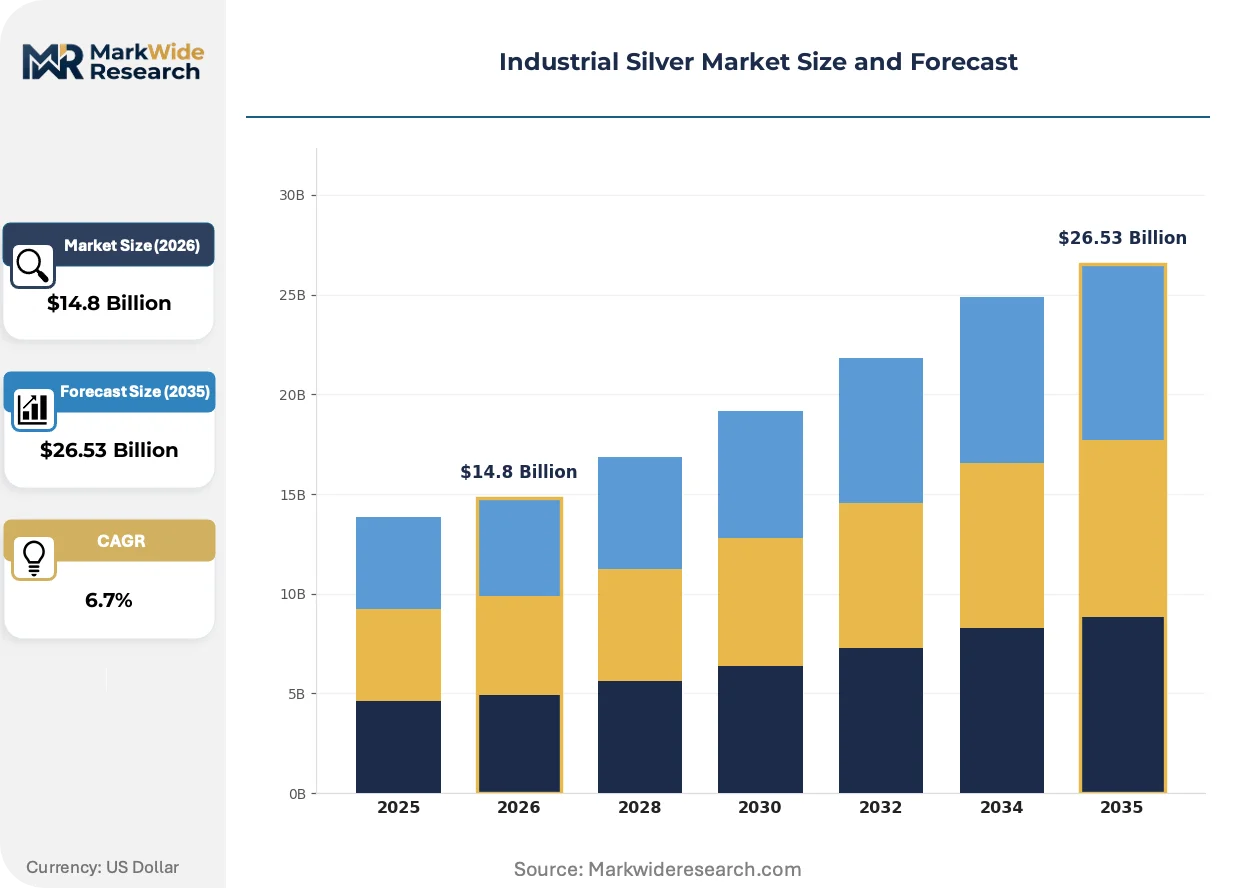
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver Nitrate, Silver Nanoparticles, Silver Oxide, Silver Chloride Application: Electronics, Automotive Components, Medical Devices, Conductive Adhesives End User: Manufacturers, Research Institutions, Healthcare Providers, Electronics Industries Certification: ISO 9001, RoHS Compliant, FDA Approved, DEA Registered |
| Companies Covered | Fresnillo plc, Pan American Silver Corp, Hecla Mining Company, Newmont Corporation, KGHM, Hindustan Zinc Ltd, Coeur Mining Inc, First Majestic Silver Corp, Silvercorp Metals Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Silver Market Shifts & Advancements
Silver paste chemistry and procurement structures are evolving in parallel as solar cell efficiency roadmaps and supply security concerns reshape buyer behavior.
Silver nanoparticle dispersions are integrating into printed electronics manufacturing as inkjet and aerosol deposition methods displace photolithography for flexible substrate patterning. Wearable device manufacturers are qualifying these formulations for stretchable circuit applications. The technology is integrating antenna and sensor production into garment manufacturing lines, collapsing traditional electronics assembly steps.
China's dual carbon goals are tightening MEE enforcement across electroplating hubs in Guangdong and Jiangsu provinces. Facility closures and consolidation are concentrating silver salt demand among surviving operators with advanced wastewater treatment. Battery-grade silver specifications are diverging from solar paste requirements, forcing chemical derivative suppliers to segment product lines.
Industrial buyers are consolidating procurement through long-term offtake subscriptions rather than spot market exposure. Solar cell manufacturers in South Korea are negotiating direct concentrate supply agreements with Mexican mining operations. This channel compression is displacing traditional trader intermediaries in East Asian electronics fabrication clusters.
Industrial Silver Market Segmentation
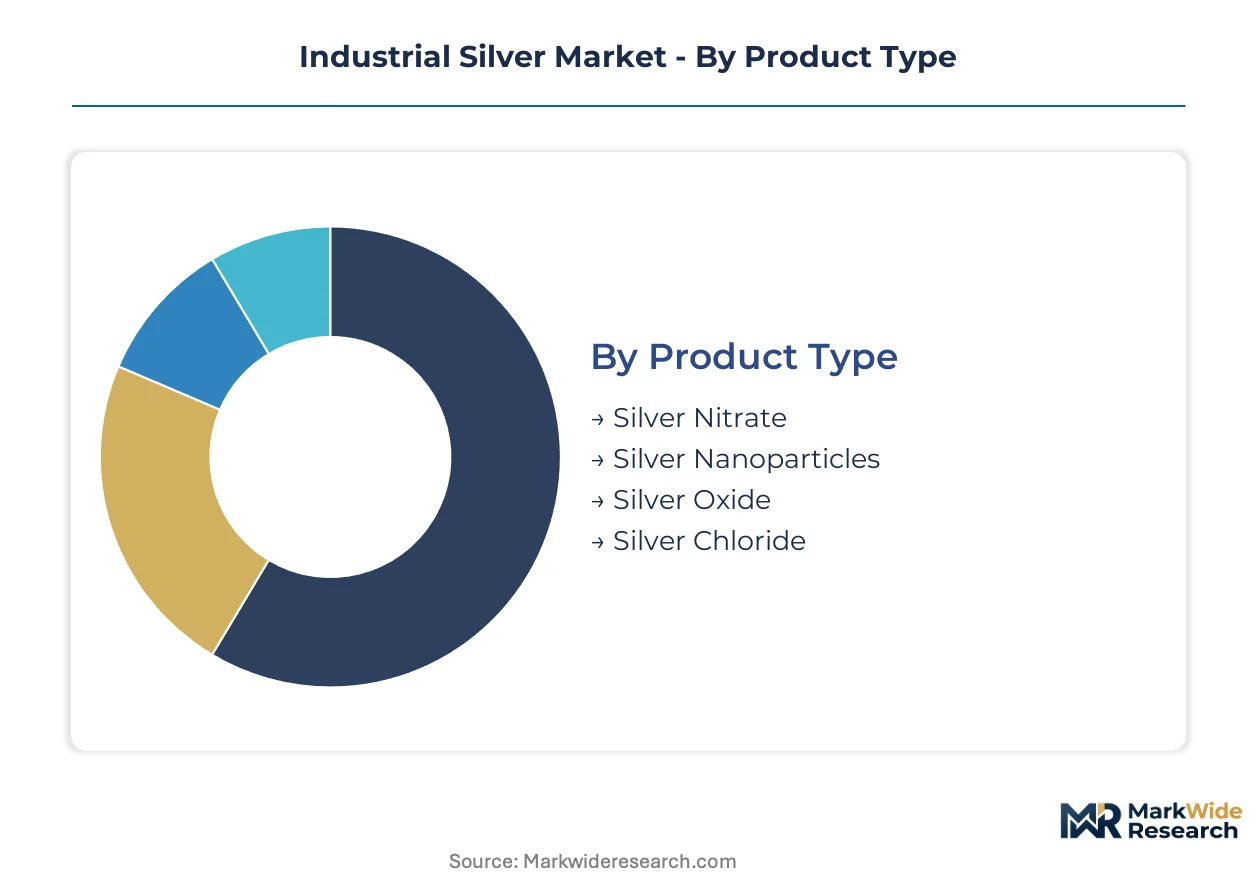
Industrial silver procurement strategies diverge sharply across chemical derivatives versus refined metal forms, with purity specifications and certification requirements dicting supplier qualification timelines. Buyers segment their sourcing based on whether applications demand antimicrobial efficacy, electrical conductivity, or metallurgical bonding properties.
Product Type:
Capital intensity peaks in silver nanoparticle production, where controlled nucleation environments and stabilization chemistries require specialized reactor infrastructure and cleanroom packaging capabilities.
- Silver Nitrate:Crystalline salt form serving as the foundational precursor for electroplating baths, photographic emulsions, and pharmaceutical compounding. Demand concentrates in Guangdong electroplating clusters where China's MEE wastewater standards are forcing facility consolidation among surviving operators with advanced effluent treatment.
- Silver Nanoparticles:Colloidal dispersions with tunable size distributions between 1-100 nanometers, stabilized by citrate or polyvinylpyrrolidone surface coatings. South Korean printed electronics manufacturers are qualifying these formulations for roll-to-roll antenna production on flexible substrates, displacing photolithography in wearable device circuits.
- Silver Oxide:Battery-grade material with controlled stoichiometry for zinc-silver oxide cell cathodes.
- Silver Chloride:Photographic-grade and reference electrode material with established pharmaceutical applications.
Most installed capacity flows through silver nitrate. Expansion is steepest in silver nanoparticles.
Application:
Margin structure varies by the stringency of end-use certification, with medical device applications commanding premium pricing through FDA and DEA compliance barriers that exclude commodity suppliers.
- Electronics:Wire bonding alloys, flip-chip interconnects, and multilayer ceramic capacitor terminations requiring 99.99% purity and controlled oxygen content. South Korean semiconductor packaging facilities concentrate demand for high-purity spherical powder, while Japanese substrate manufacturers specify exact particle size distributions for screen-printable pastes.
- Automotive Components:High-reliability electrical contacts and sensor elements exposed to thermal cycling and corrosive underhood environments. German tier-one suppliers are qualifying silver-palladium alloys for 48V mild-hybrid systems where arc erosion resistance exceeds copper-aluminum substitution thresholds.
- Medical Devices:Antimicrobial coatings on implantable hardware and wound dressing substrates.
- Conductive Adhesives:Isotropic and anisotropic formulations for die-attach and display bonding.
Electronics absorbs the greatest volume. Medical devices captures the highest margin per kilogram.
End User:
Procurement sophistication separates institutional buyers with dedicated metallurgy teams from smaller fabricators dependent on distributor technical support.
- Manufacturers:Tier-one electronics and automotive OEMs with direct smelter relationships, long-term offtake subscriptions, and in-house assay capabilities. Mexican mining operations are negotiating direct concentrate supply agreements with South Korean solar cell producers, compressing traditional trader channels.
- Research Institutions:University and national laboratory buyers with small-batch requirements and irregular ordering patterns.
- Healthcare Providers:Hospital systems and device OEMs sourcing FDA-approved silver derivatives for antimicrobial applications.
- Electronics Industries:Contract manufacturers and component suppliers with JIT inventory models.
Manufacturers dominate procurement volume. Healthcare providers are expanding fastest as antimicrobial certification pathways mature.
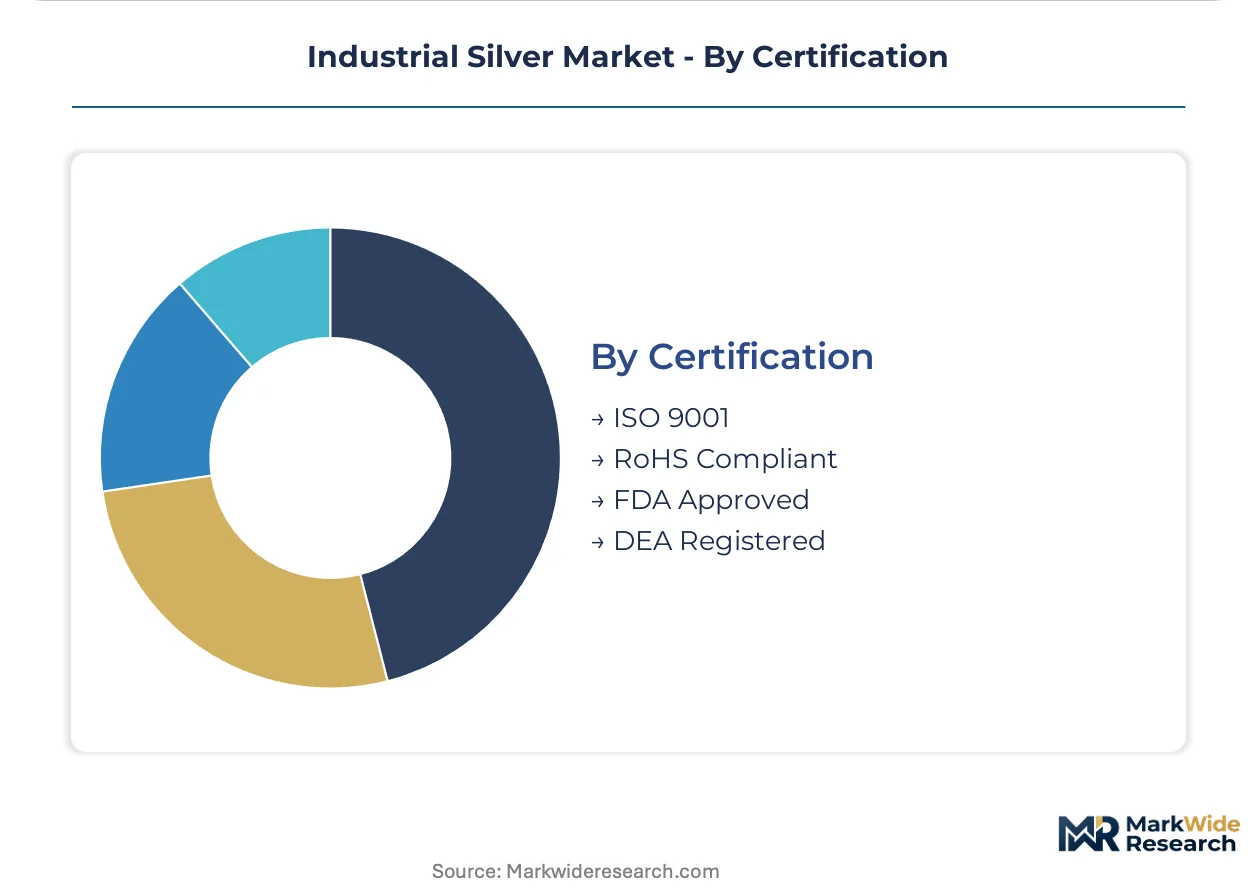
Certification:
Regulatory scope determines addressable market boundaries, with dual-certified suppliers capturing cross-border opportunities that single-standard competitors cannot pursue.
- ISO 9001:Baseline quality management system certification required for supplier qualification by major OEMs across all geographies.
- RoHS Compliant:EU substance restrictions on cadmium, lead, and mercury that silver products must document to access European electronics supply chains.
- FDA Approved:Medical device and pharmaceutical-grade silver derivatives requiring drug master files and facility inspections for wound dressing and implant coating applications.
- DEA Registered:Controlled substance handling permits for silver salts with potential precursor chemical classification, mandatory for pharmaceutical and forensic laboratory supply.
ISO 9001 and RoHS compliance are table stakes. FDA approval is gaining share fastest as medical device applications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexican mining jurisdictions sustain concentrate supply contracts with Asian smelters, while South Korean semiconductor packaging facilities concentrate demand for high-purity wire bonding materials. China's dual carbon mandates and MEE wastewater standards are compressing refined silver availability across electroplating hubs. German automotive tier-one suppliers qualify silver-palladium alloys for 48V mild-hybrid systems.
China
Photovoltaic manufacturers in Jiangsu and Guangdong provinces expand silver paste consumption for PERC and TOPCon cell architectures. The Ministry of Ecology and Environment enforces wastewater discharge standards without grandfathering provisions, forcing facility consolidation. Surviving electroplaters in the Pearl River Delta absorb concentrated demand for battery-grade silver salts.
South Korea
Semiconductor packaging facilities drive wire bonding and flip-chip interconnect material procurement. The MFDS regulates pharmaceutical-grade silver derivative imports while industrial buyers negotiate direct concentrate agreements. Seoul Capital Area electronics clusters are displacing traditional trader intermediaries through channel compression.
Mexico
Underground mining operations command premium concentrate terms through long-term smelter contracts. Labor disruptions and jurisdictional risks expose Asian buyers to single-source concentration. Sonora and Zacatecas mining districts anchor supply security for East Asian solar cell producers seeking offtake subscriptions.
Germany
Automotive electrical contact manufacturers face cost pressure from copper-aluminum substitution where thermal cycling permits. REACH substance restrictions and RoHS frameworks govern silver compound discharges across Bavarian and Baden-Württemberg fabrication facilities. KBA qualification requirements for 48V mild-hybrid systems sustain premium alloy demand.
United States
EPA hazardous waste rules and OSHA workplace exposure limits govern refining emissions across southwestern processing facilities. FDA certification pathways for antimicrobial medical device coatings create margin-protected niches. Texas and Arizona fabrication clusters specialize in high-reliability electrical contacts for aerospace applications.
Industrial Silver Market Competitive Landscape
Top-tier vendors anchor long-term concentrate supply chains, while mid-tier specialists compete on jurisdictional diversification and premium-grade underground output. The vendor base stratifies across Mexican mining breadth, Americas-wide jurisdictional spread, and high-grade specialization archetypes. Dominant competitive moves include direct offtake subscription negotiations with Asian buyers and backward integration into smelter qualification timelines.
Among mining-anchored suppliers, Fresnillo plc, Pan American Silver Corp, and Hecla Mining Company represent distinct strategic archetypes. Fresnillo exemplifies Mexican mining breadth sustaining Asian smelter relationships. Pan American Silver occupies a position emphasizing jurisdictional diversification across the Americas. Hecla Mining sits within the high-grade underground specialization tier commanding premium concentrate terms. These three entities illustrate how geographic concentration, operational focus, and customer proximity define competitive positioning in industrial silver procurement.
| Leading Market Players |
|---|
| Fresnillo plc |
| Pan American Silver Corp |
| Hecla Mining Company |
| Newmont Corporation |
| KGHM |
| Hindustan Zinc Ltd |
| Coeur Mining Inc |
| First Majestic Silver Corp |
| Silvercorp Metals Inc |
| Others |
Supply & Pricing Matrix
Silver nanoparticle inkjet formulation shifts are compressing photolithography cost structures while concentrating production among South Korean and Japanese suppliers with cleanroom packaging capabilities. This dual transformation simultaneously elevates quality premiums for qualified dispersions and exposes buyers to single-source risk in roll-to-roll manufacturing hubs.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for battery-grade silver salts as surviving Chinese electroplaters absorb demand from shuttered Guangdong facilities. Pricing stratifies across FDA-certified medical grades, RoHS-compliant electronics tiers, and industrial electroplating specifications. Cost compression in standard-grade nitrate runs through copper-aluminum substitution pressure in automotive electrical contacts. Contract manufacturers exhibit highest price sensitivity due to JIT inventory models, while healthcare providers accept premium spreads for antimicrobial certification pathways.
Supply Chain Analysis
China's dual carbon mandates and local-content requirements for solar paste qualification are reshaping sourcing patterns across East Asian fabrication clusters. Concentrate supply draws from Mexico, Peru, and Bolivia, with refined metal processing anchored in Chinese and South Korean smelter networks. Silver nitrate precursor and polyvinylpyrrolidone stabilizer inputs hinge on petrochemical supply chains exposed to feedstock volatility. Single-source vulnerability concentrates in Mexican mining jurisdictions serving Asian solar cell producers. Distribution runs through direct offtake subscriptions displacing traditional trader intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial silver constitutes a late-cycle quality story as battery-grade specifications diverge from solar paste requirements and FDA-certified medical applications command widening margin premiums. Demand is shifting toward premium purity tiers with compliance barriers that exclude commodity suppliers.
For Market Incumbents: Anticipate copper-aluminum substitution pressure in automotive electrical contacts by deepening backward integration into Mexican concentrate supply. Secure smelter qualification timelines for alternative mining jurisdictions to mitigate single-source concentration risk. Prioritize DEA registration and FDA drug master file investments to defend medical device coating margins against emerging chemical derivative specialists.
For New Entrants and Emerging Players: Capture antimicrobial medical textile white space through wound dressing FDA certification pathways that incumbent electroplaters cannot access without facility retrofit. Target South Korean printed electronics clusters with silver nanoparticle dispersions qualified for stretchable circuit roll-to-roll manufacturing. Lead with technical service bundling to offset incumbent scale advantages in spherical powder procurement.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier Mexican mining operations with uncontracted concentrate exposure to Asian solar demand. Long-term viability rests on jurisdictional diversification and underground grade quality sustaining premium terms. Watch for MEE enforcement intensity in Jiangsu and Guangdong provinces as inflection signal for Chinese electroplating consolidation pace and battery-grade salt demand concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Concentrate Supply | Mexican mining direct offtake agreements reduce working capital intensity for South Korean solar cell producers. |
| FDA Drug Master File Investment | Antimicrobial coating certification creates margin-protected niches in wound dressing and implant hardware applications. |
| Silver Nanoparticle Cleanroom Capacity Expansion | Roll-to-roll manufacturing qualification for South Korean flexible electronics clusters displaces photolithography. |
| Dual Carbon Compliance Retrofit | Advanced wastewater treatment adoption secures operating permits under China's MEE enforcement across Pearl River Delta. |
| DEA Controlled Substance Registration | Silver salt precursor handling permits unlock pharmaceutical and forensic laboratory supply contracts. |
Research Methodology
Coverage spans East Asian electronics fabrication clusters, Mexican mining districts, and German automotive supply chains, with primary inputs from each. Interviews with silver paste procurement leads at South Korean semiconductor packaging facilities, concentrate offtake negotiators at Mexican mining operations, and electroplating facility managers in Guangdong province combined with secondary validation from SEC 10-K filings, Chinese MEE discharge records, and customs trade data. Bottom-up demand modeling and top-down supply capacity triangulation anchored volume and value estimates.
Rate-of-change decomposition across the analysis window separated photovoltaic paste demand expansion from electronics miniaturization and medical device certification growth. Segmentation dimensions modeled include product type purity tiers, application certification requirements, end-user procurement sophistication, and regional regulatory frameworks. CAGRs derived from installed capacity buildout schedules, solar cell efficiency roadmaps, and battery-grade specification divergence timelines.
Photovoltaic technology substitution, MEE enforcement intensity variation, and copper-aluminum alloy performance thresholds are the dominant revision risks to demand forecasts. Concentrate supply disruption from Mexican labor actions or jurisdictional policy shifts could accelerate smelter qualification timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Bronze Market
Metals
Shipbuilding Steel Plate Market
Metals
China Copper Market
Metals
North America Grain Oriented Electrical Steel Market
Metals
Global Brass Rods Market
Metals
Rare Earth Metals Market
Metals
Metallurgical Silicon Market
Metals
Global Nickel Alloy Welding Consumables Market
Metals
Qatar Metalworking Market
Metals
Weathering Steel Market
Metals
Global Mercury Market
Metals
Steel Salvage Drums Market
Metals
Titanium Powder Market
Metals
Potassium Platinochloride Market
Metals
Metal Casting Market
Metals
Niobium Market