
 Flexible Bio-Foams Market | 2026-2036
Flexible Bio-Foams Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Bio-Foams Market Analytics
European chemical producers is expanding flexible bio-foam capacity to serve automotive and furniture OEMs seeking lower-carbon cushioning materials. BASF SE leverages its integrated polyols platform to supply certified bio-based polyurethane systems to seating manufacturers. Covestro AG anchors its competitive position through advanced catalysis research that improves the mechanical performance of sugarcane-derived foam grades.
Flexible bio-foams comprise cellular polymer structures manufactured from renewable feedstocks such as corn starch or sugarcane-derived polyols, with densities typically ranging from 20 to 80 kg per cubic meter depending on end-use load-bearing requirements. These materials primarily replace petroleum-based polyurethane in applications requiring compressive resilience combined with reduced cradle-to-gate carbon intensity. Bio-based foams currently lead volume shipments due to established supply chains and processing compatibility with conventional equipment, while plant-based foams represent the fastest-expanding category as direct-seaweed formulations achieve parity in tensile properties. Recycled foams occupy a specialized niche where post-industrial scrap streams support closed-loop manufacturing mandates from large furniture retailers.
The EPA governs volatile organic compound emissions from foam curing operations in the United States, while REACH restricts isocyanate and additive chemistries across European manufacturing sites. ECHA's ongoing substance evaluations are forcing reformulation timelines that favor bio-polyol systems with inherently lower hazard classifications. Stakeholders must monitor evolving certification schemes for biodegradability and carbon footprint accounting, as these standards will determine which material sources qualify for preferential procurement by multinational automotive and furniture brands.
Market Dynamics
Automotive OEM decarbonization mandates are compressing specification timelines for interior materials, forcing polyurethane suppliers to validate bio-based polyol systems within 18-month product cycles rather than traditional 36-month horizons.
Growth Catalysts
- EU Green Deal carbon intensity targets:REACH-compliant bio-polyol formulations now qualify for preferential procurement scoring by German and French seating manufacturers seeking Scope 3 reductions.
- Sugarcane-derived polyol catalysis advances:Improved mechanical performance parity with petroleum-based systems is accelerating adoption in luxury vehicle cushioning applications.
- Post-industrial scrap recovery infrastructure:Closed-loop manufacturing mandates from large furniture retailers in the United States are creating captive demand for recycled foam feedstocks.
Market Restraints
- Feedstock price volatility:Corn starch and sugarcane polyol costs fluctuate with agricultural commodity cycles, compressing margin predictability for foam compounders.
- Isocyanate supply concentration:European MDI production clusters in Germany and Belgium create geographic vulnerability for bio-foam manufacturers dependent on regional isocyanate supply.
- Curing temperature limitations:Bio-based formulations require modified processing windows that constrain throughput on legacy polyurethane production lines.
Strategic Opportunities
- Indian automotive component manufacturing:PLI scheme incentives for domestic auto parts production are opening specification windows for certified bio-based cushioning materials in Chennai and Pune supply clusters.
- Direct-seaweed foam formulations:Marine biomass-derived polyols achieving tensile property parity create white space in premium furniture and marine upholstery segments.
- Biodegradability certification alignment:ECHA substance evaluation timelines favor bio-polyol systems with inherently lower hazard classifications, accelerating qualification pathways.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise spanning both bio-polyol chemistry and conventional polyurethane processing commands premium compensation and extended hiring cycles.
- Multi-standard certification complexity:Reconciling carbon footprint accounting methodologies across ISO, REACH, and automotive OEM proprietary schemes extends product qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Bio-Foams Market |
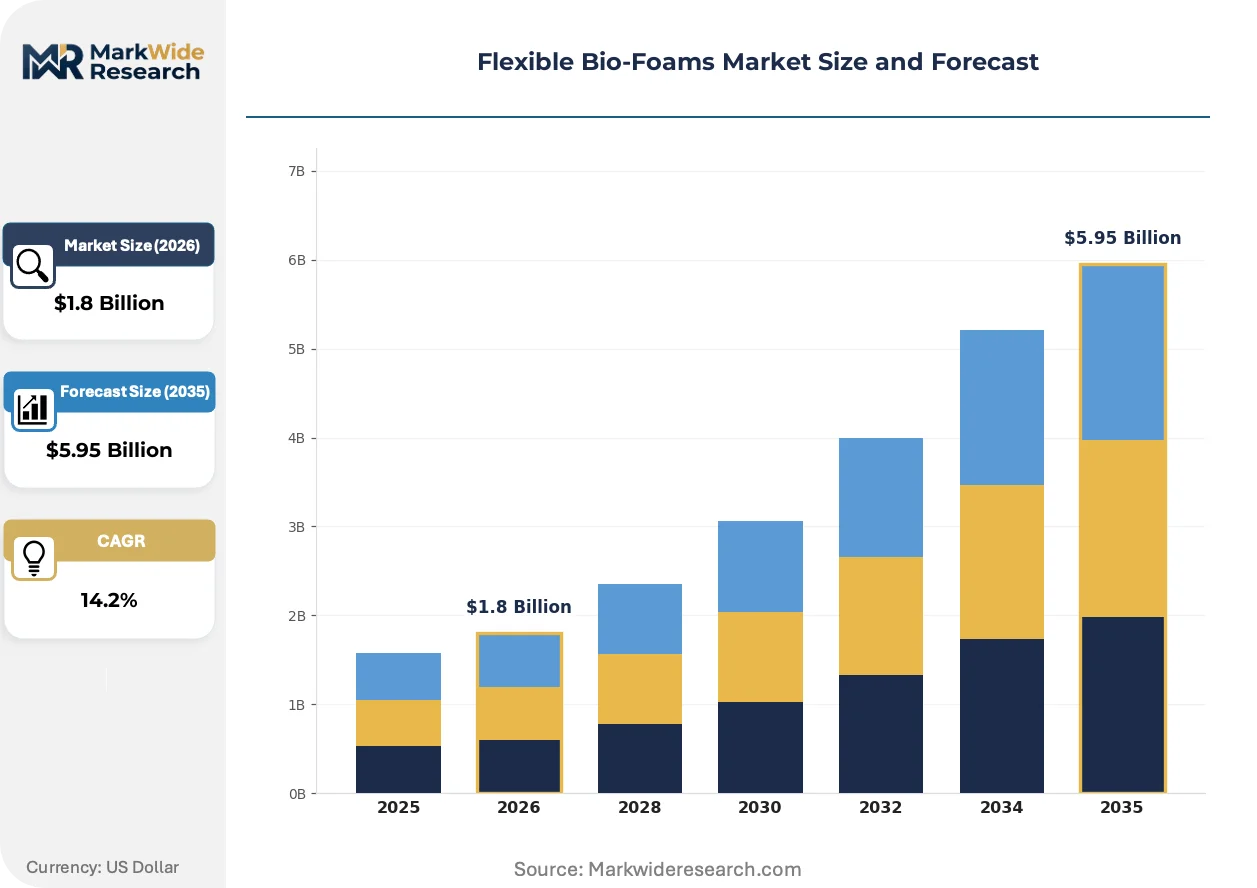
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Polyurethane Foams, Bio-Based Foams, Plant-Based Foams, Recycled Foams End Use Industry: Furniture, Automotive Interiors, Packaging, Construction Material Source: Corn Starch, Sugarcane, Seaweed, Other Natural Polymers Form: Sheet, Block, Roll, Moulded |
| Companies Covered | BASF SE, Covestro AG, Dow Inc., Huntsman International LLC, Armacell, Recticel, INOAC Corporation, Sekisui Chemical Co. Ltd., Woodbridge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Bio-Foams Market Evolving Landscape
Advanced catalysis research is collapsing the performance gap between renewable and petroleum-derived foam systems. Three convergent developments are restructuring competitive advantage in material specification.
Plant-based polyurethane chemistry is converging with conventional high-pressure processing equipment. Tier 1 seating suppliers in Germany and the United States are validating sugarcane-derived formulations at production scale without capital-intensive line retrofits. This compatibility is compressing adoption barriers for automotive OEMs with constrained capex cycles.
REACH substance evaluations are forcing isocyanate reformulation across European manufacturing sites. ECHA's hazard reclassification timeline is disqualifying legacy additive packages and accelerating migration toward bio-polyol systems with inherently lower toxicity profiles. German chemical clusters are consolidating reformulation expertise to capture specification mandates from Stuttgart and Munich automotive headquarters.
Furniture retailers are unbundling after-sales material provenance from product warranties. Large-format chains in the United States and France now require cradle-to-gate carbon documentation for cushioning components, displacing spot-buying relationships with long-term supply agreements tied to certified bio-content thresholds. This contractual shift is most visible in North American bedroom and upholstery categories.
Flexible Bio-Foams Market Segmentation
Flexible bio-foam procurement decisions split sharply between volume-driven automotive contracts and premium furniture specifications. Each segmentation dimension reveals distinct margin structures and qualification barriers that reshape supplier positioning.
Product Type:
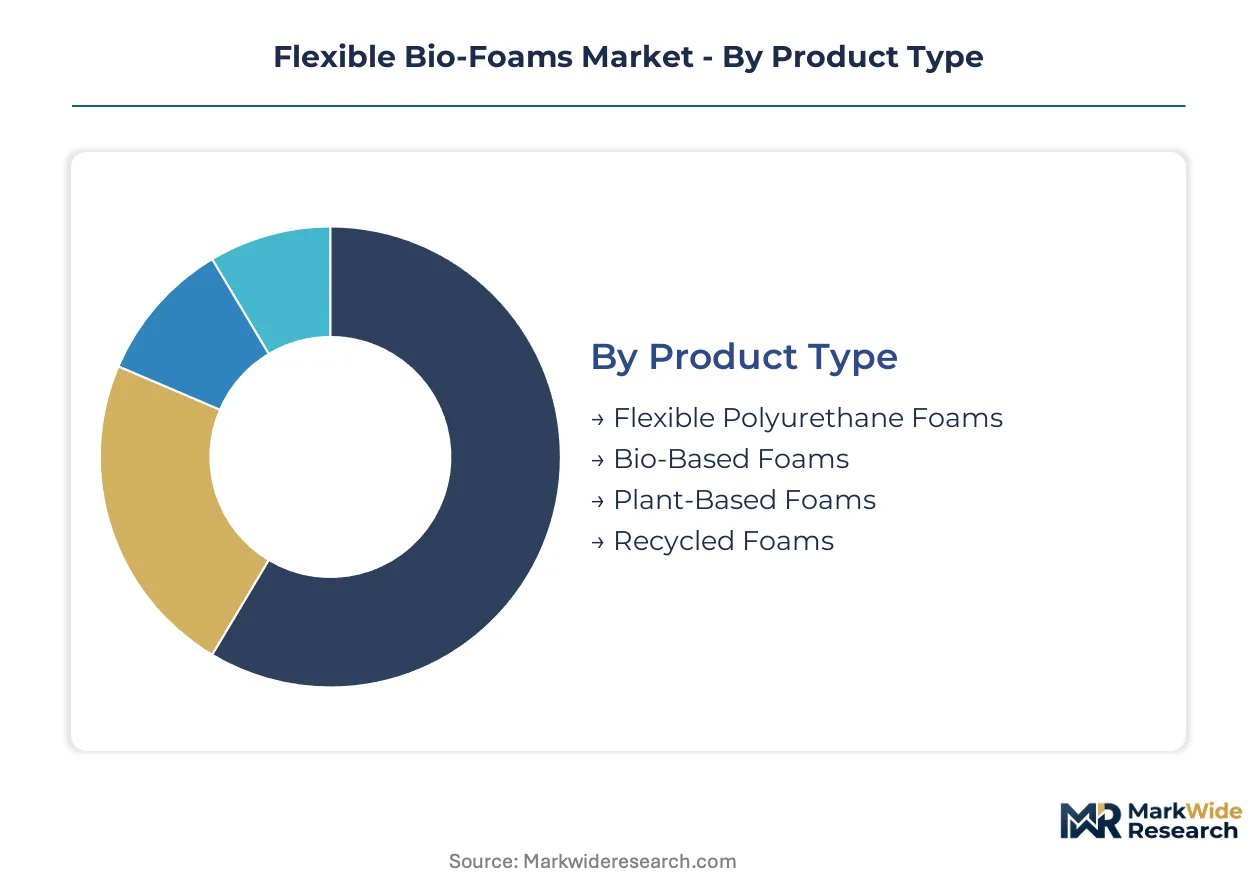
Bio-based foams dominate current shipment volumes while plant-based formulations command expanding specification premiums.
- Bio-Based Foams:Polyol systems derived from renewable feedstocks with established supply chains and processing compatibility with conventional polyurethane equipment. German automotive seating manufacturers specify these for Scope 3 carbon reduction mandates under EU Green Deal targets.
- Plant-Based Foams:Direct-seaweed and agricultural biomass formulations achieving tensile property parity with petroleum systems. Luxury vehicle cushioning applications in France and premium furniture segments in the United States drive fastest adoption.
- Flexible Polyurethane Foams:Conventional petroleum-derived systems still anchoring high-volume automotive production.
- Recycled Foams:Post-industrial scrap streams serving closed-loop manufacturing mandates from large furniture retailers.
Today's leader: Bio-Based Foams. Tomorrow's challenger: Plant-Based Foams.
End Use Industry:
Automotive qualification cycles compress specification timelines while furniture procurement locks in long-term carbon accounting contracts.
- Automotive Interiors:OEM decarbonization mandates force 18-month validation windows for bio-polyol seating systems versus traditional 36-month horizons. German and French manufacturers lead procurement volume.
- Furniture:Large-format retailers in the United States and France now require cradle-to-gate carbon documentation, displacing spot-buying with certified bio-content supply agreements. Bedroom and upholstery categories show strongest contractual shift.
- Packaging:Protective cushioning applications with emerging biodegradability requirements.
- Construction:Insulation and sealing applications with slower adoption due to building code certification complexity.
Automotive Interiors capture current procurement volume. Furniture contracts are climbing the fastest toward premium pricing tiers.
Material Source:
Sugarcane polyol chemistry advances reshape competitive positioning against corn starch supply chain maturity.
- Sugarcane:Brazilian and Indian agricultural supply bases feed advanced catalysis research improving mechanical performance parity. Covestro AG anchors competitive positioning through sugarcane-derived foam grades for luxury vehicle applications.
- Corn Starch:Established North American and European supply chains with price volatility tied to agricultural commodity cycles. BASF SE leverages integrated polyols platforms for certified systems to seating manufacturers.
- Seaweed:Marine biomass polyols creating white space in premium furniture and marine upholstery with tensile property achievements.
- Other Natural Polymers:Experimental feedstocks including lignin and cellulose derivatives.
Corn Starch anchors supply security. Sugarcane is gaining share fastest through performance parity milestones.
Form:
Processing compatibility determines adoption barriers across legacy equipment footprints.
- Sheet:Flat stock for lamination and cutting operations in furniture manufacturing.
- Block:Bun stock for fabrication into custom shapes across automotive and furniture applications.
- Roll:Continuous formats for automated cutting and bedding production lines.
- Moulded:Direct-shape forming for complex automotive seating contours requiring highest dimensional precision.
Block forms dominate current fabrication flexibility. Moulded formats are expanding most quickly through automotive specification consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting flexible bio-foam production toward jurisdictions where REACH compliance costs and carbon accounting mandates create specification premiums that offset feedstock logistics expenses.
Germany
Automotive OEM decarbonization mandates from Stuttgart and Munich headquarters compress validation timelines for bio-polyol seating systems. EU Green Deal carbon intensity targets qualify REACH-compliant formulations for preferential procurement scoring by seating manufacturers. The North Rhine-Westphalia chemical cluster consolidates reformulation expertise to capture specification mandates from German automotive headquarters.
United States
Large-format furniture retailers in North Carolina and California now require cradle-to-gate carbon documentation for cushioning components. EPA volatile organic compound emissions regulations govern foam curing operations across manufacturing sites. The Southeast automotive corridor in Tennessee and South Carolina validates sugarcane-derived formulations at production scale for domestic OEM supply chains.
France
Luxury vehicle cushioning applications drive fastest adoption of plant-based foam grades with tensile property parity. REACH restrictions on isocyanate and additive chemistries accelerate migration toward bio-polyol systems with lower hazard classifications. The Auvergne-Rhône-Alpes region hosts seating manufacturers seeking Scope 3 reductions under EU Green Deal targets.
India
PLI scheme incentives for domestic auto parts production open specification windows for certified bio-based cushioning materials. The country's national chemical regulator evaluates substance classifications for polyol systems used in automotive applications. Chennai and Pune supply clusters integrate bio-foam formulations into component manufacturing for export and domestic OEM programs.
Brazil
Sugarcane-derived polyol supply bases feed advanced catalysis research improving mechanical performance parity with petroleum systems. The national environmental regulator oversees emissions standards for foam curing operations in industrial zones. São Paulo state chemical producers expand flexible bio-foam capacity to serve furniture OEMs seeking lower-carbon cushioning materials.
Flexible Bio-Foams Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-seaweed formulations and closed-loop scrap recovery systems. The market structure consolidates around integrated polyol platforms and specialized catalysis research capabilities. Three archetypes dominate: multinational chemical conglomerates with certified bio-based systems, mid-scale compounders focused on regional automotive supply chains, and marine biomass specialists developing premium furniture grades. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure feedstock offtake agreements and validate processing compatibility with legacy equipment.
Among European-based chemical producers, BASF SE and Covestro AG exemplify the integrated platform archetype, leveraging established polyols infrastructure to supply certified bio-based polyurethane systems. Dow Inc. occupies a position spanning conventional petroleum-derived capacity and renewable feedstock development. These three entities anchor the competitive landscape through reformulation expertise that reconciles bio-polyol chemistry with high-pressure processing equipment requirements demanded by Tier 1 seating suppliers.
| Leading Market Players |
|---|
| BASF SE |
| Covestro AG |
| Dow Inc. |
| Huntsman International LLC |
| Armacell |
| Recticel |
| INOAC Corporation |
| Sekisui Chemical Co. Ltd. |
| Woodbridge |
| Others |
Value Network & Pricing Analysis
Sugarcane-derived polyol catalysis advances simultaneously compress production costs and redistribute supply concentration toward Brazilian and Indian agricultural processing hubs. This dual transformation rewards compounders with captive feedstock arrangements while exposing spot-market buyers to agricultural commodity cycle volatility.
Pricing Analysis
Distributor margins on bio-based foam formulations compress under direct-to-OEM contracting arrangements that German and French automotive seating manufacturers favor for Scope 3 carbon reduction programs. Three-tier pricing structure across certified bio-content, transitional blends, and conventional petroleum systems reflects REACH compliance tiering and volume scale commitments. Pricing pressure stems from corn starch feedstock volatility that squeezes compounder margins during harvest shortfalls. Furniture retailers exhibit highest price sensitivity due to long-term carbon accounting contracts that lock in bio-content thresholds, while luxury vehicle cushioning applications tolerate premium positioning for tensile property parity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Stuttgart and Munich automotive headquarters, bypassing traditional chemical distribution networks. Supply concentrates in Germany, Brazil, and India, with German chemical clusters anchoring reformulation expertise and Brazilian sugarcane processing feeding polyol supply security. Raw material dependencies rest on isocyanate supply from Belgian and German MDI production clusters, agricultural polyol feedstocks, and specialized catalyst packages. Single-source vulnerability in European isocyanate supply creates geographic concentration risk for bio-foam manufacturers. Distribution runs through Tier 1 seating supplier networks that validate processing compatibility with legacy high-pressure equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance cost differentials between European and Indian manufacturing jurisdictions create arbitrage opportunities for compounders willing to relocate formulation capacity to Chennai and Pune supply clusters.
For Market Incumbents: Anchor competitive position through backward integration into sugarcane polyol supply bases in Brazil and India, securing captive feedstock offtake against agricultural commodity volatility. Expand catalysis research partnerships to defend margin position against direct-seaweed foam entrants achieving tensile property parity. Prioritize certification investment in biodegradability standards that ECHA substance evaluations favor for lower hazard classifications. For New Entrants and Emerging Players: E-commerce platform direct sourcing offers the lowest-friction route to penetrate premium furniture segments in France and the United States, bypassing incumbent distributor relationships. Target marine upholstery and luxury vehicle cushioning applications where plant-based foam grades command specification premiums. Pursue white-label manufacturing partnerships with Chennai automotive component suppliers benefiting from PLI scheme incentives. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale compounders lacking integrated polyol platforms but possessing validated OEM qualification pathways. Five-to-ten year viability hinges on successful navigation of ECHA reformulation timelines and carbon accounting standard consolidation. Watch for inflection signals in direct-seaweed foam tensile property achievements that could displace sugarcane-derived systems in premium segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive sugarcane polyol offtake from Brazilian agricultural processors insulates margin predictability against commodity cycles. |
| Advanced Catalysis Research Partnership | Collaboration with German chemical clusters accelerates mechanical performance parity milestones for bio-polyol seating systems. |
| Biodegradability Certification Investment | ECHA substance evaluation alignment qualifies formulations for preferential procurement scoring under EU Green Deal targets. |
| Direct-to-OEM Channel Expansion | Long-term supply agreements with Stuttgart automotive headquarters displace spot-buying relationships and lock in volume commitments. |
| Geographic Manufacturing Footprint Shift | Chennai and Pune production placement captures PLI scheme incentives for domestic auto parts manufacturing. |
Research Methodology
Direct dialogue with polyurethane plant managers, Tier 1 seating supplier procurement leads, automotive OEM platform engineers, and ECHA regulatory affairs specialists grounded qualitative assessment in operational reality. Secondary validation drew from customs and trade data, Cefic chemical industry reports, SEC 10-K filings from listed compounders, and REACH substance evaluation documentation. Bottom-up shipment estimates from individual production facilities reconciled with top-down demand modeling across automotive and furniture end-use segments.
Segment-level value outputs across the projection horizon reflect modeled interactions between bio-based, plant-based, and recycled foam categories with automotive interior, furniture, packaging, and construction applications. The analytical framework incorporated grade tier differentiation, regional production hub concentration, and end-use industry qualification cycle compression. CAGRs derived from elasticity-adjusted demand curves that weight EU Green Deal carbon intensity targets against feedstock price volatility assumptions.
Feedstock price volatility, ECHA hazard reclassification timing, and automotive OEM decarbonization mandate acceleration are the dominant revision risks that could shift trajectory materially. Forecasts reflect documented assumptions regarding catalysis research progress and certification scheme evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Synthetic Graphite Market
Advanced Materials
Curable Materials Market
Advanced Materials
Buckminsterfullerene Market
Advanced Materials
North America Advanced Phase Change Materials Market
Advanced Materials
North America Plasma Powder Market
Advanced Materials
Lab-Grown Rough Diamond Market
Advanced Materials
Advanced Nanomaterials Market
Advanced Materials
Corundum Market
Advanced Materials
High Nickel Cathode Materials Market
Advanced Materials
APAC Advanced Building Materials Market
Advanced Materials
Silica Aerogel Market
Advanced Materials
Glass Reinforced Vinyl Ester (GRV) Market
Advanced Materials
Electromagnetic Shielding Market
Advanced Materials
Lithium Hydride Market
Advanced Materials
Global Next Generation Anode Materials Market
Advanced Materials
Europe Advanced Building Materials Market