
 Flexible Epoxy Resin Market | 2026-2036
Flexible Epoxy Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Epoxy Resin Market Intelligence
Distributor networks for specialty chemicals is narrowing as direct procurement from resin producers gains ground among large-volume buyers. Hexion leverages its integrated phenolic and epoxy supply chain to secure raw material access across North American manufacturing corridors. Olin Corporation anchors its position through chlor-alkali backward integration, controlling critical feedstock costs for bisphenol-A derived epoxies. Huntsman International LLC differentiates via polyurethane-epoxy hybrid technologies that serve demanding automotive and aerospace specifications.
Flexible epoxy resin denotes a modified thermoset polymer system formulated with aliphatic or rubber-toughened backbones to achieve elongation at break typically exceeding 5% while retaining chemical resistance and adhesion strength. Manufacturers produce these resins through reaction of epichlorohydrin with flexible polyols or carboxy-terminated butadiene-acrylonitrile rubbers, yielding materials engineered primarily for stress-absorbing adhesives, impact-resistant coatings, and compliant composite matrices in dynamic-load applications. Water-based formulations are capturing share as environmental compliance tightens, though solvent-based systems still dominate high-performance coatings where rapid cure and extreme chemical resistance remain non-negotiable. Adhesives applications lead volume consumption in automotive structural bonding, while composites represent the fastest-expanding category as wind blade and electric vehicle component producers adopt toughened epoxy systems.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based formulation production, while REACH registration requirements in Europe enforce comprehensive toxicity documentation for epoxy hardeners and diluents. China's MEE administers GB standards for volatile organic compound emissions that directly shape local formulation strategies and import eligibility. Buyers and producers must track evolving substance restrictions and carbon border mechanisms to anticipate reformulation investments and geographic sourcing shifts.
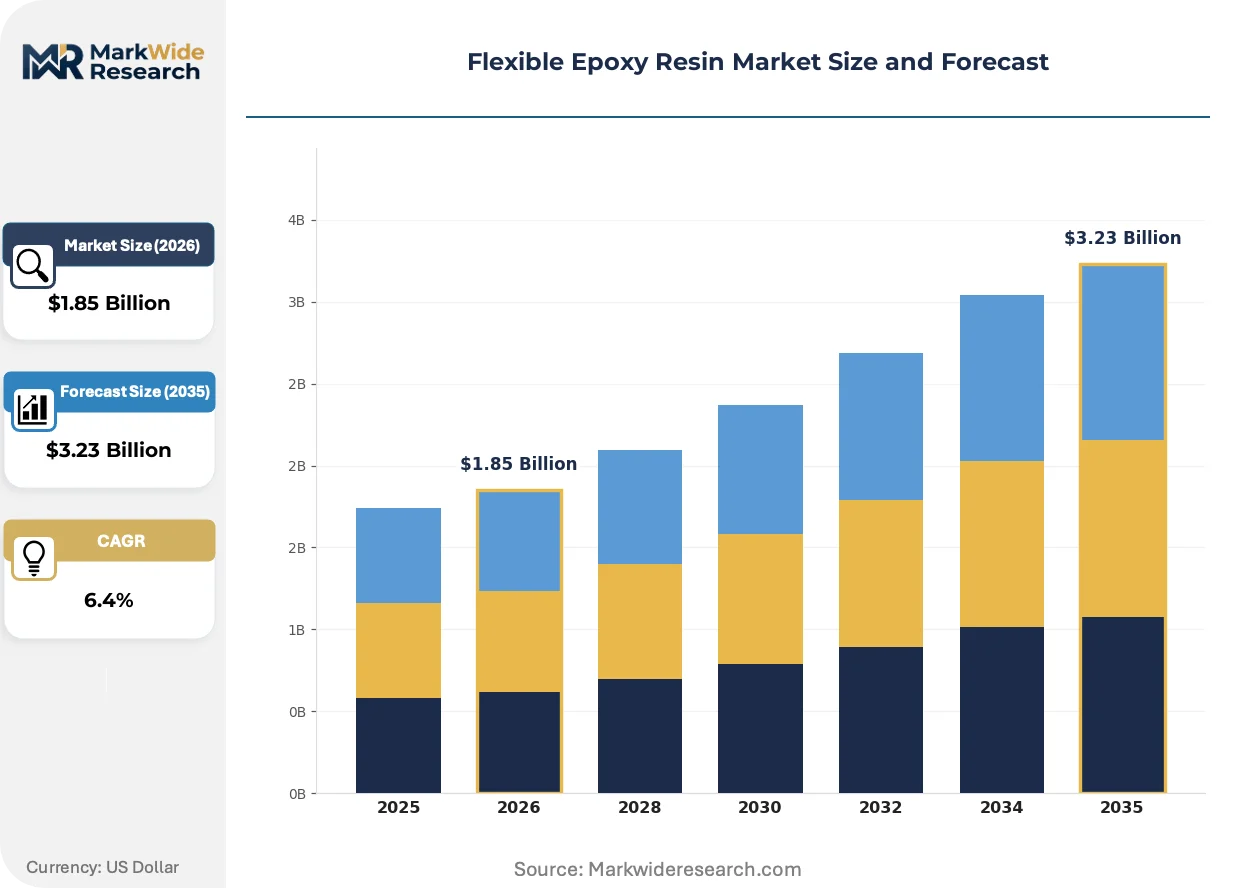
Market Dynamics
Automotive lightweighting mandates and tightening VOC regulations are compressing formulation cycles while forcing solvent-to-water technology transitions across adhesive and coating applications.
Growth Catalysts
- REACH Phase-In Substances:ECHA's updated registration requirements for epoxy hardeners are accelerating compliant water-based formulation development among European coating manufacturers.
- Wind Blade Manufacturing:Toughened epoxy systems for longer turbine blades are displacing polyester in composite matrices across Denmark and Spain production facilities.
- Electric Vehicle Battery Encapsulation:Flexible epoxy's thermal cycling resistance is capturing design-in opportunities with German and South Korean automotive OEMs.
Market Restraints
- Epichlorohydrin Feedstock Volatility:Chlor-alkali capacity concentration in China and the US Gulf Coast exposes resin producers to caustic soda and propylene cost swings.
- Curing Agent Supply Concentration:Aliphatic amine production clusters in Belgium and the Netherlands create single-source vulnerability for European formulators.
- Acrylic Urethane Substitution:UV-curable acrylates with comparable elongation properties are eroding flexible epoxy share in decorative industrial coatings.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor and PCB production are creating localized demand for conformal coating-grade flexible epoxies.
- Repair and Maintenance Channel:Two-component cartridge systems for infrastructure concrete repair are bypassing traditional distributor networks through direct contractor sales.
- EU Green Deal Public Procurement:Biobased content thresholds in construction tenders are opening formulation partnerships with epoxidized vegetable oil suppliers.
Industry Challenges
- Formulation Chemist Shortage:Specialized expertise in rubber-toughening chemistry and cure kinetics is scarce across US and European resin laboratories.
- Dual-Cure Certification Complexity:UV-thermal hybrid systems for automotive assembly require simultaneous validation under SAE and OEM-specific test protocols.
- Legacy Equipment Retrofit Costs:Water-based system conversion demands heated spray booths and humidity-controlled curing environments incompatible with existing solvent infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Epoxy Resin Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Hot Melt, Two-Part End Use Industry: Aerospace, Automotive, Marine, Construction Formulation Type: Flexible, Rigid, High-Temperature, Low-Viscosity Application: Adhesives, Coatings, Composites, Sealants |
| Companies Covered | Hexion, Olin Corporation, Huntsman International LLC, Kukdo Chemical, DIC Corporation, Aditya Birla Chemicals, 3M Co., Daikin Industries Ltd., DuPont de Nemours Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Epoxy Resin Market Strategic Shifts & Innovations
Formulation chemistry is pivoting toward bio-derived feedstocks and hybrid cure mechanisms while digital tools compress development timelines for application-specific grades.
Bio-based epoxidized linseed and soybean oils are achieving performance parity with petrochemical-derived flexible epoxies in non-structural coating applications. Scandinavian and Dutch formulators are qualifying these systems for marine and flooring specifications at accelerated pace. Petrochemical bisphenol-A flexible epoxy is rendering obsolete in decorative and semi-structural segments where biogenic content certificates command procurement preference.
EPA National Emission Standards for Hazardous Air Pollutants are tightening facility-level VOC thresholds for solvent-based coating production. US manufacturers face capital-intensive abatement equipment or reformulation to exempt water-based and 100% solids systems. High-performance industrial coatings segment is responding with hybrid waterborne-UV technologies that preserve chemical resistance while meeting Hazardous Air Pollutant limits.
Direct technical service relationships between resin producers and tier-one automotive OEMs are displacing traditional distributor-mediated specification processes. Huntsman and Hexion field application engineers now embed with Stuttgart and Detroit engineering teams during adhesive selection phases. This pattern concentrates most visibly in electric vehicle platform development programs where structural bonding specifications are set years ahead of production ramp.
Flexible Epoxy Resin Market Segmentation
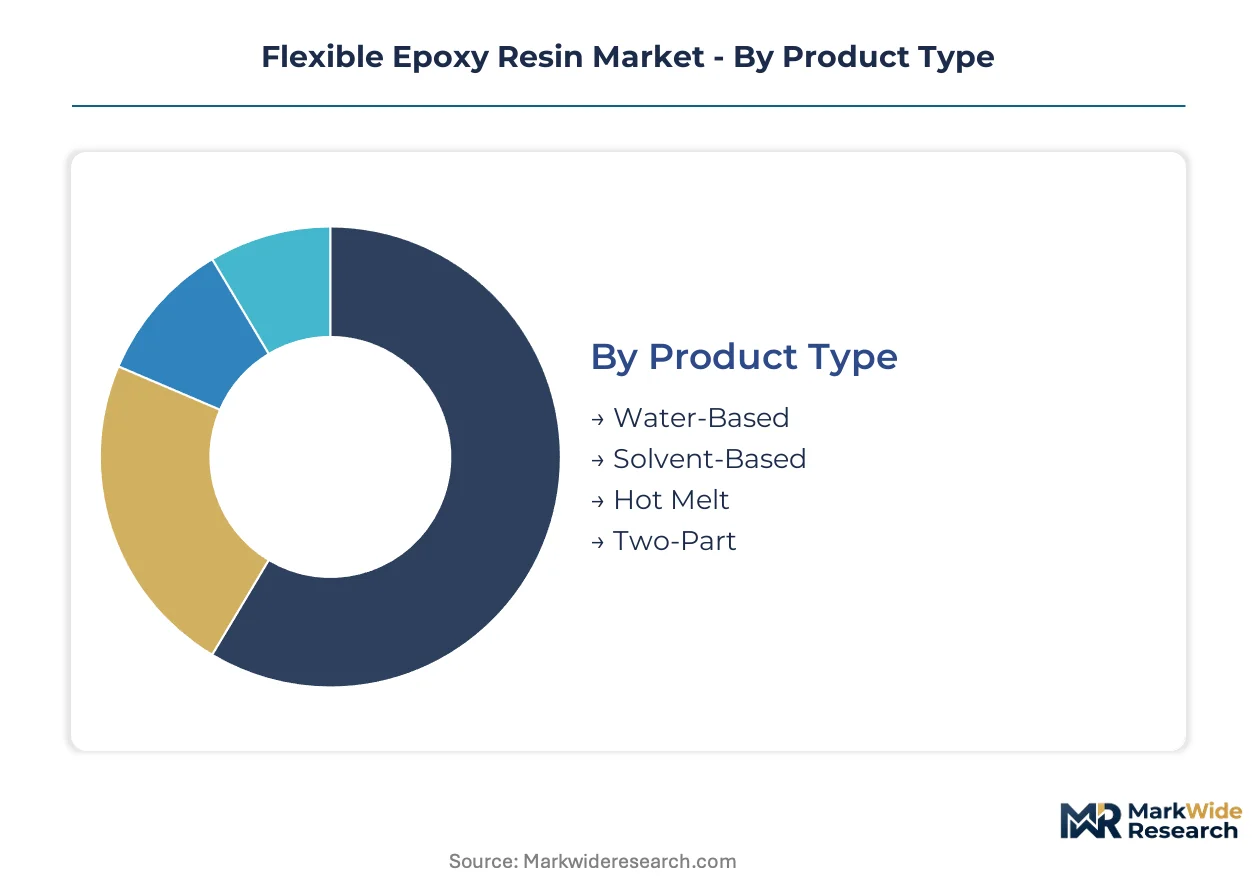
Segmentation in flexible epoxy resins tracks how formulation chemistry, application requirements, and regulatory pressures fragment demand across incompatible specification tiers. Buyers select systems based on cure kinetics, elongation targets, and compliance boundaries rather than commodity pricing.
Product Type:
Cost tier differentiation separates commodity formulations from premium systems requiring specialized curing infrastructure or environmental compliance investments.
- Water-Based:Emulsion-dispersed epoxy resins with aliphatic amine hardeners enable low-VOC application in heated spray environments. European coating manufacturers in Stuttgart and Milan are converting legacy solvent lines to meet ECHA registration thresholds. Water-based systems command the established base. The steepest expansion runs through two-part systems.
- Solvent-Based:Aromatic hydrocarbon carriers deliver rapid cure and extreme chemical resistance for industrial maintenance coatings. EPA National Emission Standards for Hazardous Air Pollutants constrain US Gulf Coast production capacity, forcing abatement investments or reformulation.
- Hot Melt:Solid epoxy formulations applied molten for immediate green strength in automated assembly. Automotive tier suppliers in South Korea favor these systems for battery tray bonding where solvent-free operation eliminates drying stages.
- Two-Part:Separately packaged resin and hardener components mixed at point of application. Marine repair contractors in Rotterdam and Singapore specify these for underwater cure capability and adjustable working time.
Water-based formulations anchor volume in regulated European markets. Two-part systems gain share fastest in repair and maintenance channels bypassing traditional distribution.
End Use Industry:
Application severity dictates backbone chemistry selection, with dynamic-load environments demanding rubber-toughened modifications unavailable in standard grades.
- Automotive:Crash-durable structural adhesives for aluminum-intensive body-in-white construction. German OEMs in Munich and Wolfsburg specify toughened epoxies for electric vehicle platform bonding where thermal cycling resistance exceeds 150°C. Automotive commands the established base. The steepest expansion runs through aerospace.
- Construction:Concrete repair mortars and crack-injection systems for infrastructure rehabilitation. US Department of Transportation specifications in California and New York mandate elongation at break above 8% for seismic-rated applications.
- Aerospace:Film adhesives and syntactic core materials for primary structure bonding. Toulouse and Hamburg assembly lines qualify flexible epoxy systems for 180°C cure cycles compatible with carbon fiber prepregs.
- Marine:Osmosis-resistant barrier coats and flexible fairing compounds for composite hull construction. Dutch yacht builders in Friesland specify low-modulus systems accommodating fiberglass laminate movement in North Sea conditions.
Automotive structural bonding generates the largest volume commitments. Aerospace qualification cycles are compressing as satellite constellation producers accelerate material approvals.
Formulation Type:
Performance tier segmentation reflects trade-offs between elongation, temperature resistance, and processing viscosity that cannot be optimized simultaneously.
- Flexible:CTBN rubber-toughened backbones achieving 15-50% elongation with retained adhesion. Wind blade manufacturers in Denmark specify these for root insert bonding where cyclic loading exceeds 10^7 cycles. Flexible formulations command the established base. The steepest expansion runs through high-temperature grades.
- High-Temperature:Anhydride-cured or BMI-modified systems maintaining properties above 200°C. Electric motor manufacturers in Japan specify these for stator encapsulation where thermal class H requirements apply.
- Rigid:Unmodified bisphenol-A or bisphenol-F resins for maximum modulus and compressive strength. Printed circuit board laminators in Taiwan favor rigid systems for dimensional stability in multilayer fabrication.
- Low-Viscosity:Reactive diluent-containing formulations enabling vacuum infusion of large composite structures. Spanish wind blade producers use these for 80-meter-plus carbon spar cap manufacturing.
Flexible systems dominate adhesives consumption. High-temperature grades are climbing fastest as electrification applications multiply.
Application:
Functional requirement separates surface protection from structural integration, with each demanding incompatible rheology and cure chemistry.
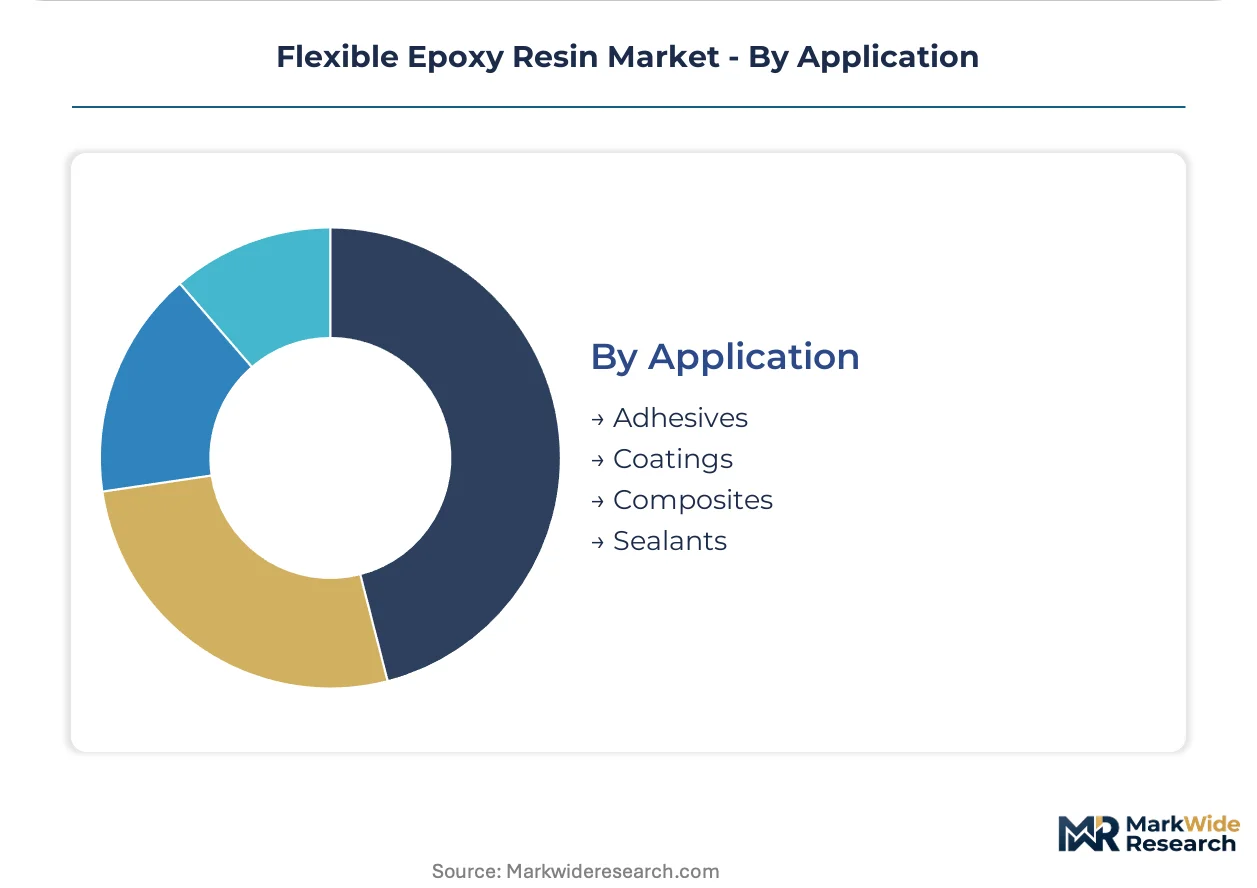
- Adhesives:Toughened systems for load-bearing joints in dissimilar material assemblies. Stuttgart engineering teams specify SAE-validated grades for aluminum-to-composite bonding in electric vehicle architectures. Adhesives command the established base. The steepest expansion runs through composites.
- Composites:Toughened matrix resins for impact-resistant fiber-reinforced structures. Vestas and Siemens Gamesa production in Spain specify these for 100-meter blade spar caps where resin fracture toughness exceeds 1.5 MPa·m^1/2.
- Coatings:Elastomeric films for chemical containment and abrasion resistance. German chemical processors specify flexible epoxy tank linings for sulfuric acid service with 5% design elongation.
- Sealants:Low-modulus compounds accommodating joint movement in building envelopes. Singapore infrastructure contractors specify these for movement joints in tropical high-humidity exposure.
Adhesives applications concentrate procurement among tier-one automotive suppliers. Composites consumption is expanding most quickly as wind turbine dimensions increase.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese resin producers command pricing leverage over European coating formulators due to captive epichlorohydrin supply, while US Gulf Coast chlor-alkali concentration exposes buyers to caustic soda cost volatility. This asymmetry reshapes procurement geography across automotive and wind energy supply chains.
China
Domestic composites and electronics manufacturing scale drives flexible epoxy consumption in Jiangsu and Guangdong provinces. MEE-administered GB standards for volatile organic compound emissions shape local formulation strategies and import eligibility for foreign suppliers. Yangtze River Delta chemical clusters near Shanghai are expanding water-based system capacity to serve PCB laminators and battery encapsulators.
United States
Automotive lightweighting mandates from NHTSA and California Air Resources Board compress formulation cycles for structural adhesives. EPA National Emission Standards for Hazardous Air Pollutants constrain solvent-based production capacity along the Gulf Coast, forcing abatement investments or reformulation to exempt systems. Detroit engineering teams specify toughened epoxies for electric vehicle platform bonding years ahead of production ramp.
Germany
REACH Phase-In Substances requirements from ECHA accelerate compliant water-based formulation development among Stuttgart and Munich coating manufacturers. EU Green Deal public procurement biobased content thresholds open formulation partnerships with epoxidized vegetable oil suppliers. Hamburg and Wolfsburg automotive OEMs specify flexible epoxy systems for aluminum-intensive body-in-white construction with thermal cycling resistance exceeding 150°C.
India
PLI scheme incentives for semiconductor and PCB production create localized demand for conformal coating-grade flexible epoxies in Maharashtra and Karnataka. BIS certification requirements for imported resin systems slow market entry while domestic formulators scale capacity. Gujarat chemical corridors near Ahmedabad are attracting epoxy hardener investments to serve electronics manufacturing clusters.
South Korea
Electric vehicle battery encapsulation demand captures design-in opportunities with domestic automotive OEMs seeking thermal cycling resistance. MFDS chemical substance registration requirements align with REACH-equivalent documentation standards for epoxy hardeners and diluents. Busan-Ulsan industrial zones specialize in hot melt formulations for battery tray bonding where solvent-free operation eliminates drying stages.
Flexible Epoxy Resin Market Key Industry Players
Integrated petrochemical conglomerates and specialty chemical specialists split the market between feedstock security and formulation expertise. Concentration is moderate, with top producers controlling chlor-alkali or phenolic supply chains while mid-tier players compete on application-specific grades. Two strategic archetypes dominate: backward-integrated resin producers securing epichlorohydrin access, and hybrid-technology specialists combining epoxy with polyurethane or acrylate chemistries. Competitive moves center on captive raw material investments and direct technical service embedding with tier-one OEMs.
Among North American integrated producers, Hexion and Olin Corporation exemplify the backward-integrated archetype, with the former leveraging phenolic supply chain integration and the latter anchoring position through chlor-alkali control. Huntsman International LLC occupies the hybrid-technology specialist tier, representing polyurethane-epoxy convergence strategies that serve demanding automotive and aerospace specifications through embedded application engineering.
| Leading Market Players |
|---|
| Hexion |
| Olin Corporation |
| Huntsman International LLC |
| Kukdo Chemical |
| DIC Corporation |
| Aditya Birla Chemicals |
| 3M Co. |
| Daikin Industries Ltd. |
| DuPont de Nemours Inc. |
| Others |
Cost & Logistics Intelligence
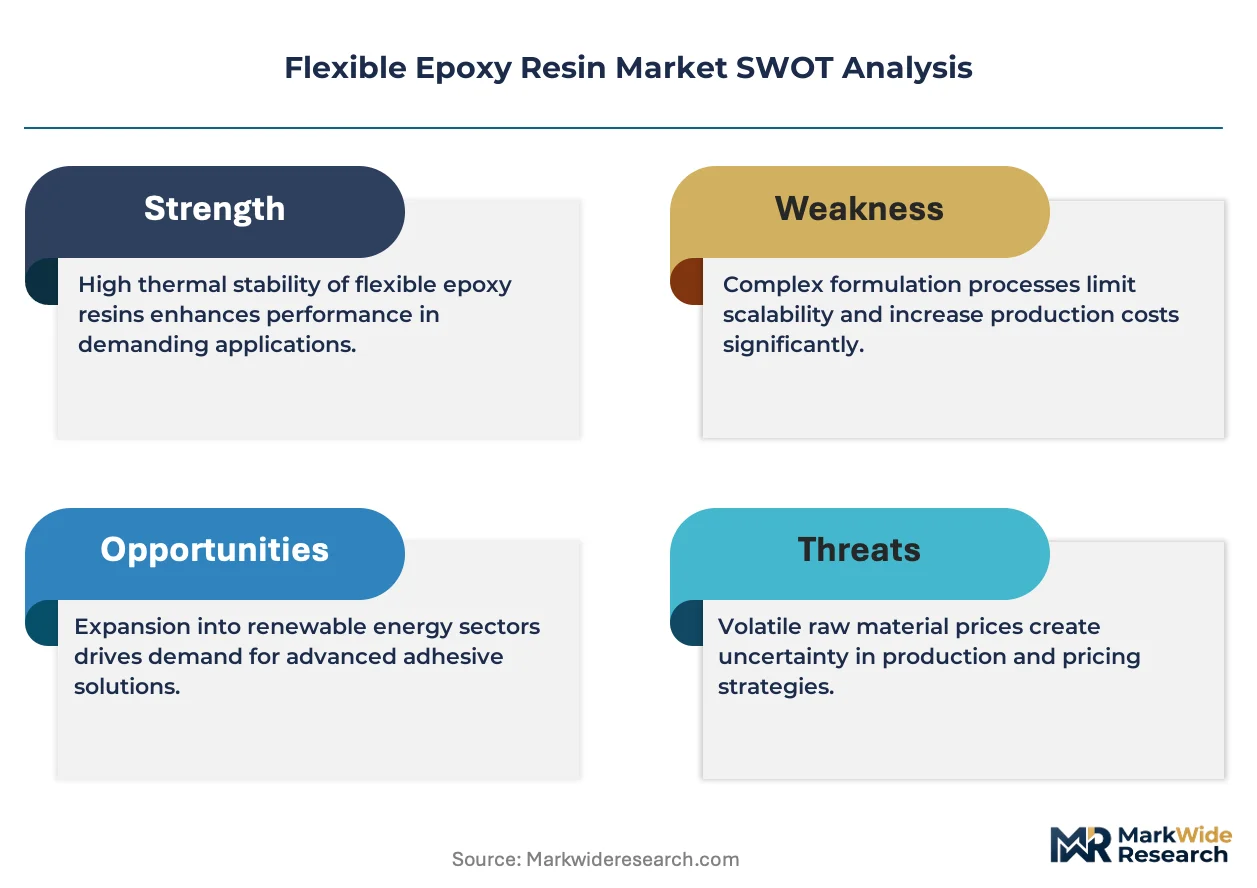
Yangtze River Delta chemical clusters near Shanghai anchor global epichlorohydrin capacity, granting Chinese resin producers pricing leverage over European coating formulators who must absorb elevated feedstock costs or reformulate around supply bottlenecks. This geographic asymmetry compresses margins for buyers lacking backward integration while rewarding producers with captive chlor-alkali infrastructure.
Pricing Analysis
Configured-to-order pricing for CTBN rubber-toughened grades commands substantial premiums over standard bisphenol-A flexible epoxy formulations. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification grade and volume scale, with automotive OEMs least price-sensitive due to qualification lock-in. Cost compression in commodity water-based tiers is intensifying because Chinese capacity expansion outpaces demand growth in regulated European markets. Decorative coating buyers exhibit highest price sensitivity, driving substitution toward acrylic urethanes.
Supply Chain Analysis
Extended payment terms from Yangtze River Delta producers to Southeast Asian distributors are reshaping working capital requirements across the value chain. Supply concentrates in China, Belgium, and the United States, with epichlorohydrin, bisphenol-A, and aliphatic amines as critical inputs. Single-source vulnerability in Belgian and Dutch curing agent production creates disruption risk for European formulators. Distribution runs through direct technical service relationships with tier-one automotive OEMs, bypassing traditional specialty chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible epoxy resin markets face high-growth disruption as electric vehicle thermal management requirements and wind blade dimension expansion force rapid formulation iteration cycles. ECHA REACH Phase-In Substances requirements represent the decisive regulatory inflection accelerating water-based system adoption.
For Market Incumbents: Entrench position through captive epichlorohydrin supply and embedded application engineering with Stuttgart and Detroit OEMs. Accelerate water-based capacity in Jiangsu province to preempt MEE GB standard enforcement. Defend against acrylic urethane substitution by qualifying hybrid UV-thermal systems under SAE protocols.
For New Entrants and Emerging Players: Indian electronics manufacturing clusters under PLI scheme incentives represent the most penetrable entry point for conformal coating-grade formulations. Two-component cartridge systems for infrastructure concrete repair offer direct contractor channel access bypassing established distributor networks. Pursue formulation partnerships with epoxidized vegetable oil suppliers to capture EU Green Deal biobased procurement preferences.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid-technology specialists combining epoxy with polyurethane or acrylate chemistries over pure-play commodity producers. Five-to-ten year viability rests on qualification speed with electric vehicle platform engineering teams. Monitor ECHA substance restriction announcements as early signals of reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali | Hexion and Olin Corporation secure captive epichlorohydrin feedstock cost control across North American manufacturing corridors. |
| Water-Based Formulation Expansion | European coating manufacturers in Stuttgart and Milan convert legacy solvent lines to meet ECHA registration thresholds. |
| Direct Technical Service Embedding | Huntsman application engineers co-locate with Detroit and Stuttgart OEM teams during adhesive specification phases. |
| Biobased Feedstock Partnerships | Scandinavian formulators qualify epoxidized linseed and soybean oils for marine and flooring specifications. |
| Two-Part System Cartridge Development | Marine repair contractors in Rotterdam and Singapore specify adjustable working time systems for underwater cure capability. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with resin plant managers, procurement leads at automotive OEMs, distribution channel partners, and technical R&D directors specializing in rubber-toughening chemistry. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA National Emission Standards documentation. Bottom-up volume modeling and top-down value triangulation reconciled segmentation outputs across product type, end-use industry, formulation chemistry, and application function.
Calibration against historical capacity utilization and feedstock cost trajectories anchored projections across the analysis window. Segmentation dimensions modeled include water-based versus solvent-based versus hot melt versus two-part systems, automotive versus construction versus aerospace versus marine end-uses, and adhesives versus composites versus coatings versus sealants applications. CAGRs derived from elasticity-adjusted demand curves incorporating electric vehicle production ramp schedules and wind turbine blade dimension expansion rates.
Practitioners should monitor epichlorohydrin feedstock volatility and ECHA substance restriction announcements for early signals of margin compression or reformulation cycles. Forecasts reflect assumptions about regulatory enforcement timelines and technology substitution elasticities. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Methacrylate Monomers Market
Polymers & Resins
Redispersible Polymer Powder Market
Polymers & Resins
Synthetic Polymer Waxes Market
Polymers & Resins
Global Acrylic Polymer Market
Polymers & Resins
Silicon Anode Binder Polymers for Lithium-Ion Batteries Market
Polymers & Resins
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market
Polymers & Resins
Circular Polymers Market
Polymers & Resins
Polyethylene Furanoate (PEF) Barrier Resin Market
Polymers & Resins
Ionomer Resins Market
Polymers & Resins
Europe Polyacrylamide Market
Polymers & Resins
Scleroglucan Market
Polymers & Resins
Polyacrylamide Market
Polymers & Resins
India Polymer Emulsion Market
Polymers & Resins
Europe Polyols Market
Polymers & Resins
Thermoplastic Polyimide Market
Polymers & Resins
PEKK Market