
 Intake Filter Media Market | 2026-2036
Intake Filter Media Market Size, Share, and Industry Trends Forecast 2026-2036
Intake Filter Media Market Intelligence
The EU Green Deal is rebalancing procurement criteria toward lower-emission, higher-efficiency intake media across European automotive supply chains. Mann+Hummel leverages its vertical integration from meltblown production to finished modules to sustain margin control in synthetic media. Donaldson Company anchors its position in heavy-duty industrial applications where dust-loading requirements exceed standard automotive specifications. Ahlstrom-Munksjö specializes in wet-laid fiberglass composites that serve both engine intake and HVAC filtration end uses.
Intake filter media comprises engineered fibrous or membrane structures designed to capture particulate contaminants while maintaining airflow permeability, typically measured in pressure drop coefficients and filtration efficiency ratings under ISO 5011 or ASHRAE 52.2 protocols. Synthetic media dominates automotive engine applications due to superior moisture resistance and pleatability compared to traditional cellulose paper, while nanofiber surface coatings represent the fastest-growing technology segment as OEMs pursue sub-micron capture without flow penalty. HVAC Systems application demand is expanding fastest among the four tracked segments, driven by commercial building energy retrofits and indoor air quality mandates that prioritize high-efficiency media with extended service intervals.
EPA Tier 3 particulate standards and the EU F-Gas Regulation together compel filter manufacturers to validate efficiency across broader temperature and humidity ranges, tightening the testing protocols that govern OEM qualification. China's MIIT enforces GB standards for engine air cleaner performance that diverge from ISO methods, creating parallel certification burdens for suppliers serving multiple production geographies. Stakeholders must monitor how divergent regional test protocols reshape product development priorities and qualification timelines.
Market Dynamics
Synthetic media is displacing cellulose across automotive intake systems as EPA Tier 3 and EU F-Gas Regulation tighten efficiency benchmarks, forcing suppliers to requalify materials across broader temperature and humidity ranges.
Growth Catalysts
- EPA Tier 3 particulate standards:The regulation mandates sub-micron capture efficiency that cellulose cannot achieve, accelerating synthetic media qualification in US engine production.
- Commercial HVAC energy retrofits:Building owners in Germany and China are specifying high-efficiency media with extended service intervals to reduce maintenance downtime.
- Nanofiber surface coating technology:This process layer enables sub-micron particulate retention without airflow penalty, penetrating premium automotive segments first.
Market Restraints
- Petrochemical input volatility:Synthetic media depends on polypropylene and polyester feedstocks whose pricing fluctuates with crude oil indices, compressing margin predictability.
- Meltblown capacity concentration:Germany and China host the majority of specialized meltblown production equipment, creating geographic supply risk for qualified media.
- GB standard divergence:China's MIIT enforces engine air cleaner test protocols that differ from ISO 5011, forcing parallel certification investments for multinational suppliers.
Strategic Opportunities
- India automotive production expansion:The country's engine and HVAC manufacturing clusters lack localized filter media supply, creating first-mover advantage for qualified entrants.
- Electrified vehicle thermal management:Battery pack cooling systems require specialized low-pressure-drop media that incumbent suppliers have not optimized.
- EU Green Deal procurement criteria:Public and fleet purchasing is reweighting toward lower-lifecycle-emission media, favoring suppliers with verified carbon footprints.
Industry Challenges
- OEM qualification timeline compression:Accelerated vehicle development cycles are compressing filter validation from 18 months to 12 months without reducing test rigor.
- Cross-functional talent scarcity:Suppliers struggle to hire engineers fluent in both polymer science and ASHRAE 52.2 airflow dynamics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intake Filter Media Market |
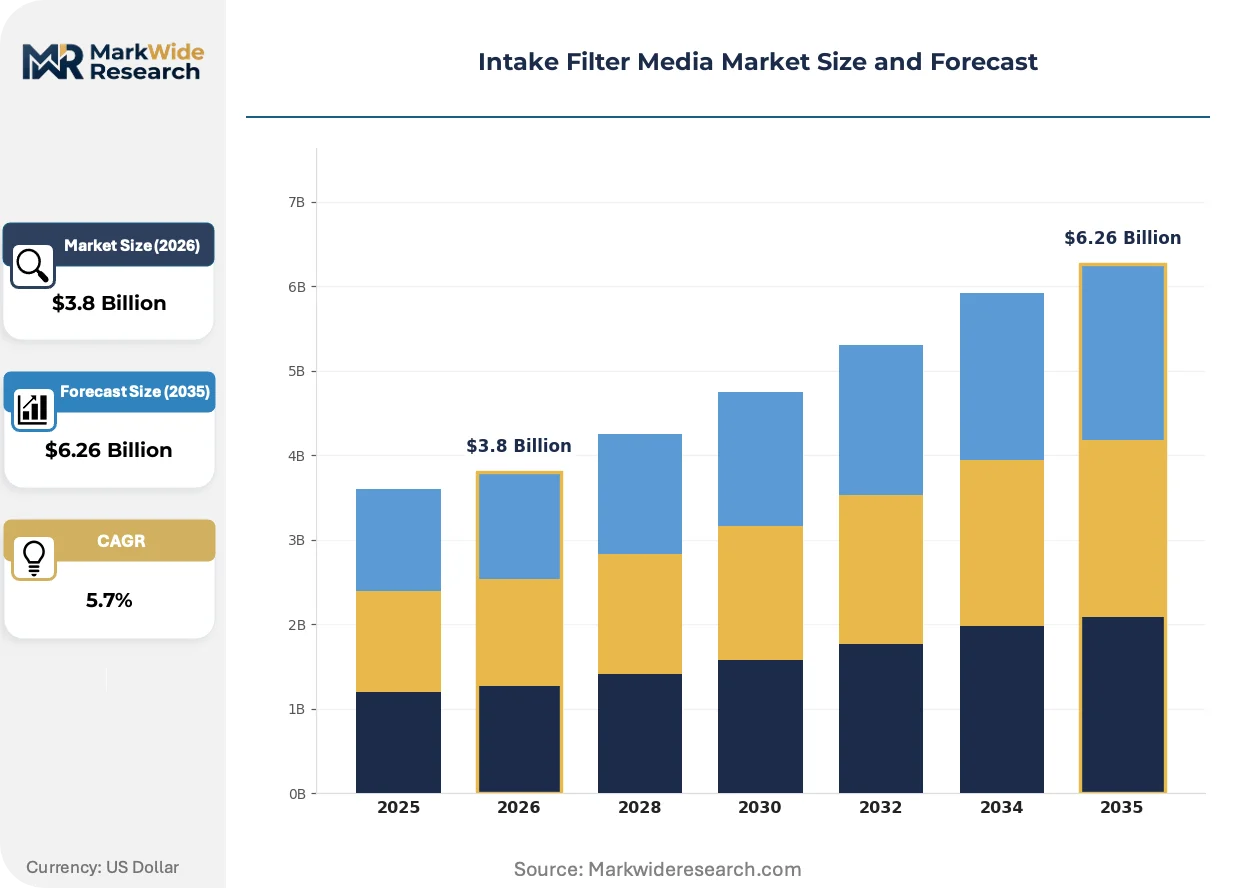
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Fiberglass, Paper, Metal Application: Automotive Engines, HVAC Systems, Industrial Equipment, Residential Air Purifiers Technology: Electrostatic, Activated Carbon, HEPA, Nanofiber End User: Manufacturers, Contractors, Homeowners, Distributors |
| Companies Covered | Mann+Hummel, Filtration Group, Donaldson Company, Inc., Sogefi Group, Camfil, Parker Hannifin Corporation, 3M Company, K&N Engineering, Inc., Ahlstrom-Munksjö, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intake Filter Media Market Strategic Shifts & Innovations
Filter media is evolving from passive barrier to active performance component as OEMs integrate filtration into thermal and energy management systems, requiring materials that communicate condition and adapt to operating environment.
Multilayer composite media is unifying nanofiber surface layers with spunbond structural substrates into single pleatable sheets. Tier 1 module suppliers in Germany and the United States are specifying these composites for next-generation engine air cleaners. This unification is compressing the supplier base by disqualifying single-layer specialists from premium platform bids.
REACH chemical restriction expansions are forcing reformulation of binders and additives used in wet-laid fiberglass production. The regulation's Substances of Very High Concern list now captures several legacy resin systems common in HVAC media. European manufacturers are responding by accelerating bio-based binder development programs to maintain CE marking compliance.
Fleet operators are consolidating filter procurement through integrated maintenance contracts that bundle media supply with installation and monitoring services. This disintermediates traditional aftermarket distributors in the United States and Germany. The shift is most visible in commercial vehicle segments where total cost of ownership modeling dominates supplier selection.
Intake Filter Media Market Segmentation
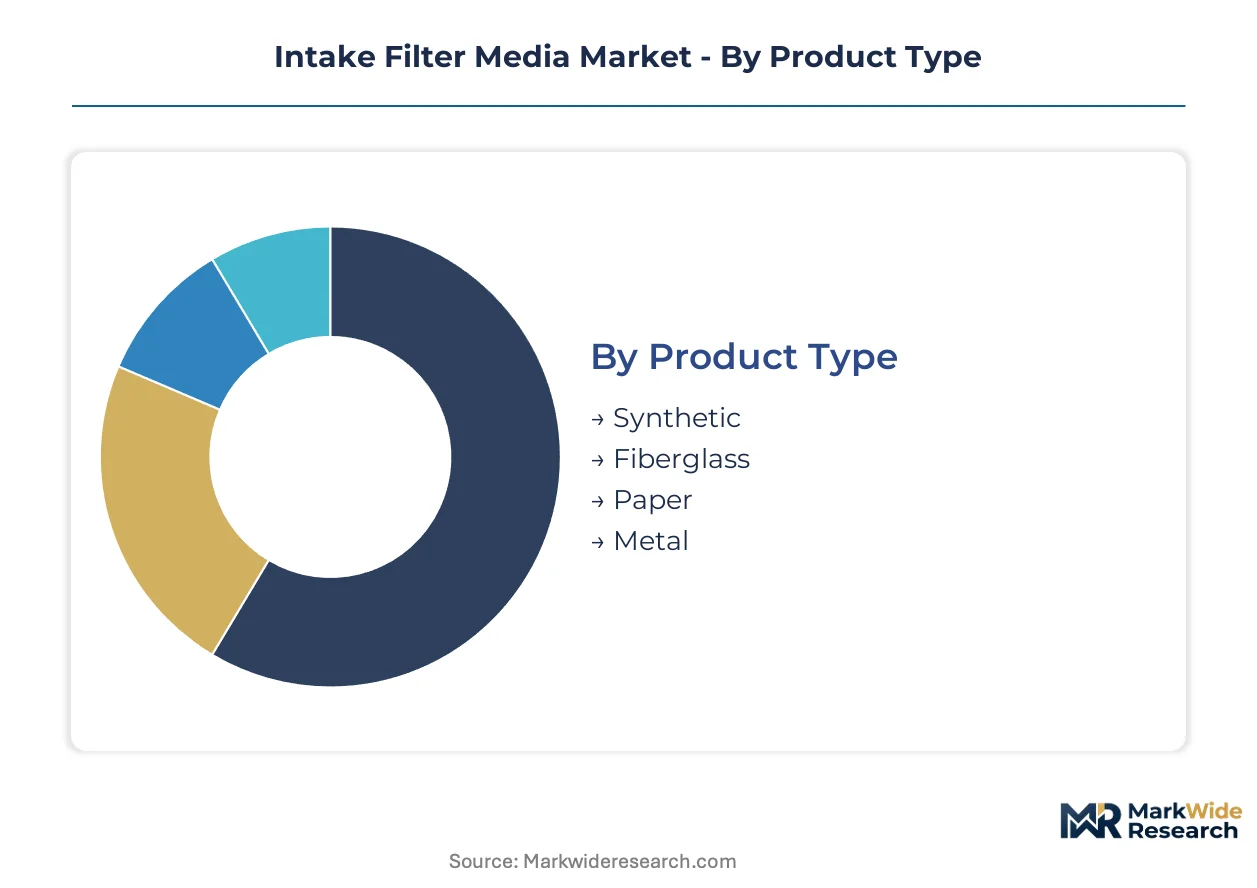
Segmentation in intake filter media determines which certification pathways suppliers must navigate. EPA Tier 3, EU F-Gas Regulation, and China's GB standards each map to distinct product-performance combinations, fragmenting qualification requirements across the supplier base.
Product Type:
Synthetic media carries the heaviest certification burden, requiring validation under EPA Tier 3 particulate standards and EU F-Gas humidity-cycle testing. Cellulose paper faces lighter ISO 5011 protocols but cannot access premium automotive platforms.
- Synthetic:Polypropylene and polyester meltblown structures dominate automotive engine applications due to moisture resistance and pleatability. Mann+Hummel and Donaldson specify synthetic media for US and German OEM platforms where sub-micron capture is mandatory. EPA Tier 3 compliance forces synthetic adoption in light-duty vehicle production.
- Fiberglass:Wet-laid composites from Ahlstrom-Munksjö serve dual engine intake and HVAC filtration end uses. The material withstands broader temperature ranges than cellulose, qualifying it for commercial building energy retrofits in Germany where extended service intervals reduce maintenance downtime.
- Paper:Traditional cellulose media retains cost-sensitive aftermarket share but cannot achieve Tier 3 efficiency benchmarks.
- Metal:Stainless steel mesh structures serve heavy-duty industrial applications with extreme dust-loading requirements.
Synthetic sits at the top of the volume ranking, with fiberglass climbing the fastest as HVAC energy retrofits expand across Germany and China.
Application:
Cost tier separation runs deepest in this dimension, with automotive OEM specifications commanding premium pricing against commoditized residential replacement cycles.
- Automotive Engines:Engine air cleaner modules integrate multilayer composites with nanofiber surface coatings for sub-micron retention without airflow penalty. OEM qualification timelines have compressed from eighteen months to twelve, tightening the supplier base to vertically integrated specialists.
- HVAC Systems:Commercial building retrofits in Germany and China specify high-efficiency media with ASHRAE 52.2 validation. The segment demands extended service intervals that reduce facility maintenance downtime.
- Industrial Equipment:Heavy-duty dust-loading applications exceed standard automotive specifications, anchoring Donaldson's market position.
- Residential Air Purifiers:Price-sensitive replacement cycles concentrate demand in big-box retail channels with minimal certification requirements.
Automotive Engines commands the largest revenue pool, while HVAC Systems gains share fastest on building energy mandates.
Technology:
Technology selection determines margin structure, with surface-modified layers capturing premium positioning against commodity depth-loading media.
- Nanofiber:Surface coating technology enables sub-micron particulate retention without pressure drop penalty. Tier 1 module suppliers in Germany and the United States specify nanofiber composites for next-generation engine air cleaners, compressing the supplier base by disqualifying single-layer specialists.
- HEPA:High-efficiency particulate air ratings govern HVAC and residential applications where ASHRAE 52.2 protocols validate performance across humidity ranges.
- Electrostatic:Charge-enhanced media improves initial efficiency but degrades under moisture exposure, limiting automotive adoption.
- Activated Carbon:Adsorptive layers address odor and VOC capture in cabin air and residential purifier segments.
HEPA holds the broadest installed base, with nanofiber expanding most quickly as OEMs pursue sub-micron capture without flow penalty.
End User:
Customer type dictates procurement pattern, with integrated maintenance contracts disintermediating traditional distributors in fleet and commercial segments.
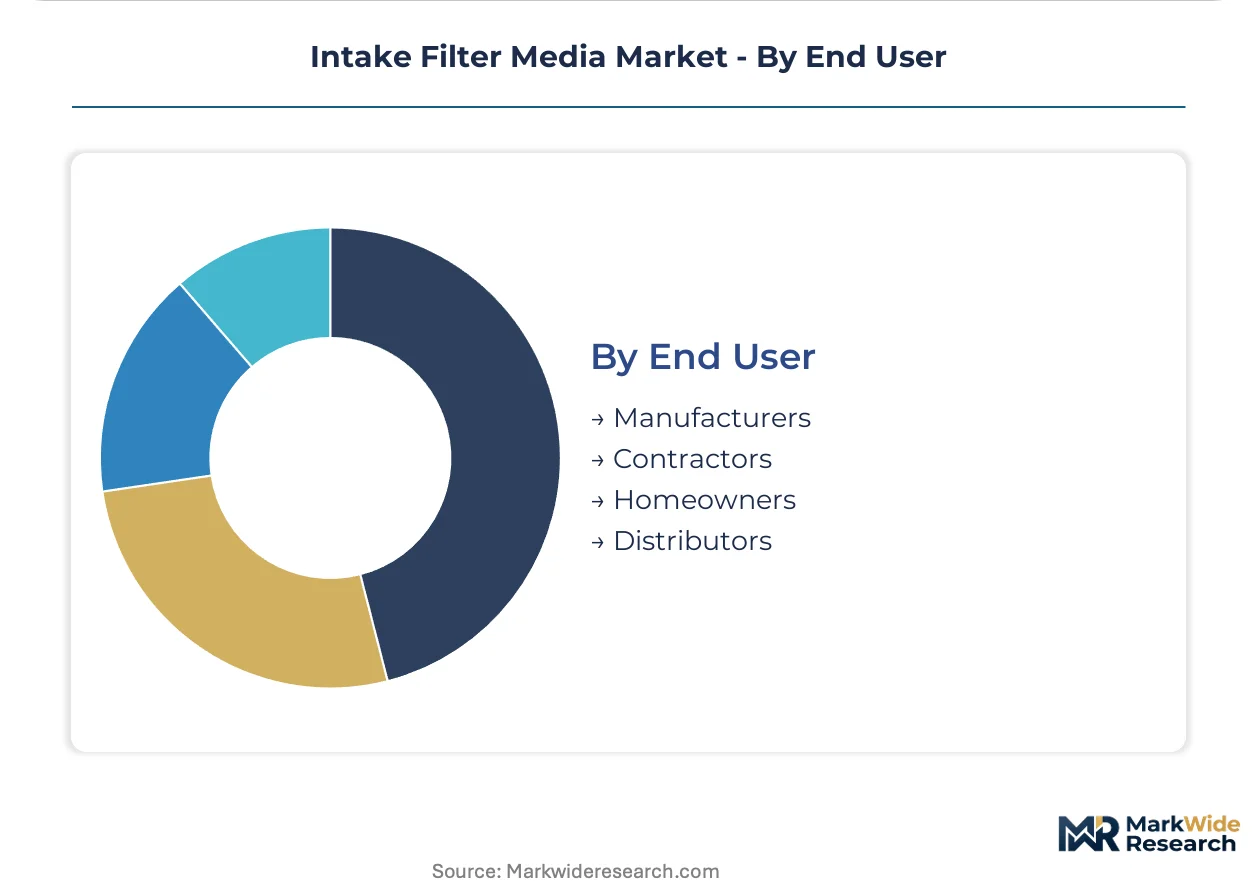
- Manufacturers:Tier 1 module suppliers and OEMs specify media through eighteen-month qualification cycles with ISO 5011 or ASHRAE 52.2 validation requirements.
- Contractors:Commercial HVAC installation and maintenance firms bundle media supply with service contracts, consolidating procurement in Germany and the United States.
- Distributors:Traditional aftermarket channels face margin compression as fleet operators shift to integrated maintenance contracts.
- Homeowners:Price-driven replacement purchases concentrate in retail channels with minimal technical specification requirements.
Manufacturers represent the highest-value customer tier, with Contractors gaining procurement influence fastest through bundled service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer engineers and filtration scientists concentrate in Stuttgart, Shanghai, and Detroit, anchoring the industry's R&D footprint across three continents. Their expertise drives synthetic media qualification cycles that now span twelve months instead of eighteen. Regional regulatory divergence is fragmenting certification requirements.
United States
EPA Tier 3 particulate standards mandate sub-micron capture efficiency that cellulose media cannot achieve, forcing synthetic adoption across light-duty vehicle production. The regulation's humidity-cycle testing protocols compel suppliers to validate materials across broader temperature ranges. Detroit's engine manufacturing cluster is deepening supply localization as OEMs compress qualification timelines.
Germany
EU F-Gas Regulation and the EU Green Deal are rebalancing procurement criteria toward lower-emission, higher-efficiency intake media across automotive supply chains. REACH chemical restrictions are forcing reformulation of binders in wet-laid fiberglass production. Stuttgart's Tier 1 module suppliers specify multilayer nanofiber composites for next-generation engine air cleaners.
China
MIIT enforces GB standards for engine air cleaner performance that diverge from ISO 5011 methods, creating parallel certification burdens for multinational suppliers. The country's dual carbon goals are accelerating HVAC energy retrofit mandates in commercial buildings. Shanghai's meltblown production equipment hosts the majority of qualified synthetic media capacity serving domestic OEMs.
India
Engine and HVAC manufacturing clusters lack localized filter media supply, creating first-mover advantage for qualified entrants under the PLI scheme. BIS certification requirements for automotive components are tightening as domestic production scales. Tamil Nadu's automotive corridor is attracting Tier 1 module suppliers seeking to bypass import dependency.
Japan
METI efficiency standards for commercial building HVAC systems prioritize high-efficiency media with extended service intervals. JIS protocols for filtration performance diverge subtly from ASHRAE 52.2, requiring dedicated test rig investments. Nagoya's industrial equipment manufacturers anchor demand for heavy-duty dust-loading specifications.
Intake Filter Media Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the intake filter media value chain. Meltblown manufacturing equipment and nanofiber coating lines require substantial fixed investment, while specialized compounders and design houses operate with minimal physical assets. Three archetypes dominate: vertically integrated module suppliers controlling raw material through finished product, standalone media specialists serving multiple Tier 1 customers, and diversified industrial conglomerates leveraging cross-divisional polymer science capabilities. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing captive resin supply or co-developing next-generation pleating technologies.
Among vertically integrated specialists, Mann+Hummel and Donaldson Company occupy positions exemplifying divergent strategic emphases. Mann+Hummel represents the archetype of backward integration from meltblown production through finished modules, while Donaldson anchors heavy-duty industrial applications where dust-loading requirements exceed standard automotive specifications. Ahlstrom-Munksjö sits within the standalone media specialist tier, serving dual engine intake and HVAC filtration end uses through wet-laid fiberglass composites.
| Leading Market Players |
|---|
| Mann+Hummel |
| Filtration Group |
| Donaldson Company, Inc. |
| Sogefi Group |
| Camfil |
| Parker Hannifin Corporation |
| 3M Company |
| K&N Engineering, Inc. |
| Ahlstrom-Munksjö |
| Others |
Cost & Logistics Intelligence
Nanofiber coating technology adoption simultaneously compresses production costs for sub-micron filtration and concentrates supply leverage among equipment owners in Germany and China. Meltblown production lines require substantial capital deployment, creating asymmetric pricing power for incumbents with installed capacity as qualification timelines tighten under EPA Tier 3 and EU F-Gas protocols.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates OEM-validated synthetic media from aftermarket cellulose and unbranded imports. Price differentiation rests on ISO 5011 certification grade and volume commitment scale, with automotive Tier 1 contracts commanding substantial premiums over HVAC replacement cycles. Cost compression in the economy tier is intensifying because Chinese producers are expanding meltblown capacity for domestic OEM qualification. Fleet operators bundling maintenance services exhibit the lowest price sensitivity, while residential purifier buyers concentrate demand in retail channels with minimal technical specification requirements.
Supply Chain Analysis
Freight cost volatility from Red Sea disruptions and transpacific rate spikes is forcing inventory repositioning among European filter module suppliers. Geographic supply concentration centers on Germany, China, and the United States for qualified meltblown and nanofiber coating equipment. Raw material flows draw from polypropylene resin producers in the US Gulf Coast and polyester feedstock suppliers in South Korea. Single-source vulnerability runs through specialized nanofiber electrospinning equipment manufacturers in Germany. Distribution runs through Tier 1 module suppliers with backward integration into media production, disintermediating standalone distributors in premium automotive segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through nanofiber technology premiums and synthetic media substitution economics, with cost-down drivers accelerating as meltblown equipment utilization rates improve across installed bases.
For Market Incumbents: Anchor defensive positioning through captive meltblown capacity additions in China and Germany to forestall qualification bottlenecks. Secure resin supply agreements with polypropylene producers to offset petrochemical input volatility. Prioritize backward integration into nanofiber coating equipment to maintain OEM platform access as qualification timelines compress. For New Entrants and Emerging Players: E-commerce direct procurement channels targeting Indian automotive Tier 2 suppliers offer the most penetrable entry vector. Focus white-space capture on battery pack cooling media for electrified vehicle thermal management, where incumbent optimization lags. Pursue PLI scheme qualification in Tamil Nadu to bypass import dependency and establish local production credentials. For Investors and Strategic Acquirers: Valuations sit cheapest among standalone wet-laid fiberglass specialists lacking nanofiber coating capabilities. Long-term viability favors assets with verified EU Green Deal carbon footprints and REACH-compliant binder formulations. Watch for MIIT harmonization of GB standards with ISO 5011 as the signal for accelerated multinational supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Meltblown Production | Mann+Hummel's captive resin-to-module control sustains margin predictability against petrochemical volatility. |
| Nanofiber Coating Capacity Expansion | Equipment investments in Stuttgart and Detroit compress supplier bases by disqualifying single-layer specialists from OEM bids. |
| India Manufacturing Footprint Establishment | Tamil Nadu corridor localization under PLI schemes captures first-mover advantage in undersupplied engine clusters. |
| EU Green Deal Carbon Footprint Verification | Verified lifecycle emissions documentation unlocks public procurement reweighting toward lower-emission media suppliers. |
| Integrated Maintenance Contract Bundling | Fleet operator service consolidation in Germany and the United States disintermediates traditional aftermarket distributors. |
Research Approach
Coverage spans the United States, Germany, China, India, and Japan, with primary inputs from each market's stakeholder base. The approach combines interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distribution heads, and filtration R&D directors with secondary validation from EPA Tier 3 regulatory filings, MIIT GB standard documentation, EU F-Gas Regulation impact assessments, and vehicle production databases. Bottom-up segment sizing and top-down macro anchoring were triangulated to ensure consistency across synthetic media, fiberglass, and cellulose product categories.
Rate-of-change decomposition across the projection horizon isolates volume drivers from price-mix effects in synthetic media substitution trends. Segmentation dimensions modeled include product type, application, technology, and end user, with additional granularity on certification pathway requirements across EPA, EU, and MIIT regulatory clusters. CAGRs were derived from trend extrapolation of meltblown capacity utilization, nanofiber coating penetration curves, and HVAC retrofit mandate implementation schedules in commercial building segments.
The model assumes a particular technology adoption path; alternative pathways for electrospun nanofiber surface layers would alter the outlook if spray-coating methods achieve comparable sub-micron capture efficiency at lower capital intensity. Forecasts reflect assumptions regarding regulatory harmonization timelines, resin price correlation with crude indices, and OEM platform consolidation patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Global Baghouse Filters Market
Filters
Polishing Filter Market
Filters
Global Filtration and Contamination Control Market
Filters
Coolant Filtration Systems Market
Filters
ePTFE Filter Film Market
Filters
Filtration and Separation Market
Filters
Global Industrial Filters Market
Filters
Filter Coatings Market
Filters
Fiberglass Filters Market
Filters
Global Filter Market
Filters
Sintered Metal Filters Market
Filters
Anti-Microbial Filter Market
Filters
Color Filter Glass Market
Filters
Europe Industrial Air Filtration Market
Filters
High-Efficiency Particulate Air (HEPA) Filters Market
Filters
Residential Filters Market