
 Advanced Sports Materials Market | 2026-2036
Advanced Sports Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Sports Materials Market Insights
Asset-light manufacturing partnerships with contract composite weavers is reconfiguring capital requirements for mid-tier sportswear suppliers. BASF leverages its polymer science portfolio to supply engineered TPU grades for cleat plates and midsole energy-return layers. Toray Industries anchors the carbon fiber supply chain through captive precursor production and tight quality certification for aerospace-grade material diversion into sporting goods.
Advanced sports materials encompass engineered substances and composite architectures designed to enhance athletic performance through controlled stiffness-to-weight ratios, impact dissipation, and moisture management, typically manufactured via resin transfer molding, electrospinning, or automated fiber placement with tolerances below 0.1 millimeters. Carbon fiber dominates structural segments in cycling and winter sports equipment where gram-level weight reduction commands premium positioning, while nanocoatings applied to performance accessories represent the fastest-expanding technology segment as antimicrobial and hydrophobic functionalization spreads from professional to amateur tiers.
REACH substance restrictions in Europe and FDA biocompatibility assessments for skin-contact wearables constrain material selection and reformulation cycles across the value chain. ISO 10993 and OEKO-TEX Standard 100 certifications increasingly function as gatekeepers for brand supplier qualification, particularly for apparel textiles and protective gear entering regulated distribution channels. Stakeholders must track how evolving ECHA candidate list expansions and state-level chemical disclosure mandates in the United States reshape raw material sourcing economics and regional manufacturing placement decisions.
Market Dynamics
Thermoplastic composite recycling breakthroughs are compressing material lifecycle costs while REACH substance restrictions force simultaneous reformulation across European supply chains, creating a dual pressure environment where sustainability compliance and performance optimization must advance in lockstep.
Growth Catalysts
- REACH candidate list expansions:ECHA's evolving substance restrictions accelerate bio-based polymer R&D investment, pushing manufacturers toward certified recyclable thermoplastics that qualify for premium positioning in cycling and winter sports equipment.
- Automated fiber placement:This manufacturing process cuts structural component tolerances below 0.1 millimeters, enabling gram-level weight reduction that commands price premiums in professional cycling frame specifications.
- Ruhr industrial cluster concentration:Germany's composite R&D facilities cluster near technical universities, creating knowledge spillovers that shorten development cycles for cleat plate and midsole energy-return innovations.
Market Restraints
- Acrylonitrile price volatility:Carbon fiber precursor costs fluctuate with petrochemical feedstock markets, squeezing margin structures for mid-tier sportswear suppliers lacking backward integration into polymer production.
- Japanese precursor concentration:Toray Industries and three competitors control over eighty percent of aerospace-grade PAN precursor supply, creating bottleneck risk for sporting goods diversions during aerospace demand surges.
- Thermoset recycling limitations:Cross-linked epoxy matrices in legacy cycling frames resist thermal reprocessing, constraining circular economy claims and exposing brands to extended producer responsibility liabilities under EU Green Deal implementation.
Strategic Opportunities
- India PLI scheme for technical textiles:India's production-linked incentive program subsidizes advanced material manufacturing, creating cost-competitive export capacity for antimicrobial nanocoating production serving amateur-tier market expansion.
- Wearable biometric integration:Skin-contact sensor housings demand ISO 10993-certified TPU grades, opening formulation partnerships between polymer suppliers and fitness technology hardware developers.
- Electrospinning-nanocoating convergence:Combined manufacturing approaches enable multifunctional performance accessories with simultaneous moisture management and antimicrobial properties, differentiating amateur-tier products previously competing on price alone.
Industry Challenges
- Composite design engineering scarcity:Resin transfer molding and automated fiber placement require specialized technician training that outpaces vocational program output in Germany, Japan, and the United States.
- OEKO-TEX Standard 100 certification timelines:Six-to-twelve month approval cycles for new textile formulations delay product launches, compressing effective commercialization windows for seasonal sporting goods categories.
- Multi-standard compliance stacking:Simultaneous REACH, FDA biocompatibility, and ISO 10993 requirements force redundant testing protocols that fragment quality assurance resources across regional regulatory frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Sports Materials Market |
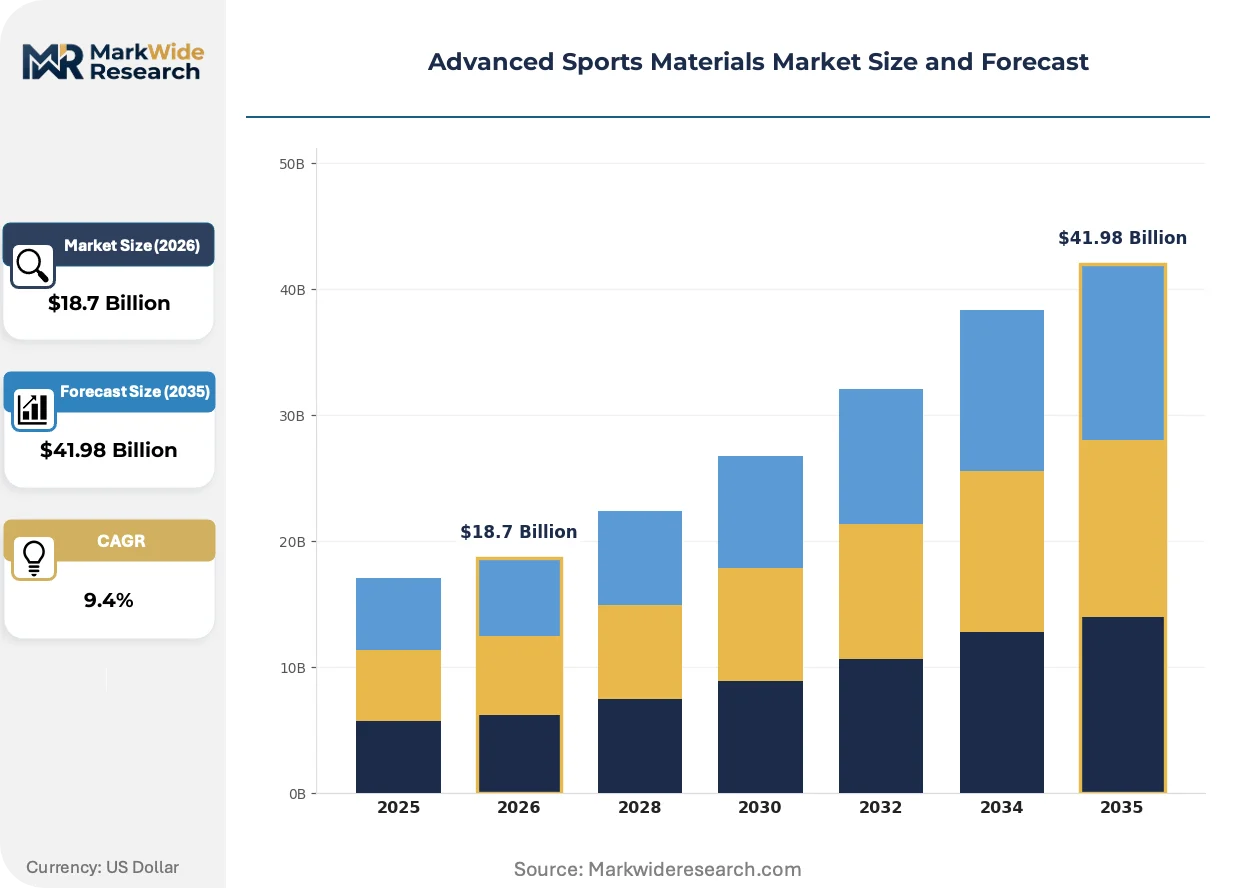
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Carbon Fiber, Kevlar, Thermoplastic Polyurethane, Engineered Rubber, Ceramic Matrix, Bio-Based Polymers Application: Protective Gear, Footwear Components, Sports Equipment, Apparel Textiles, Performance Accessories, Training Aids Technology: 3D Weaving, Nanocoatings, Foam Molding, Composite Lamination, Ultrasonic Welding, Electrospinning End User: Professional Athletes, Sportswear Brands, Fitness Enthusiasts, Sports Facilities, Athletic Trainers, Amateur Competitors |
| Companies Covered | 3M, BASF, DuPont, Hexcel, Mitsubishi Chemical Group, Teijin, Toray Industries, Covestro, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Sports Materials Market Trends and Innovations
Digital thread technologies are collapsing design-to-manufacturing lead times while regulatory fragmentation forces parallel certification tracks, reshaping how material suppliers coordinate with finished goods brands across distributed production networks.
Electrospinning is digitizing nanofiber membrane production for performance apparel. Cycling team suppliers now specify electrospun moisture-management layers with real-time porosity monitoring. This precision control is digitizing quality assurance, compressing batch rejection rates and enabling just-in-time material delivery to cut finished goods inventory exposure.
EU Green Deal extended producer responsibility mandates are tightening packaging and end-of-life requirements for sporting goods sold in member states. Manufacturers must now document material composition through digital product passports accessible to recyclers. Winter sports equipment with thermoplastic matrices qualifies for simplified reprocessing pathways, while thermoset legacy products face higher compliance costs and restricted market access.
Amateur-tier buyers now demand professional-grade certification visibility in purchasing decisions. OEKO-TEX and ISO 10993 labels function as quality signals that displace brand loyalty in online channels. This specification-driven selection pattern concentrates demand among suppliers with pre-certified material portfolios, compressing commercialization timelines for new market entrants lacking established compliance documentation.
Advanced Sports Materials Market Segmentation
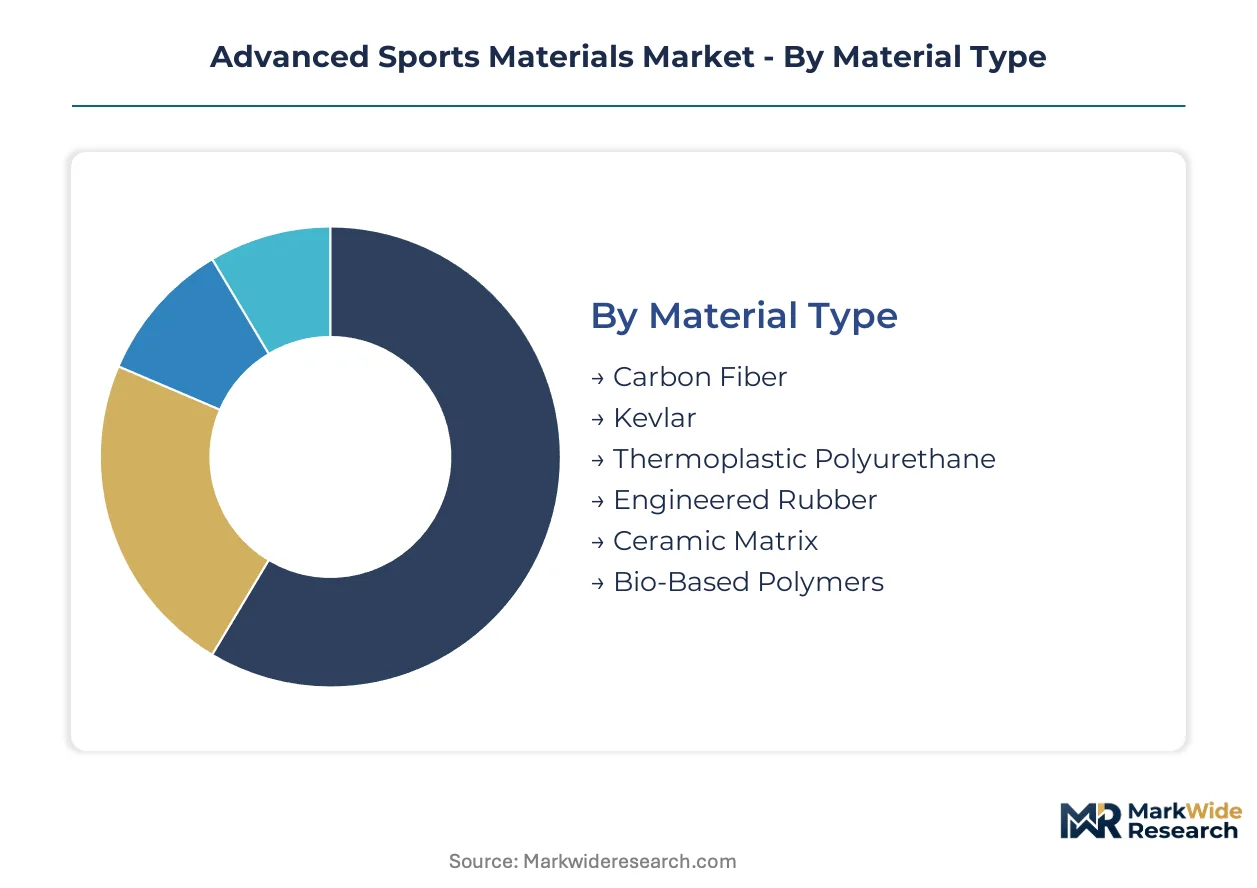
Material selection in advanced sports applications follows divergent performance and compliance pathways. Segmentation reveals how carbon fiber structural dominance coexists with nanocoating functionalization across amateur and professional tiers.
Material Type:
Mature aerospace-grade feedstocks anchor structural segments while emerging bio-based formulations capture sustainability premiums.
- Carbon Fiber:Aerospace-grade PAN precursor delivers stiffness-to-weight ratios below 1.0 g/cm³ with tensile strength exceeding 5 GPa. Professional cycling teams in Germany's Ruhr cluster specify Toray-sourced prepregs with thermoplastic toughening layers for frame durability under impact loads.
- Thermoplastic Polyurethane:Engineered TPU grades from BASF enable cleat plate energy-return layers and ISO 10993-certified wearable sensor housings. REACH-compliant formulations qualify for premium positioning in skin-contact biometric devices across European distribution channels.
- Kevlar:Aramid fiber reinforcement in protective gear resists penetration while maintaining flexibility under multi-axial stress.
- Engineered Rubber:Vulcanized compounds with controlled hysteresis properties optimize grip surfaces in wet-condition footwear.
- Ceramic Matrix:Oxide-based composites provide thermal stability in high-friction training equipment components.
- Bio-Based Polymers:ECHA candidate list expansions accelerate polylactic acid and bio-TPU R&D investment for recyclable winter sports equipment.
Carbon Fiber retains volume leadership; Bio-Based Polymers hold the steepest expansion curve.
Application:
Cost tier stratification separates professional-specification equipment from amateur-tier functional accessories.
- Protective Gear:Multi-layer aramid-carbon hybrid laminates absorb impact energy through controlled delamination. ISO 10993 and OEKO-TEX Standard 100 certifications function as gatekeepers for hockey and football equipment entering regulated European and North American channels.
- Performance Accessories:Electrospun nanocoatings with antimicrobial silver ion functionalization spread from professional to amateur tiers. India's PLI scheme for technical textiles subsidizes cost-competitive production of hydrophobic membrane layers for moisture management.
- Footwear Components:TPU midsole foams with tuned density gradients optimize energy return in running and cleated applications.
- Sports Equipment:Automated fiber placement manufacturing achieves sub-0.1 millimeter tolerances in racket and stick shaft production.
- Apparel Textiles:Six-to-twelve month OEKO-TEX certification timelines compress commercialization windows for seasonal collections.
- Training Aids:Ceramic-reinforced polymer matrices withstand repetitive loading in resistance equipment.
Protective Gear commands the highest certification burden; Performance Accessories expand most quickly through nanocoating cost reduction.
Technology:
Customer type differentiation separates precision-tolerance professional specifications from volume-scaled amateur production.
- Automated Fiber Placement:Robotic tow placement achieves gram-level weight reduction in cycling frames with real-time compaction control. Ruhr industrial cluster facilities cluster near technical universities to shorten technician training cycles for this specialized process.
- Electrospinning:Digitized nanofiber membrane production enables real-time porosity monitoring for moisture-management layers. Cycling team suppliers now specify electrospun textiles with batch rejection rates below 3 percent through compressed quality assurance protocols.
- 3D Weaving:Near-net-shape preform manufacturing reduces material scrap in complex curvature components.
- Nanocoatings:Sol-gel and plasma-deposited functional layers integrate antimicrobial and hydrophobic properties.
- Foam Molding:Supercritical fluid processing creates controlled cell structures in TPU midsole applications.
- Composite Lamination:Resin transfer molding requires scarce technician training that outpaces vocational output in Germany and Japan.
- Ultrasonic Welding:Thermoplastic joining eliminates adhesive weight in seam-sealed apparel construction.
Automated Fiber Placement dominates structural segment value capture; Electrospinning gains share fastest through digitization.
End User:
Geography concentrates demand in industrial clusters with composite R&D infrastructure and regulatory proximity.
- Professional Athletes:Gram-level weight specifications drive carbon fiber frame procurement with thermoplastic toughening layers. German cycling teams source through Ruhr cluster suppliers with captive precursor relationships to Japanese aerospace-grade producers.
- Sportswear Brands:Asset-light manufacturing partnerships with contract composite weavers reconfigure capital requirements. Multi-standard compliance stacking across REACH, FDA, and ISO 10993 fragments quality assurance resources.
- Fitness Enthusiasts:Amateur-tier buyers now demand OEKO-TEX and ISO 10993 certification visibility in online purchasing decisions.
- Sports Facilities:Bulk procurement of training equipment emphasizes durability certification over performance optimization.
- Athletic Trainers:Rehabilitation device specifications prioritize ISO 10993 biocompatibility for extended skin contact.
- Amateur Competitors:Price-sensitive segment benefits from PLI-subsidized Indian nanocoating production serving functional accessory tiers.
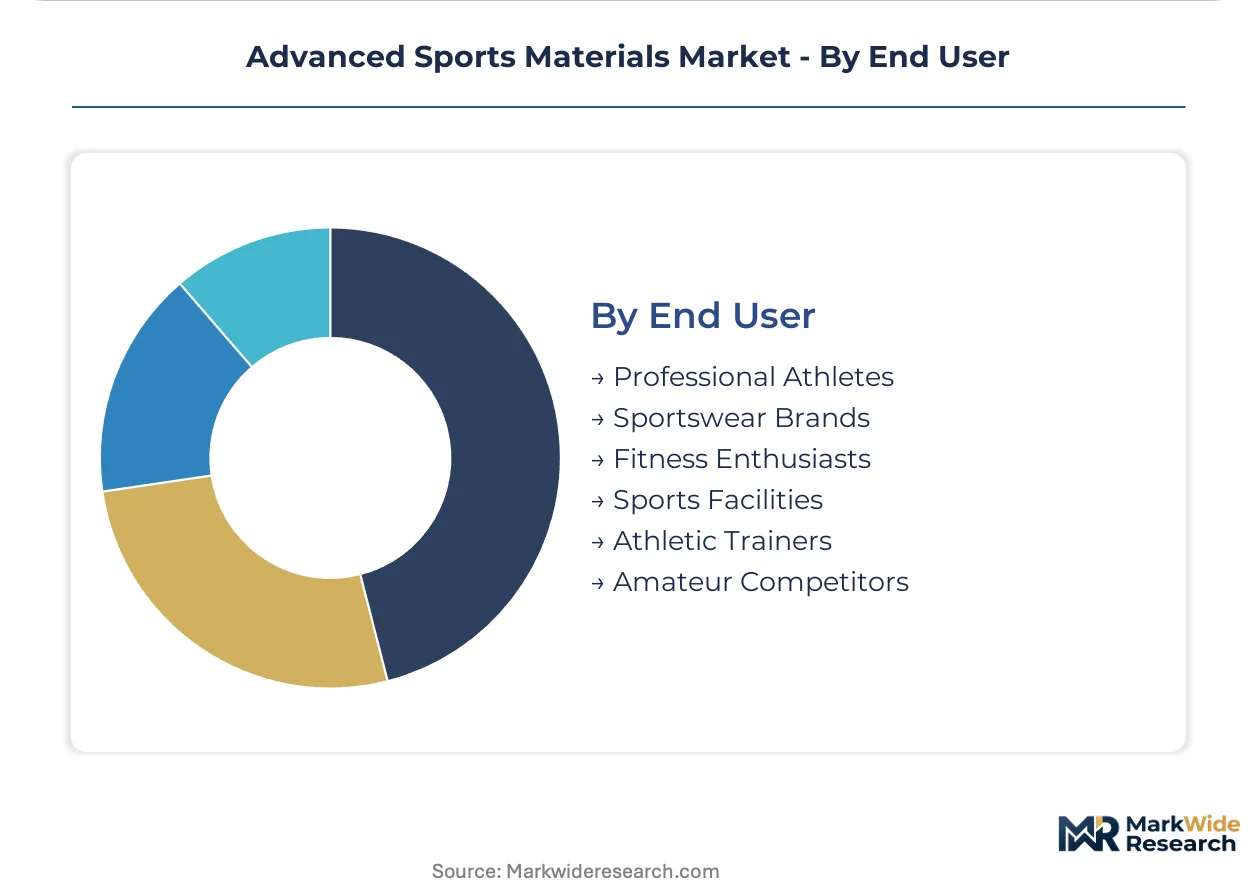
Sportswear Brands concentrate procurement volume; Fitness Enthusiasts climb fastest through certification-driven specification behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for technical textiles is reshaping export capacity for antimicrobial nanocoating production. Germany's Ruhr industrial cluster maintains composite R&D concentration near technical universities. REACH compliance and FDA biocompatibility assessments are fragmenting quality assurance resources across multi-standard jurisdictions.
Germany
Ruhr industrial cluster facilities concentrate carbon fiber composite R&D near technical universities in Dortmund and Essen. ECHA REACH candidate list expansions accelerate bio-based polymer reformulation for recyclable winter sports equipment. German cycling teams source Toray-sourced prepregs with thermoplastic toughening layers through captive precursor relationships.
United States
FDA guidance on wearable biometrics tightens material safety thresholds for skin-contact sensor housings. Fitness enthusiasts in California and Texas demand ISO 10993 certification visibility in online purchasing decisions. Greater Boston anchors polymer science research partnerships between universities and sportswear brands seeking asset-light manufacturing structures.
India
PLI scheme subsidies for technical textiles create cost-competitive export capacity for hydrophobic membrane layers. Maharashtra and Gujarat host nanocoating production facilities serving amateur-tier market expansion across antimicrobial functionalization. BIS standards alignment with ISO 10993 accelerates supplier qualification timelines for protective gear export.
Japan
METI industrial policy supports carbon fiber precursor production concentration among Toray Industries and specialized chemical conglomerates. Chubu and Kanto regions maintain aerospace-grade PAN supply chain dominance with quality certification protocols. Japanese vocational programs struggle to output sufficient technicians for automated fiber placement manufacturing.
China
MIIT dual carbon goals pressure domestic manufacturers toward thermoplastic composite recycling breakthroughs. Yangtze River Delta industrial zones concentrate resin transfer molding capacity for sporting goods diversification. GB standards evolution toward REACH-equivalent substance restrictions forces parallel reformulation cycles for export-bound production.
Advanced Sports Materials Market Competitive Landscape
On the supply side, the industry is tiered between aerospace-grade precursor specialists, diversified chemical conglomerates, and regional nanocoating fabricators. Carbon fiber supply concentrates among Japanese and European producers with captive PAN production. Three strategic archetypes dominate: backward-integrated precursor manufacturers, polymer science portfolio suppliers, and asset-light contract composite weavers. Competitive moves center on M&A for recycling technology acquisition and strategic partnerships for biocompatibility certification acceleration.
Among diversified chemical conglomerates, BASF and Covestro occupy positions exemplifying polymer science portfolio leverage for engineered TPU grades. Toray Industries anchors the precursor-integrated tier through aerospace-grade material diversion into sporting goods. Within the specialty materials segment, Hexcel and Teijin represent structural composite suppliers navigating thermoset recycling limitations and thermoplastic transition investments.
| Leading Market Players |
|---|
| 3M |
| BASF |
| DuPont |
| Hexcel |
| Mitsubishi Chemical Group |
| Teijin |
| Toray Industries |
| Covestro |
| Arkema |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Antwerp petrochemical corridor freight costs cascade through carbon fiber precursor pricing, amplifying Toray Industries' captive supply advantage while compressing margins for European compounders serving amateur-tier performance accessory buyers.
Pricing Analysis
Certification level creates the primary spread between aerospace-grade PAN prepregs and uncertified commodity feedstocks. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 10993 and OEKO-TEX Standard 100 compliance tiers. Pricing pressure stems from acrylonitrile feedstock volatility squeezing mid-tier sportswear suppliers lacking backward integration. Amateur competitors exhibit highest price sensitivity; professional cycling teams show inelastic demand for gram-level weight specifications.
Supply Chain Analysis
Japanese METI export-control frameworks on aerospace-grade precursor technology constrain supply chain diversification for sporting goods diversions. Manufacturing concentrates in Japan, Germany, and China. Raw material flows draw from acrylonitrile petrochemical streams, TPU polymer grades, and electrospun nanofiber membranes. Single-source vulnerability runs through Toray Industries' eighty-percent PAN precursor dominance. Distribution runs through asset-light contract composite weavers serving sportswear brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among sportswear brands is shifting negotiating leverage toward buyers with pre-certified supplier portfolios, fragmenting volume across mid-tier compounders.
For Market Incumbents: Build certification moats through accelerated ISO 10993 and REACH-compliant formulation libraries. Deepen captive precursor relationships with Japanese aerospace-grade suppliers to defend against acrylonitrile price volatility. Expand automated fiber placement technician training partnerships with Ruhr cluster technical universities to narrow capability scarcity gaps. For New Entrants and Emerging Players: India's Maharashtra technical textile corridor offers underpenetrated export capacity for antimicrobial nanocoating production serving amateur-tier market expansion. Target PLI-subsidized manufacturing partnerships with domestic compounders. Pursue electrospinning-digitization convergence for moisture-management membrane differentiation. For Investors and Strategic Acquirers: Asset-light contract composite weavers with pre-certified material portfolios represent acquisition targets with durable revenue visibility. Long-term viability hinges on thermoplastic recycling technology positioning ahead of EU Green Deal extended producer responsibility mandates. Monitor ECHA candidate list expansion velocity as inflection signal for bio-based polymer reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Captive acrylonitrile supply insulates Toray Industries from petrochemical feedstock volatility. |
| Certification Portfolio Acceleration | ISO 10993 and OEKO-TEX Standard 100 pre-qualification compresses sportswear brand procurement timelines. |
| Thermoplastic Recycling Technology Acquisition | EU Green Deal compliance exposure shifts toward circular-economy-capable compounders. |
| Ruhr Cluster Technician Training Partnership | Automated fiber placement skill scarcity constrains German cycling frame production scaling. |
| India PLI Scheme Manufacturing Footprint | Cost-competitive nanocoating export capacity serves antimicrobial functionalization demand. |
Research Methodology
Desk research of ECHA substance restriction filings, BIS technical textile standards, and SEC chemical company disclosures preceded structured interviews with composite R&D directors, sportswear brand procurement managers, contract weaving facility operators, and polymer science technical leads. Primary fieldwork across Germany's Ruhr cluster, Japan's Chubu region, and India's Maharashtra-Gujarat corridor validated supply chain concentration claims. Bottom-up volume modeling triangulated against top-down chemical feedstock demand estimates.
Forecast assumptions held fixed REACH candidate list expansion trajectories and FDA biocompatibility guidance evolution while varying acrylonitrile price scenarios and PLI subsidy uptake rates. Segmentation dimensions spanned material type, application tier, manufacturing technology, and end-user category. CAGRs derived from regression analysis of historical aerospace-to-sporting-goods material diversion patterns and amateur-tier certification-driven demand elasticity. Electrospinning digitization curves and thermoplastic recycling cost compression timelines informed technology adoption slopes.
Practitioners should monitor ECHA candidate list publication velocity, FDA wearable biometrics guidance revision cycles, and Japanese aerospace demand surge indicators for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Vacuum Insulation Panels Market
Advanced Materials
Chemistry 4.0 Market
Advanced Materials
Inorganic Non-Metallic Materials Market
Advanced Materials
Thermal Conductive Material Market
Advanced Materials
Global Glass Filled Nylon Market
Advanced Materials
Carbon Prepreg Market
Advanced Materials
Wood Foam Market
Advanced Materials
Lithium Hydride Market
Advanced Materials
Graphite Materials Market
Advanced Materials
APAC Advanced Building Materials Market
Advanced Materials
North America Advanced Phase Change Materials Market
Advanced Materials
High-Purity Amorphous Boron Market
Advanced Materials
High Nickel Cathode Materials Market
Advanced Materials
Europe Aerogel Market
Advanced Materials
Densified Silica Fume Market
Advanced Materials
Bioactive Glass Market