
 US Graphene Market | 2026-2036
US Graphene Market Size, Share, and Industry Trends Forecast 2026-2036
US Graphene Market Insights
Multi-source procurement for precursor graphite is hardening as domestic buyers reduce reliance on single-origin supply chains. U.S. Graphene Group leverages its Ohio-based production assets to anchor regional fulfillment capacity. NeoGraf Solutions specializes in thermal management grades for defense contractors. Angstron Materials Inc. competes through R&D intensity in few-layer graphene architectures.
Graphene comprises a single atomic layer of sp²-bonded carbon atoms arranged in a hexagonal lattice, with in-plane tensile strength exceeding 130 GPa and electrical conductivity surpassing copper by a factor of roughly 200. Manufacturers synthesize it via chemical vapor deposition onto copper foils or through liquid-phase exfoliation of expanded graphite for industrial-scale output. Graphene nanoplatelets dominate volume shipments due to lower production costs and established compounding compatibility with thermoplastics. Energy storage applications are expanding fastest as silicon-graphene anode formulations gain traction with cell producers. Composite materials retain mature margins in aerospace tier-one supply chains where qualification timelines lock in supplier relationships.
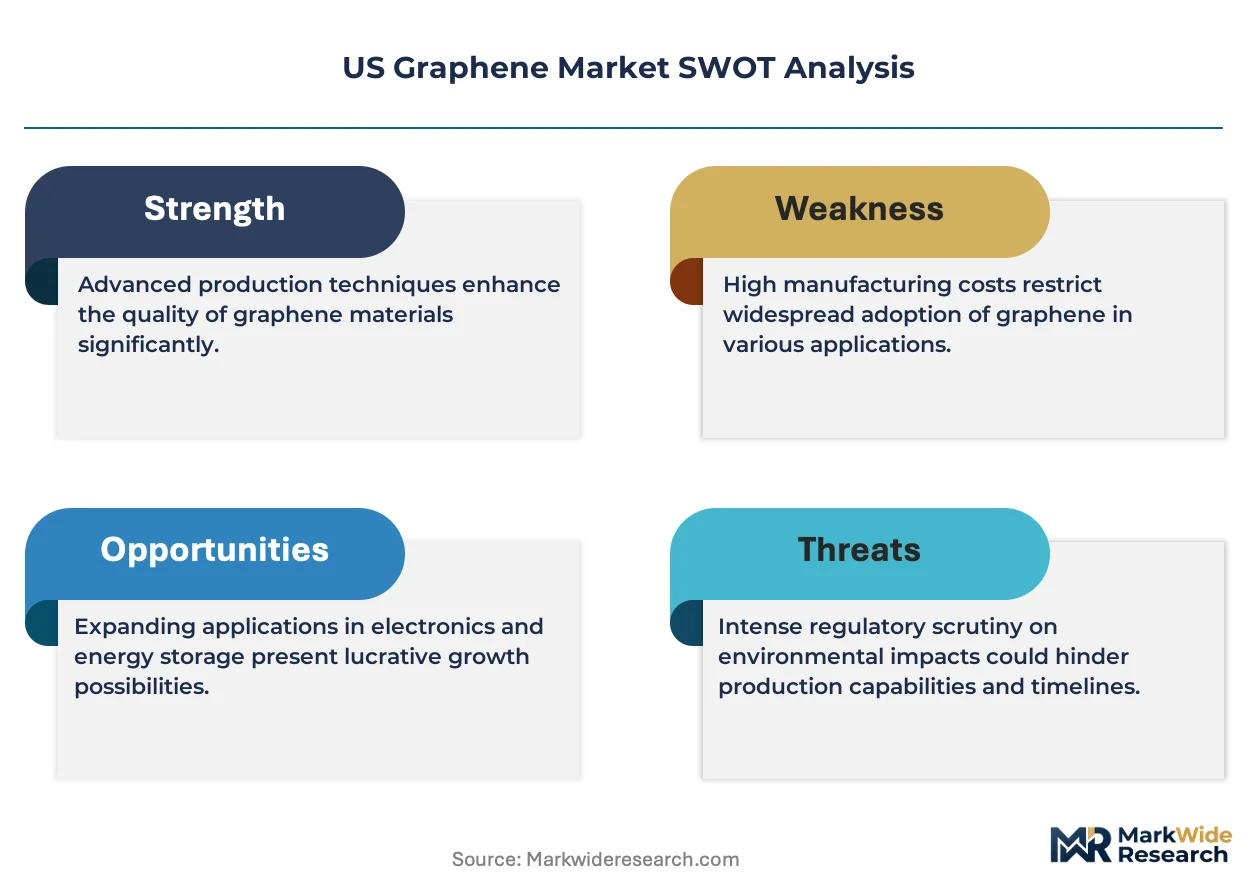
The EPA enforces TSCA Section 8(a) reporting for nanoscale materials including graphene, while OSHA maintains permissible exposure limits for carbon nanostakelets in manufacturing environments. The NHTSA and FAA both scrutinize flame-retardant and structural claims for graphene-loaded components in transportation applications. Stakeholders must monitor how FDA guidance on graphene-incorporated medical devices evolves, as this pathway could unlock premium pricing tiers currently inaccessible to general industrial grades.
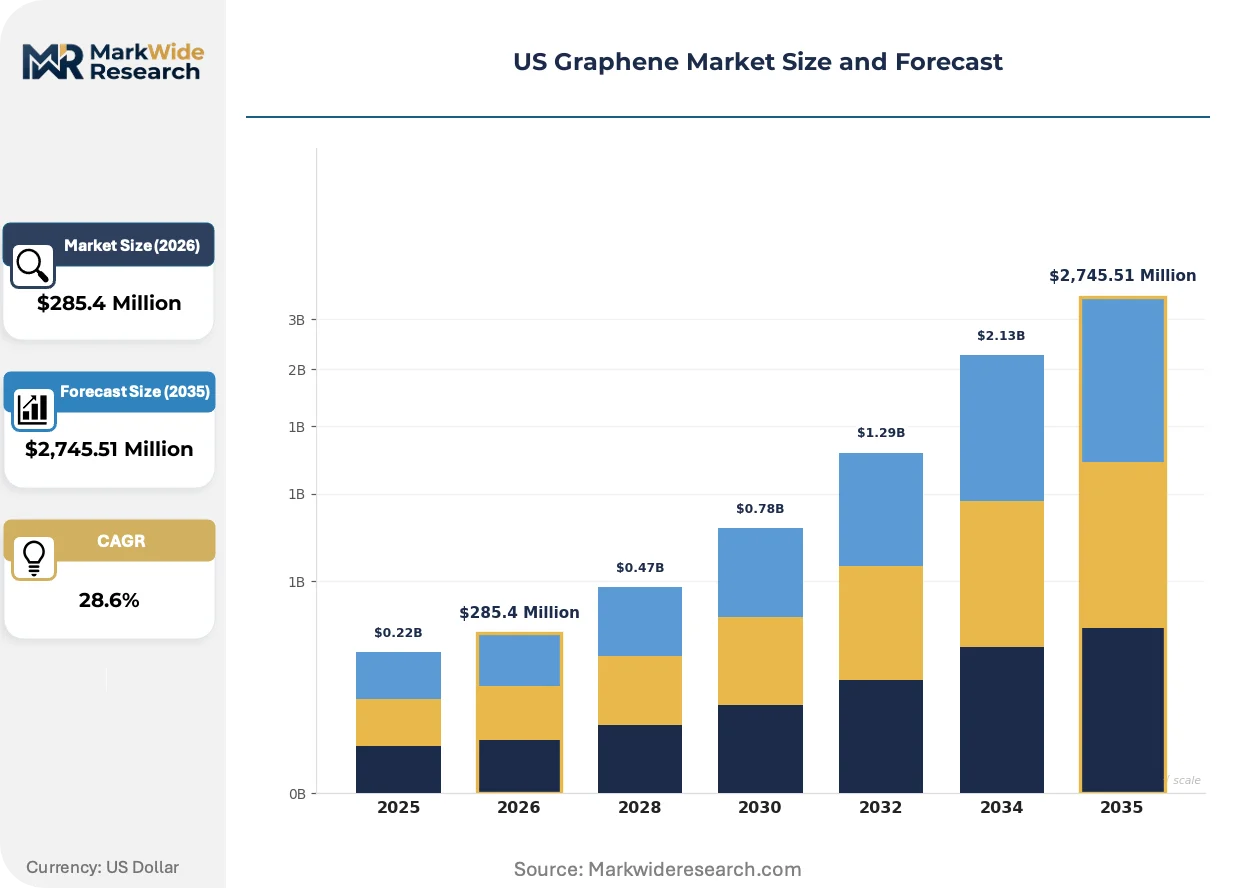
Market Dynamics
The EPA's TSCA Section 8(a) nanomaterial reporting rules are compressing compliance timelines and forcing producers to revalidate supply chain documentation before the enforcement window closes.
Growth Catalysts
- Silicon-graphene anode chemistry:Battery producers across the Midwest and Southeast are qualifying next-generation cell architectures that leverage graphene's conductivity to stabilize silicon expansion during charge cycles.
- IRA clean energy manufacturing credits:Domestic production incentives are accelerating capital deployment into Ohio and Texas-based synthesis facilities serving defense and aerospace contractors.
- Texas and California aerospace clusters:Tier-one manufacturers are locking in multi-year composite supply agreements as qualification timelines extend beyond eighteen months for structural airframe components.
Market Restraints
- Flake graphite import concentration:Precursor supply chains remain anchored to single-origin feedstock from Mozambique and Madagascar, exposing processors to geopolitical disruption and shipping cost volatility.
- CVD synthesis capex intensity:Chemical vapor deposition equipment for electronics-grade monolayer films requires cleanroom infrastructure that amortizes poorly below pilot scale.
- Carbon black substitution in rubber:Tire manufacturers continue specifying conventional fillers for cost-sensitive commodity grades, capping graphene penetration in high-volume automotive applications.
Strategic Opportunities
- Southeast battery corridor expansion:Georgia and Kentucky cell gigafactories are soliciting regional anode material suppliers to reduce inbound logistics exposure from Asian precursor networks.
- FDA medical device pathway:Class II orthopedic and cardiovascular device submissions incorporating graphene oxide coatings could unlock premium pricing tiers currently inaccessible to industrial grades.
- AI-assisted defect detection:Machine vision integration with roll-to-roll CVD lines is reducing yield loss from copper foil substrate irregularities during monolayer growth.
Industry Challenges
- Process engineering talent scarcity:Liquid-phase exfoliation scale-up requires specialized expertise in high-shear mixing and solvent recovery that competes with broader advanced materials sectors for limited personnel.
- Aerospace qualification timelines:FAA certification cycles for structural composite inserts extend supplier validation periods beyond typical venture capital fund horizons, constraining early-stage capital access.
- Batch-to-batch property variance:Few-layer graphene architectures exhibit inconsistent aspect ratios across production runs, complicating compounding protocols for thermoplastic masterbatch customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Graphene Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $2,745.51 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphene Oxide, Reduced Graphene Oxide, Few-Layer Graphene, Graphene Nanoplatelets, Graphene Quantum Dots Technology: Chemical Vapor Deposition, Liquid Phase Exfoliation, Mechanical Exfoliation, Thermal Reduction, Electrochemical Exfoliation Application: Composite Materials, Electronics, Energy Storage, Sensors, Thermal Management End User Industry: Aerospace & Defense, Consumer Electronics, Electrical Equipment Manufacturing, Research Institutions, Coatings & Paints |
| Companies Covered | U.S. Graphene Group, Graphite Central, NeoGraf Solutions, Angstron Materials Inc., CVD Equipment, ACS Material, Grolltex Inc, Vorbeck Materials Corp., XG Sciences, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Graphene Market Trends and Innovations
Production-scale defect engineering and regulatory data infrastructure are compressing the gap between laboratory performance claims and qualified industrial supply.
Roll-to-roll chemical vapor deposition onto electropolished copper foils is electrifying throughput economics for transparent conductive electrode manufacturers. Flexible display producers in Arizona and Oregon are integrating these films at pilot scale, displacing indium tin oxide sputtering lines that require vacuum chambers and precious metal inventories. The structural consequence is a compression in capital intensity per square meter of conductive surface area.
The EPA's TSCA Section 8(a) nanoscale material reporting rule is forcing graphene importers and domestic producers to submit comprehensive characterization data including particle size distribution and surface area metrics. Industrial chemical distributors are withdrawing from spot market trading to avoid documentation liability, consolidating volume through qualified supplier networks with established testing protocols. Battery anode compounders in the Midwest are absorbing compliance costs into long-term offtake contracts rather than spot purchases.
Defense contractors are mandating domestic provenance certification for thermal interface materials in satellite and avionics applications. Prime manufacturers are rejecting blended-origin graphite precursors, compelling Ohio and Pennsylvania processors to establish captive mining partnerships or synthetic graphite conversion capabilities. This preference shift is most visible in NASA and Space Force supply chains where supply security outweighs unit cost optimization.
US Graphene Market Segmentation
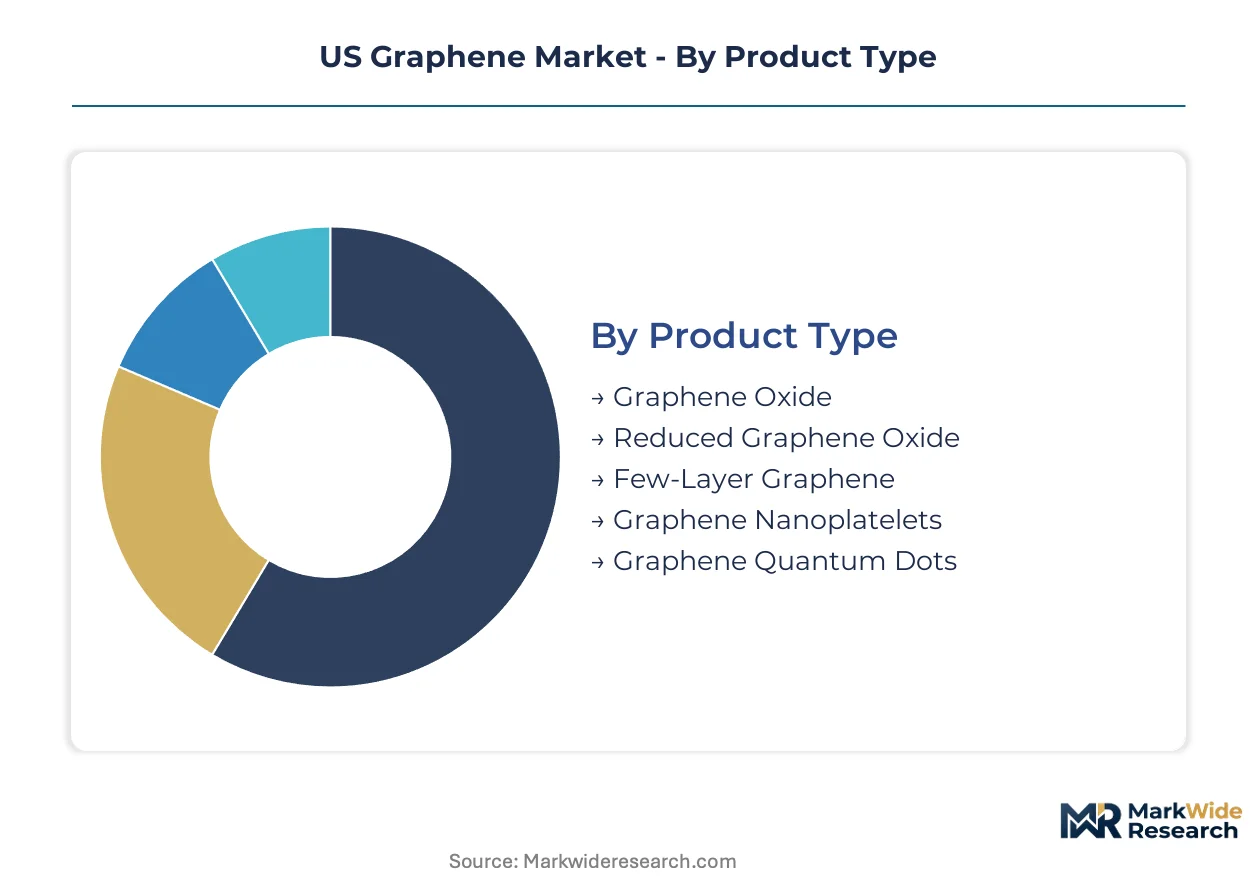
Graphene's commercial value crystallizes through precise product specifications and synthesis pathways. Buyers select grades based on layer count, defect density, and dispersibility requirements for target applications.
Product Type:
Purchasing decisions pivot on cost-performance tradeoffs between functionalized and pristine graphene architectures.
- Graphene Nanoplatelets:Multi-layered structures with 5-10 nm thickness and high aspect ratios dominate thermoplastic compounding. Ohio and Texas compounders specify these grades for automotive underhood components where electrical conductivity must balance against per-kilogram cost targets.
- Graphene Oxide:Oxygen-functionalized surfaces enable aqueous dispersion for coating formulations and biomedical device substrates. FDA pre-submission activity concentrates on orthopedic implant coatings where hydrophilic surface modification accelerates bone integration.
- Reduced Graphene Oxide:Partially restored conductivity after chemical reduction serves printed electronics and flexible sensor applications. Kentucky battery developers evaluate rGO as a lower-cost anode additive alternative to pristine graphene.
- Few-Layer Graphene:2-5 layer architectures preserve quantum transport properties for high-frequency electronics. California semiconductor fabs require tight thickness distributions that liquid-phase exfoliation struggles to deliver consistently.
- Graphene Quantum Dots:Nanoscale fragments below 10 nm exhibit tunable photoluminescence for bioimaging and photodetector applications. Research procurement from NIH-funded labs in Maryland and Massachusetts sustains pilot-scale production.
Graphene Nanoplatelets lead on scale; Graphene Oxide leads on momentum.
Technology:
Capital deployment and throughput economics separate viable industrial processes from laboratory curiosities.
- Chemical Vapor Deposition:Copper-catalyzed growth of monolayer films achieves the structural perfection required for transparent conductive electrodes. Arizona display manufacturers amortize cleanroom infrastructure across roll-to-roll lines serving flexible OLED production.
- Liquid Phase Exfoliation:High-shear dispersion of expanded graphite in solvents yields scalable nanoplatelet output. Midwest processors compete on solvent recovery efficiency as EPA reporting requirements tighten under TSCA Section 8(a).
- Mechanical Exfoliation:Scotch-tape-derived flakes retain crystalline quality for research-grade samples. Limited to gram-scale output, this method supplies university labs and metrology standards rather than commercial applications.
- Thermal Reduction:Rapid thermal shock converts graphite oxide to reduced forms without chemical reagents. Texas facilities integrate this pathway with upstream graphite oxidation to capture margin across the value chain.
- Electrochemical Exfoliation:Intercalation-driven layer separation operates at ambient conditions with tunable oxidation levels. Emerging producers in Pennsylvania pilot this approach to bypass hazardous solvent handling permits.
Liquid Phase Exfoliation anchors volume supply; CVD commands premium positioning.
Application:
End-use qualification timelines and performance thresholds dictate grade selection and supplier relationships.
- Energy Storage:Silicon-graphene composite anodes stabilize volume expansion during lithiation. Georgia and Kentucky cell gigafactories specify surface-area-optimized grades from regional compounders to minimize inbound logistics.
- Composite Materials:Masterbatch integration with thermoset and thermoplastic matrices enhances mechanical and electrical properties. Boeing and Lockheed Martin suppliers in California enforce lot-to-lot consistency protocols that extend qualification cycles beyond eighteen months.
- Thermal Management:Through-plane conductivity exceeding 10 W/mK suits satellite and avionics heat spreaders. Space Force contractors mandate domestic provenance certification that excludes blended-origin precursors.
- Electronics:Transparent conductive films and interconnect applications require monolayer uniformity. Oregon flexible display pilots displace indium tin oxide where sheet resistance targets fall below 100 ohms per square.
- Sensors:High surface-to-volume ratios enable gas detection and biosensing platforms. NIH-funded research in Boston and San Diego drives prototype demand before clinical translation.
Composite Materials retains the deepest supplier relationships; Energy Storage shows the steepest expansion trajectory.
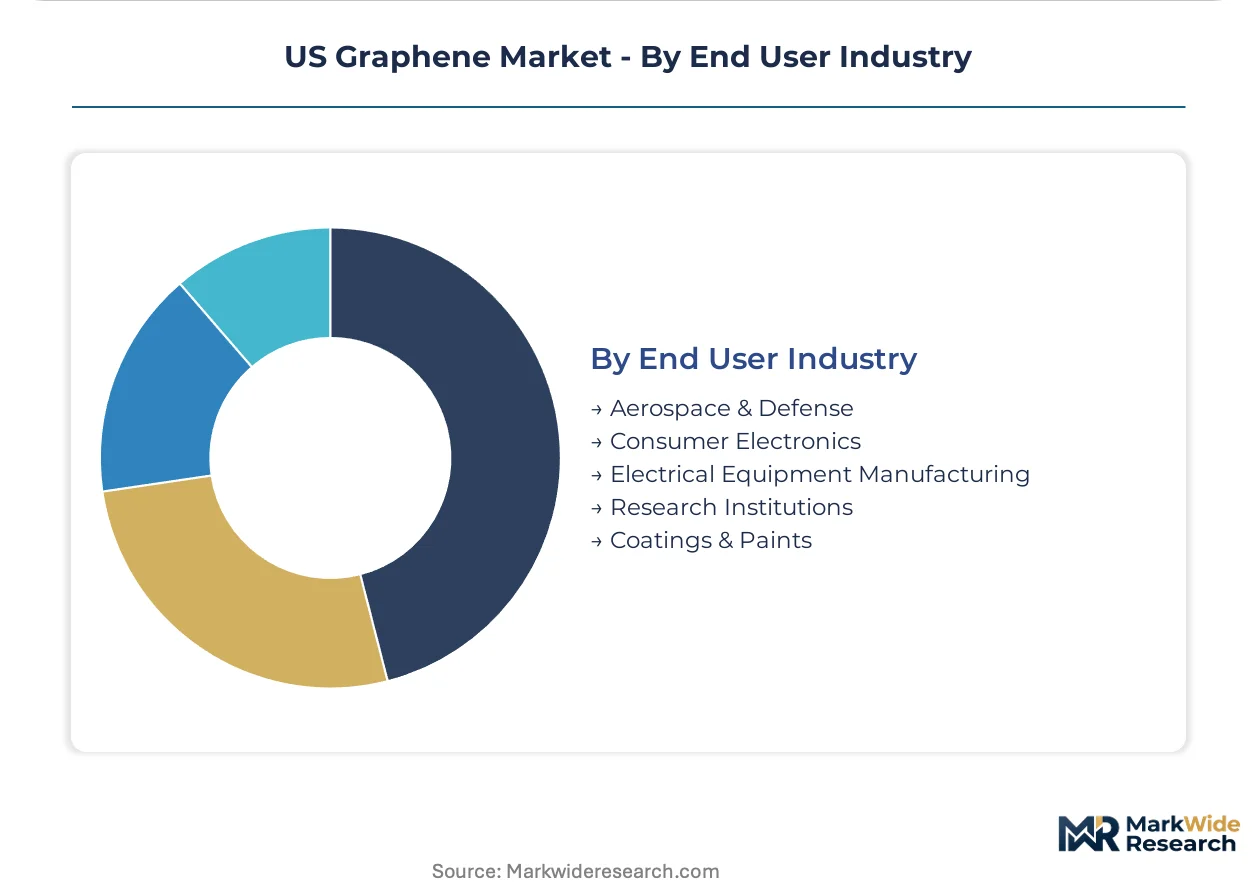
End User Industry:
Regulatory exposure and procurement sophistication vary sharply across buyer categories.
- Aerospace & Defense:FAA and NASA qualification requirements for structural composites create vendor lock-in. Prime contractors in Texas concentrate multi-year offtake agreements with Ohio-based producers holding AS9100 certification.
- Consumer Electronics:Rapid product cycles demand cost-optimized grades with relaxed specification windows. California device assemblers source through qualified distributor networks to manage TSCA documentation liability.
- Electrical Equipment Manufacturing:Transformer and cable producers evaluate graphene-enhanced conductive inks for grid infrastructure. FERC-jurisdictional utilities pilot these materials in substation monitoring applications.
- Research Institutions:ARPA-E and NSF grants sustain demand for characterization standards and novel synthesis methods. University procurement operates through cooperative purchasing agreements with limited price sensitivity.
- Coatings & Paints:Corrosion protection and EMI shielding formulations target industrial maintenance markets. Ohio and Pennsylvania applicators prioritize dispersibility in conventional solvent systems over pristine structural properties.
Aerospace & Defense concentrates premium value; Consumer Electronics drives volume scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas and California aerospace clusters anchor domestic demand for graphene-enhanced composites, while Ohio-based synthesis facilities serve battery producers across the Midwest and Southeast.
Texas
Space Force contractors and NASA suppliers concentrate in Houston and Dallas-Fort Worth for satellite thermal management materials. The Department of Defense mandates domestic provenance certification for defense-grade graphene precursors. Lockheed Martin and Boeing tier-one suppliers enforce AS9100 qualification protocols that lock in multi-year offtake agreements with regional compounders.
California
Flexible display manufacturers in Arizona and Oregon pilot roll-to-roll CVD films, displacing indium tin oxide sputtering lines. The FAA scrutinizes flame-retardant claims for graphene-loaded structural airframe components. San Francisco Bay Area semiconductor fabs require tight thickness distributions for high-frequency electronics applications.
Ohio
Battery anode compounders serve Georgia and Kentucky cell gigafactories with silicon-graphene formulations. The EPA's TSCA Section 8(a) reporting rules force producers to revalidate supply chain documentation. Cleveland and Columbus processors absorb compliance costs into long-term contracts rather than spot purchases.
Southeast
Georgia and Kentucky cell gigafactories solicit regional anode material suppliers to reduce inbound logistics exposure. The IRA clean energy manufacturing credits accelerate capital deployment into domestic synthesis facilities. Research Triangle Park in North Carolina sustains NIH-funded graphene quantum dot procurement for bioimaging applications.
Pennsylvania
Coatings and paints applicators prioritize dispersibility in conventional solvent systems for corrosion protection markets. OSHA maintains permissible exposure limits for carbon nanostakelets in manufacturing environments. Pittsburgh processors pilot electrochemical exfoliation to bypass hazardous solvent handling permits.
US Graphene Market Competitive Landscape
Global majors compete with regional champions across synthesis technology and qualification timelines. The vendor base spans CVD equipment suppliers, liquid-phase exfoliation specialists, and integrated compounders serving defense and aerospace supply chains. Three archetypes dominate: Ohio-based volume producers anchoring regional fulfillment, California-focused R&D-intensive few-layer specialists, and Texas-centered defense contractors with captive qualification protocols. Competitive moves concentrate on multi-year offtake agreements and domestic provenance certification rather than price competition.
Within the integrated production tier, U.S. Graphene Group and NeoGraf Solutions exemplify regional anchoring strategies. Angstron Materials Inc. occupies a position among R&D-intensive architects of few-layer graphene. These three represent distinct competitive vectors: volume fulfillment capacity, thermal management specialization for defense contractors, and research-driven product architectures.
| Leading Market Players |
|---|
| U.S. Graphene Group |
| Graphite Central |
| NeoGraf Solutions |
| Angstron Materials Inc. |
| CVD Equipment |
| ACS Material |
| Grolltex Inc |
| Vorbeck Materials Corp. |
| XG Sciences |
| Others |
Pricing and Supply Chain Analysis
EPA TSCA Section 8(a) nanomaterial reporting compliance gates both qualified supply access and premium-tier pricing for graphene producers serving defense and aerospace contractors. Battery anode compounders absorb documentation costs into long-term offtake contracts rather than spot purchases, compressing margins for processors lacking established testing protocols.
Pricing Analysis
Flake graphite import costs pass through directly to nanoplatelet pricing, with Mozambique and Madagascar feedstock anchoring cost structures for Midwest compounders. Three-tier pricing structure across electronics-grade monolayer, industrial nanoplatelet, and research-grade few-layer separates qualification-intensive aerospace tiers from commodity battery additives. Pricing pressure stems from carbon black substitution in tire manufacturing, where commodity rubber fillers cap graphene penetration. Consumer electronics assemblers exhibit highest price sensitivity, while Space Force contractors accept substantial premiums for domestic provenance certification.
Supply Chain Analysis
Single-source vulnerability sits with flake graphite precursors concentrated in Mozambique, Madagascar, and China's processed graphite exports. Synthesis equipment draws from German and Japanese precision manufacturing, with CVD reactor components facing extended lead times. Tariff exposure on Chinese graphite derivatives threatens cost structures for Pennsylvania and Ohio processors. Distribution runs through qualified supplier networks with established EPA documentation protocols, displacing spot market trading.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic synthesis capacity in Ohio and Texas commands arbitrage value against Asian precursor dependence, with IRA clean energy credits widening cost differentials for battery-grade material producers.
For Market Incumbents: Anchor multi-year offtake agreements with Georgia and Kentucky cell gigafactories before Southeast regional supply matures. Deepen backward integration into synthetic graphite conversion to satisfy Defense Department provenance mandates. Lock in AS9100-certified compounder relationships ahead of FAA qualification timeline extensions. For New Entrants and Emerging Players: AI-assisted defect detection for roll-to-roll CVD lines offers technology-first wedge against incumbent yield losses. Target electrochemical exfoliation pilots in Pennsylvania to bypass hazardous solvent permits constraining liquid-phase competitors. Lead with thermal management grades for satellite applications where Space Force procurement prioritizes supply security over unit cost. For Investors and Strategic Acquirers: Roll-up economics work for regional compounders with captive EPA compliance infrastructure because documentation liability is consolidating volume through qualified networks. Five-to-ten year viability hinges on FDA medical device pathway maturation for orthopedic coatings. Watch Georgia-Tennessee battery corridor supplier solicitation intensity as inflection indicator for regional pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Provenance Certification | Space Force and NASA procurement mandates exclude blended-origin precursors from qualified supplier lists. |
| Silicon-Graphene Anode Scale-Up | Kentucky and Georgia gigafactories specify regional compounders to minimize inbound logistics exposure. |
| Electrochemical Exfoliation Piloting | Pennsylvania processors bypass EPA hazardous solvent handling permits constraining liquid-phase competitors. |
| FDA Pre-Submission Investment | Orthopedic implant coatings unlock premium pricing tiers inaccessible to industrial-grade producers. |
| AI-Assisted Defect Detection Integration | Machine vision reduces yield loss from copper foil substrate irregularities in Arizona display manufacturing. |
Research Methodology
Direct dialogue with battery anode compounders, aerospace tier-one procurement directors, EPA compliance officers, and CVD equipment engineers grounded qualitative findings in operational realities. Secondary validation drew from TSCA Section 8(a) submission databases, SEC filings of listed advanced materials producers, customs import records for flake graphite, and FAA certification bulletins. Bottom-up and top-down triangulation reconciled facility-level capacity assessments with end-use demand aggregation across energy storage and composite applications.
Bottom-up modeling segmented volume and value across product type, synthesis technology, application, and end-user industry dimensions throughout the forecast period. CAGRs derived from elasticity-adjusted demand curves incorporating silicon-anode penetration rates and IRA credit absorption timelines. Forecast inputs included aerospace qualification cycle durations, battery gigafactory ramp schedules, and EPA enforcement window assumptions.
The model holds under sustained IRA credit availability and TSCA reporting compliance timelines; deviation in defense procurement prioritization or graphite export restrictions would shift regional supply economics. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Densified Silica Fume Market
Advanced Materials
Global Graphene Market
Advanced Materials
Inorganic Non-Metallic Materials Market
Advanced Materials
Advanced Functional Materials Market
Advanced Materials
Lithium Hydride Market
Advanced Materials
High-Purity Amorphous Boron Market
Advanced Materials
Advanced Carbon Materials Market
Advanced Materials
Hexagonal Boron Nitride (HBN) Market
Advanced Materials
North America Advanced Phase Change Materials Market
Advanced Materials
High Nickel Cathode Materials Market
Advanced Materials
Liquid Thermal Interface Materials Market
Advanced Materials
Cathode Materials Market
Advanced Materials
Europe Aerogel Market
Advanced Materials
Advanced Nanomaterials Market
Advanced Materials
Buckminsterfullerene Market
Advanced Materials
Natural Single Crystal Diamond Market