
 Curable Materials Market | 2026-2036
Curable Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Curable Materials Market Analysis
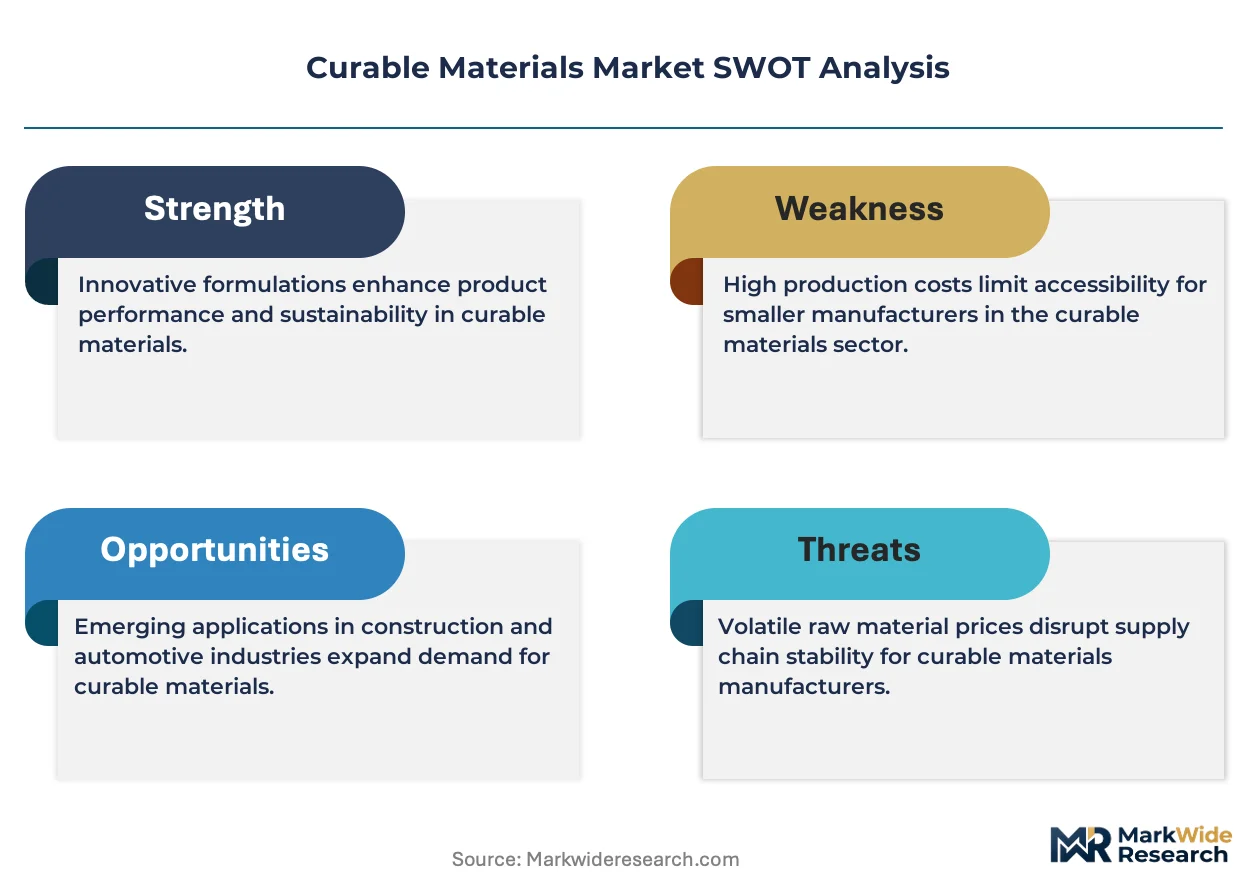
The gap between performance-grade formulations and bulk commodity resins is consolidating around certification requirements and supply chain reliability. BASF SE leverages its integrated precursor network to sustain pricing power in epoxy and polyurethane systems. Dow anchors North American supply through proprietary acrylic resin platforms, while Henkel AG & Co. KGaA differentiates via adhesive specialization for automotive OEM qualification programs.
Curable materials encompass polymers and oligomers that undergo irreversible hardening through UV irradiation, thermal activation, or chemical crosslinking, typically achieving full cure in seconds to minutes depending on initiator concentration and energy input. These materials serve as structural binders, protective barriers, and precision joining layers across manufacturing industries. Epoxy formulations dominate aerospace and electronics applications where thermal stability and dielectric strength command premium positioning, while UV-curing acrylics capture fastest growth in 3D printing and digital dentistry due to rapid processing speeds. Polyurethane sealants occupy mature construction end uses where cost efficiency outweighs performance differentiation.
REACH in Europe, EPA regulations in the United States, and China's MEE emission standards collectively restrict solvent content and mandate hazard communication across curable material supply chains. FDA oversight of medical-grade adhesives and electronics-grade IPC standards further segment qualification pathways by end-use industry. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs and market access delays.
Market Dynamics
UV-curable adhesive adoption for semiconductor packaging is concentrating procurement power among East Asian electronics manufacturers, forcing formulators to restructure supply chains around rapid-cure specifications and REACH-aligned low-emission chemistries.
Growth Catalysts
- REACH VOC limits:ECHA's tightening volatile organic compound restrictions in Europe are pushing formulators toward low-emission epoxy and polyurethane systems, creating qualified supplier scarcity that rewards early compliance investments.
- Semiconductor packaging:Electronics manufacturers in Taiwan, South Korea, and Japan are expanding UV-curable adhesive adoption for advanced chip bonding, driving specification-grade volume commitments.
- Automotive-electronics clustering:China's coastal manufacturing provinces concentrate thermosetting resin demand through co-located automotive OEM and tier-1 electronics supplier parks, enabling bulk procurement efficiencies.
Market Restraints
- Petrochemical feedstock volatility:Epoxy resin precursors derived from propylene and bisphenol-A expose margin structures to crude oil derivative swings, compressing working capital flexibility for mid-scale formulators.
- Photoinitiator supply concentration:Specialty photoinitiator production concentrates among German and Japanese chemical houses, creating single-source vulnerability for UV-curable acrylic producers.
- Thermal cure speed limitations:Aerospace-grade epoxy systems require extended oven cycles that constrain throughput against in-line UV alternatives, limiting penetration in time-sensitive assembly operations.
Strategic Opportunities
- Digital dentistry equipment:Chairside 3D printing systems in dental practices are creating distributed demand for biocompatible UV-curable resins with ISO 10993 certification pathways.
- EU Green Deal chemistry incentives:Horizon Europe funding streams and ECHA substitution mandates are accelerating bio-based oligomer development, opening qualification windows for renewable feedstock formulators.
- AI-actuated formulation design:Machine learning convergence with high-throughput rheometry is compressing new product development cycles, enabling rapid customization for niche electronics bonding applications.
Industry Challenges
- IPC-A-610 certification timelines:Electronics-grade adhesive qualification for semiconductor packaging requires 18-24 month reliability testing, delaying revenue recognition and straining R&D capitalization.
- Legacy thermal oven infrastructure:Automotive and aerospace manufacturers face stranded asset risk from existing capital-intensive cure systems, creating adoption friction for UV-curable alternatives despite processing speed advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Curable Materials Market |
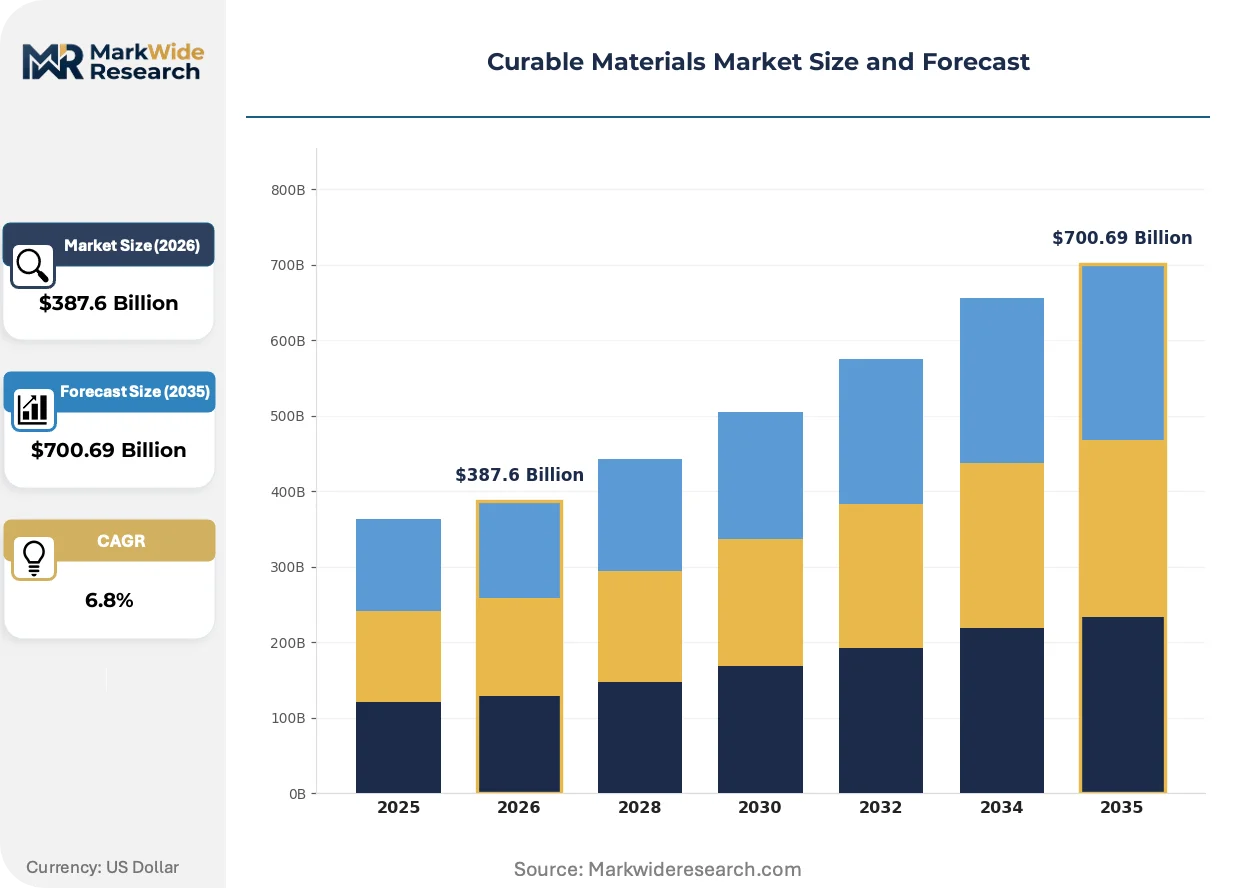
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Silicone Application: Coatings, Adhesives, Sealants, 3D Printing End User: Aerospace, Automotive, Construction, Electronics Technology: UV-Curing, Thermosetting, Thermoplastic, Chemical Curing |
| Companies Covered | BASF SE, Dow, Henkel AG & Co. KGaA, Royal DSM, Covestro, 3M, Arkema, Wacker Chemie, Dymax Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Curable Materials Market Emerging Trajectories
Dual-cure systems combining UV initiation with moisture or thermal secondary crosslinking are collapsing the performance gap between speed and depth-of-cure, reshaping specification standards across electronics and medical device assembly.
Cationic UV-curable epoxy formulations are electrifying shadow-cure capabilities in complex semiconductor package geometries. Taiwan-based OSATs are qualifying these systems for underfill and encapsulation layers at production scale. The technology is electrifying throughput benchmarks previously constrained by oxygen-inhibition limits in radical acrylics.
China's MEE emission standards are mandating solvent-content reductions in industrial coatings and adhesives that exceed prior GB standard baselines. Formulators serving export-oriented electronics manufacturers in Jiangsu and Guangdong provinces are accelerating waterborne UV and 100% solids thermal cure substitutions. Medical-grade adhesive producers face parallel FDA 21 CFR 175.105 compliance burdens that segment qualification pathways from commodity construction applications.
Specification-driven procurement consolidation is compressing supplier panels among automotive OEMs and tier-1 electronics assemblers. Buyers in Germany's Baden-Württemberg automotive cluster and Japan's Kansai electronics corridor are consolidating annual volume commitments to qualified formulators with REACH documentation and IATF 16949 certification. This consolidation is displacing spot-market purchasing and rewarding integrated precursor-to-formulation suppliers with multi-year contract structures.
Curable Materials Market Segmentation
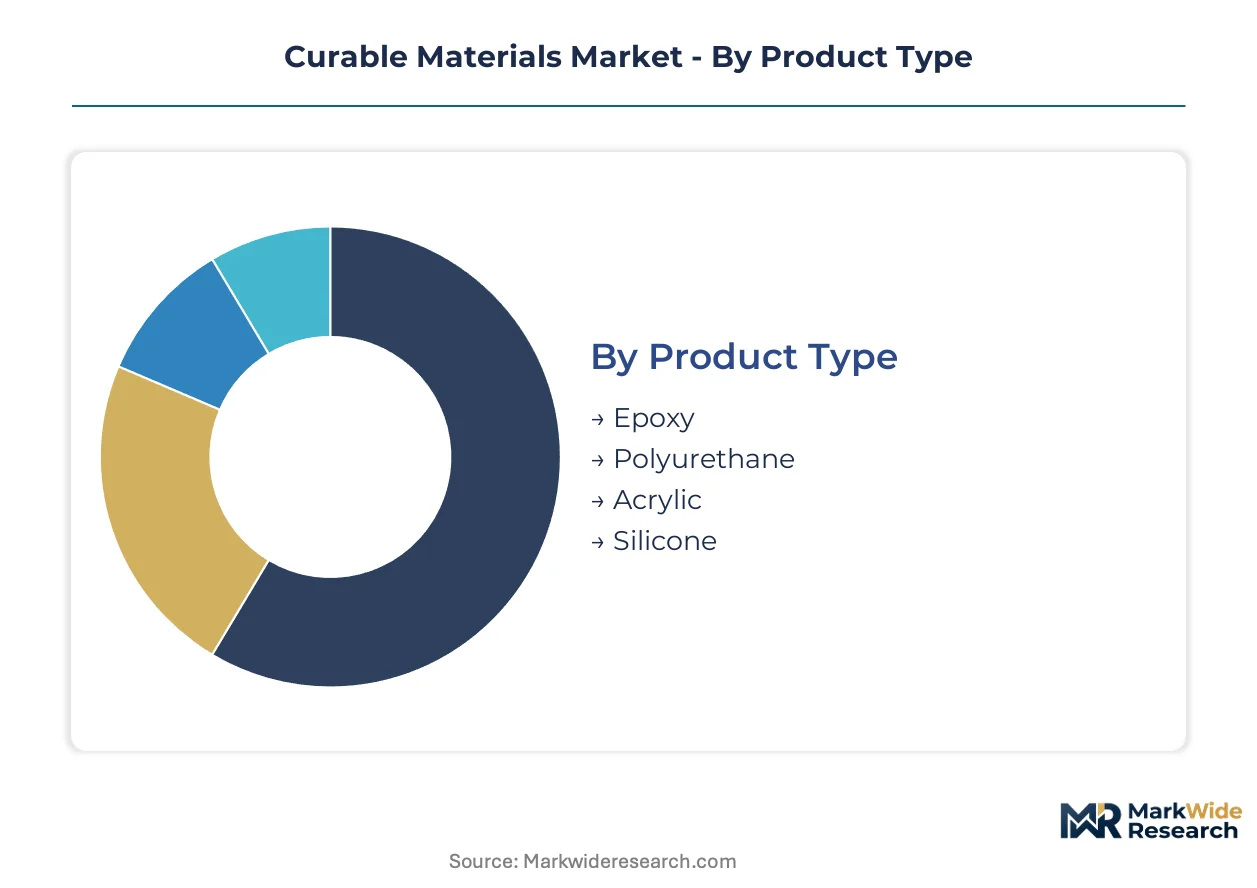
Curable materials fragment across four intersecting dimensions that determine formulation specifications, cure protocols, and qualification pathways. Product chemistry governs thermal and mechanical properties, while application format dictates viscosity, pot life, and equipment compatibility. End-user industries impose distinct certification regimes, and cure technology constrains throughput economics.
Product Type:
Customization intensity spans from aerospace-grade epoxies with 18-month qualification cycles to commodity construction sealants purchased on spot pricing.
- Epoxy:Bisphenol-A and novolac-based systems achieve glass transition temperatures exceeding 150°C, serving semiconductor underfill and aerospace structural bonding where IPC-A-610 and FAA fire-resistance standards apply. Taiwan-based OSATs and Germany's Baden-Württemberg automotive cluster drive specification-grade procurement with REACH-compliant low-VOC formulations.
- Acrylic:UV-curable oligomers with radical photoinitiator systems achieve tack-free surfaces in sub-10 second exposures, capturing dental 3D printing and electronics potting applications where speed outweighs thermal performance. Japanese photoinitiator suppliers constrain raw material security for formulators outside East Asia.
- Polyurethane:Moisture-cure and two-part systems balance elasticity with chemical resistance for construction joint sealing and automotive glazing, competing primarily on cost per liter in China's Jiangsu province manufacturing corridors.
- Silicone:Platinum-catalyzed addition cure systems deliver biocompatibility and extreme temperature stability for medical device encapsulation and aerospace gasketing, with FDA 21 CFR 175.105 and ISO 10993 pathways segmenting suppliers from commodity tiers.
Leading the category by volume: Polyurethane construction sealants. Growing fastest: UV-curable acrylics in digital dentistry and electronics.
Application:
Volume concentration in coatings contrasts with value concentration in precision adhesives for semiconductor packaging.
- Adhesives:Structural bonding layers for chip-to-substrate attachment and automotive lightweighting require tailored rheology and controlled fillet formation. East Asian electronics manufacturers consolidate procurement among IATF 16949-qualified formulators with documented REACH substance inventories.
- Coatings:Protective barriers for industrial equipment and consumer electronics dominate tonnage consumption, with China's MEE emission standards accelerating waterborne UV substitutions in Jiangsu and Guangdong export zones.
- Sealants:Elastic joint fillers for construction and transportation applications compete on price elasticity, with mature supply chains in North American and European building materials distribution.
- 3D Printing:Photopolymer resins for vat photopolymerization and material jetting require biocompatibility certification for dental and medical applications, creating ISO 10993 qualification barriers for new entrants.
Coatings generate the highest absolute volume. Adhesives command the steepest premium expansion trajectory.
End User:
Certification burden intensity separates aerospace and medical electronics from construction and general industrial applications.
- Electronics:Semiconductor packaging, PCB protection, and display bonding require ionic purity below 10 ppm and coefficient of thermal expansion matching silicon substrates. Taiwan, South Korea, and Japan concentrate demand for advanced underfill and encapsulation materials.
- Aerospace:Structural composites and interior assemblies demand FAA flammability compliance and outgassing controls per ASTM E595, with cure cycles extending to hours for epoxy prepreg systems.
- Automotive:Powertrain, electronics, and lightweight body-in-white applications consolidate procurement through IATF 16949-certified suppliers, with China's coastal OEM parks enabling bulk thermosetting resin commitments.
- Construction:Mature demand for joint sealants, flooring coatings, and waterproofing membranes competes on installed cost, with limited differentiation beyond weathering warranty terms.
Electronics leads value concentration. Construction dominates tonnage.
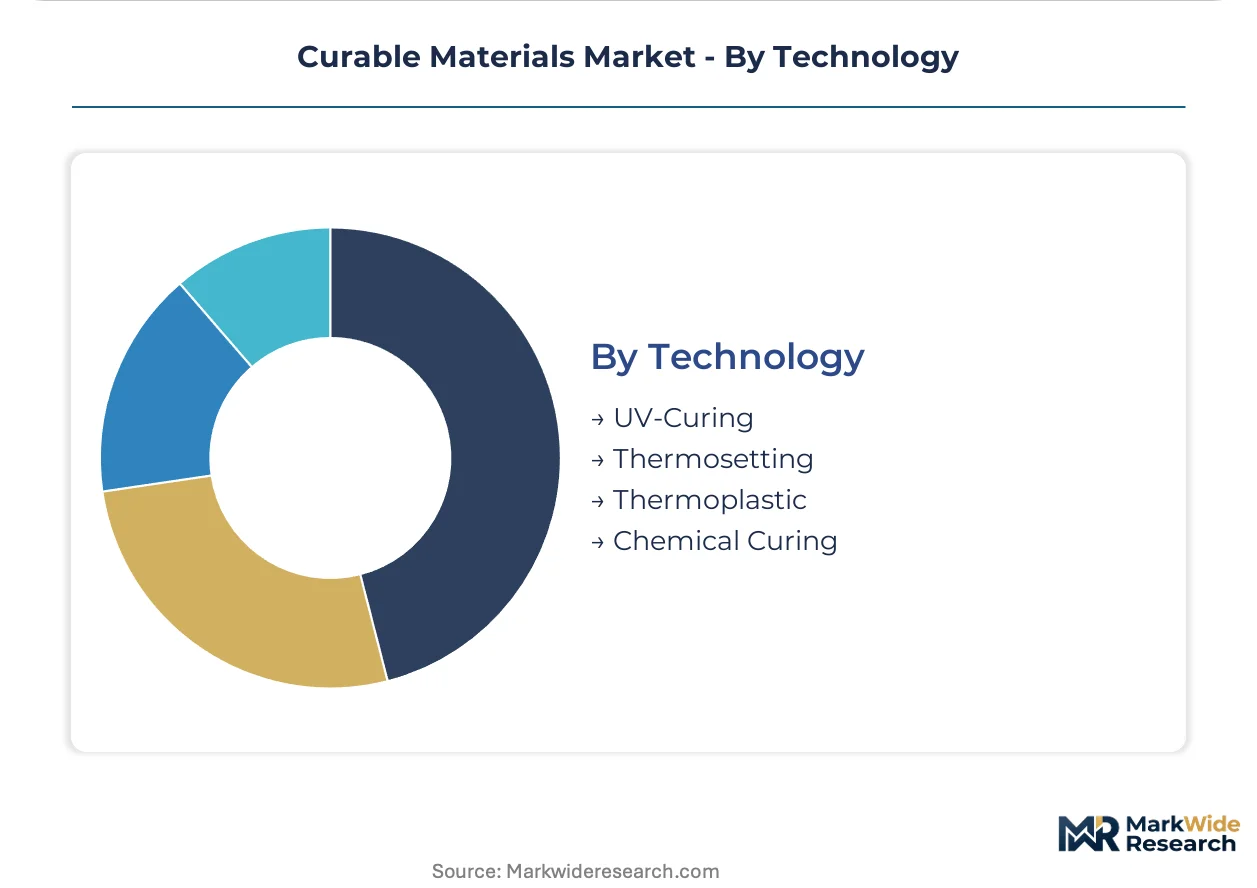
Technology:
Capital equipment requirements and energy inputs create divergent adoption economics across manufacturing scales.
- UV-Curing:Mercury and LED lamp systems deliver instant polymerization for high-throughput electronics and dental applications, constrained by oxygen inhibition in radical systems and photoinitiator supply concentration among German and Japanese chemical houses.
- Thermosetting:Epoxy and polyurethane systems requiring oven cure or ambient chemical reaction serve structural applications where depth-of-cure and thermal stability outweigh speed, with legacy automotive and aerospace infrastructure creating stranded asset friction against UV alternatives.
- Thermoplastic:Reversible melt-processable systems occupy niche repair and rework applications outside permanent bonding use cases, with limited penetration in structural curable materials.
- Chemical Curing:Two-part mixing systems for construction and marine applications operate independently of energy input, enabling field application without capital equipment but requiring precise mix ratio control.
Thermosetting retains volume leadership. UV-curing posts the steepest share gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors the world's densest concentration of curable materials demand through co-located semiconductor packaging foundries and automotive OEM assembly parks.
United States
Texas and Arizona semiconductor fabrication investments are pulling specification-grade epoxy and UV-curable adhesive volumes. EPA emission standards under the Clean Air Act constrain solvent-based formulation expansion. Detroit's automotive corridor maintains bulk thermosetting resin procurement through IATF 16949-qualified supplier networks.
China
Jiangsu and Guangdong export manufacturing zones concentrate electronics-grade adhesive consumption for display bonding and PCB protection. MEE emission standards mandate solvent-content reductions exceeding prior GB baselines. Yangtze River Delta automotive clusters are consolidating multi-year thermosetting resin contracts with coastal formulators.
Germany
Baden-Württemberg automotive OEMs are consolidating procurement panels among REACH-documented adhesive suppliers. ECHA VOC restrictions under REACH are disqualifying high-solvent formulations from qualified supplier lists. Bavaria's precision electronics corridor drives specification-grade epoxy demand for industrial sensor packaging.
Japan
Kansai electronics manufacturers are qualifying cationic UV-curable epoxies for advanced semiconductor underfill applications. METI industrial standards govern photoinitiator purity specifications for electronics-grade formulations. Nagoya automotive suppliers are transitioning structural bonding lines from thermal cure to dual-cure UV systems.
South Korea
Seoul Capital Area display panel manufacturers are expanding UV-curable optical adhesive adoption for OLED lamination. MFDS biocompatibility pathways segment medical-grade silicone suppliers from commodity tiers. Busan-Ulsan chemical complexes supply captive epoxy precursors to domestic formulators serving Samsung and SK Hynix supply chains.
Curable Materials Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the curable materials landscape. Integrated petrochemical houses with captive bisphenol-A and propylene oxide supply dominate bulk epoxy and polyurethane tonnage. Specialty formulators concentrate on qualification-intensive electronics and medical segments where certification documentation commands premium positioning. Strategic moves center on backward integration into photoinitiator supply and geographic co-location with East Asian electronics manufacturing clusters.
Within the integrated chemical conglomerate tier, BASF SE and Dow exemplify upstream control strategies that sustain margin structures against feedstock volatility. Covestro occupies a position between commodity scale and performance-grade specialization through its polyurethane systems focus. Among adhesive specialists, Henkel AG & Co. KGaA anchors automotive OEM qualification pathways with documented REACH substance inventories and IATF 16949 certification.
| Leading Market Players |
|---|
| BASF SE |
| Dow |
| Henkel AG & Co. KGaA |
| Royal DSM |
| Covestro |
| 3M |
| Arkema |
| Wacker Chemie |
| Dymax Corporation |
| Others |
Supply Flow & Price Mechanics
Dual-cure UV-thermal systems are collapsing the performance premium between rapid-cure acrylics and aerospace-grade epoxies, simultaneously compressing formulation margins and redistributing supply power toward photoinitiator producers in Germany and Japan. This technology convergence forces mid-scale formulators to absorb higher input costs or cede specification-grade contracts to integrated chemical houses with captive precursor supply.
Pricing Analysis
Yield-guaranteed throughput pricing anchors specification-grade contracts for semiconductor packaging adhesives, with Taiwan-based OSATs paying premiums for documented IPC-A-610 reliability. Three-tier pricing structure across qualification-intensive, industrial-grade, and commodity construction tiers separates IATF 16949-certified suppliers from spot-market competitors. Cost compression in industrial coatings is intensifying because China's MEE standards mandate solvent-content reformulations without corresponding price recovery mechanisms. Construction sealant buyers in China's Jiangsu province exhibit highest price sensitivity, while aerospace OEMs in Germany's Baden-Württemberg cluster prioritize thermal stability over unit cost.
Supply Chain Analysis
Skilled formulation chemist availability constrains capacity expansion in Taiwan, South Korea, and Germany despite surging electronics-grade demand. Bisphenol-A, propylene oxide, and specialty photoinitiators feed from concentrated petrochemical and fine chemical producers, creating single-source vulnerability for UV-curable acrylic manufacturers outside East Asia. Tariff exposure on Chinese-sourced epoxy precursors threatens margin structures for North American formulators lacking backward integration. Distribution runs through qualified supplier panels at automotive OEMs and tier-1 electronics assemblers, displacing spot-market purchasing with multi-year contract structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photoinitiator production capacity bottlenecks in German and Japanese chemical houses prop pricing power for UV-curable formulations, sustaining premium capture for integrated suppliers with captive supply.
For Market Incumbents: Anticipate REACH-aligned low-emission chemistry mandates by accelerating bio-based oligomer development through Horizon Europe funding access. Defend specification-grade positioning by securing IATF 16949 certification maintenance and documented substance inventories ahead of ECHA VOC restriction tightening. Capacity additions in China's Yangtze River Delta automotive clusters offer geographic hedge against European regulatory compliance costs. For New Entrants and Emerging Players: Direct-to-formulator digital platforms bypass entrenched distribution channels serving China's coastal electronics manufacturers, enabling rapid qualification for niche UV-curable adhesive applications. Target digital dentistry equipment supply chains with ISO 10993-certified biocompatible resins, where chairside 3D printing growth outpaces incumbent response capacity. White-space concentration exists in AI-actuated formulation design services for custom electronics bonding specifications. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty formulator acquisitions by integrated chemical conglomerates seeking electronics-grade qualification capabilities. Long-term viability favors targets with REACH documentation infrastructure and established OEM supplier relationships over commodity resin producers. Watch photoinitiator supply concentration indices as inflection indicator for UV-curable segment margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiator Supply | Reduces single-source vulnerability for UV-curable acrylic producers serving Taiwan OSATs. |
| REACH-Compliant Low-VOC Formulation Expansion | Qualifies suppliers for Baden-Württemberg automotive OEM procurement consolidation. |
| Digital Dentistry Resin Certification Pathway | Opens ISO 10993-qualified revenue streams through chairside 3D printing equipment partnerships. |
| Dual-Cure System Production Scale-Up | Captures specification-grade electronics contracts from legacy thermal-cure infrastructure constraints. |
| Yangtze River Delta Manufacturing Co-Location | Enables bulk thermosetting resin commitments from clustered automotive and electronics demand. |
Methodological Framework
Document review covered ECHA REACH substance inventories, SEC 10-K filings from integrated chemical producers, and customs trade data for epoxy precursor flows, complemented by interviews with plant managers at Taiwan OSATs, procurement leads at German automotive OEMs, distribution channel partners in China's Jiangsu province, and technical R&D directors at specialty adhesive formulators. Bottom-up volume modeling from application-specific consumption rates was triangulated against top-down chemical industry production data.
Segment-level outputs across the projection horizon reflect chemistry type, cure technology, end-use industry, and regional manufacturing cluster dimensions. CAGRs were derived from elasticity-adjusted demand projections incorporating semiconductor packaging intensity, automotive lightweighting penetration, and regulatory compliance cost pass-through assumptions. Forecast inputs included photoinitiator supply concentration indices, MEE emission standard implementation timelines, and IATF 16949 certification queue lengths.
Inputs from ECHA substance databases and Taiwan Semiconductor Industry Association members were available through the study window; gaps in real-time OEM procurement contract terms introduce uncertainty bands around specification-grade volume assumptions. Forecasts reflect documented regulatory trajectories and capacity expansion announcements. Photoinitiator supply disruption events, REACH restriction acceleration, and automotive platform electrification pace warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Densified Silica Fume Market
Advanced Materials
Glass Reinforced Vinyl Ester (GRV) Market
Advanced Materials
Silica Aerogel Market
Advanced Materials
Long-Range Ordered Porous Carbon (LOPC) Market
Advanced Materials
Nanofibrillar Cellulose Market
Advanced Materials
Global Next Generation Anode Materials Market
Advanced Materials
Si-C Anode Material Market
Advanced Materials
Synthetic Graphite Market
Advanced Materials
Lithium Hydride Market
Advanced Materials
Carbon Graphite Market
Advanced Materials
Thermal Spray Materials Market
Advanced Materials
Wood Foam Market
Advanced Materials
North America Advanced Phase Change Materials Market
Advanced Materials
Advanced Nanomaterials Market
Advanced Materials
US Graphene Market
Advanced Materials
Advanced Carbon Materials Market