
 Superconducting Materials Market | 2026-2036
Superconducting Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Superconducting Materials Market Intelligence
Second-generation REBCO tape manufacturing is fragmenting across multiple deposition techniques, forcing equipment suppliers to support both pulsed-laser and metal-organic chemical vapor deposition toolsets. American Superconductor Corporation sustains its position through proprietary matrix architecture for grid-scale cable systems. Sumitomo Electric Industries Ltd. dominates liquid-nitrogen-cooled wire production for fusion energy prototypes. Bruker Corporation leverages its installed base of NMR magnets to secure long-term niobium-tin supply contracts.
Superconducting materials exhibit zero electrical resistance below a critical temperature, enabling persistent-current operation in magnetic fields exceeding 20 tesla for medical imaging and scientific instrumentation. Low-temperature superconductors still anchor the majority of commercial volume due to decades of validated performance in MRI magnets, though high-temperature superconductors are capturing margin pools in fusion and grid applications where cryogenic cooling costs determine project economics. Wire form deployments lead in value terms, while coated conductors represent the fastest-expanding fabrication category for power transmission and compact accelerator magnets.
FDA device clearance requirements shape superconducting magnet qualification pathways for MRI OEMs, while EU REACH compliance governs rare-earth element sourcing from European refiners. China's GB standards and MIIT technology roadmaps dictate domestic superconducting cable deployment timelines for urban grid segments. Stakeholders must monitor how national hydrogen strategies and fusion energy commitments redirect government R&D funding between low-temperature and high-temperature material platforms.
Market Dynamics
The transition from liquid-helium to liquid-nitrogen cooling architectures is compressing total cost of ownership for high-field magnet systems, forcing wire suppliers to requalify conductor designs across multiple cryogenic operating points simultaneously.
Growth Catalysts
- Fusion Energy Prototypes:ITER and private reactor developers in the United States and Germany are placing multi-year procurement contracts for REBCO tape, creating anchored demand visibility for coated conductor foundries.
- China's Dual Carbon Mandates:MIIT technology roadmaps and GB standards are accelerating superconducting cable pilots in Shanghai and Shenzhen urban grid segments, with state grid operators mandated to trial fault-current limiters.
- Helium Conservation Policies:F-Gas Regulation in Europe and equivalent refrigerant phase-down frameworks in Japan are pushing MRI OEMs toward conduction-cooled magnet designs that tolerate higher operating temperatures.
Market Restraints
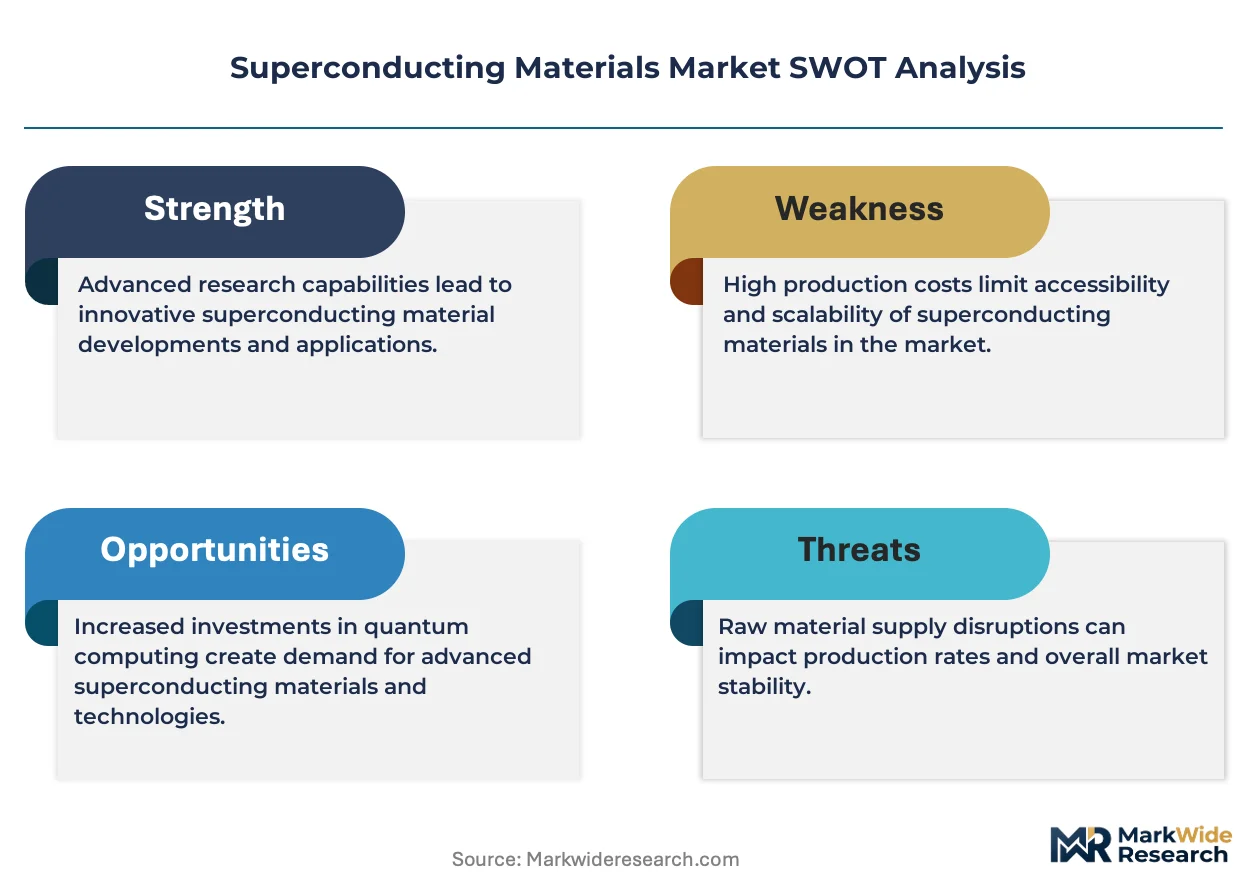
- Rare-Earth Supply Concentration:REBCO tape production depends on yttrium and gadolinium refined primarily in China, exposing non-Chinese cable manufacturers to export quota volatility and price spikes.
- Cryogenic Infrastructure Capital:Urban substation retrofits require specialized subcoolers and vacuum-insulated cryostats that add 40-60% to project capital intensity versus conventional copper solutions.
- Low-Temperature Superconductor Lock-In:Decades of validated niobium-titanium performance in clinical MRI systems create switching costs that slow high-temperature superconductor penetration despite superior field-temperature margins.
Strategic Opportunities
- Offshore Wind Collector Grids:Germany and Denmark transmission operators are evaluating superconducting DC links for North Sea turbine clusters, where compact footprint and zero resistive losses offset cryogenic system complexity.
- Quantum Computing Interconnects:Dilution refrigerator manufacturers require specialized superconducting coaxial cabling for qubit control planes, opening a precision-fabrication niche distinct from bulk power applications.
- India PLI Scheme Alignment:Production-linked incentives for advanced materials and medical device components create a pathway for domestic superconducting wire manufacturing serving South Asian MRI and scientific instrument markets.
Industry Challenges
- Cryogenic Engineering Talent Scarcity:The specialized knowledge base spanning thermodynamics, vacuum technology, and superconducting electrodynamics concentrates in national laboratories and a handful of university programs, constraining workforce scaling for commercial projects.
- Multi-Agency Certification Complexity:Grid-connected superconducting equipment must satisfy FERC interconnection standards, IEEE testing protocols, and local utility technical specifications simultaneously, extending qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Superconducting Materials Market |
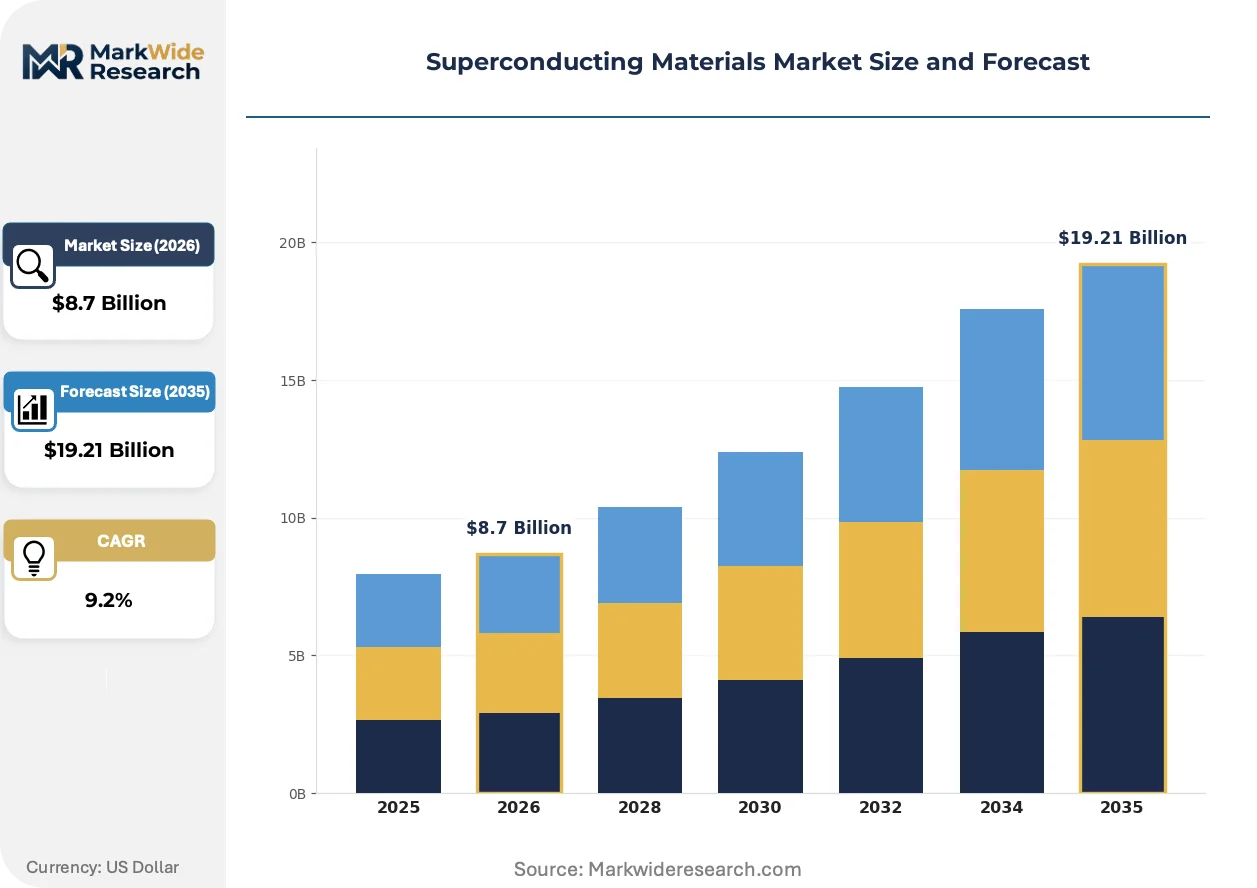
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.21 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Temperature Superconductors, Low-Temperature Superconductors, Iron-Based Superconductors, Magnesium Diboride Superconductors Application: Magnetic Resonance Imaging, Particle Accelerators, Power Transmission, Magnetic Levitation, Quantum Computing End User: Research Laboratories, Power Utilities, Transportation Firms, Telecommunication Companies Deployment: Bulk Form, Wire Form, Thin Films, Coated Conductors |
| Companies Covered | Furukawa Electric Co., Ltd., American Superconductor Corporation, Sumitomo Electric Industries Ltd., Bruker Corporation, Fujikura Ltd., Western Superconducting Technologies Co., Ltd., Hitachi Ltd., NEXANS SA, SuperPower Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Superconducting Materials Market Strategic Shifts & Innovations
Deposition equipment vendors are supporting divergent REBCO manufacturing methodologies while buyers consolidate around performance-optimized conductor architectures that minimize alternating-current losses in pulsed-field operation.
Second-generation coated conductor technology is hybridizing metal-organic chemical vapor deposition and pulsed-laser deposition processes into sequential manufacturing flows that optimize both throughput and critical current density. Fusion energy developers in the United States and Germany are qualifying these hybrid tapes for high-field magnet inserts operating above 20 tesla. The resulting process flexibility is compressing capital requirements for new tape manufacturing capacity while fragmenting equipment vendor market positions.
EU F-Gas Regulation phase-down schedules are forcing MRI magnet designers to eliminate helium boil-off entirely through conduction-cooled niobium-tin alternatives or closed-cycle refrigeration systems. European OEMs are requalifying magnet designs for zero-liquid-helium operation ahead of 2030 refrigerant quota reductions. The regulatory pressure is accelerating substitution timelines in premium imaging segments while preserving low-temperature superconductor dominance through material formulation changes rather than platform shifts.
Utility procurement departments are bundling superconducting cable contracts with 20-year cryogenic maintenance service agreements to internalize operational risk and secure lifecycle cost predictability. Korean and German transmission operators pioneered this integrated sourcing model for urban grid projects, and the approach is displacing traditional equipment-plus-installation contracting in fault-current limiter deployments. The service bundling trend concentrates vendor selection criteria on field service network density rather than unit manufacturing cost alone.
Superconducting Materials Market Segmentation
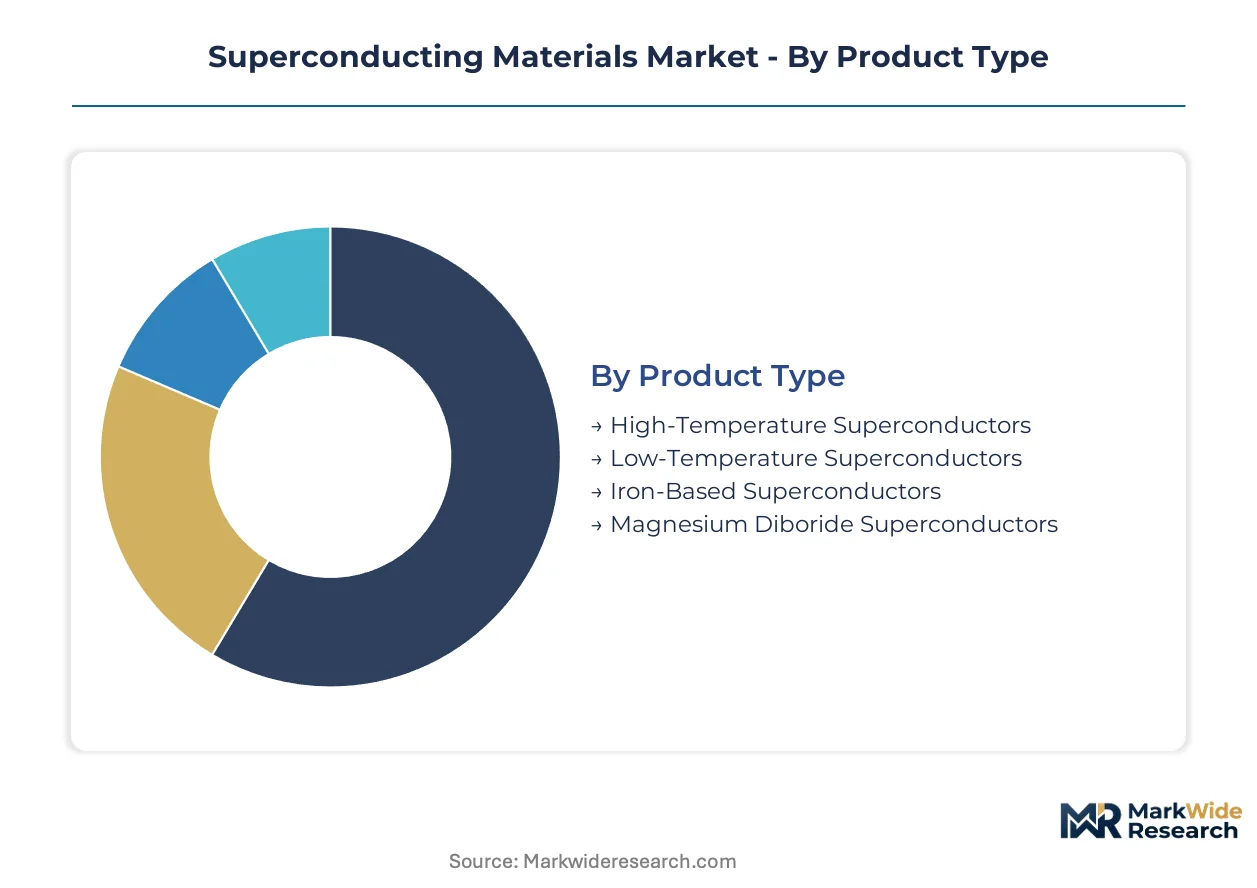
Superconducting materials demand diverges sharply across cooling architectures and fabrication formats, with each segment carrying distinct service lifecycle requirements and qualification barriers that shape vendor selection criteria.
Product Type:
After-sales-service intensity varies dramatically across superconducting material classes, driven by cryogenic system complexity and operational criticality.
- High-Temperature Superconductors:REBCO and BSCCO compounds operate at liquid-nitrogen temperatures, slashing cooling infrastructure costs for grid and fusion applications. Demand concentrates in Shanghai and Shenzhen urban grid pilots where MIIT mandates fault-current limiter trials.
- Low-Temperature Superconductors:Niobium-titanium and niobium-tin alloys require liquid-helium cooling but deliver validated performance in 20+ tesla magnetic fields. MRI OEMs in the United States and Germany sustain procurement volumes despite helium conservation pressures from EU F-Gas Regulation.
- Iron-Based Superconductors:Emerging material platform with intermediate critical temperatures; Japanese national laboratories lead development funding through METI programs.
- Magnesium Diboride Superconductors:Cost-competitive intermediate-temperature option; research laboratories in Italy and Germany evaluate deployment for compact magnet systems.
Low-Temperature Superconductors hold the largest share; momentum sits with High-Temperature Superconductors.
Application:
Cost tier stratification separates premium imaging applications from emerging infrastructure deployments with unproven lifecycle economics.
- Magnetic Resonance Imaging:Dominant commercial volume anchored in clinical diagnostics; FDA device clearance pathways enforce rigorous magnet qualification timelines for OEMs.
- Power Transmission:Superconducting cables promise zero resistive losses for urban substations; South Korean and German utilities bundle 20-year cryogenic maintenance contracts to manage operational risk.
- Particle Accelerators:Scientific instrumentation demands persistent-current stability; CERN and Brookhaven National Laboratory procurements sustain niobium-tin wire volumes.
- Magnetic Levitation:Transportation applications require kilometer-scale conductor deployment; Japan's SCMaglev test line validates system integration at commercial speeds.
- Quantum Computing:Dilution refrigerator interconnects demand precision-fabricated coaxial cabling; specialized foundries serve this precision niche distinct from bulk power markets.
Magnetic Resonance Imaging generates the highest revenue concentration; Power Transmission is climbing the fastest.
End User:
Customer type determines procurement sophistication, with utilities and research laboratories operating under divergent technical specifications and funding mechanisms.
- Power Utilities:Grid operators in Germany, South Korea, and China evaluate superconducting cable pilots; capital intensity concerns slow adoption despite demonstrated loss reductions.
- Research Laboratories:National facilities in the United States, France, and Japan sustain baseline demand for high-field magnets and accelerator components.
- Transportation Firms:Maglev operators and urban transit authorities assess superconducting motor applications; deployment remains pre-commercial outside Japan.
- Telecommunication Companies:Emerging interest in superconducting RF filters for 5G infrastructure; volume negligible relative to power and imaging segments.
Power Utilities command the largest project scale; Research Laboratories provide the most stable demand visibility.
Deployment:
Supply concentration varies by fabrication format, with coated conductor manufacturing fragmenting across deposition methodologies while bulk forms consolidate around established metallurgical suppliers.
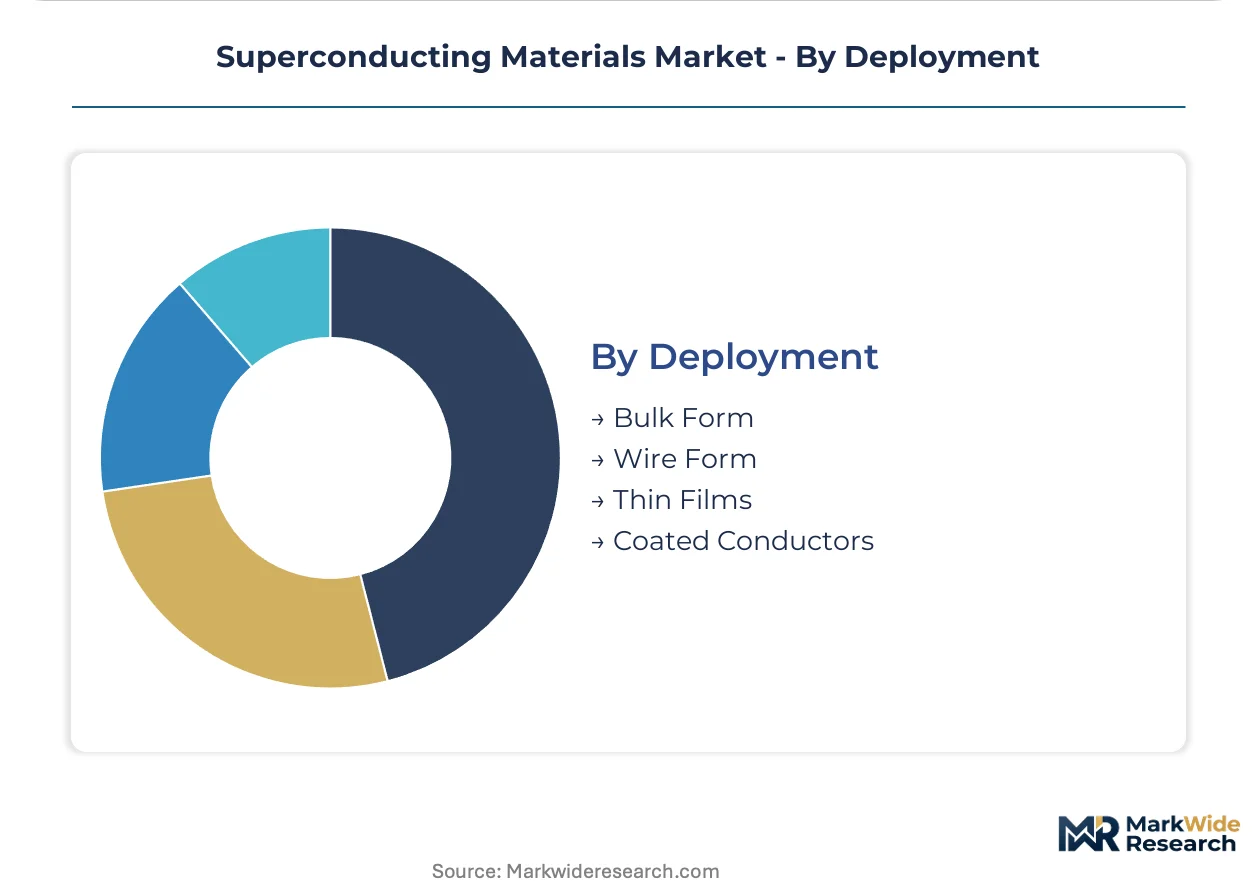
- Wire Form:Dominant value category spanning low-temperature and high-temperature architectures; Sumitomo Electric and Bruker secure long-term supply contracts through magnet OEM relationships.
- Coated Conductors:REBCO tape production expands fastest for grid and fusion applications; equipment vendors support both pulsed-laser and metal-organic chemical vapor deposition toolsets.
- Bulk Form:Sintered superconducting disks for magnetic bearings and fault-current limiters; Chinese refiners concentrate rare-earth supply for yttrium-barium-copper-oxide formulations.
- Thin Films:Specialized deposition for SQUID sensors and microwave devices; quantum computing control planes drive precision requirements.
Wire Form retains the largest installed base; Coated Conductors are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power utilities and fusion energy developers concentrate procurement across Germany, China, the United States, Japan, and South Korea, with each geography driving distinct superconducting material specifications.
United States
Fusion energy startups in Massachusetts and California place multi-year REBCO tape orders for compact reactor prototypes. The Department of Energy directs national laboratory funding toward high-field magnet development through FESAC program roadmaps. Brookhaven National Laboratory on Long Island sustains niobium-tin wire demand for accelerator upgrades.
Germany
Transmission operators TenneT and 50Hertz evaluate superconducting DC links for North Sea offshore wind clusters. EU F-Gas Regulation phase-down schedules force MRI OEMs toward conduction-cooled magnet designs by 2030. Siemens Energy anchors superconducting cable trials in Munich and Erlangen manufacturing corridors.
China
State Grid Corporation mandates fault-current limiter pilots in Shanghai and Shenzhen urban substations under MIIT technology roadmaps. Dual carbon goals accelerate superconducting cable deployment timelines for 220kV grid segments. Western Superconducting Technologies concentrates tape production in Xi'an for domestic fusion and grid applications.
Japan
Central Japan Railway Company validates kilometer-scale REBCO conductor deployment on the Yamanashi SCMaglev test line. METI programs fund iron-based superconductor development through national laboratory consortia. Furukawa Electric and Fujikura anchor coated conductor manufacturing in Tokyo and Osaka industrial basins.
South Korea
Korea Electric Power Corporation bundles 20-year cryogenic maintenance contracts with superconducting cable procurement for Seoul metropolitan grid segments. MFDS medical device regulations shape MRI magnet qualification pathways for domestic OEMs. LS Cable & System and SuNam drive REBCO tape production in Gumi and Changwon clusters.
Superconducting Materials Market Key Industry Players
Channel-controlling players compete with product-specialist players across deposition equipment, wire fabrication, and integrated cable system tiers. The market structure consolidates around magnet OEM supply relationships while fragmenting across coated conductor manufacturing methodologies. Three archetypes dominate: vertically integrated cable system suppliers, precision wire specialists serving scientific instrumentation, and deposition equipment vendors supporting hybrid manufacturing flows. Capacity expansion and strategic technology licensing represent the dominant competitive moves as fusion energy procurement creates anchored demand visibility.
Among Japanese industrial conglomerates, Furukawa Electric Co., Ltd., Fujikura Ltd., and Hitachi Ltd. occupy positions spanning wire fabrication through integrated cable system deployment. American Superconductor Corporation exemplifies the channel-controlling archetype through proprietary grid-scale architectures. Sumitomo Electric Industries Ltd. anchors the precision wire specialist tier with liquid-nitrogen-cooled production capabilities. Western Superconducting Technologies Co., Ltd. represents the emerging Chinese fabricator archetype serving domestic fusion and grid pilots. Bruker Corporation and SuperPower Inc. sit within the scientific-instrument and coated-conductor specialist segments respectively.
| Leading Market Players |
|---|
| Furukawa Electric Co., Ltd. |
| American Superconductor Corporation |
| Sumitomo Electric Industries Ltd. |
| Bruker Corporation |
| Fujikura Ltd. |
| Western Superconducting Technologies Co., Ltd. |
| Hitachi Ltd. |
| NEXANS SA |
| SuperPower Inc. |
| Others |
Cost & Logistics Intelligence
Rare-earth export quota volatility from Chinese refiners determines both REBCO tape pricing spreads and the geographic distribution of coated conductor manufacturing capacity. Buyers respond by negotiating multi-year offtake contracts with indexation clauses tied to yttrium and gadolinium spot markets, while suppliers diversify deposition equipment sourcing to reduce single-country dependency.
Pricing Analysis
Cost-plus contracts with London Metal Exchange rare-earth indexation dominate REBCO tape procurement, separating premium fusion-grade conductors from standard grid cables through critical current density certification tiers. Price differentiation rests on cryogenic maintenance bundling and field service network density rather than unit manufacturing cost alone. Cost compression in standard-grade cables is intensifying because Korean and German utilities consolidate procurement volumes around integrated 20-year service agreements. Research laboratories demonstrate the lowest price sensitivity due to grant-funded capital budgets, while urban grid operators in China negotiate aggressively against capital intensity benchmarks.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk assessment for non-Chinese cable manufacturers dependent on yttrium and gadolinium refined primarily in China, Japan, and Australia. Raw material inputs draw from rare-earth oxide concentrates, high-purity nickel-tungsten substrates, and specialized silver overlayer chemistries. Single-source vulnerability concentrates in Chinese rare-earth refining capacity, exposing tape foundries to export quota disruptions. Distribution runs through magnet OEM direct contracts for niobium-titanium wire, while coated conductors flow via utility procurement departments and national laboratory grant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Superconducting materials markets are approaching a platform-economics inflection where REBCO tape standardization for fusion energy creates interoperability lock-in effects analogous to semiconductor lithography nodes. The emergence of hybrid pulsed-laser and metal-organic chemical vapor deposition workflows signals ecosystem consolidation around performance-optimized conductor architectures.
For Market Incumbents: Harden supply relationships with national laboratory procurement offices through multi-year magnet development partnerships, insulating against fusion energy startups bypassing established qualification pathways. Prioritize backward integration into rare-earth refining joint ventures in Australia or Canada to offset Chinese export quota exposure. Lock in MRI OEM exclusivity via conduction-cooled niobium-tin formulations ahead of EU F-Gas Regulation phase-down deadlines. For New Entrants and Emerging Players: Quantum computing dilution refrigerator interconnects represent the most penetrable entry point, requiring precision-fabrication capabilities distinct from bulk power cable manufacturing and commanding premium margins through low volume tolerance. India's PLI scheme for advanced materials creates a second white-space opportunity for domestic wire production serving South Asian MRI and scientific instrument markets. Pursue technology licensing from Japanese iron-based superconductor consortia to differentiate from crowded REBCO tape competition. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down schedules through 2030 reshape the acquisition landscape toward conduction-cooled magnet specialists and closed-cycle refrigeration system providers. Five-to-ten-year viability favors vertically integrated cable system suppliers with captive cryogenic service networks rather than pure-play tape manufacturers. Monitor ITER and private fusion reactor construction milestones as the critical demand inflection signal for coated conductor capacity utilization.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Deposition Process Adoption | Equipment vendors supporting both PLD and MOCVD toolsets capture fusion energy procurement volumes. |
| Cryogenic Maintenance Service Bundling | Korean and German utilities internalize operational risk through 20-year integrated sourcing contracts. |
| Rare-Earth Refining Joint Ventures | Non-Chinese tape manufacturers secure yttrium supply chains against MIIT export quota volatility. |
| Conduction-Cooled Magnet Requalification | European MRI OEMs eliminate helium dependency ahead of EU F-Gas Regulation phase-down mandates. |
| Iron-Based Superconductor Development | Japanese national laboratories fund intermediate-temperature alternatives through METI program roadmaps. |
Research Approach
The analysis maps low-temperature superconductor wire fabrication, high-temperature coated conductor manufacturing, cryogenic system integration, and deposition equipment supply tiers, each validated through procurement directors at fusion energy developers, grid planning engineers at transmission operators, MRI magnet design leads, and national laboratory materials scientists. Primary interview intelligence triangulates against secondary sources including FERC interconnection filings, EU F-Gas Regulation implementation reports, MIIT technology roadmaps, and CERN procurement databases. Bottom-up segment sizing cross-checks against top-down market reconstruction across cooling architectures and fabrication formats.
Forecast assumptions hold fixed national hydrogen strategy funding allocations and fusion energy demonstration timelines while varying rare-earth export quota stringency, helium conservation policy enforcement, and superconducting cable pilot scale-up rates. Segmentation dimensions span product type, application, end user, and deployment format with regional regulatory cluster overlays. CAGRs derive from installed base replacement cycles, project pipeline visibility, and technology substitution elasticity parameters. Fusion energy prototype procurement schedules and urban grid fault-current limiter deployment mandates provide industry-specific demand anchors.
Practitioners should monitor ITER construction delays, Chinese rare-earth export license approvals, and EU F-Gas Regulation refrigerant quota allocations for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Europe Advanced Building Materials Market
Advanced Materials
Rigid Foam Market
Advanced Materials
Bioactive Glass Market
Advanced Materials
Global Thermal Interface Materials Market
Advanced Materials
High Nickel Cathode Materials Market
Advanced Materials
Cathode Active Material Market
Advanced Materials
Chemistry 4.0 Market
Advanced Materials
Thermal Conductive Material Market
Advanced Materials
Glass Reinforced Vinyl Ester (GRV) Market
Advanced Materials
Synthetic Graphite Market
Advanced Materials
North America Advanced Phase Change Materials Market
Advanced Materials
Magnetic Shielding Sheets Market
Advanced Materials
Lab-Grown Rough Diamond Market
Advanced Materials
Europe Graphene Market
Advanced Materials
Organic Aerogel Market
Advanced Materials
Global Electrochromic Materials Market