
 3D Printing Iron Powder Market | 2026-2036
3D Printing Iron Powder Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing Iron Powder Market Insights
Aftermarket service revenue from powder recycling and parameter optimization is narrowing as equipment OEMs bundle these capabilities into initial system sales. Höganäs AB leverages its integrated atomization and alloy development operations to control feedstock quality from ore to final powder specification. GKN Powder Metallurgy anchors its position through captive demand from aerospace and automotive powertrain programs. Sandvik competes by extending its materials science expertise from cemented carbides into high-performance tool steel powders for additive manufacturing.
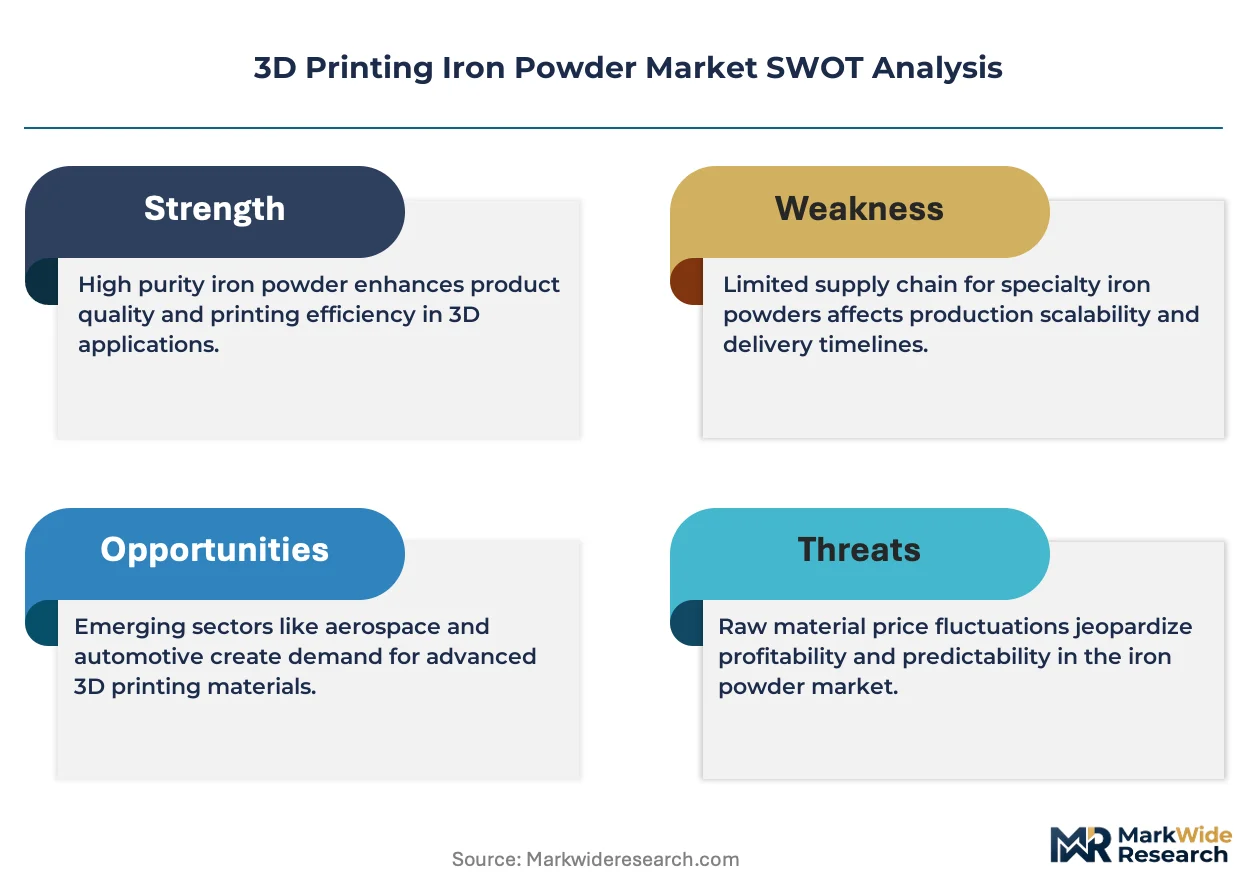
3D printing iron powder encompasses ferrous metal feedstocks engineered with controlled particle size distributions, typically 15–45 microns, and specific oxygen content below 0.1% to ensure laser or electron beam processability. These powders enable near-net-shape fabrication of complex geometries that subtractive machining cannot achieve, serving critical applications in weight-sensitive structural components. Stainless steel grades dominate current volume due to established supply chains and broad corrosion resistance requirements across medical and industrial segments. Tool steel powders represent the fastest-growing category as mold and die producers adopt conformal cooling channels to reduce cycle times. Alloy steel formulations for aerospace turbine components command premium positioning because of lengthy qualification protocols and limited qualified suppliers.
FDA device regulations and EU MDR conformity requirements shape material traceability and biocompatibility testing for medical implant applications of iron-based powders. REACH registration obligations and RoHS substance restrictions govern chemical composition disclosures and restricted element thresholds for European market access. China's GB standards for metal additive manufacturing feedstocks, administered by SAMR, establish particle morphology and purity benchmarks that influence import competitiveness. Stakeholders must monitor evolving qualification protocols from aviation authorities and medical device regulators as these frameworks increasingly dictate which powder grades achieve production approval.
Market Dynamics
Equipment OEMs bundling powder recycling and parameter optimization into initial system sales is compressing aftermarket service revenue streams and forcing feedstock suppliers to compete on integrated solution value rather than standalone powder specifications.
Growth Catalysts
- Conformal cooling channel adoption:Mold and die producers in automotive and consumer electronics sectors are specifying tool steel powders with optimized thermal conductivity to reduce injection molding cycle times by 15–40%.
- REACH compliance harmonization:ECHA registration obligations for iron-based feedstocks are consolidating qualified supplier pools, advantaging vertically integrated atomizers with in-house chemical certification capabilities.
- Ruhr industrial cluster concentration:Germany's automotive and tooling OEMs integrating metal additive manufacturing into serial production workflows are creating captive demand for certified 18Ni300 maraging steel and H13 tool steel powders.
Market Restraints
- Scrap metal price volatility:Atomization feedstock costs fluctuate with ferrous scrap indices, compressing margins for independent powder producers lacking long-term ore supply contracts.
- Plasma atomization supply concentration:Premium spherical powder production capacity clusters among three specialized equipment operators, creating bottleneck risk for aerospace-qualified grades.
- Limited electron beam process compatibility:Conventional water-atomized powders exhibit excessive satellite formation and oxygen pickup above 0.08%, excluding them from electron beam powder bed fusion qualification protocols.
Strategic Opportunities
- India PLI scheme alignment:India's production-linked incentive scheme for advanced manufacturing is attracting metal 3D printing system deployments in medical implant and aerospace subcontracting clusters around Bengaluru and Hyderabad.
- Copper-iron bimetal convergence:Hybrid heat exchanger applications combining laser powder bed fusion iron structural cores with copper thermal pathways are opening design space unavailable to single-material processes.
- Digital inventory substitution:Spare part digitization mandates from industrial asset operators are converting physical warehousing demand to on-demand powder consumption for legacy machinery components.
Industry Challenges
- Multi-parameter technician scarcity:Laser power, scan speed, and hatch spacing optimization for novel iron alloys requires metallurgists with cross-training in thermal modeling and machine operation, a profile rare outside aerospace primes.
- Part qualification timeline compression:FAA and EASA airworthiness certification for flight-critical iron-based components demands 18–36 month build-and-test cycles that delay revenue recognition for powder suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing Iron Powder Market |
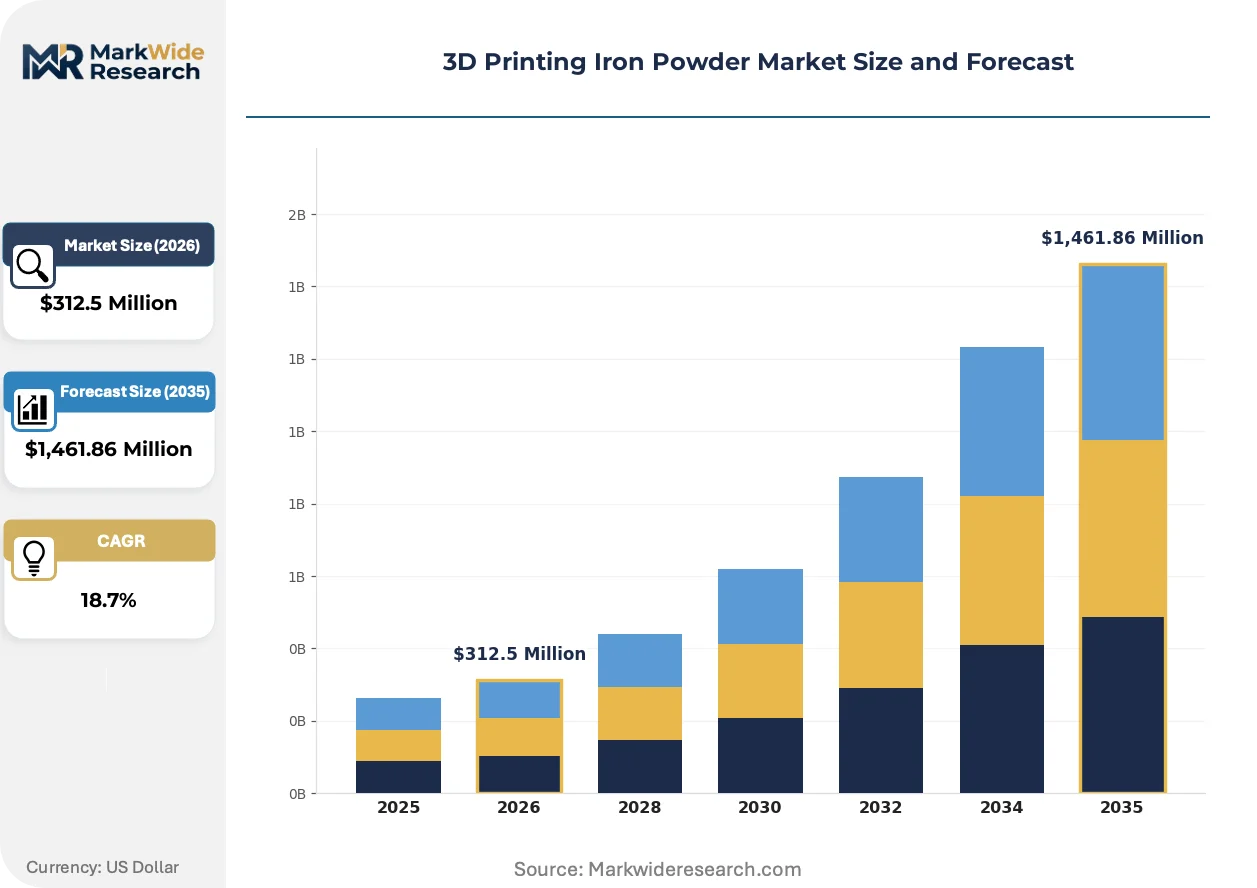
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,461.86 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Iron, Stainless Steel, Tool Steel, Alloy Steel Application: Aerospace, Automotive Components, Medical Devices, Industrial Machinery End User: Manufacturers, Research Institutions, Prototyping Services, Educational Entities Form: Powder, Granules, Pellets, Blends |
| Companies Covered | Höganäs AB, Rio Tinto Metal Powders, CNPC Powders, GKN Powder Metallurgy, Sandvik, ATI, JFE Steel Corporation, Carpenter Technology Corporation, Evonik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing Iron Powder Market Trends and Innovations
Plasma atomization and ultrasonic powder atomization are displacing conventional gas atomization for high-oxygen-sensitivity iron alloys, while regulatory frameworks in Europe and North America harden material traceability requirements beyond batch-level documentation.
Ultrasonic atomization of molten iron streams is rendering obsolete water-atomized powder for laser powder bed fusion applications. Medical implant manufacturers in Switzerland and orthopedic device suppliers in Massachusetts are qualifying these low-satellite, sub-20-micron distributions for spinal cage and cranial plate production. The structural consequence is a bifurcation between commodity water-atomized feedstock for binder jetting and premium spherical powder for fusion-based processes.
EU MDR conformity requirements are extending material traceability from powder lot to finished implant, with notified bodies demanding oxygen, nitrogen, and hydrogen content documentation at 50ppm resolution. Device manufacturers serving European markets are consolidating supplier relationships to three qualified atomizers with ISO 13485 certification. The segment most affected is orthopedic trauma plates, where biocompatibility testing timelines now exceed 24 months for new iron-manganese biodegradable alloy formulations.
Aftermarket service unbundling is reversing as equipment OEMs capture powder lifecycle value. Renishaw and EOS are integrating real-time melt pool monitoring with closed-loop parameter adjustment, eliminating standalone consulting engagements previously sold to tier-two aerospace machine shops. This consolidation is most visible in Germany's automotive supplier base, where in-house metallurgy teams are shrinking and machine OEMs assume full process liability for qualified part production.
3D Printing Iron Powder Market Segmentation
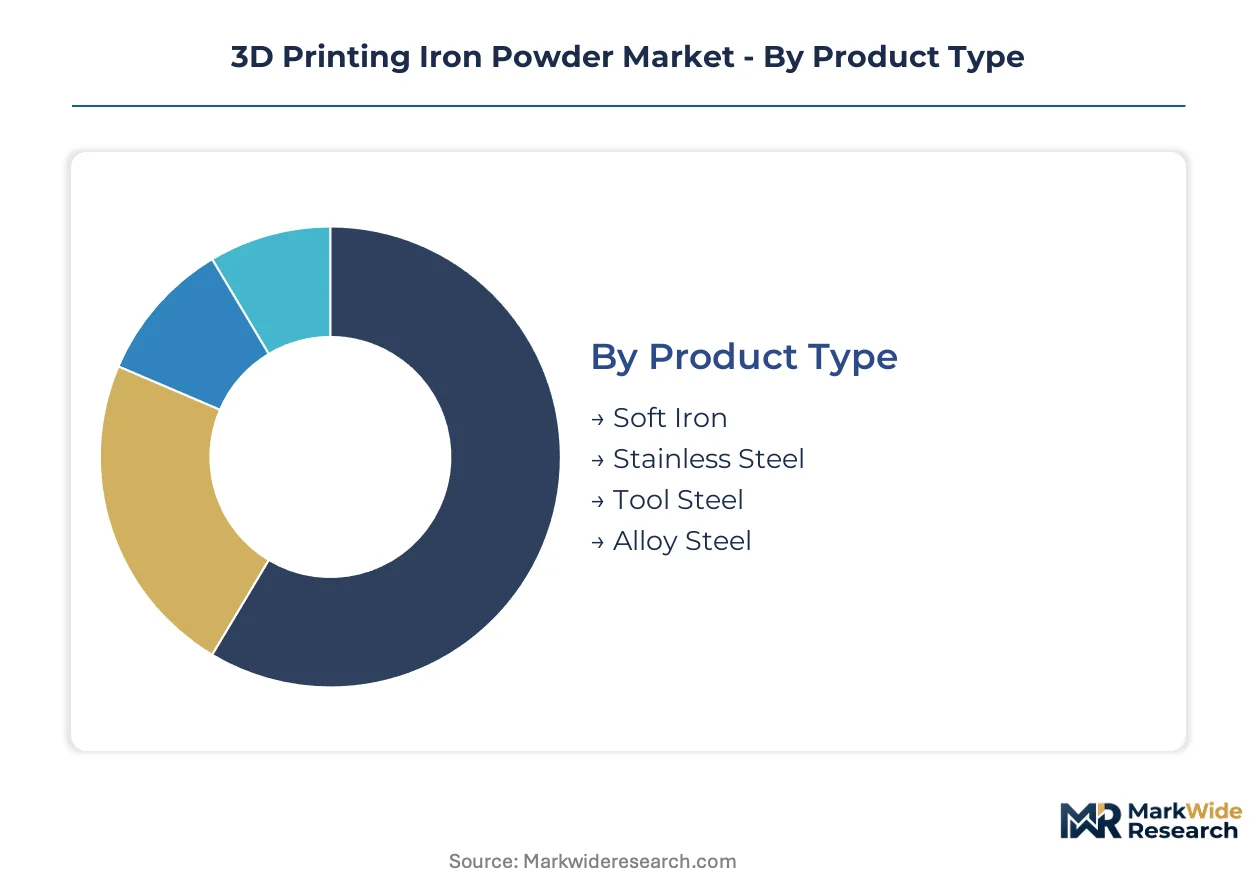
Iron powder segmentation reveals how material specifications align with distinct thermal and mechanical demands across additive manufacturing platforms. Process constraints and end-use qualification requirements fragment supply into incompatible grade categories.
Product Type:
End-use spectrum spans soft magnetic cores through aerospace turbine alloys, with each formulation demanding atomization methods matched to oxygen sensitivity and particle morphology requirements.
- Stainless Steel:Austenitic and martensitic grades dominate current powder volumes due to established corrosion resistance protocols across medical and food-processing equipment. Demand concentrates in Switzerland's orthopedic device cluster, where ISO 13485-certified atomizers supply spinal fixation manufacturers facing EU MDR traceability mandates.
- Tool Steel:H13 and 18Ni300 maraging formulations enable conformal cooling channels that reduce injection molding cycle times. German automotive suppliers in the Ruhr industrial cluster specify these grades for serial production of hot-runner mold inserts, with captive demand from BMW and Volkswagen powertrain programs.
- Soft Iron:High-purity ferromagnetic feedstocks serve electric motor laminations and magnetic shielding applications with minimal hysteresis loss.
- Alloy Steel:Nickel-cobalt superalloy variants command premium positioning for turbine blade repair and rocket engine components.
The dominant share belongs to Stainless Steel, while Tool Steel is closing the gap fastest.
Application:
Cost tier differentiation separates flight-critical aerospace qualification from prototyping workflows where parameter optimization costs dominate material selection.
- Aerospace:FAA and EASA airworthiness certification demands 18–36 month build-and-test cycles for engine brackets and landing gear components. Plasma-atomized spherical powders with oxygen content below 0.08% qualify for electron beam powder bed fusion, with supply bottlenecking among three specialized equipment operators.
- Medical Devices:FDA device regulations and EU MDR conformity requirements enforce 50ppm-resolution documentation of oxygen, nitrogen, and hydrogen content. Massachusetts-based cranial plate manufacturers and Swiss spinal cage producers consolidate supplier relationships to ISO 13485-certified atomizers with full lot-to-implant traceability.
- Automotive Components:Serial production integration in Germany drives specification of 18Ni300 for structural brackets where weight reduction offsets powder cost premiums.
- Industrial Machinery:Legacy equipment spare part digitization converts physical warehousing to on-demand powder consumption for obsolete component geometries.
Aerospace commands the highest value per kilogram, though Medical Devices is expanding most quickly as bioresorbable iron-manganese alloys advance through extended biocompatibility timelines.
End User:
Customer type determines whether procurement prioritizes certified batch documentation or experimental parameter development.
- Manufacturers:Tier-one automotive and aerospace primes specify qualified powder grades with locked process parameters, transferring full liability to equipment OEMs like EOS and Renishaw for production outcomes.
- Research Institutions:Alloy development programs at universities and national laboratories demand small-batch atomization with custom composition flexibility.
- Prototyping Services:Bureau customers optimize for machine utilization rates across multiple material grades, favoring powder recyclability and rapid parameter switching.
- Educational Entities:Training programs prioritize cost-efficient water-atomized grades for student exposure to laser powder bed fusion fundamentals.
Manufacturers absorb the majority of certified powder volume, while Research Institutions are gaining share fastest through government-funded additive manufacturing initiatives.
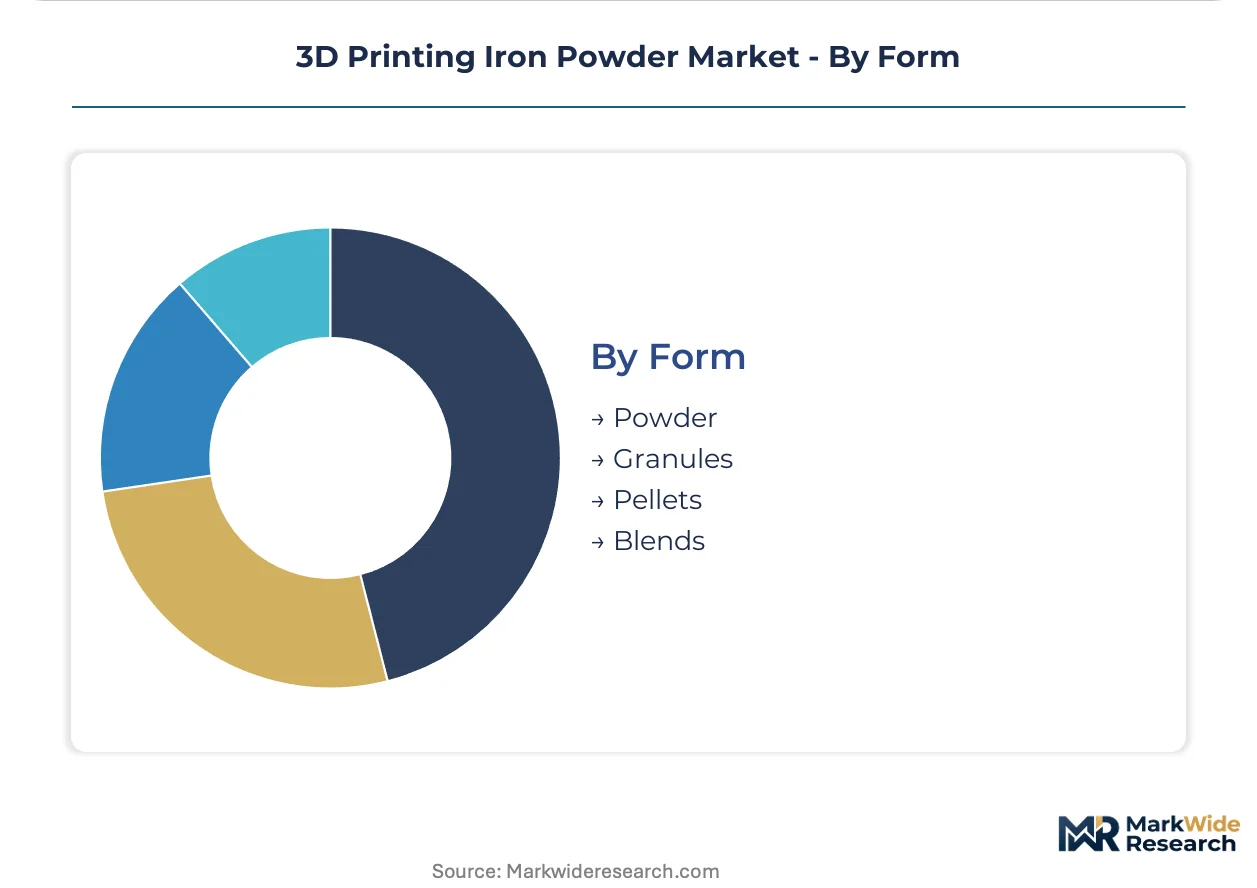
Form:
Physical presentation dictates compatibility with specific deposition mechanisms and handling automation.
- Powder:Spherical 15–45 micron distributions dominate laser and electron beam powder bed fusion, with plasma atomization displacing water atomization for oxygen-sensitive grades.
- Granules:Coarser irregular morphologies serve binder jetting and directed energy deposition where layer thickness tolerance relaxes.
- Pellets:Compacted feedstocks enable wire-fed laser deposition for large-scale repair applications.
- Blends:Pre-mixed elemental powders allow in-situ alloy formation during melting, reducing inventory complexity for niche compositions.
Powder maintains overwhelming volume dominance, though Blends are climbing the fastest as distributed manufacturing models seek to minimize SKU proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India's emerging aerospace subcontracting hubs exhibit acute price sensitivity to powder premiums, while German automotive OEMs absorb cost increases without volume reduction due to locked qualification protocols.
Germany
Automotive powertrain programs at BMW and Volkswagen drive captive consumption of 18Ni300 maraging steel and H13 tool steel powders. REACH registration obligations administered by ECHA consolidate qualified supplier pools to vertically integrated atomizers. The Ruhr industrial cluster hosts serial production workflows where metal additive manufacturing replaces conventional tooling for hot-runner mold inserts.
United States
FAA airworthiness certification demands for engine brackets and landing gear components sustain premium pricing for plasma-atomized spherical grades. FDA device regulations enforce 50ppm-resolution documentation of interstitial elements for Massachusetts-based cranial plate manufacturers. Greater Boston's orthopedic device corridor concentrates demand for ISO 13485-certified feedstock with full lot-to-implant traceability.
China
SAMR-administered GB standards for metal additive manufacturing feedstocks establish particle morphology benchmarks that filter import competitiveness. Domestic atomizers scale gas atomization capacity for stainless steel grades serving medical and food-processing equipment. Yangtze River Delta tooling producers adopt conformal cooling channels to reduce injection molding cycle times.
India
The PLI scheme for advanced manufacturing attracts metal 3D printing system deployments around Bengaluru and Hyderabad medical implant clusters. Price-sensitive aerospace subcontractors prioritize cost-efficient water-atomized grades for non-flight-critical components. CDSCO regulatory pathways for orthopedic implants remain under development, delaying premium powder qualification timelines.
Switzerland
Swissmedic and EU MDR conformity requirements extend material traceability from powder lot to finished spinal cage. Orthopedic device manufacturers in the Lake Geneva region consolidate supplier relationships to three qualified atomizers with in-house chemical certification. Premium positioning for biodegradable iron-manganese alloys supports 24-month biocompatibility testing investments.
3D Printing Iron Powder Market Competitive Landscape
Integrated atomizers and specialized powder metallurgy divisions split the market between captive supply chains and merchant feedstock distribution. Three strategic archetypes dominate: ore-to-powder vertical integrators controlling atomization and alloy development; diversified materials science conglomerates extending cemented carbide expertise into tool steel formulations; and steel mill-affiliated powder operations leveraging ferrous scrap access. Competitive moves concentrate on ECHA registration consolidation and plasma atomization capacity expansion for aerospace-qualified grades.
Within the vertical integration tier, Höganäs AB anchors Scandinavian supply of controlled-oxygen feedstocks, while GKN Powder Metallurgy occupies a position bridging captive aerospace demand with automotive powertrain programs. Sandvik exemplifies materials science extension from cemented carbides into high-performance tool steel powders. These three represent distinct strategic postures: ore-origin control, program-locked demand absorption, and cross-material technology transfer.
| Leading Market Players |
|---|
| Höganäs AB |
| Rio Tinto Metal Powders |
| CNPC Powders |
| GKN Powder Metallurgy |
| Sandvik |
| ATI |
| JFE Steel Corporation |
| Carpenter Technology Corporation |
| Evonik |
| Others |
Pricing and Supply Chain Analysis
Plasma atomization capacity underutilization in North American aerospace-qualified facilities is compressing spot pricing for premium spherical grades while forcing European suppliers to absorb fixed costs through long-term offtake contracts with German automotive primes.
Pricing Analysis
Aftermarket service bundling into initial system sales now drives lifetime value capture for equipment OEMs like EOS and Renishaw. Three-tier pricing structure across aerospace-qualified, medical-grade, and industrial-standard levels separates plasma-atomized spherical powder from water-atomized feedstock. Cost compression in medical-grade tiers is intensifying because ISO 13485-certified atomizers face consolidated buyer pools under EU MDR traceability mandates. Indian aerospace subcontractors exhibit acute price sensitivity, while German Ruhr cluster OEMs absorb premiums without volume reduction due to locked qualification protocols.
Supply Chain Analysis
Export-control restrictions on plasma atomization equipment limit technology transfer to Chinese and Indian domestic producers, constraining local supply development. Feedstock supply concentrates in Sweden, Germany, and the United States, with Höganäs AB and GKN Powder Metallurgy anchoring European capacity. Raw material sourcing draws from ferrous scrap indices, high-purity ore contracts, and nickel-cobalt alloy streams. Single-source vulnerability plagues aerospace-qualified spherical powder production, where three specialized equipment operators control electron beam-compatible grades. Distribution runs through direct mill relationships for tier-one primes and merchant distributors for prototyping services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as equipment OEMs capture powder lifecycle value through integrated melt pool monitoring and closed-loop parameter adjustment, collapsing standalone aftermarket revenue streams into bundled system sales.
For Market Incumbents: Build regulatory certification moats by securing ECHA REACH registrations for novel iron-manganese biodegradable alloys ahead of EU MDR timeline compression. Deepen backward integration into captive atomization capacity for plasma-spherical grades to defend against emerging Chinese gas atomizers. Channel control through locked qualification protocols with BMW and Volkswagen powertrain programs protects pricing power. For New Entrants and Emerging Players: Mid-market tool steel powders for conformal cooling applications in Yangtze River Delta injection molding clusters represent the most penetrable entry point, bypassing aerospace qualification bottlenecks. India's PLI scheme medical implant clusters around Bengaluru offer second-mover advantage as CDSCO regulatory pathways mature. Partner with Renishaw or EOS for parameter development outsourcing to accelerate machine qualification timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across plasma atomization capacity expansion, favoring asset-light powder recyclers and parameter optimization software plays over greenfield atomization builds. Long-term viability across the next decade hinges on FDA and EASA regulatory alignment for flight-critical components. Acquisition targets should display ISO 13485 certification with locked automotive supply agreements. Watch for FAA airworthiness certification timeline compression as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Atomization Capacity Expansion | Secures electron beam powder bed fusion qualification for aerospace turbine component repair applications. |
| REACH Registration Consolidation | ECHA compliance for iron-manganese alloys locks out non-vertically integrated feedstock competitors. |
| Closed-Loop Parameter Integration | EOS and Renishaw bundle real-time melt pool monitoring to capture previously standalone consulting revenue. |
| Bioresorbable Alloy Development | Iron-manganese formulations for spinal cages require 24-month biocompatibility investment under Swissmedic oversight. |
| Digital Inventory Substitution Partnerships | Industrial asset operators convert physical warehousing to on-demand powder consumption for obsolete machinery. |
Research Methodology
The analysis maps stainless steel, tool steel, soft iron, and alloy steel sub-sectors, each validated through powder metallurgy directors, additive manufacturing engineers at tier-one automotive suppliers, orthopedic device procurement managers, and plasma atomization equipment operators. Primary interviews combined with secondary validation from ECHA registration databases, FDA 510(k) filings, SAMR GB standard publications, and SEC 10-K disclosures from listed materials companies. Bottom-up powder consumption estimates triangulated against top-down equipment installation data across the analysis window.
Assumptions held fixed include regulatory timeline stability for FAA and EASA airworthiness protocols, while plasma atomization capacity expansion rates and ferrous scrap price indices were varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type, application tier, end-user category, and physical form factor throughout the forecast period. CAGRs derived from regression against qualified part production volumes and machine utilization rates at German Ruhr cluster facilities. Industry-specific inputs included EU MDR traceability mandate implementation pace and India PLI scheme disbursement timelines.
Practitioners should monitor ECHA registration consolidation patterns and CDSCO orthopedic implant pathway finalization for early signals of supplier pool restriction. Forecasts reflect assumptions of stable REACH compliance costs and continued electron beam process adoption in aerospace. Material shifts in FAA airworthiness certification timelines or SAMR import restriction tightening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
Global Metal Additive Manufacturing Market
3D Printing Materials
3D Printing Powder Market
3D Printing Materials
Thermoformed Plastics for Printing Market
3D Printing Materials
Aerospace 3D Printing Materials Market
3D Printing Materials
3D Printing Applications Polymers Market
3D Printing Materials
Polypropylene in 3D Printing Market
3D Printing Materials
Polyamide 12 Powder for High-Performance 3D Printing Market
3D Printing Materials
3D Printing Elastomers Market
3D Printing Materials
3D Printing Materials Market
3D Printing Materials
Middle East 3D Printing Materials Market
3D Printing Materials
3D Printing Consumables Market
3D Printing Materials
3D Printing Photopolymers Market
3D Printing Materials
3D Printing Materials and Services Market
3D Printing Materials
3D Printing Coating Market
3D Printing Materials
Graphene in 3D Printing Market
3D Printing Materials
Low-Temperature Flow Improver Additives for 3D Printing Resins Market