
 Organic Scintillators Market | 2026-2036
Organic Scintillators Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Scintillators Market Analysis
Modular detector array configurations is recalibrating how research laboratories and nuclear medicine departments evaluate procurement costs against upgrade flexibility. Saint-Gobain Crystals anchors European supply through captive crystal growth capabilities and long-standing CERN supplier status. Eljen Technology leverages its plastic scintillator specialization to dominate radiation portal monitor installations at border security checkpoints. Inrad Optics sustains niche positioning through precision optical polishing for scintillator-photodetector coupling interfaces.
Organic scintillators are luminescent materials—typically anthracene, stilbene, or p-terphenyl derivatives in polymer matrices—that convert ionizing radiation into visible photons detectable by photomultiplier tubes or silicon photomultipliers, with decay constants ranging from sub-nanosecond to tens of nanoseconds depending on host material and dopant concentration. Their primary purpose spans radiation spectroscopy, particle physics tracking, and medical imaging where pulse-shape discrimination between neutron and gamma events proves critical. Plastic scintillators occupy the volume tier due to low cost and machinability for large-area detectors, while crystal scintillators command premium positioning in nuclear medicine where energy resolution directly impacts diagnostic accuracy. Silicon photomultipliers represent the fastest-growing technology segment as magnetic-field immunity and compact footprint displace photomultiplier tubes in next-generation PET-MRI systems.
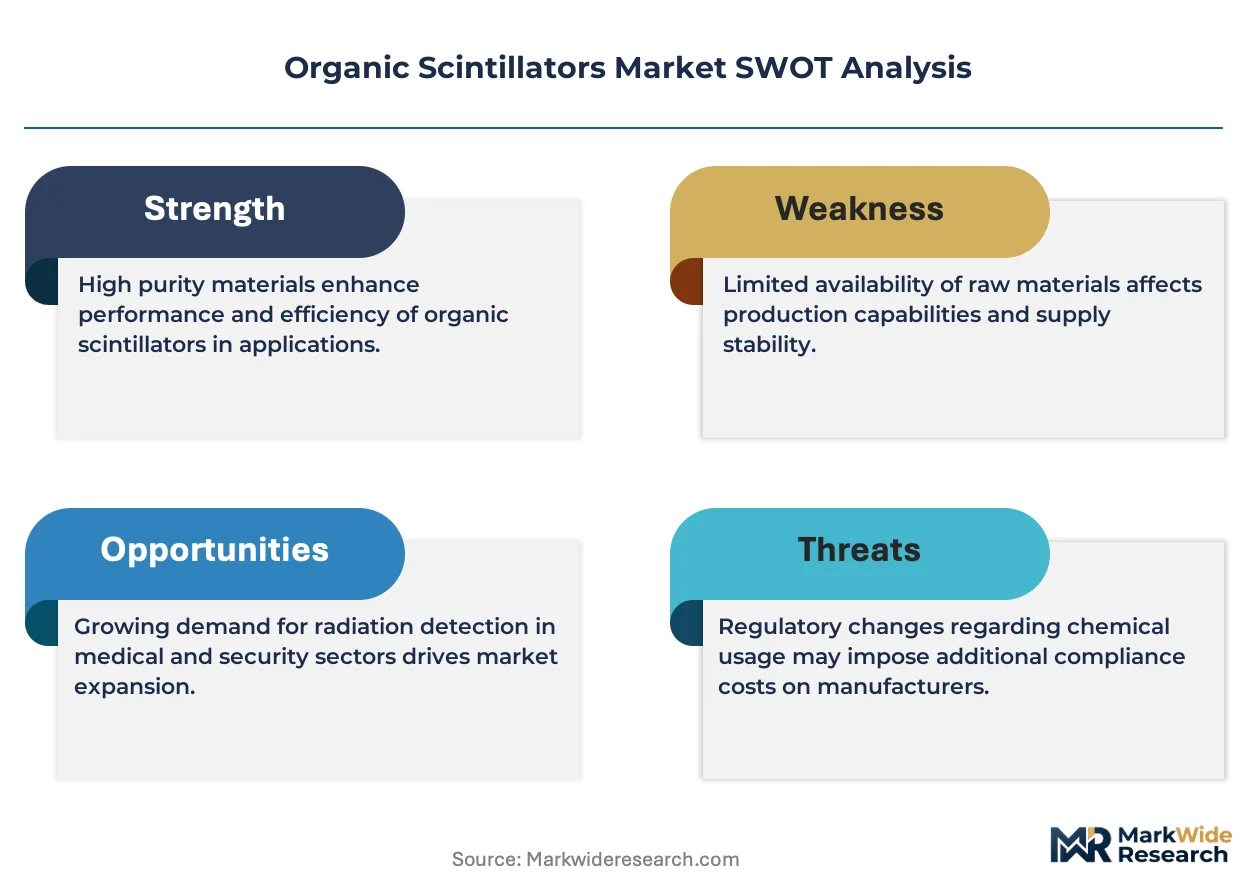
The FDA's radiological health program and EPA environmental radiation monitoring mandates shape product certification requirements and procurement specifications across North American end users. REACH restrictions on aromatic hydrocarbons and RoHS substance thresholds constrain European formulation choices for liquid and plastic scintillator bases. Stakeholders must monitor how NRC licensing requirements for nuclear power plant radiation monitoring systems evolve alongside photodetector technology transitions, as compliance timelines will determine competitive positioning between incumbent and emerging scintillator-detector pairings.
Market Dynamics
Silicon photomultiplier displacement of photomultiplier tubes is restructuring detector subsystem economics across medical imaging and particle physics installations, forcing scintillator manufacturers to recalibrate optical coupling specifications and quality assurance protocols.
Growth Catalysts
- PET-CT system procurement:Hospital networks in Germany are expanding crystal scintillator array purchases for molecular imaging suites, sustaining above-average replacement cycles.
- REACH compliance adaptation:European reformulation of liquid scintillator bases to meet aromatic hydrocarbon restrictions is creating certified-supplier premiums for compliant producers.
- Radiation portal monitor deployment:Border security agencies are specifying plastic scintillator panels for gamma-neutron discrimination at checkpoint infrastructure.
Market Restraints
- Anthracene supply concentration:Purified organic crystal feedstock depends on limited specialty chemical producers in Central Europe, exposing formulations to input volatility.
- Photodetector transition friction:Silicon photomultiplier adoption requires redesigned optical interfaces, delaying certification timelines for legacy scintillator-PMT pairings.
- Alternative detector competition:Inorganic crystal alternatives including cerium-doped lanthanum bromide capture premium spectroscopy applications with superior energy resolution.
Strategic Opportunities
- PET-MRI convergence:Magnetic-field-immune detector configurations are opening specification opportunities for scintillator-SiPM modules in hybrid imaging systems.
- Helmholtz research network expansion:German federal laboratory instrument refresh programs are concentrating demand for neutron-gamma discrimination detectors.
- EPA environmental monitoring mandates:North American atmospheric radiation surveillance networks are specifying field-deployable liquid scintillator systems for tritium detection.
Industry Challenges
- Optical polishing precision:Scintillator-photodetector coupling interfaces require sub-micron surface finish capabilities that concentrate among specialized optical fabricators.
- FDA radiological health verification:Updated performance standards for radiation detection equipment are extending type-approval timelines for new scintillator formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Scintillators Market |
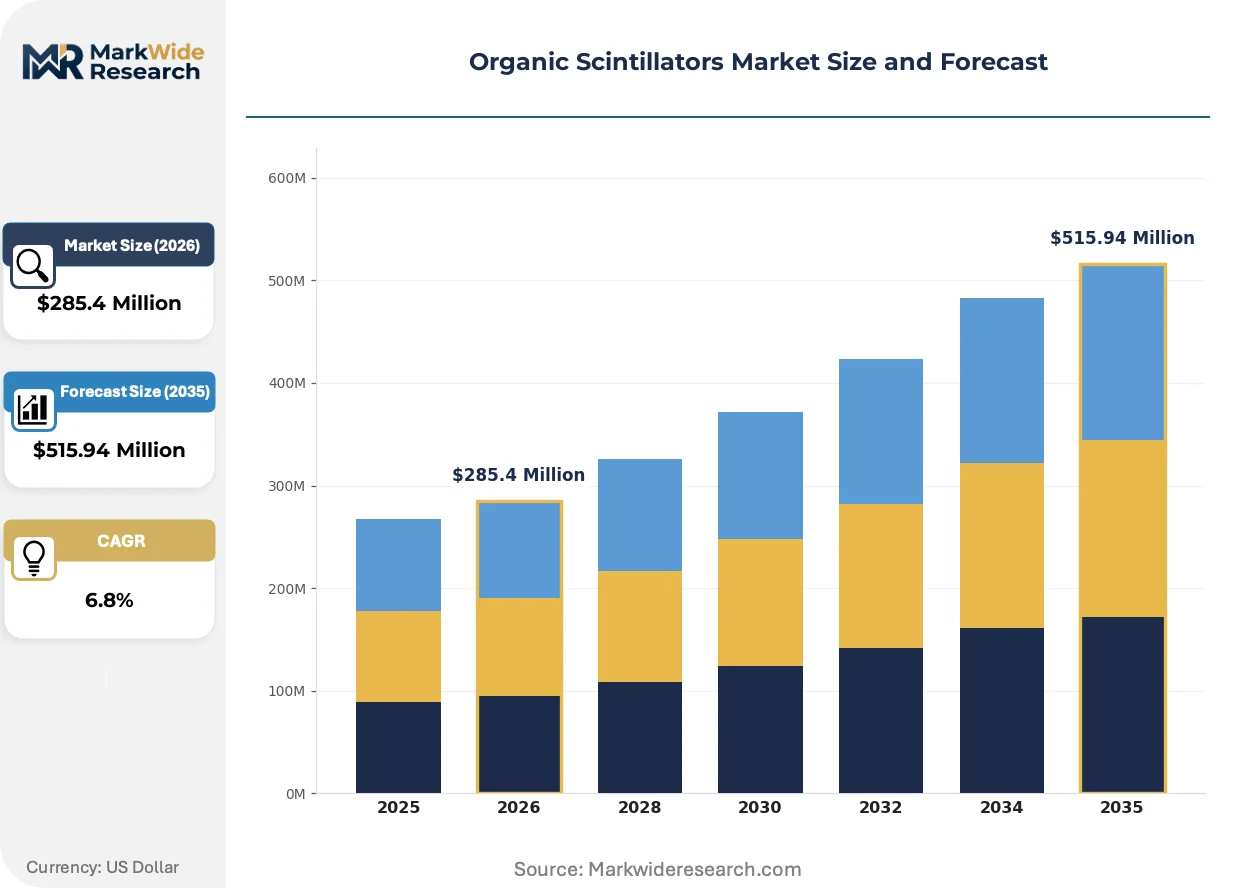
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Scintillators, Liquid Scintillators, Crystal Scintillators, Fiber Scintillators Application: Nuclear Medicine, Radiation Detection, High Energy Physics, Medical Imaging End User: Healthcare Facilities, Research Laboratories, Nuclear Power Plants, Safety & Security Agencies Technology: Photomultiplier Tubes, Silicon Photomultipliers, Avalanche Photodiodes, Hybrid Detectors |
| Companies Covered | Inrad Optics, Eljen Technology, Saint-Gobain Crystals, ME Taylor Engineering, Advatech UK Limited, EPIC Crystal, Detec, Cryos-Beta, Rexon Components, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Scintillators Market Emerging Trajectories
Pulse-shape discrimination algorithms and solid-state photodetector integration are compressing the performance gap between plastic and crystal scintillator categories while enabling new application architectures.
Machine learning-based pulse-shape analysis is automating neutron-gamma event classification in real-time spectroscopy systems. Research laboratories at CERN and DESY are deploying these algorithms in liquid scintillator calorimeters. The technology is automating data processing pipelines that previously required manual calibration, reducing specialist labor intensity in high-event-rate environments.
RoHS substance thresholds are constraining European plastic scintillator formulation choices for consumer-adjacent applications. Manufacturers are reformulating polymer matrices to eliminate restricted phthalate plasticizers while maintaining light output efficiency. Medical device producers in Germany and France are prioritizing pre-certified scintillator assemblies to avoid downstream compliance verification delays.
Modular detector array configurations are fragmenting procurement decisions across research consortia. University physics departments are unbundling scintillator crystal supply from integrated detector system purchases, sourcing crystals directly from Saint-Gobain while contracting separate photodetector integration. This pattern concentrates in German-speaking research clusters where Helmholtz center technical specifications set de facto standards for affiliated institutions.
Organic Scintillators Market Segmentation
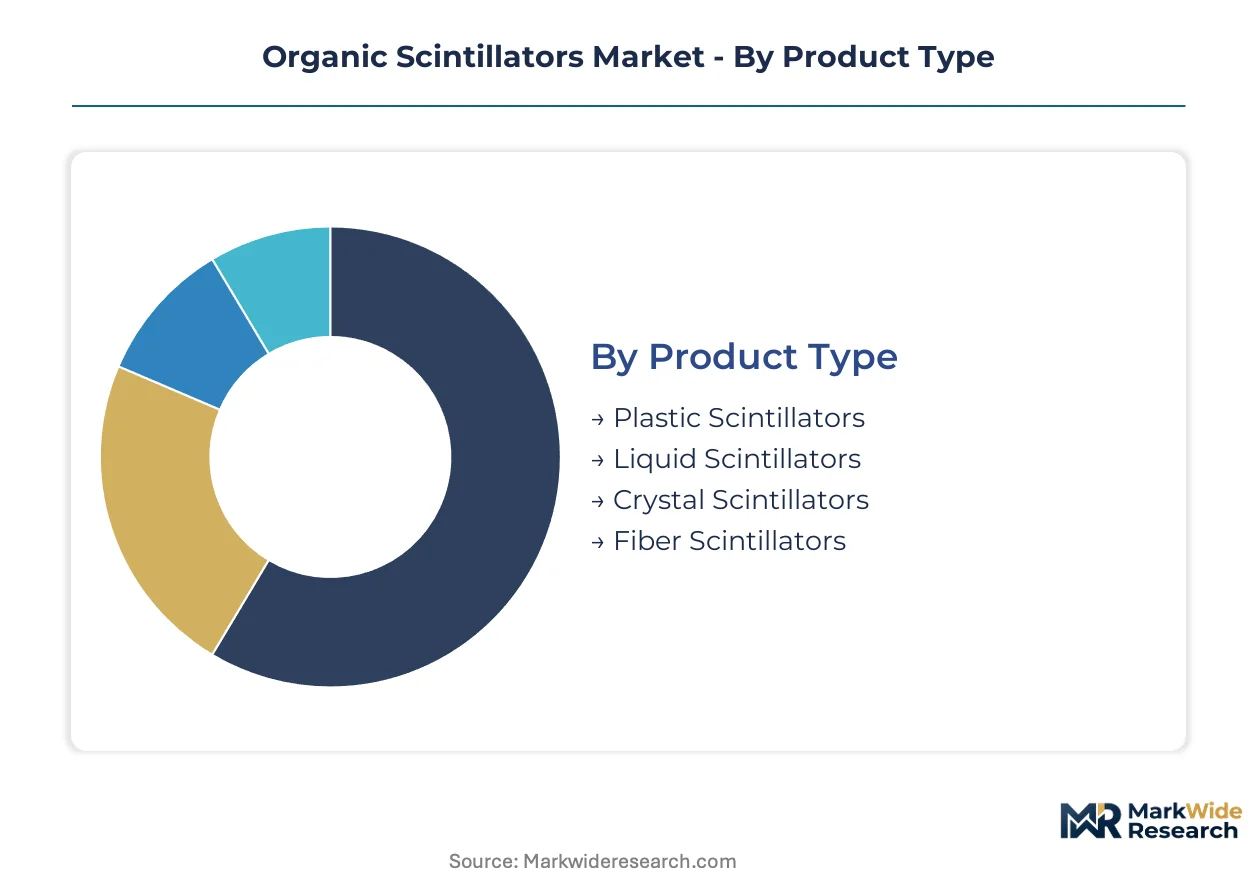
Scintillator procurement decisions fragment across performance requirements, regulatory environments, and integration complexity. Each segmentation axis reveals distinct supplier-customer dynamics that reshape competitive positioning.
Product Type:
Standardization dominates at the plastic and liquid tiers where formulation chemistry permits volume manufacturing, while crystal growth and fiber drawing demand bespoke process control.
- Plastic Scintillators:Polymer matrices doped with fluorescent compounds enable machining into large-area panels for radiation portal monitors. Border security agencies in Germany specify these for gamma-neutron discrimination at checkpoint infrastructure. Leading the category by volume: Plastic Scintillators. Growing fastest: Crystal Scintillators.
- Liquid Scintillators:Organic solvents dissolved with primary and secondary solutes deliver homogeneous detection volumes for environmental tritium monitoring. EPA atmospheric surveillance networks in the United States are field-deploying certified systems for aqueous sample analysis. REACH aromatic hydrocarbon restrictions are forcing European reformulation investments.
- Crystal Scintillators:Anthracene and stilbene single crystals provide superior energy resolution for PET-CT diagnostic suites. Hospital networks concentrate procurement in Germany where Helmholtz center specifications set technical standards.
- Fiber Scintillators:Polystyrene core-silica cladding structures enable flexible routing in compact detector geometries. CERN tracking systems utilize these for particle physics calorimetry where space constraints dominate.
Volume leadership sits with plastic formulations. Steepest expansion trajectory: crystal categories driven by medical imaging upgrade cycles.
Application:
End-use requirements diverge sharply between clinical settings demanding regulatory certification and research environments prioritizing experimental flexibility.
- Nuclear Medicine:PET-CT and SPECT systems require crystal arrays with precise light output uniformity for quantitative imaging. FDA radiological health regulations are tightening performance verification standards for equipment approval. German hospital networks sustain above-average replacement cycles through federal procurement programs.
- Radiation Detection:Portal monitors and handheld survey instruments utilize plastic scintillators for cost-sensitive large-area coverage. Eljen Technology dominates border security installations through specialized formulation expertise.
- High Energy Physics:Liquid scintillator calorimeters at CERN and DESY deploy machine learning pulse-shape discrimination for real-time neutron-gamma classification. Research consortia are unbundling crystal supply from integrated detector purchases.
- Medical Imaging:Hybrid PET-MRI configurations demand magnetic-field-immune detector modules. Silicon photomultiplier displacement of photomultiplier tubes is restructuring subsystem economics across imaging OEMs.
Clinical applications command premium pricing. Research physics installations are expanding most quickly through Helmholtz network instrument refresh programs.
End User:
Procurement authority concentrates differently across institutional types, from centralized hospital purchasing to distributed principal-investigator decision-making in academic settings.
- Healthcare Facilities:Hospital networks negotiate multi-system contracts with imaging equipment OEMs. Crystal scintillator arrays are specified as replacement components within molecular imaging suite upgrades.
- Research Laboratories:University physics departments and national laboratories source unbundled components directly from crystal growers. German Helmholtz centers establish technical specifications that affiliated institutions adopt.
- Nuclear Power Plants:NRC licensing requirements govern radiation monitoring system procurement with extended compliance timelines. Incumbent scintillator-photodetector pairings retain positioning through certification inertia.
- Safety & Security Agencies:Border checkpoint infrastructure drives volume demand for plastic scintillator panels. Government procurement specifications emphasize gamma-neutron discrimination performance.
Healthcare procurement represents the largest revenue pool. Research laboratory demand is gaining share fastest through modular detector array adoption.
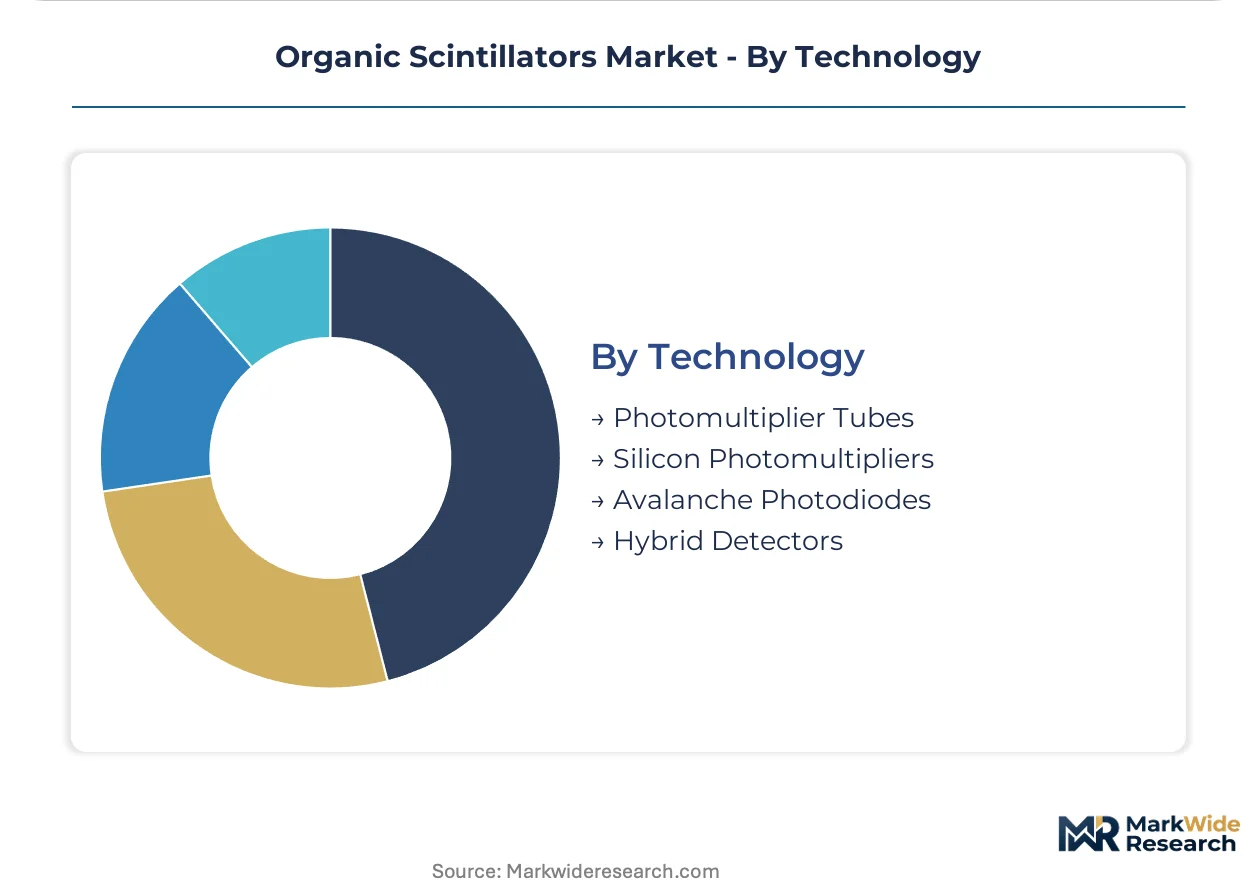
Technology:
Photodetector selection determines optical coupling requirements, voltage supply architectures, and magnetic field compatibility across detector subsystems.
- Photomultiplier Tubes:Vacuum photoelectric devices with established dynode amplification chains dominate legacy installations. High voltage requirements and magnetic sensitivity constrain deployment in hybrid imaging systems.
- Silicon Photomultipliers:Solid-state Geiger-mode avalanche arrays deliver magnetic-field immunity and compact footprint. Next-generation PET-MRI systems are specifying these for detector module integration.
- Avalanche Photodiodes:Linear-mode silicon sensors provide intermediate performance for cost-constrained spectroscopy applications. Lower gain relative to SiPMs limits adoption in low-light scintillator readout.
- Hybrid Detectors:Combined photodetector architectures merge multiple sensing technologies for specialized measurement protocols. Research environments experiment with these for pulse-shape discrimination enhancement.
Photomultiplier tubes retain volume leadership through installed base inertia. Silicon photomultipliers show the steepest adoption curve as magnetic-field immunity becomes mandatory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Central Europe where purified anthracene feedstock originates, while consumption clusters in German-speaking research networks and North American medical imaging corridors. This geographic split shapes procurement patterns and regulatory compliance requirements across the value chain.
Germany
Helmholtz research centers and university physics laboratories sustain above-average instrument replacement cycles for neutron-gamma discrimination detectors. REACH aromatic hydrocarbon restrictions are forcing reformulation investments among liquid scintillator producers. The Berlin-Brandenburg and Bavarian clusters concentrate crystal growth capabilities and photodetector integration expertise.
United States
Hospital networks are expanding crystal scintillator array procurement for molecular imaging suite upgrades. EPA atmospheric radiation surveillance mandates are driving field-deployable liquid scintillator system specifications for tritium detection. The Greater Boston and Pacific Northwest research corridors anchor high-energy physics detector development.
France
Medical device producers are prioritizing pre-certified scintillator assemblies to avoid downstream compliance verification delays. ANSM radiological health oversight aligns with FDA-equivalent performance standards for imaging equipment. The Île-de-France region concentrates nuclear medicine research institutions sourcing unbundled detector components.
United Kingdom
Research laboratories are adopting modular detector array configurations that fragment procurement across scintillator crystal and photodetector suppliers. The country's national pharmaceutical regulator maintains alignment with EMA standards for clinical imaging equipment. The Oxford-Cambridge arc hosts particle physics consortia deploying machine learning pulse-shape discrimination systems.
Japan
PET-MRI hybrid imaging OEMs are specifying magnetic-field-immune silicon photomultiplier modules, restructuring subsystem economics for scintillator suppliers. METI industrial standards govern radiation detection equipment certification timelines. The Kanto region around Tokyo concentrates medical imaging equipment manufacturing and photodetector integration capabilities.
Organic Scintillators Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across detector subsystem tiers. The market structure consolidates around captive crystal growth capabilities and long-standing research facility supplier relationships. Three archetypes dominate: integrated materials-scintillator-photodetector suppliers, specialized crystal growers with optical polishing expertise, and plastic formulation houses serving volume security applications. Competitive moves concentrate on optical interface redesign for silicon photomultiplier compatibility and REACH-compliant reformulation of liquid scintillator bases.
Among European-anchored suppliers, Saint-Gobain Crystals represents the integrated materials-to-detector archetype through captive supply positioning. Eljen Technology exemplifies the plastic scintillator specialization vector with volume manufacturing scale. Inrad Optics occupies a niche fabrication position where precision optical polishing capabilities concentrate.
| Leading Market Players |
|---|
| Inrad Optics |
| Eljen Technology |
| Saint-Gobain Crystals |
| ME Taylor Engineering |
| Advatech UK Limited |
| EPIC Crystal |
| Detec |
| Cryos-Beta |
| Rexon Components |
| Others |
Supply Flow & Price Mechanics
REACH aromatic hydrocarbon restrictions gate qualified supply for European liquid scintillator producers, concentrating premium-tier pricing access among reformulation-certified suppliers while forcing non-compliant manufacturers toward standard-grade positioning or market exit. This regulatory filter reshapes procurement negotiations across hospital networks and research consortia.
Pricing Analysis
Margin tightening in crystal scintillator tiers reflects silicon photomultiplier displacement forcing optical interface redesign investments. Pricing stratifies across premium, standard, and economy tiers based on energy resolution grade and FDA certification status. Cost-down pressure on plastic formulations accelerates as border security agencies consolidate volume procurement. Healthcare facilities demonstrate lowest price sensitivity where diagnostic accuracy requirements override budget constraints.
Supply Chain Analysis
FDA and EPA certification requirements concentrate qualified supply among producers with established type-approval track records. Purified anthracene feedstock originates from Central European specialty chemical producers, while crystal growth capabilities cluster in Germany and France. The supply chain rests on limited-source organic crystal precursors and precision optical polishing subcontractors. Single-source vulnerability in anthracene purification exposes formulations to input volatility. Distribution runs through direct OEM contracts for medical imaging and research consortia procurement for physics installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organic scintillator market sits in a photodetector transition phase as silicon photomultipliers displace photomultiplier tubes across PET-MRI hybrid imaging systems, restructuring subsystem economics and recalibrating competitive positioning.
For Market Incumbents: Hedge against silicon photomultiplier transition friction by accelerating optical interface certification timelines and deepening captive crystal growth capabilities in Germany. Defend positioning through REACH-compliant liquid scintillator reformulation ahead of aromatic hydrocarbon restriction enforcement. Prioritize Helmholtz center supplier relationships as de facto standard-setters for affiliated research institutions. For New Entrants and Emerging Players: EPA atmospheric radiation surveillance mandates in the United States open a window for field-deployable liquid scintillator system specialists. Target environmental tritium monitoring applications where established medical imaging incumbents maintain weaker presence. Pursue direct contracting with atmospheric surveillance network operators bypassing integrated detector OEM channels. For Investors and Strategic Acquirers: Saint-Gobain Crystals' sustained CERN supplier status is the leading indicator that captive crystal growth capabilities command durable premium positioning. Long-term viability hinges on photodetector-agnostic optical coupling expertise transferable across SiPM and legacy PMT architectures. Monitor FDA radiological health regulation updates as inflection signals for certification-timeline risk and incumbent advantage reinforcement.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Interface Redesign for SiPM Compatibility | Enables PET-MRI detector module qualification ahead of hybrid imaging OEM procurement cycles. |
| REACH-Compliant Liquid Scintillator Reformulation | Secures European hospital network and research laboratory supply positioning against aromatic hydrocarbon restrictions. |
| Helmholtz Center Direct Supplier Certification | Captures de facto standard-setting influence across German-speaking physics research clusters. |
| Precision Optical Polishing Capability Acquisition | Addresses sub-micron surface finish bottlenecks in scintillator-photodetector coupling interfaces. |
| EPA Atmospheric Surveillance System Partnership | Positions for North American environmental tritium monitoring procurement outside medical imaging concentration. |
Methodological Framework
Document review covered FDA radiological health filings, EPA environmental monitoring procurement specifications, and REACH substance restriction databases, complemented by interviews with crystal growth operations directors, nuclear medicine department procurement leads, and high-energy physics detector engineers. Secondary validation drew from customs trade data, Helmholtz center instrument refresh program disclosures, and hospital network capital expenditure records. Bottom-up demand modeling and top-down supply capacity assessment were triangulated against silicon photomultiplier adoption curve projections.
Segment-level outputs across the projection horizon reflect product type, application, end user, and photodetector technology dimensions. CAGRs were derived from replacement cycle analysis, regulatory compliance timeline modeling, and research funding trajectory assessment. Forecast inputs incorporated PET-CT system procurement patterns, border security infrastructure deployment schedules, and machine learning pulse-shape discrimination adoption rates in liquid scintillator calorimetry.
The model assumes a particular silicon photomultiplier adoption path; alternative pathways for photomultiplier tube retention in cost-constrained spectroscopy would alter the outlook. Forecasts reflect assumptions on FDA radiological health regulation enforcement intensity and REACH aromatic hydrocarbon restriction implementation timing. A model refresh is warranted upon material change in NRC licensing requirements for nuclear power plant radiation monitoring systems.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Silicone Gel Market
Specialty Materials
Sheath Materials Market
Specialty Materials
Erbium-169 Market
Specialty Materials
Nanocapsules Market
Specialty Materials
Nanoencapsulation Market
Specialty Materials
India Collagen Market
Specialty Materials
Global Cellulose Acetate Market
Specialty Materials
Battery Separator Films Market
Specialty Materials
UK Lab-Grown Diamonds Market
Specialty Materials
PCB Prepreg Material Market
Specialty Materials
Global Supplementary Cementitious Materials Market
Specialty Materials
Alginate Films Market
Specialty Materials
Melamine Foam Market
Specialty Materials
Electrode Paste Market
Specialty Materials
Marine Mineral Complexes from Mediterranean Shells Market
Specialty Materials
Semiconductor O-Rings Market