
 Amino Silicone Oil Market | 2026-2036
Amino Silicone Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Amino Silicone Oil Market Analysis
The EU F-Gas Regulation is hardening refrigerant and industrial fluid standards, indirectly tightening specifications for silicone derivatives used in heat-transfer and coating applications. Dow Inc. leverages its integrated silicone feedstock network to sustain cost-competitive amino fluid production across North American and European manufacturing sites. Wacker Chemie AG anchors its position through backward integration into chlorosilane precursors, while Bluestar competes on volume scale from its China-based silicone hubs.
Amino silicone oil denotes a polydimethylsiloxane backbone grafted with primary or secondary amine functional groups, typically exhibiting amine values between 0.1 and 1.0 meq/g and viscosity ranges of 100–10,000 cSt depending on chain length and substitution degree. These fluids impart softness, lubricity, and hydrophilicity to substrates, serving as conditioning agents in hair care formulations and as fabric softening agents in textile finishing baths. Emulsions command the largest volume share due to their ease of dilution and compatibility with aqueous textile processing lines, while water-based formulations gain share as solvent-free systems displace oil-based carriers under tightening volatile organic compound limits. Fluids retain margin strength in high-performance automotive care and industrial coating segments where thermal stability and film-forming precision justify premium positioning.
REACH registration requirements in Europe and EPA Toxic Substances Control Act oversight in the United States constrain unregistered amino-functional silicone imports and mandate full substance characterization for commercial access. China's SAMR enforces GB standards for silicone products in consumer applications, creating a three-jurisdiction compliance burden for multinational suppliers. Buyers and producers must monitor evolving per- and polyfluoroalkyl substance restrictions, as regulatory spillover into silicone adjacencies could reshape formulation priorities and substitution timelines.
Market Dynamics
Water-based formulation advances are compressing solvent-based amino silicone oil volumes across textile finishing lines, as REACH compliance deadlines in Europe and EPA volatile organic compound limits in the United States harden performance benchmarks and reformulation timelines simultaneously.
Growth Catalysts
- REACH registration mandates:ECHA substance characterization requirements filter unregistered imports from Asian suppliers, creating protected market access for compliant European and North American producers with established dossiers.
- China's textile export engine:Domestic silicone producers scale amino-functional fluid output to supply finishing baths for export-oriented fabric mills concentrated in Zhejiang and Jiangsu provinces.
- Emulsion technology maturation:Micro-emulsion stability improvements allow higher active-content water-based systems to displace solvent carriers in automotive care and industrial coating segments.
Market Restraints
- Chlorosilane feedstock concentration:Backward integration into silane precursors concentrates among German and Chinese chemical conglomerates, exposing mid-scale amino fluid producers to input cost volatility and allocation priority risks.
- Per- and polyfluoroalkyl substance spillover:Regulatory scrutiny of PFAS in textile water-repellency applications creates formulation complexity as downstream mills audit entire chemical portfolios for contamination risk.
- Dimethylsiloxane oligomer technical ceiling:Low-molecular-weight cyclic siloxane content limits in personal care applications constrain amino fluid molecular design flexibility for hair conditioning formulations.
Strategic Opportunities
- India textile cluster penetration:Surat and Tiruppur finishing houses upgrade from conventional softeners to amino-functional systems as BIS standards align with EU import requirements for garment exports.
- EU Green Deal chemistry incentives:Bio-based amine grafting pathways and renewable feedstock verification protocols open preferential procurement channels for sustainability-certified suppliers.
- Digital textile printing convergence:Amino silicone pre-treatment fluids enable ink adhesion on synthetic fabrics, positioning functional fluids within the growth trajectory of on-demand garment production.
Industry Challenges
- Silicone synthesis expertise scarcity:Hydrosilylation catalyst handling and amine-functionalization process control require specialized chemical engineering talent concentrated among legacy German and Japanese producers.
- Multi-jurisdiction certification lag:Parallel REACH, EPA TSCA, and China GB standard compliance timelines extend product launch cycles by 18–24 months for novel amino fluid compositions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amino Silicone Oil Market |
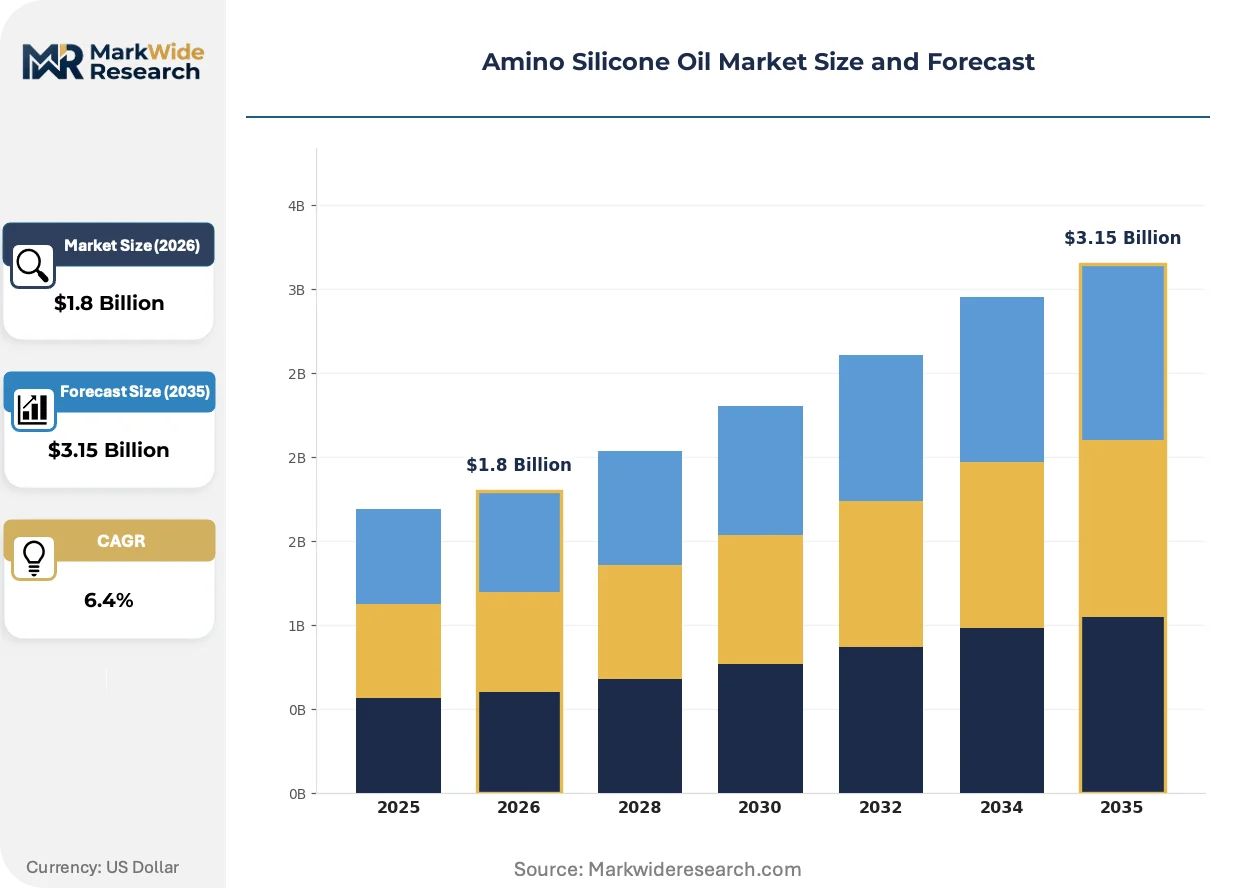
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsions, Fluids, Powders, Surfactants End Use Industry: Textiles, Personal Care, Automotive, Coatings Application: Hair Care, Skin Care, Fabric Treatment, Automotive Care Formulation Type: Water-based, Oil-based, Solvent-free, Silicone-based |
| Companies Covered | Shin-Etsu Chemical, Dow Inc., DuPont, KCC Corporation, ACC Silicones, Wacker Chemie AG, Bluestar, Elkem ASA, Momentive Performance Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amino Silicone Oil Market Emerging Trajectories
Formulation chemistry and regulatory compliance architectures are restructuring competitive position in amino silicone oils, with water-based system performance now matching solvent-based benchmarks and digital integration altering how textile mills specify and procure finishing agents.
Hybrid amine-siloxane architectures with tunable hydrophilic-lipophilic balance are modularizing across textile wet processing lines, enabling single-bath softening and moisture-management combinations that previously required sequential treatment stages. Italian and Turkish denim finishers pilot these systems to compress processing time by 30–40 percent while maintaining hand-feel consistency. The technology is modularizing equipment configurations and chemical inventory requirements for mid-scale dye houses.
The EU F-Gas Regulation is tightening refrigerant and industrial fluid specifications, indirectly elevating thermal stability requirements for silicone derivatives used in heat-transfer and coating adjacencies. Downstream formulators must now document fluorine-free status and thermal degradation profiles for amino fluid components. German automotive coating suppliers lead the adaptation, pushing amino silicone specifications toward higher viscosity grades with proven 200°C+ stability.
Direct mill procurement of concentrated amino fluid emulsions is displacing distributor-blended finished softeners across South Asian textile corridors. Bangladesh and Vietnam garment manufacturers now specify active content and amine value directly, bypassing regional compounders. This pattern concentrates volume with integrated silicone producers capable of technical service deployment to factory-floor finishing departments.
Amino Silicone Oil Market Segmentation
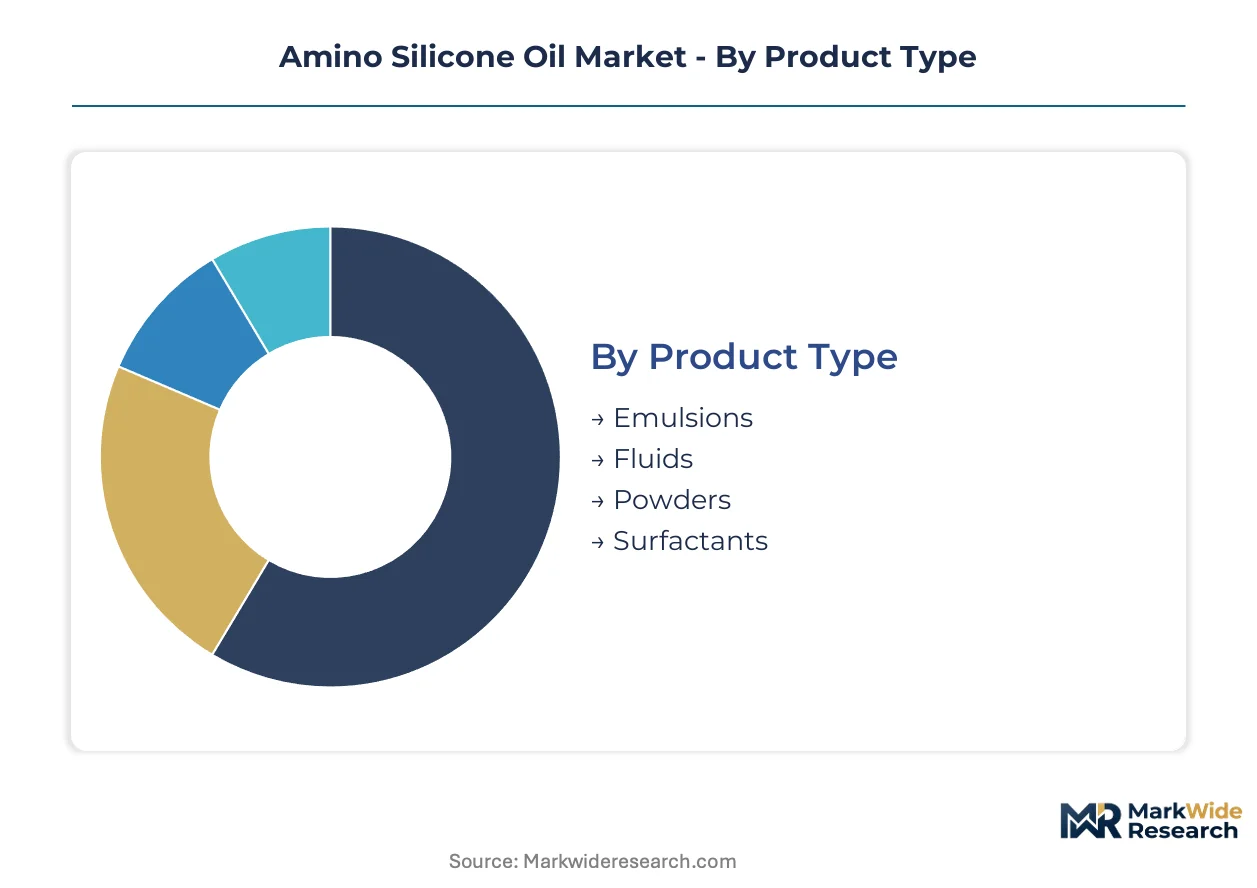
Product architecture and formulation chemistry determine margin capture and regulatory exposure across amino silicone oil supply chains. Segment boundaries reflect divergent technical service requirements, compliance burdens, and customer procurement sophistication.
Product Type:
Supply concentration in emulsion technology favors producers with captive surfactant capabilities and regional technical service networks.
- Emulsions:Aqueous dispersions of amino-functional silicone droplets stabilized by nonionic surfactants, typically 15-60% active content. Textile finishing houses in Zhejiang and Jiangsu provinces specify these systems for compatibility with continuous pad-dry-cure lines and REACH-compliant volatile organic compound profiles.
- Fluids:Neat polydimethylsiloxane backbones with pendant amine functionality, viscosity-calibrated for direct blending or specialized coating applications. Automotive sealant formulators in Germany source high-viscosity grades (5,000-10,000 cSt) for thermal stability above 200°C under EU F-Gas Regulation pressure testing protocols.
- Powders:Spray-dried amino silicone microcapsules for dry-blend personal care formulations and powder coating additives.
- Surfactants:Amino-silicone hybrid molecules functioning as dual-purpose emulsifiers and conditioning agents in shampoo concentrates.
Emulsions absorb the bulk of installed capacity; fluids are expanding most quickly as automotive thermal management specifications harden.
End Use Industry:
Cost tier differentiation separates commodity textile softeners from performance-specified automotive and personal care grades.
- Textiles:Fabric softening and finishing treatments for cotton, polyester, and blended substrates. Export-oriented mills in Bangladesh and Vietnam upgrade from conventional fatty acid softeners to amino-functional systems as EU import requirements tighten.
- Personal Care:Hair conditioning and skin moisturization applications requiring low-cyclic siloxane content under EU and FDA cosmetic safety guidelines. Shampoo manufacturers specify amine values of 0.3-0.6 meq/g for optimal substantivity on damaged hair cuticles.
- Automotive:Dashboard protectants, tire dressings, and leather conditioning formulations demanding UV stability and high-temperature resistance.
- Coatings:Industrial and decorative paint additives providing mar resistance and substrate wetting.
Textiles command the largest volume position; personal care applications are climbing the fastest as clean beauty formulation standards proliferate.
Application:
Volume concentration in fabric treatment reflects the scale of Asian textile production infrastructure.
- Fabric Treatment:Pad-batch and exhaust finishing processes imparting softness, drape, and sewability to woven and knitted goods. Tiruppur and Surat dye houses transition to amino silicone systems as BIS standards align with EU REACH protocols for garment export certification.
- Hair Care:Rinse-off conditioners and leave-in treatments leveraging cationic amine groups for electrostatic adhesion to anionic hair surfaces. Korean and Japanese formulators drive specification toward ultra-low volatile cyclic siloxane content.
- Skin Care:Moisturizing lotions and sun care products utilizing amino silicone film-forming and sensory modification properties.
- Automotive Care:Exterior and interior surface protection products requiring durability against weathering and plasticizer migration.
Fabric treatment anchors production scale; hair care applications are gaining share fastest as silicone-free marketing claims recede in professional salon channels.
Formulation Type:
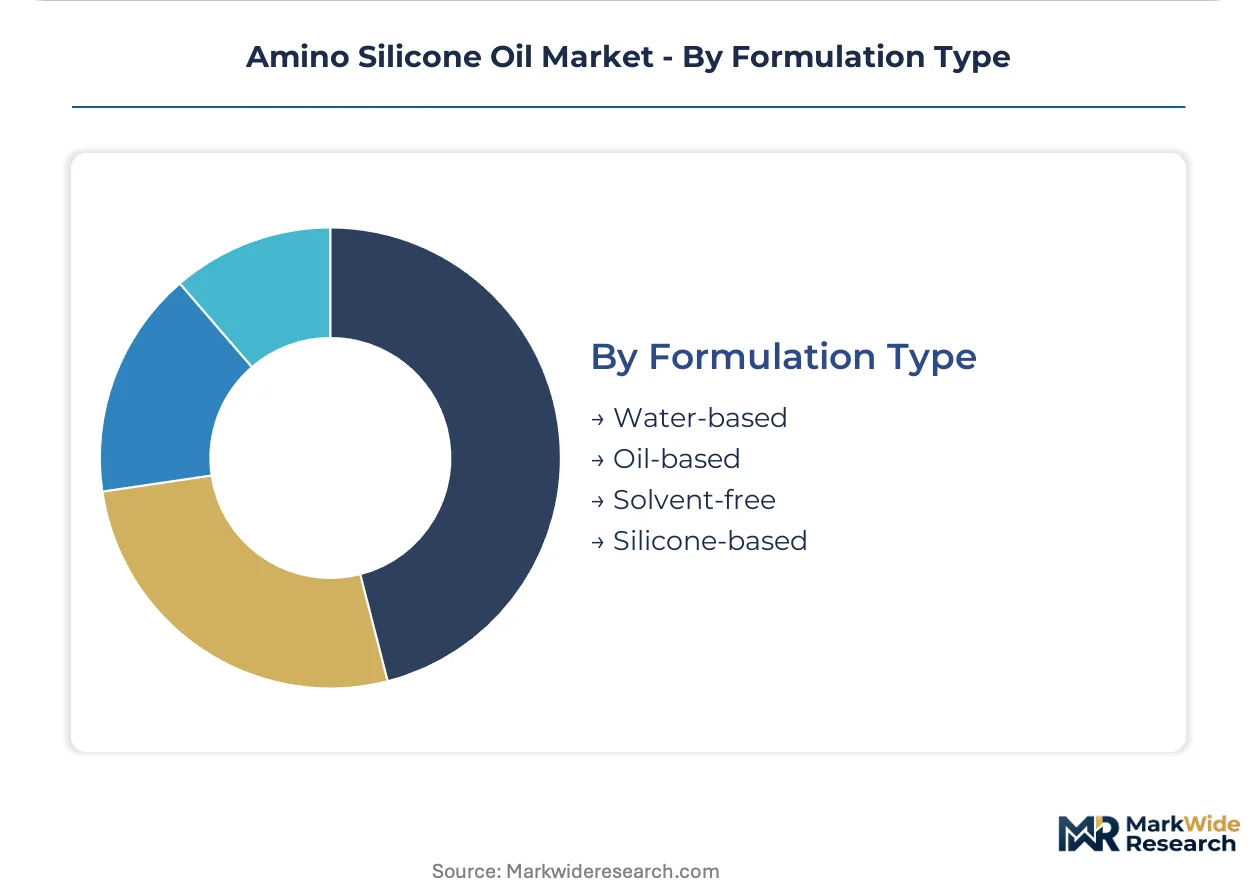
Margin structure favors solvent-free systems as regulatory limits on volatile organic compounds compress oil-based formulation economics.
- Water-based:Emulsion and dispersion systems with water as continuous phase, compliant with EPA volatile organic compound limits and EU solvent emission directives. Micro-emulsion stability advances now match solvent-based performance in automotive care segments.
- Solvent-free:100% active fluid or paste systems eliminating carrier entirely. German automotive coating suppliers specify these grades for fluorine-free thermal management formulations under EU F-Gas Regulation documentation requirements.
- Oil-based:Hydrocarbon or ester carrier solutions for applications requiring extended open time or specific evaporation profiles.
- Silicone-based:Blends with other silicone fluids (dimethicone, cyclomethicone) for tailored sensory or performance properties.
Water-based systems hold the dominant capacity share; solvent-free formulations are expanding most quickly as thermal stability specifications escalate across industrial coatings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the bulk of amino-functional silicone fluids while European and North American buyers absorb premium grades for REACH-compliant textile finishing and automotive thermal management applications.
China
Export-oriented textile mills in Zhejiang and Jiangsu provinces drive amino silicone oil consumption for fabric softening baths serving EU and US garment buyers. SAMR enforces GB standards for silicone products in consumer applications, creating compliance checkpoints for domestic producers. Domestic silicone hubs in Jiangsu scale amino-functional fluid output to capture share from multinational suppliers in water-based formulation segments.
Germany
Automotive coating formulators source high-viscosity amino silicone grades for dashboard protectants and sealants requiring thermal stability above 200°C. The EU F-Gas Regulation elevates documentation requirements for fluorine-free thermal management formulations. Industrial clusters in North Rhine-Westphalia and Bavaria concentrate backward-integrated chlorosilane production and amino fluid finishing operations.
United States
Hair care manufacturers specify low-cyclic siloxane amino fluids for conditioning formulations under FDA cosmetic safety guidelines and California Proposition 65 exposure limits. EPA TSCA oversight mandates full substance characterization for commercial access, filtering unregistered imports. Personal care formulation houses in New Jersey and California drive specification toward ultra-low volatile content grades.
India
Surat and Tiruppur textile finishing houses upgrade from conventional fatty acid softeners to amino-functional systems as BIS standards align with EU REACH protocols for garment export certification. The country's textile up-gradation fund subsidizes chemical processing modernization in export-oriented clusters. Dye houses in Tamil Nadu and Gujarat now specify active content and amine value directly, bypassing regional compounders.
Japan
Shampoo and rinse-off conditioner formulators drive amino silicone specifications toward ultra-low cyclic siloxane content under METI chemical safety guidelines. Korean and Japanese cosmetic brands demand precise amine value control for electrostatic adhesion performance on damaged hair. Personal care innovation clusters in Osaka and Tokyo anchor regional formulation chemistry development.
Amino Silicone Oil Market Vendor Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive chlorosilane supply and regional technical service networks. Three archetypes dominate: German-Japanese precision specialists with hydrosilylation catalyst expertise, Chinese volume-scale producers leveraging domestic silicone metal access, and North American diversified material science platforms with textile industry relationships. Competitive moves concentrate on backward integration into silane precursors and emulsion technology licensing to capture water-based formulation share.
Within the integrated multinational tier, Dow Inc. and Wacker Chemie AG exemplify archetypes combining feedstock control with regional manufacturing presence. Dow leverages its North American and European silicone feedstock network for cost-competitive amino fluid production across multiple sites. Wacker anchors its position through in-house chlorosilane precursor production at German manufacturing complexes. Shin-Etsu Chemical occupies a position representing Japanese precision chemistry capabilities in low-cyclic siloxane grades for personal care applications.
| Leading Market Players |
|---|
| Shin-Etsu Chemical |
| Dow Inc. |
| DuPont |
| KCC Corporation |
| ACC Silicones |
| Wacker Chemie AG |
| Bluestar |
| Elkem ASA |
| Momentive Performance Materials |
| Others |
Supply Flow & Price Mechanics
Specialized hydrosilylation catalyst handlers concentrated in Germany and Japan command wage premiums that widen spreads between precision-grade amino fluids and commodity textile emulsions. Labor-cost differentials between these engineering clusters and volume-scale Chinese production sites stratify pricing tiers across REACH-certified and export-grade product categories.
Pricing Analysis
Margin tightening in textile-grade emulsions traces to chlorosilane feedstock allocation priorities favoring integrated conglomerates over mid-scale blenders. Three-tier pricing structure across premium, standard, and economy levels separates automotive thermal-management grades from personal-care low-cyclic formulations and bulk textile softeners. Certification investment for EU REACH dossiers and FDA cosmetic safety tiers drives price differentiation between compliant and unregistered supply. Cost-down pressure on standard-grade emulsions accelerates because Bangladesh and Vietnamese mills now specify active content directly, bypassing regional compounder markups. Export-oriented garment manufacturers in Tiruppur exhibit highest price sensitivity; German automotive coating formulators demonstrate lowest sensitivity due to thermal stability specifications above 200°C.
Supply Chain Analysis
Return flows of spent catalyst and silicone fluid recovery for reprocessing concentrate in Jiangsu province chlorosilane hubs. Geographic supply concentration centers on China, Germany, and the United States for amino-functional fluid production. Raw material dependencies rest on methylchlorosilane precursors, platinum-group hydrosilylation catalysts, and amine grafting agents. Single-source vulnerability from German-Japanese catalyst expertise concentration exposes mid-scale producers to allocation disruption. Distribution runs through direct mill procurement channels displacing regional compounders across South Asian textile corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Amino silicone oil supply is tightening around hydrosilylation catalyst expertise scarcity, with qualified process engineers in German and Japanese clusters propping pricing for precision-grade formulations.
For Market Incumbents: Deploy captive chlorosilane supply to secure feedstock allocation priority as Chinese silicone hubs scale amino-functional output. Defensive consolidation should concentrate on emulsion technology licensing to capture water-based formulation share from solvent-based competitors. Backward integration into silane precursors protects margin position against mid-scale blender displacement. Certification investment for EU REACH, EPA TSCA, and China GB parallel compliance creates barrier against unregistered Asian imports. For New Entrants and Emerging Players: Enter via India textile cluster penetration as Surat and Tiruppur finishing houses upgrade from fatty acid softeners to amino-functional systems. White-space targets include bio-based amine grafting pathways for EU Green Deal preferential procurement and digital textile printing pre-treatment fluids for on-demand garment production. Most penetrable segment is water-based emulsions for Bangladesh and Vietnam garment manufacturers specifying active content directly. Go-to-market angle should leverage BIS standard alignment with EU REACH protocols for export certification. For Investors and Strategic Acquirers: Re-rating potential sits with integrated silicone producers possessing regional technical service networks given water-based formulation technology maturation. Long-term viability favors conglomerates with captive chlorosilane supply and hydrosilylation catalyst handling expertise over pure-play emulsion blenders. Acquisition target archetype includes mid-scale European amino fluid producers with established REACH dossiers and underutilized emulsion capacity. Signal to watch is EU F-Gas Regulation documentation requirements for fluorine-free thermal management formulations accelerating specification shifts toward higher viscosity grades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorosilane Precursors | Wacker Chemie AG anchors cost position through in-house silane production at German manufacturing complexes. |
| Emulsion Technology Licensing | Micro-emulsion stability advances allow higher active-content water-based systems to displace solvent carriers in automotive care. |
| EU Green Deal Chemistry Certification | Bio-based amine grafting pathways open preferential procurement channels for sustainability-certified suppliers in European textile finishing. |
| Direct Mill Technical Service Deployment | Bangladesh and Vietnam garment manufacturers now specify amine value directly, bypassing regional compounders. |
| Digital Textile Printing Pre-treatment Development | Amino silicone fluids enable ink adhesion on synthetic fabrics within on-demand garment production growth trajectory. |
Methodological Framework
Document review covered trade customs data, SEC 10-K filings from silicone producers, and ECHA REACH registration databases, complemented by interviews with textile finishing plant managers, automotive coating formulators, personal care R&D directors, and chlorosilane procurement leads. Primary fieldwork engaged technical service engineers at integrated silicone producers and quality control officers at Zhejiang and Jiangsu textile mills. Secondary validation drew from ACC silicone market reports, Chinese customs export statistics, and FDA cosmetic ingredient safety assessments. Bottom-up volume estimates from individual production facilities were cross-referenced against top-down demand aggregation across end-use industries.
Historical capacity utilization trends were cross-referenced against panel input from silicone industry executives to establish baseline growth assumptions across the projection horizon. Segmentation dimensions modeled include product architecture (emulsion, fluid, powder), end-use industry (textiles, personal care, automotive), formulation type (water-based, solvent-free, oil-based), and regional production hub configuration. CAGRs were derived from slope analysis of historical demand trajectories adjusted for regulatory phase-in timelines and technology substitution curves. Industry-specific forecast inputs incorporated EU F-Gas Regulation thermal stability specifications and REACH registration compliance deadlines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under chlorosilane feedstock disruption or accelerated PFAS regulatory spillover into silicone adjacencies. Forecasts reflect assumptions around hydrosilylation catalyst supply continuity and water-based formulation performance parity achievement. Practitioners should monitor EU Green Deal chemistry incentive allocations and India BIS standard implementation timelines for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Global Methyl Ester Sulfonate Market
Surfactants
Global Barium Petroleum Sulfonate Market
Surfactants
Cetyl Trimethyl Ammonium Chloride Market
Surfactants
Sodium Lauroyl Glycinate Market
Surfactants
Natural Wax Emulsion Market
Surfactants
Global Calcium Sulfonate Market
Surfactants
Alkylamines Market
Surfactants
Waxing Sponge Market
Surfactants
Alkyl Polyglucosides Market
Surfactants
Global Sodium Cocoyl Glutamate Market
Surfactants
Global Detergents Market
Surfactants
Acrylamide Tertiary-Butyl Sulfonic Acid (ATBS) Market
Surfactants
Benzyl Trimethyl Ammonium Chloride Market
Surfactants
Sodium Lauroyl Sarcosinate Market
Surfactants
Global Sodium Lauryl Sulfate Market
Surfactants
Secondary Alkane Sulfonate Market