
 Microwave Absorbing Materials Market | 2026-2036
Microwave Absorbing Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Microwave Absorbing Materials Market Foresight
Carbon fiber composites are restructuring traditional ferrite-based absorber economics across military and aerospace supply chains. Parker Hannifin Corp. leverages its electromagnetic shielding portfolio to anchor defense contractor relationships in North America. Cuming Microwave Corp. specializes in castable absorber formulations that sustain niche demand from naval platform integrators. Rogers Corp. differentiates through ceramic-based laminates that dominate satellite payload applications.
Microwave absorbing materials are engineered composites, coatings, and films designed to convert electromagnetic energy into heat through dielectric or magnetic loss mechanisms, typically operating across 1-40 GHz with reflection loss below -10 dB. Their primary purpose is to suppress radar cross-sections, eliminate cavity resonances, and ensure electromagnetic compatibility in enclosed electronic systems. Carbon-based formulations currently lead volume consumption due to cost scalability, while metal-based segments capture premium margin pools in aerospace thermal management. Polymer-based absorbers represent the fastest-growing structural category as injection-moldable compounds displace machined ferrites in automotive radar housings.
The FCC governs electromagnetic emissions limits for commercial telecommunications equipment, while the EU AI Act and CE marking frameworks impose conformity assessment burdens on radar-integrated automotive systems entering European markets. Military procurement through the US Department of Defense mandates MIL-STD-285 shielding effectiveness validation, creating a bifurcated regulatory landscape between commercial and defense qualification pathways. Stakeholders must monitor evolving 5G mmWave spectrum allocations and corresponding absorber performance thresholds as frequency bands expand beyond conventional test regimes.
Market Dynamics
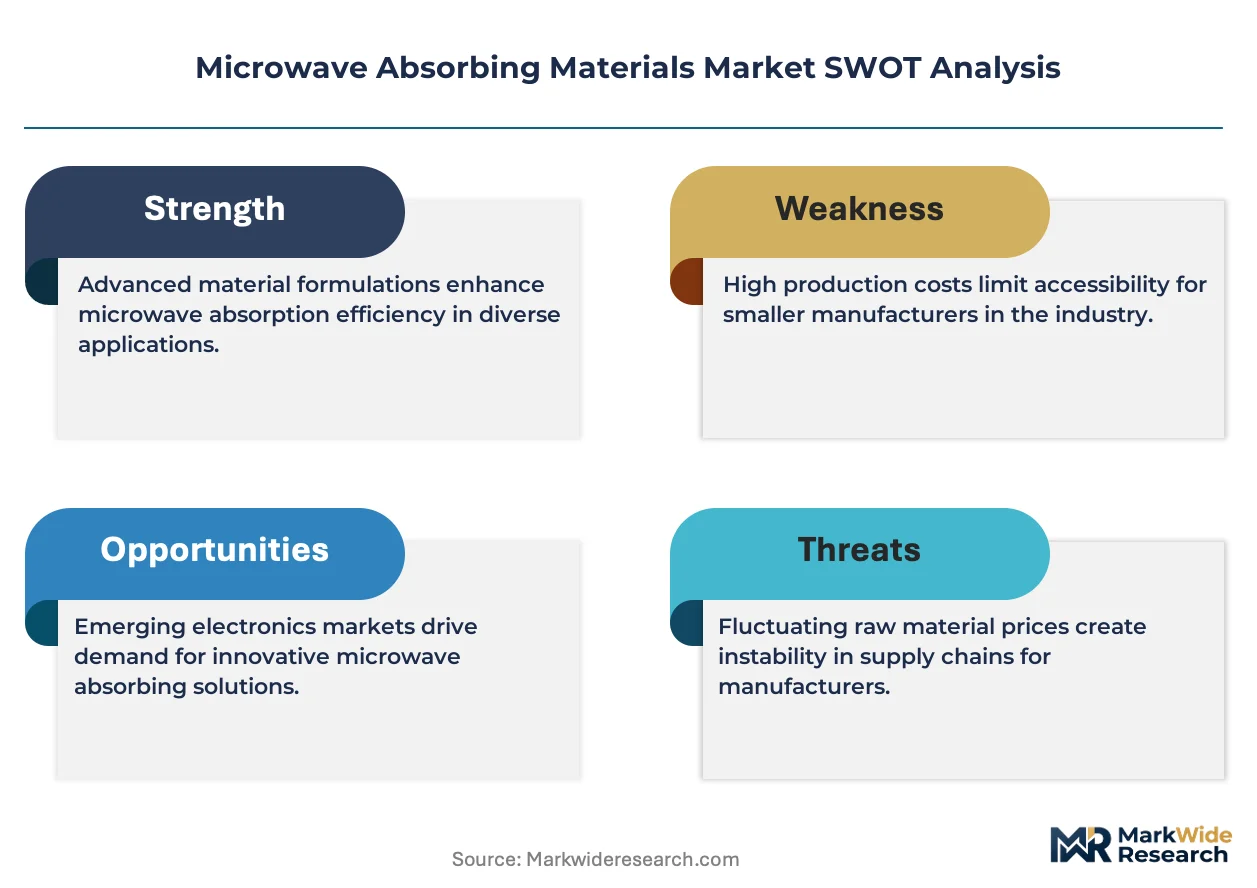
Defense electronics procurement across NATO member states is restructuring supplier qualification requirements, while stricter electromagnetic compatibility mandates from the FCC and EU AI Act accelerate material certification cycles. This dual pressure is concentrating demand around absorber formulations that satisfy both military shielding effectiveness standards and commercial automotive radar integration protocols.
Growth Catalysts
- EU AI Act electromagnetic conformity:The EU AI Act imposes conformity assessment burdens on radar-integrated automotive systems entering European markets, forcing absorber material upgrades across Tier 1 supplier networks.
- Germany's industrial corridor concentration:Automotive radar integration in Germany's industrial corridor requires next-generation absorber formulations, pulling specialized compound development from material suppliers.
- Carbon-based formulation scalability:Carbon fiber composites are restructuring traditional ferrite-based absorber economics, enabling cost-efficient volume production for commercial telecommunications equipment.
Market Restraints
- Rare earth supply concentration:Ferrite absorber production depends on rare earth oxide inputs concentrated in Chinese processing facilities, exposing formulators to geopolitical supply disruption risk.
- MIL-STD-285 certification friction:US Department of Defense procurement mandates MIL-STD-285 shielding effectiveness validation, creating a bifurcated regulatory landscape that extends commercial qualification timelines by 18-24 months.
- Metamaterial substitution threat:Programmable electromagnetic surfaces are emerging as functional substitutes in satellite payload applications, threatening ceramic-based laminate margins at the premium tier.
Strategic Opportunities
- Naval platform castable formulations:Cuming Microwave Corp.'s specialization in castable absorber formulations sustains niche demand from naval platform integrators seeking conformal coating solutions for complex hull geometries.
- 5G mmWave spectrum expansion:Evolving 5G mmWave spectrum allocations above 28 GHz create performance threshold gaps that absorber manufacturers can fill with dielectrically-tuned composites.
- Injection-moldable polymer compounds:Polymer-based absorbers represent structural white space as injection-moldable compounds displace machined ferrites in automotive radar housings, enabling tiered pricing stratification.
Industry Challenges
- Electromagnetic compatibility test engineer scarcity:The specialized skill set required for anechoic chamber calibration and reflection loss measurement is concentrating in defense contractor facilities, constraining commercial certification throughput.
- Dual-use technology export control complexity:Absorber formulations with military applications trigger ITAR and EAR licensing requirements that fragment supplier-customer relationships across NATO and non-NATO jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microwave Absorbing Materials Market |
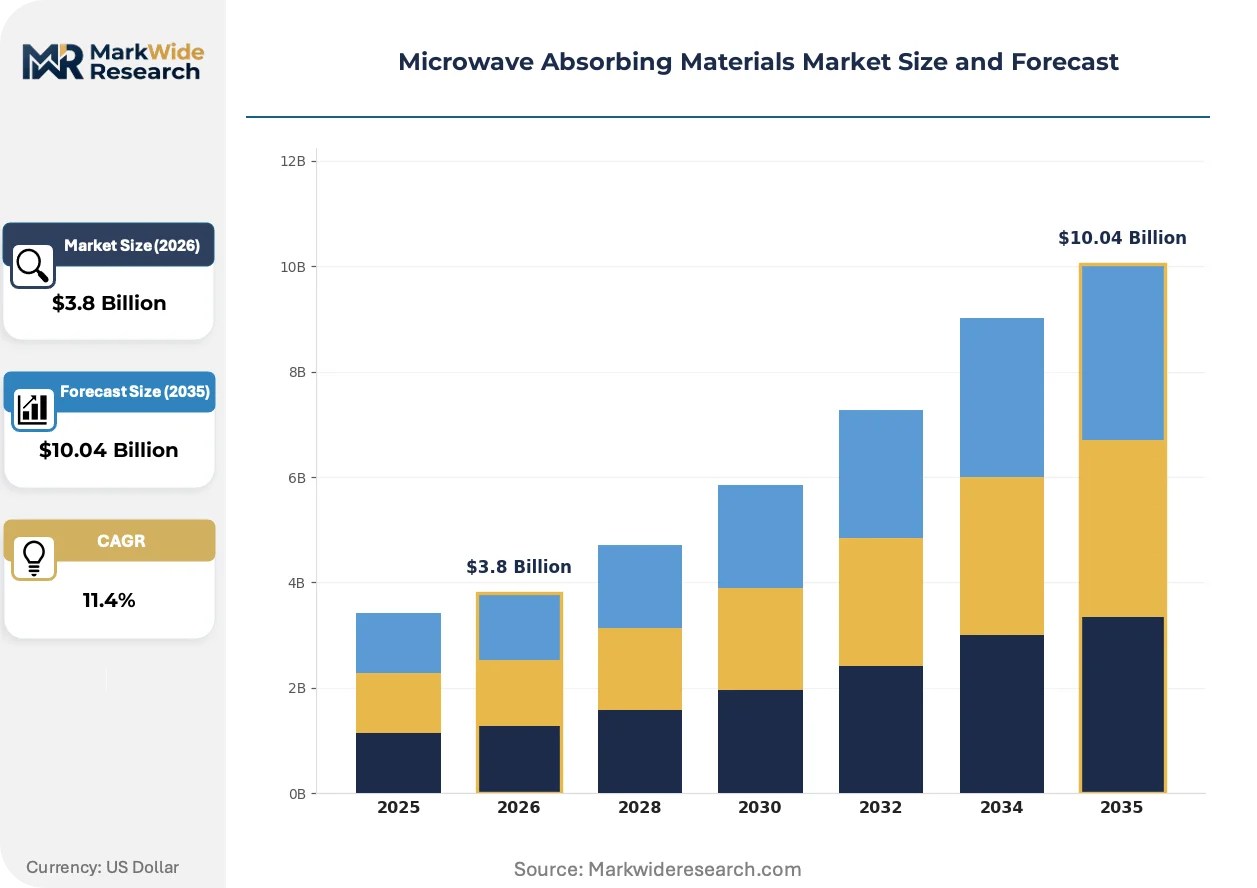
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromagnetic Shielding, Coatings, Films, Composites Material: Carbon-Based, Polymer-Based, Metal-Based, Ceramic-Based Application: Aerospace, Automotive, Telecommunications, Military Form Factor: Sheet, Granules, Powder, Foam |
| Companies Covered | Parker Hannifin Corp., Cuming Microwave Corp., Laird Technologies, MAST Technologies, ESCO Technologies Corporation, 3M, Rogers Corp., TDK Corp., ARC Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microwave Absorbing Materials Market Shifts & Advancements
Material science convergence with electromagnetic simulation software is compressing absorber development cycles from multi-year defense procurement timelines toward automotive-speed qualification protocols. This acceleration is reshaping competitive positioning around computational design capabilities rather than empirical testing heritage.
Graphene-enhanced dielectric composites are absorbing electromagnetic energy across extended frequency bands with reduced thickness penalties compared to traditional ferrite-loaded elastomers. Satellite payload manufacturers are adopting these formulations at accelerated pace to meet mass budget constraints. The technology is absorbing market share from ceramic-based laminates in low-earth orbit constellation applications where every gram carries launch cost implications.
The FCC's expanded enforcement of Part 15 unintentional radiator limits is compressing compliance timelines for commercial telecommunications equipment manufacturers. This regulatory pressure is forcing absorber specification upgrades in Wi-Fi 6E and 7 access point designs. North American OEMs are responding by pre-qualifying dual-use materials that satisfy both commercial emissions limits and provisional military shielding thresholds.
Buyer consolidation among Tier 1 automotive radar module suppliers is compressing supplier qualification cycles and unbundling after-sales technical support from material supply contracts. German and Japanese automotive electronics manufacturers are driving this pattern most visibly, demanding absorber suppliers assume cavity design optimization responsibilities previously retained in-house.
Microwave Absorbing Materials Market Segmentation
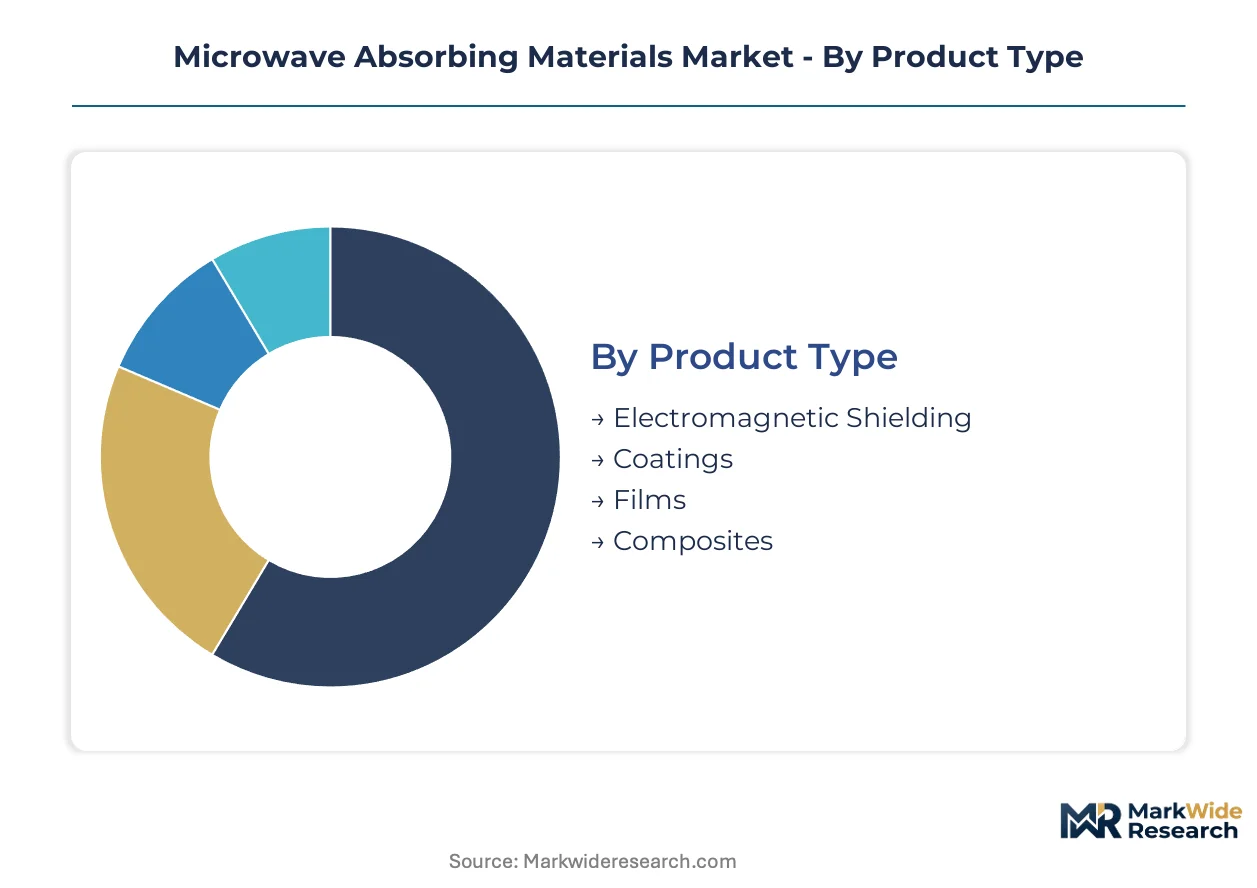
Microwave absorbing materials segment along four intersecting dimensions that determine qualification pathways and margin structures. Certification requirements from the FCC, EU AI Act, and MIL-STD-285 bifurcate demand across product categories, while material chemistry and form factor dictate supply chain positioning.
Product Type:
FCC Part 15 governs electromagnetic shielding for commercial telecommunications, while MIL-STD-285 applies to composites and coatings in defense procurement, creating divergent approval timelines across this category.
- Electromagnetic Shielding:Enclosures and gaskets engineered for cavity resonance suppression in electronic housings. Demand concentrates in North American Wi-Fi 6E access point manufacturing, where FCC enforcement of unintentional radiator limits is compressing compliance timelines. The category requires dual-use pre-qualification strategies to bridge commercial and provisional military thresholds.
- Composites:Structural absorber formulations integrating conductive fillers into load-bearing matrices. German automotive radar module suppliers are driving specification upgrades, demanding cavity design optimization responsibilities shift from OEMs to material vendors. Carbon fiber variants are restructuring traditional ferrite economics across military supply chains.
- Coatings:Spray-applied or dip-coated absorber layers for conformal coverage of complex geometries. Naval platform integrators specify castable formulations for hull applications.
- Films:Thin, flexible absorber substrates for aperture and window treatments. Satellite payload manufacturers adopt these for mass budget constraints in low-earth orbit constellations.
Leading the category by volume: Composites. Growing fastest: Electromagnetic Shielding.
Material:
Cost tier stratification separates premium formulations from volume-grade alternatives, with metal and ceramic commanding margin premiums while carbon and polymer scale toward automotive price points.
- Carbon-Based:Graphite, carbon nanotube, and carbon fiber formulations leveraging dielectric loss mechanisms. Volume consumption leads across commercial telecommunications due to cost scalability, with graphene-enhanced variants gaining share in satellite applications through reduced thickness penalties.
- Metal-Based:Magnetic fillers including iron, nickel, and cobalt particles dispersed in polymer binders. Aerospace thermal management applications in the United States capture premium margin pools, though rare earth supply concentration in Chinese processing facilities exposes formulators to geopolitical disruption risk.
- Polymer-Based:Injection-moldable compounds displacing machined ferrites in automotive radar housings. Tier 1 suppliers in Germany and Japan are compressing qualification cycles and unbundling technical support from supply contracts.
- Ceramic-Based:Ferrite and dielectric ceramic laminates for high-temperature, high-frequency operation. Rogers Corp. dominates satellite payload applications, though metamaterial substitution threatens premium-tier margins.
Highest volume segment: Carbon-Based. Steepest expansion trajectory: Polymer-Based.
Application:
End-use concentration determines whether absorber specifications prioritize military shielding effectiveness or commercial automotive radar integration protocols.
- Military:Radar cross-section reduction and anechoic chamber applications requiring MIL-STD-285 validation. NATO procurement restructuring is tightening supplier qualification requirements, extending commercial qualification timelines by 18-24 months.
- Automotive:Radar module integration for advanced driver-assistance systems. Germany's industrial corridor concentrates demand, with EU AI Act conformity assessments forcing material upgrades across Tier 1 networks.
- Aerospace:Thermal management and electromagnetic compatibility in avionics enclosures. The FAA and EASA airworthiness frameworks impose additional certification layers beyond baseline absorber performance.
- Telecommunications:5G mmWave and Wi-Fi 6E/7 equipment shielding. FCC Part 15 enforcement is accelerating specification upgrades in North American access point designs.
Dominant revenue segment: Military. Expanding most quickly: Automotive.
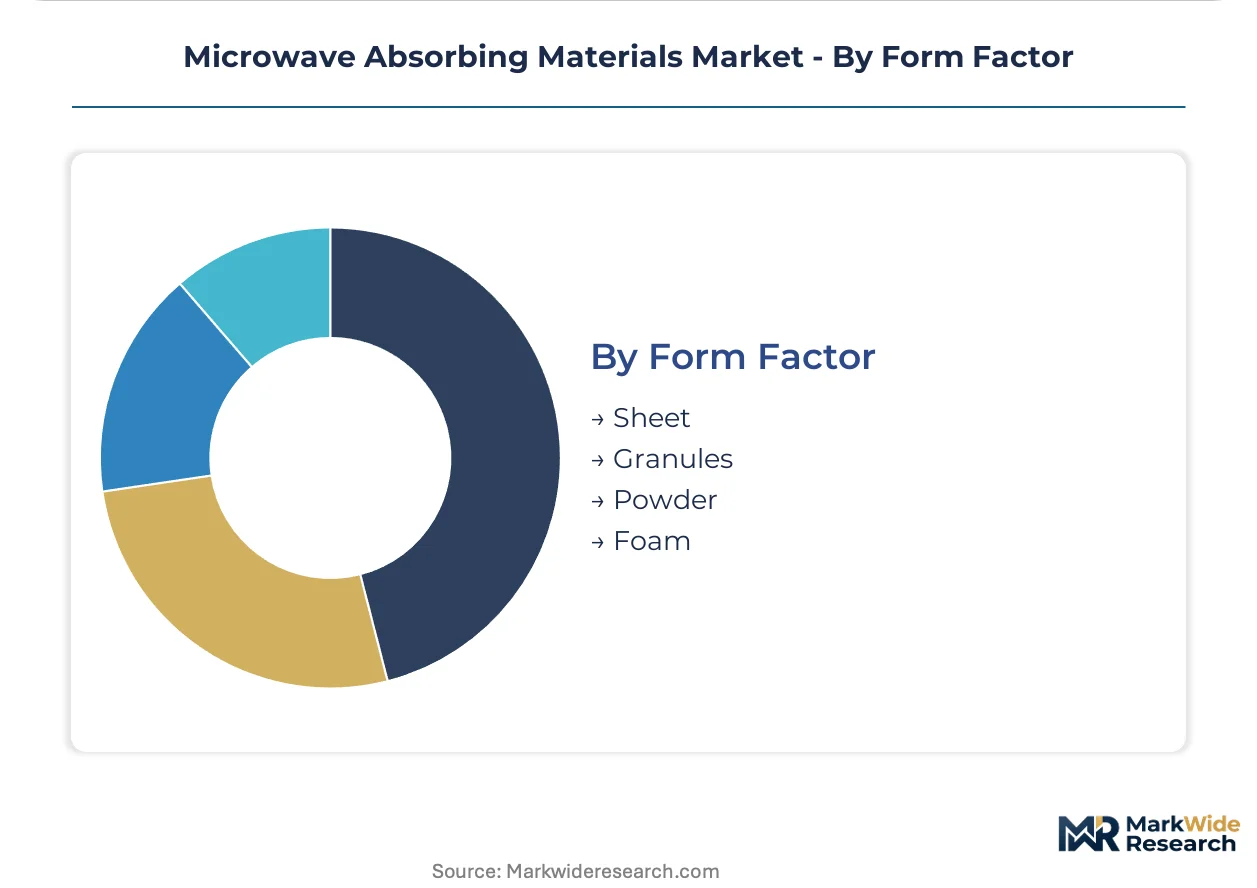
Form Factor:
Manufacturing process compatibility and installation method drive selection, with sheet and foam serving structural applications while granules and powder feed compound formulations.
- Sheet:Laminated absorber panels for flat surface applications. Standardized dimensions serve telecommunications enclosure manufacturers seeking rapid assembly integration.
- Foam:Lightweight, conformable absorber structures for anechoic chambers and payload fairings. Satellite manufacturers prioritize mass reduction for launch cost containment.
- Granules:Pelletized feedstock for injection molding and extrusion compounding. Automotive radar housing production in Germany and Japan relies on consistent granule sizing for process stability.
- Powder:Fine particulate for coating formulations and custom composite blending. Naval platform integrators specify powder grades for castable absorber viscosity control.
Highest shipment volume: Sheet. Gaining share fastest: Foam.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense electronics procurement concentrates demand in Germany's industrial corridor, where automotive radar integration pulls specialized absorber development from material suppliers across three continents.
United States
Military procurement through the Department of Defense mandates MIL-STD-285 shielding effectiveness validation, extending commercial qualification timelines by 18-24 months. The FCC governs electromagnetic emissions limits for commercial telecommunications equipment under Part 15. North American OEMs in the Pacific Northwest and Southwest are pre-qualifying dual-use materials that satisfy both commercial emissions limits and provisional military thresholds.
Germany
Automotive radar module suppliers in Germany's industrial corridor are compressing supplier qualification cycles and unbundling after-sales technical support from material supply contracts. The EU AI Act imposes conformity assessment burdens on radar-integrated automotive systems entering European markets. Tier 1 suppliers in Bavaria and Baden-Württemberg demand absorber suppliers assume cavity design optimization responsibilities previously retained in-house.
China
Rare earth oxide inputs for ferrite absorber production concentrate in Chinese processing facilities, exposing formulators to geopolitical supply disruption risk. The country's national electromagnetic compatibility regulator enforces GB standards for telecommunications equipment. Industrial clusters in the Yangtze River Delta and Pearl River Delta feed carbon-based formulation scale into commercial telecommunications supply chains.
Japan
Automotive electronics manufacturers in Japan are driving buyer consolidation patterns most visibly, demanding tiered pricing stratification from absorber suppliers. METI oversees industrial standards coordination for radar-integrated systems. The Kansai region around Osaka and the Chubu region around Nagoya concentrate injection-moldable polymer compound development for automotive radar housings.
United Kingdom
Aerospace thermal management applications capture premium margin pools, with satellite payload manufacturers adopting graphene-enhanced dielectric composites for mass budget constraints. The country's national aerospace regulator imposes airworthiness frameworks beyond baseline absorber performance. The Southeast and Midlands regions host defense contractor facilities where electromagnetic compatibility test engineering skill sets concentrate, constraining commercial certification throughput.
Microwave Absorbing Materials Market Competitive Landscape
Portfolio diversification dominates the current landscape as suppliers bridge bifurcated military and commercial qualification pathways. The vendor base stratifies across three tiers: integrated conglomerates with electromagnetic shielding heritage, specialized absorber formulators with castable and laminate expertise, and regional compounders serving price-sensitive telecommunications equipment. Two archetypes define competitive positioning: defense-anchored suppliers leveraging MIL-STD certification assets, and automotive-focused compounders optimizing injection-moldable polymer throughput. Capacity expansion and technology licensing represent the dominant competitive moves, with players securing rare earth supply agreements and dielectric simulation software partnerships to compress development cycles.
Among North American-anchored conglomerates, Parker Hannifin Corp. and Rogers Corp. exemplify divergent specialization vectors within the electromagnetic materials space. Parker Hannifin Corp. occupies a position tied to defense contractor relationship architectures, while Rogers Corp. represents the ceramic-based laminate tier serving satellite payload applications. Cuming Microwave Corp. sits within the specialized naval platform tier, anchoring castable absorber formulation expertise for conformal coating solutions. These three entities illustrate how competitive positioning fragments across end-use concentration rather than consolidating around unified technology platforms.
| Leading Market Players |
|---|
| Parker Hannifin Corp. |
| Cuming Microwave Corp. |
| Laird Technologies |
| MAST Technologies |
| ESCO Technologies Corporation |
| 3M |
| Rogers Corp. |
| TDK Corp. |
| ARC Technologies |
| Others |
Supply & Pricing Matrix
Injection-moldable polymer compounds are simultaneously compressing automotive radar housing costs and redistributing manufacturing gravity toward Germany and Japan, where Tier 1 suppliers demand absorber vendors absorb cavity design responsibilities previously retained in-house. This production-method transition tightens margin capture at the formulation tier while loosening price discipline downstream.
Pricing Analysis
Volume-grade carbon-based absorbers trade at commodity-adjacent price points, while ceramic-based laminates and metal-filled formulations command premium tiers anchored in MIL-STD-285 certification overhead. Price differentiation hinges on electromagnetic performance bandwidth and dual-use qualification status, with automotive OEMs exhibiting acute sensitivity to per-kilogram costs and defense contractors tolerating higher unit economics for shielding effectiveness guarantees. Cost compression in polymer-based segments is intensifying because Tier 1 automotive suppliers are unbundling technical support from material contracts.
Supply Chain Analysis
Domestic-content mandates in US defense procurement and EU strategic autonomy frameworks are reshaping sourcing patterns for rare earth oxide feedstocks. Ferrite absorber production draws from Chinese processing concentration for neodymium and samarium oxides, while carbon fiber supply anchors in Japan's Toray-led ecosystem and Germany's SGL Carbon facilities. Single-source vulnerability in rare earth separation capacity exposes formulators to geopolitical disruption risk. Distribution runs through defense contractor prime channels for military grades and Tier 1 automotive module suppliers for commercial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over rare earth oxide supply and electromagnetic simulation software partnerships determines who captures formulation margin versus who bleeds value to input suppliers and design-tool vendors.
For Market Incumbents: Deploy certification asset leverage by accelerating MIL-STD-285 dual-use pre-qualification to bridge defense and automotive procurement channels. Deepen backward integration into rare earth oxide sourcing through offtake agreements with Australian and North American mining projects, insulating margin structures from Chinese supply concentration. Metamaterial substitution in satellite payloads threatens ceramic-based laminate premiums; counter by embedding graphene-enhanced dielectric composites in low-earth orbit constellation supplier specifications.
For New Entrants and Emerging Players: The price-point gap between Rogers Corp.-grade ceramic laminates and commodity carbon-loaded elastomers creates entry space for mid-tier dielectrically-tuned composites targeting 5G mmWave equipment shielding. Naval platform castable formulations represent the most penetrable niche, with Cuming Microwave Corp.'s specialization proving incumbent vulnerability to conformal coating solutions for complex hull geometries. Pursue electromagnetic simulation software partnerships to compress development cycles toward automotive-speed qualification protocols.
For Investors and Strategic Acquirers: Exit pathways concentrate in defense-anchored suppliers with MIL-STD certification assets and automotive-focused compounders with injection-molding throughput. Long-term viability favors entities controlling both formulation IP and raw material supply agreements. Watch FCC Part 15 enforcement intensity as the inflection indicator for commercial telecommunications specification upgrade cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Rare Earth Supply Agreement | Secures oxide feedstock outside Chinese processing concentration for ferrite formulations. |
| Dielectric Simulation Partnership | Compresses absorber development cycles from defense procurement timelines toward automotive protocols. |
| Dual-Use Pre-Qualification | Bridges MIL-STD-285 and FCC Part 15 thresholds for unified commercial-defense supplier status. |
| Castable Formulation Capacity | Captures naval platform conformal coating demand from hull integrators seeking complex geometry solutions. |
| Graphene Composite Scale-Up | Displaces ceramic laminates in low-earth orbit satellite payloads facing mass budget constraints. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with electromagnetic compatibility test engineers, defense contractor procurement leads, Tier 1 automotive radar module suppliers, and material formulation R&D directors. FCC Part 15 enforcement databases, EU AI Act conformity assessment registries, and MIL-STD-285 certification logs provided compliance trajectory validation. Bottom-up segment sizing triangulated against top-down defense electronics procurement forecasts and automotive radar unit production estimates.
Data-stream reconciliation across product type, material chemistry, application end-use, and form factor dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level demand elasticity modeling against regulatory mandate timelines and technology substitution curves. Forecast inputs incorporated 5G mmWave spectrum allocation decisions and NATO supplier qualification restructuring patterns.
Inputs from defense procurement databases and automotive production registries were available through the study window; gaps in real-time rare earth oxide spot pricing and electromagnetic simulation software licensing terms introduce uncertainty bands around formulation cost projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Melamine Foam Market
Specialty Materials
EVA Interlayer for Photovoltaic Market
Specialty Materials
Global Synthetic Zeolite Market
Specialty Materials
Hydrolysis Stable Polyester Films Market
Specialty Materials
Global Montan Wax Market
Specialty Materials
Medical Grade Silicone Market
Specialty Materials
Global PU Films Market
Specialty Materials
Marine Mineral Complexes from Mediterranean Shells Market
Specialty Materials
Glass Ionomer Cement Market
Specialty Materials
Fumed Silica Market
Specialty Materials
UV Stabilized Films Market
Specialty Materials
Hornbeam Market
Specialty Materials
Global Cellulose Esters Market
Specialty Materials
Asia-Pacific Reflective Tape Market
Specialty Materials
Electrode Paste Market
Specialty Materials
Plastic Dielectric Films Market