
 Cadmium Sulfide Market | 2026-2036
Cadmium Sulfide Market Size, Share, and Industry Trends Forecast 2026-2036
Cadmium Sulfide Market Analytics
Buyer concentration in the photovoltaic sector is pivoting toward vertically integrated solar module producers that internalize thin-film deposition processes. Korea Zinc anchors cadmium feedstock supply through integrated zinc smelting operations. Henan Yuguang Gold & Lead Co., Ltd. dominates Chinese domestic refining capacity for cadmium-based precursors. Stanford Advanced Materials specializes in high-purity sputtering targets for research-scale semiconductor fabrication.
Cadmium sulfide is a binary II-VI compound semiconductor with a direct bandgap of approximately 2.42 eV at room temperature, typically synthesized through chemical precipitation or vapor transport methods for use as a buffer layer in thin-film solar cells, photoconductive sensors, and pigment applications. Powder formulations for pigment applications represent the most mature revenue pool with stable offtake from plastics and coatings manufacturers, while sputtering target demand for electronics and semiconductor R&D exhibits the fastest growth trajectory as research institutes scale thin-film device prototyping. The renewable energy industry vertical commands the largest volume share through photovoltaic deployment, though healthcare and aerospace end users generate premium pricing for specification-grade material.
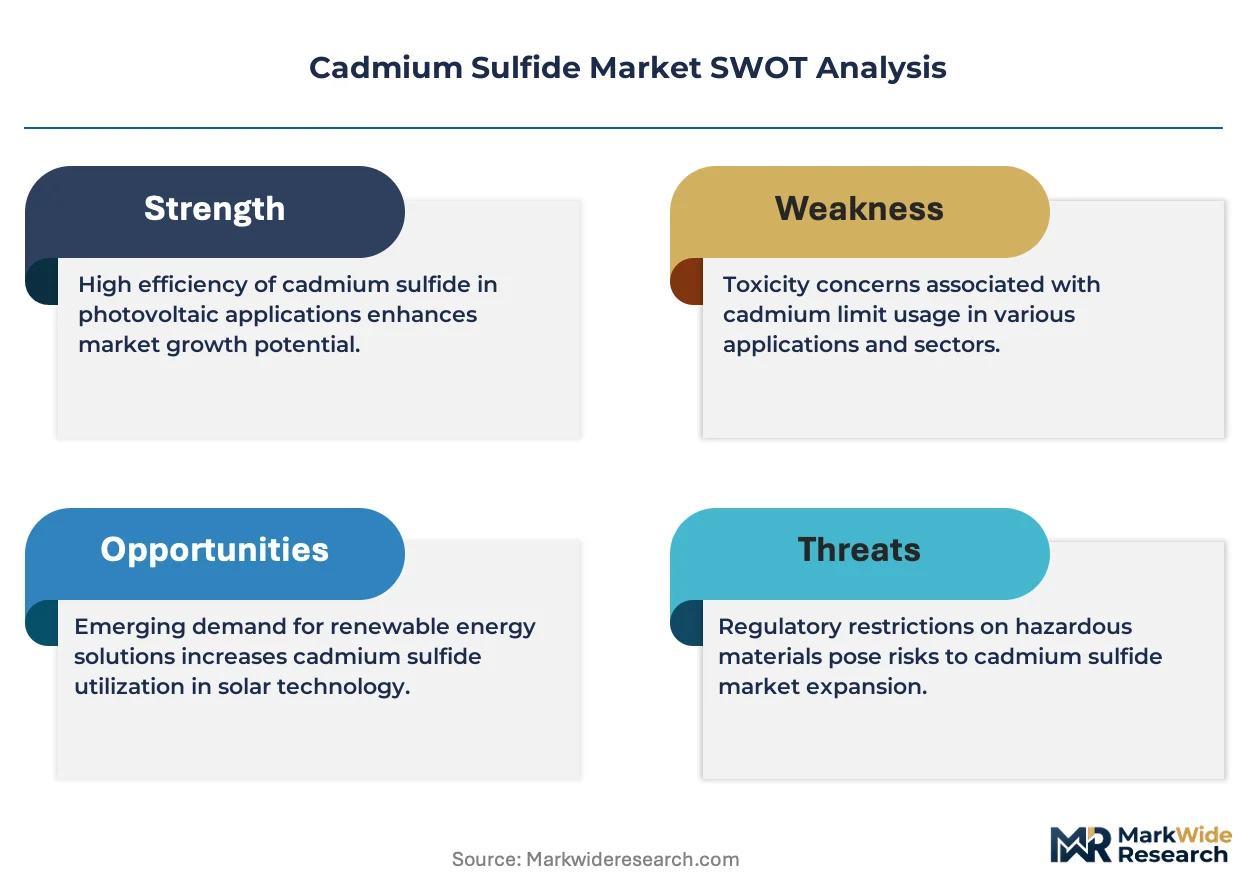
EPA oversight of cadmium compounds under the Toxic Substances Control Act constrains manufacturing emissions and waste disposal pathways in the United States, while REACH registration requirements and RoHS restrictions across Europe limit unrestricted cadmium use in consumer-facing applications. China's MEE enforces discharge standards for heavy metal processing that elevate compliance costs for domestic refiners. Stakeholders must monitor evolving substitution dynamics as cadmium-free buffer layer research advances in photovoltaic laboratories worldwide.
Market Dynamics
Photovoltaic cell manufacturers are consolidating thin-film deposition capabilities in-house, compressing merchant demand for cadmium sulfide precursors while elevating specification requirements for remaining external suppliers.
Growth Catalysts
- Thin-film solar deployment:Cadmium telluride module producers in the United States and China are expanding manufacturing footprints, pulling demand for buffer layer materials through captive and merchant channels.
- REACH registration pathways:European formulators are securing downstream-use authorizations for encapsulated pigment grades, preserving market access against outright substitution.
- Zinc smelting byproduct recovery:Integrated zinc refiners in East Asia are extracting cadmium feedstock from electrolytic residue streams, expanding raw material availability for regional sulfide production.
Market Restraints
- RoHS restrictions on cadmium compounds:European electronics manufacturers face outright bans on cadmium content in consumer-facing devices, eliminating a historical demand channel for high-purity sulfide.
- Feedstock concentration in zinc smelting:Over two-thirds of refined cadmium originates as byproduct of primary zinc production, tying supply to base metal economics and geographic concentration in China and Korea.
- Cadmium-free buffer research:Laboratory-scale development of zinc oxysulfide and tin sulfide alternatives at NREL and Fraunhofer institutes threatens long-term substitution in photovoltaic applications.
Strategic Opportunities
- India solar manufacturing incentives:Production-linked incentive schemes for photovoltaic module assembly are attracting thin-film investments that would localize buffer layer procurement.
- Aerospace specification-grade demand:Satellite and unmanned aerial vehicle manufacturers require radiation-hardened photoconductive sensors, commanding premium pricing for ultra-high-purity sulfide.
- Encapsulated pigment formulations:Polymer-encapsulated cadmium sulfide pigments for industrial coatings meet leach-test standards under evolving EPA and MEE discharge protocols.
Industry Challenges
- Heavy metal handling certification:Operators across the value chain must maintain OSHA and MEE-compliant workplace exposure controls, extending facility qualification timelines.
- Sputtering target fabrication yield:Achieving theoretical density in ceramic targets for semiconductor R&D requires specialized hot isostatic pressing capacity that remains scarce outside Japan and Germany.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cadmium Sulfide Market |
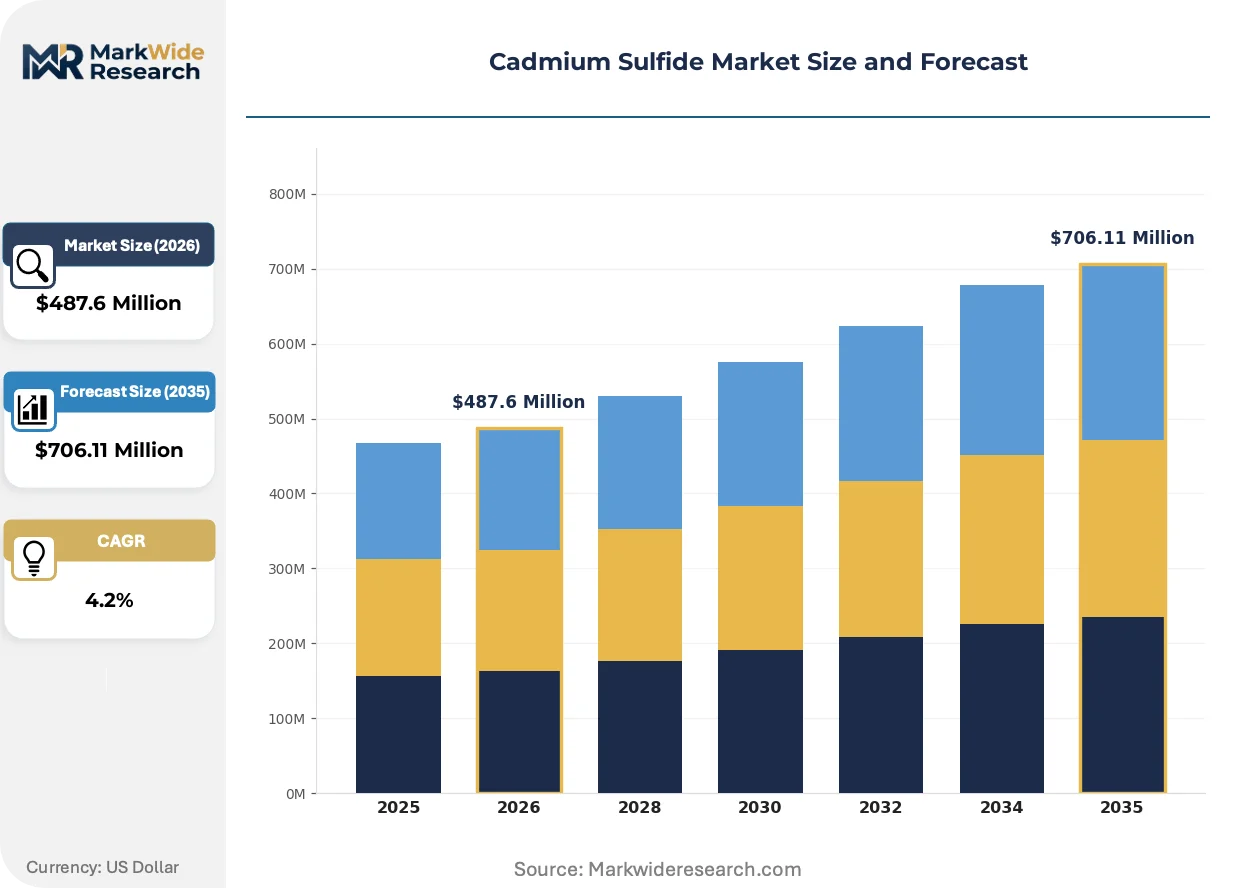
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $706.11 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granule, Sputtering Target, Coating Application: Photovoltaics, Pigments, Electronics, Semiconductors Industry Vertical: Healthcare, Automotive, Aerospace, Renewable Energy End User: Manufacturers, Research Institutes, Construction, Electronics Firms |
| Companies Covered | BASF, DowDuPont, Bayer, Lanxess, Henan Yuguang Gold & Lead Co., Ltd., Korea Zinc, Huntsman Corporation, JX Advanced Metals Corporation, Stanford Advanced Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cadmium Sulfide Market Evolving Landscape
Process intensification and regulatory compliance automation are reconfiguring how cadmium sulfide is synthesized, qualified, and delivered to end-use verticals with diverging purity requirements.
Closed-loop chemical precipitation systems with real-time particle-size monitoring are automating quality consistency in pigment-grade production. Plastics compounders in automotive supply chains are qualifying these outputs for color-stable interior applications. The technology is compressing batch-to-batch variation penalties that previously eroded supplier margins.
EPA's revised National Emission Standards for Hazardous Air Pollutants for secondary nonferrous metals are forcing cadmium refiners to install enhanced baghouse and scrubber infrastructure. Smelters in the United States are consolidating operations to amortize compliance capital across larger throughput bases. Merchant sulfide producers dependent on domestic feedstock are negotiating long-term offtake agreements to secure volume commitments.
Vertically integrated solar module producers are internalizing buffer layer deposition through in-house chemical bath deposition lines. Equipment suppliers from Germany and Japan are shipping turnkey reactor systems to manufacturing sites in China and the United States. This pattern concentrates specification-setting power with a narrowing set of buyers capable of validating incoming material chemistry.
Cadmium Sulfide Market Segmentation
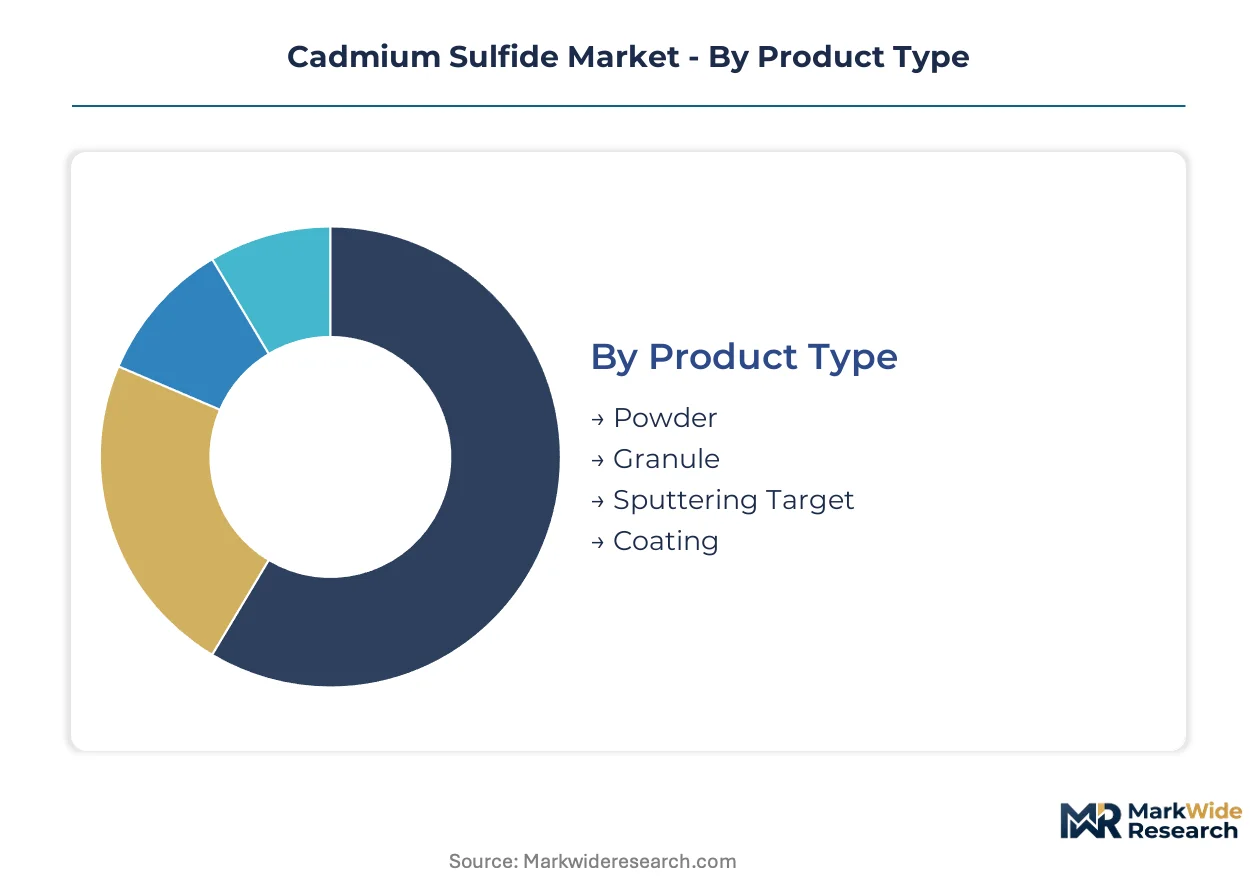
Cadmium sulfide's diverse physical forms and purity grades create distinct commercial pathways. Each segment carries unique specification requirements, regulatory exposure, and customer concentration patterns that shape supplier strategy.
Product Type:
Powder formulations dominate volume throughput while sputtering targets command the steepest price premiums per kilogram.
- Powder:Sub-micron precipitated particles serve pigment compounders and chemical bath deposition lines for photovoltaic buffer layers. Plastics manufacturers in China absorb the majority of commodity-grade offtake for color-stable automotive interior components.
- Sputtering Target:Hot isostatically pressed ceramic disks achieve theoretical density exceeding 99.5% for physical vapor deposition in semiconductor R&D. Research institutes in Japan and Germany drive procurement of these ultra-high-purity formats for thin-film device prototyping.
- Granule:Millimeter-scale fused chunks facilitate vapor transport synthesis and melt-based coating applications. Specialty chemical distributors stock these for smaller-scale electronics coating operations.
- Coating:Pre-formulated suspensions and slurries reduce handling complexity for end users lacking in-house chemical processing capabilities. Industrial coating contractors in the United States specify these for radiation-hardened sensor fabrication.
Today's leader: Powder. Tomorrow's challenger: Sputtering Target.
Application:
Photovoltaic deployment anchors volume demand while pigment applications provide revenue stability through mature customer relationships.
- Photovoltaics:Chemical bath-deposited buffer layers in cadmium telluride thin-film modules require semiconductor-grade purity with controlled stoichiometry. First Solar and Chinese module producers internalize deposition processes, compressing merchant precursor demand.
- Pigments:Polymer-encapsulated cadmium sulfide delivers color stability in high-temperature plastics processing. REACH-registered formulations preserve European market access against outright substitution bans.
- Electronics:Photoconductive sensors for industrial automation and security systems utilize polycrystalline thin films. RoHS restrictions eliminate consumer electronics applications, concentrating demand in industrial and aerospace niches.
- Semiconductors:Epitaxial layers and quantum dot research require 99.999% purity with trace metal specification below 1 ppm. National laboratories and university consortia in the United States and Germany fund this highest-specification segment.
Pigments generate the steadiest cash flows. Photovoltaics face the most substitution pressure from zinc oxysulfide alternatives.
Industry Vertical:
Renewable energy procurement dwarfs other verticals in tonnage while aerospace specifications create the most demanding qualification barriers.
- Renewable Energy:Thin-film solar module manufacturing consumes buffer layer materials at scale. Vertically integrated producers in China and the United States control specification-setting through captive deposition lines.
- Aerospace:Satellite manufacturers require radiation-hardened photoconductive sensors with documented lot traceability and thermal cycling resistance. Prime contractors pay 3-5x commodity pricing for certified material.
- Healthcare:Biomedical imaging and diagnostic equipment utilize cadmium sulfide in specialized photodetector arrays. FDA device regulations impose validation requirements that extend supplier qualification timelines.
- Automotive:Pigment applications in interior plastics and under-hood components demand thermal stability above 150°C. Tier-1 compounders in Germany and Japan specify encapsulated grades to meet OEM substance restrictions.
Renewable Energy holds volume dominance. Aerospace commands the highest unit margins.
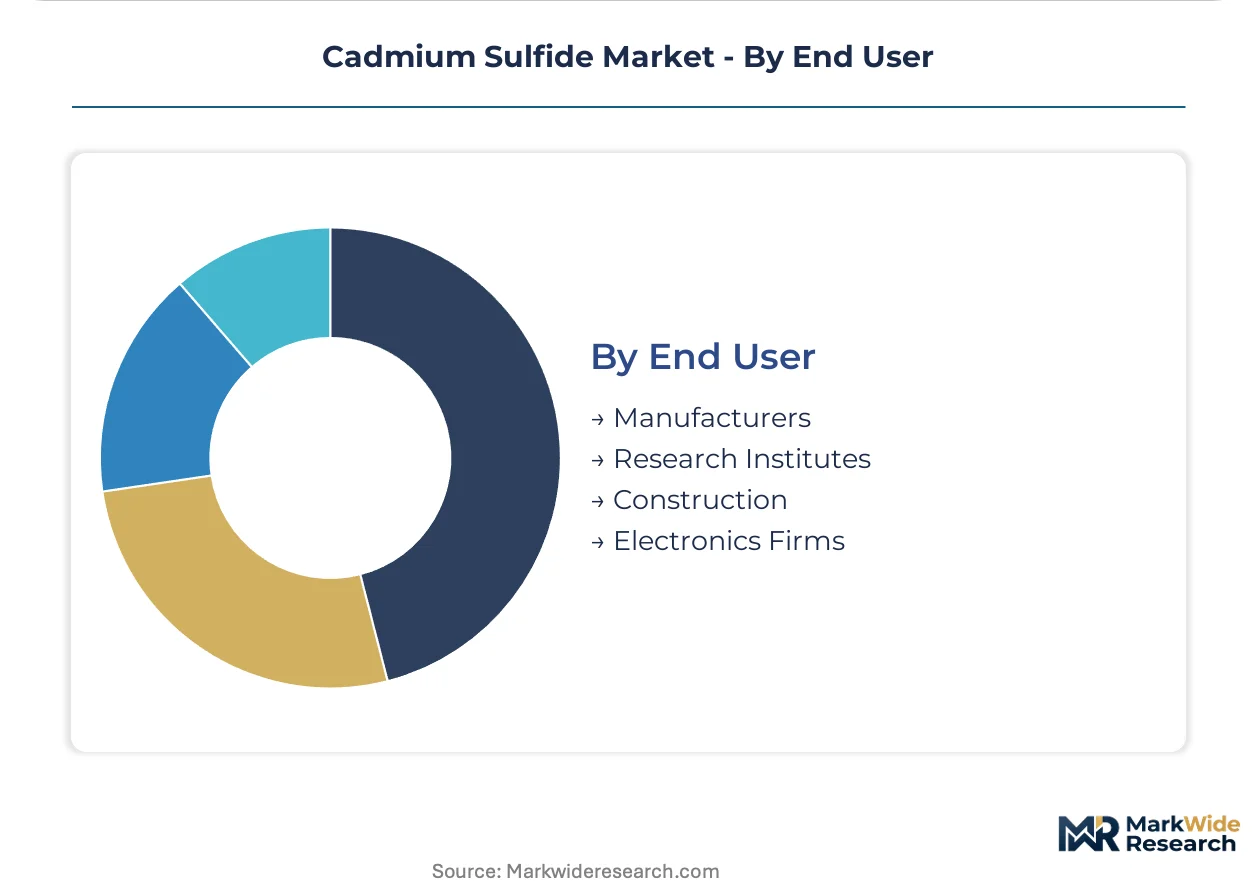
End User:
Large-scale manufacturers drive procurement standardization while research institutes tolerate pricing volatility for specification flexibility.
- Manufacturers:Solar module and pigment compounder operations negotiate annual contracts with volume commitments and technical service requirements. These buyers consolidate supplier bases to reduce qualification overhead.
- Research Institutes:National laboratories and university centers purchase small-lot, ultra-high-purity material with custom specifications. Procurement tolerates 6-12 month lead times for specialized sputtering target geometries.
- Construction:Architectural coating applications for specialized glazing and art restoration represent fragmented, specification-diverse demand. Distributors serve this channel through stocked powder and suspension formats.
- Electronics Firms:Industrial sensor and specialty component producers require consistent batch-to-batch performance in photoconductive applications. These mid-scale buyers balance price sensitivity with reliability requirements.
Manufacturers concentrate purchasing power. Research institutes expand fastest as thin-film device R&D accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes the majority of cadmium sulfide supply for photovoltaic and pigment manufacturing, while the United States maintains specialized demand for semiconductor-grade material and aerospace applications.
China
Domestic solar wafer production and pigment manufacturing absorb most regional cadmium sulfide output. MEE discharge standards for heavy metal processing elevate compliance costs for refiners in Henan and Hunan provinces. The Yangtze River Delta hosts concentrated thin-film module assembly operations that internalize buffer layer deposition.
United States
First Solar and cadmium telluride module producers drive demand for semiconductor-grade buffer layer precursors. EPA oversight under the Toxic Substances Control Act constrains manufacturing emissions and waste disposal pathways. Ohio and Arizona manufacturing clusters integrate chemical bath deposition lines that reduce merchant precursor procurement.
Germany
Research institutes at Fraunhofer ISF and university consortia procure ultra-high-purity sputtering targets for thin-film device prototyping. REACH registration requirements and RoHS restrictions limit unrestricted cadmium use in consumer-facing applications. The Dresden-Leipzig semiconductor cluster concentrates specification-grade material demand.
Japan
Hot isostatic pressing capacity for ceramic sputtering targets remains concentrated among specialized fabricators serving national laboratories. METI industrial policy supports advanced materials R&D through university-industry partnerships. The Kyushu region maintains legacy photoconductive sensor manufacturing for industrial automation applications.
South Korea
Korea Zinc anchors regional cadmium feedstock supply through integrated zinc smelting operations at Onsan. Domestic photovoltaic module assembly creates captive demand for buffer layer materials. The Gumi electronics cluster sources specification-grade sulfide for photodetector array fabrication.
Cadmium Sulfide Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct specification tiers in the cadmium sulfide market. Consolidation among zinc smelting operations has concentrated upstream feedstock control, while downstream formulation remains fragmented across pigment compounders and specialty chemical distributors. Three strategic archetypes dominate: integrated zinc refiners extracting cadmium byproduct, high-purity materials specialists serving semiconductor R&D, and encapsulated pigment formulators navigating REACH compliance. Capacity expansion and geographic diversification represent the dominant competitive moves as suppliers seek to amortize regulatory compliance costs across larger throughput bases.
Within the integrated refiner archetype, Korea Zinc and Henan Yuguang Gold & Lead Co., Ltd. occupy positions tied to zinc smelting economics and regional feedstock access. Stanford Advanced Materials exemplifies the high-purity specialist tier, serving research-scale demand with specification flexibility. These three entities represent contrasting scale and specialization vectors that structure competitive positioning across merchant and captive supply channels.
| Leading Market Players |
|---|
| BASF |
| DowDuPont |
| Bayer |
| Lanxess |
| Henan Yuguang Gold & Lead Co., Ltd. |
| Korea Zinc |
| Huntsman Corporation |
| JX Advanced Metals Corporation |
| Stanford Advanced Materials |
| Others |
Value Network & Pricing Analysis
Photovoltaic module manufacturers consolidating chemical bath deposition capabilities are squeezing merchant precursor margins while elevating purity specifications for remaining external suppliers, forcing sulfide producers to absorb qualification costs or exit the merchant channel entirely.
Pricing Analysis
Capacity additions in China are reshaping price floors for commodity-grade powder formulations as Henan Yuguang Gold & Lead Co. expands electrolytic residue processing. Three-tier pricing structure across aerospace specification-grade, semiconductor-grade, and commodity pigment tiers reflects certification burden and volume scale. Cost compression in commodity pigment grades is intensifying because REACH-registered encapsulated formulations command regulatory compliance premiums. Solar module producers exhibit the highest price sensitivity due to captive deposition alternatives, while research institutes tolerate premium pricing for custom sputtering target geometries.
Supply Chain Analysis
India's production-linked incentive schemes for solar manufacturing are redirecting procurement patterns toward localized buffer layer sourcing. Supply concentrates in China, South Korea, and the United States for distinct specification tiers. Cadmium feedstock draws from zinc smelting byproduct streams, hot isostatic pressing capacity, and encapsulated pigment polymer systems. Single-source vulnerability pervades the sputtering target tier where Japanese and German fabricators control theoretical density achievement. Distribution runs through specialty chemical distributors for research-scale volumes and direct long-term contracts for photovoltaic producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through specification-grade tier migration as aerospace and semiconductor buyers absorb compliance-driven cost pass-throughs that commodity pigment purchasers resist.
For Market Incumbents: Acquire hot isostatic pressing capacity in Germany or Japan to secure sputtering target fabrication yield. Korea Zinc and Henan Yuguang should lock in long-term offtake agreements with First Solar and Chinese module producers before zinc oxysulfide alternatives mature at NREL. Backward integration into encapsulated polymer systems preserves European pigment market access against outright REACH substitution bans. For New Entrants and Emerging Players: The 3-5x pricing gap between aerospace specification-grade and commodity pigment grades creates entry space for mid-purity semiconductor-grade specialists. Target India's emerging solar manufacturing cluster where PLI incentives are attracting thin-film investments without established supplier relationships. Qualify encapsulated formulations under evolving EPA discharge protocols to serve industrial coating contractors seeking leach-test compliance. For Investors and Strategic Acquirers: Asymmetric upside sits with high-purity materials specialists serving national laboratory R&D procurement. Five-to-ten-year viability hinges on cadmium-free buffer layer substitution timelines at Fraunhofer and NREL. Watch zinc oxysulfide laboratory-scale efficiency milestones as the inflection signal for photovoltaic demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc Smelting Byproduct Recovery | Korea Zinc's electrolytic residue processing secures captive cadmium feedstock against base metal price volatility. |
| Hot Isostatic Pressing Capacity Expansion | Japanese fabricators serving Fraunhofer institutes control theoretical density achievement for semiconductor R&D targets. |
| REACH-Registered Encapsulated Pigment Formulation | Polymer-encapsulated grades preserve European coatings market access against RoHS outright bans. |
| Long-term Supply Agreement with Solar Module Producers | First Solar's Ohio and Arizona clusters internalize deposition lines that compress merchant demand. |
| Joint Venture for India Solar Manufacturing Localization | PLI schemes attract thin-film investments that would localize buffer layer procurement away from Chinese supply. |
Research Methodology
Direct dialogue with zinc refinery operations managers, photovoltaic procurement leads at thin-film module producers, pigment compounder technical directors, and specialty chemical distribution channel heads grounded qualitative findings. Secondary validation drew from EPA NESHAP filings for secondary nonferrous metals, MEE heavy metal discharge standards, Korea Zinc annual smelting reports, and SEC 10-K disclosures from diversified materials conglomerates. Bottom-up segment sizing triangulated against top-down zinc byproduct availability models.
Segment-level value and volume trajectories across the projection horizon reflect grade-tier, end-use industry, and regional production hub dimensions. CAGRs derived from installed thin-film solar capacity buildouts, REACH registration pathway completion rates, and zinc smelting byproduct recovery economics. Forecast inputs incorporated NREL cadmium-free buffer layer efficiency progression and MEE compliance cost escalation for Henan and Hunan refiners.
The model assumes a particular technology adoption path; alternative pathways for zinc oxysulfide buffer layers at Fraunhofer ISF would alter the photovoltaic outlook substantially. Forecasts reflect assumptions regarding substitution timeline delays, regulatory grandfathering provisions, and aerospace specification-grade demand persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Conductive Carbon Black Market
Specialty Materials
Polyphenylsulfone Market
Specialty Materials
Super-Hard Material Market
Specialty Materials
Cellulose Derivative Excipient Market
Specialty Materials
Advanced Green Septa Market
Specialty Materials
Conductive Plastics Market
Specialty Materials
Edge Banding Materials Market
Specialty Materials
Flexible Colored Polyurethane (PU) Foams Market
Specialty Materials
Global Graphic Film Market
Specialty Materials
Conductive Fluted Sheets Market
Specialty Materials
Ballistic Protection Materials Market
Specialty Materials
Gutta-Percha Market
Specialty Materials
UV Stabilized Films Market
Specialty Materials
Global Ajinomoto Build-Up Film Substrate Market
Specialty Materials
Lab Grown Diamonds Market
Specialty Materials
Metallic Hot Stamping Foils Market