
 Acrylic Based Elastomers Market | 2026-2036
Acrylic Based Elastomers Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylic Based Elastomers Market Analysis
Aftermarket service revenue for acrylic elastomer compounding and formulation support is fragmenting across regional specialists and integrated resin producers. BASF SE leverages its Ludwigshafen polymer complex to sustain captive supply of specialty acrylate monomers for automotive grades. Arkema S.A. anchors its position through fluorinated acrylic hybrid R&D at its Serquigny facility. Zeon Corporation dominates high-purity solid elastomer output for Japanese OEM seal programs.
Acrylic based elastomers are synthetic rubbers synthesized from alkyl acrylate monomers, typically exhibiting continuous service temperatures between 150°C and 175°C with excellent resistance to ozone, weathering, and transmission fluids. These polymers serve primarily as high-performance sealing and damping materials in applications where hydrocarbon-resistant silicones prove too costly and standard nitriles thermally degrade. Hydrophobic thermoset grades occupy the deepest margin pools in automotive underhood sealing, while thermoplastic acrylic elastomers represent the fastest-expanding category as processors seek recyclable alternatives to crosslinked rubber. Liquid forms are gaining traction in medical device dip-molding applications where gel consistency and biocompatibility requirements intersect.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based acrylic processing in United States manufacturing facilities, while REACH authorization requirements in Europe restrict certain acrylate monomer chemistries in consumer-facing applications. Japan's METI chemical substance evaluation framework adds layer-specific compliance costs for exporters serving automotive Tier 1 suppliers. Stakeholders must monitor regulatory divergence between Asian production hubs and Western consumption centers when situating compounding capacity and certifying product grades for cross-border supply.
Market Dynamics
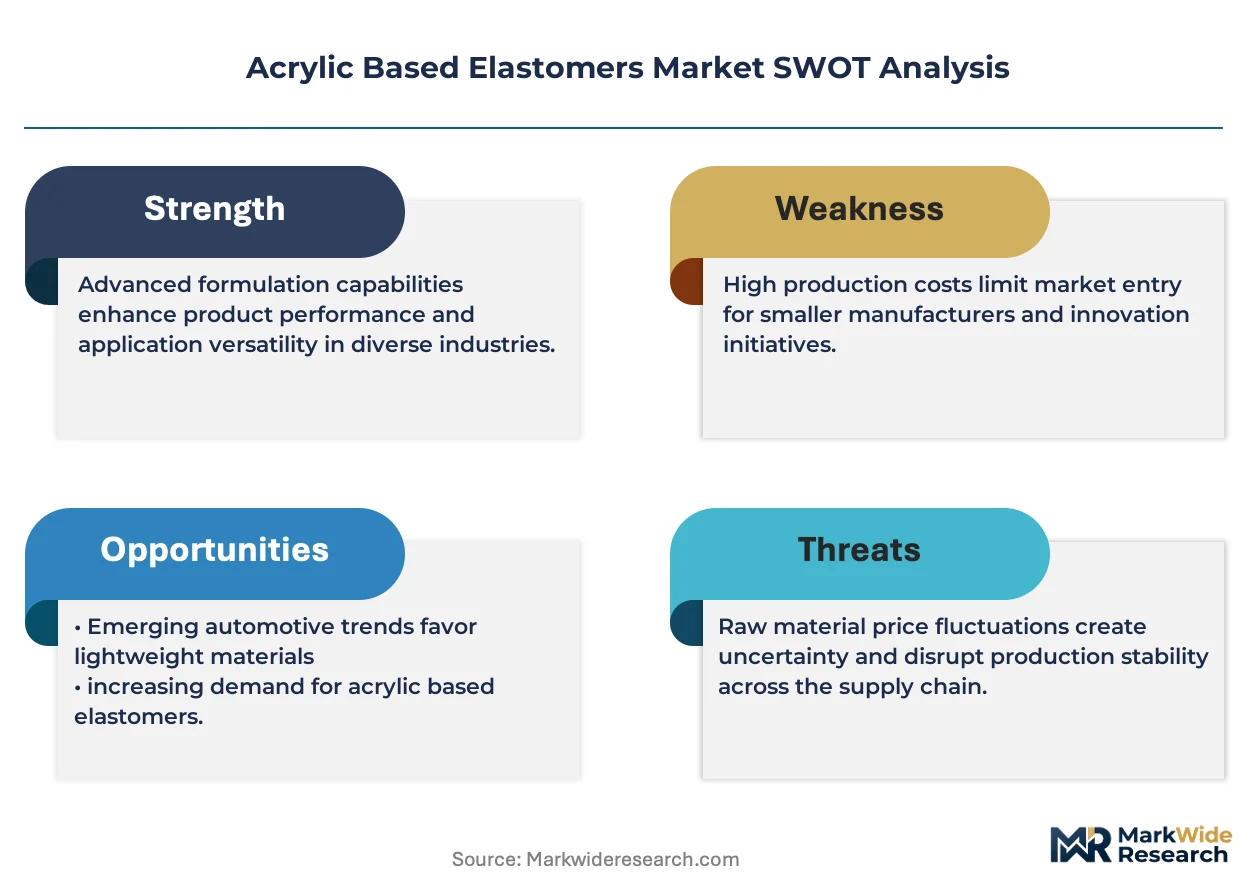
Automotive OEMs are consolidating seal specifications around heat-resistant polymers as underhood temperatures climb above 175°C, forcing compounders to abandon legacy nitrile formulations and recertify entire product lines.
Growth Catalysts
- EPA NESHAP solvent restrictions:United States manufacturers are accelerating waterborne acrylic development to meet hazardous air pollutant thresholds, expanding addressable markets for compliant compounders.
- Transmission fluid compatibility mandates:Dual-clutch and electric vehicle thermal management systems require seals that withstand synthetic lubricants at sustained elevated temperatures.
- Japan's precision polymer cluster:Concentrated automotive supplier engineering in Kanagawa and Aichi prefectures generates specification pull for high-purity solid elastomer grades.
Market Restraints
- Acrylate monomer cost volatility:Crude-linked acrylic acid feedstock prices swing with naphtha cracking economics, compressing compounder margins unpredictably.
- German automotive supplier corridor concentration:Three states dominate European seal procurement decisions, creating customer concentration risk for non-integrated compounders.
- Fluorosilicone substitution ceiling:Premium applications above 200°C service temperature permanently exit the acrylic addressable market regardless of price.
Strategic Opportunities
- Medical device dip-molding:Liquid acrylic elastomers with gel consistency are penetrating catheter and balloon markets where biocompatibility certification creates switching costs.
- EU Green Deal circularity incentives:Thermoplastic acrylic elastomer recyclability aligns with automotive OEM sustainability scorecard requirements.
- REACH authorization gaps:Certain acrylate chemistries face restricted substance listings, opening formulation windows for compliant alternative monomers.
Industry Challenges
- Cross-border certification timelines:Japan METI substance evaluation layering adds 18-24 months to automotive Tier 1 supplier qualification.
- Compounding equipment retooling:Waterborne processing lines demand capital redeployment from solvent-based infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylic Based Elastomers Market |
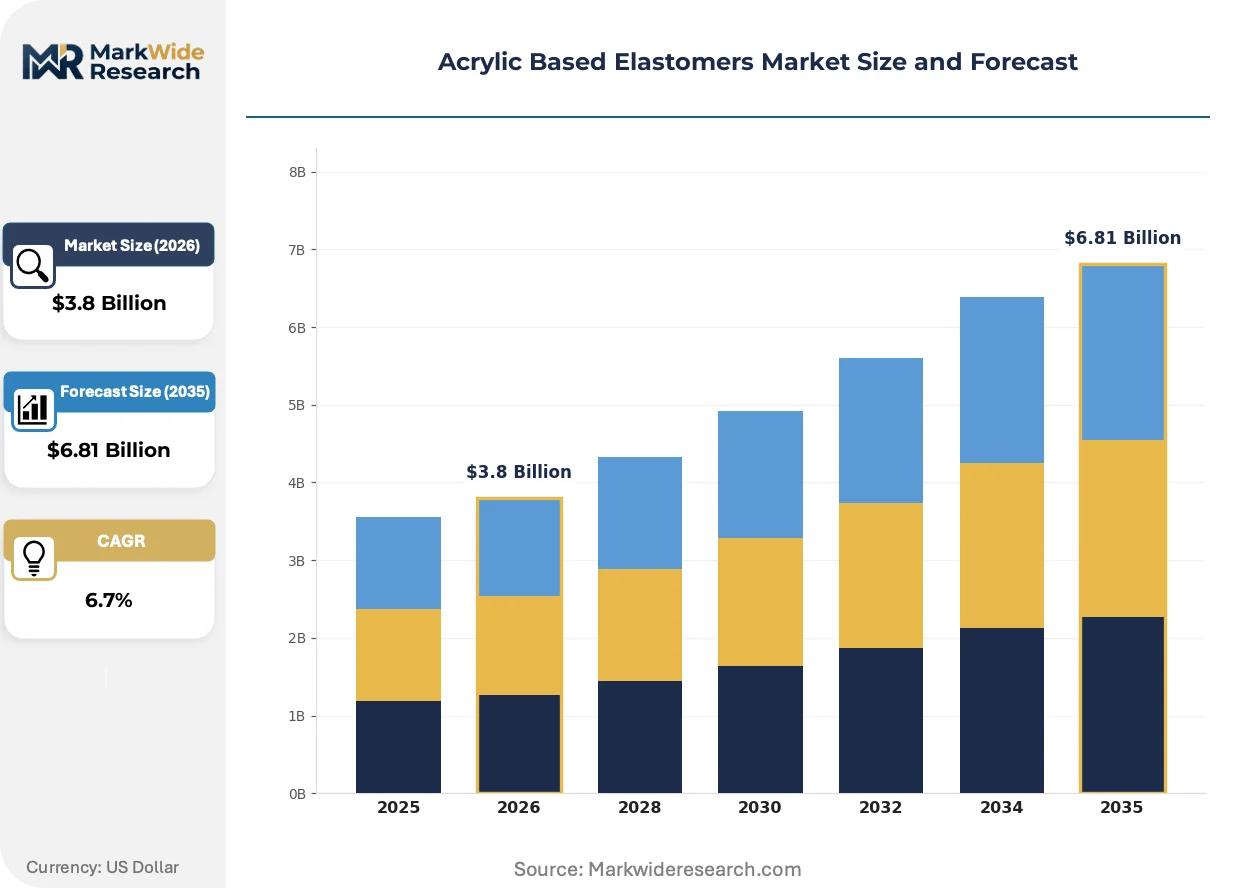
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrophobic, Hydrophilic, Thermoplastic, Thermoset Application: Automotive Seals, Medical Devices, Footwear, Coatings End User: Consumer Goods, Healthcare, Automotive, Industrial Form: Liquid, Solid, Powder, Gel |
| Companies Covered | BASF SE, Arkema S.A., Zeon Corporation, NOK Corporation, Mitsubishi Chemical Corporation, Dow Inc., Kuraray Co., Ltd., DuPont de Nemours, Inc., Denka Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylic Based Elastomers Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are converging to redefine acceptable performance thresholds and processing methods across automotive and medical applications.
Thermoplastic vulcanizate hybridization is rendering obsolete conventional thermoset acrylics in automotive weatherstrip applications. European OEMs are specifying recyclable seal architectures for 2030 model-year platforms. This shift compresses demand for permanently crosslinked grades while expanding compounder service revenue for material redesign.
REACH authorization requirements are restricting specific acrylate monomer chemistries in consumer-facing applications across European markets. Compounders must reformulate legacy automotive interior seal grades or exit those specifications entirely. German suppliers are responding fastest, leveraging captive monomer supply to certify replacement chemistries ahead of authorization deadlines.
Specification unbundling is fragmenting procurement between resin producers and regional formulation specialists. Automotive Tier 1 seal manufacturers are sourcing base polymers separately from compounding services, disintermediating integrated suppliers. This pattern concentrates most visibly in Japan's precision polymer cluster where OEM engineering offices directly qualify raw material grades.
Acrylic Based Elastomers Market Segmentation
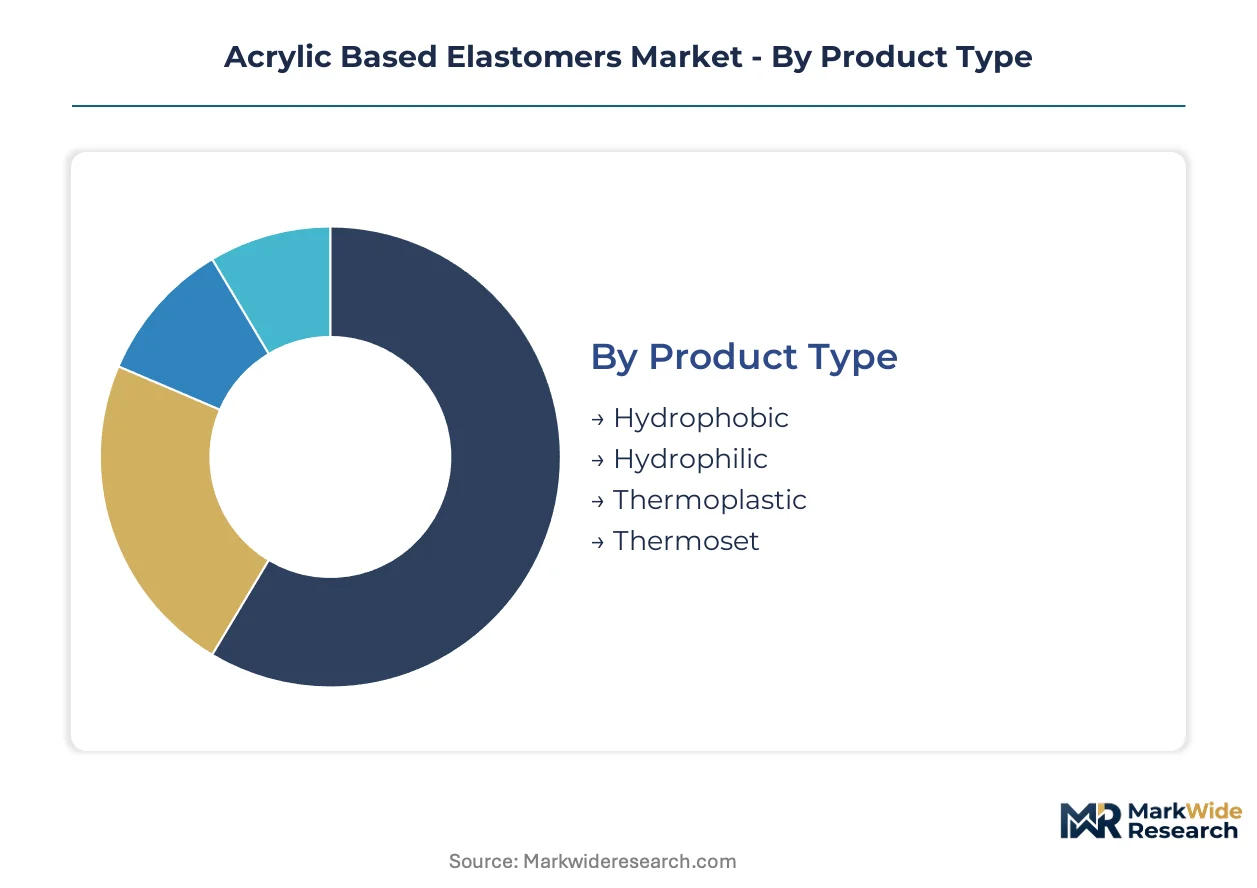
Segmentation in acrylic elastomers tracks divergent technical requirements across temperature thresholds, processing methods, and regulatory compliance tiers. Each dimension reveals distinct margin structures and qualification barriers that shape supplier positioning.
Product Type:
Mature thermoset chemistries dominate installed automotive capacity while emerging thermoplastic alternatives capture sustainability-driven redesigns.
- Thermoset:Permanently crosslinked networks deliver continuous service temperatures between 150°C and 175°C with exceptional transmission fluid resistance. Automotive underhood sealing in Germany's supplier corridor sustains specification lock-in for these grades despite permanent recyclability limitations.
- Thermoplastic:Physical crosslinking enables melt reprocessing and closed-loop recovery without property degradation. EU Green Deal circularity scorecards accelerate OEM adoption for 2030 model-year weatherstrip architectures.
- Hydrophobic:Water-repellent surface chemistry serves deep-margin automotive gaskets where moisture ingress protection commands premium pricing.
- Hydrophilic:Controlled water absorption characteristics suit medical device coatings requiring controlled permeability.
Thermoset retains volume leadership; thermoplastic holds the steepest expansion curve.
Application:
Cost tier separation runs widest between medical certification requirements and commodity footwear consumption.
- Automotive Seals:Underhood gaskets and transmission seals face sustained thermal loads above 175°C as OEMs consolidate specifications around heat-resistant polymers. Dual-clutch and electric vehicle thermal management systems drive reformulation away from legacy nitrile compounds.
- Medical Devices:Catheter balloons and dip-molded components demand gel-consistency liquid elastomers with biocompatibility certification creating steep switching costs. FDA and EMA device master file requirements extend qualification timelines.
- Coatings:Weather-resistant protective layers leverage ozone and UV stability for architectural and industrial substrates.
- Footwear:Midsole cushioning and outsole compounds compete on cost with polyurethane and EVA alternatives in price-sensitive consumer markets.
Automotive seals command the highest average selling prices; medical devices are climbing fastest on regulatory moat expansion.
End User:
Customer type concentration fragments procurement authority between integrated OEM engineering offices and distributed industrial distributors.
- Automotive:Tier 1 seal manufacturers source base polymers separately from compounding services, disintermediating integrated suppliers in Japan's precision polymer cluster.
- Healthcare:Device manufacturers prioritize batch consistency and extractable testing over unit cost, sustaining specialist compounder margins.
- Industrial:Fluid power and conveyor belt applications tolerate broader specification ranges, enabling spot-market purchasing.
- Consumer Goods:Footwear and sporting goods brands drive hard volume negotiations with limited technical differentiation.
Automotive end users absorb the largest absolute tonnage; healthcare delivers the most stable margin profile.
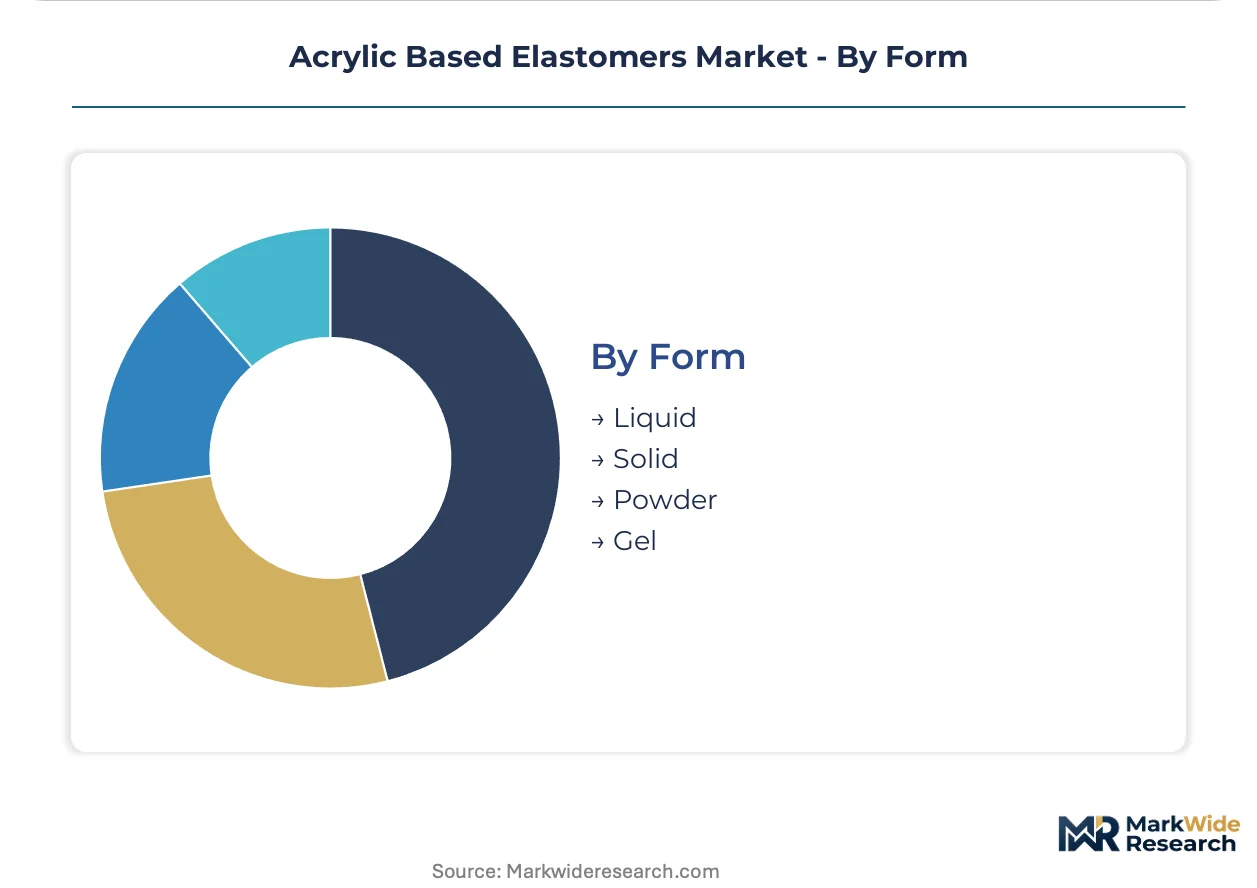
Form:
Supply concentration in high-purity solid elastomers contrasts with fragmented liquid formulation specialists.
- Solid:Baled and pelletized grades serve compression and injection molding of automotive seals with established supply chains from Japanese polymer complexes.
- Liquid:Low-viscosity pourable systems enable dip-molding and cast applications where gel consistency requirements intersect with biocompatibility mandates.
- Powder:Micronized particles support rotational molding and sintering processes for niche industrial components.
- Gel:Soft-solid consistency targets medical device interfaces requiring tissue-mimicking mechanical properties.
Solid forms retain manufacturing scale leadership; liquid and gel variants are expanding most quickly into certified medical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive seal consumption patterns diverge sharply by geography. Germany's supplier corridor prioritizes thermoset grades for underhood endurance, while Japan's precision polymer cluster drives specification unbundling toward high-purity solid elastomers.
United States
EPA NESHAP solvent restrictions compel waterborne acrylic reformulation across Midwest automotive compounding facilities. The National Emission Standards for Hazardous Air Pollutants constrain solvent-based processing lines, forcing capital redeployment toward compliant infrastructure. Detroit's Tier 1 supplier ecosystem sources base polymers separately from formulation services, fragmenting procurement authority.
Germany
REACH authorization requirements restrict specific acrylate monomer chemistries in automotive interior applications. The European Chemicals Agency's evolving substance listings force compounders to certify replacement chemistries ahead of deadlines. Ludwigshafen's polymer complex sustains captive specialty acrylate supply for heat-resistant automotive grades.
Japan
METI chemical substance evaluation frameworks add 18-24 months to automotive Tier 1 supplier qualification timelines. Kanagawa and Aichi prefectures concentrate OEM engineering offices that directly qualify raw material grades, disintermediating integrated suppliers. Zeon Corporation anchors high-purity solid elastomer output for domestic seal programs.
China
Dual-clutch and electric vehicle thermal management systems drive transmission fluid compatibility mandates for domestic OEMs. MIIT standards on volatile organic compound emissions tighten polymer production thresholds in Yangtze River Delta manufacturing zones. Local compounders face margin compression from crude-linked acrylic acid feedstock volatility.
Acrylic Based Elastomers Market Vendor Landscape
Capability concentration sits with integrated resin producers; scale advantage sits with regional formulation specialists. The vendor base stratifies across three tiers: captive monomer suppliers, independent compounders, and niche medical-grade specialists. Consolidation pressures mount as automotive OEMs consolidate seal specifications around fewer qualified suppliers. Dominant competitive moves include backward integration into acrylate monomer production and geographic expansion to serve Japan's precision polymer cluster directly.
Among integrated chemical conglomerates, BASF SE and Arkema S.A. exemplify the capability-heavy archetype through polymer complex integration and hybrid R&D positioning. Zeon Corporation occupies a specialist position in high-purity solid elastomer supply. These three entities represent distinct strategic postures: European integrated production, fluorinated acrylic hybrid development, and Japanese precision-grade manufacturing.
| Leading Market Players |
|---|
| BASF SE |
| Arkema S.A. |
| Zeon Corporation |
| NOK Corporation |
| Mitsubishi Chemical Corporation |
| Dow Inc. |
| Kuraray Co., Ltd. |
| DuPont de Nemours, Inc. |
| Denka Company Limited |
| Others |
Supply Flow & Price Mechanics
Captive acrylate monomer production at Ludwigshafen and Serquigny polymer complexes concentrates upstream margin capture with integrated resin producers, while regional compounders downstream face margin compression from crude-linked feedstock volatility. Automotive Tier 1 procurement unbundling fragments pricing power between base polymer suppliers and formulation specialists.
Pricing Analysis
Long-term offtake agreements dominate automotive seal supply contracts, insulating BASF and Arkema from spot acrylic acid volatility while exposing independent compounders to naphtha-cracking economics. Price differentiation rests on REACH certification tier and captive monomer supply. Cost compression in standard thermoset grades is intensifying because of specification consolidation by German OEMs. Footwear compounders exhibit highest price sensitivity; medical device specialists show least.
Supply Chain Analysis
Contract manufacturing concentration sits with Zeon Corporation's Kawasaki complex and NOK Corporation's sealing fabrication facilities across Aichi prefecture. Raw material flows draw from German acrylic acid crackers, Japanese butyl acrylate refiners, and Korean specialty monomer importers. Single-source vulnerability runs through Zeon's high-purity solid elastomer output for Japanese OEM programs. Distribution runs through automotive Tier 1 seal manufacturers and regional medical device compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. Automotive qualification timelines and biocompatibility certification create switching costs that protect incumbent positions.
For Market Incumbents: Entrench through backward integration into specialty acrylate monomer production and accelerated REACH-compliant chemistry certification ahead of authorization deadlines. Fluorosilicone substitution above 200°C service temperatures threatens premium acrylic grades. Capacity addition in Japan's precision polymer cluster represents the priority defensive lever. For New Entrants and Emerging Players: China's Yangtze River Delta automotive manufacturing zones offer the most penetrable geography for waterborne acrylic compounding capacity. Medical device dip-molding applications present white-space opportunity where biocompatibility certification creates specialist margin pools. Joint development agreements with catheter OEMs provide viable go-to-market positioning. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap compounders with captive monomer supply and established automotive qualification pipelines. Long-term viability across the analysis window favors suppliers with dual certification in REACH-compliant automotive grades and FDA device master files. Monitor EPA NESHAP enforcement intensity as inflection indicator for waterborne acrylic adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylate Monomers | Ludwigshafen and Serquigny complexes demonstrate margin capture from captive specialty acrylate supply. |
| Waterborne Processing Line Deployment | EPA NESHAP compliance in Midwest automotive compounding facilities expands addressable contract manufacturing. |
| REACH Alternative Chemistry Certification | ECHA authorization gaps open formulation windows for compliant monomer substitutions ahead of deadlines. |
| Medical Device Master File Investment | FDA and EMA biocompatibility pathways create specialist compounder switching costs in catheter markets. |
| Japan Precision Polymer Cluster Expansion | Kanagawa and Aichi prefecture proximity reduces METI qualification timelines for automotive Tier 1 supply. |
Methodological Framework
Desk research of customs trade data, ECHA substance registrations, and SEC chemical segment disclosures preceded structured interviews with automotive Tier 1 procurement managers, medical device regulatory affairs leads, polymer plant operations directors, and specialty chemical distribution channel heads. Primary fieldwork combined with secondary validation through ACC and Cefic industry reports, METI chemical substance evaluation databases, and IHS Markit vehicle production data. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Assumptions held fixed include regulatory enforcement intensity at observed levels and automotive thermal management specification consolidation rates; crude-linked feedstock pricing and OEM sustainability scorecard weightings were varied across scenarios. Segmentation dimensions encompassed product type, application, end user, and form factor across regional production hubs. CAGRs derived from volume trajectory modeling against value-per-ton trends. Industry-specific inputs included transmission fluid compatibility test standards and biocompatibility extractables testing protocols.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed chemical conglomerates or accelerated fluorosilicone cost reduction would shift outcomes. Quarterly review of ECHA authorization list updates, EPA NESHAP enforcement actions, and Japanese OEM seal specification unbundling velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Global Rubber Additives Market
Rubber
Silicone Rubber Market
Rubber
Tire and Rubber Lubricants Market
Rubber
US Nitrile Gloves Market
Rubber
Rubber Conveyor Belt Market
Rubber
Corrosion Protection Rubber Linings and Coatings Market
Rubber
Ethylene Propylene Rubber Cable Market
Rubber
Performance Elastomers Market
Rubber
Polyisoprene Market
Rubber
Global Tire Material Market
Rubber
Global Rubber Processing Chemicals Market
Rubber
Solution Styrene Butadiene Rubber (S-SBR) Market
Rubber
Snap on Rubber Stopper Market
Rubber
Rubber Masterbatch Market
Rubber
Global Rubber Coated Fabrics Market
Rubber
Isobutylene Market