
 Dysprosium Oxide Sputtering Target Market | 2026-2036
Dysprosium Oxide Sputtering Target Market Size, Share, and Industry Trends Forecast 2026-2036
Dysprosium Oxide Sputtering Target Market Insights
Neodymium-iron-boron magnet chemistry is hardening around heavy rare earth additives, elevating dysprosium oxide from optional dopant to critical formulation component. Tosoh Corporation leverages its ceramic powder synthesis heritage to sustain premium positioning in high-purity target supply. American Elements anchors North American availability through domestic rare earth separation partnerships. Plansee SE competes via refractory metal bonding expertise applied to oxide ceramic target architectures.
Dysprosium oxide sputtering targets are ceramic deposition sources fabricated to purity thresholds exceeding 99.9 percent, typically produced through hot isostatic pressing or vacuum sintering of calcined rare earth oxide powders for controlled thin film stoichiometry. Their primary function is enabling precise dysprosium doping of magnetic thin films, optical interference layers, and protective coatings via physical vapor deposition. High-purity targets command margin concentration from semiconductor and magnet technology applications where trace contamination degrades magnetic coercivity. Standard targets serve cost-sensitive photovoltaic and research institute segments where specification tolerance widens. Alloy configurations incorporating terbium or gadolinium represent the fastest-growing product configuration as co-doping protocols advance.
China's MIIT governs rare earth production quotas and export license administration, directly constraining dysprosium oxide feedstock availability for target manufacturers outside the country. Japan's METI maintains strategic stockpile mandates for heavy rare earth elements, creating institutional demand floor for certified high-purity material. REACH registration requirements in Europe impose substance documentation burdens on importers that favor established suppliers with compliant supply chains. Stakeholders must monitor quota announcements from Chinese regulators and evaluate captive feedstock strategies before supply tightness amplifies procurement risk.
Market Dynamics
Heavy rare earth magnet chemistry is hardening around dysprosium oxide as a mandatory coercivity additive, converting what was once an optional dopant into a non-substitutable formulation component for high-temperature neodymium-iron-boron magnets. This chemical lock-in is compressing procurement timelines and amplifying feedstock competition among sputtering target manufacturers.
Growth Catalysts
- Electric vehicle traction motor mandates:Automakers in Germany, Japan, and South Korea are specifying dysprosium-doped magnets for 800V architectures, pulling high-purity target demand from semiconductor and magnet coating applications.
- China's dual carbon goals:MIIT production quotas for heavy rare earths are tightening export availability, creating scarcity premiums that accelerate long-term offtake contracting by non-Chinese target fabricators.
- Terbium co-doping protocols:Advanced sputtering configurations incorporating terbium-oxide alloys are displacing single-element targets in next-generation magnetic thin films for aerospace actuators.
Market Restraints
- Feedstock concentration:Over 85 percent of separated dysprosium oxide originates from Chinese rare earth processors, exposing non-domestic target manufacturers to quota-driven supply interruptions.
- Hot isostatic pressing capex:Target densification requires specialized HIP vessels with refractory metal tooling, creating capital barriers for new entrants in high-purity ceramic fabrication.
- Substitution ceiling:Terbium oxide can partially replace dysprosium in some magnet grades, but coercivity penalties above 150°C limit viable substitution in automotive traction applications.
Strategic Opportunities
- Domestic rare earth separation partnerships:US and Australian rare earth developers are advancing hydrometallurgical circuits that could reduce import dependency for oxide feedstock by the early 2030s.
- Optical interference layer expansion:Dysprosium oxide thin films are penetrating infrared coating stacks for thermal imaging systems, opening demand from defense and industrial sensor OEMs outside traditional magnet channels.
- EU Critical Raw Materials Act:Strategic stockpiling mandates and processing subsidies are creating institutional demand floors for certified high-purity material with documented supply chain provenance.
Industry Challenges
- Rare earth metallurgy talent scarcity:Target manufacturers face acute shortages of ceramic powder synthesis specialists capable of controlling oxygen stoichiometry in calcined oxide precursors.
- REACH documentation burdens:European importers must maintain substance volume tracking and safety dossiers that favor incumbent suppliers with established compliance infrastructure over emerging competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dysprosium Oxide Sputtering Target Market |
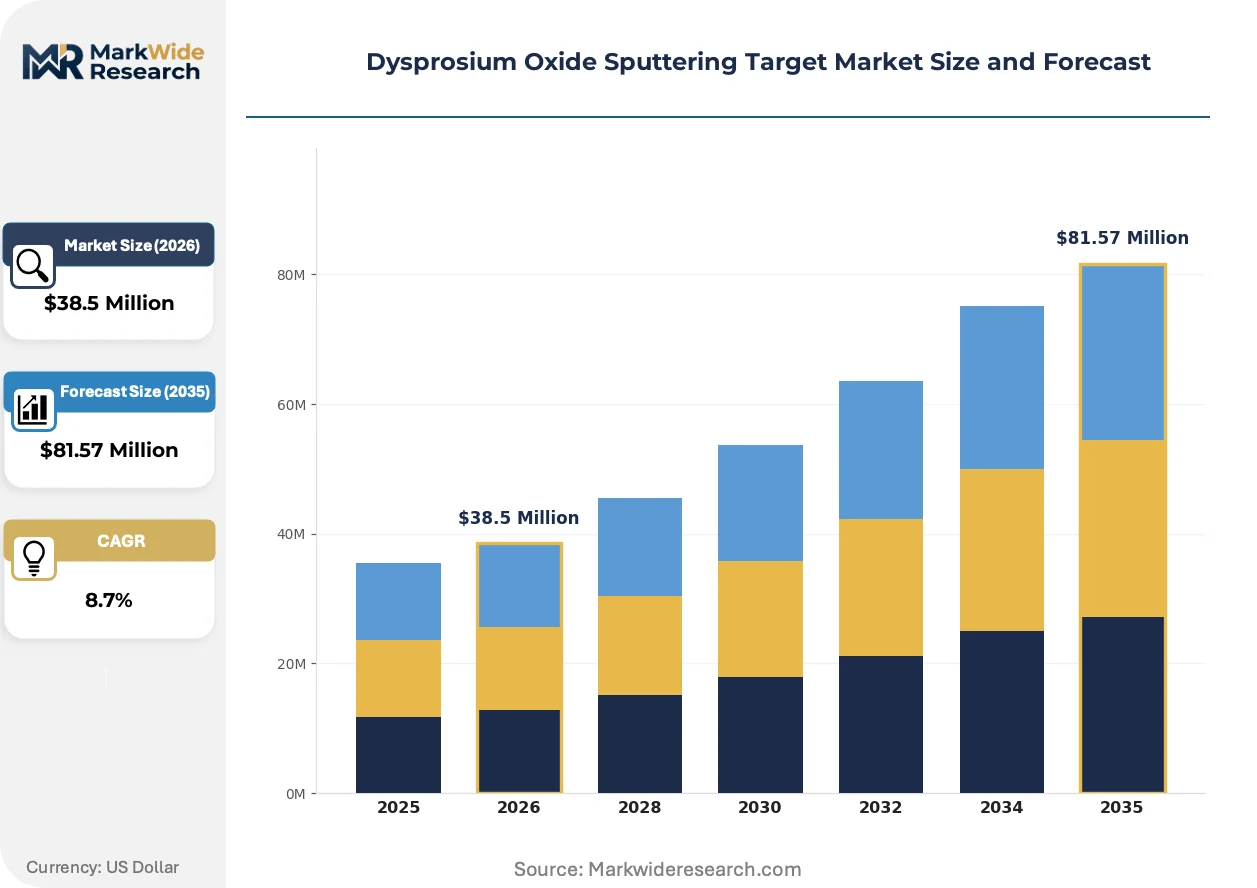
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $81.57 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Purity Sputtering Targets, Standard Sputtering Targets, Reactive Sputtering Targets, Alloy Sputtering Targets Application: Electronics Manufacturing, Thin Film Coatings, Optical Coatings, Magnet Technology End User: Semiconductor Industry, Photovoltaic Industry, Aerospace Industry, Research Institutes Form: Disc, Plate, Rod, Custom Shapes |
| Companies Covered | American Elements, Tosoh Corporation, Stanford Materials Corporation, Kurt J. Lesker Company, Materion Corporation, Plansee SE, Hitachi Metals, Heraeus, JX Nippon Mining & Metals Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dysprosium Oxide Sputtering Target Market Trends and Innovations
Magnet coating architectures are fragmenting into application-specific formulations, with sputtering target chemistry diverging between automotive traction systems requiring thermal stability and consumer electronics prioritizing deposition efficiency. This specification divergence is forcing target fabricators to maintain parallel product lines with distinct purity thresholds and bonding metallurgies.
Alloy target configurations incorporating controlled terbium-gadolinium ratios are modularizing sputtering system architectures, enabling rapid chemistry switching without chamber requalification. Semiconductor equipment OEMs in Japan and South Korea are adopting these modular sources for magnetic thin film R&D lines. The shift is compressing product development cycles from 18 months to under 6 months for new magnet stack formulations.
REACH registration requirements in Europe are hardening substance documentation standards for imported rare earth compounds, with ECHA now requiring full supply chain disclosure for heavy rare earth oxides used in industrial applications. Target importers must maintain certified analytical records from mine concentrate through final densification. High-purity ceramic suppliers with captive separation partnerships are capturing preferential placement in EU magnet manufacturer approved vendor lists.
Long-term offtake contracting is displacing spot market purchasing for high-purity dysprosium oxide feedstock, with Japanese and South Korean magnet manufacturers locking 3-5 year supply agreements directly with Chinese rare earth processors. This procurement consolidation is squeezing independent target fabricators without backward integration into oxide separation. The behavior is most pronounced in automotive supply chains where OEMs mandate documented supply security for critical magnetic materials.
Dysprosium Oxide Sputtering Target Market Segmentation
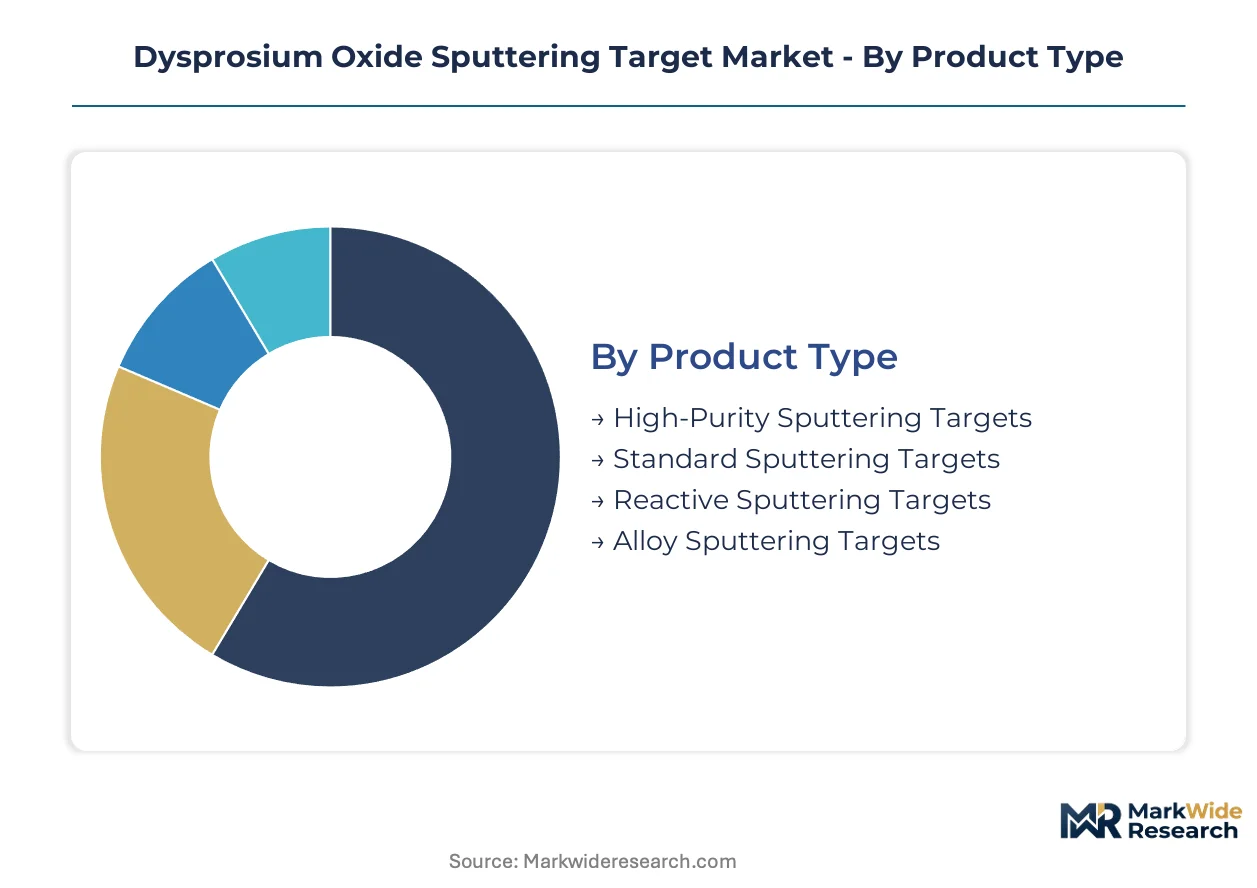
Sputtering target segmentation reveals how purity thresholds and geometric configurations map to distinct value capture opportunities. Each category reflects divergent technical requirements between standalone deposition systems and integrated manufacturing lines.
Product Type:
Integration depth varies sharply across purity grades, with embedded semiconductor lines demanding certified supply chains while research installations accept broader specification tolerances.
- High-Purity Sputtering Targets:Fabricated to 99.9 percent-plus purity through hot isostatic pressing of calcined oxide powders. Semiconductor foundries in Japan and South Korea specify these for magnetic thin film coercivity control where trace contamination degrades performance.
- Standard Sputtering Targets:Produced via vacuum sintering with wider stoichiometric tolerance. Photovoltaic manufacturers and university laboratories absorb volume here, prioritizing deposition throughput over extreme purity certification.
- Reactive Sputtering Targets:Engineered for oxygen-controlled deposition environments. Aerospace coating suppliers leverage these for protective thermal barrier applications.
- Alloy Sputtering Targets:Terbium and gadolinium co-doping configurations enable rapid chemistry switching in modular sputtering architectures.
Volume placements concentrate in Standard Sputtering Targets; the faster expansion belongs to Alloy Sputtering Targets.
Application:
Cost tier stratification separates capital-intensive electronics manufacturing from experimental coating development where equipment utilization rates differ.
- Electronics Manufacturing:Drives premium pricing through automated deposition lines requiring continuous target replacement schedules. South Korean memory chip fabricators anchor demand here with multi-chamber sputtering clusters.
- Thin Film Coatings:Encompasses protective and functional layers across industrial tooling. German automotive suppliers specify dysprosium-doped magnetic coatings for 800V traction motor components.
- Optical Coatings:Infrared interference stacks for thermal imaging systems. Defense contractors in the United States and Japan source certified high-purity material with documented supply chain provenance.
- Magnet Technology:Neodymium-iron-boron magnet doping for high-temperature coercivity stability. Chinese rare earth processors dominate feedstock supply to this channel.
Electronics Manufacturing commands the largest absolute volume; Thin Film Coatings is climbing the fastest as automotive electrification accelerates.
End User:
Customer type determines procurement modality, with institutional buyers favoring long-term contracts against spot-market flexibility preferred by experimental facilities.
- Semiconductor Industry:Requires bonded target assemblies with refractory metal backing plates. Japanese equipment OEMs specify proprietary interface geometries that lock in approved vendor relationships.
- Photovoltaic Industry:Cost-sensitive thin film deposition for cadmium telluride and copper indium gallium selenide cells. Chinese panel manufacturers drive procurement scale here.
- Aerospace Industry:Thermal barrier and sensor coating applications demanding full REACH documentation. European suppliers with captive separation partnerships capture preferential placement.
- Research Institutes:Small-batch custom geometries with extended lead time tolerance. National laboratories in the United States and Germany maintain diverse target inventories for materials science programs.
Semiconductor Industry absorbs the heaviest volume placements; Aerospace Industry shows the steepest expansion trajectory as defense thermal imaging procurement intensifies.
Form:
Geometric configuration directly constrains which deposition chamber architectures can accept feedstock, fragmenting addressable markets by equipment installed base.
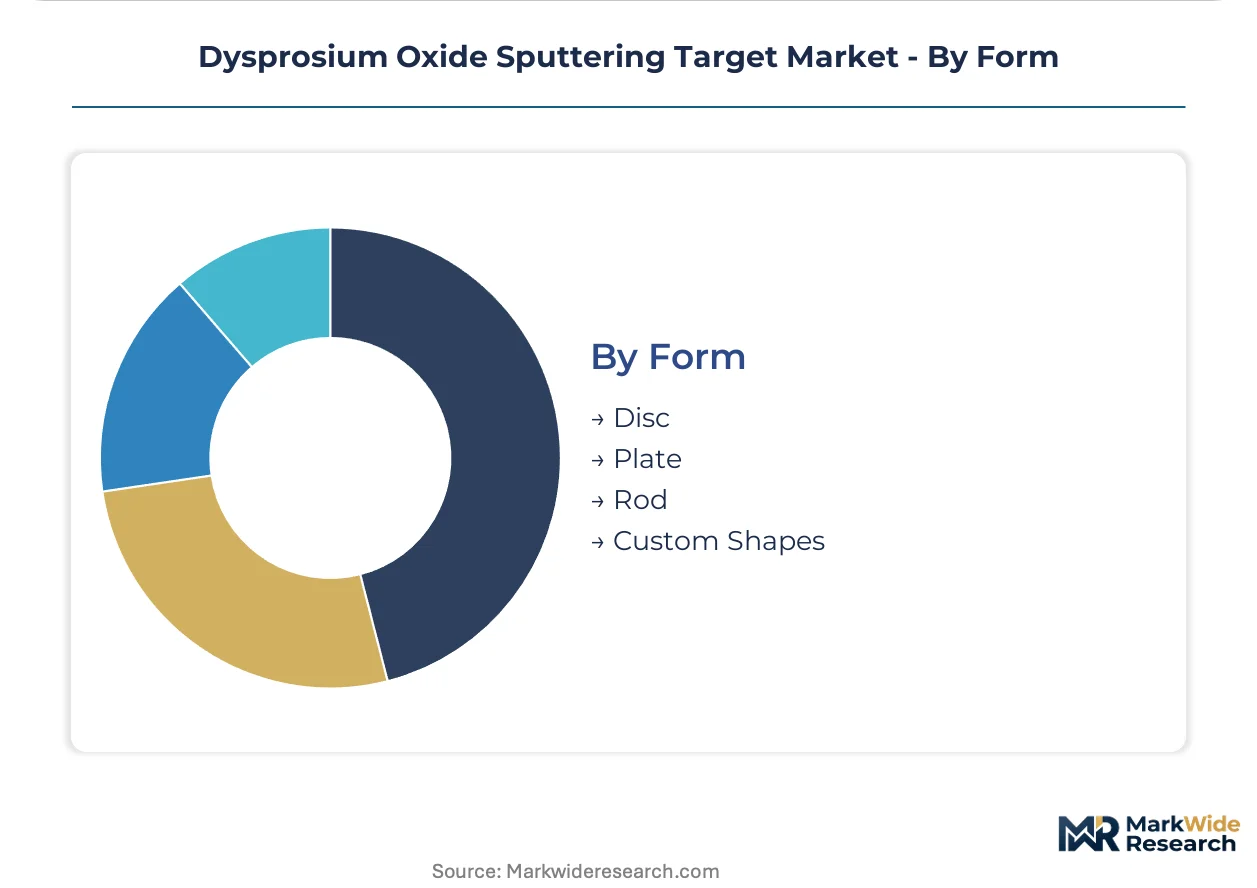
- Disc:Dominant geometry for rotating cylindrical magnetron systems. Japanese and South Korean semiconductor equipment OEMs standardize on 2-inch to 12-inch diameter specifications.
- Plate:Planar magnetron configurations for large-area coating. Photovoltaic and architectural glass manufacturers deploy these for uniform deposition across extended substrates.
- Rod:Cylindrical cathode designs enabling 360-degree sputtering coverage. Specialized aerospace coating lines utilize rod targets for complex component geometries.
- Custom Shapes:Engineered contours for legacy equipment or prototype development. Research institutes and niche industrial applications absorb this fragmented demand.
Disc configurations hold the dominant volume position; Custom Shapes is expanding most quickly as modular sputtering architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and South Korean magnet manufacturers concentrate procurement through long-term offtake agreements with Chinese rare earth processors. China's MIIT production quotas constrain export availability for non-domestic target fabricators. German automotive OEMs specify dysprosium-doped coatings for 800V traction architectures.
China
MIIT governs rare earth production quotas and export license administration, directly constraining dysprosium oxide feedstock availability for target manufacturers outside the country. The dual carbon goals tighten supply chain visibility for international buyers. Rare earth processing clusters in Inner Mongolia and Jiangxi dominate heavy rare earth separation capacity.
Japan
METI maintains strategic stockpile mandates for heavy rare earth elements, creating institutional demand floors for certified high-purity material. Semiconductor foundries in Tokyo and Osaka specify bonded target assemblies with proprietary interface geometries. Japanese equipment OEMs lock in approved vendor relationships through multi-year supply contracts.
South Korea
Memory chip fabricators anchor demand through multi-chamber sputtering clusters requiring continuous target replacement schedules. The country's national industrial policy supports magnet technology procurement for electric vehicle supply chains. Busan-Ulsan industrial corridors concentrate coating equipment manufacturing and rare earth magnet assembly.
Germany
Automotive suppliers specify dysprosium-doped magnetic coatings for 800V traction motor components under EU Green Deal electrification mandates. REACH registration requirements impose substance documentation burdens on importers that favor established suppliers. Bavaria's industrial belt hosts precision coating equipment OEMs and automotive tier-one suppliers.
United States
Defense contractors source certified high-purity material with documented supply chain provenance for infrared thermal imaging systems. Domestic rare earth developers advance hydrometallurgical circuits to reduce import dependency by the early 2030s. National laboratories maintain diverse target inventories for materials science programs across multiple sites.
Dysprosium Oxide Sputtering Target Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium-tier fabricators capturing margin concentration from semiconductor and magnet technology applications. The vendor base organizes around purity certification tiers, with high-purity specialists commanding pricing premiums against standard-grade competitors. Three archetypes dominate: captive feedstock integrators, ceramic powder synthesis specialists, and refractory metal bonding experts. Strategic moves concentrate on backward integration into oxide separation and modular alloy target development for rapid chemistry switching.
Among established fabricators, Tosoh Corporation exemplifies ceramic powder synthesis heritage applied to high-purity target supply, while Plansee SE occupies a position reframing refractory metal expertise toward oxide ceramic architectures. American Elements anchors North American availability through domestic rare earth separation partnerships. These three represent distinct strategic postures: Japanese precision ceramic processing, Austrian refractory metal integration, and US-based supply chain localization.
| Leading Market Players |
|---|
| American Elements |
| Tosoh Corporation |
| Stanford Materials Corporation |
| Kurt J. Lesker Company |
| Materion Corporation |
| Plansee SE |
| Hitachi Metals |
| Heraeus |
| JX Nippon Mining & Metals Corporation |
| Others |
Pricing and Supply Chain Analysis
Hot isostatic pressing equipment upgrades at Japanese and South Korean target fabricators are compressing production economics while China's MIIT export licensing protocols tighten feedstock availability, creating asymmetric pricing power between integrated and non-integrated manufacturers.
Pricing Analysis
Volume placements concentrate in standard-grade targets for photovoltaic and research applications, while premium pricing accrues to high-purity certified material for semiconductor foundries and magnet technology OEMs. Price differentiation hinges on purity certification thresholds and bonded target assembly complexity, with refractory metal backing plate integration commanding substantial premiums. Cost compression in standard tiers is intensifying as Chinese panel manufacturers scale procurement, while pricing stability persists in high-purity segments due to MIIT quota constraints on heavy rare earth oxide feedstock. Photovoltaic manufacturers exhibit the highest price sensitivity, prioritizing deposition throughput over certification documentation.
Supply Chain Analysis
Dysprosium oxide feedstock rests on Chinese rare earth separation clusters in Inner Mongolia and Jiangxi, with Japanese and South Korean magnet manufacturers anchoring downstream demand through multi-year offtake agreements. Critical inputs span calcined rare earth oxide powders, refractory metal tooling for HIP vessels, and certified analytical documentation for REACH compliance. Single-source vulnerability concentrates in Chinese heavy rare earth processing capacity, exposing non-domestic target fabricators to quota-driven supply interruptions. Distribution runs through direct procurement contracts from rare earth processors to target manufacturers, bypassing spot market intermediaries for high-purity material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dysprosium oxide sputtering target market is becoming a vertical-integration race, with captive feedstock control over Chinese rare earth separation emerging as the decisive competitive lever.
For Market Incumbents: Deepen backward integration into heavy rare earth oxide separation through partnerships with Australian and US rare earth developers, insulating against MIIT quota volatility. Lock in multi-year bonded target assembly contracts with Japanese semiconductor equipment OEMs to secure proprietary interface geometry relationships. Priority rests on ceramic powder synthesis talent retention as oxygen stoichiometry control becomes the scarce technical capability. For New Entrants and Emerging Players: EU Critical Raw Materials Act stockpiling mandates in Europe open a window for certified high-purity material with documented supply chain provenance, bypassing incumbent relationships in Asia-Pacific. Target aerospace thermal imaging applications where defense contractors prioritize REACH-compliant sourcing over cost minimization. Go-to-market angle centers on rapid alloy target customization for modular sputtering architectures serving R&D-intensive magnet formulation programs. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by magnet technology OEMs seeking captive target supply, with strategic value accruing to ceramic powder synthesis specialists with existing HIP infrastructure. Long-term viability favors fabricators with demonstrated terbium-gadolinium co-doping capabilities as alloy configurations displace single-element targets. Watch MIIT quota announcement timing as the critical inflection signal for feedstock cost trajectories and competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Separation | Captive oxide feedstock insulates Japanese and South Korean fabricators from MIIT quota volatility. |
| Alloy Target Configuration Development | Terbium-gadolinium co-doping capabilities enable rapid chemistry switching for modular sputtering architectures. |
| REACH Compliance Infrastructure Investment | Full supply chain documentation secures preferential placement in EU aerospace and defense vendor lists. |
| Ceramic Powder Synthesis Talent Acquisition | Oxygen stoichiometry control in calcined precursors determines high-purity target performance thresholds. |
| Long-term Offtake Contracting with Magnet OEMs | Automotive supply chain security mandates lock in demand visibility for certified high-purity material. |
Research Methodology
Document review covered customs and trade data for rare earth oxide shipments, MIIT production quota announcements, and REACH registration filings, complemented by interviews with target fabrication plant managers, procurement leads at Japanese semiconductor foundries, rare earth separation specialists, and ceramic powder synthesis R&D directors. Secondary validation drew from SEC 10-K disclosures of listed rare earth processors, ECHA substance volume tracking records, and automotive OEM magnetic material sourcing specifications. Bottom-up capacity modeling and top-down demand triangulation anchored volume and value estimates.
Cross-referencing historical price series for high-purity dysprosium oxide against panel input from equipment OEM procurement officers informed the analytical framework across the analysis window. Segmentation dimensions modeled include purity grade tier, end-use application, target geometric form, and regional regulatory cluster. CAGRs derived from supply-demand balance projections incorporating MIIT quota trajectory assumptions and electric vehicle traction motor penetration curves. Industry-specific inputs span hot isostatic pressing capacity utilization rates and terbium oxide substitution elasticity estimates.
Caveats apply where MIIT quota policy shifts, terbium substitution breakthroughs in high-temperature magnet grades, or EU Critical Raw Materials Act implementation delays could materially shift the outlook. Forecasts reflect assumptions around Chinese rare earth processing capacity expansion timelines and automotive electrification regulatory enforcement intensity. A small set of named triggers—MIIT announcement timing, terbium oxide price spreads, and EU stockpiling procurement initiation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
India Collagen Market
Specialty Materials
Melamine Foam Market
Specialty Materials
Global Polybenzimidazoles (PBI) Market
Specialty Materials
Eptfe in Spotlight-Poly-Vents Market
Specialty Materials
Super-Hard Material Market
Specialty Materials
Surface Technology Market
Specialty Materials
Specialty Silicone Market
Specialty Materials
Asia-Pacific Polyether Ether Ketone (Peek) Market
Specialty Materials
Global Consumer Foam Market
Specialty Materials
Asia Pacific Cellulose Acetate Market
Specialty Materials
Polyetherimide (PEI) Market
Specialty Materials
Vulcanized Fiber Market
Specialty Materials
Global Conductive Silicone Market
Specialty Materials
Polyester Medical Films Market
Specialty Materials
Colloidal Silica Market
Specialty Materials
Adhesion Laminated Surface Protection Films Market