
 Specialty Coating Market | 2026-2036
Specialty Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Coating Market Outlook
Waterborne resin chemistry is tilting specialty coating formulation away from high-VOC solvent systems toward low-emission industrial finishes. PPG Industries leverages its automotive refinish heritage to anchor premium positions in aerospace and transportation segments. Axalta Coating Systems competes through geographic density in automotive OEM supply chains across North America and Europe. BASF SE differentiates via integrated polymer science capabilities that extend from raw material synthesis to applied coating systems.
Specialty coatings are engineered film-forming systems, typically 25-250 micrometers dry-film thickness, composed of binders, pigments, functional additives, and curing agents designed to protect substrates from corrosion, chemical attack, thermal degradation, or electrical interference. Their primary industrial purpose is to extend asset life and enable performance in environments beyond the tolerance of standard decorative paints. Epoxy coatings dominate marine and heavy industrial maintenance due to superior adhesion and chemical resistance, while polyurethane coatings lead transportation and exterior architectural applications where UV stability and gloss retention command price premiums. Waterborne technology is gaining share fastest in regulated manufacturing environments, though solventborne systems still occupy high-performance niches where cure speed and film integrity remain non-negotiable.
EPA emissions standards and REACH chemical authorization in Europe are forcing reformulation investments and reshaping raw material procurement across the value chain. OSHA workplace exposure limits and state-level VOC regulations in California and New York add compliance complexity for U.S. manufacturing and construction end users. The EU F-Gas Regulation and evolving MEE enforcement in China are tightening environmental parameters for coating production and application. Stakeholders must monitor regulatory divergence between jurisdictions and decide whether to standardize formulations globally or maintain region-specific product portfolios.
Market Dynamics
Waterborne resin chemistry is compressing formulation cycles as manufacturers abandon solventborne systems to meet tightening VOC limits across industrial jurisdictions.
Growth Catalysts
- Automotive OEM specification upgrades:Electric vehicle battery enclosures and lightweight body structures demand thermal management coatings that solvent systems cannot deliver.
- REACH authorization timelines:ECHA's sunset dates for chromium trioxide and cadmium pigments force conversion to compliant alternatives in European aerospace and marine maintenance.
- China infrastructure scale:Bridge and pipeline investment concentrates demand for heavy-duty epoxy and polyurethane protective systems in domestic manufacturing clusters.
Market Restraints
- Titanium dioxide supply concentration:Pigment production clusters in China create input cost volatility and procurement risk for Western formulators.
- Cure speed limitations:Waterborne two-component epoxies lag solventborne equivalents in ambient temperature cure, restricting adoption in field maintenance applications.
- MEE enforcement escalation:China's Ministry of Ecology and Environment inspections shutter non-compliant coating facilities, disrupting regional supply.
Strategic Opportunities
- India manufacturing localization:PLI scheme incentives for electronics and automotive assembly create captive coating demand currently served by imports.
- UV-LED curing convergence:Combination of photoinitiator advances and LED lamp efficiency enables energy-cured industrial finishes for heat-sensitive substrates.
- Direct-to-applicator digital channels:E-commerce platforms bypass traditional distributor tiers in North American automotive refinish and wood coating segments.
Industry Challenges
- Formulation chemist scarcity:Retirement waves in polymer science and colloid chemistry constrain R&D throughput at mid-size coating houses.
- Dual certification timelines:Aerospace OEM qualification cycles for new primers and topcoats extend 18-36 months, freezing product portfolios.
- Legacy application equipment incompatibility:Existing spray booth humidity controls and gun configurations require capital retrofit for waterborne conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Coating Market |
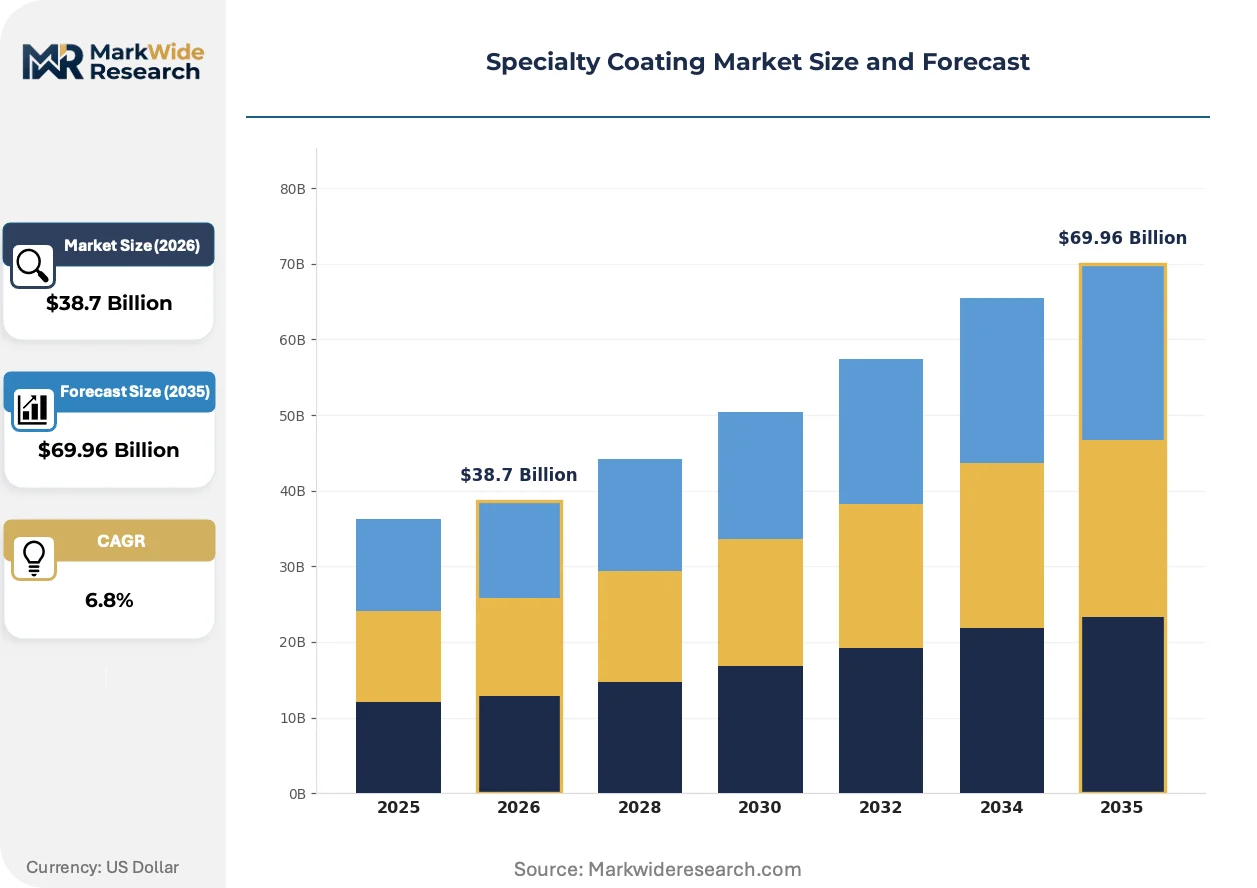
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy Coatings, Polyurethane Coatings, Acrylic Coatings, Polyester Coatings Application: Aerospace, Automotive OEMs, Marine, Electronics Technology: Waterborne, Solventborne, Powder Coating, UV-Curable End User: Construction, Manufacturing, Packaging, Transportation |
| Companies Covered | PPG Industries, Inc., Axalta Coating Systems Ltd., The Sherwin-Williams Company, Akzo Nobel N.V., BASF SE, RPM International Inc., Nippon Paint Holdings Co., Ltd., Hempel A/S, Jotun Powder Coatings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Coating Market Strategic Shifts
Functional coating architectures are diverging from commodity protective films as end-users specify performance guarantees tied to measurable substrate protection outcomes.
Self-healing polymer networks incorporating microencapsulated healing agents are migrating from laboratory demonstration to commercial marine and automotive clearcoat applications. Shipbuilders in South Korea and Germany specify these systems for ballast tank linings where mechanical damage tolerance extends maintenance intervals. The technology is migrating from premium niche positions toward mid-tier industrial specifications as capsule manufacturing scales.
EPA NESHAP standards for hazardous air pollutants from coating manufacturing operations tighten monitoring and control technology requirements. Facility upgrades for thermal oxidizers and carbon adsorption systems absorb capital that smaller formulators cannot deploy. U.S. automotive OEM supply chains accelerate qualification of waterborne basecoat alternatives to preempt compliance-driven supply disruptions.
Asset owner procurement teams now specify coating performance through warranty-backed service life guarantees rather than material certificates alone. This model transfers technical risk to applicator-contractor networks in North American infrastructure maintenance. State transportation departments in Texas and California pilot these arrangements for bridge deck waterproofing systems where traditional bid specifications failed to prevent premature failure.
Specialty Coating Market Segmentation
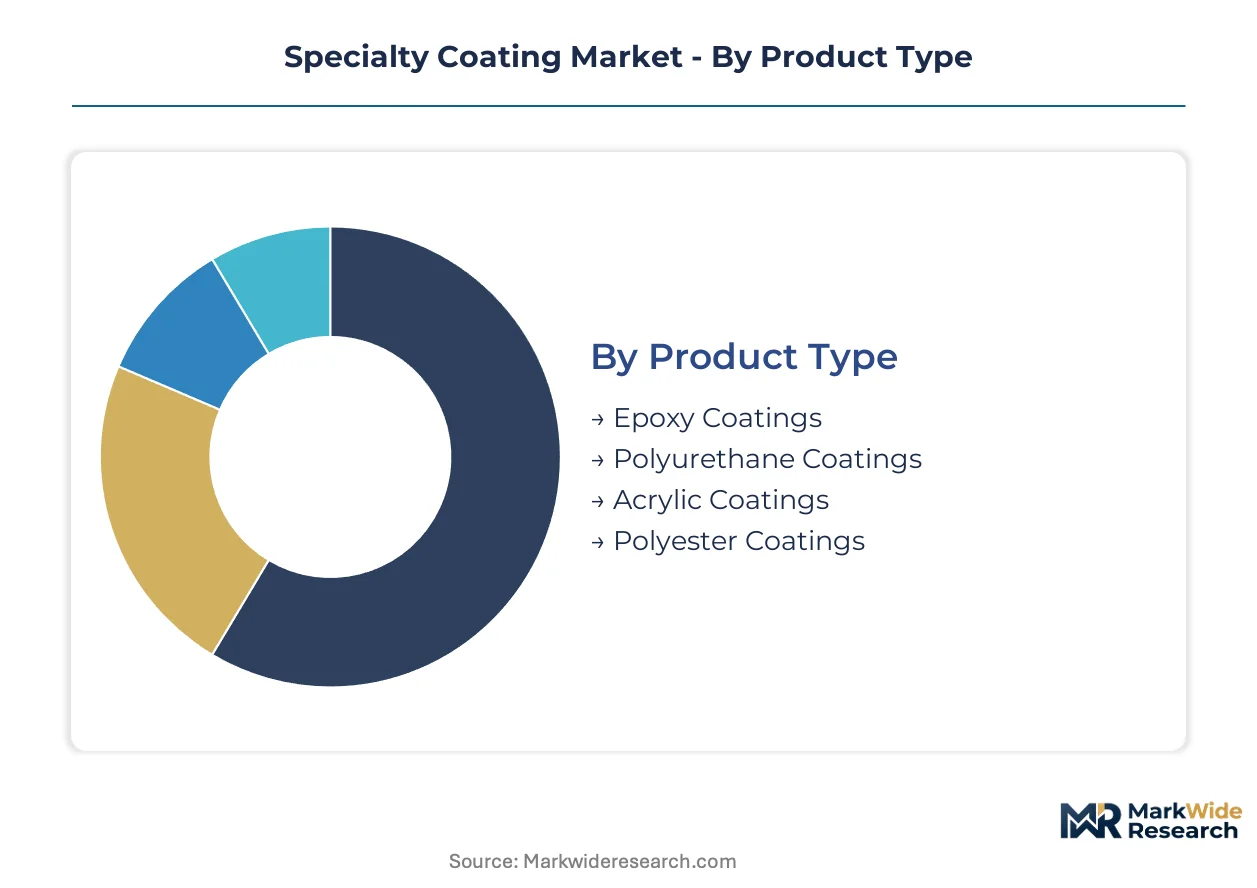
Specialty coating procurement cycles vary dramatically by formulation chemistry and end-use criticality. Specification inertia in aerospace and marine maintenance stretches replacement timelines, while automotive OEM color changes and electronics miniaturization compress decision windows. Understanding these velocity differences enables suppliers to align inventory, technical service, and pricing models to segment-specific buying patterns.
Product Type:
Epoxy systems turn over slowest due to specification lock-in for infrastructure assets, while acrylic formulations refresh fastest as architectural color trends shift seasonally.
- Epoxy Coatings:Two-component thermoset systems built on bisphenol-A or novolac backbones deliver superior chemical resistance and substrate adhesion. Demand concentrates in Chinese port infrastructure and German offshore wind installations where 20-year service life specifications dominate procurement criteria.
- Polyurethane Coatings:Aliphatic and aromatic isocyanate-cured films provide UV stability and gloss retention for exterior exposure. Automotive OEM clearcoat specifications in Stuttgart and Wolfsburg production clusters drive premium grade consumption as electric vehicle panel complexity increases.
- Acrylic Coatings:Thermoplastic and thermoset acrylics serve architectural metal and plastic substrates requiring rapid dry-to-touch properties. Color-matching services for commercial building facades in Dubai and Singapore sustain regional formulator margins.
- Polyester Coatings:Saturated and unsaturated polyester binders dominate coil coating and powder applications for appliance and building products. Chinese steel mill coating lines in Hebei Province represent the largest single consumption cluster globally.
Epoxy coatings dominate installed base. Polyurethane coatings are where expansion concentrates.
Application:
Cost tier separation is extreme: aerospace qualification costs exclude mid-tier suppliers, while marine maintenance tolerates broader vendor participation.
- Aerospace:Chromate-free primer and polyurethane topcoat systems must meet OEM qualification protocols for fuel tank, fuselage, and engine nacelle applications. Boeing and Airbus supply chains in Seattle and Toulouse enforce 18-36 month approval cycles that freeze incumbent positions.
- Automotive OEMs:Basecoat-clearcoat architectures for steel, aluminum, and composite body panels require integrated color styling and corrosion protection. Battery enclosure thermal management coatings for electric vehicle platforms in Shanghai and Detroit represent the steepest expansion trajectory.
- Marine:Anti-corrosive primers, antifouling biocide systems, and ballast tank linings protect vessels through saltwater exposure. South Korean shipbuilders in Ulsan and Geoje specify self-polishing copolymer formulations with 60-month docking intervals.
- Electronics:Conformal coatings and encapsulants shield printed circuit boards from moisture, dust, and thermal cycling. Smartphone and semiconductor manufacturing in Shenzhen and Hsinchu drives demand for parylene and acrylic spray variants.
Aerospace commands the highest specification barriers. Electronics is expanding most quickly.
Technology:
Volume concentration favors waterborne systems in regulated manufacturing environments, though solventborne retains不可替代 positions in field repair applications.
- Waterborne:Acrylic and polyurethane dispersions with VOC content below regulatory thresholds serve automotive assembly and wood finishing. EPA NESHAP compliance deadlines and REACH authorization timelines in Michigan and Bavaria accelerate conversion investments.
- Solventborne:High-solids and conventional solvent systems deliver rapid cure and film integrity where ambient humidity control is unavailable. Heavy industrial maintenance in Texas oil refineries and Rotterdam petrochemical clusters sustains demand despite regulatory pressure.
- Powder Coating:Thermoset epoxy, polyester, and hybrid powders provide zero-VOC finishes for metal substrates via electrostatic spray. Appliance and agricultural equipment manufacturers in Ohio and Lombardy favor the technology for edge coverage and transfer efficiency.
- UV-Curable:Photoinitiator-acrylate formulations cure instantly under UV-LED exposure for heat-sensitive plastics and electronics. Wood flooring and furniture producers in North Carolina and Veneto adopt the technology for scratch-resistant surface finishes.
Solventborne technology dominates installed base. Waterborne systems are where expansion concentrates.
End User:
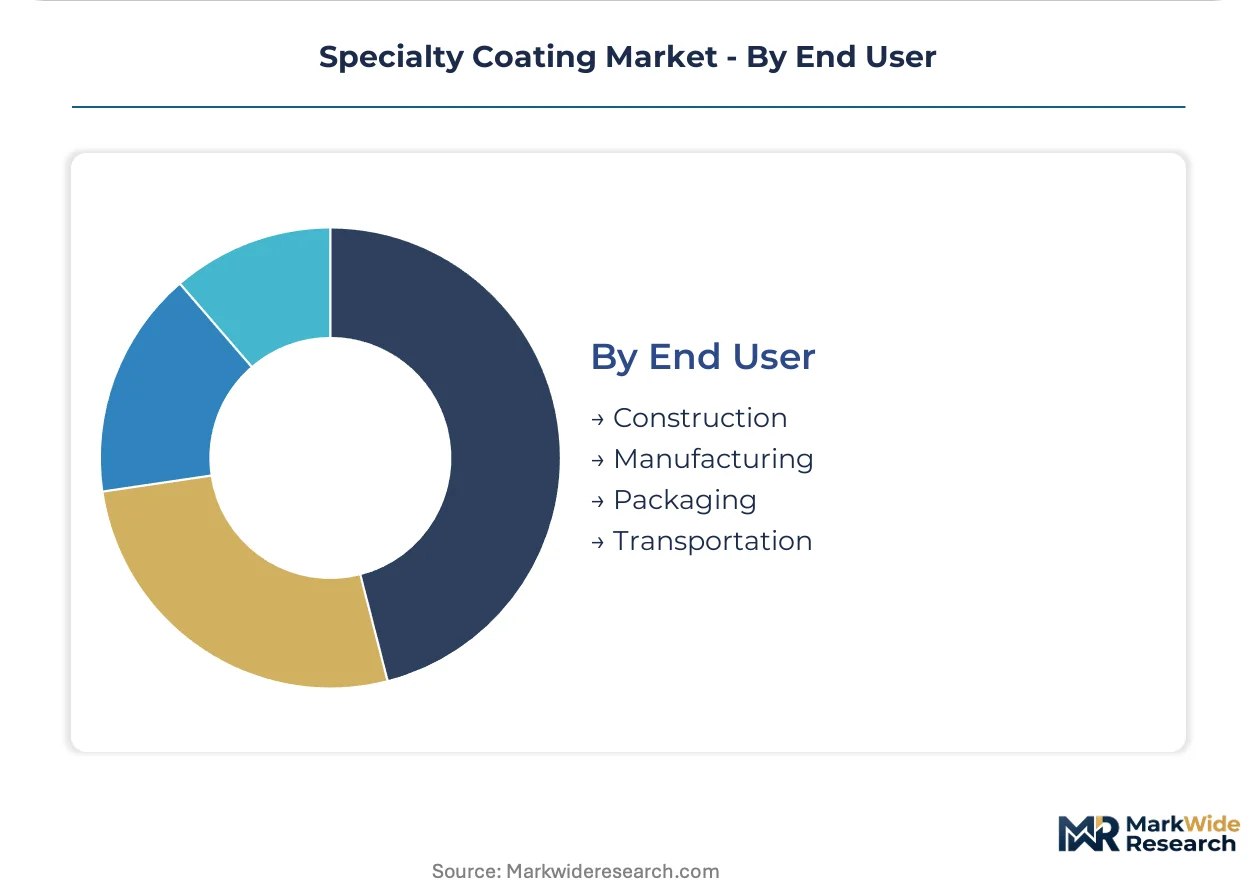
Customer type determines specification authority: construction owners delegate to contractor networks, while manufacturing retains in-house technical control.
- Construction:Protective coatings for steel structures, concrete waterproofing, and architectural metal finishes serve infrastructure and commercial building markets. Bridge and highway departments in California and Texas pilot warranty-backed performance contracts for deck waterproofing systems.
- Manufacturing:Industrial machinery, metal fabrication, and process equipment require chemical-resistant and abrasion-resistant finishes. German machine tool builders in Baden-Württemberg specify polyurethane and epoxy systems for factory floor equipment longevity.
- Packaging:Interior and exterior coatings for metal cans, aerosol containers, and drum linings protect contents from corrosion and contamination. Food and beverage can manufacturing in Pennsylvania and São Paulo drives epoxy-phenolic and organosol demand.
- Transportation:Rail car, truck, and bus manufacturers specify high-durability finishes for exterior panels and underbody protection. Freight rail operators in Illinois and railcar builders in Mexico specify urethane and epoxy systems for extended maintenance intervals.
Construction dominates installed base. Manufacturing is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows reveal distinct regional dependencies: Western formulators source titanium dioxide pigment from Chinese production clusters, while European coating houses ship high-performance aerospace systems to assembly plants in the United States and China. These trade patterns expose supply vulnerabilities and shape localization strategies.
United States
Automotive OEM battery enclosure coatings and infrastructure bridge deck systems drive formulation demand. EPA NESHAP standards for hazardous air pollutants force manufacturing facility upgrades for thermal oxidizers and carbon adsorption systems. Michigan automotive assembly clusters around Detroit accelerate waterborne basecoat qualification to preempt compliance disruptions.
Germany
Offshore wind installation protective systems and automotive OEM clearcoat specifications concentrate demand for polyurethane and epoxy technologies. REACH authorization timelines from ECHA sunset chromium trioxide and cadmium pigments, forcing aerospace and marine maintenance conversion. Stuttgart and Wolfsburg production corridors anchor premium-grade consumption as electric vehicle panel complexity rises.
China
Domestic port infrastructure, pipeline networks, and bridge construction concentrate demand for heavy-duty epoxy and polyurethane protective systems. MEE enforcement inspections shutter non-compliant coating facilities, disrupting regional supply while consolidating compliant manufacturers. Hebei Province steel mill coating lines represent the largest single polyester powder consumption cluster globally.
South Korea
Shipbuilding antifouling systems and electronics conformal coatings sustain specialty formulation demand. KBA vehicle certification standards influence automotive coating specifications for export-bound production. Ulsan and Geoje shipbuilding clusters specify self-polishing copolymer formulations with extended 60-month docking intervals.
India
PLI scheme incentives for electronics and automotive assembly create captive coating demand currently served by imports. BIS standards for industrial and protective coatings tighten quality parameters for domestic manufacturing. Maharashtra and Gujarat industrial corridors attract formulation investments seeking to replace imported epoxy and polyurethane systems.
Specialty Coating Market Competitive Environment
On the supply side, the industry is tiered between integrated chemical conglomerates with captive resin synthesis capabilities, independent coating specialists focused on application-specific formulations, and regional distributors with blending and color-matching services. Three archetypes dominate: vertically integrated polymer science operators, automotive supply chain-embedded finish providers, and marine-industrial maintenance specialists. Competitive moves concentrate on geographic density expansion in automotive OEM corridors and waterborne technology licensing to mid-size formulators facing regulatory conversion deadlines.
Within the integrated chemical tier, BASF SE exemplifies backward control from raw material synthesis through applied coating systems. PPG Industries and Axalta Coating Systems anchor automotive refinish and OEM supply chain positions respectively. These three represent distinct strategic postures: polymer science integration, geographic density in transportation segments, and automotive heritage extension into aerospace applications.
| Leading Market Players |
|---|
| PPG Industries, Inc. |
| Axalta Coating Systems Ltd. |
| The Sherwin-Williams Company |
| Akzo Nobel N.V. |
| BASF SE |
| RPM International Inc. |
| Nippon Paint Holdings Co., Ltd. |
| Hempel A/S |
| Jotun Powder Coatings |
| Others |
Value Chain & Pricing Dynamics
Hebei Province steel mill coating lines anchor global polyester powder consumption, concentrating pigment procurement leverage among Chinese titanium dioxide producers and compressing margin recovery for Western formulators facing feedstock volatility. This geographic supply dominance translates directly into pricing power asymmetries that downstream applicators absorb through long-term offtake contracts or pass through to asset owners via performance-guarantee premiums.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure where pricing stratifies across aerospace qualification tiers, automotive volume commitments, and marine maintenance spot purchases. Price differentiation hinges on certification grade—REACH-compliant and chromate-free systems command substantial premiums over legacy formulations—and volume scale, with multi-year automotive supply agreements securing preferential resin allocation. Cost compression in standard-grade epoxy systems is intensifying because titanium dioxide supply volatility feeds directly into raw material indices, while aerospace OEMs remain least price-sensitive due to 18-36 month qualification lock-in that freezes incumbent positions.
Supply Chain Analysis
Upstream feedstock dynamics center on bisphenol-A and isocyanate precursors drawing from German and Chinese petrochemical complexes, with titanium dioxide pigment production clustering in Shandong and Henan provinces. Specialty coating formulation rests on epoxy resin, aliphatic isocyanates, and microencapsulated self-healing agents as critical inputs. Single-source vulnerability concentrates in Chinese pigment production, where environmental compliance inspections trigger abrupt supply disruptions. Distribution runs through integrated formulator-direct channels for automotive OEMs and multi-tier distributor networks for marine maintenance and construction applicators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward automotive OEMs and infrastructure asset owners as procurement teams consolidate specification authority through warranty-backed performance contracts that transfer technical risk to applicator networks.
For Market Incumbents: Entrench automotive OEM supply chain positions through backward integration into waterborne resin synthesis and accelerated qualification of chromate-free aerospace primers ahead of ECHA sunset deadlines. Defend against specialty chemical conglomerates by locking in 5-7 year thermal management coating agreements with electric vehicle battery enclosure manufacturers in Stuttgart and Shanghai production corridors. For New Entrants and Emerging Players: Mid-market electronics conformal coating production in India represents the most penetrable entry point, with PLI scheme incentives creating captive demand currently served by imports from Shenzhen and Hsinchu. Secondary white-space exists in UV-LED cured wood finishing systems for North Carolina and Veneto flooring manufacturers seeking scratch-resistant alternatives to solventborne lacquers. A direct-to-applicator digital channel strategy bypasses entrenched distributor tiers in automotive refinish segments. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core coating divisions lacking integrated resin synthesis capabilities. Long-term viability over a 5-10 year window favors formulators with captive waterborne technology platforms and established aerospace qualification pipelines. Watch for inflection signals in MEE enforcement intensity that shutter non-compliant Chinese facilities and consolidate market share among compliant manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Waterborne Resin Synthesis | Captive supply of low-VOC binders secures EPA NESHAP compliance ahead of Michigan and Bavaria regulatory deadlines. |
| Aerospace Qualification Pipeline Investment | Eighteen-to-thirty-six month OEM approval cycles freeze competitor entry for fuel tank and engine nacelle coating systems. |
| India Manufacturing Localization | Maharashtra and Gujarat industrial corridor facilities replace imported epoxy and polyurethane systems under PLI scheme incentives. |
| UV-LED Curing Technology Licensing | Photoinitiator-acrylate formulations enable instant cure for heat-sensitive electronics substrates in Shenzhen assembly clusters. |
| Performance-Guarantee Contract Structuring | Warranty-backed service life agreements transfer substrate protection risk from Texas and California transportation departments to applicator networks. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC 10-K filings, ACC and Cefic industry reports, and ECHA authorization databases. Plant managers at Hebei Province steel coating lines, procurement leads at Stuttgart automotive OEMs, distribution channel partners in North American refinish segments, and technical R&D directors at marine formulators provided qualitative input. Bottom-up volume modeling from end-use consumption patterns triangulates against top-down value estimates derived from raw material cost structures.
Forecast inputs include coating content per vehicle across electric and internal combustion platforms, infrastructure investment flows through Chinese port and bridge construction, and regulatory conversion timelines for waterborne technology adoption. Segmentation dimensions span formulation chemistry, application criticality, cure technology, and end-user specification authority. CAGRs emerge from regression analysis of historical volume trajectories adjusted for technology substitution elasticities and regional enforcement intensity of VOC regulations.
Practitioners should monitor ECHA sunset date accelerations, MEE inspection campaign intensity, and titanium dioxide export quota adjustments for early signals of forecast revision. Cross-checking against IHS Markit vehicle production databases and national infrastructure procurement announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Reflective Polarizing Films Market
Specialty Materials
Asia-Pacific Green Sic Market
Specialty Materials
Hydrolysis Stable Polyester Films Market
Specialty Materials
Solar Control Films Market
Specialty Materials
Super-Hard Material Market
Specialty Materials
Metallised Polyester Films Market
Specialty Materials
Non-Semiconductor Neon Market
Specialty Materials
Cadmium Sulfide Market
Specialty Materials
Asia-Pacific Polyether Ether Ketone (Peek) Market
Specialty Materials
Battery Separator Films Market
Specialty Materials
Medical Injection Molded Plastics Market
Specialty Materials
North America Microspheres Market
Specialty Materials
Global Cellulose Acetate Market
Specialty Materials
Lab Grown Diamonds Market
Specialty Materials
Charge Generation Materials (CGM) Market
Specialty Materials
United States Microspheres Market