
 Asia Pacific Cellulose Acetate Market | 2026-2036
Asia Pacific Cellulose Acetate Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Cellulose Acetate Market Insights
China's dual carbon goals are restructuring cellulose acetate procurement across the Asia Pacific, forcing acetylation facilities to decarbonize feedstock chains and energy inputs. Mitsubishi Chemical Corporation leverages captive wood pulp supplies to sustain cost advantages in filament yarn grades. Daicel Corporation anchors regional supply of high-purity pharmaceutical grades through advanced esterification controls. Celanese Corporation competes on membrane-grade specialty formulations for water treatment end uses.
Cellulose acetate is a semi-synthetic polymer derived from cellulose esterification with acetic anhydride, typically containing 40-44% acetyl content by weight and processed through solution or melt spinning into fibers and films. Its primary commercial purpose centers on controlled permeability and biodegradability in filtration, textile, and molded applications. Fibers dominate value capture due to entrenched cigarette filter tow demand, while filtration membranes represent the fastest-expanding margin pool as municipal water standards tighten across Southeast Asian megacities. Plastics trail in growth velocity but retain niche defensibility in injection-molded eyeglass frames and tool handles where surface polish and organic warmth differentiate against petroleum alternatives.
China's MEE enforces wastewater discharge limits on acetic anhydride plants that elevate compliance costs for domestic acetylation operators. Japan's METI promotes bio-based material substitution through circular economy roadmaps that favor cellulose acetate against fossil-derived competitors in consumer goods. India's BIS mandates food-contact safety certifications for packaging films that filter smaller exporters from import channels. Stakeholders must monitor how China's dual carbon implementation timelines reshape acetic acid pricing and whether Japanese pharmaceutical regulators expand excipient-grade requirements to capture more regional refining value.
Market Dynamics
China's dual carbon goals are forcing acetylation facilities to decarbonize feedstock chains and energy inputs, restructuring procurement patterns across the Asia Pacific cellulose acetate supply base.
Growth Catalysts
- Dual carbon policy framework:China's MEE mandates on acetic anhydride plants accelerate investment in bio-based feedstock alternatives and carbon capture retrofits.
- Municipal water treatment expansion:Southeast Asian megacities tighten discharge standards, driving membrane-grade cellulose acetate demand for filtration systems.
- Pharmaceutical excipient upgrading:Japan's METI circular economy roadmaps favor cellulose acetate against fossil-derived competitors in drug delivery applications.
Market Restraints
- Acetic acid supply concentration:Eastern Chinese provinces host disproportionate acetylation capacity, creating geographic vulnerability to regional energy rationing or environmental enforcement spikes.
- Wood pulp cost volatility:Dissolving pulp prices fluctuate with textile viscose demand cycles, compressing margin stability for filament yarn producers.
- Polypropylene substitution in filtration:Melt-blown synthetics compete on unit cost in coarse filtration tiers where biodegradability carries no regulatory premium.
Strategic Opportunities
- India packaging film certification gap:BIS food-contact safety mandates filter smaller exporters, creating white space for compliant regional producers to capture import substitution volume.
- Biodegradable eyewear frames:Consumer goods brands in Japan and South Korea seek petroleum-alternative injection molding resins with surface polish equivalence.
- Membrane-bioreactor convergence:Wastewater treatment operators combine cellulose acetate membranes with anaerobic digestion, opening industrial effluent processing contracts.
Industry Challenges
- Esterification process control expertise:High-purity pharmaceutical grades require advanced acetyl distribution management, and qualified chemical engineers concentrate at incumbent Japanese and Korean producers.
- Legacy equipment carbon retrofit costs:Acetic anhydride plants face capital-intensive boiler and compressor replacements to meet MEE emission intensity benchmarks.
- Cross-border excipient harmonization delays:Divergent pharmacopeia standards between China's NMPA and Japan's PMDA complicate regional product registration strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Cellulose Acetate Market |
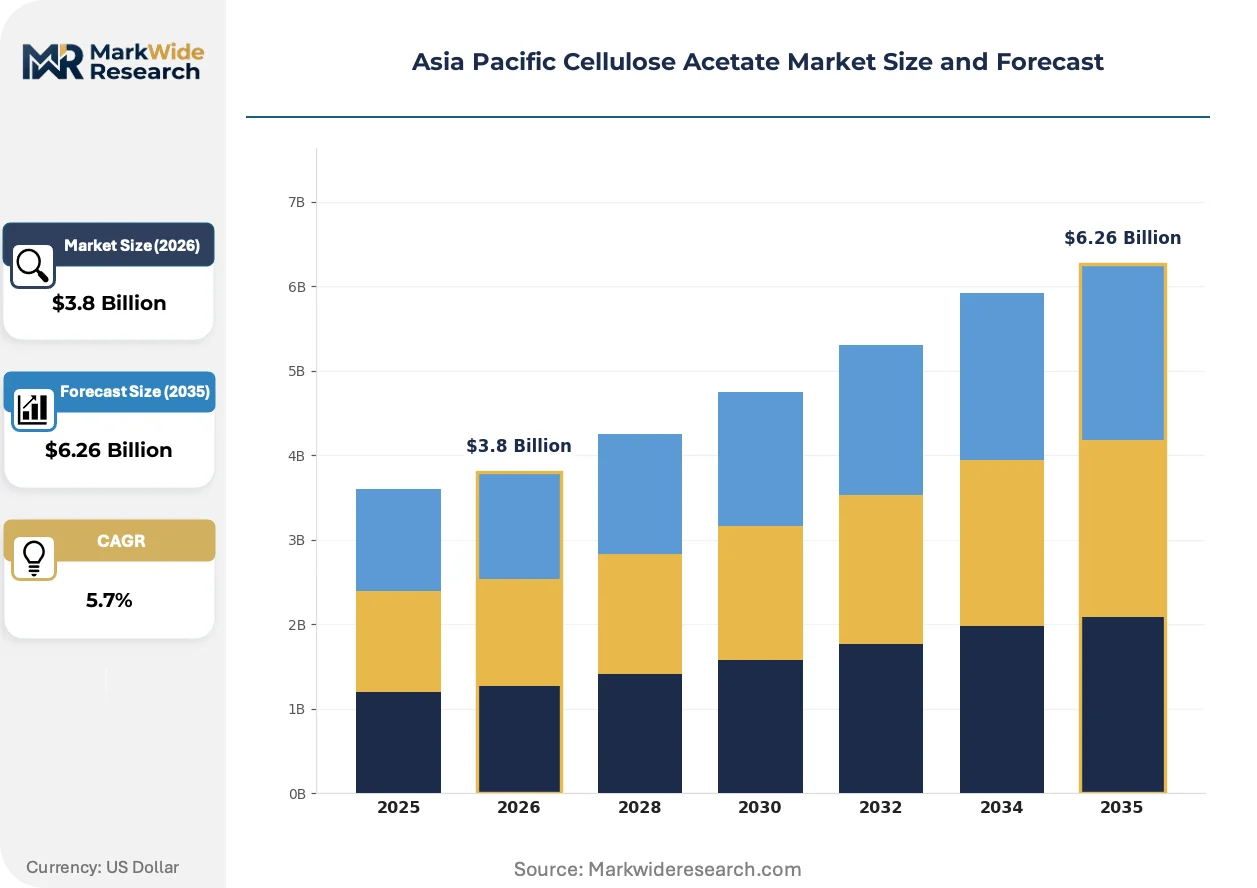
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filtration Membranes, Coatings, Fibers, Plastics End User: Textiles, Automotive, Pharmaceuticals, Packaging Application: Personal Care, Medical Devices, Food Packaging, Adhesives Form: Granules, Films, Powders, Solutions |
| Companies Covered | China National Tobacco Corporation, Mitsubishi Chemical Corporation, Daicel Corporation, Borregaard AS, RYAM, Celanese Corporation, Sichuan Push Cellulose Acetate Co Ltd, Central Drug House, Eastman Chemical Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Cellulose Acetate Market Trends and Innovations
Technology convergence, regulatory tightening on chemical inputs, and buyer consolidation in filtration end-uses are reshaping competitive positioning across the Asia Pacific cellulose acetate value chain.
Membrane surface modification technology is converging with cellulose acetate substrate manufacturing, enabling nanofiltration pore precision previously requiring polyamide thin-film composites. Korean water treatment engineering firms integrate these membranes into compact municipal skid systems for Southeast Asian deployment. The convergence is compressing the performance gap between bio-based and synthetic polymer membranes in reverse osmosis pretreatment stages.
China's MEE wastewater discharge limits on acetic anhydride production are elevating compliance costs for domestic acetylation operators and accelerating capital flight toward integrated pulp-to-ester facilities. Plants without captive acetic acid or on-site carbon capture face margin compression against Japanese and Korean competitors with cleaner feedstock chains. Filtration-grade producers in Shandong and Jiangsu provinces are most affected, responding with joint ventures for bio-acetic acid offtake agreements.
Filter tow buyers in China are consolidating procurement decisions at the provincial tobacco monopoly level, reducing supplier negotiation leverage and compressing contract durations. Long-term offtake agreements are fragmenting into shorter volume commitments with price renegotiation clauses tied to dissolving pulp indices. Eastern Chinese provinces exhibit the most visible concentration, where China National Tobacco Corporation subsidiaries now coordinate multi-facility purchasing.
Asia Pacific Cellulose Acetate Market Segmentation
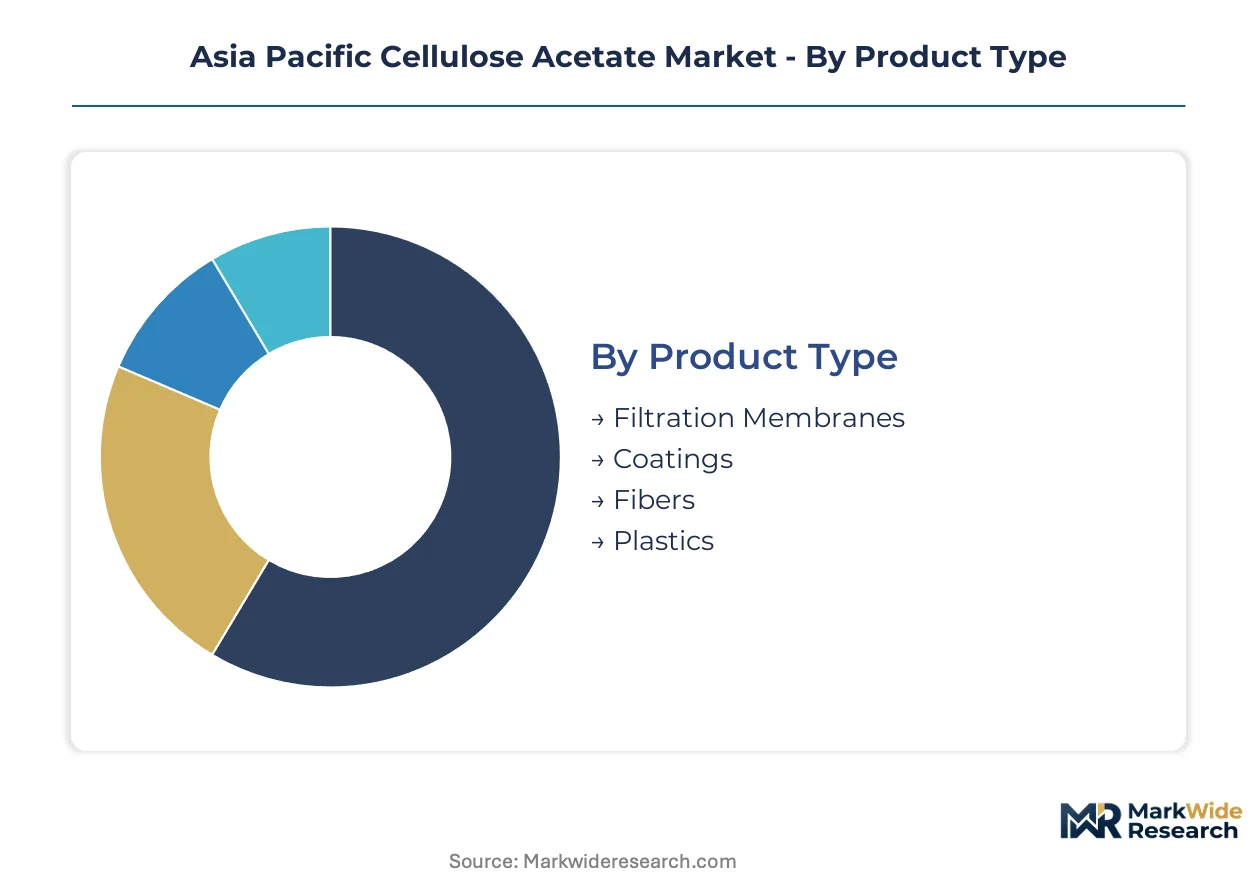
Segmentation in cellulose acetate reveals how acetyl content and physical form dictate buyer procurement criteria across disparate end-use specifications. Manufacturers configure esterification processes differently for cigarette filter tow versus membrane substrates, creating divergent margin structures within the same chemical family.
Product Type:
Buyers select grades based on permeability requirements and biodegradability mandates in their target applications.
- Filtration Membranes:These substrates feature controlled pore architecture engineered for reverse osmosis pretreatment and ultrafiltration stages. Municipal water operators in Vietnam and Indonesia specify cellulose acetate membranes for anaerobic digestion integration, though polypropylene competes aggressively on unit cost in coarse filtration tiers.
- Fibers:Solution-spun filaments dominate commercial volume through cigarette filter tow demand concentrated in eastern Chinese provinces. Acetyl content typically ranges 40-44% by weight, optimized for pressure-drop performance and biodegradability compliance under China's evolving tobacco waste regulations.
- Coatings:Solvent-cast formulations serve pharmaceutical tablet film-coating and specialty packaging lamination where moisture barrier properties prove critical.
- Plastics:Injection-molding grades target eyeglass frames and tool handles in Japan and South Korea, valued for surface polish equivalence to petroleum-derived competitors.
Fibers lead on scale; filtration membranes lead on momentum.
End User:
Volume concentration tracks regulatory enforcement intensity and substitution economics in each sector.
- Textiles:Filament yarn producers in China and India consume dissolving pulp-derived acetate for apparel linings and specialty fabrics, facing margin pressure from viscose demand cycles that drive wood pulp cost volatility.
- Pharmaceuticals:High-purity excipient grades require advanced acetyl distribution management for controlled-release drug delivery, with Japan's PMDA and China's NMPA maintaining divergent pharmacopeia standards that complicate regional registration strategies.
- Packaging:Food-contact films must satisfy India's BIS safety certifications, filtering smaller exporters and creating white space for compliant regional producers.
- Automotive:Interior trim applications remain limited by heat resistance constraints relative to engineering thermoplastics.
Textiles anchor procurement volume; pharmaceuticals expand most quickly on regulatory tailwinds.
Application:
Specification depth varies dramatically between commodity personal care uses and validated medical device grades.
- Medical Devices:Hemodialysis membranes and surgical tool handles demand batch-to-batch consistency with full traceability, concentrating qualified supply among Japanese and Korean producers with esterification process control expertise.
- Food Packaging:Clarity and grease resistance specifications drive adoption for premium confectionery and fresh produce wrapping, particularly where India's BIS mandates filter non-compliant imports.
- Personal Care:Cosmetic applicators and nail polish removers utilize standard-grade acetate with minimal regulatory burden.
- Adhesives:Solvent-based formulations serve tape and label bonding applications facing substitution pressure from hot-melt alternatives.
Personal care dominates shipment counts; medical devices command steepest expansion trajectory.
Form:
Processing method selection determines working capital requirements and equipment compatibility for downstream converters.
- Films:Cast or extruded sheet serves membrane lamination and packaging windows, with thickness tolerance critical for automated packaging line compatibility.
- Solutions:Dope formulations for direct fiber spinning and coating operations concentrate near acetylation capacity in Shandong and Jiangsu provinces to minimize solvent transport costs.
- Granules:Pelletized resin enables injection molding of eyewear frames and consumer goods where surface aesthetics differentiate against commodity plastics.
- Powders:Fine particle grades facilitate rapid dissolution in adhesive and coating formulations.
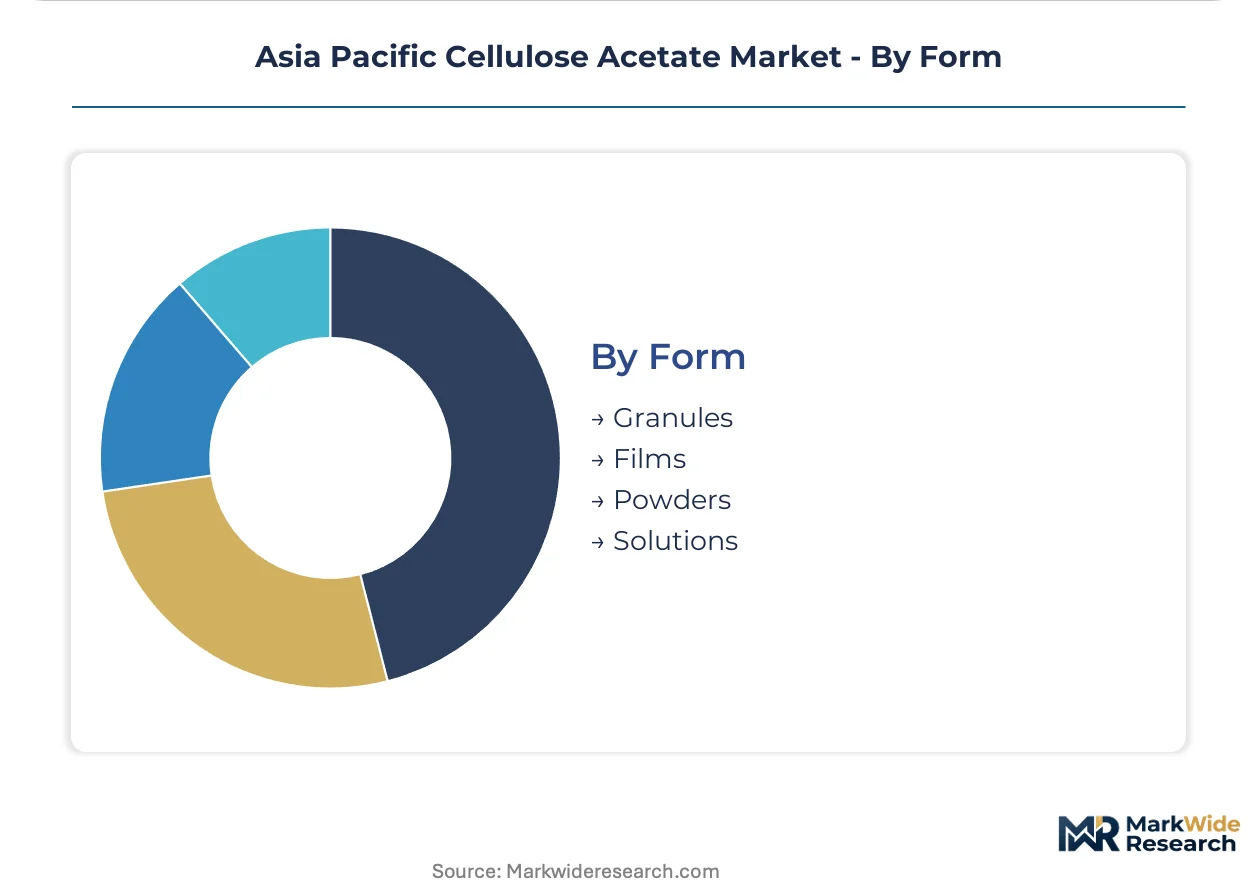
Solutions capture the greatest tonnage; films gain share fastest on membrane demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cellulose acetate industrialization traces to German chemical innovation in the early 1900s, but commercial scale crystallized in Japan's post-war textile expansion and China's subsequent integration into global cigarette supply chains. The Asia Pacific region now concentrates over two-thirds of worldwide acetylation capacity.
China
China National Tobacco Corporation subsidiaries in Shandong and Jiangsu provinces coordinate multi-facility filter tow procurement, consolidating buyer leverage against suppliers. The Ministry of Ecology and Environment enforces wastewater discharge limits on acetic anhydride plants, elevating compliance costs for domestic acetylation operators. Eastern Chinese provinces host disproportionate capacity clusters, creating geographic vulnerability to regional energy rationing.
Japan
Pharmaceutical excipient demand from controlled-release drug delivery applications drives high-purity grade consumption in Osaka and Tokyo pharmaceutical corridors. The Ministry of Economy, Trade and Industry promotes bio-based material substitution through circular economy roadmaps favoring cellulose acetate against fossil-derived competitors. Kansai region producers anchor regional supply of pharmaceutical grades through advanced esterification controls.
India
Food-contact packaging film demand expands as domestic confectionery and fresh produce sectors upgrade wrapping specifications. The Bureau of Indian Standards mandates food-contact safety certifications that filter smaller exporters from import channels. Maharashtra and Gujarat textile hubs consume dissolving pulp-derived acetate for apparel linings, facing margin pressure from viscose demand cycles.
South Korea
Municipal water treatment engineering firms integrate cellulose acetate membranes into compact skid systems for Southeast Asian export. The country's national pharmaceutical regulator maintains excipient standards that align with Japanese pharmacopeia, facilitating regional product registration. Seoul Capital Area membrane manufacturers compete on surface modification technology for nanofiltration precision.
Vietnam
Municipal water operators specify cellulose acetate membranes for anaerobic digestion integration in Ho Chi Minh City and Hanoi wastewater treatment expansions. National environmental discharge standards tighten in response to industrial effluent concerns, driving filtration infrastructure investment. Northern industrial zones exhibit fastest membrane adoption velocity as foreign engineering firms deploy Korean-imported skid systems.
Asia Pacific Cellulose Acetate Market Competitive Landscape
Premium-margin players sit above commodity-margin players across acetyl distribution control and pharmacopeia certification dimensions, with pharmaceutical-grade specialists commanding substantial pricing power over cigarette filter tow commoditizers. The vendor base stratifies into three tiers: integrated pulp-to-ester conglomerates with captive wood pulp supplies, acetylation-focused chemical specialists with advanced esterification process control, and regional commodity producers dependent on merchant acetic acid. Dominant competitive moves include backward integration into dissolving pulp supply and strategic partnerships for bio-acetic acid offtake agreements.
Within the integrated conglomerate tier, Mitsubishi Chemical Corporation and Daicel Corporation exemplify archetypes leveraging captive feedstock advantages and advanced process control respectively. Celanese Corporation occupies a position among specialty formulation specialists competing on membrane-grade product differentiation. These three anchors demonstrate how geographic origin and company structure correlate with strategic positioning: Japanese corporations with chemical heritage dominate high-purity segments, while US-based multinationals compete on application-specific formulation expertise.
| Leading Market Players |
|---|
| China National Tobacco Corporation |
| Mitsubishi Chemical Corporation |
| Daicel Corporation |
| Borregaard AS |
| RYAM |
| Celanese Corporation |
| Sichuan Push Cellulose Acetate Co Ltd |
| Central Drug House |
| Eastman Chemical Company |
| Others |
Pricing and Supply Chain Analysis
China National Tobacco Corporation subsidiaries concentrate filter tow procurement decisions at the provincial monopoly level, anchoring contract-based long-term offtake agreements as the dominant pricing model across the Asia Pacific cellulose acetate supply base.
Pricing Analysis
Contract-based long-term offtake agreements with price renegotiation clauses tied to dissolving pulp indices dominate volume transactions in eastern Chinese provinces. Price differentiation hinges on acetyl content precision and pharmacopeia certification tier, with pharmaceutical-grade producers commanding substantial premiums over cigarette filter tow commoditizers. Cost compression in standard fiber grades is intensifying because provincial tobacco monopolies now coordinate multi-facility purchasing, reducing supplier leverage. Filter tow buyers exhibit highest price sensitivity, while membrane-grade specialty formulations for water treatment show lowest elasticity due to performance-critical specifications.
Supply Chain Analysis
Acetic acid supply rests on eastern Chinese provinces, Japan, and South Korea, with dissolving pulp feeding from Scandinavian and North American timber operations. Key inputs include wood pulp, acetic anhydride, and sulfuric acid catalysts. Single-source vulnerability concentrates in China's MEE-regulated acetic anhydride corridor, where environmental enforcement spikes threaten feedstock continuity. Distribution runs through integrated pulp-to-ester conglomerates for captive consumption, supplemented by merchant esterification facilities serving regional textile and pharmaceutical converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific cellulose acetate market functions as a stable compounder, with China's dual carbon policy framework driving steady reinvestment in bio-based feedstock alternatives and carbon capture retrofits.
For Market Incumbents: Extend backward integration into dissolving pulp supply to insulate margin stability from viscose demand cycles that drive wood pulp cost volatility. Deepen esterification process control expertise in pharmaceutical-grade segments to defend against Korean membrane manufacturers advancing surface modification technology. Prioritize bio-acetic acid offtake agreements ahead of MEE emission intensity benchmark deadlines.
For New Entrants and Emerging Players: Municipal water treatment engineering firms in Vietnam and Indonesia represent the most penetrable channel partner type for membrane-grade cellulose acetate, given tightening national environmental discharge standards and Korean-imported skid system deployment. Target India's BIS-compliant food-contact packaging film segment where certification gaps filter smaller exporters. Pursue joint venture structures with established acetylation operators to bypass capital-intensive boiler and compressor replacement requirements.
For Investors and Strategic Acquirers: Integrated chemical conglomerates with captive wood pulp supplies are the most active acquirer in this space, seeking pharmaceutical-grade capability accretion. The market offers long-term viability through biodegradable material substitution tailwinds across consumer goods and filtration end-uses. Acquisition candidates should demonstrate advanced acetyl distribution management and existing pharmacopeia registrations. Watch for NMPA-PMDA excipient harmonization progress as the inflection indicator for regional product registration scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dissolving Pulp | Mitsubishi Chemical Corporation leverages captive timber assets to stabilize input costs against viscose demand cycles. |
| Bio-Acetic Acid Offtake Agreement | Shandong and Jiangsu filtration-grade producers secure low-carbon feedstock chains ahead of MEE emission benchmarks. |
| Pharmaceutical Excipient Certification Investment | Daicel Corporation anchors Kansai region supply through PMDA-aligned advanced esterification controls. |
| Membrane Surface Modification R&D | Seoul Capital Area manufacturers compress the performance gap with polyamide thin-film composites in reverse osmosis pretreatment. |
| Joint Venture for Regional Production | Compliant Indian producers capture Maharashtra and Gujarat textile hub demand under BIS food-contact safety mandates. |
Research Methodology
Multiple input streams — acetylation plant manager interviews, downstream textile and pharmaceutical procurement lead discussions, distribution channel partner assessments, and regulatory affairs director consultations — were reconciled against customs and trade data, China MEE discharge filings, Japan METI circular economy reports, and India BIS certification records. Bottom-up capacity and production estimates were triangulated with top-down demand aggregation across cigarette filter tow, membrane filtration, and pharmaceutical excipient end-uses.
Historical capacity utilization and pricing patterns were cross-referenced against panel input from chemical industry specialists to construct the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, acetyl content grade, end-use industry, and regional regulatory cluster. CAGRs were derived through slope analysis of normalized historical trajectories adjusted for policy implementation timelines, with specific inputs from dissolving pulp price indices and municipal water treatment investment pipelines.
Revisions become necessary when China's dual carbon implementation timelines accelerate, Japanese pharmaceutical regulators expand excipient-grade requirements, or Southeast Asian environmental discharge standards tighten beyond modeled trajectories. A small set of named triggers — MEE enforcement intensity, NMPA-PMDA harmonization progress, and polypropylene substitution elasticity in coarse filtration — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Specialty Carbon Black Market
Specialty Materials
Vulcanized Fiber Market
Specialty Materials
Erbium-169 Market
Specialty Materials
Advanced Green Septa Market
Specialty Materials
Adhesion Laminated Surface Protection Films Market
Specialty Materials
Europe Green Sic Market
Specialty Materials
Rigid Polyurethane Foams Market
Specialty Materials
Crusher Backing Materials Market
Specialty Materials
Reflective Polarizing Films Market
Specialty Materials
Super-Hard Material Market
Specialty Materials
ePTFE Electronic Film Market
Specialty Materials
UV Stabilized Films Market
Specialty Materials
Global Montan Wax Market
Specialty Materials
Plastic Dielectric Films Market
Specialty Materials
Asia-Pacific Colloidal Silica Market
Specialty Materials
Light Diffusion Materials Market