
 Magnesium Fluoride Market | 2026-2036
Magnesium Fluoride Market Size, Share, and Industry Trends Forecast 2026-2036
Magnesium Fluoride Market Intelligence
Customized purity and particle size specifications for specific optical applications is rebalancing the relationship between material suppliers and end-users. Morita Chemical Industries leverages its expertise in fluorine chemistry to supply high-purity grades for sensitive electronics. Stella Chemifa Corporation competes on its manufacturing scale for both optical and industrial applications. Saint-Gobain differentiates through its production of finished optical components like windows and lenses from its own captive material supply.
Magnesium fluoride is an inorganic crystalline compound with the chemical formula MgF2. It is notable for its wide optical transmission range, from approximately 120 nm in the vacuum ultraviolet to 8 μm in the infrared spectrum. High-purity Optical Grade material commands a significant price premium and is used for specialized infrared optics and photolithography. In contrast, Industrial Grade powders and granules are utilized in larger volumes for applications like ceramic additives and metallurgical fluxes.
Supplier compliance with chemical control laws, such as the EPA's Toxic Substances Control Act in the United States and ECHA's REACH framework in Europe, governs market access. Additionally, ISO standards for optics dictate the purity and performance requirements for materials used in defense and aerospace systems. Future profitability will depend on a supplier's ability to manage the technical and capital-intensive demands of producing optical-grade material while competing in lower-margin industrial segments.
Market Dynamics
The market's central dynamic is the bifurcation between capital-intensive, high-purity optical-grade material and high-volume, lower-margin industrial grades. This split creates distinct competitive arenas, separating suppliers based on technical capability, capital access, and strategic focus on either specialized optics or industrial applications.
Growth Catalysts
- Infrared Systems Expansion:Demand for high-performance infrared windows and domes in aerospace and defense systems, particularly for guidance and thermal imaging, drives consumption of optical-grade magnesium fluoride due to its excellent transmission properties and durability.
- Asian Electronics Manufacturing:The concentration of semiconductor and consumer electronics production in China and Taiwan fuels volume demand for MgF2 in applications like anti-reflective coatings for displays and lenses, sustaining a large segment of the market.
- Synthesis Process Refinements:Advances in chemical vapor deposition and single-crystal growth techniques are enabling the production of higher-purity magnesium fluoride with fewer defects, unlocking its use in more demanding applications like deep-ultraviolet photolithography optics.
Market Restraints
- High Production Costs:The manufacturing of optical-grade material requires significant capital investment in high-temperature furnaces and controlled environments, coupled with high energy consumption, which creates a substantial barrier to entry and pressures margins.
- Stringent Chemical Regulations:Compliance with chemical control laws like the EPA's TSCA in the United States and ECHA's REACH framework in Europe adds complexity and cost, limiting market access for non-compliant suppliers.
- Threat of Material Substitution:In less critical optical applications, materials like calcium fluoride or fused silica can offer a viable, lower-cost alternative to magnesium fluoride, capping its adoption in certain price-sensitive segments of the optics industry.
Strategic Opportunities
- Advanced Lithography Applications:The push toward smaller semiconductor nodes creates an opportunity for ultra-high purity MgF2 in optics for excimer lasers used in deep-ultraviolet (DUV) and vacuum-ultraviolet (VUV) photolithography systems.
- Nanostructured Coatings:Developing nano-particle or nano-structured magnesium fluoride opens new possibilities for advanced anti-reflective and protective coatings with superior performance characteristics for specialized optical and electronic devices.
- Emerging Aerospace Markets:The growth of domestic aerospace and defense industries in countries such as India and Brazil presents an opportunity to supply optical components for new platforms, diversifying demand away from traditional markets.
Industry Challenges
- Optical Standards Compliance:Adhering to the rigorous and evolving purity and performance specifications dictated by ISO standards for optical materials presents a continuous operational challenge, requiring extensive quality control and metrology capabilities.
- Batch-to-Batch Consistency:Maintaining consistent purity and optical properties across different production batches is a significant technical hurdle, particularly when scaling up production to meet large-volume orders for sensitive applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnesium Fluoride Market |
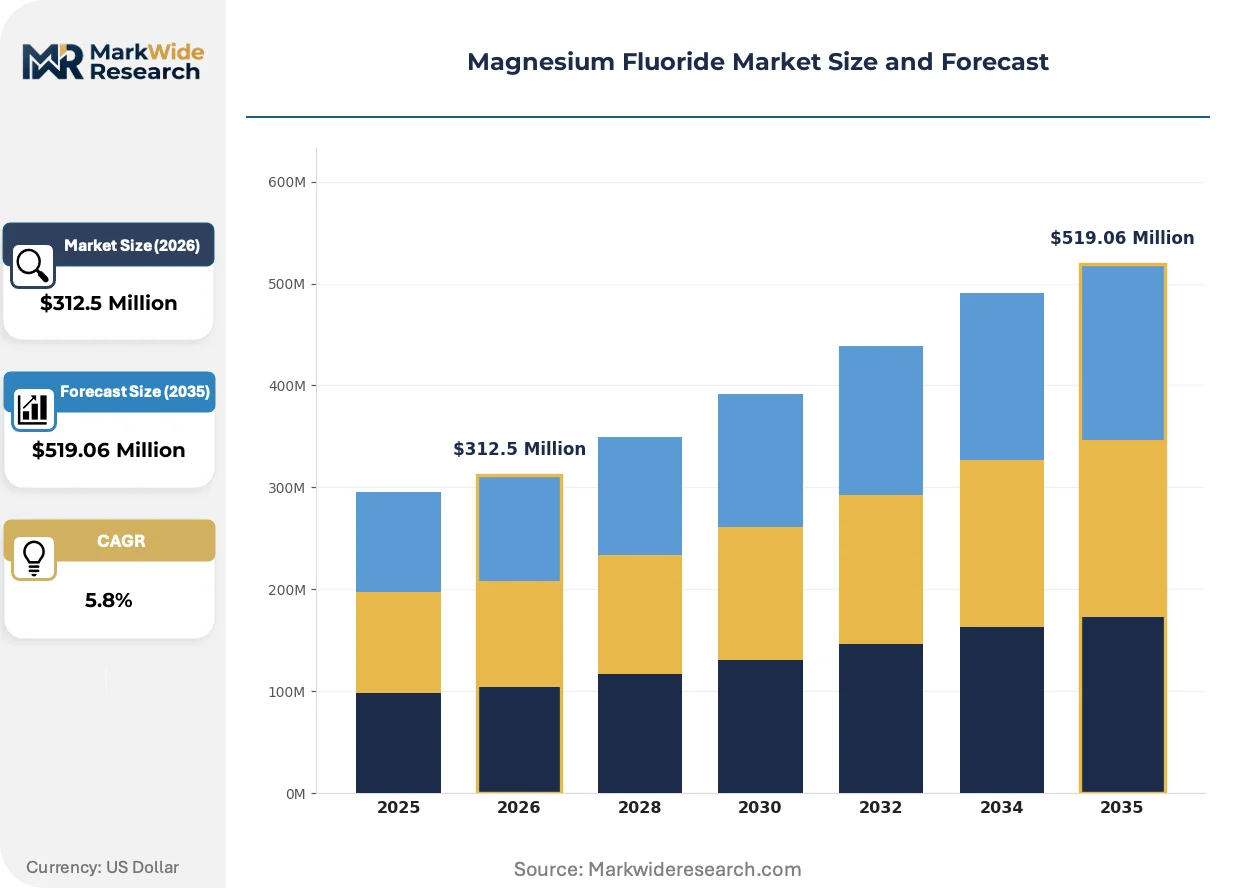
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Grade, Ceramics Grade, Industrial Grade, Electronic Grade Application: Infrared Optics, Coatings, Lasers, Photolithography, Ceramics Form: Powder, Granules, Pellets, Crystals End Use Industry: Electronics Manufacturing, Aerospace, Chemical Processing, Defense |
| Companies Covered | Morita Chemical Industries, Henan Kingway Chemicals, Stella Chemifa Corporation, Fairsky Industrial, Fluoro Chemicals, Wuxi Ruiyuan Chemical, Fujian Qucheng Chemical, Jiangxi Yono Industry, Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnesium Fluoride Market Strategic Shifts & Innovations
Material science advancements are widening the performance and price gap between standard industrial-grade powders and highly engineered optical crystals. This trend is forcing a strategic choice upon suppliers to either compete on scale in the industrial segment or invest in the deep technical capabilities required for the optics sector.
High-purity, single-crystal growth techniques produce large, flawless magnesium fluoride boules essential for advanced optical components. Aerospace contractors and semiconductor equipment firms are steadily adopting these superior materials for critical systems where performance cannot be compromised. This technology is consolidating the premium segment of the market around a few suppliers possessing the capital-intensive synthesis infrastructure and proprietary expertise.
The European Chemicals Agency's (ECHA) REACH regulation imposes stringent registration, evaluation, and authorization requirements on chemical substances. This framework increases compliance costs and documentation burdens for producers and importers of magnesium fluoride into the European Union market. Suppliers targeting the EU's ceramics and metallurgical sectors are most affected, often investing in specialized consulting and testing to maintain market access.
A shift toward co-development partnerships between material suppliers and end-users is altering procurement patterns. This collaborative model replaces transactional purchasing, allowing optical designers to specify custom purity levels and physical forms for precise applications. The trend is most visible within the specialized deep-ultraviolet lithography and high-power laser segments, particularly in technology hubs across Taiwan and Germany.
Magnesium Fluoride Market Segmentation
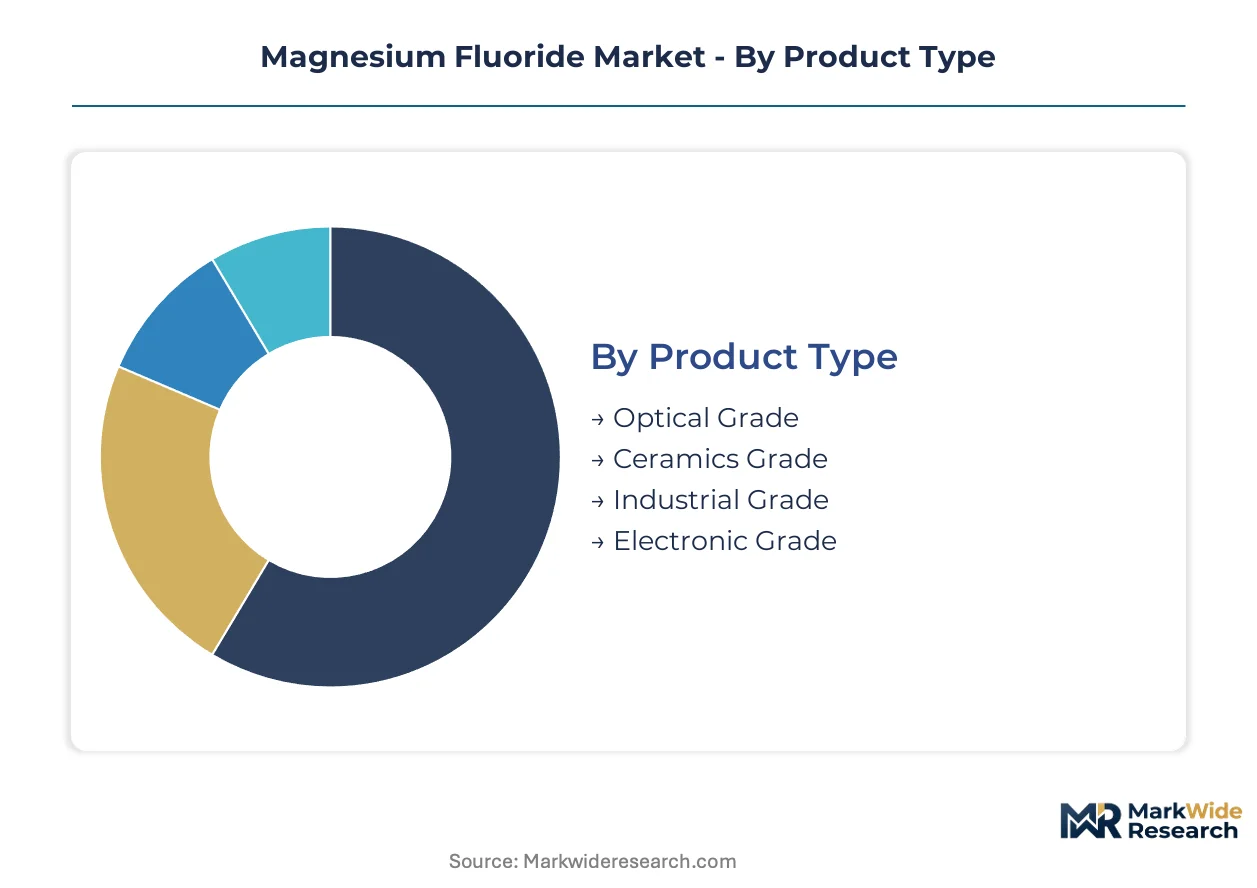
Understanding the magnesium fluoride market through segmentation reveals the distinct value propositions and operational demands across its diverse applications. This bifurcation between high-purity optical-grade material and high-volume industrial grades shapes competitive strategies and investment priorities for suppliers.
Product Type:
The supply concentration for magnesium fluoride directly influences product type availability and specialization.
- Optical Grade:This material possesses wide optical transmission from vacuum ultraviolet to infrared, requiring ultra-high purity and advanced single-crystal growth techniques. Demand concentrates in aerospace and defense for infrared optics, alongside specialized deep-ultraviolet photolithography systems.
- Industrial Grade:Comprising powders and granules with lower purity specifications, this product type is produced in larger volumes for less demanding applications. Demand is significant in ceramic additives and metallurgical fluxes, particularly within industrial manufacturing hubs like China.
- Ceramics Grade:This product type features specific particle sizes and controlled purity levels, tailored for integration into advanced ceramic formulations.
- Electronic Grade:High-purity material with controlled particle morphology is essential for sensitive electronic components, including specialized coatings and substrates.
Today's leader: Industrial Grade. Tomorrow's challenger: Optical Grade.
Application:
Specific applications for magnesium fluoride drive distinct material specifications and performance requirements across various industries.
- Infrared Optics:This application demands magnesium fluoride for its excellent transmission properties and durability, particularly in aerospace and defense systems. Demand is strong for guidance and thermal imaging components where high performance is critical.
- Photolithography:Ultra-high purity magnesium fluoride is essential for optics in excimer lasers used for deep-ultraviolet (DUV) and vacuum-ultraviolet (VUV) photolithography systems. The concentration of semiconductor manufacturing in Taiwan and China drives this demand.
- Coatings:Magnesium fluoride is widely utilized in anti-reflective coatings for displays, lenses, and other optical surfaces due to its low refractive index.
- Lasers:Components within high-power laser systems benefit from magnesium fluoride's optical clarity and transmission characteristics.
- Ceramics:Magnesium fluoride functions as an additive in ceramic production, enhancing material properties or facilitating lower processing temperatures.
Infrared Optics currently represents the largest volume segment, while Photolithography applications are expanding most quickly.
Form:
The physical form of magnesium fluoride often correlates with its processing complexity and target market volume.
- Powder:This fine particulate material comes in various purity levels and serves high-volume industrial applications. Demand is prevalent in metallurgical fluxes and lower-margin segments globally.
- Crystals:Produced through single-crystal growth techniques, these flawless boules are critical for advanced optical components in aerospace, defense, and semiconductor equipment. Performance cannot be compromised in these critical systems.
- Granules:Characterized by a larger particle size than powder, granules are often preferred for specific ceramic manufacturing processes or industrial uses.
- Pellets:These compressed forms are commonly employed in evaporation coating processes for optical and electronic devices, offering controlled material delivery.
Powder forms dominate industrial market share, while Crystals command the premium optical segment.
End Use Industry:
End-use industries dictate the required performance specifications and ultimately the profit margins for magnesium fluoride suppliers.
- Electronics Manufacturing:This industry requires high-purity magnesium fluoride for anti-reflective coatings, display components, and photolithography optics. Extensive electronics production in China and Taiwan drives significant volume demand.
- Aerospace:Optical-grade magnesium fluoride is critical for infrared windows, domes, and sensors in aerospace systems due to its durability and transmission properties. Major defense contractors utilize it for guidance and thermal imaging.
- Chemical Processing:Industrial grades of magnesium fluoride are used as a catalyst or reagent in various chemical reactions and manufacturing processes.
- Defense:This sector relies on magnesium fluoride for advanced optical systems in military hardware, including targeting, surveillance, and communication platforms.
Electronics Manufacturing provides significant volume, whereas Aerospace applications offer higher strategic value due to stringent requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global magnesium fluoride market experiences shifts in production and consumption, influenced by differing regulatory frameworks and manufacturing cost structures across regions. Suppliers often evaluate the cost-of-compliance gap between markets when establishing new production facilities or expanding existing operations. This dynamic impacts the strategic focus on either high-purity optical grades or high-volume industrial materials.
China
China's extensive electronics manufacturing and industrial sectors drive significant demand for magnesium fluoride. The nation's GB standards for chemical substances guide purity and safety requirements. Industrial clusters within the Yangtze River Delta concentrate high-volume industrial-grade powders and granules.
Taiwan
Taiwan's robust semiconductor industry fuels substantial demand for ultra-high purity magnesium fluoride in photolithography optics. The Environmental Protection Administration (EPA) enforces strict regulations on chemical handling and waste management. Foundries in the Hsinchu Science Park utilize advanced optical materials for deep-ultraviolet lithography systems.
United States
United States aerospace and defense sectors require optical-grade magnesium fluoride for high-performance infrared windows and domes. Compliance with the EPA's Toxic Substances Control Act (TSCA) governs chemical substance registration. Major aerospace hubs in California and Texas specialize in fabricating advanced optical components for guidance and thermal imaging.
Germany
Germany's precision engineering and advanced optics industries generate demand for high-purity magnesium fluoride in specialized applications. The ECHA's REACH framework imposes stringent registration and authorization requirements. Optical manufacturing centers in Jena and Wetzlar develop cutting-edge components for scientific instruments and lithography equipment.
India
India's expanding aerospace and defense industries, alongside growing electronics manufacturing, create new opportunities for magnesium fluoride. The Bureau of Indian Standards (BIS) sets quality benchmarks for chemical products. Bengaluru's defense and aerospace R&D centers integrate advanced optical materials into developing indigenous platforms.
Magnesium Fluoride Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments of the magnesium fluoride market. The market exhibits a bifurcated structure, separating suppliers focused on capital-intensive optical grades from those targeting high-volume industrial applications. Key strategic archetypes include high-purity material innovators, integrated component manufacturers, and bulk industrial chemical suppliers. Companies engage in capacity expansion and strategic partnerships to secure market position.
Specialists in high-purity chemical production, Morita Chemical Industries exemplifies an innovator focusing on sensitive electronics applications, leveraging deep expertise in fluorine chemistry. Stella Chemifa Corporation represents a scale-driven player, leveraging extensive manufacturing capabilities for both optical and industrial applications across a broad customer base. Furthermore, Saint-Gobain occupies a position as an integrated component manufacturer, producing finished optical parts like windows and lenses from its own captive material supply. This strategic integration provides control over material quality and supply chain. These companies anchor distinct competitive strategies within the magnesium fluoride market, ranging from pure material supply to value-added component manufacturing.
| Leading Market Players |
|---|
| Morita Chemical Industries |
| Henan Kingway Chemicals |
| Stella Chemifa Corporation |
| Fairsky Industrial |
| Fluoro Chemicals |
| Wuxi Ruiyuan Chemical |
| Fujian Qucheng Chemical |
| Jiangxi Yono Industry |
| Saint-Gobain |
| Others |
Cost & Logistics Intelligence
The European Chemicals Agency's (ECHA) REACH framework gates qualified supply and premium-tier pricing access for magnesium fluoride producers targeting the European Union market. This regulatory environment necessitates significant investment in compliance, influencing both production costs and market entry strategies.
Pricing Analysis
Capacity additions in China are reshaping price floors for industrial-grade magnesium fluoride, intensifying competition in high-volume segments. The market exhibits tiered pricing separating optical-grade from industrial-grade material. Purity levels and ISO standards compliance drive significant price differentiation for specialized applications. Margins face pressure from high production costs and stringent chemical regulations, particularly for optical-grade material. Industrial-grade buyers exhibit higher price sensitivity, while defense and aerospace procurement prioritizes performance over cost.
Supply Chain Analysis
Domestic-content mandates for critical components reshape sourcing strategies for aerospace and defense contractors in the United States and India. Geographic supply concentration exists with China and Taiwan dominating industrial and electronics-grade production, while specialized optical-grade material sources from Germany and the United States. Supply chains depend on access to high-purity fluorine chemistry for advanced grades. Regulatory compliance complexity, particularly with ECHA's REACH framework, poses a structural risk. Distribution runs through direct sales channels for specialized optical components, contrasting with broader distributor networks for industrial powders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The magnesium fluoride market functions as a regulatory compounder, where the push toward smaller semiconductor nodes drives demand for ultra-high purity material in advanced lithography applications.
For Market Incumbents:
Anchor existing market share by investing in advanced single-crystal growth techniques for optical-grade material, particularly for deep-ultraviolet photolithography. Expand production capacity for industrial-grade powders in strategic regions like the Yangtze River Delta to leverage economies of scale. Mitigate the threat of material substitution in less critical optical applications through continuous R&D into nanostructured coatings. Ensure rigorous adherence to ISO standards for optics to maintain access to defense and aerospace systems procurement.
For New Entrants and Emerging Players:
Capture opportunities in emerging aerospace markets in countries such as India and Brazil by focusing on optical components for new platforms. Target the growing electronics manufacturing sector in Southeast Asia for anti-reflective coatings and display applications. The industrial-grade segment in developing economies presents a penetrable entry point due to lower purity specifications. A viable go-to-market angle involves establishing co-development partnerships with end-users to provide customized purity and particle size specifications.
For Investors and Strategic Acquirers:
Roll-up economics work for specialized optical material producers because technical capability scarcity and capital-intensive production create high barriers to entry. The long-term viability of high-purity magnesium fluoride is strong, driven by persistent demand from advanced optics and semiconductor manufacturing. Target acquisition archetypes include innovators with proprietary synthesis techniques or integrated component manufacturers with captive material supplies. The expansion of deep-ultraviolet lithography capacity in Taiwan and Germany serves as a key signal to watch for inflection in high-purity demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Stella Chemifa Corporation can reinforce its scale in industrial applications through strategic investments. |
| Backward Integration | Saint-Gobain enhances control over material quality for finished optical components. |
| Green Manufacturing Transition | Compliance with ECHA's REACH framework can open premium market access in Europe. |
| Long-term Supply Agreement | Securing contracts with aerospace and defense contractors stabilizes demand for optical-grade material. |
| Joint Venture | Collaboration with semiconductor equipment firms accelerates development of ultra-high purity MgF2 for photolithography. |
Research Approach
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core for the magnesium fluoride market. This approach integrates primary interviews with optical engineers, procurement managers in aerospace and defense, R&D leads in semiconductor manufacturing, and chemical plant managers. Secondary validation draws from industry association reports, government trade statistics, company annual reports, and patent databases, triangulating data for accuracy and comprehensiveness.
Historical trendline analysis and correlation modeling establish the foundation for forecasting magnesium fluoride demand across the analysis window. The analytical framework models segmentation dimensions including product type, application, form, end-use industry, and regional demand patterns. Compound annual growth rates are calculated through a weighted average of segment-specific projections over the forecast period, incorporating inputs like semiconductor fabrication expansion rates and defense spending budgets.
Geopolitical shifts affecting trade, technological breakthroughs in alternative materials, and evolving regulatory landscapes are the dominant revision risks for market forecasts. Forecasts reflect assumptions regarding these dynamics, providing a baseline for market trajectory. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Epoxy Encapsulation Material Market
Specialty Materials
APAC Fluoroelastomer Market
Specialty Materials
Metalized Biaxially Oriented Polypropylene Films Market
Specialty Materials
ePTFE Electronic Film Market
Specialty Materials
Specialty Silica Market
Specialty Materials
EVA Interlayer for Photovoltaic Market
Specialty Materials
Ballistic Protection Materials Market
Specialty Materials
Global Flexible Substrates Market
Specialty Materials
Fumed Silica Market
Specialty Materials
Europe Solar Control Window Films Market
Specialty Materials
Dysprosium Oxide Sputtering Target Market
Specialty Materials
Global PU Films Market
Specialty Materials
Engineered Quartz Surface Market
Specialty Materials
Conductive Fluted Sheets Market
Specialty Materials
Dura Substitute Market
Specialty Materials
Mica Sheet Market