
 Silicone in Car Care Products Market | 2026-2036
Silicone in Car Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Silicone in Car Care Products Market Intelligence
Professional workshop demand is broadening as detailers shift from consumer-grade sprays toward concentrated silicone sealants with extended durability claims. Turtle Wax sustains mass-market shelf presence through retail partnerships with auto parts chains across North America. Sonax GmbH dominates professional channel supply in Europe with VOC-compliant formulations tailored to ECHA restrictions. Meguiar's differentiates through enthusiast-focused gloss enhancers that occupy premium positioning at specialty e-commerce platforms.
Silicone in car care products refers to polydimethylsiloxane-based compounds and modified siloxane polymers formulated into waxes, sealants, polishes, and cleaners that provide hydrophobic surface protection, gloss enhancement, and UV resistance for automotive substrates. These formulations typically contain between five and fifteen percent silicone content by weight, with volatile silicone fluids serving as carriers that evaporate to leave durable protective films bonded to clear coat or trim surfaces. Wax and sealant categories lead current value generation due to recurring application cycles and premium price positioning, while cleaner formulations with integrated silicone protection represent the fastest-expanding segment as time-constrained consumers seek multifunctional products. Exterior applications command the largest volume share, though interior trim dressings with low-VOC silicone emulsions are capturing margin pools as cabin air quality standards tighten.
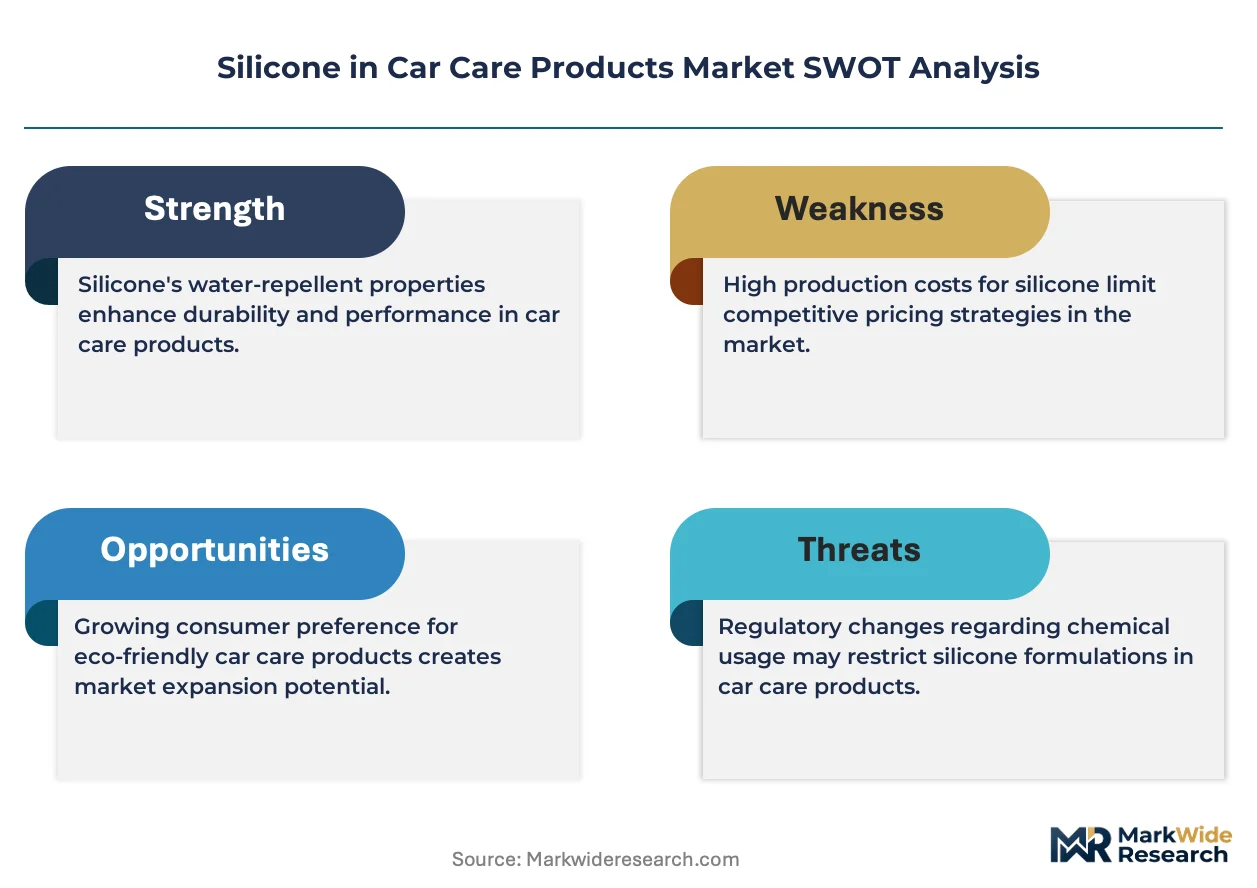
EPA oversight of volatile organic compound limits under 40 CFR Part 59 shapes permissible silicone carrier formulations in the United States, while REACH registration requirements through ECHA constrain cyclosiloxane content in European formulations. California Air Resources Board regulations enforce the strictest state-level VOC thresholds, forcing reformulation of traditional silicone sprays for compliance. OEM specification programs from major vehicle manufacturers increasingly require silicone-free or low-residue products for warranty-compliant detailing, pressuring suppliers to diversify chemistries. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions that may extend to silicone-fluoropolymer hybrid sealants and decide whether to accelerate bio-based silicone alternatives or defend incumbent formulations through regulatory exemption pathways.
Market Dynamics
REACH compliance through ECHA is forcing wholesale reformulation of silicone car care products across European supply chains, compressing cyclosiloxane content while elevating water-based emulsion chemistry as the dominant R&D priority for sealant manufacturers.
Growth Catalysts
- Professional Detailer Channel Expansion:Independent detailing workshops in the United States are migrating from consumer aerosols toward concentrated silicone sealants with extended durability claims, creating pull-through demand for bulk-format professional products.
- REACH-Driven Water-Based Transition:ECHA registration requirements for silicone intermediates are accelerating adoption of aqueous silicone emulsions that satisfy VOC thresholds without sacrificing hydrophobic performance.
- Ceramic-Silicone Hybridization:SiO2-infused silicone sealants are capturing premium shelf placement at specialty auto retailers by combining sprayable application ease with ceramic-grade durability.
Market Restraints
- Petrochemical Feedstock Volatility:Siloxane precursor costs track chlorosilane and methanol input prices, exposing formulators to margin compression when energy markets spike.
- OEM Warranty Exclusion Clauses:Major vehicle manufacturers specify silicone-free or low-residue products for factory-compliant detailing, restricting addressable market for traditional high-silicone formulations.
- Per- and Polyfluoroalkyl Substance Scrutiny:Expanding PFAS restrictions threaten silicone-fluoropolymer hybrid sealants, forcing suppliers to defend incumbent chemistries through regulatory exemption petitions.
Strategic Opportunities
- Interior Trim Emulsion Growth:Cabin air quality standards are tightening across multiple jurisdictions, opening margin pools for low-VOC silicone dressings that satisfy IAQ certification programs.
- Multifunctional Cleaner Integration:Time-constrained consumers are consolidating steps, creating white space for spray cleaners with integrated silicone protection that eliminates separate sealing applications.
- German KBA Type-Approval Pathway:Vehicle component testing protocols from Germany's Federal Motor Transport Authority offer a regulatory tailwind for silicone products achieving OEM-equivalent durability certification.
Industry Challenges
- Reformulation Timeline Compression:California Air Resources Board 40 CFR Part 59 compliance deadlines are forcing simultaneous chemistry redevelopment across aerosol and liquid product lines.
- Application Technician Certification:Professional detailers require training on proper silicone sealant cure times and layering protocols to prevent clear coat staining or trim residue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicone in Car Care Products Market |
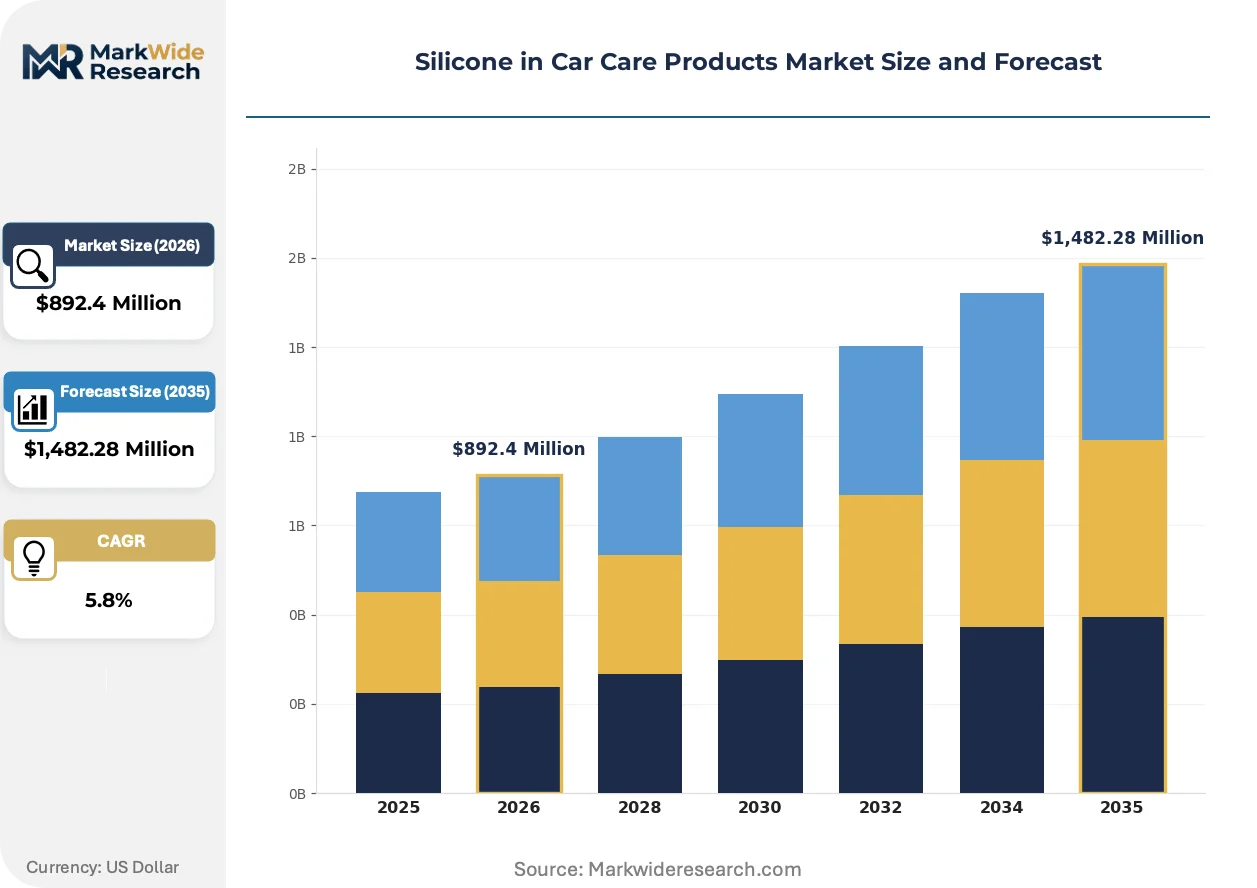
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,482.28 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wax, Sealant, Polish, Cleaner Application: Exterior, Interior, Engine, Tires End User: Consumers, Workshops, OEMs, Distributors Feature: Water Repellent, UV Protection, Gloss Enhancement, Scratch Resistance |
| Companies Covered | Simoniz USA, Inc., Autoglym Limited, 3M Company, Griot's Garage, LLC, Chemical Guys, Inc., Turtle Wax, Inc., Sonax GmbH, P&S Detail Products, Inc., Meguiar's, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicone in Car Care Products Market Strategic Shifts & Innovations
Silicone car care chemistry is pivoting from standalone hydrophobic films toward integrated multifunctional systems that combine protection, gloss, and cleaning in single-application formats.
Automated dispensing systems for concentrated silicone sealants are automating dilution and application in high-volume detailing operations. Fleet maintenance departments and rental car processors are adopting these systems to standardize finish quality across multiple locations. The technology is automating labor cost out of recurring vehicle preparation workflows while reducing product waste from manual mixing errors.
EPA oversight under 40 CFR Part 59 is tightening volatile organic compound limits for silicone carrier fluids used in aerosol waxes and spray sealants. Formulators are responding by substituting volatile methylsiloxanes with high-boiling-point aqueous emulsions that flash off through evaporation rather than solvent volatilization. Aerosol-dependent product categories face the steepest compliance costs, accelerating SKU consolidation among mass-market brands.
Subscription-based auto detailing services are unbundling product procurement from application labor, shifting silicone sealant purchasing decisions from individual consumers to fleet managers and platform operators. These buyers negotiate annual supply contracts with performance guarantees rather than per-unit retail transactions. The United States exhibits the most advanced development of this procurement model, driven by corporate vehicle fleet outsourcing trends.
Silicone in Car Care Products Market Segmentation
Silicone car care purchasing decisions diverge sharply between enthusiast hobbyists seeking premium gloss and fleet operators prioritizing throughput economics. Workshop procurement managers evaluate concentrated bulk formats against retail consumers buying spray-and-wipe convenience. Product formulation requirements further fragment across OEM warranty compliance, professional durability claims, and regulatory VOC thresholds.
Product Type:
Application frequency and per-unit price point drive buyer selection within this category, with recurring-use products commanding larger volume commitments than one-time restoration treatments.
- Wax:Carnauba-silicone hybrid formulations deliver 3-6 month protection cycles through paste and liquid carriers. Consumer retail channels in the United States stock these SKUs most heavily due to established brand recognition and seasonal reapplication rituals.
- Sealant:Polydimethylsiloxane-based synthetic coatings bond covalently to clear coat surfaces for 6-12 month durability. Professional detailing workshops in Germany specify these for fleet contracts under KBA-equivalent performance certification requirements.
- Polish:Abrasive silicone-oil suspensions remove oxidation while depositing thin protective films. Restoration specialists favor these for aged paint rehabilitation.
- Cleaner:Multifunctional spray formulations integrate surfactant cleaning with silicone residue deposition. Time-constrained vehicle owners consolidate steps, expanding this segment's addressable base.
Volume sits with Sealant; growth tilts toward Cleaner.
Application:
Surface exposure severity and aesthetic visibility determine silicone specification intensity across vehicle zones.
- Exterior:Clear coat, trim, and glass surfaces receive silicone sealants with 5-15% polydimethylsiloxane content for hydrophobic performance. UV degradation exposure drives reapplication cycles and recurring revenue pools.
- Interior:Dashboard, door panel, and leather treatments employ low-VOC silicone emulsions to satisfy cabin air quality standards tightening under EPA and ECHA oversight.
- Engine:Heat-resistant silicone dressings protect rubber hoses and plastic shrouds from thermal cycling damage. Specialty formulations tolerate sustained temperatures above 150°C.
- Tires:Solvent-based silicone sprays restore sidewall appearance with high-gloss finishes. Water-based alternatives are gaining share where VOC regulations restrict petroleum distillate carriers.
Revenue concentrates in Exterior; expansion is steepest in Interior.
End User:
Procurement scale and technical sophistication separate buyer segments, from individual retail transactions to negotiated annual supply agreements.
- Consumers:Individual vehicle owners purchase aerosol and trigger-spray formats through auto parts retailers and e-commerce platforms. Brand loyalty and application convenience dominate selection criteria.
- Workshops:Independent detailing operations and collision repair centers source concentrated bulk sealants with dilution systems. These buyers prioritize per-vehicle material cost and labor efficiency.
- OEMs:Vehicle manufacturers specify silicone-free or low-residue products for factory finish preservation and warranty-compliant dealer detailing programs.
- Distributors:Regional supply houses aggregate demand from smaller workshops, negotiating volume discounts and private-label formulation services.
Transaction volume flows through Workshops; margin capture favors Distributors.
Feature:
Performance claims differentiate formulations at shelf and in professional specification documents, with multi-benefit positioning commanding price premiums.
- Water Repellent:Hydrophobic silicone films create contact angles above 90 degrees, sheeting water from painted surfaces. This property anchors consumer value perception and marketing messaging.
- UV Protection:UV-absorber additives in silicone matrices prevent clear coat oxidation and color fade. Sunbelt regions in the United States drive geographic concentration of demand.
- Gloss Enhancement:Refractive index matching between silicone films and clear coat produces depth-of-gloss effects prized by enthusiast detailers and show vehicle owners.
- Scratch Resistance:Ceramic-silicone hybrid formulations deposit SiO2 particles that increase surface hardness measurably. These products occupy premium positioning at specialty retailers.
Market presence is broadest for Water Repellent; premium positioning concentrates in Scratch Resistance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of silicone car care formulations clusters in Germany and the United States, while consumption spreads across multiple geographies with distinct regulatory thresholds and channel preferences.
United States
California Air Resources Board 40 CFR Part 59 enforcement drives reformulation of aerosol silicone sprays toward aqueous carriers. EPA oversight shapes permissible volatile organic compound limits nationwide, compressing margins for legacy solvent-based products. Specialty auto retailers in Los Angeles and Miami command premium placement for ceramic-silicone hybrid waxes.
Germany
REACH registration requirements through ECHA constrain cyclosiloxane content in professional sealant formulations. KBA type-approval pathways offer regulatory tailwinds for products achieving OEM-equivalent durability certification. Detailing workshops in Stuttgart and Munich specify concentrated bulk sealants under fleet contracts.
China
Domestic automakers specify silicone-free or low-residue products for warranty-compliant dealer detailing programs. MIIT oversight of chemical manufacturing standards shapes formulation requirements for both domestic consumption and export markets. Production clusters in Guangdong province supply aqueous emulsion chemistry to Southeast Asian distributors.
Japan
METI guidelines on volatile organic compound emissions influence silicone carrier selection in automotive aftermarket products. JIS standards for surface protection coatings create certification barriers for imported sealant formulations. Detailing specialists in Osaka and Nagoya prioritize gloss-enhancing silicone polishes for enthusiast vehicle owners.
United Kingdom
Post-Brexit alignment with REACH principles maintains cyclosiloxane restrictions while creating divergence from EU ECHA registration timelines. Independent detailing chains in London and Birmingham consolidate procurement through regional distributors negotiating volume discounts. E-commerce platforms capture growing share of consumer-grade silicone wax purchases.
Silicone in Car Care Products Market Key Industry Players
Top-tier vendors anchor professional and retail channels with established brand recognition, while mid-tier specialists occupy niche positioning through formulation differentiation and geographic focus. The vendor base spans multinational chemical conglomerates with diversified portfolios, dedicated automotive aftermarket pure-plays, and regional formulators serving localized regulatory requirements. Two dominant competitive moves are reshaping positioning: portfolio diversification into ceramic-silicone hybrid chemistries, and strategic partnerships with professional detailing networks for specification lock-in.
Within the dedicated automotive aftermarket tier, Turtle Wax, Inc. and Sonax GmbH exemplify divergent geographic anchoring and channel specialization. Turtle Wax sustains mass-market shelf presence through retail partnerships across North America. Sonax GmbH dominates professional channel supply in Europe with formulations tailored to ECHA restrictions. Meguiar's, Inc. occupies a position within the enthusiast-focused segment, differentiating through gloss enhancers at specialty e-commerce platforms. These three companies represent the spectrum from volume-driven retail to compliance-driven professional supply.
| Leading Market Players |
|---|
| Simoniz USA, Inc. |
| Autoglym Limited |
| 3M Company |
| Griot's Garage, LLC |
| Chemical Guys, Inc. |
| Turtle Wax, Inc. |
| Sonax GmbH |
| P&S Detail Products, Inc. |
| Meguiar's, Inc. |
| Others |
Cost & Logistics Intelligence
REACH-driven reformulation mandates from ECHA are compressing cyclosiloxane availability and forcing formulators toward aqueous emulsion chemistry, which elevates input costs and fragments pricing power across compliant versus legacy product tiers.
Pricing Analysis
Short lead-time premiums for KBA-certified sealants run 15-25% above standard professional grades, while spot inventory of VOC-compliant concentrates trades at discounts in oversupplied German distribution channels. Three-tier pricing structure across premium ceramic-silicone hybrids, standard polydimethylsiloxane sealants, and economy-grade spray waxes anchors the market. Price differentiation hinges on ECHA compliance certification and volume procurement scale. Cost compression in aerosol formats is intensifying because California Air Resources Board deadlines are forcing simultaneous line redevelopment. Fleet operators exhibit the highest price sensitivity, while enthusiast detailers at specialty retailers show the least.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg orchestrate hub-and-spoke patterns for aqueous silicone emulsions entering European professional channels. Manufacturing concentrates in Germany, the United States, and China, with chlorosilane and methanol feedstock costs tethered to energy market volatility. Siloxane precursor supply draws from petrochemical complexes in the US Gulf Coast and German chemical corridors. Single-source vulnerability in cyclosiloxane intermediates creates concentration risk for REACH-compliant formulations. Distribution runs through dedicated automotive aftermarket distributors serving independent detailing workshops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressures are mounting as ECHA registration costs and reformulation timelines force sub-scale formulators toward exit or acquisition, concentrating share among compliant professional suppliers.
For Market Incumbents: Deploy certification leverage by accelerating KBA type-approval acquisition to lock fleet contracts before smaller competitors complete compliance transitions. Deepen backward integration into aqueous emulsion production to defend margin position against chlorosilane price spikes. Sonax GmbH's established ECHA-compliant supply chain demonstrates how regulatory anticipation creates defensive moats.
For New Entrants and Emerging Players: California Air Resources Board 40 CFR Part 59 implementation in the United States opens a window for aqueous-based concentrate specialists to capture share from aerosol-dependent incumbents struggling with simultaneous line redevelopment. Interior trim emulsions for cabin air quality certification represent the most penetrable white space. A direct-to-workshop bulk supply model bypasses retail shelf slotting barriers.
For Investors and Strategic Acquirers: The window for entry favors mid-tier European formulators with pending ECHA dossier completion and established KBA testing relationships. Five-to-ten year viability rests on regulatory compliance infrastructure rather than brand equity alone. Monitor PFAS restriction expansion signals as the inflection indicator for silicone-fluoropolymer hybrid obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aqueous Emulsion Production | Captive supply of REACH-compliant chemistry reduces exposure to chlorosilane volatility and ECHA-registered intermediate shortages. |
| KBA Type-Approval Investment | OEM-equivalent durability certification unlocks fleet contract specification lock-in across German professional detailing networks. |
| Ceramic-Silicone Hybrid R&D Pipeline | SiO2-infused formulations command premium shelf placement at specialty retailers in Los Angeles and Miami. |
| Professional Workshop Distribution Partnership | Direct supply agreements with independent detailers bypass retail margin compression and build recurring revenue pools. |
| Low-VOC Interior Emulsion Development | Cabin air quality certification positions products for tightening EPA and ECHA oversight on dashboard and trim treatments. |
Research Approach
Document review covered ECHA registration databases, EPA 40 CFR Part 59 compliance filings, and KBA type-approval records, complemented by interviews with formulation chemists at silicone sealant manufacturers, procurement managers at German fleet detailing operations, and category buyers at North American auto parts retailers. Secondary validation drew from chemical industry trade association reports, customs data on siloxane precursor imports, and SEC filings from diversified chemical conglomerates with automotive aftermarket exposure. Bottom-up demand modeling from workshop and retail channel volumes was cross-referenced against top-down chemical consumption estimates.
Historical volume trajectories were cross-referenced against expert panel input from technical directors at professional detailing product suppliers. Segmentation modeling spanned product type, application surface, end-user procurement scale, and feature-based performance tier across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating regulatory compliance cost pass-through assumptions. Forecast inputs included ECHA registration timeline probabilities, California Air Resources Board enforcement intensity scenarios, and ceramic-silicone hybrid adoption curves at specialty retailers.
The model assumes a particular technology adoption path for aqueous silicone emulsions; alternative pathways for solvent-based formulation persistence would alter the outlook if regulatory enforcement delays materialize. Forecasts reflect documented assumptions about REACH compliance cost trajectories and PFAS restriction scope expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Car Care Cosmetics Market
Vehicle Maintenance & Aftermarket
Engine Module-Level Repair and Refurbishment Services Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Fuel Additives Market
Vehicle Maintenance & Aftermarket
Highway Maintenance Market
Vehicle Maintenance & Aftermarket
Car Wash Ancillary Products Market
Vehicle Maintenance & Aftermarket
Europe E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Wash Market
Vehicle Maintenance & Aftermarket
Classic Car Restoration and Restomod Services Market
Vehicle Maintenance & Aftermarket
Global Integrated Vehicle Health Management Market
Vehicle Maintenance & Aftermarket
Antimicrobial Car Care Products Market
Vehicle Maintenance & Aftermarket
Asia Pacific Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Global Road Maintenance Market
Vehicle Maintenance & Aftermarket
Car Duster Market
Vehicle Maintenance & Aftermarket
Car Care Products Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Cleaning Products Market
Vehicle Maintenance & Aftermarket
Car and Truck Wash Market