

Highway Maintenance Market Size, Share, and Industry Trends Forecast 2026-2036
Highway Maintenance Market Insights
The EU Green Deal is repositioning highway maintenance specifications across member states toward lower-carbon binders and reclaimed asphalt thresholds. Vinci leverages its integrated concessions model to control lifecycle asset performance on European toll corridors. Colas Group sustains leadership in warm-mix asphalt technologies that reduce production emissions. Skanska competes through digital twin deployment on Scandinavian bridge portfolios.
Highway maintenance encompasses the scheduled inspection, repair, and renewal of paved road surfaces, drainage infrastructure, signage, and roadside vegetation to preserve design service levels and user safety. Core activities include crack sealing with polymer-modified sealants, asphalt overlay placement at 40-60 mm thickness, and subgrade stabilization using geosynthetics or cement treatment. Pavement Repair dominates service-type revenue due to recurrent thermal cracking and rutting remediation needs, while Drone Inspection represents the fastest-expanding technology segment as agencies adopt automated distress detection to reduce manual survey labor and accelerate work-order generation.
The Federal Highway Administration enforces National Highway System condition standards that mandate minimum pavement serviceability ratings, while state departments of transportation implement Americans with Disabilities Act-compliant curb ramp replacement programs. The EPA regulates stormwater runoff from maintenance yards through National Pollutant Discharge Elimination System permits, constraining equipment wash-down and material storage practices. Stakeholders must monitor evolving Buy America domestic content rules for steel and aggregates, as waiver eligibility will reshape supplier qualification and project bidding strategies.
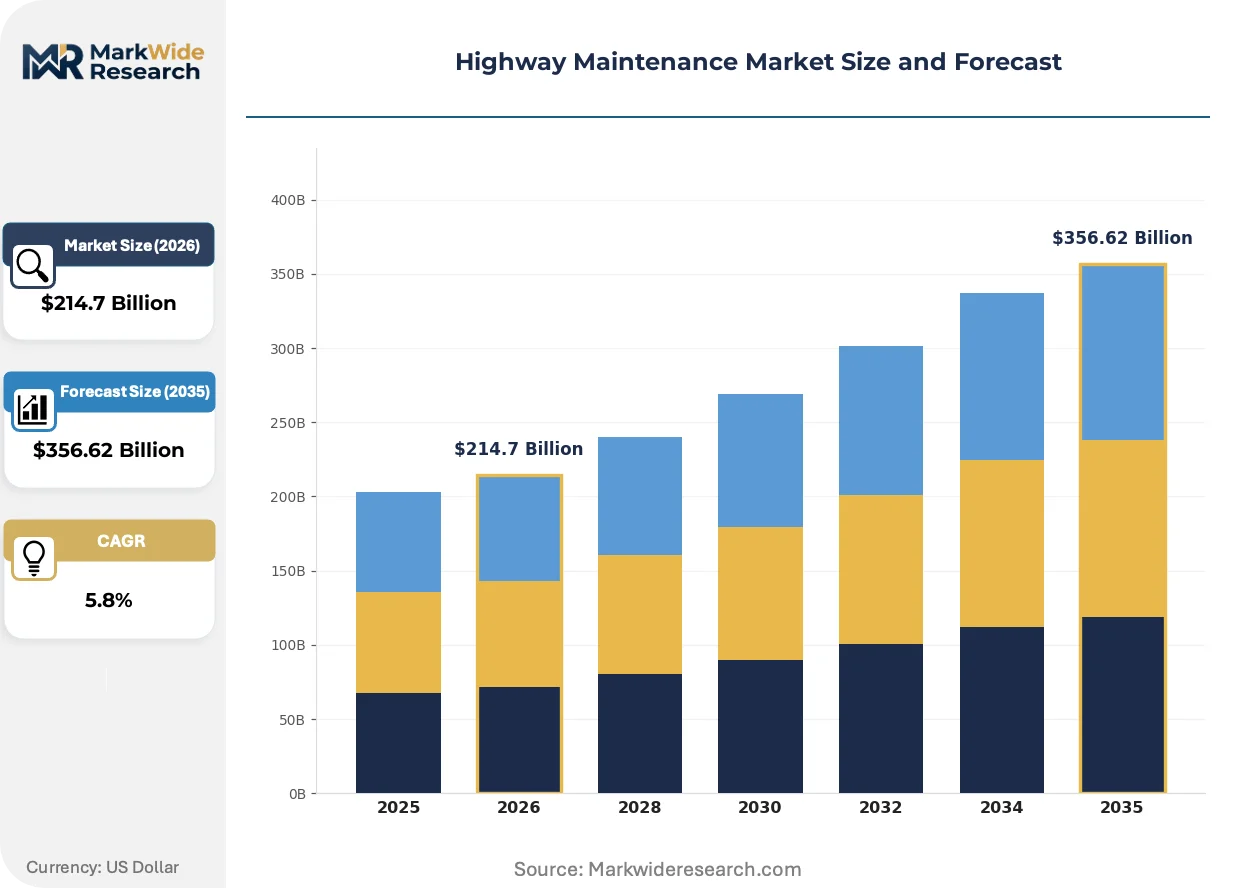
Market Dynamics
Cold in-place recycling technology is compressing project timelines and material costs for state transportation departments, while federal stimulus programs expand the total addressable contract volume for pavement rehabilitation services.
Growth Catalysts
- Federal infrastructure stimulus:United States procurement volumes for pavement rehabilitation contracts are expanding under congressional appropriations, with state departments of transportation accelerating project lettings to capture available funding.
- Asset management frameworks:India's National Highways Authority is compressing lane-kilometer renewal schedules, creating sustained demand for inspection and overlay services across the national highway network.
- Drone inspection adoption:Automated distress detection systems are displacing manual survey labor, with transportation agencies reducing work-order generation cycles from weeks to days.
Market Restraints
- Bitumen price volatility:Crude oil-linked input costs create margin compression for asphalt overlay contractors, forcing hedging strategies or price escalation clauses in multi-year maintenance agreements.
- Specialized equipment concentration:Cold recycling machinery manufacturing concentrates among German and Italian suppliers, creating procurement bottlenecks for North American contractors seeking fleet expansion.
- Buy America compliance friction:Waiver eligibility uncertainty for steel and aggregate domestic content rules is delaying supplier qualification and project bidding timelines.
Strategic Opportunities
- Warm-mix asphalt penetration:Lower-carbon production technologies align with EU Green Deal binder specifications, opening replacement cycles for conventional hot-mix capacity across European member states.
- Digital twin integration:Bridge portfolio operators in Scandinavia are converging sensor networks with predictive analytics, creating demand for lifecycle performance modeling services.
- Geosynthetics substitution:Subgrade stabilization applications are expanding beyond cement treatment to polymer-based solutions, offering faster cure times in high-moisture environments.
Industry Challenges
- Geotechnical engineer scarcity:Specialized pavement design expertise is concentrating among aging practitioners, with university programs failing to replenish technical capacity for subgrade analysis and overlay thickness calculations.
- Legacy equipment retrofit costs:Cold planer fleets require emissions control upgrades to meet state environmental operating permits, straining contractor capital allocation between maintenance and expansion.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Highway Maintenance Market Trends and Innovations
Technology convergence and regulatory carbon constraints are reshaping material specifications and inspection methodologies across highway maintenance operations.
Digital twin platforms are unifying structural health monitoring with predictive maintenance scheduling for bridge and tunnel assets. Scandinavian transportation authorities are deploying these systems across major corridors, compressing inspection intervals while extending component replacement cycles. The technology is unifying previously siloed engineering, operations, and finance functions into single-source-of-truth asset registries.
EU Green Deal specifications are mandating reclaimed asphalt pavement thresholds and lower-temperature binder grades across member state procurement frameworks. National highway agencies are revising technical standards to accommodate higher recycled content without compromising fatigue resistance. France and Germany are most affected, with their concession operators renegotiating performance contracts to reflect revised material compliance obligations.
Performance-based contracting is displacing unit-price arrangements for major rehabilitation programs. State transportation departments are transferring pavement condition risk to contractors through multi-year availability payments tied to serviceability index targets. This shift is most visible in the United States, where federal stimulus project delivery methods are accelerating design-build-finance-operate structures for interstate corridor renewal.
Highway Maintenance Market Segmentation
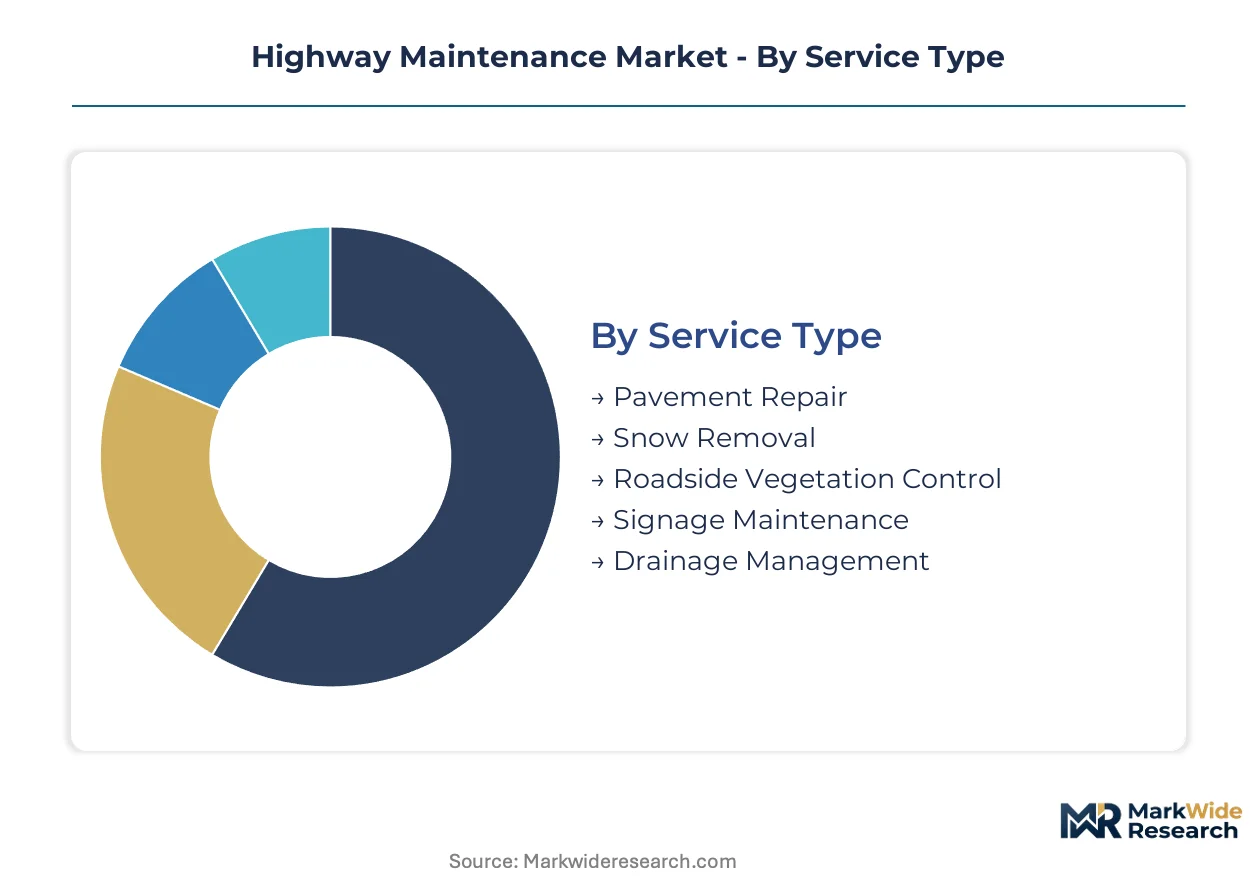
Highway maintenance procurement patterns diverge sharply across service modalities, technology platforms, and asset ownership structures. Understanding these divisions reveals where budget allocation concentrates and which contractor capabilities command premium positioning.
Service Type:
Municipal buyers prioritize lifecycle cost over upfront expenditure; highway authorities weight traffic disruption minimization more heavily.
- Pavement Repair:Polymer-modified sealants and 40-60 mm asphalt overlays address recurrent thermal cracking and rutting. State transportation departments in the United States dominate contract volume, with federal stimulus programs accelerating mill-and-fill and cold in-place recycling procurements.
- Snow Removal:Mechanical plowing, chemical de-icing, and abrasive spreading preserve winter mobility on priority corridors. Scandinavian municipalities and mountain-state departments in the United States sustain the densest equipment fleets, driven by statutory lane-clearance time mandates.
- Roadside Vegetation Control:Mowing schedules and herbicide applications maintain sight distance and drainage function. Utility corridor easements and wildfire-prone jurisdictions in California and Australia drive specialized mechanized clearing contracts.
- Signage Maintenance:Retroreflective sheeting replacement and structural post repair ensure nighttime visibility compliance. Americans with Disabilities Act curb ramp programs in the United States generate concentrated retrofit demand.
- Drainage Management:Culvert rehabilitation, ditch regrading, and stormwater infrastructure cleaning prevent subgrade saturation. EPA National Pollutant Discharge Elimination System permit enforcement constrains maintenance yard practices.
Pavement Repair leads volumes today; Drone Inspection (under Technology) is gaining share fastest.
Technology:
Agency technology adoption splits between productivity-enhancing automation and compliance-driven monitoring systems.
- Automated Road Surveying:Laser profilometers and accelerometer-equipped vehicles capture roughness, rutting, and cracking indices at highway speeds. India's National Highways Authority deploys these systems across lane-kilometer renewal schedules to compress inspection cycles.
- Drone Inspection:Automated distress detection algorithms process high-resolution imagery to classify pavement defects and bridge deterioration. Transportation agencies reduce work-order generation timelines from weeks to days, displacing manual survey labor.
- Infrared Asphalt Repair:On-demand heating of existing pavement enables seamless patch placement without cold joints. Urban road maintenance divisions favor this technology for high-traffic corridor spot repairs.
- Tire Pressure Monitoring:Fleet telematics integration tracks heavy equipment tire conditions to minimize downtime and fuel consumption. Large-scale pavement contractors deploy these systems across cold planer and paver fleets.
- Road Weather Information Systems:Sensor networks and predictive algorithms guide anti-icing treatment timing and traffic management decisions. Mountain corridor operators in the United States and Alpine jurisdictions rely on these platforms for avalanche and ice hazard mitigation.
Automated Road Surveying anchors current procurement; Drone Inspection climbs the fastest.
Application:
Asset ownership structures dictate maintenance funding mechanisms and contractor payment terms.
- Expressway Maintenance:Multi-lane controlled-access corridors demand continuous pavement serviceability and rapid incident response. Performance-based contracting with availability payments tied to serviceability index targets is displacing unit-price arrangements.
- Toll Road Upkeep:Concession operators integrate lifecycle asset performance obligations into long-term contracts. Vinci and Colas Group leverage integrated concessions models to control European toll corridor maintenance specifications.
- Urban Road Care:Signalized intersection maintenance, curb and gutter repair, and ADA-compliant ramp replacement dominate municipal workloads. City transportation departments balance resident accessibility complaints with compressed overnight work windows.
- Rural Highway Service:Lower traffic volumes permit longer response times but stretch resources across dispersed networks. County road agencies prioritize gravel road grading and low-volume bridge load posting.
- Bridge Maintenance:Structural health monitoring, joint repair, and deck overlay placement preserve load-carrying capacity. Skanska deploys digital twin platforms across Scandinavian bridge portfolios to unify sensor networks with predictive analytics.
Expressway Maintenance commands the largest contract value; Toll Road Upkeep shows the steepest expansion trajectory.
End User:
Buyer sophistication ranges from standardized procurement departments to engineering-intensive asset managers.
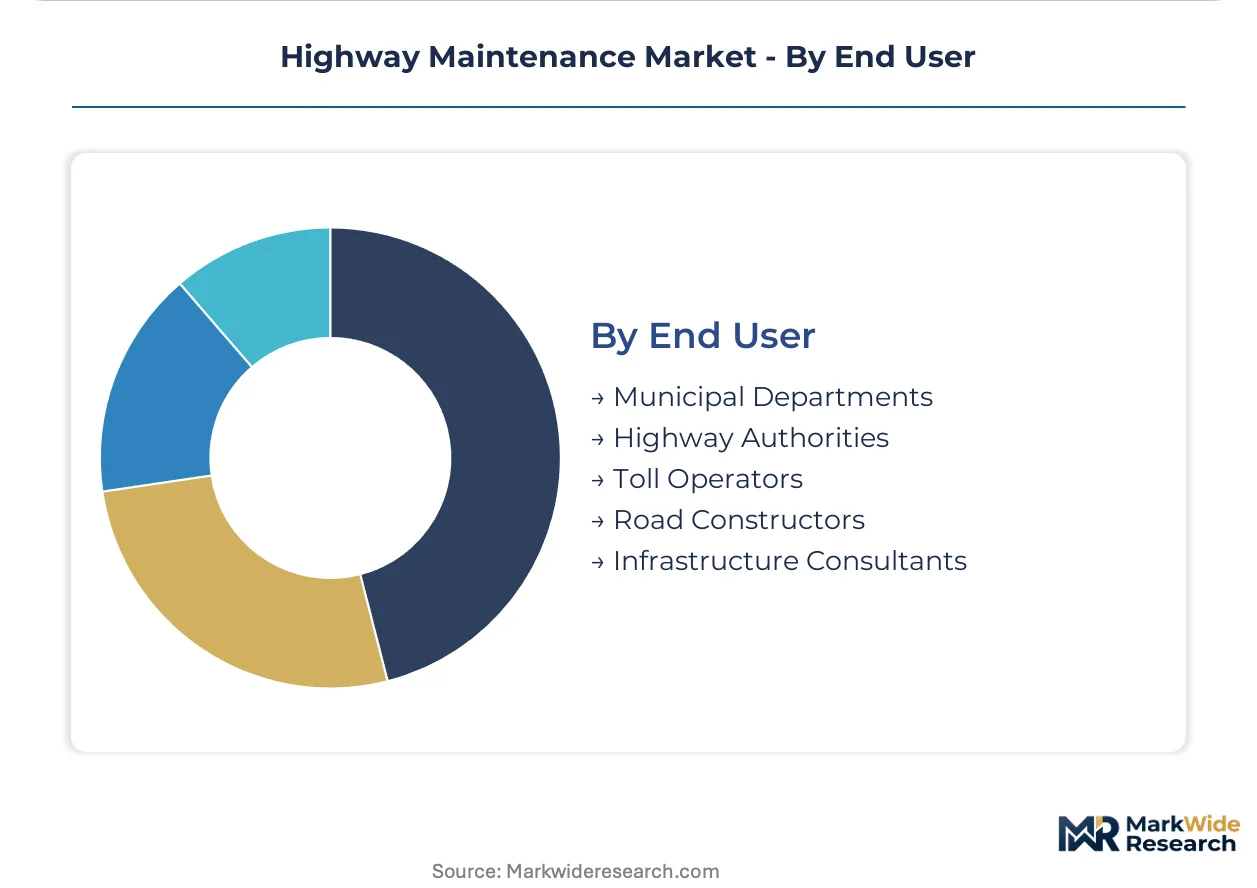
- Highway Authorities:Centralized technical standards and multi-year capital programs enable complex rehabilitation project packaging. India's National Highways Authority and United States state DOTs concentrate pavement overlay and bridge renewal demand.
- Toll Operators:Revenue-risk-bearing entities prioritize traffic flow preservation and lifecycle cost optimization. European concession holders negotiate performance contract renegotiations to reflect EU Green Deal material compliance obligations.
- Municipal Departments:Politically accountable agencies weight visible service delivery and resident complaint resolution. Snow removal and pothole repair dominate seasonal procurement cycles.
- Road Constructors:Design-build and design-build-finance-operate contractors internalize maintenance risk across extended contract terms. Federal stimulus project delivery methods accelerate these structures for interstate corridor renewal in the United States.
- Infrastructure Consultants:Engineering firms provide pavement design, condition assessment, and asset management planning services. Geotechnical engineer scarcity concentrates specialized pavement design expertise among aging practitioners.
Highway Authorities represent the dominant procurement volume; Toll Operators are expanding their share most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern highway maintenance industry traces its scaled operational roots to post-war interstate construction programs in the United States, where systematic pavement management systems first institutionalized lifecycle asset planning across thousands of lane-kilometers.
United States
Federal infrastructure stimulus appropriations are accelerating state DOT project lettings for pavement rehabilitation contracts. The Federal Highway Administration enforces National Highway System condition standards mandating minimum serviceability ratings. Texas and California transportation departments concentrate cold in-place recycling procurements, compressing traditional mill-and-fill timelines.
India
The National Highways Authority is compressing lane-kilometer renewal schedules under its asset management framework, creating sustained inspection and overlay demand. Central government capital allocation prioritizes national corridor connectivity upgrades. Maharashtra and Gujarat highway circles host the densest contractor mobilization for overlay placement contracts.
Germany
EU Green Deal binder specifications are mandating reclaimed asphalt thresholds and lower-temperature production grades across federal procurement frameworks. The KBA coordinates technical standards alignment with carbon reduction roadmaps. Bavarian and North Rhine-Westphalian concession operators are renegotiating performance contracts to reflect revised material compliance obligations.
France
Integrated concessions models control lifecycle asset performance on European toll corridors, transferring pavement condition risk to operators through availability payment structures. The EU Green Deal is repositioning highway maintenance specifications toward lower-carbon binders. Greater Paris and Lyon corridor networks concentrate warm-mix asphalt technology deployment.
Sweden
Digital twin platforms are unifying structural health monitoring with predictive maintenance scheduling across Scandinavian bridge portfolios. The Swedish Transport Administration compresses inspection intervals while extending component replacement cycles through sensor network integration. Stockholm and Gothenburg metropolitan corridors anchor predictive analytics service demand.
Highway Maintenance Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth and concession tenure length, with integrated asset managers commanding superior returns against unit-price contractors. The vendor base stratifies between global engineering-construction conglomerates, specialized pavement technology providers, and regional maintenance contractors. Two strategic archetypes dominate: concession-integrated operators leveraging long-term availability contracts, and technology-forward specialists deploying predictive asset management platforms. Competitive moves concentrate on performance-based contracting conversions and digital twin capability acquisitions.
Within the integrated concessions tier, Vinci and Colas Group exemplify archetypes of lifecycle asset control through European toll corridor operations. Skanska occupies a position representing technology-forward positioning through digital twin deployment across Scandinavian infrastructure portfolios. These three entities anchor the competitive structure, with Vinci and Colas Group representing concession-integrated models and Skanska exemplifying predictive analytics specialization.
| Leading Market Players |
|---|
| Vinci |
| Colas Group |
| Skanska |
| Jacobs Engineering Group |
| AECOM |
| WSP Global |
| Ferrovial |
| Balfour Beatty |
| Kier Group |
| Others |
Pricing and Supply Chain Analysis
Geotechnical engineer scarcity in Germany and Italy compresses labor-cost differentials between premium-tier design-build operators and standard unit-price contractors, widening pricing spreads as specialized pavement design expertise concentrates among aging practitioners.
Pricing Analysis
Performance-based contracting with multi-year availability payments tied to serviceability index targets now dominates expressway rehabilitation programs, separating concession-integrated operators from commodity unit-price bidders. Price differentiation hinges on digital twin capability depth and warm-mix asphalt certification grade. Cost compression in standard overlay tiers is intensifying because cold recycling machinery procurement bottlenecks strain contractor capital allocation. Municipal departments exhibit highest price sensitivity; toll operators prioritize lifecycle cost optimization over upfront expenditure.
Supply Chain Analysis
Dual-sourcing requirements from state transportation departments mandate multi-supplier qualification for cold planer fleets and polymer-modified binder feedstocks, mitigating single-source vulnerability. Manufacturing concentrates in Germany, Italy, and the United States for specialized recycling equipment. Raw material dependencies span crude oil-linked bitumen, reclaimed asphalt pavement, and geosynthetic polymers. Tariff exposure on steel and aggregate imports under evolving Buy America rules creates procurement friction. Distribution runs through regional equipment dealerships and direct manufacturer relationships to contractor fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Highway maintenance offers margin-expansion potential as drone inspection technology displaces manual survey labor, compressing work-order generation costs while enabling premium-tier predictive analytics services.
For Market Incumbents: Anticipate displacement risk from cold in-place recycling technology by securing exclusive distribution agreements with German and Italian equipment manufacturers. Invest in digital twin platform acquisitions to defend concession-integrated positioning against technology-forward specialists. Strengthen backward integration into reclaimed asphalt pavement processing to control binder cost volatility. For New Entrants and Emerging Players: Drone-as-a-service platforms offer the most penetrable entry vector for state transportation departments seeking automated distress detection capabilities. Target county road agencies in rural highway service segments where inspection labor shortages are most acute. Pursue pilot program partnerships with India's National Highways Authority to establish lane-kilometer renewal credentials. For Investors and Strategic Acquirers: Integrated construction-engineering conglomerates are the most active acquirers in this space, consolidating digital twin capabilities and concession portfolios. Focus on mid-cap contractors with established state DOT relationships and cold recycling equipment fleets. Watch federal infrastructure stimulus appropriation velocity as the signal for contract volume inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Recycling Equipment Fleet Expansion | Texas and California DOTs are compressing mill-and-fill timelines through accelerated procurement. |
| Digital Twin Platform Integration | Swedish Transport Administration deployments unify sensor networks with predictive maintenance scheduling. |
| Reclaimed Asphalt Processing Backward Integration | EU Green Deal thresholds mandate higher recycled content across French and German concessions. |
| Warm-Mix Asphalt Certification Investment | Colas Group sustains leadership as member states revise technical standards for lower-carbon binders. |
| Performance-Based Contracting Conversion | Federal stimulus programs accelerate design-build-finance-operate structures for interstate corridor renewal. |
Research Methodology
Multiple input streams — executive interviews with state DOT procurement officers, technical discussions with pavement engineering directors, and operational assessments from concession operators — were reconciled against regulatory filings from the Federal Highway Administration and National Highways Authority of India. Secondary validation drew from EPA National Pollutant Discharge Elimination System permit databases, EU Green Deal implementation frameworks, and equipment manufacturer customs records. Bottom-up project letting analysis and top-down infrastructure budget appropriation tracking were triangulated to establish market sizing.
Historical contract award patterns were cross-referenced against expert panel assessments of technology adoption timelines across the analysis window. Segmentation modeling incorporated service type, technology platform, application structure, and end-user sophistication dimensions. CAGRs were derived from expenditure trajectory analysis and funding authorization projections. Forecast inputs included federal stimulus appropriation schedules, lane-kilometer renewal commitments under India's asset management framework, and cold in-place recycling penetration assumptions.
The model assumes a particular technology adoption path; alternative pathways for drone inspection deployment would alter the outlook if regulatory certification delays emerge. Forecasts reflect assumptions regarding bitumen price stability, equipment manufacturing capacity expansion, and concession contract renegotiation timelines. Deviation in federal infrastructure funding continuity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.