
 Global Integrated Vehicle Health Management Market | 2026-2036
Global Integrated Vehicle Health Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Integrated Vehicle Health Management Market Intelligence
ISO 26262 functional safety certification is redrawing competitive boundaries in integrated vehicle health management. Robert Bosch GmbH leverages its semiconductor and sensor portfolio to anchor integrated diagnostics across powertrain domains. Continental AG sustains R&D intensity in edge-computing modules that process sensor data at the vehicle level. KPIT specializes in software-layer solutions that navigate heterogeneous vehicle networks for commercial fleet operators.
Integrated Vehicle Health Management denotes the continuous acquisition, fusion, and analysis of multi-source vehicle data to predict failures, optimize performance, and schedule maintenance before critical degradation occurs. Systems typically integrate accelerometers, temperature sensors, CAN bus loggers, and oil particulate counters sampling at 1–10 kHz to detect incipient bearing wear, thermal stress, or battery cell imbalance. Predictive Analytics Systems lead in value contribution as fleet operators prioritize uptime economics over reactive repair models. Cloud-Based Platforms represent the fastest-expanding deployment mode, though Onboard Systems retain margin concentration in heavy-duty applications where connectivity gaps persist.
FDA oversight of automotive-grade software in the United States, ECE R10 electromagnetic compatibility standards in Europe, and China's GB/T vehicle networking security protocols collectively shape product certification timelines and market access requirements. NHTSA defect investigation protocols in the United States further accelerate OEM investment in preemptive fault detection to mitigate recall exposure. Stakeholders must monitor divergence between regional data sovereignty mandates and cross-border fleet telematics architectures as a primary strategic uncertainty.
Market Dynamics
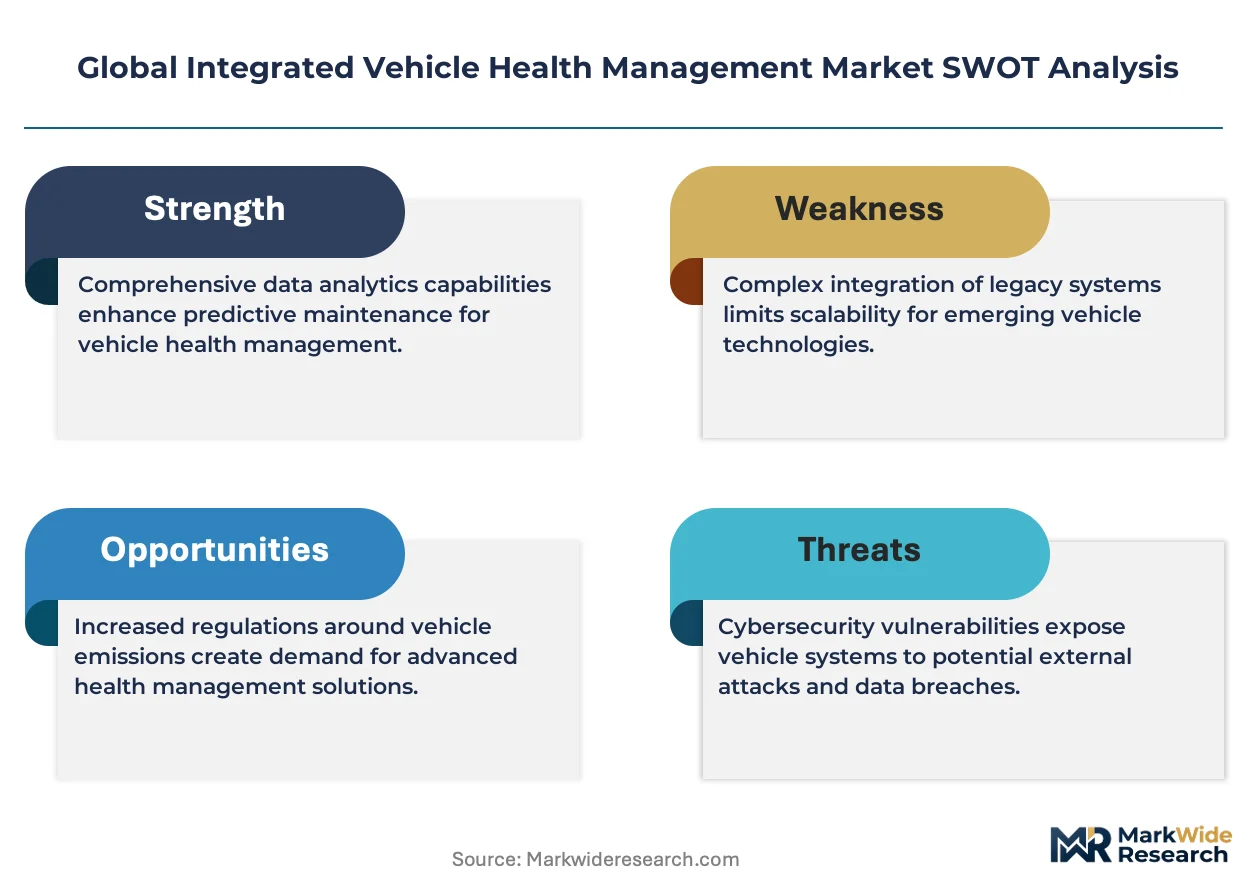
ISO 26262 functional safety certification is redrawing competitive boundaries as automakers embed predictive diagnostics into powertrain architectures, forcing tier-1 suppliers to consolidate sensor fusion capabilities or exit the value chain.
Growth Catalysts
- EU F-Gas Regulation:Stringent fluorinated gas emission caps mandate real-time refrigerant leak detection in commercial vehicle fleets, accelerating deployment of continuous monitoring architectures across European logistics operators.
- Edge-computing modules:Onboard processing at 1–10 kHz sampling rates enables millisecond-level anomaly detection in bearing wear and thermal stress without cloud dependency, penetrating heavy-duty mining and construction equipment.
- Commercial transport uptime economics:Fleet operators in Germany and the United States prioritize predictive maintenance platforms over reactive repair models, converting unplanned downtime into scheduled service windows.
Market Restraints
- Semiconductor supply concentration:Advanced sensor fusion chipsets depend on concentrated foundry capacity in East Asia, exposing IVHM system integrators to allocation volatility and extended lead times.
- Data sovereignty fragmentation:Divergent cross-border telematics architectures between China's GB/T vehicle networking security protocols and EU GDPR create compliance overhead for multinational fleet deployments.
- Legacy fleet inertia:Retrofit costs for CAN bus loggers and oil particulate counters on vehicles older than seven years exceed residual value thresholds, capping addressable fleet penetration.
Strategic Opportunities
- Battery cell imbalance detection:Electric commercial vehicle platforms in China lack mature prognostics, creating white space for predictive analytics systems targeting thermal runaway prevention.
- NHTSA defect investigation protocols:Preemptive fault detection mandates in the United States create procurement pull from OEMs seeking recall exposure mitigation through embedded health management.
- Software-layer specialization:Heterogeneous vehicle network navigation for mixed-fleet operators represents an underserved segment as hardware commoditization compresses margins in sensor manufacturing.
Industry Challenges
- Functional safety engineering scarcity:ISO 26262 ASIL-D certification expertise concentrates among semiconductor and tier-1 suppliers, constraining independent software vendors from automotive-grade deployments.
- Multi-source data fusion complexity:Integrating accelerometer, temperature, and particulate counter streams into unified degradation models requires calibration expertise that outpaces current workforce supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Integrated Vehicle Health Management Market |
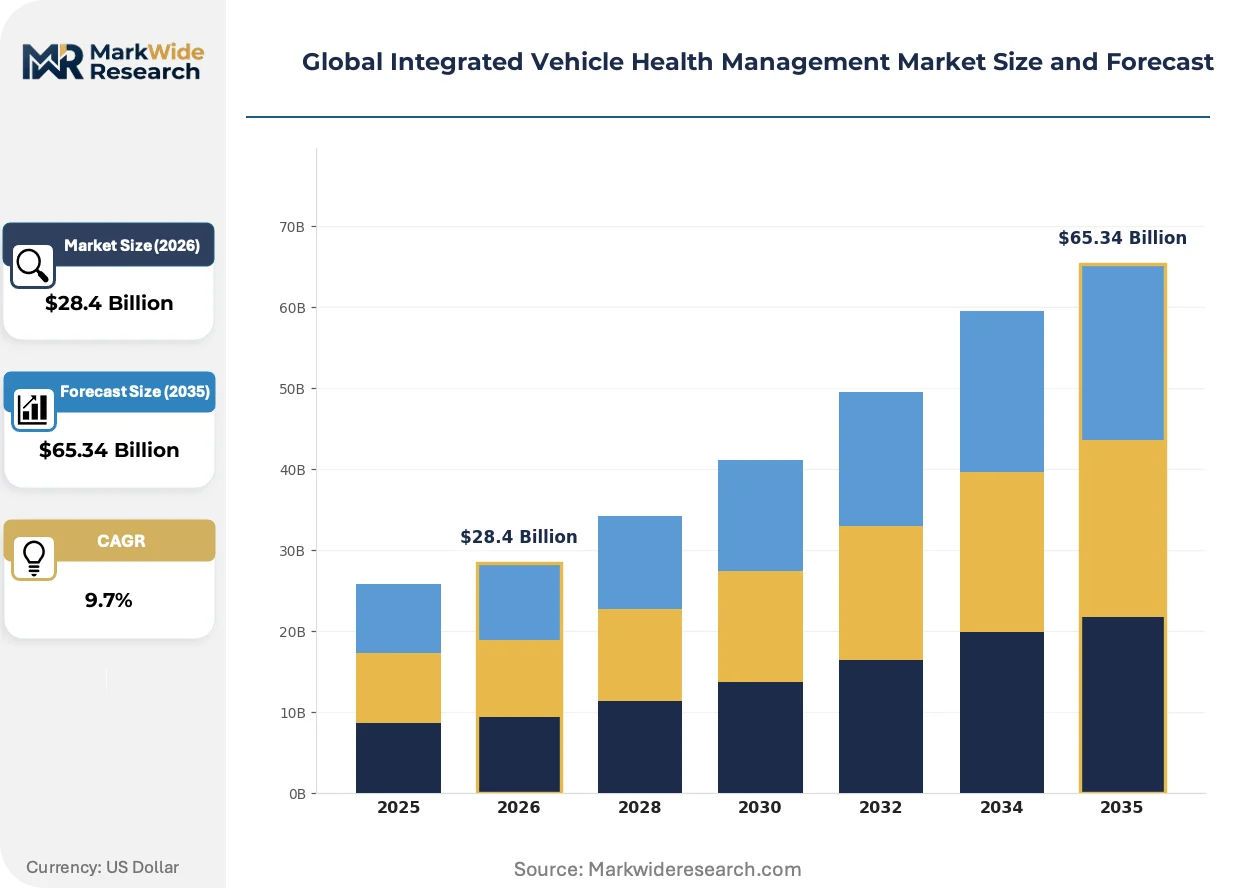
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $65.34 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Predictive Analytics Systems, Fault Diagnostics Modules, Telematics Devices, Condition Monitoring Sensors, Data Acquisition Units Application: Fleet Management, Performance Optimization, Safety Enhancement, Maintenance Scheduling, Warranty Analysis End User: Commercial Transport Companies, Public Transit Operators, Logistics Providers, Vehicle Repair Garages, Transportation Agencies Deployment: Onboard Systems, Cloud-Based Platforms, Hybrid Solutions, Edge Computing, Mobile Applications |
| Companies Covered | Robert Bosch GmbH, Continental AG, Visteon Corporation, ZF Friedrichshafen AG, Garrett Motion Inc., Delphi Technologies, KPIT, OnStar, Cummins Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Integrated Vehicle Health Management Market Strategic Shifts & Innovations
Predictive maintenance architectures are converging with electrification platforms, compressing development cycles and forcing recalibration of hardware-software value capture across the supply chain.
Digital twin-based prognostics is supplanting threshold-based alarm systems in commercial fleet applications. Logistics operators in Germany now mandate continuous virtual replication of powertrain degradation states. This capability is compressing maintenance scheduling windows from weeks to hours.
China's GB/T vehicle networking security protocols and the EU AI Act are mandating explainable anomaly detection in safety-critical subsystems. Automotive OEMs must now document decision pathways for battery thermal warnings. Heavy-duty electric truck platforms face the steepest compliance recertification timelines.
Leasing companies are unbundling predictive maintenance from capital contracts, creating standalone service revenue streams. Fleet management providers in the United States now procure IVHM capabilities separately from vehicle acquisition. This shift is visible most acutely in long-haul trucking segments where utilization rates determine financing terms.
Global Integrated Vehicle Health Management Market Segmentation
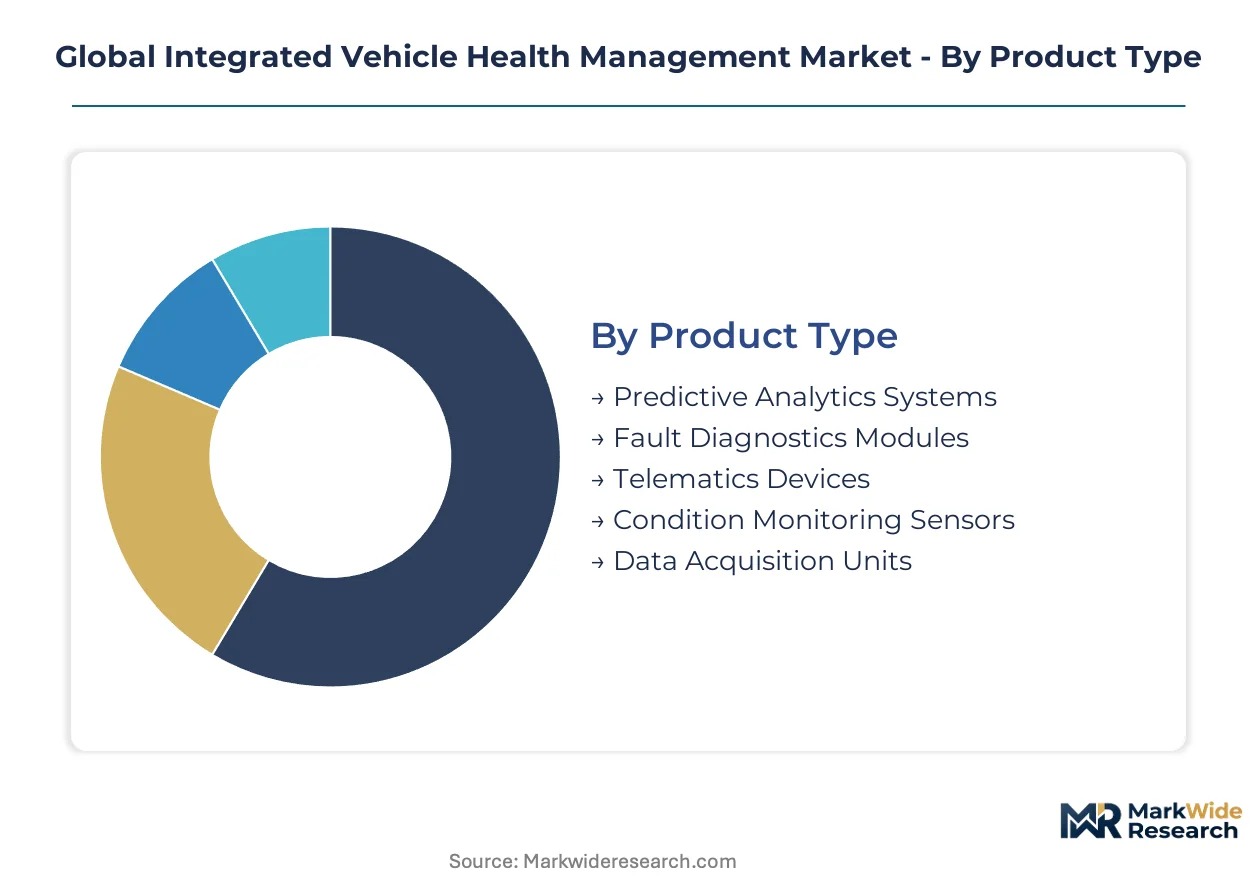
IVHM market segmentation reveals divergent value capture strategies across hardware, software, and service layers. Product architecture choices determine margin profiles, while deployment modes reflect connectivity infrastructure maturity in target geographies.
Product Type:
Predictive Analytics Systems and Condition Monitoring Sensors concentrate demand in Germany and the United States, while Fault Diagnostics Modules and Data Acquisition Units serve export-heavy supply chains into China and Brazil.
- Predictive Analytics Systems:Machine learning platforms process multi-source sensor streams to forecast component degradation. Fleet operators in Germany prioritize these systems to convert unplanned downtime into scheduled maintenance windows under stringent uptime contracts.
- Condition Monitoring Sensors:Accelerometers, temperature transducers, and oil particulate counters sample at 1–10 kHz to detect incipient bearing wear. Mining equipment manufacturers in Australia and Canada specify these for heavy-duty applications where cloud connectivity gaps persist.
- Fault Diagnostics Modules:Embedded controllers execute real-time anomaly detection at the ECU level.
- Telematics Devices:Cellular and satellite communication hardware transmits health data to centralized fleet platforms.
- Data Acquisition Units:CAN bus loggers aggregate heterogeneous vehicle network signals for downstream analysis.
Predictive Analytics Systems commands the established base. The steepest expansion runs through Condition Monitoring Sensors.
Application:
Cost tier stratification separates premium predictive platforms from standard diagnostic tools, with Fleet Management and Safety Enhancement commanding price premiums over Maintenance Scheduling and Warranty Analysis.
- Fleet Management:Integrated platforms coordinate vehicle health monitoring with route optimization and driver behavior analytics. Logistics providers in the United States procure these as standalone services unbundled from capital leases, converting fixed costs to variable operating expenditures.
- Safety Enhancement:Real-time thermal monitoring and brake wear detection prevent catastrophic failures. China's GB/T vehicle networking security protocols and the EU AI Act mandate explainable anomaly detection in these safety-critical subsystems, extending certification timelines.
- Performance Optimization:Engine calibration and energy consumption tuning based on degradation state.
- Maintenance Scheduling:Automated work order generation triggered by prognostic thresholds.
- Warranty Analysis:Post-failure data mining to validate OEM liability and improve design.
Fleet Management anchors current procurement volumes. Safety Enhancement is climbing the fastest as regulatory mandates harden.
End User:
Volume concentration favors large-scale operators, with Commercial Transport Companies and Logistics Providers driving procurement scale that Vehicle Repair Garages and Transportation Agencies cannot match.
- Commercial Transport Companies:Long-haul trucking and regional delivery fleets deploy comprehensive IVHM architectures across thousands of vehicles. Operators in Germany and the United States embed predictive maintenance into financing structures where utilization rates determine lease terms.
- Logistics Providers:Third-party fulfillment and last-mile delivery networks require heterogeneous fleet compatibility. These operators in China face acute demand for battery cell imbalance detection as electric commercial vehicle platforms proliferate without mature prognostics.
- Public Transit Operators:Municipal bus and rail systems with regulated service reliability mandates.
- Vehicle Repair Garages:Independent service providers retrofitting legacy fleets with aftermarket monitoring.
- Transportation Agencies:Government fleet operators with extended asset holding periods.
Commercial Transport Companies hold the dominant installed base. Logistics Providers are gaining share fastest as e-commerce fulfillment networks expand.
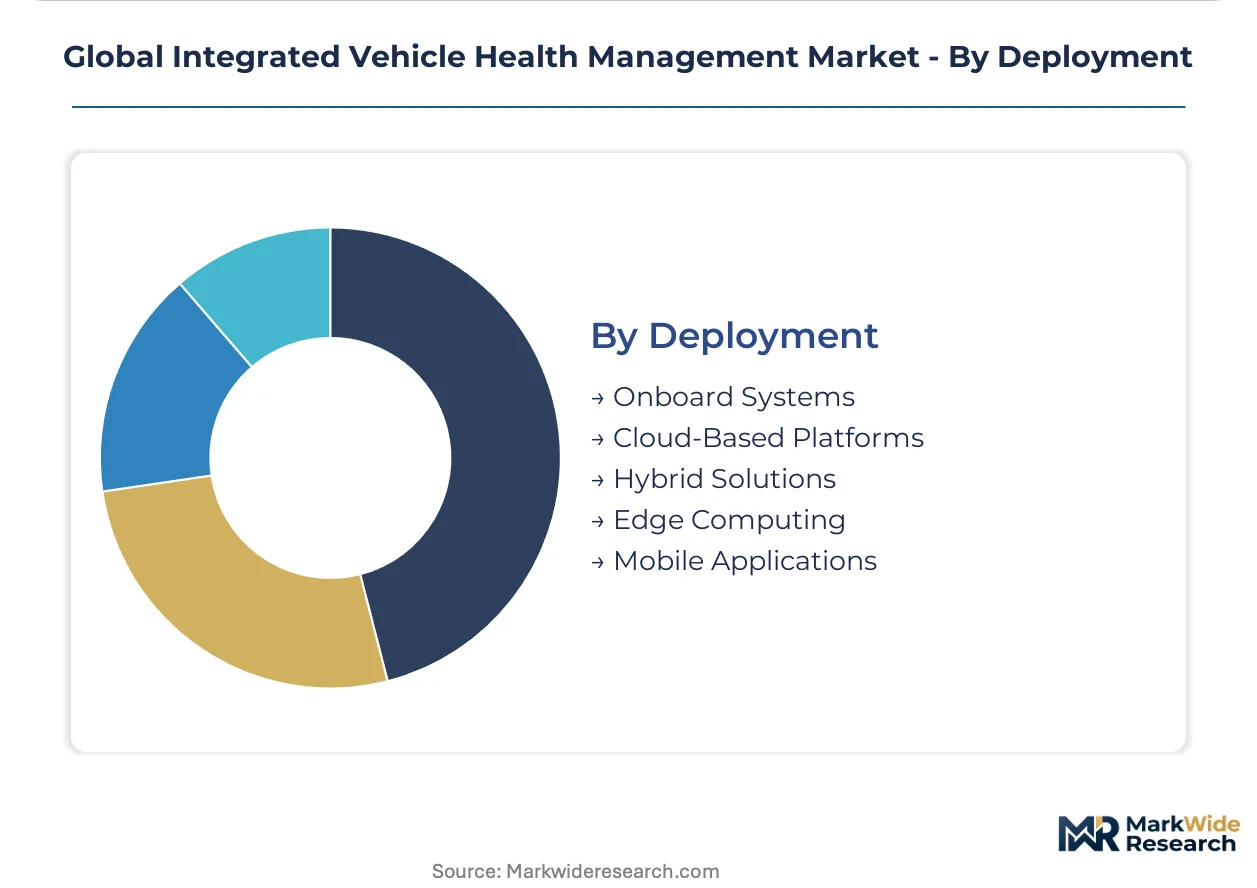
Deployment:
Supply concentration in edge-computing silicon shapes margin distribution, with Onboard Systems and Edge Computing retaining hardware premiums while Cloud-Based Platforms and Mobile Applications compete on software economics.
- Cloud-Based Platforms:Centralized data lakes enable fleet-wide benchmarking and machine learning model training. These architectures expand most quickly in the United States and Germany where 4G/5G coverage supports continuous connectivity for commercial logistics.
- Onboard Systems:Self-contained processing units execute diagnostics without network dependency. Heavy-duty mining and construction equipment in Canada and Australia specify these where cellular infrastructure remains sparse.
- Hybrid Solutions:Tiered processing with edge filtering and cloud aggregation for bandwidth optimization.
- Edge Computing:Millisecond-level anomaly detection at the vehicle level without latency to remote servers.
- Mobile Applications:Smartphone-based interfaces for driver alerts and simplified fleet manager dashboards.
Onboard Systems retain the established heavy-duty footprint. Cloud-Based Platforms are expanding most quickly as connectivity infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation and NHTSA defect investigation protocols are accelerating IVHM deployment across logistics-intensive economies. Germany, the United States, China, Japan, and India concentrate procurement scale as fleet operators convert unplanned downtime into scheduled maintenance windows.
United States
Long-haul trucking operators embed predictive maintenance into utilization-based financing structures. NHTSA defect investigation protocols drive OEM procurement of preemptive fault detection systems to mitigate recall exposure. Detroit's automotive corridor anchors tier-1 supplier R&D in edge-computing diagnostics for commercial fleets.
Germany
Logistics providers mandate continuous virtual replication of powertrain degradation states, compressing maintenance windows from weeks to hours. The EU AI Act and GDPR shape explainable anomaly detection requirements for safety-critical subsystems. Stuttgart's OEM engineering clusters embed health management into next-generation electric commercial vehicle architectures.
China
Electric commercial vehicle platforms proliferate without mature battery cell imbalance prognostics, creating white space for predictive analytics specialists. GB/T vehicle networking security protocols mandate localized data processing architectures. Shanghai and Beijing automotive technology parks concentrate domestic IVHM software development for heterogeneous fleet networks.
Japan
Premium commercial vehicle manufacturers integrate health management into export-oriented powertrain platforms. METI industrial standards guide functional safety certification pathways for semiconductor-dependent sensor fusion systems. Nagoya's automotive supplier corridor sustains R&D in millisecond-level onboard anomaly detection for mining and construction equipment.
India
Third-party logistics networks expand last-mile delivery fleets requiring heterogeneous compatibility across mixed vehicle ages. PLI scheme incentives accelerate domestic manufacturing of telematics hardware for commercial transport applications. Karnataka's Bangalore-Tumkur industrial corridor hosts software-layer specialists navigating multi-source vehicle data fusion.
Global Integrated Vehicle Health Management Market Key Industry Players
Player mix skews toward diversified automotive suppliers with captive semiconductor and sensor portfolios. Tier-1 conglomerates anchor the premium segment through integrated hardware-software stacks, while independent software vendors occupy the fleet-service layer. Two strategic archetypes dominate: full-stack powertrain integrators leveraging ASIL-D certification barriers, and software-layer specialists targeting heterogeneous network navigation. Competitive moves concentrate on strategic partnerships for edge-computing silicon access and portfolio diversification into battery prognostics.
Within the full-stack integrator tier, Robert Bosch GmbH and Continental AG exemplify archetypes leveraging semiconductor and sensor portfolios to anchor diagnostics across powertrain domains. KPIT occupies a position representing software-layer specialists that navigate heterogeneous vehicle networks for commercial fleet operators without captive hardware production. These three entities collectively illustrate the competitive boundary between hardware-integrated and software-defined value capture in predictive maintenance architectures.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Visteon Corporation |
| ZF Friedrichshafen AG |
| Garrett Motion Inc. |
| Delphi Technologies |
| KPIT |
| OnStar |
| Cummins Inc. |
| Others |
Cost & Logistics Intelligence
Capacity utilization at advanced semiconductor foundries in Taiwan and South Korea shapes both component availability floors and tier-1 supplier pricing power across IVHM system architectures. This scale concentration compresses margins for independent software vendors while anchoring premium pricing for ASIL-D certified integrated modules.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO 26262 ASIL-D qualified systems commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects functional safety grade, volume scale, and after-sales service bundling. Cost compression in the economy tier is intensifying because hardware commoditization in sensor manufacturing accelerates price erosion. Fleet operators with heterogeneous vehicle networks exhibit highest price sensitivity, while OEMs integrating health management into new vehicle architectures demonstrate lowest sensitivity due to recall exposure mitigation value.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for sensor fusion chipsets and edge-computing modules. Manufacturing concentrates in Taiwan, South Korea, and Germany for semiconductor-dependent components, with China and Mexico hosting final assembly operations. The supply chain draws from silicon wafers, rare earth magnets for accelerometers, and automotive-grade resin substrates. Single-source vulnerability in 7nm and below foundry capacity represents the dominant structural risk. Distribution runs through tier-1 automotive supplier networks with direct OEM integration, supplemented by aftermarket channels for retrofit applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IVHM incumbents face substitution pressure from over-the-air diagnostic platforms that bypass traditional hardware-integrated architectures, requiring defensive repositioning around certification moats and captive semiconductor access.
For Market Incumbents: Compound ASIL-D certification barriers through deeper collaboration with foundry partners to secure edge-computing silicon allocation. Prioritize backward integration into sensor manufacturing to defend margin position against software-defined diagnostic substitutes encroaching from the fleet-service layer. For New Entrants and Emerging Players: Anchor in battery cell imbalance detection for electric commercial vehicle platforms in China, where mature prognostics remain underdeveloped. Target mixed-fleet logistics operators with software-layer solutions that navigate heterogeneous CAN bus architectures without requiring captive hardware production. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-layer specialists with demonstrated fleet-scale deployment capabilities over hardware-integrated tier-1 suppliers facing margin compression. Monitor NHTSA defect investigation protocol expansions as the signal indicating accelerated OEM procurement pull for preemptive fault detection capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | ISO 26262 functional safety qualification creates defensible pricing power against uncertified competitors. |
| Edge-Computing Silicon Partnership | Foundry allocation agreements secure millisecond-level anomaly detection capabilities for heavy-duty applications. |
| Battery Prognostics Development | Thermal runaway prevention addresses white space in China's electric commercial vehicle platforms. |
| Fleet-Scale Software Deployment | Heterogeneous network navigation captures procurement from logistics providers unbundling IVHM from capital leases. |
| Regional Data Sovereignty Compliance | GB/T and GDPR-aligned architectures enable cross-border fleet telematics without regulatory friction. |
Research Approach
A standing panel of OEM platform engineers, tier-1 supplier procurement leads, fleet operations directors, and aftermarket service heads provided ongoing calibration against secondary validation. Primary interviews combined with vehicle production databases, IHS Markit registration data, SEC filings from automotive suppliers, and customs records for telematics hardware trade flows. Bottom-up component demand modeling and top-down fleet penetration analysis were triangulated for consistency.
Outputs were validated against external benchmarks including regional vehicle production forecasts and fleet telematics adoption surveys across the projection horizon. Segmentation dimensions modeled encompass product architecture, deployment mode, vehicle class, propulsion architecture, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to baseline penetration estimates, with electric commercial vehicle platform ramp rates and NHTSA protocol expansion timelines serving as key industry-specific inputs.
Material uncertainties — semiconductor allocation volatility, divergence in cross-border data sovereignty enforcement, and legacy fleet retrofit economic thresholds — sit outside the modeled envelope. Forecasts reflect documented assumptions about connectivity infrastructure maturation and regulatory mandate implementation timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Glass Market
Vehicle Maintenance & Aftermarket
Automotive Cleaner and Degreaser Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Car Care Products Market
Vehicle Maintenance & Aftermarket
Asia Pacific Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Portable Leather Polishing Machine Market
Vehicle Maintenance & Aftermarket
Car Duster Market
Vehicle Maintenance & Aftermarket
Antimicrobial Car Care Products Market
Vehicle Maintenance & Aftermarket
APEJ Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Classic Car Restoration and Restomod Services Market
Vehicle Maintenance & Aftermarket
Europe Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Automotive Repair and Maintenance Services Market
Vehicle Maintenance & Aftermarket
Engine Module-Level Repair and Refurbishment Services Market
Vehicle Maintenance & Aftermarket
United Kingdom Vehicle Recycling Market
Vehicle Maintenance & Aftermarket
Car Polisher Market
Vehicle Maintenance & Aftermarket
Automotive Exhaust Aftertreatment Systems Market