
 US Car Care Products Market | 2026-2036
US Car Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
US Car Care Products Market Intelligence
The proliferation of ceramic and graphene-based coating technologies is narrowing the performance gap between professional-grade and consumer-available protectants. Meguiar's Inc. leverages its strong brand heritage to introduce hybrid ceramic formulations to the mainstream market. Chemical Guys differentiates through a digital-first marketing strategy and extensive product education for enthusiasts. 3M Company sustains its position by supplying advanced abrasives and compounds to the professional auto body and repair sector.
US car care products encompass a range of chemical formulations designed for cleaning, protecting, and enhancing automotive surfaces. These products often feature specific compositions, such as pH-neutral shampoos to protect wax layers or polymer-based sealants that form a hydrophobic barrier. Within product types, high-margin polish and ceramic coating products are gaining share over traditional waxes. Online retail represents the fastest-growing distribution channel, utilized heavily by DIY Enthusiasts seeking wider product selection.
The regulatory environment is shaped by the US EPA, which sets limits on volatile organic compounds in cleaning agents and other chemical formulations. Additionally, OSHA standards govern chemical handling safety in professional settings, while FTC guidelines regulate product performance claims and advertising. Stakeholders must monitor the shift in consumer preference toward water-based, biodegradable formulations and long-duration protection to maintain market relevance.
Market Dynamics
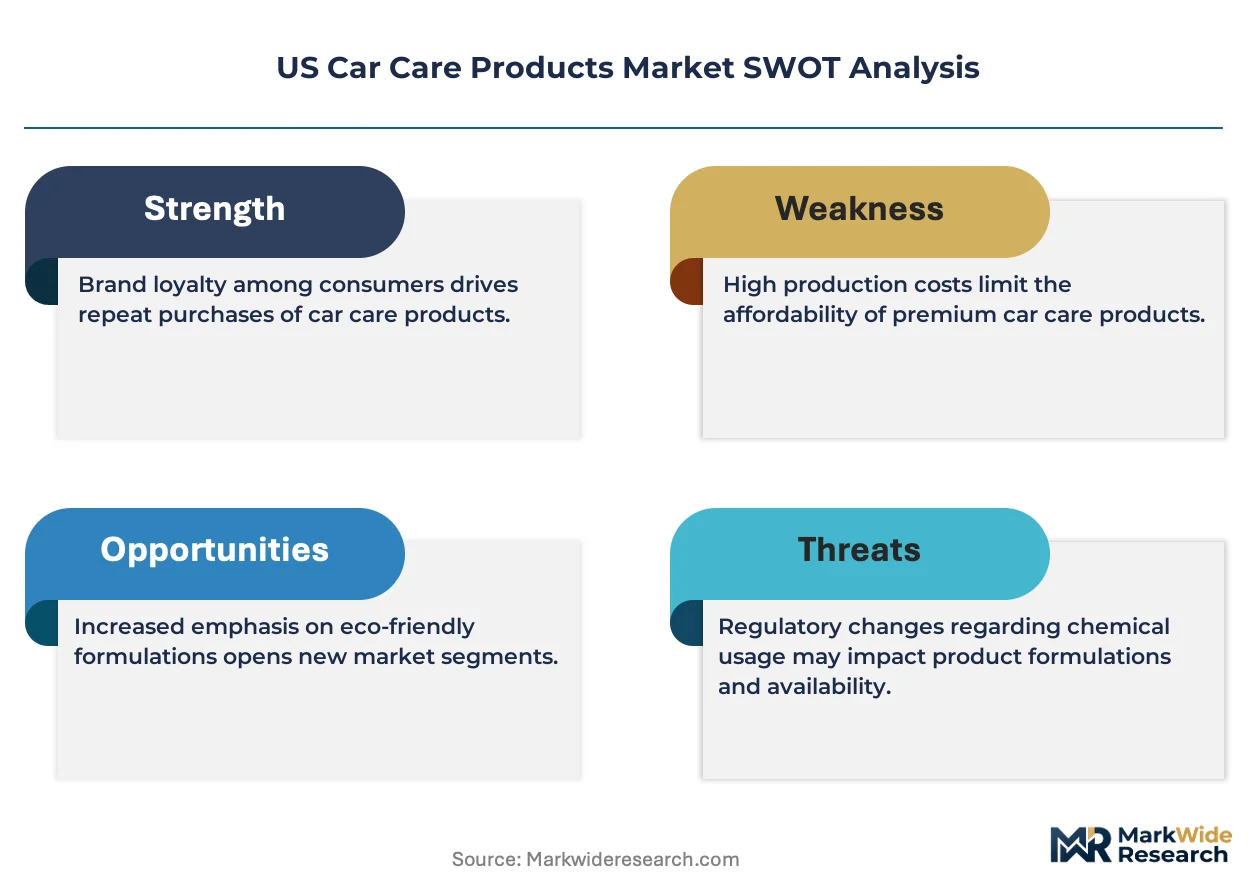
The primary structural force in the US car care market is regulatory pressure from the EPA. Its strict limits on volatile organic compounds (VOCs) are compelling an industry-wide pivot toward water-based and biodegradable product formulations.
Growth Catalysts
- Advanced Coating Accessibility:Diffusion of ceramic and graphene technologies to consumer markets expands the high-margin protectants segment for DIY users.
- DIY Enthusiast Segment Expansion:A growing cohort of vehicle owners performing their own detailing increases demand for consumer-grade polishes, waxes, and cleaners.
- High-Density Vehicle Parcs:States like California, with large vehicle populations and car culture, exhibit concentrated demand for appearance and protection products.
Market Restraints
- Petrochemical Input Volatility:Costs for solvents, polymers, and surfactants derived from crude oil introduce price instability and margin pressure for manufacturers.
- State-Level Regulatory Fragmentation:Navigating differing VOC limits between federal EPA rules and stricter state regulations from entities like CARB increases compliance costs.
- Growth of Professional Detailing Services:Expansion of detailing services using bulk-purchased products reduces individual consumer purchases of packaged goods.
Strategic Opportunities
- Specialized Formulations for EVs:Developing products for electric vehicle materials, such as plastic composites and battery coatings, creates a new market segment.
- Subscription Box Models:Curated delivery services for DIY enthusiasts build brand loyalty and create predictable revenue outside traditional retail.
- Integration of Smart Nanomaterials:Incorporating self-healing properties into ceramic coatings opens avenues for premium product categories beyond standard protection.
Industry Challenges
- Substantiating Performance Claims:Adhering to FTC guidelines for advertising long-duration protection requires extensive testing, creating barriers for brands making claims about ceramic coatings.
- Sourcing Sustainable Inputs:Securing a consistent supply of effective, biodegradable, and water-based raw materials that meet performance expectations is a key operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Car Care Products Market |
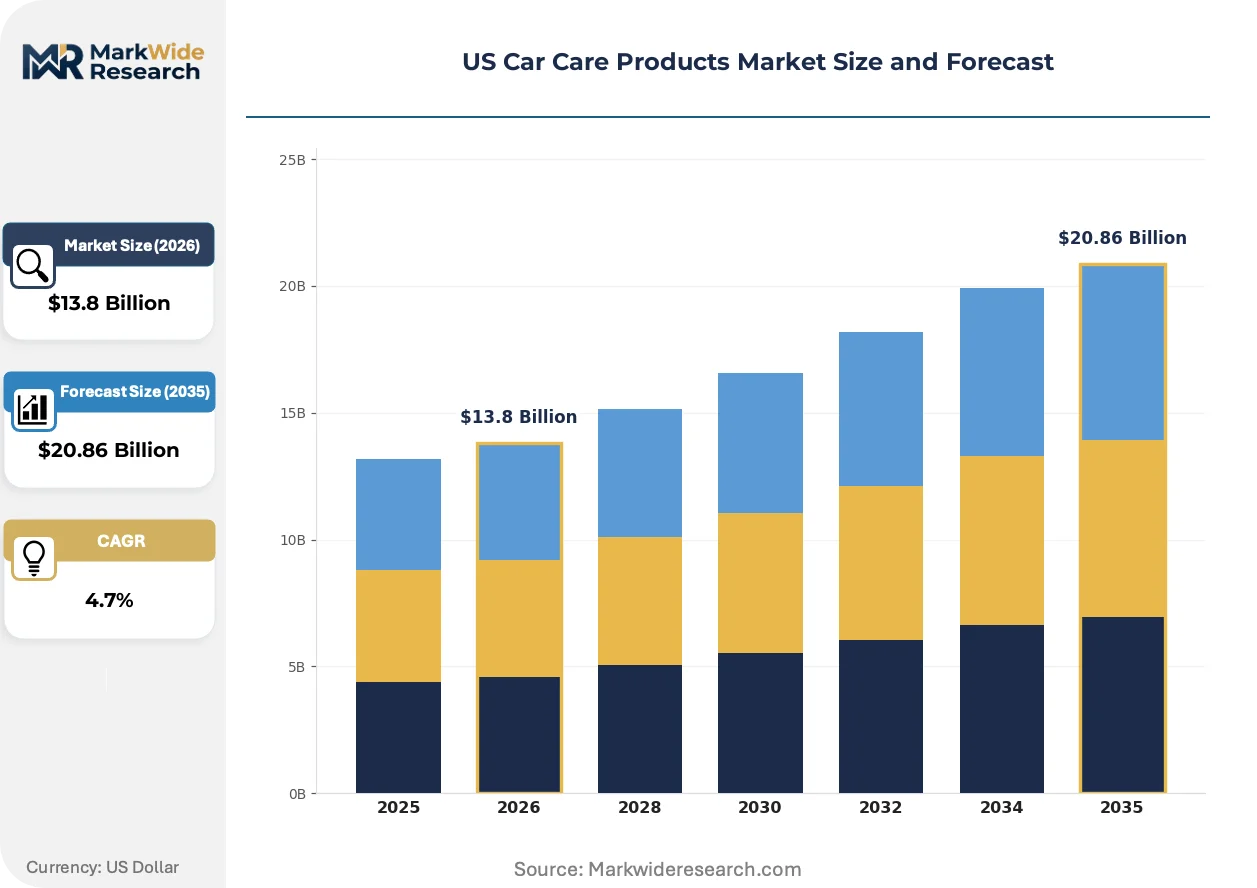
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $20.86 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wax, Polish, Shampoo, Cleaner Application: Cleaning, Protection, Restoration, Maintenance End User: DIY Enthusiasts, Automotive Professionals, Dealerships, Fleet Managers Distribution Channel: Online Retail, Automotive Stores, Supermarkets, Specialty Stores |
| Companies Covered | Armor All, Autoglym, 3M Company, Chemical Guys, Simoniz USA, Turtle Wax, Sonax GmbH, Liqui Moly GmbH, Meguiar's Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Car Care Products Market Strategic Shifts & Innovations
Chemical innovation in surface protection is converging with digital-first consumer engagement models. This dynamic alters how products are developed, marketed, and used by both professional and DIY segments in the US market.
Advanced sensor-based application tools, paired with mobile apps, provide real-time feedback on coating thickness and curing. Professional detailers and technologically-savvy DIY enthusiasts are early adopters seeking perfect, repeatable results. This hardware-software integration is digitizing the art of surface application, turning a manual skill into a data-driven process.
The US EPA’s Safer Choice program provides a voluntary label for cleaning products meeting strict health and environmental criteria. This encourages manufacturers to reformulate products using ingredients from the EPA's Safer Chemical Ingredients List. Car wash and interior cleaner categories are most affected, using the label to attract eco-conscious consumers.
Subscription-based e-commerce models are gaining traction among dedicated car care hobbyists. This direct-to-consumer channel bypasses traditional auto parts stores, allowing brands to capture higher margins and build direct customer relationships. The trend is most visible among digitally native brands targeting the US enthusiast segment.
US Car Care Products Market Segmentation
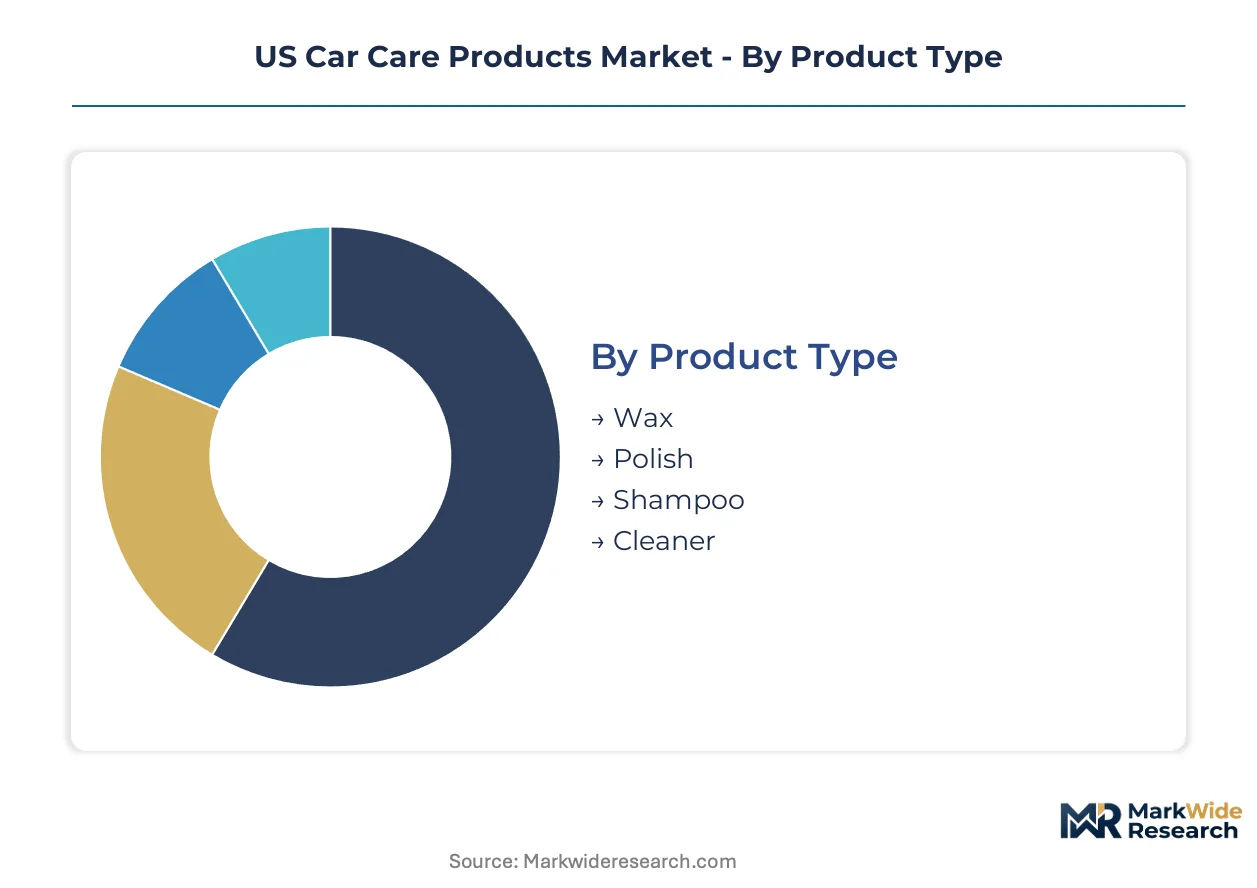
Understanding the US car care market's segmentation is vital for manufacturers to align product development with specific consumer needs. This detailed breakdown reveals distinct purchasing behaviors and channel preferences across different user groups. Strategic targeting of these segments allows companies to optimize marketing efforts and product offerings within the competitive landscape.
Product Type:
The intensity of after-sales service requirements often dictates the formulation complexity and packaging of various car care product types.
- Polish:These abrasive compounds refine painted surfaces, removing imperfections and enhancing gloss through mechanical or chemical action. Demand concentrates in California and Florida, where vehicle aesthetics are highly valued, driving sales among detailing enthusiasts.
- Wax:Natural or synthetic blends create a sacrificial layer, providing hydrophobic properties and UV protection to automotive finishes. DIY enthusiasts frequently purchase these products for routine vehicle maintenance, seeking ease of application and visible results.
- Shampoo:pH-neutral detergents safely remove dirt and grime from vehicle exterfaces without stripping existing protective layers.
- Cleaner:Specialized formulations target specific contaminants, such as bug splatter, tar, or interior stains, restoring surface cleanliness.
By volume, Shampoo leads. By growth pace, Polish is ahead.
Application:
Different application categories often correlate with varying cost tiers, reflecting product sophistication and required labor.
- Protection:This segment includes sealants, ceramic coatings, and waxes that form a barrier against environmental damage and enhance gloss. Demand for long-duration protection products is strong among DIY enthusiasts and professionals seeking advanced hydrophobic properties.
- Restoration:Products in this category address significant paint defects like heavy scratches, oxidation, and swirls, often requiring abrasive compounds and specialized equipment. Automotive professionals and dedicated hobbyists drive this segment, focusing on achieving showroom finishes.
- Cleaning:This fundamental application involves removing dirt, grime, and contaminants from all vehicle surfaces using various detergents and degreasers.
- Maintenance:Routine care products preserve the vehicle's appearance and protective layers, including quick detailers, tire dressings, and interior wipes.
Protection products demonstrate the steepest expansion trajectory, while Cleaning applications maintain consistent demand.
End User:
Distinct customer types exhibit unique purchasing habits and product preferences, influencing brand strategies and distribution models.
- DIY Enthusiasts:These consumers perform their own vehicle detailing and maintenance, purchasing a wide array of products through online retail and specialty stores. Their preference shifts towards accessible advanced coatings and eco-friendly formulations.
- Automotive Professionals:Detailers, body shops, and service centers purchase bulk quantities of specialized chemicals, abrasives, and compounds. Their procurement decisions prioritize performance, efficiency, and adherence to OSHA safety standards.
- Dealerships:These entities use car care products for vehicle preparation, pre-sale detailing, and customer service applications, often requiring efficient and high-volume solutions.
- Fleet Managers:Overseeing large vehicle fleets, these buyers focus on cost-effective, durable, and easy-to-apply products that maintain vehicle appearance and longevity.
DIY Enthusiasts increasingly influence product innovation, while Automotive Professionals secure market stability through consistent demand for high-performance solutions.
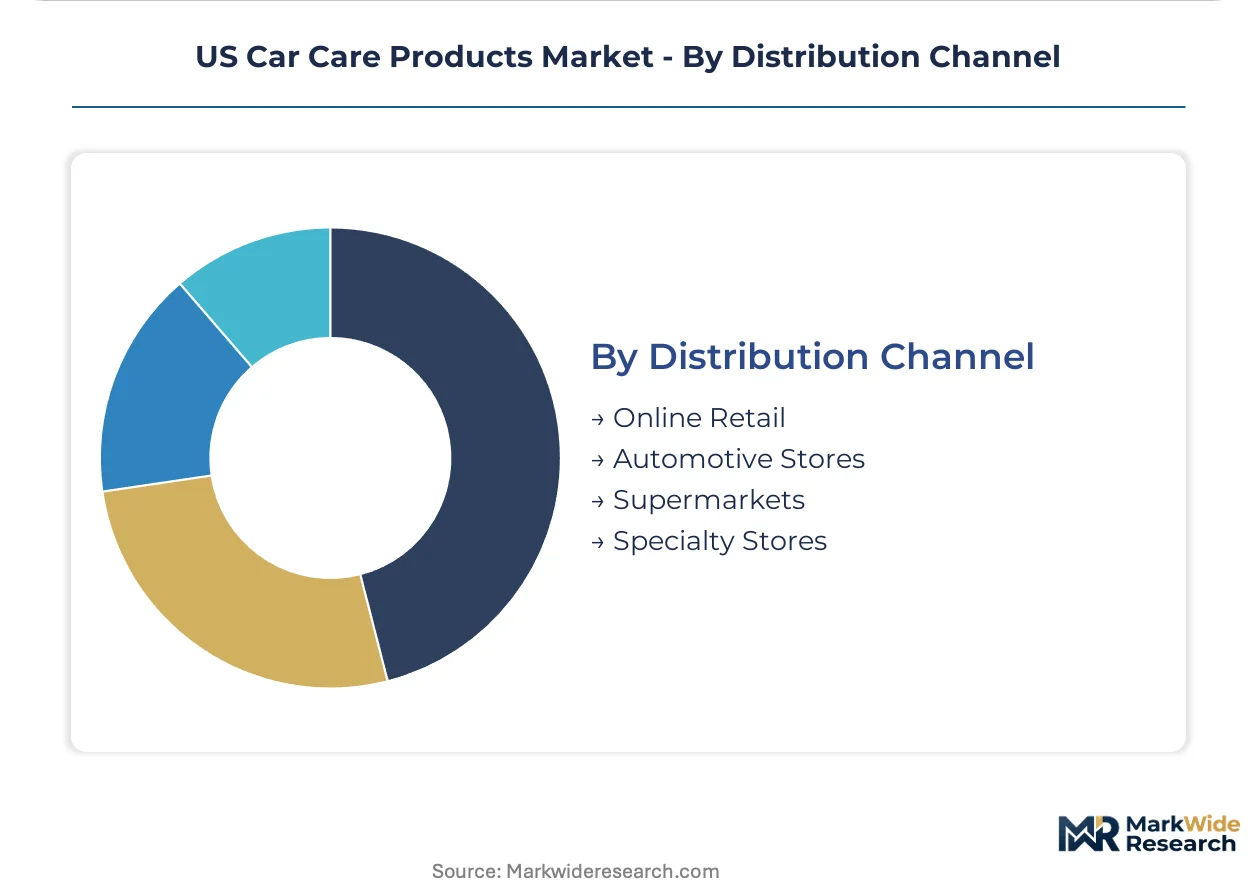
Distribution Channel:
Each distribution channel offers varying margin structures and reach, impacting brand profitability and market penetration.
- Online Retail:This channel represents the fastest-growing segment, offering consumers extensive product selections, competitive pricing, and convenience for home delivery. Digitally native brands leverage this channel for direct-to-consumer sales and enthusiast engagement.
- Automotive Stores:These physical outlets provide immediate product access, expert advice, and hands-on product comparisons for consumers. They cater to both DIY enthusiasts and professionals seeking specialized tools and chemicals.
- Supermarkets:Mass-market retailers offer basic car cleaning and protection products, appealing to general consumers seeking convenience during routine shopping trips.
- Specialty Stores:These dedicated outlets focus on premium and niche car care brands, serving dedicated hobbyists and professionals with high-performance product lines.
Online Retail exhibits significant growth, while Automotive Stores provide a stable foundation for product availability and customer service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
DIY Enthusiasts and automotive professionals drive concentrated demand across key US regions. These buyers actively seek specialized formulations for vehicle aesthetics and long-term protection. Market growth correlates directly with high vehicle ownership rates and a strong car culture in specific states.
California
California exhibits concentrated demand for premium car care products due to its extensive vehicle parc and strong car culture. The state's strict CARB regulations compel manufacturers to prioritize low-VOC and water-based formulations. In the Los Angeles metropolitan area, detailing services and specialty retailers cater to high-end automotive enthusiasts, driving sales of advanced protectants.
Texas
Texas represents a significant market, driven by its vast truck and SUV ownership and demanding environmental conditions. US EPA guidelines for chemical safety impact the formulation of heavy-duty cleaners and protectants used in the state's diverse climate. The Houston area, with its large commercial vehicle fleets, shows strong demand for industrial-grade cleaning and protection solutions.
Florida
Florida's coastal environment and intense UV exposure create specific demand for durable waxes and ceramic coatings to protect vehicle finishes. FTC regulations ensure product claims about long-duration UV protection are substantiated for consumers in this sunny state. In the Miami region, luxury vehicle owners frequently seek out premium detailing services and advanced surface protectants.
Pacific Northwest
The Pacific Northwest market values eco-friendly and water-based car care solutions due to its rainy climate and strong environmental focus. US EPA's Safer Choice program encourages the use of biodegradable formulations for car washes and interior cleaners in this region. Seattle's tech-savvy population often adopts subscription box models for convenient delivery of sustainable car care products.
US Car Care Products Market Key Industry Players
Channel-controlling players compete with product-specialist players across the US car care market, creating a dynamic competitive environment. The market structure features a mix of established brands with broad retail distribution and nimble, digitally-native companies focused on direct-to-consumer sales. Strategic archetypes include diversified chemical conglomerates, heritage detailing brands, and innovative e-commerce-focused entities. Companies pursue portfolio diversification into advanced coating technologies and strategic partnerships for sustainable raw material sourcing.
Within the advanced materials archetype, 3M Company, Inc. anchors the professional auto body and repair sector, supplying high-performance abrasives and compounds for restoration applications. Meguiar's Inc. exemplifies the heritage detailing brand, leveraging its strong brand recognition to introduce hybrid ceramic formulations to mainstream consumers through established retail channels. Chemical Guys represents the digitally-native, enthusiast-focused archetype, employing extensive product education and a strong online presence to differentiate its diverse product offerings and build community loyalty.
| Leading Market Players |
|---|
| Armor All |
| Autoglym |
| 3M Company |
| Chemical Guys |
| Simoniz USA |
| Turtle Wax |
| Sonax GmbH |
| Liqui Moly GmbH |
| Meguiar's Inc. |
| Others |
Cost & Logistics Intelligence
Petrochemical input volatility directly influences pricing across the US car care products market, impacting manufacturer margins for solvents and polymers. This upstream concentration dictates where value accumulates within the supply chain.
Pricing Analysis
Cost-plus contract patterns, often indexed to crude oil prices, define much of the bulk chemical procurement within the US car care market. Pricing stratifies across premium, standard, and economy tiers for consumer products, driven by formulation complexity and brand premium. Petrochemical input volatility causes margin pressure for manufacturers. Dealerships and fleet managers exhibit high price sensitivity for bulk purchases, while DIY Enthusiasts prioritize performance for advanced coatings and specialized products.
Supply Chain Analysis
The upstream feedstock for many car care formulations, including solvents and polymers, originates primarily from global petrochemical hubs. Key raw material dependencies include crude oil derivatives for surfactants and specialty chemicals sourced from domestic US producers. Commodity price volatility poses a structural risk to input costs and overall supply stability. Downstream distribution runs through online retail and automotive stores for packaged goods, with direct sales to automotive professionals for bulk supplies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US car care market is experiencing high-growth disruption, driven by the proliferation of ceramic and graphene-based coating technologies. This technological inflection is reshaping consumer expectations for surface protection.
For Market Incumbents: Build brand loyalty and channel control through direct-to-consumer platforms and subscription models. This counters the threat of digitally-native brands and provides a lever for sustained R&D investment in eco-friendly formulations. Consolidate market share by acquiring smaller, innovative brands specializing in advanced coating technologies and sustainable inputs. Leverage heritage to introduce hybrid ceramic solutions.
For New Entrants and Emerging Players: Specialized formulations for electric vehicle materials, such as plastic composites and battery coatings, represent a penetrable entry point. Curated subscription box models targeting tech-savvy DIY enthusiasts in the Pacific Northwest offer a strong go-to-market angle. Develop products specifically for commercial fleet managers seeking durable, cost-effective cleaning and protection solutions.
For Investors and Strategic Acquirers: Capital is best deployed toward digitally-native brands with strong online communities and intellectual property in advanced coating technologies. The market demonstrates long-term viability over a five-to-ten-year window due to sustained vehicle ownership and evolving consumer preferences. Watch for increased M&A activity among established players seeking to integrate sustainable input sourcing and advanced material science capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases production of water-based formulations to meet US EPA regulatory compliance. |
| Direct-to-Consumer Launch | Establishes brand control and captures higher margins from DIY Enthusiasts. |
| Product Launch (EV Specific) | Addresses the emerging demand for specialized electric vehicle material care. |
| Strategic Partnership (Sourcing) | Secures sustainable input supply for biodegradable formulations. |
| Subscription Model Rollout | Builds predictable revenue streams and fosters brand loyalty among hobbyists. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary research. Interviews engaged R&D directors, procurement leads from automotive professional segments, brand managers, and regulatory affairs specialists. Secondary validation drew from US EPA databases, industry association reports, and automotive registration data. This approach ensured robust bottom-up and top-down triangulation.
Forecast inputs considered vehicle parc growth, evolving US EPA regulations, and consumer preference shifts across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end-user, and distribution channel. Compound annual growth rates derived from historical trend analysis and projected market dynamics. Regulatory changes impacting VOC limits served as a key forecast input.
Practitioners should monitor new US EPA regulations and petrochemical price spikes for early signals impacting market trajectory. Forecasts reflect assumptions regarding consumer DIY engagement and technological adoption. Cross-checking against US automotive industry reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
North America Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Car Polisher Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Car Wash Ancillary Products Market
Vehicle Maintenance & Aftermarket
Catenary Maintenance Vehicle Market
Vehicle Maintenance & Aftermarket
Car Duster Market
Vehicle Maintenance & Aftermarket
Car Care Cosmetics Market
Vehicle Maintenance & Aftermarket
Global Road Maintenance Market
Vehicle Maintenance & Aftermarket
Portable Leather Polishing Machine Market
Vehicle Maintenance & Aftermarket
Car Detailing Products Market
Vehicle Maintenance & Aftermarket
Vehicle Health Monitoring Market
Vehicle Maintenance & Aftermarket
Global Integrated Vehicle Health Management Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Cleaning Products Market
Vehicle Maintenance & Aftermarket
Car and Truck Wash Market
Vehicle Maintenance & Aftermarket
Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
US Maintenance Repair and Operations (MRO) Market